
 Video Surveillance and Vsaas Market | 2026-2036
Video Surveillance and Vsaas Market Size, Share, and Industry Trends Forecast 2026-2036
Video Surveillance and Vsaas Market Outlook
ISO 27001 certification is redrawing competitive boundaries in the VSaaS ecosystem, forcing providers to demonstrate information security management before winning enterprise and government contracts. Hangzhou Hikvision Digital Technology Co., Ltd. leverages its vertically integrated manufacturing base to dominate camera hardware volumes across Asia-Pacific deployments. Axis Communications AB differentiates through open-platform architecture that sustains partner ecosystem loyalty among large-scale integrators.
Video surveillance and VSaaS encompasses networked camera systems, video management software, storage infrastructure, and cloud-delivered subscription services that enable real-time monitoring, forensic search, and automated alert generation for physical security operations. The technology stack typically processes H.265-compressed video streams at edge nodes before transmitting metadata to central or cloud repositories for analytics. IP Surveillance and Cloud Solutions segments are capturing the fastest expansion as hybrid deployment models allow organizations to preserve legacy analog investments while layering AI Analytics capabilities. Software and Analytics Tools segments concentrate margin pools where recurring licensing revenue exceeds hardware depreciation cycles.
FCC equipment authorization requirements govern wireless transmission modules in US-deployed cameras, while GDPR and EU AI Act provisions in Europe restrict facial recognition deployment in public spaces and mandate algorithmic transparency. The national pharmaceutical regulator in India and BIS certification standards shape product compliance timelines for equipment imports across South Asian infrastructure projects. Stakeholders must monitor how fragmented data sovereignty rules across jurisdictions complicate multi-tenant cloud architectures and cross-border video data flows.
Market Dynamics
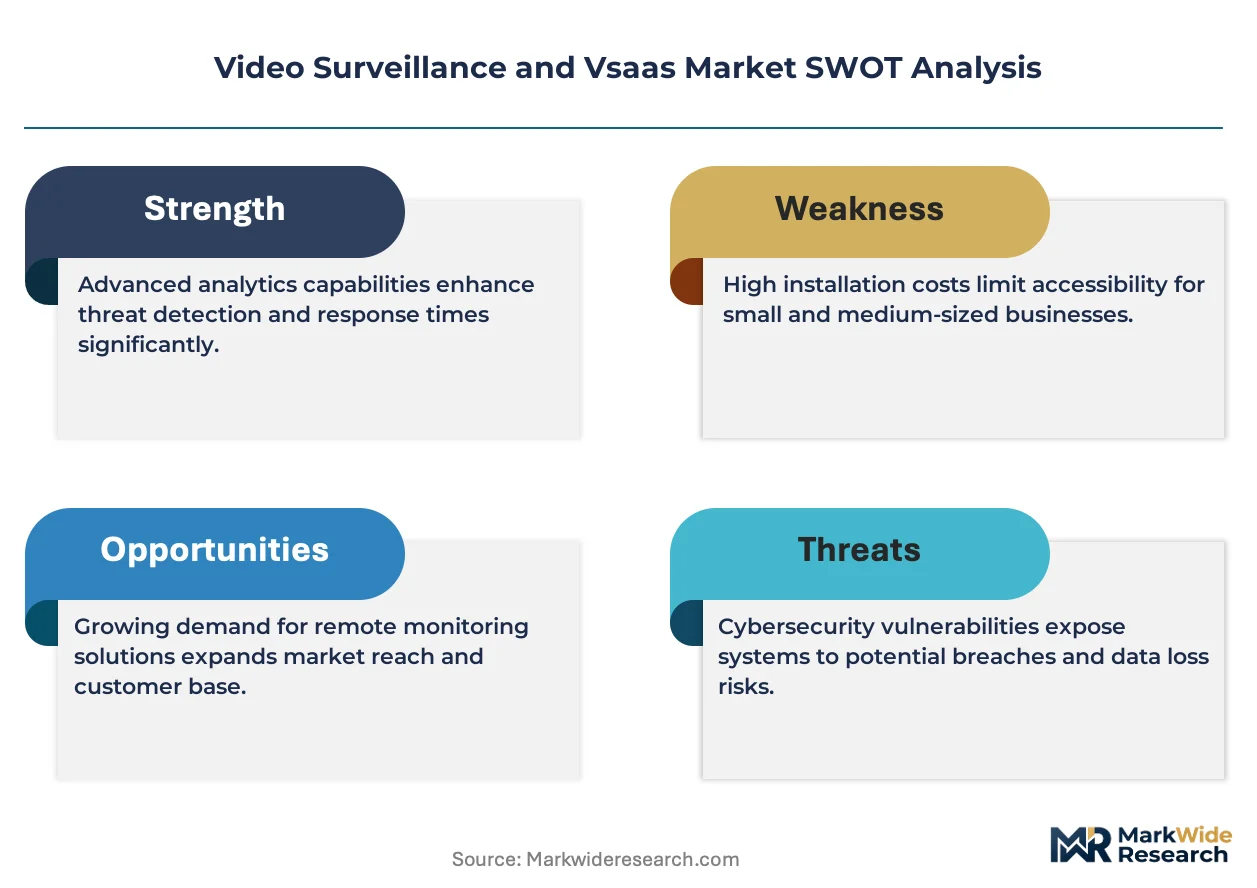
The migration from on-premise NVR systems to cloud-native VSaaS architectures is compressing hardware refresh cycles and redistributing margin pools toward software subscriptions across municipal, retail, and enterprise security deployments.
Growth Catalysts
- GDPR and EU AI Act compliance mandates:European public-sector tenders now require algorithmic transparency documentation and purpose-limitation controls, accelerating replacement of legacy analog systems with auditable IP platforms.
- Smart city infrastructure budgets:Municipal governments in India and Brazil are channeling urban development funds into centralized video command centers for traffic management and public safety coordination.
- Edge AI inference chips:On-camera processing of H.265 streams reduces backhaul bandwidth requirements by 60-70 percent, enabling analytics deployment in bandwidth-constrained environments.
Market Restraints
- CMOS sensor supply concentration:Taiwan and South Korean foundries control advanced image sensor fabrication, exposing camera OEMs to geopolitical disruption and allocation rationing during demand spikes.
- Cross-border data sovereignty fragmentation:Russia, China, and Vietnam mandate local video data residency, forcing VSaaS providers to build redundant in-country infrastructure that erodes platform economics.
- Facial recognition moratoriums:Portland, San Francisco, and multiple EU member states have banned biometric identification in public spaces, eliminating a high-margin analytics module from product roadmaps.
Strategic Opportunities
- Indonesia and Vietnam manufacturing corridors:Factory automation and port security investments in Southeast Asia are outpacing local VSaaS vendor capacity, creating entry windows for foreign platform providers.
- Cyber insurance bundling:Underwriters are beginning to mandate ISO 27001-certified video systems for policy eligibility, converting compliance from cost center to competitive differentiator.
- 5G private network integration:Ultra-reliable low-latency communication enables wireless camera deployment in mining, construction, and agriculture where fiber trenching is cost-prohibitive.
Industry Challenges
- Embedded systems security engineering talent:Shortage of firmware developers with cryptography and secure-boot expertise delays product hardening timelines and expands attack surfaces.
- Multi-tenant cloud architecture complexity:Engineering teams must isolate tenant data streams while maintaining sub-second alert latency, requiring specialized DevSecOps capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Surveillance and Vsaas Market |
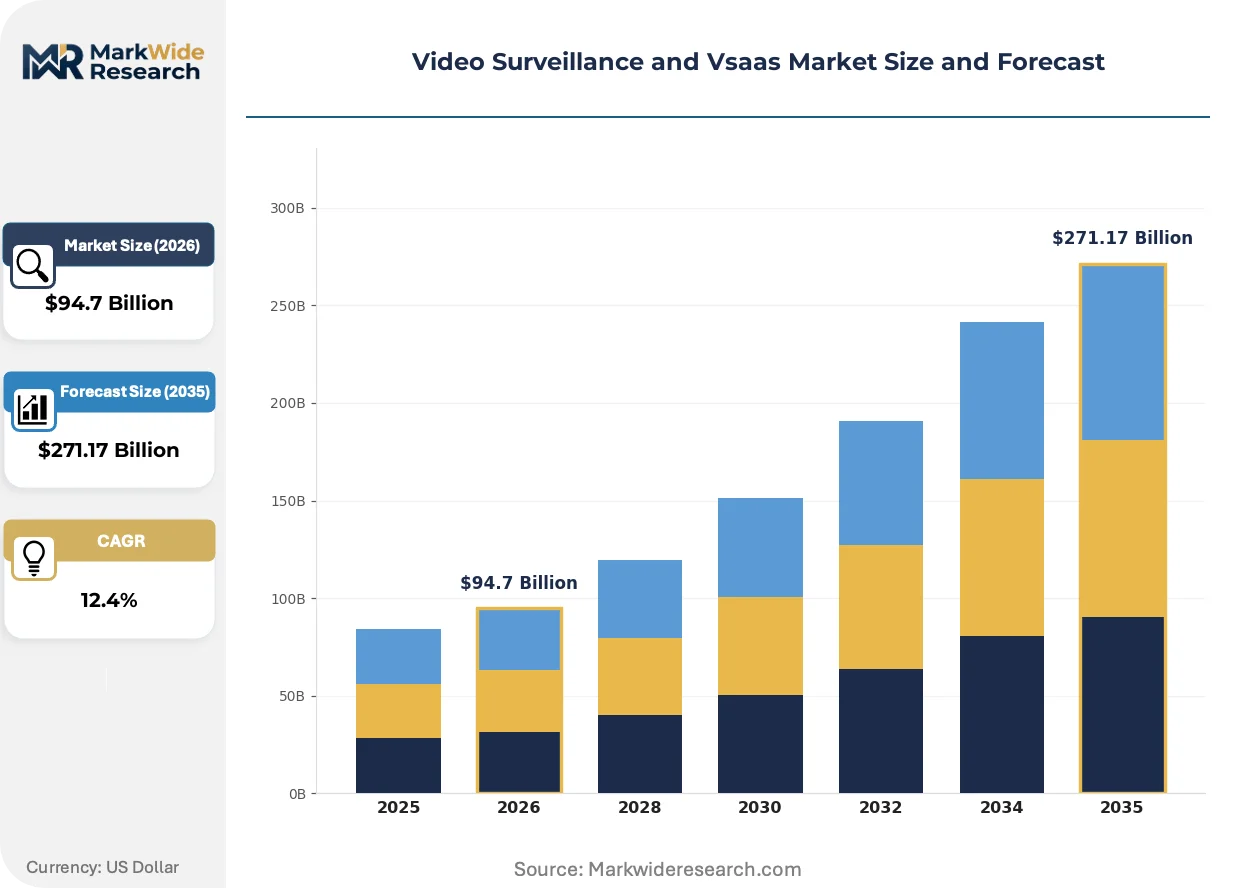
| Market Size in 2026 | $94.7 Billion |
| Market Size in 2035 | $271.17 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cameras, Storage Solutions, Software, Analytics Tools End User: Retail, Government, Transportation, Hospitality Technology: IP Surveillance, Analog Cameras, Cloud Solutions, AI Analytics Deployment Model: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Hangzhou Hikvision Digital Technology Co., Ltd., Dahua Technology Co., Ltd., Axis Communications AB, Hanwha Vision Co., Ltd., Honeywell International Inc., Motorola Solutions, Inc., Bosch Security Systems, Zhejiang Uniview Technologies Co., Ltd., Genetec Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Surveillance and Vsaas Market Strategic Shifts
Computational imaging and machine-learning inference are migrating from centralized servers to camera edge nodes, collapsing the traditional three-tier surveillance architecture into distributed intelligence networks.
Transformer-based computer vision models are supplanting convolutional neural networks for object detection and behavior analysis in high-density scenes. Airport operators and stadium security teams in Germany and Japan are piloting these architectures for crowd flow prediction. The shift is compressing hardware requirements while demanding specialized silicon that legacy camera platforms cannot accommodate.
REACH restrictions on persistent organic pollutants are phasing out certain flame-retardant plastics in camera housings sold across EU member states. Manufacturers are reformulating enclosure materials with halogen-free alternatives that maintain IP66/67 ratings. The transition is most acute in outdoor dome and bullet camera segments where thermal cycling resistance is non-negotiable.
Subscription-based VSaaS procurement is displacing capital-intensive on-premise system purchases among mid-market retail chains and multi-site logistics operators. Managed service providers are capturing recurring revenue streams that previously accrued to systems integrators. This pattern is most visible in the United Kingdom and Australia where property management firms prioritize operational expenditure predictability over ownership.
Video Surveillance and Vsaas Market Segmentation
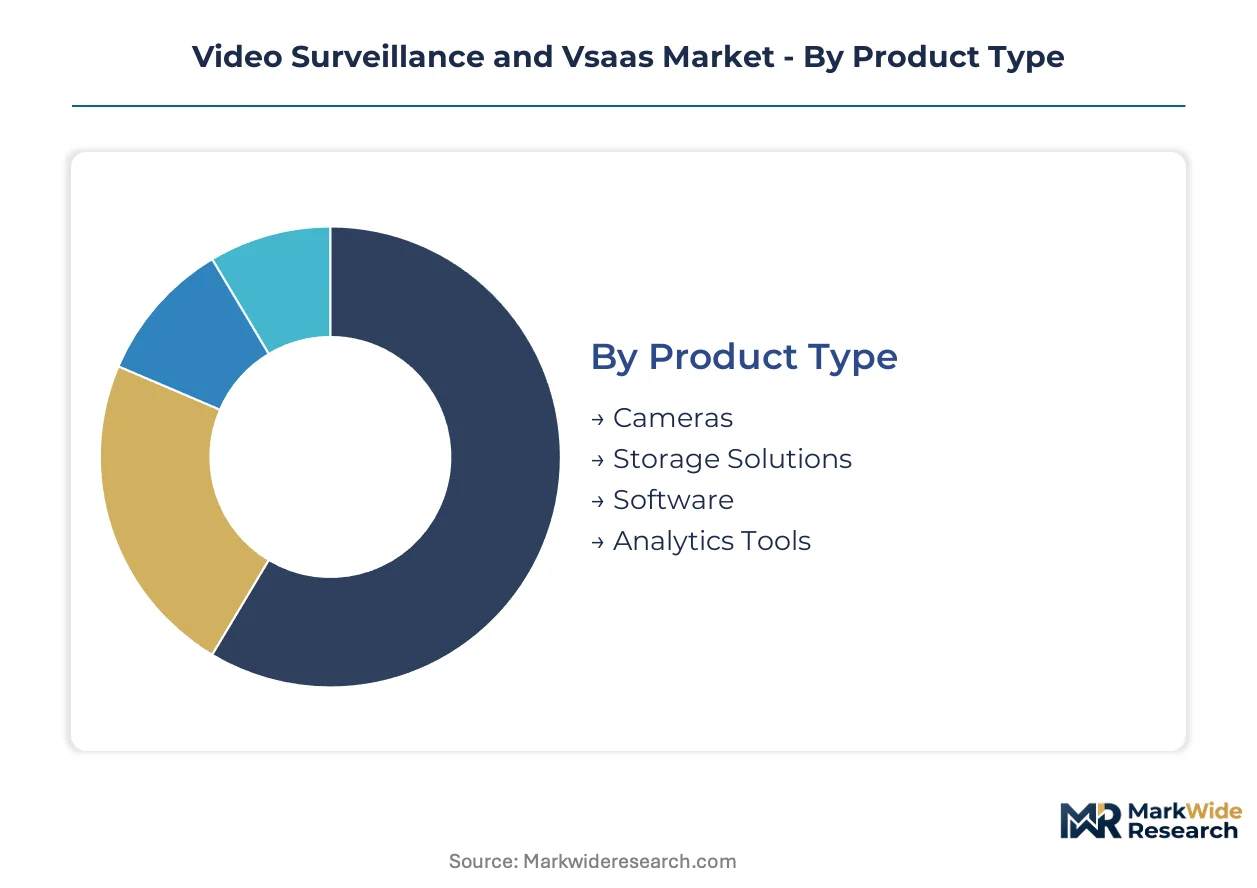
Segmentation in video surveillance and VSaaS reveals how margin pools have migrated from hardware depreciation cycles toward recurring software licensing and cloud infrastructure fees. Understanding these splits exposes where procurement authority is shifting from facilities managers to CISOs and cloud procurement teams.
Product Type:
Software and analytics concentrate the highest recurring margins, while hardware segments compete on volume and supply chain efficiency.
- Cameras:Networked devices capturing H.265-compressed video streams with edge processing capabilities. Demand clusters in Indian smart city deployments and Brazilian municipal safety programs where centralized procurement favors certified IP66-rated units. FCC equipment authorization requirements govern wireless transmission modules for US-deployed units.
- Software:Video management platforms handling multi-stream ingestion, user permission hierarchies, and forensic search indexing. Retail chains in the United Kingdom and Australia prioritize subscription-based VSaaS procurement to convert capital expenditure into predictable operational spending.
- Storage Solutions:On-premise NVR arrays and cloud object storage tiers for retention compliance. BIS certification standards shape import timelines for enterprise-grade storage deployed across South Asian infrastructure projects.
- Analytics Tools:Computer vision modules for object detection, behavior analysis, and automated alerting. GDPR and EU AI Act provisions restrict facial recognition deployment in German and French public spaces while permitting traffic flow analytics.
The dominant share belongs to Cameras, while Software is closing the gap fastest as subscription models displace perpetual licensing.
End User:
Procurement sophistication varies sharply across verticals, with government tenders demanding ISO 27001 certification while retail prioritizes operational expenditure predictability.
- Government:National and municipal agencies operating centralized command centers for public safety and traffic coordination. Indian urban development funds and Brazilian federal infrastructure budgets are channeling investment into AI-enabled camera networks with algorithmic transparency documentation.
- Retail:Multi-site chains requiring loss prevention, occupancy analytics, and frictionless investigation workflows. Mid-market operators in Australia favor managed service providers over traditional systems integrators.
- Transportation:Airports, ports, and rail operators deploying crowd flow prediction and perimeter intrusion detection. German airport operators pilot transformer-based computer vision architectures for high-density scene analysis.
- Hospitality:Hotels and entertainment venues balancing guest privacy with security coverage. GDPR purpose-limitation controls constrain analytics deployment in EU member states.
Government maintains the largest installed base, though Retail is expanding most quickly as VSaaS penetration deepens among franchise operators.
Technology:
Deployment architecture determines whether value accrues to silicon vendors, cloud hyperscalers, or specialized AI inference chip suppliers.
- IP Surveillance:Digital networked camera systems replacing coaxial analog infrastructure. European public-sector tenders under GDPR compliance mandates are accelerating replacement of legacy systems with auditable IP platforms.
- Cloud Solutions:Subscription-delivered video management eliminating on-premise server maintenance. Fragmented data sovereignty rules across Russia, China, and Vietnam force redundant in-country infrastructure builds.
- AI Analytics:Machine-learning inference for automated threat detection and operational intelligence. Edge AI inference chips reduce backhaul bandwidth requirements by 60-70 percent in bandwidth-constrained environments.
- Analog Cameras:Legacy coaxial systems persisting in cost-constrained retrofits and isolated rural deployments.
IP Surveillance holds the dominant position, yet Cloud Solutions is climbing the fastest as hybrid architectures preserve legacy investments while layering new capabilities.
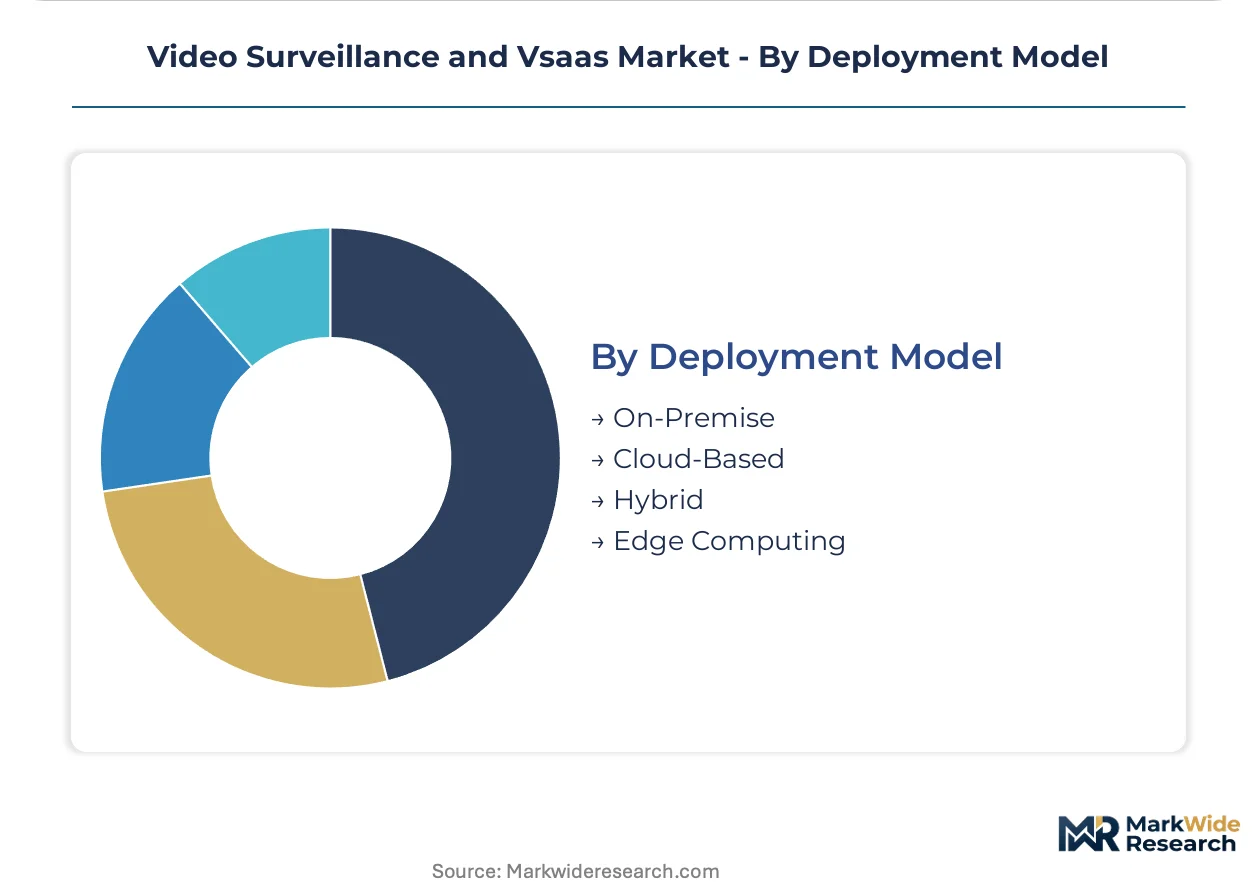
Deployment Model:
Customer technical maturity and data residency requirements dictate whether workloads remain local, distribute to edge nodes, or centralize in hyperscale facilities.
- Cloud-Based:Fully managed SaaS platforms with multi-tenant isolation and automatic feature updates. Cyber insurance underwriters increasingly mandate ISO 27001-certified systems for policy eligibility.
- Hybrid:Split architectures retaining sensitive processing on-premise while archiving to cloud tiers. This pattern dominates among German manufacturers and Japanese industrial operators with strict data classification regimes.
- Edge Computing:On-camera inference and local decision-making minimizing latency and backhaul costs. 5G private network integration enables wireless deployment in mining and agriculture where fiber trenching is prohibitive.
- On-Premise:Traditional NVR-centric systems with capital-intensive refresh cycles persisting in air-gapped critical infrastructure.
Hybrid deployments command the largest current footprint, while Cloud-Based models are gaining share fastest among mid-market buyers prioritizing operational simplicity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC equipment authorization requirements and GDPR algorithmic transparency mandates are accelerating procurement of auditable IP platforms across municipal and enterprise security deployments. National infrastructure programs in India and Brazil are channeling urban development funds into centralized video command centers. Fragmented data sovereignty rules in Russia, China, and Vietnam are forcing redundant in-country infrastructure builds.
United States
Municipal governments in Chicago and New York are deploying AI-enabled camera networks for traffic management and public safety coordination. FCC equipment authorization requirements govern wireless transmission modules in cameras deployed across federal and state infrastructure projects. Cyber insurance underwriters increasingly mandate ISO 27001-certified systems for policy eligibility in California's technology corridor.
Germany
Airport operators in Frankfurt and Munich are piloting transformer-based computer vision architectures for crowd flow prediction in high-density terminal environments. GDPR and EU AI Act provisions restrict facial recognition deployment in public spaces while permitting traffic flow analytics with algorithmic transparency documentation. Industrial operators in Baden-Württemberg favor hybrid architectures retaining sensitive processing on-premise.
India
Smart city infrastructure budgets in Mumbai and Delhi are channeling urban development funds into centralized video command centers for public safety coordination. BIS certification standards shape product compliance timelines for equipment imports across South Asian infrastructure projects. The national pharmaceutical regulator mandates specific surveillance protocols for manufacturing facility monitoring.
Brazil
Federal infrastructure budgets are accelerating procurement of IP66-rated camera units for municipal safety programs in São Paulo and Rio de Janeiro. Port security investments in Southeast Asian manufacturing corridors are outpacing local VSaaS vendor capacity. ANVISA compliance requirements influence surveillance system specifications for pharmaceutical and healthcare facility deployments.
China
Data residency mandates require local video data storage, forcing VSaaS providers to build redundant in-country infrastructure. MIIT regulations govern network security assessments for cloud-delivered video management platforms. Manufacturing clusters in Shenzhen and Hangzhou concentrate vertically integrated camera hardware production for Asia-Pacific deployments.
Video Surveillance and Vsaas Market Competitive Environment
Player mix skews toward vertically integrated hardware manufacturers and open-platform software specialists competing across subscription and perpetual licensing models. The vendor base clusters around three strategic archetypes: volume-driven camera OEMs with captive silicon sourcing, open-architecture platform providers cultivating integrator ecosystems, and cloud-native VSaaS operators capturing recurring revenue streams. Dominant competitive moves include backward integration into edge AI inference silicon and geographic expansion through compliance-certified local infrastructure builds.
Within the vertically integrated tier, Hangzhou Hikvision Digital Technology Co., Ltd. and Dahua Technology Co., Ltd. occupy positions anchored by manufacturing scale across Asia-Pacific deployments. Axis Communications AB exemplifies the open-platform archetype that sustains partner ecosystem loyalty among large-scale integrators. These three entities represent the structural poles around which competitive positioning organizes: volume efficiency, architectural openness, and subscription monetization.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Dahua Technology Co., Ltd. |
| Axis Communications AB |
| Hanwha Vision Co., Ltd. |
| Honeywell International Inc. |
| Motorola Solutions, Inc. |
| Bosch Security Systems |
| Zhejiang Uniview Technologies Co., Ltd. |
| Genetec Inc. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts for CMOS image sensors lock in both supply access and price visibility for camera OEMs, insulating procurement teams from Taiwan foundry allocation volatility while compressing margin flexibility for downstream integrators serving municipal and retail buyers.
Pricing Analysis
Certification level creates the primary spread between ISO 27001-certified VSaaS platforms and uncertified alternatives, with cyber insurance eligibility now bundling compliance costs into subscription tiers. Three-tier pricing structure across premium, standard, and economy levels segments by edge AI inference capability and data residency architecture. Cost compression in mid-market hardware stems from South Korean and Chinese sensor oversupply. Government tenders exhibit lowest price sensitivity due to mandate-driven procurement, while mid-market retail chains prioritize operational expenditure predictability over feature depth.
Supply Chain Analysis
Container availability fluctuations on Asia-Pacific trade lanes complicate inbound logistics for camera housings and edge processing modules, extending lead times for European and North American deployments. Manufacturing gravity centers on China, Taiwan, and South Korea for CMOS sensors, PCB assemblies, and AI inference silicon. Raw material dependencies span rare earth elements for optical coatings, copper for thermal management, and halogen-free flame retardants for EU-compliant enclosures. Single-source vulnerability concentrates in advanced image sensor fabrication. Distribution runs through certified systems integrators and managed service providers rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Video surveillance and VSaaS sits in early-cycle expansion as municipal smart city budgets and cyber insurance mandates accelerate replacement of depreciated analog infrastructure with auditable cloud-native platforms.
For Market Incumbents: Shield installed base relationships by accelerating ISO 27001 certification roadmaps before cyber insurance eligibility hardens into tender requirements. Deepen captive supply of edge AI inference silicon to offset South Korean foundry allocation risk. Consolidate position in hybrid deployment architectures where German and Japanese industrial operators retain sensitive processing on-premise. For New Entrants and Emerging Players: Lead with subscription-based VSaaS penetration in Indonesia and Vietnam manufacturing corridors, where port security and factory automation investments outpace local vendor capacity. Target mid-market retail chains in Australia and the United Kingdom prioritizing operational expenditure predictability. Differentiate through 5G private network integration for wireless deployment in mining and agriculture verticals. For Investors and Strategic Acquirers: Cloud-native platform specialists with multi-tenant architecture expertise represent the most defensible acquisition profile as margin pools migrate from hardware depreciation to recurring software licensing. Long-term viability hinges on data sovereignty compliance infrastructure across Russia, China, and Vietnam residency mandates. Monitor ANVISA and BIS certification timeline compression as inflection indicators for South Asian market entry windows.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 27001 Certification Acceleration | Cyber insurance eligibility converts compliance from cost center to competitive moat in government tenders. |
| Edge AI Inference Silicon Development | On-camera processing reduces backhaul bandwidth requirements for bandwidth-constrained municipal deployments. |
| Data Sovereignty Infrastructure Build | Local video data residency mandates in Russia, China, and Vietnam force redundant in-country platform investments. |
| 5G Private Network Integration | Ultra-reliable low-latency communication enables wireless camera deployment in mining and agriculture verticals. |
| Hybrid Deployment Architecture Expansion | Split architectures retain sensitive processing on-premise for German and Japanese industrial operators. |
Study Parameters
Desk research of customs filings, FCC equipment authorization databases, and municipal procurement records preceded structured interviews with municipal security directors, VSaaS platform engineers, cyber insurance underwriters, and systems integration specialists. Primary fieldwork validated secondary findings against BIS certification timelines, GDPR implementation patterns, and edge AI deployment economics. Bottom-up segment sizing triangulated against top-down infrastructure budget allocations across smart city programs.
Variance decomposition across product type, deployment model, end-user vertical, and regional regulatory cluster shaped analytical framework construction over the projection horizon. CAGRs derived from segment-level adoption curves, replacement cycle compression, and subscription revenue recognition patterns. Model inputs incorporated edge AI chip shipment data, cloud hyperscaler capex disclosures, and cyber insurance policy penetration rates by industry vertical.
Forecasts assume regulatory continuity in GDPR enforcement, EU AI Act implementation, and FCC equipment authorization requirements; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
France Surveillance Camera Market
Video Surveillance Systems
Video Surveillance Market
Video Surveillance Systems
Middle East and Africa Surveillance Analog Camera Market
Video Surveillance Systems
Wearable and Body-Worn Cameras Market
Video Surveillance Systems
Surveillance Camera Systems Market
Video Surveillance Systems
Connected Enterprise Video Surveillance Solutions Market
Video Surveillance Systems
Mexico Surveillance Analog Camera Market
Video Surveillance Systems
Asia-Pacific Surveillance Storage Market
Video Surveillance Systems
India Surveillance Analog Camera Market
Video Surveillance Systems
Concealed Weapon Detection Systems Market
Video Surveillance Systems
Night Vision System (NVS) Market
Video Surveillance Systems
Europe Video Surveillance As a Service Market
Video Surveillance Systems
Middle East and Africa Video Surveillance Market
Video Surveillance Systems
China Video Surveillance Market
Video Surveillance Systems
3D Surveillance Software Market
Video Surveillance Systems
Latin America Surveillance IP Cameras Market