
 Latin America Surveillance Camera Market | 2026-2036
Latin America Surveillance Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Surveillance Camera Market Insights
Multi-source procurement for video analytics chipsets is expanding across Latin American system integrators as supply chain resilience becomes a strategic priority. Hangzhou Hikvision Digital Technology Co. Ltd anchors regional manufacturing partnerships that reduce import dependency for large-scale government contracts. Dahua Technology competes through localized technical support networks spanning São Paulo and Mexico City distribution hubs. Bosch Security Systems differentiates via European-certified product lines that satisfy stringent data protection requirements in Chile and Argentina.
Latin America surveillance cameras encompass fixed and pan-tilt-zoom imaging devices with resolutions from two to eight megapixels, designed for continuous environmental monitoring through IP or coaxial connectivity. These systems serve commercial loss prevention, municipal law enforcement, and critical infrastructure perimeter defense across tropical and temperate climate zones. Dome configurations dominate indoor retail and banking deployments where vandal resistance and discreet positioning matter most, while bullet cameras lead exterior perimeter applications across industrial facilities and transportation corridors. Network technology is displacing analog installations fastest among government end users pursuing centralized command-and-control architectures.
Brazil's ANATEL certification mandates electromagnetic compatibility testing for all wireless surveillance equipment, creating compliance barriers for uncertified imports. Mexico's Federal Law on Protection of Personal Data imposes strict video retention and access protocols that shape product feature requirements across the region. Stakeholders must weigh cloud versus edge storage architectures against evolving national data sovereignty frameworks before committing to multi-year municipal contracts.
Market Dynamics
Network-enabled camera architectures are displacing analog infrastructure across Latin American municipal procurement, forcing integrators to restructure service portfolios around IP-based command platforms and cloud-native storage configurations.
Growth Catalysts
- Smart city mandates:Brazilian municipalities are embedding surveillance networks into traffic management and public safety modernization programs, creating sustained institutional demand for scalable monitoring infrastructure.
- Spectrum liberalization:Mexico's Federal Telecommunications Institute reforms for wireless video transmission are accelerating rural coverage expansion where coaxial cabling remains cost-prohibitive.
- AI-integrated procurement:Urban security programs in Bogotá and Medellín specify onboard analytics chipsets for real-time facial recognition and behavioral pattern detection in high-density public zones.
Market Restraints
- Import dependency concentration:Video analytics chipsets and CMOS sensors concentrate in East Asian foundries, exposing Latin American integrators to extended lead times and currency volatility.
- ANATEL certification barriers:Brazil's electromagnetic compatibility testing mandates create compliance friction for uncertified wireless equipment, delaying deployment timelines for non-established suppliers.
- Edge-to-cloud cost structures:Municipal budgets face pressure from recurring bandwidth and storage fees associated with centralized video retention architectures.
Strategic Opportunities
- Colombia's secondary cities:Cali, Barranquilla, and Cartagena lag Bogotá in surveillance density, presenting greenfield deployment opportunities for integrated security contractors.
- Edge AI convergence:On-device inference engines combined with low-power wide-area networks are enabling standalone rural installations without fiber backhaul dependency.
- Data sovereignty frameworks:Evolving national cloud localization requirements in Chile and Argentina are creating preference for regionally hosted video management platforms.
Industry Challenges
- Multi-protocol integration complexity:Municipal command centers must reconcile ONVIF, PSIA, and proprietary camera protocols within unified video management software stacks.
- Specialized technician scarcity:Network security certification programs for surveillance-specific IP configuration and cybersecurity hardening remain underdeveloped across regional technical institutes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Surveillance Camera Market |
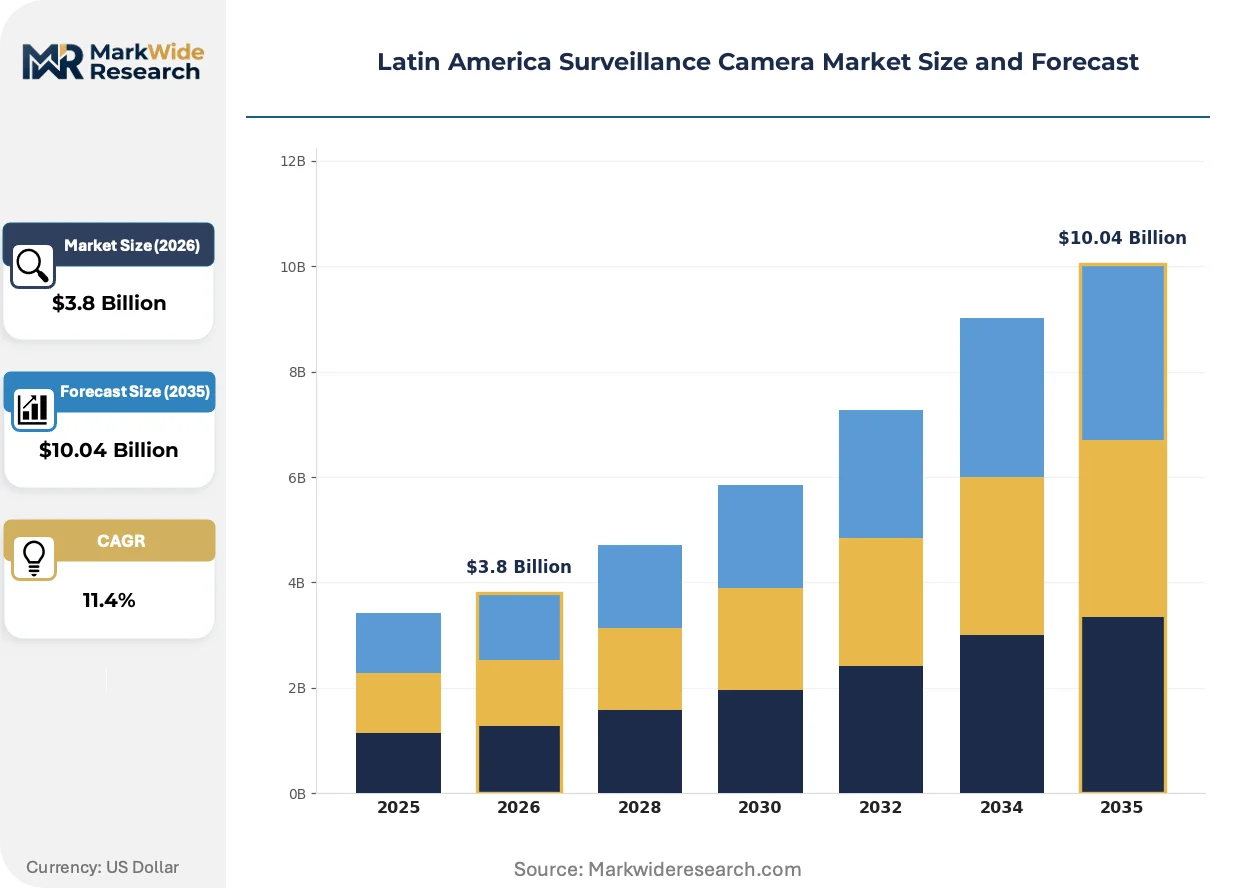
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dome, Bullet, PTZ, IP Application: Retail, Transportation, Healthcare, Public Infrastructure Technology: Analog, HD-SDI, Network, Wireless End User: Government, Commercial, Industrial, Residential |
| Companies Covered | Honeywell International Inc, Hangzhou Hikvision Digital Technology Co. Ltd, Dahua Technology, Bosch Security Systems, Panasonic Holdings Corp, Teledyne FLIR LLC, Eagle Eye Networks, Verkada Inc, Motorola Solutions Inc, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Surveillance Camera Market Trends and Innovations
Artificial intelligence inference at the camera edge is compressing response times for municipal law enforcement while reshaping how integrators architect storage and bandwidth provisioning across Latin American deployments.
On-camera GPU-accelerated processing is electrifying real-time analytics capabilities for license plate recognition and crowd density estimation. São Paulo traffic authorities are deploying these units at arterial intersections to automate violation detection without centralized server dependency. The shift is compressing infrastructure costs for mid-sized municipalities previously priced out of intelligent video networks.
Argentina's Personal Data Protection Agency is enforcing stricter biometric storage limitations on public surveillance systems, compelling vendors to implement automatic pixelation and retention-period enforcement at the firmware level. Banking and retail end-users in Buenos Aires are retrofitting existing installations to comply. The regulation is accelerating demand for privacy-by-design camera platforms with configurable masking zones.
Subscription-based video-surveillance-as-a-service is displacing capital-intensive ownership models among small commercial buyers in Mexico City and Guadalajara. Local distributors are unbundling hardware from monitoring contracts, lowering entry barriers for retail chains and warehouse operators. The pattern is most pronounced in segments with high churn sensitivity and limited in-house IT staffing.
Latin America Surveillance Camera Market Segmentation
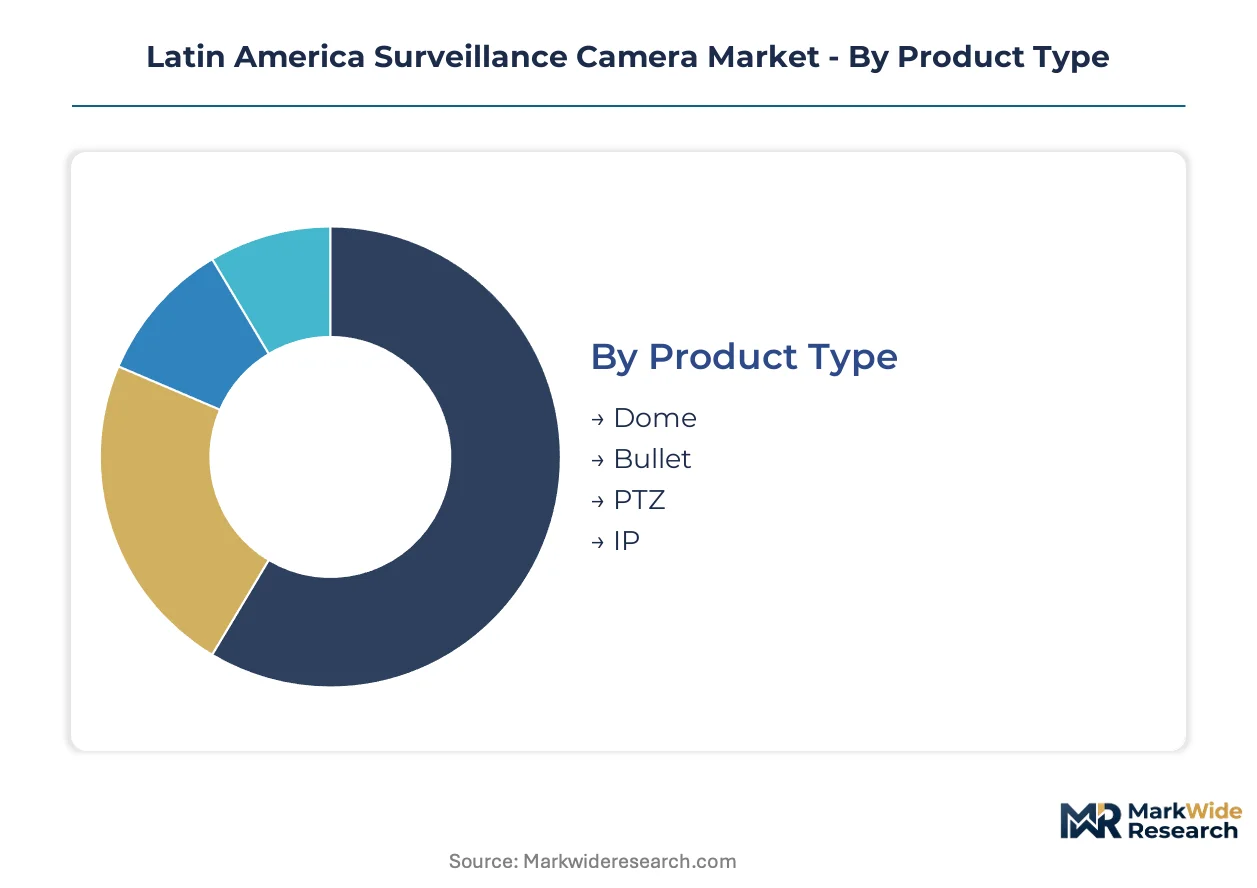
Segmentation reveals how procurement priorities diverge across Latin American surveillance deployments. Technical specifications, connectivity architectures, and end-use compliance requirements create distinct competitive battlegrounds for integrators and manufacturers.
Product Type:
Supply concentration for imaging housings and motorized assemblies shapes competitive dynamics across form factor categories.
- Dome:Vandal-resistant polycarbonate enclosures with 360-degree coverage capability suit indoor banking and retail environments. Brazilian shopping centers specify IK10 impact ratings for high-theft corridors, driving premium procurement for reinforced dome variants.
- Bullet:Weather-sealed aluminum housings with integrated IR illuminators dominate exterior perimeter applications. Mexican industrial facilities along Monterrey-Saltillo manufacturing corridors deploy these for fence-line monitoring where dust ingress resistance matters.
- PTZ:Pan-tilt-zoom mechanisms with optical zoom ranges exceeding 30x enable remote operator tracking of moving subjects across large public venues.
- IP:Network-native cameras with Power-over-Ethernet compatibility are displacing coaxial infrastructure fastest among government command center projects.
Dome configurations absorb the bulk of installed capacity; IP cameras are expanding most quickly.
Application:
Cost tier differentiation separates turnkey commercial installations from customized municipal security architectures.
- Retail:Loss prevention systems with POS integration and heat-mapping analytics concentrate in São Paulo and Mexico City shopping districts. Colombian department chains are retrofitting analog installations with network cameras to enable centralized monitoring across multi-store portfolios.
- Transportation:Ruggedized cameras with vibration resistance and wide dynamic range handle tunnel lighting transitions and platform crowd density. Buenos Aires subway authority specifications require ONVIF Profile S compliance for interoperability with legacy access control systems.
- Healthcare:Patient privacy-compliant installations with automatic masking zones serve hospital pharmacy and pediatric ward monitoring.
- Public Infrastructure:Traffic intersection and utility perimeter deployments demand ANATEL-certified wireless backhaul for Brazilian state highway contracts.
Retail applications absorb the bulk of installed capacity; transportation represents the fastest-growing trajectory.
Technology:
Volume concentration in network migration programs is accelerating obsolescence of legacy transmission standards.
- Network:IP-based cameras with H.265 compression and edge storage capabilities enable centralized video management platforms. Bogotá municipal procurement mandates PoE+ power delivery for simplified cabling in historic district retrofits where conduit space is constrained.
- Wireless:License-free spectrum cameras with mesh networking eliminate fiber trenching costs for rural Colombian oil pipeline monitoring and Argentine agricultural perimeter applications.
- Analog:Coaxial CVBS technology persists in small commercial retrofits where existing cable plant reduces capital outlay.
- HD-SDI:High-definition serial digital interface offers uncompressed video for broadcast-quality surveillance in Chilean casino and stadium deployments.
Network technology absorbs the bulk of installed capacity; wireless is gaining share fastest.
End User:
Customer type determines procurement channel structure and service contract complexity across Latin American deployments.
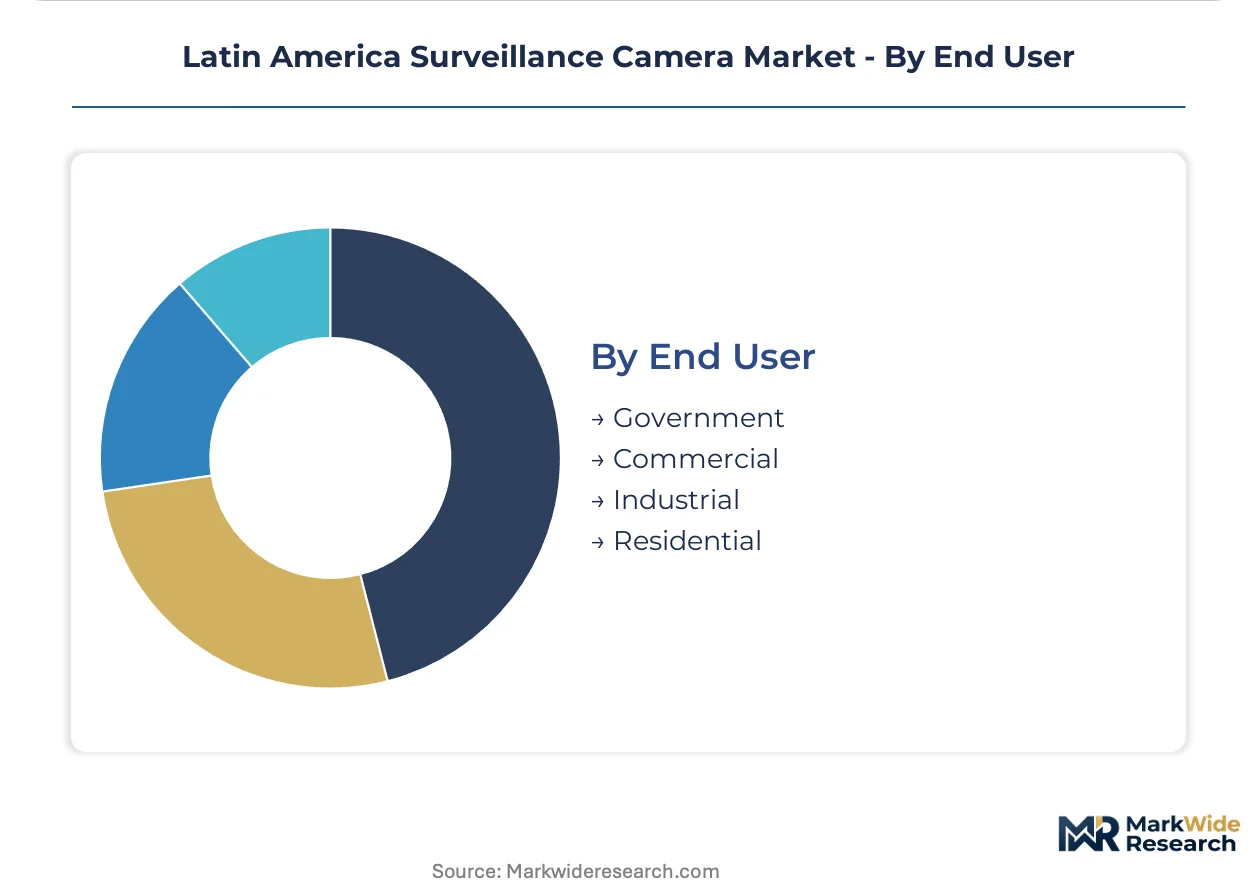
- Government:Municipal and federal tenders with multi-year maintenance clauses and data sovereignty requirements dominate large-scale procurement. ANATEL certification and local content preferences filter vendor eligibility for Brazilian smart city contracts.
- Commercial:Banking, hospitality, and corporate campus buyers prioritize vandal resistance and discreet positioning over extreme weather sealing.
- Industrial:Mining and energy facilities specify explosion-proof housings and extended temperature ranges for Atacama Desert and Amazon basin extraction operations.
- Residential:Gated community and single-family installations concentrate in upper-income São Paulo and Mexico City neighborhoods with subscription monitoring services.
Government end users absorb the bulk of installed capacity; commercial segments are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentrates in Brazilian municipalities pursuing smart city modernization, with secondary demand emerging from Mexican spectrum reforms and Colombian urban security programs. ANATEL certification requirements and data sovereignty frameworks reshape competitive eligibility across national markets.
Brazil
São Paulo and Rio de Janeiro municipalities drive network-enabled camera deployment for traffic management and public safety command centers. ANATEL mandates electromagnetic compatibility testing for all wireless surveillance equipment, filtering vendor participation in federal tenders. Minas Gerais state highway contracts specify certified wireless backhaul for perimeter monitoring along industrial corridors.
Mexico
Mexico City and Guadalajara retail chains accelerate subscription-based video-surveillance-as-a-service adoption among small commercial buyers. Federal Telecommunications Institute spectrum reforms for wireless video transmission enable faster rural coverage expansion where fiber trenching costs are prohibitive. Monterrey-Saltillo manufacturing corridors deploy weather-sealed bullet cameras for fence-line monitoring in dust-prone industrial zones.
Colombia
Bogotá and Medellín lead municipal investment in AI-integrated surveillance infrastructure with onboard analytics chipsets for real-time facial recognition. Cali, Barranquilla, and Cartagena present greenfield deployment opportunities with lower existing surveillance density. Urban security modernization programs specify PoE+ power delivery for historic district retrofits where conduit space is constrained.
Argentina
Buenos Aires banking and retail end-users retrofit existing installations to comply with Personal Data Protection Agency biometric storage limitations. Automatic pixelation and retention-period enforcement at the firmware level accelerate demand for privacy-by-design camera platforms. Subway authority specifications require ONVIF Profile S compliance for interoperability with legacy access control systems.
Chile
Santiago casino and stadium deployments specify HD-SDI broadcast-quality surveillance with uncompressed video transmission. European-certified product lines satisfy stringent data protection requirements in municipal procurement. Atacama Desert mining and energy facilities specify explosion-proof housings with extended temperature ranges for extraction operations.
Latin America Surveillance Camera Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers establish localized technical support networks and regional manufacturing alliances. The vendor base stratifies across three tiers: East Asian technology conglomerates with captive chipset supply, European security specialists with certified compliance portfolios, and North American cloud-native entrants with subscription service models. Competitive positioning hinges on ANATEL certification attainment, data sovereignty-aligned cloud architectures, and edge AI inference capabilities.
Among East Asian technology conglomerates, Hangzhou Hikvision Digital Technology Co. Ltd and Dahua Technology exemplify the manufacturing partnership archetype reducing import dependency for large-scale government contracts. Bosch Security Systems occupies a position within the European-certified tier, while Eagle Eye Networks and Verkada Inc represent the cloud-native subscription model disrupting traditional ownership structures among small commercial buyers.
| Leading Market Players |
|---|
| Honeywell International Inc |
| Hangzhou Hikvision Digital Technology Co. Ltd |
| Dahua Technology |
| Bosch Security Systems |
| Panasonic Holdings Corp |
| Teledyne FLIR LLC |
| Eagle Eye Networks |
| Verkada Inc |
| Motorola Solutions Inc |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between ANATEL-compliant wireless equipment and uncertified imports manifests in both pricing premiums and supply chain eligibility. Brazilian federal tenders filter out non-certified suppliers, compressing margins for vendors absorbing electromagnetic compatibility testing costs while granting pricing power to established certification holders.
Pricing Analysis
Volume-vs-margin split separates municipal bulk procurement from subscription-based commercial monitoring services. Three-tier pricing structure across premium certified, standard network-native, and economy analog-retrofit levels tracks certification investment and after-sales bundling intensity. Cost compression in the economy tier intensifies because currency volatility inflates import-dependent chipset costs. Small commercial buyers in Mexican retail corridors exhibit highest price sensitivity; government command-center integrators with multi-year maintenance clauses show lowest.
Supply Chain Analysis
Reverse-logistics flows for edge-AI camera refurbishment and firmware-upgraded legacy units are emerging as Latin American distributors build technical service capacity. Component supply concentrates in Taiwan, South Korea, and China for CMOS sensors and video analytics chipsets. Raw material dependencies span rare earth elements for lens coatings, copper for PoE cabling, and polycarbonate resin for vandal-resistant housings. Single-source vulnerability in East Asian foundries exposes integrators to extended lead time volatility. Distribution runs through São Paulo and Mexico City technical support hubs serving government and commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as players pursue captive supply of video analytics chipsets to reduce import dependency and currency exposure.
For Market Incumbents: Hedge against East Asian supply concentration by qualifying secondary chipset sources in Taiwan and South Korea while deepening firmware development in Brazilian engineering centers. ANATEL certification moats defend against low-cost entrants, but cloud-native subscription competitors threaten ownership-model margins in Mexico's commercial segment. For New Entrants and Emerging Players: Capture greenfield deployment opportunities in Colombia's secondary cities—Cali, Barranquilla, and Cartagena—where surveillance density lags Bogotá and procurement barriers remain lower. Edge-AI convergence for rural standalone installations offers the most penetrable application. A go-to-market angle anchored to low-power wide-area network compatibility bypasses fiber backhaul requirements that disadvantage established players. For Investors and Strategic Acquirers: Re-rating potential sits with regional cloud-hosting platform operators given evolving data sovereignty frameworks in Chile and Argentina. Long-term viability in this market hinges on compliance architecture adaptability rather than hardware scale alone. Acquisition targets should display ANATEL certification attainment plus localized technical support networks. The signal to watch is municipal tender language shifting from capital expenditure ownership toward video-surveillance-as-a-service recurring revenue models.| Strategic Initiative | Industry Significance |
|---|---|
| ANATEL Certification Investment | Unlocks Brazilian federal and state-level procurement eligibility for wireless surveillance equipment. |
| Edge AI Chipset Partnership | Enables onboard inference for facial recognition without centralized server dependency in Bogotá deployments. |
| Cloud-Native Platform Launch | Captures subscription revenue from small commercial buyers in Mexico City retail corridors. |
| Regional Manufacturing Alliance | Reduces import dependency and currency exposure for large-scale Colombian municipal contracts. |
| Privacy-by-Design Firmware Development | Addresses Argentina's biometric storage limitations through automatic pixelation and retention enforcement. |
Research Methodology
Independent corroboration across municipal procurement officers, network security integrators, and regional distributor technical directors underwrites the qualitative findings. Primary fieldwork encompassed conversations with ANATEL certification consultants, smart city program managers in São Paulo and Bogotá, and cloud platform engineers at subscription-based monitoring providers. Secondary validation drew from ANATEL regulatory filings, IFT spectrum allocation records, Colombian national procurement databases, and customs import data for surveillance equipment categories. Bottom-up demand modeling triangulated against top-down market sizing from government budget disclosures.
Rate-of-change decomposition across the projection horizon separates network technology displacement velocity from analog obsolescence patterns. Segmentation dimensions modeled include product form factor, connectivity architecture, end-use application, and national regulatory cluster. CAGRs were derived from installed base growth rates adjusted for technology transition timing. Forecast inputs incorporated municipal smart city budget trajectories, spectrum liberalization implementation schedules, and edge-AI chipset cost curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to East Asian supply chain disruptions and currency volatility against the real and peso. Forecasts reflect documented assumptions regarding government procurement continuity and data sovereignty enforcement intensity. Practitioners should monitor IFT spectrum auction results and ANATEL certification backlog indicators for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Surveillance Camera Systems Market
Video Surveillance Systems
Mexico Surveillance IP Camera Market
Video Surveillance Systems
Middle East and Africa Surveillance Analog Camera Market
Video Surveillance Systems
People Counting System Market
Video Surveillance Systems
Integrated Video Surveillance Systems Market
Video Surveillance Systems
Italy Video Surveillance Market
Video Surveillance Systems
Middle East and Africa Surveillance IP Cameras Market
Video Surveillance Systems
Latin America Surveillance IP Cameras Market
Video Surveillance Systems
Europe Surveillance IP Camera Market
Video Surveillance Systems
Latin America Video Surveillance Market
Video Surveillance Systems
Camera Alarm System Market
Video Surveillance Systems
Europe Video Surveillance Systems Market
Video Surveillance Systems
Gunshot Detection System Market
Video Surveillance Systems
US Video Surveillance Market
Video Surveillance Systems
3D Surveillance Software Market
Video Surveillance Systems
Smart Home Security Camera Market