
 Under-Vehicle Surveillance Market | 2026-2036
Under-Vehicle Surveillance Market Size, Share, and Industry Trends Forecast 2026-2036
Under-Vehicle Surveillance Market Analysis
The performance gap between military-grade fixed installations and entry-level portable units is repositioning vendor priorities across the Under-Vehicle Surveillance landscape. Robert Bosch GmbH leverages its automotive sensor heritage to anchor high-reliability embedded platforms for OEM integration. Hangzhou Hikvision Digital Technology Co. Ltd. competes aggressively on camera-based architectures with manufacturing scale that undercuts Western assembly costs. Thales Group differentiates through dual-use technology transfer from defense to civilian checkpoint applications.
Under-vehicle surveillance encompasses sensor arrays, imaging hardware, and software analytics designed to detect explosives, contraband, or structural anomalies beneath vehicles at speeds ranging from stationary inspection to 30 mph drive-through operation. Fixed systems dominate revenue due to permanent border crossings and embassy installations requiring 24/7 operational readiness, while mobile systems represent the fastest-expanding segment as tactical military units demand rapid-deploy checkpoint capability. Camera-based technology leads unit shipments though radar-based alternatives are gaining traction in dusty or low-visibility environments where optical performance degrades.
The EU AI Act and CE marking requirements are reshaping algorithmic transparency standards for automated threat-detection software sold in Europe, while FAA security directives govern airport perimeter implementations in the United States. NHTSA and ISO standards increasingly intersect as automotive OEMs explore embedded under-vehicle monitoring for autonomous vehicle safety verification. Stakeholders must evaluate how divergent certification timelines across regulatory jurisdictions will affect product roadmaps and regional market entry sequencing.
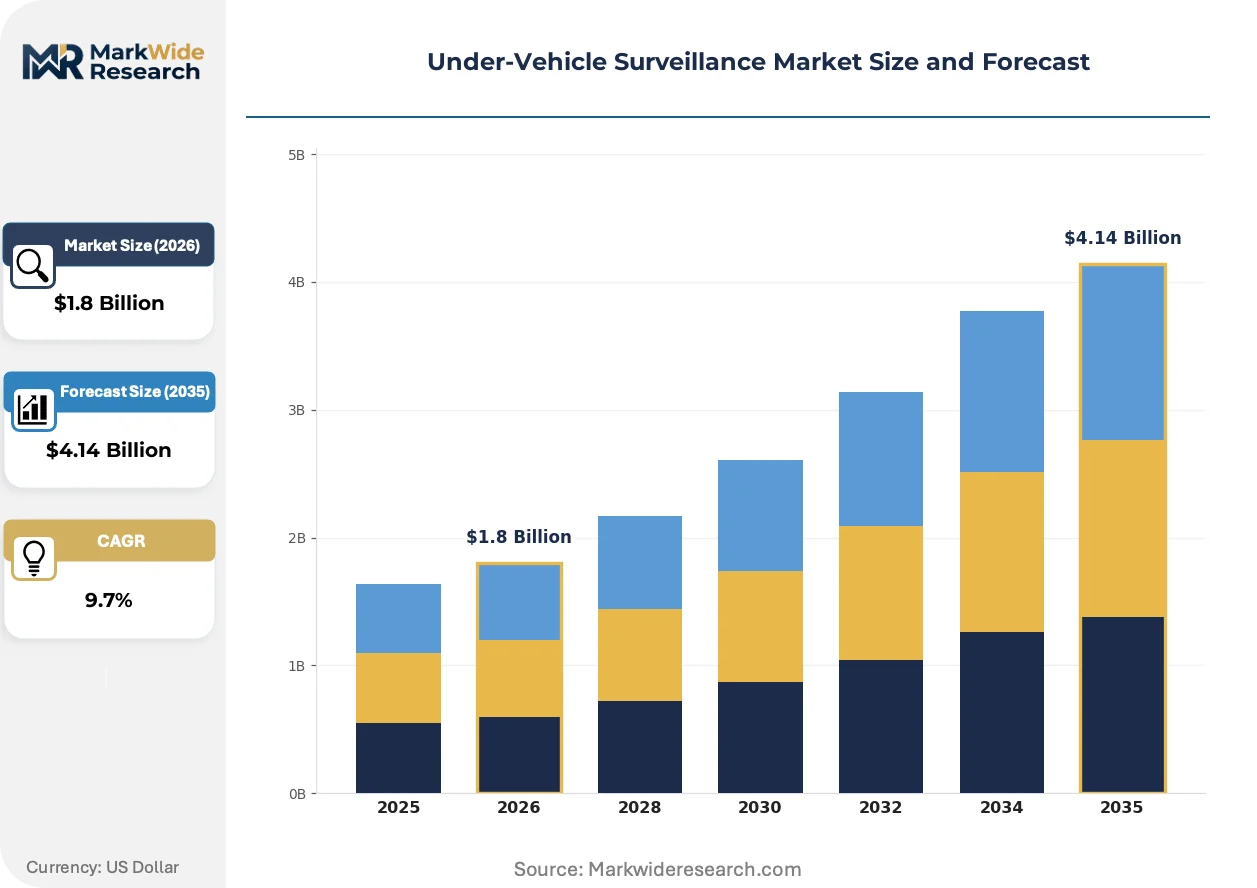
Market Dynamics
The divergence between legacy camera-based architectures and emerging multi-sensor fusion platforms is fragmenting procurement standards across border security, military checkpoints, and critical infrastructure protection. Buyers now face technical debt decisions as regulatory bodies mandate algorithmic auditability while operational users demand sub-second threat classification.
Growth Catalysts
- EU AI Act compliance mandates:Automated threat-detection systems sold in Europe must now meet algorithmic transparency standards, forcing vendors to invest in explainable AI architectures that command premium positioning.
- Drive-through inspection speeds:Border agencies in Germany and the United States are replacing stationary gantries with 30 mph capable systems, expanding addressable checkpoint throughput by an order of magnitude.
- Explosive trace detection convergence:Chemical sensors from defense programs are migrating into civilian under-vehicle platforms, creating dual-use procurement channels that accelerate technology maturation.
Market Restraints
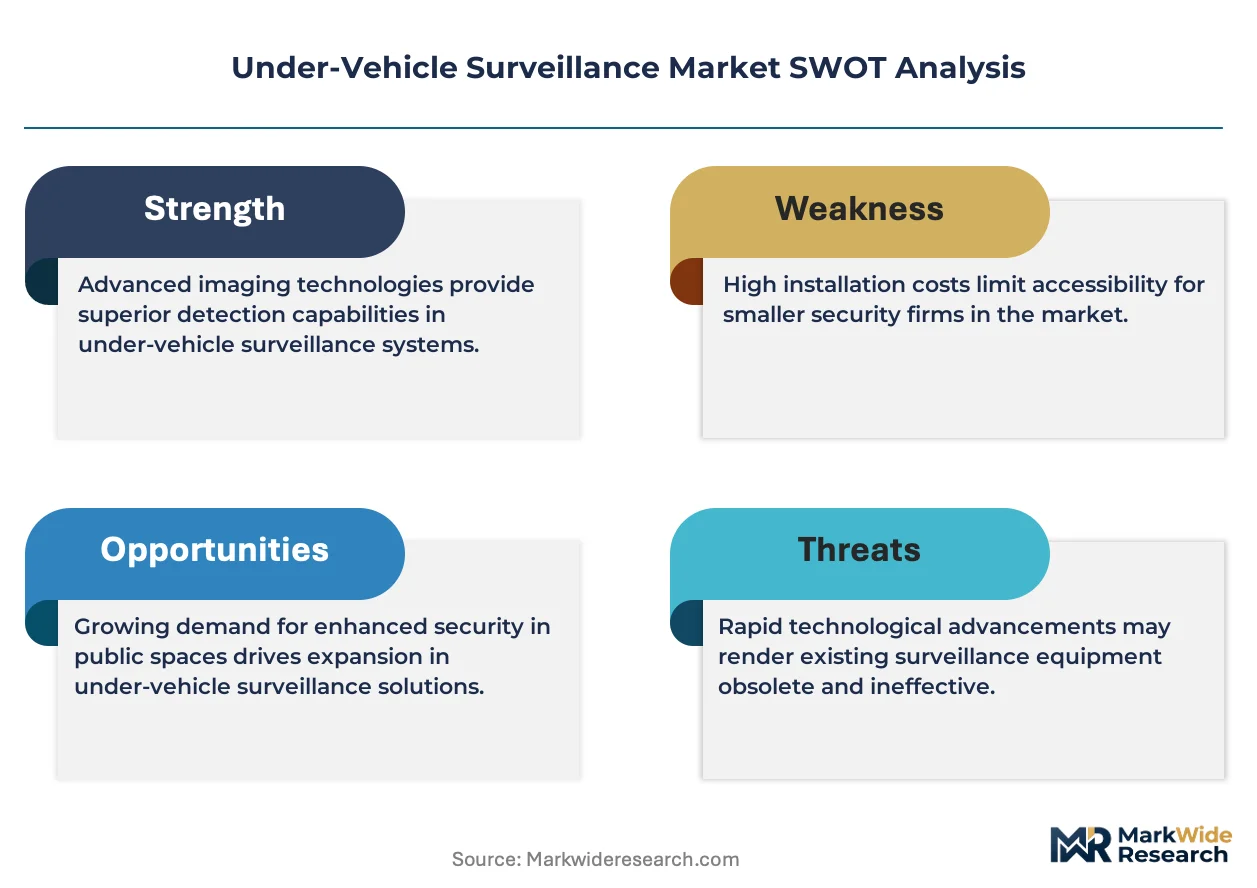
- Optical component supply concentration:High-resolution line-scan cameras rely on sensor fabrication concentrated in East Asian foundries, exposing Western system integrators to geopolitical supply disruptions.
- Radar subsystem cost structure:Millimeter-wave arrays for all-weather operation remain prohibitively expensive for municipal police budgets, constraining penetration below the federal agency tier.
- CE marking timeline friction:The EU's machinery directive and AI Act certification processes impose 18-24 month approval cycles that delay product launches relative to less regulated jurisdictions.
Strategic Opportunities
- India critical infrastructure expansion:Airport Authority of India procurement for 75+ greenfield terminals creates first-mover advantage for vendors establishing local assembly partnerships.
- Autonomous vehicle verification:NHTSA and ISO standards convergence is opening embedded under-vehicle monitoring for pre-deployment safety validation, a greenfield application distinct from security screening.
- Software-as-a-service threat libraries:Cloud-delivered signature updates are displacing five-year hardware refresh cycles, enabling recurring revenue models in installed base markets.
Industry Challenges
- Multi-sensor calibration expertise:Fusing camera, radar, and chemical detection outputs requires rare cross-disciplinary engineering talent that vendors compete aggressively to secure.
- Legacy analog infrastructure integration:Decades-old checkpoint wiring and power standards in established border crossings impose retrofit complexity that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Under-Vehicle Surveillance Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Systems, Mobile Systems, Portable Systems, Integrated Systems Technology: Camera-based, Radar-based, Lidar-based, Acoustic Sensors End User: Government, Military, Law Enforcement, Commercial Installation: Ground Installations, Portable Installations, Embedded Installations, Temporary Installations |
| Companies Covered | Robert Bosch GmbH, Continental AG, Magna International, DENSO Corporation, Honeywell Security Group, Hangzhou Hikvision Digital Technology Co. Ltd., Delphi Automotive PLC, Rapiscan Systems, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Under-Vehicle Surveillance Market Emerging Trajectories
Sensor fusion architectures are displacing single-modality systems as the technical baseline for high-assurance checkpoints. This shift compresses competitive differentiation around software analytics while commoditizing imaging hardware.
Multi-spectral imaging is integrating short-wave infrared capture with conventional visible-spectrum analysis to detect thermal anomalies and material composition beneath vehicle undercarriages. Military procurement programs in the United States and Germany are driving adoption, with Thales Group and Robert Bosch GmbH embedding these capabilities into next-generation fixed installations. The technology is integrating previously separate explosive detection and structural integrity verification into unified inspection workflows, reducing lane occupancy time and personnel requirements.
The EU AI Act's risk classification framework is mandating human-in-the-loop verification for automated threat alerts at Category 2 checkpoints, effectively capping full autonomy penetration in European aviation and border applications. System vendors must now architect dual-mode operation that satisfies both automated throughput targets and regulatory override requirements. Germany's Federal Police and France's border control agencies are piloting hybrid configurations where AI pre-screens anomalies for human confirmation, establishing a template likely to propagate across Schengen Area implementations.
Buyers are consolidating vendor relationships around integrated platform providers capable of delivering hardware, software, and sustained threat-signature updates under unified service contracts. Municipal and regional police departments in the United States are abandoning point-product procurement in favor of multi-year performance agreements that transfer obsolescence risk to suppliers. This reconfiguration favors vendors with captive software development and cloud infrastructure, compressing margins for hardware-only competitors in the North American municipal segment.
Under-Vehicle Surveillance Market Segmentation
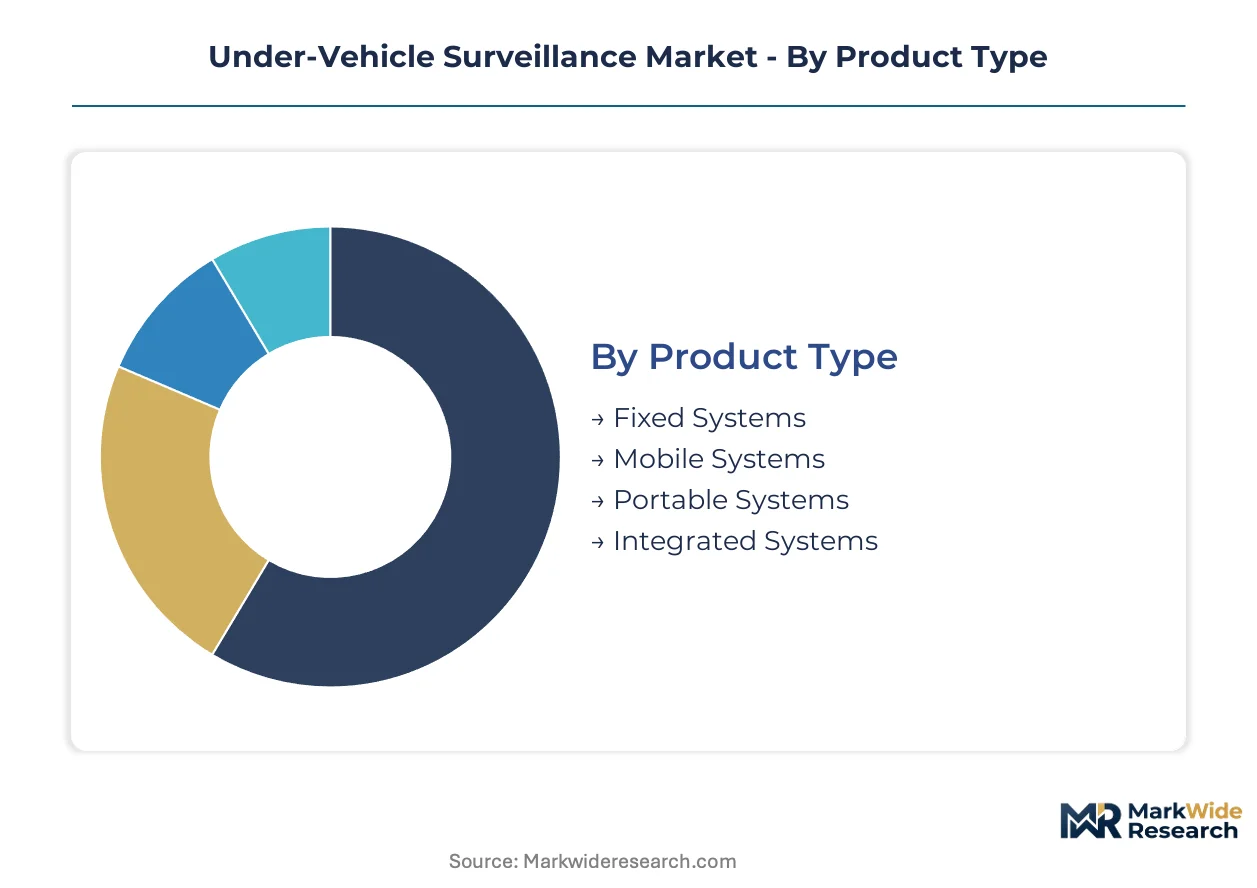
Procurement decisions in under-vehicle surveillance hinge on operational tempo, environmental conditions, and integration complexity. Buyers evaluate trade-offs between throughput speed, detection fidelity, and lifecycle maintenance burden across distinct product configurations.
Product Type:
Capital allocation intensity and deployment permanence drive buyer selection across system mobility tiers.
- Fixed Systems:Permanent gantry or in-ground installations deliver 24/7 operational readiness at border crossings and embassy perimeters. Demand concentrates in Germany and the United States where federal agencies mandate hardened infrastructure for critical checkpoint nodes. FAA security directives and EU anti-terrorism mandates accelerate replacement cycles for legacy analog installations.
- Mobile Systems:Vehicle-mounted or trailer-deployed platforms enable rapid repositioning for tactical military units and emergency response scenarios. Military procurement programs in the United States and Germany are expanding orders for 30 mph drive-through capable units that compress lane occupancy time. These configurations command premium positioning due to integrated power generation and environmental hardening.
- Portable Systems:Man-portable units suit temporary checkpoints and low-throughput municipal applications.
- Integrated Systems:Multi-sensor fusion architectures combine imaging, radar, and chemical detection in unified platforms.
Volume sits with Fixed Systems; growth tilts toward Mobile Systems.
Technology:
Environmental operating conditions and threat signature requirements determine sensor modality selection.
- Camera-based:Line-scan and area-array cameras dominate unit shipments due to mature supply chains and sub-millimeter resolution capability. East Asian sensor fabrication concentration exposes Western integrators to geopolitical supply disruptions. Optical performance degrades in dusty or low-visibility environments, constraining deployment latitude.
- Radar-based:Millimeter-wave arrays penetrate dust, rain, and darkness where optical systems fail. Federal agency budgets in the United States absorb unit costs that exclude municipal police departments. Thales Group and defense contractors are transferring military radar architectures into civilian checkpoint applications.
- Lidar-based:Laser ranging systems generate precise three-dimensional undercarriage maps for anomaly detection.
- Acoustic Sensors:Vibration and sound signature analysis detects structural voids or concealed compartments.
Camera-based platforms anchor current procurement volumes; radar-based alternatives are climbing the fastest as all-weather reliability becomes non-negotiable.
End User:
Budget authority tiers and threat assessment protocols create distinct procurement specifications across buyer categories.
- Government:Border control agencies and aviation authorities mandate certified systems with algorithmic auditability under EU AI Act and FAA directives. Germany's Federal Police and France's border control agencies are piloting hybrid human-in-the-loop configurations that satisfy automated throughput targets alongside regulatory override requirements.
- Military:Tactical units demand rapid-deploy capability with hardened environmental specifications. Procurement channels accelerate technology maturation through dual-use transfer from defense programs to civilian platforms.
- Law Enforcement:Municipal and regional police departments are consolidating vendor relationships around multi-year performance agreements that transfer obsolescence risk to suppliers.
- Commercial:Private facility operators prioritize cost-optimized configurations for parking structure and logistics yard monitoring.
Government agencies command the largest committed budgets; military end users are gaining share fastest through expeditionary checkpoint modernization programs.
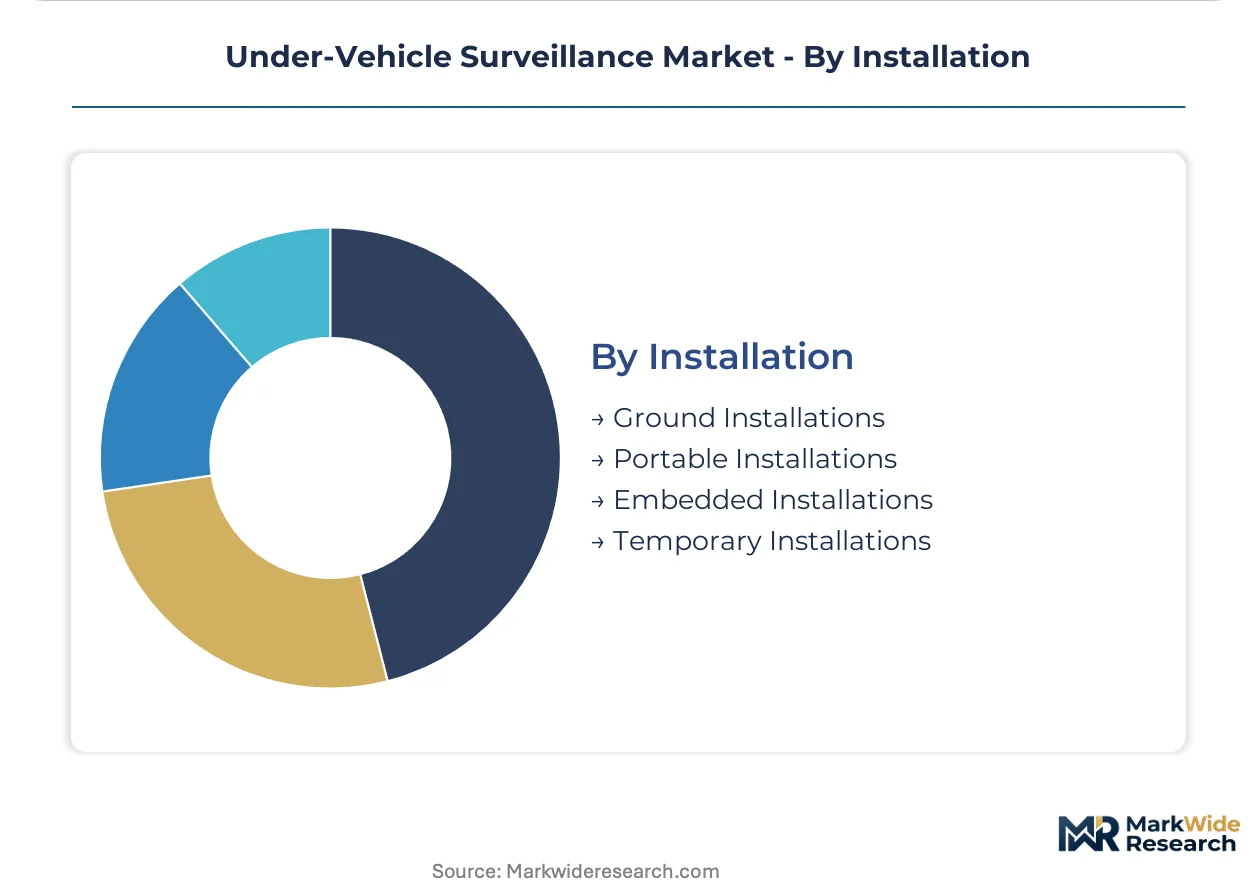
Installation:
Physical infrastructure constraints and deployment duration determine mounting architecture selection.
- Ground Installations:In-ground or surface-mounted systems dominate permanent border crossings and aviation perimeters. Decades-old checkpoint wiring and power standards in established crossings impose retrofit complexity that extends deployment timelines for modern sensor arrays.
- Portable Installations:Rapid-deploy configurations suit temporary checkpoints and emergency response scenarios. Demand is expanding among tactical military units requiring expeditionary lane establishment without permanent civil works.
- Embedded Installations:Integration into vehicle platforms or roadway infrastructure supports autonomous vehicle safety verification under converging NHTSA and ISO standards.
- Temporary Installations:Short-duration deployments accommodate event security and construction zone monitoring.
Ground Installations retain the largest installed base; Embedded Installations are expanding most quickly through automotive OEM safety system integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors the industry's sensor technology corridor, with Bosch and Continental engineering centers driving fixed-system innovation for border and aviation applications. Federal procurement in Germany and the United States absorbs the majority of premium-tier installations, while India's airport expansion and China's manufacturing scale reshape volume distribution.
United States
FAA security directives mandate under-vehicle inspection at commercial aviation perimeters, accelerating replacement of legacy analog gantries at major hubs. NHTSA standards convergence with ISO frameworks is embedding surveillance capability into autonomous vehicle verification protocols. Dallas-Fort Worth and Atlanta airport authorities are piloting 30 mph drive-through systems that compress lane occupancy time.
Germany
Federal Police procurement for Schengen border crossings demands algorithmic auditability under EU AI Act risk classification frameworks. KBA technical standards intersect with machinery directive compliance timelines that extend certification cycles. Bavaria's Munich Airport and Baden-Württemberg's Stuttgart logistics corridor are deploying hybrid human-in-the-loop configurations for throughput optimization.
China
MIIT standards for intelligent transportation infrastructure are integrating under-vehicle monitoring into smart checkpoint networks along strategic corridors. GB certification requirements and SAMR quality frameworks govern domestic procurement specifications. Hangzhou's Hikvision manufacturing base and Shenzhen's component fabrication clusters supply camera modules that dominate global unit shipments.
India
Airport Authority of India procurement for 75-plus greenfield terminals under PLI scheme incentives is creating first-mover opportunities for system integrators. BIS certification and DGFT import regulations are steering vendor selection toward local assembly partnerships. Delhi-NCR and Mumbai's Chhatrapati Shivaji International are prioritizing embedded installations for pre-security zone throughput.
United Kingdom
Home Office border modernization programs are replacing aging Channel crossing infrastructure with multi-sensor fusion platforms. CE marking alignment post-Brexit maintains EU AI Act algorithmic transparency requirements for threat-detection software. London Heathrow and the Port of Dover are consolidating vendor relationships around unified service contracts that transfer obsolescence risk.
Under-Vehicle Surveillance Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification complexity and software integration depth, with federal agency procurement concentrating volume among tier-one system integrators. The vendor base stratifies between automotive heritage conglomerates, defense technology transfer specialists, and scale-driven camera manufacturers. Three archetypes dominate: sensor-heritage automotive suppliers, dual-use defense contractors, and vertically integrated imaging hardware producers. Competitive dynamics center on M&A for algorithmic capability and strategic partnerships for local certification compliance.
Among German automotive-heritage conglomerates, Robert Bosch GmbH and Continental AG exemplify the premium-tier archetype through embedded platform engineering for OEM integration. Hangzhou Hikvision Digital Technology Co. Ltd. occupies a position within the scale-driven imaging tier, leveraging manufacturing concentration to undercut Western assembly economics. Thales Group represents the defense-transfer archetype, anchoring dual-use technology migration from military checkpoint programs into civilian aviation and border applications.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Magna International |
| DENSO Corporation |
| Honeywell Security Group |
| Hangzhou Hikvision Digital Technology Co. Ltd. |
| Delphi Automotive PLC |
| Rapiscan Systems |
| Thales Group |
| Others |
Supply Flow & Price Mechanics
Captive sensor fabrication in East Asian foundries anchors both component availability and pricing power for Western system integrators facing EU AI Act compliance costs. This integration pattern concentrates margin pressure on vendors lacking backward control over imaging hardware while rewarding those with in-house algorithm development.
Pricing Analysis
Value-based pricing tied to checkpoint throughput and threat-detection yield anchors vendor positioning across the Under-Vehicle Surveillance landscape. Three-tier pricing structure across premium, standard, and economy levels separates federal agency specifications from municipal police budgets, with certification grade under EU AI Act and FAA directives commanding substantial premiums. Cost compression in the municipal tier is intensifying because Hangzhou Hikvision's manufacturing scale undercuts Western assembly economics. Federal agencies exhibit the lowest price sensitivity due to mandate-driven procurement, while commercial facility operators resist premium positioning.
Supply Chain Analysis
Engineering talent scarcity in Germany and the United States constrains production scaling for multi-sensor fusion architectures despite strong demand signals. Component supply concentrates in China's sensor fabrication clusters and South Korea's semiconductor foundries, with high-resolution line-scan cameras and millimeter-wave radar modules drawing from these geographies. Single-source vulnerability in East Asian optical component supply exposes Western integrators to geopolitical disruption. Distribution runs through defense procurement channels and aviation security integrators with established certification relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Under-Vehicle Surveillance Market functions as a cost-of-compliance arena where EU AI Act algorithmic auditability requirements erect formidable barrier-to-entry moats for vendors lacking sustained certification investment capacity.
For Market Incumbents: Anchor defensive positioning through captive software development and cloud infrastructure ownership that transfers obsolescence risk to buyers under multi-year performance agreements. Consolidate around integrated platform provision to compress margins for hardware-only competitors. Deepen backward integration into sensor arrays to mitigate East Asian supply concentration exposure. For New Entrants and Emerging Players: Launch via SaaS-delivered threat signature libraries that displace five-year hardware refresh cycles in installed base markets. Target India's Airport Authority of India procurement for greenfield terminals where local assembly partnerships satisfy PLI scheme incentives and BIS certification requirements. Pursue embedded automotive OEM integration for autonomous vehicle safety verification as a greenfield application distinct from saturated security screening. For Investors and Strategic Acquirers: Exit pathways concentrate in dual-use defense technology transfer specialists with proven civilian checkpoint migration track records. Long-term viability hinges on sustained R&D commitment spanning the decade ahead as sensor fusion architectures commoditize imaging hardware. Monitor CE marking timeline friction as an inflection indicator—vendors demonstrating compressed 12-month certification cycles signal superior regulatory navigation capability.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Investment | Algorithmic transparency certification under EU AI Act secures premium positioning in Schengen border and aviation procurement. |
| Local Assembly Partnership Formation | India PLI scheme-aligned manufacturing satisfies BIS and DGFT requirements for Airport Authority of India terminal deployments. |
| SaaS Threat Library Development | Cloud-delivered signature updates displace hardware refresh cycles and enable recurring revenue in installed base markets. |
| Multi-Sensor Fusion R&D Expansion | Integrated camera-radar-chemical platforms compress competitive differentiation around software analytics capabilities. |
| Automotive OEM Integration Program | NHTSA and ISO convergence opens embedded under-vehicle monitoring for autonomous vehicle safety verification protocols. |
Methodological Framework
Independent corroboration across primary interviews with border security procurement officers, aviation authority technical directors, and defense program managers, combined with secondary validation through FAA security directive filings, EU AI Act regulatory texts, and customs trade data, underwrites the qualitative findings. Bottom-up segmentation modeling and top-down macroeconomic anchoring were cross-checked for consistency.
Comparable-period anchoring to historical procurement cycles and replacement timelines structured the forecast window across the analysis window. Segmentation dimensions modeled include system mobility tier, sensor modality, end-user budget authority, and regional regulatory cluster. CAGRs were derived from installed base expansion rates and technology substitution patterns, with drive-through inspection speed capabilities and algorithmic auditability requirements as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for radar-based all-weather systems displacing camera dominance would alter the outlook. Forecasts reflect assumptions regarding EU AI Act implementation timelines and defense-to-civilian technology transfer velocity. Material deviation in CE marking approval cycles or East Asian supply chain stability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
China Surveillance Camera Market
Video Surveillance Systems
Gunshot Detection System Market
Video Surveillance Systems
Connected Enterprise Video Surveillance Solutions Market
Video Surveillance Systems
Germany Surveillance Analog Camera Market
Video Surveillance Systems
United Kingdom Surveillance IP Camera Market
Video Surveillance Systems
Video Surveillance Software Market
Video Surveillance Systems
Smart Camera System Market
Video Surveillance Systems
Germany Surveillance IP Camera Market
Video Surveillance Systems
Global Video Surveillance Systems Market
Video Surveillance Systems
Latin America Surveillance IP Cameras Market
Video Surveillance Systems
Europe Video Surveillance Storage Market
Video Surveillance Systems
Asia-Pacific Video Surveillance Systems Market
Video Surveillance Systems
Asia-Pacific Surveillance Analog Camera Market
Video Surveillance Systems
Mexico Surveillance IP Camera Market
Video Surveillance Systems
Employee Monitoring Solutions (Automated) Market
Video Surveillance Systems
North America Video Surveillance Systems Market