
 Brazil Video Surveillance Market | 2026-2036
Brazil Video Surveillance Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Video Surveillance Market Insights
Modular camera-plus-software bundling is repositioning procurement patterns across Brazilian enterprises and municipal buyers. Honeywell International Inc leverages its building-automation heritage to anchor integrated security suites in commercial real estate. Intelbras SA dominates domestic manufacturing scale, while Axis Communications AB differentiates through open-architecture IP camera platforms that reduce vendor lock-in.
Brazil video surveillance encompasses camera hardware, recording devices, video management software, and analytics engines designed for real-time monitoring and forensic review. IP camera systems transmit encrypted digital streams over Ethernet or fiber networks, enabling remote access and AI-powered object detection at edge nodes. Cloud-based technology is outpacing analog infrastructure as Brazilian datacenter operators expand local hosting capacity to satisfy LGPD data-residency requirements. Among end users, government and transportation segments command the deepest procurement pipelines, while retail adoption accelerates through loss-prevention analytics and self-checkout monitoring.
ANVISA governs biometric data handling in healthcare-adjacent surveillance deployments, while the LGPD framework imposes consent and retention rules that constrain facial-recognition rollouts. The National Public Security Force and state-level military police procurement standards further dictate product certification and interoperability mandates for vendors. Stakeholders must monitor pending federal legislation on automated identification in public spaces, as regulatory clarity will determine whether cloud-based analytics can scale beyond pilot programs into nationwide infrastructure.
Market Dynamics
LGPD-mandated data localization is forcing rapid infrastructure rebuilding across Brazilian video surveillance deployments. Municipal buyers and enterprise security teams now confront architectural decisions that lock in cloud-versus-edge trade-offs for the next procurement cycle.
Growth Catalysts
- Smart city mandates in São Paulo:The metropolitan authority's integrated operations center specifications require networked camera density increases across transit corridors and public squares.
- ANVISA biometric protocols:Healthcare-adjacent surveillance deployments must upgrade to compliant analytics engines, creating replacement demand in hospital and clinic security systems.
- Edge AI processing:On-camera inference chips reduce bandwidth costs and latency for real-time threat detection in bandwidth-constrained northern municipalities.
Market Restraints
- Semiconductor input volatility:Image sensor and SoC lead times from Asian foundries create procurement uncertainty for domestic integrators.
- LGPD consent architecture:Facial recognition in public spaces requires explicit legal basis documentation that slows deployment timelines for federal security projects.
- Legacy analog substitution:Existing coaxial infrastructure in smaller municipalities delays IP migration despite total-cost advantages.
Strategic Opportunities
- Amazon basin corridor monitoring:Environmental enforcement agencies seek thermal and multispectral systems for illegal mining and deforestation detection.
- Retail loss-prevention analytics:Self-checkout monitoring and shelf-integrity algorithms open mid-market adoption among grocery and pharmacy chains.
- LGPD-compliant cloud hosting:Local datacenter operators can capture analytics workloads previously routed to international infrastructure.
Industry Challenges
- Certification timeline compression:National Public Security Force interoperability mandates require extensive lab testing that extends product launch schedules.
- Edge-to-cloud integration complexity:Hybrid architectures demand specialized systems integrators scarce outside São Paulo and Rio de Janeiro metro areas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Video Surveillance Market |
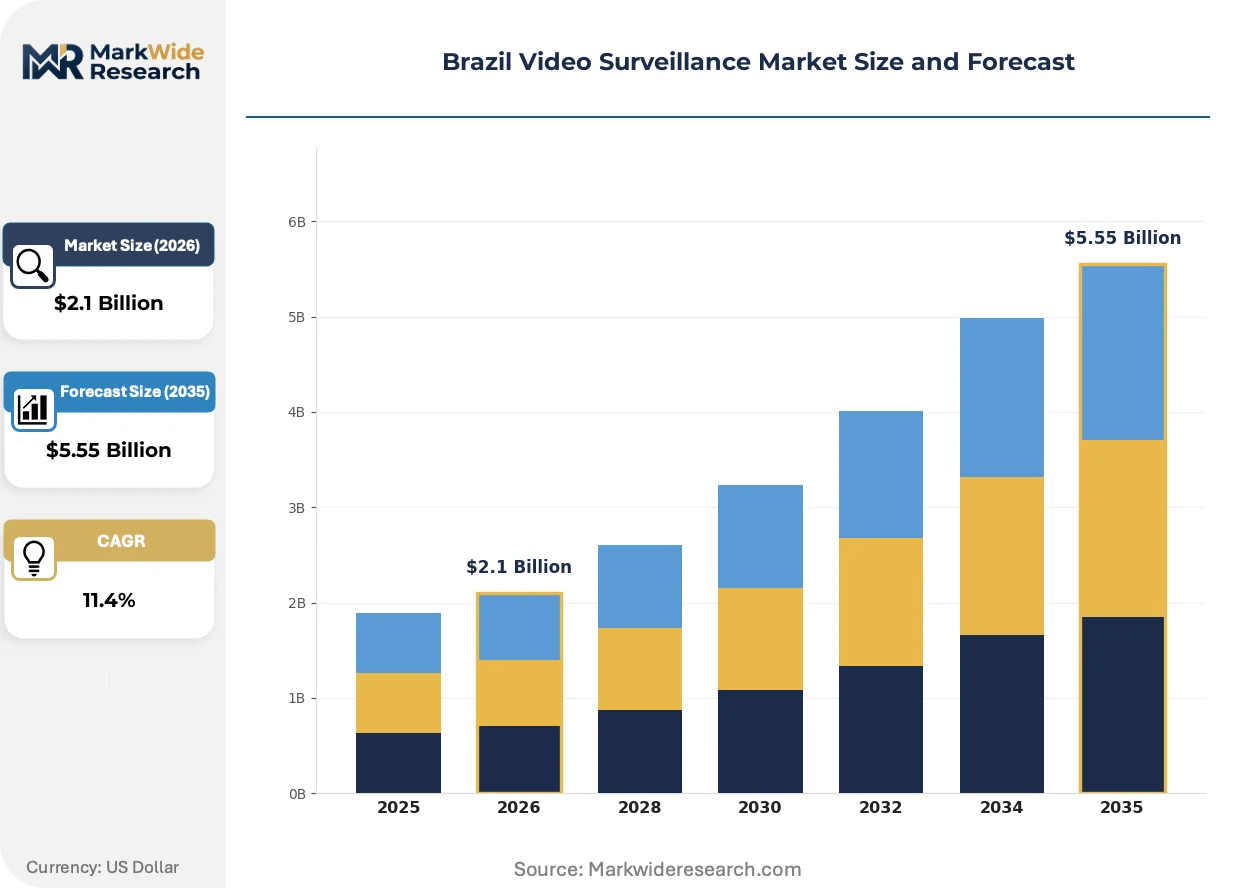
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CCTV Cameras, IP Cameras, Digital Video Recorders, Video Analytics End User: Retail, Transportation, Government, Residential Technology: Analog, Digital, Wireless, Cloud-based Application: Traffic Monitoring, Public Safety, Facility Management, Home Security |
| Companies Covered | Honeywell International Inc, Bosch Security Systems Incorporated, Hangzhou Hikvision Digital Technology Co. Ltd, Eagle Eye Networks Inc, Intelbras SA, Zhejiang Dahua Technology Co. Ltd, Teledyne FLIR LLC, Motorola Solutions Inc, Axis Communications AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Video Surveillance Market Trends and Innovations
Video surveillance architecture in Brazil is pivoting from centralized recording to distributed intelligence. This shift redefines vendor value capture and buyer procurement evaluation criteria.
AI-powered video analytics is integrating behavioral recognition and anomaly detection directly into camera firmware. Large retail chains and transit operators are deploying these systems at scale to reduce server infrastructure and bandwidth commitments. The technology is integrating forensic search capabilities that compress incident investigation timelines from hours to minutes.
LGPD enforcement actions by Brazil's national data protection authority are tightening consent and retention requirements for biometric data processing. Security operators must now implement technical measures including purpose limitation and storage minimization by default. Federal law enforcement procurement is most affected, with several pilot programs suspended pending compliance architecture redesign.
Municipal buyers are consolidating vendor relationships around full-stack security providers rather than discrete hardware purchases. State-level military police forces now specify bundled camera, software, and maintenance contracts in single-tender awards. This pattern is most visible in Minas Gerais and Paraná, where procurement frameworks favor five-year total-cost-of-ownership evaluations over upfront capital expenditure metrics.
Brazil Video Surveillance Market Segmentation
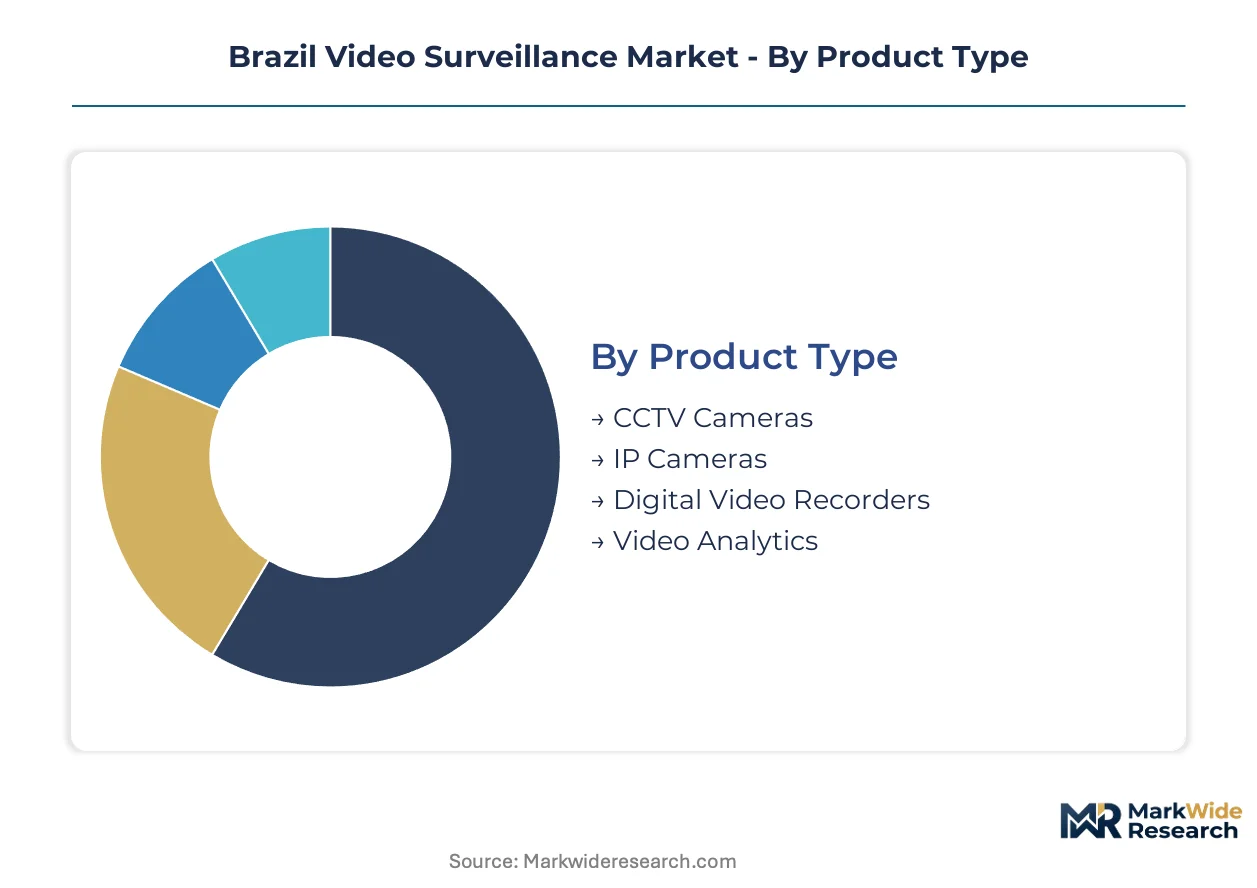
Brazilian procurement teams evaluate surveillance investments through four distinct lenses: hardware specifications, operational environment, connectivity architecture, and deployment purpose. Each segmentation dimension carries different weight across municipal, enterprise, and residential buyers navigating LGPD compliance requirements.
Product Type:
Municipal buyers prioritize total cost of ownership over upfront hardware expenditure, driving bundling preferences that reshape vendor selection criteria.
- IP Cameras:These devices transmit encrypted H.265 streams over Ethernet or fiber infrastructure, supporting edge AI inference for real-time object classification. Demand concentrates in São Paulo and Rio de Janeiro smart city corridors where ANVISA-compliant biometric analytics require high-resolution sensor arrays and on-camera processing to minimize cloud data transfer.
- CCTV Cameras:Coaxial-based analog systems persist in legacy municipal installations across northern Brazil where IP migration budgets remain constrained. Smaller cities in Pará and Amazonas states delay infrastructure replacement despite higher long-term maintenance burdens, creating a bifurcated procurement landscape between coastal metropolises and interior municipalities.
- Digital Video Recorders:On-premise storage appliances with RAID redundancy serve facilities requiring 90-day retention under LGPD minimization principles. These systems dominate hospital and banking deployments where local datacenter hosting costs exceed edge recording economics.
- Video Analytics:AI engines for behavioral recognition and anomaly detection integrate at VMS or camera firmware layers. Federal security pilots in border zones drive thermal-multispectral fusion demand for illegal mining detection in Amazon basin enforcement corridors.
Volume sits with CCTV Cameras in legacy infrastructure; growth tilts toward IP Cameras.
End User:
Regulatory exposure varies sharply across buyer categories, with public sector procurement subject to National Public Security Force interoperability mandates that private deployments escape.
- Government:Federal and state security budgets prioritize border control, transit corridor monitoring, and integrated operations centers. Military police procurement in Minas Gerais and Paraná specifies five-year bundled contracts with certified interoperability, compressing vendor qualification timelines.
- Transportation:Metro operators and highway concessionaires deploy edge-AI systems for crowd density analysis and incident response. São Paulo's metropolitan transit authority mandates networked camera density increases across 400+ station environments.
- Retail:Loss-prevention analytics and self-checkout monitoring drive mid-market adoption among grocery and pharmacy chains. Shelf-integrity algorithms reduce shrinkage in high-turnover environments where labor costs exceed technology investment.
- Residential:Condominium associations and individual homeowners favor wireless cloud-connected kits with mobile app management. LGPD consent requirements constrain facial recognition features in multi-unit buildings, limiting premium feature penetration.
Government captures procurement volume; retail applications are climbing the fastest.
Technology:
Connectivity architecture decisions lock in operational cost structures and data residency compliance paths for the full procurement cycle.
- Cloud-based:Brazilian datacenter operators expand local hosting capacity to satisfy LGPD data-residency requirements, enabling analytics workloads previously routed to international infrastructure. Municipal buyers in bandwidth-constrained regions require hybrid edge-cloud designs.
- Digital:IP-over-Ethernet deployments dominate new construction and major retrofit projects where structured cabling investments amortize across building automation systems. Commercial real estate developers specify PoE+ infrastructure to support pan-tilt-zoom and thermal camera power demands.
- Wireless:4G/5G cellular backhaul serves temporary deployments and remote environmental monitoring in Amazon basin corridors where fiber installation costs prove prohibitive. Battery-solar hybrid units support illegal mining detection in off-grid enforcement zones.
- Analog:Coaxial infrastructure persists in smaller municipalities and legacy industrial facilities where capital replacement cycles extend beyond typical technology obsolescence. These systems face component availability constraints as semiconductor vendors discontinue legacy image signal processors.
Digital deployments hold current volume; cloud-based architectures show the steepest expansion trajectory.
Application:
Use-case specificity determines sensor configuration, analytics engine selection, and retention policy architecture under LGPD purpose limitation requirements.
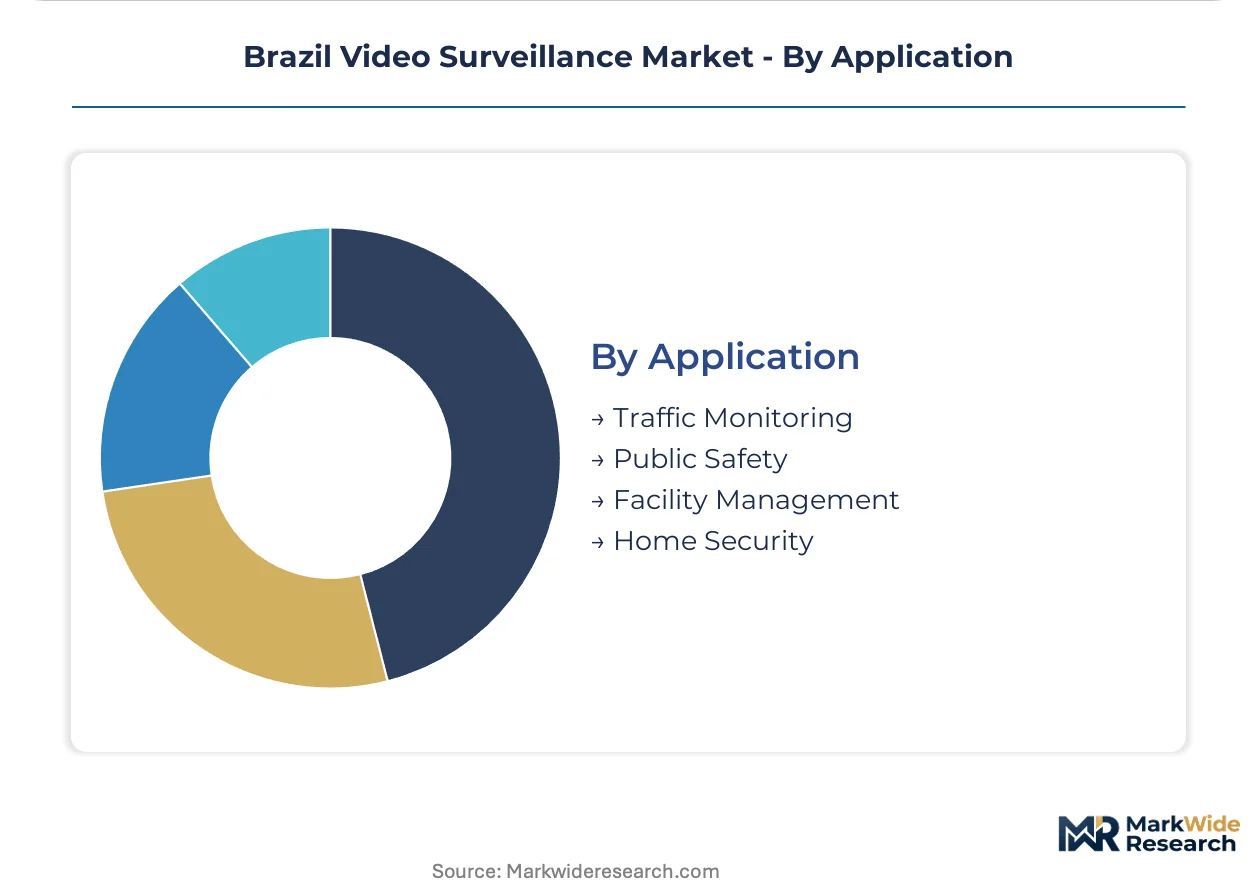
- Public Safety:Urban surveillance networks integrate gunshot detection, facial recognition, and license plate reading across metropolitan operations centers. ANVISA biometric protocols and LGPD consent architecture constrain facial recognition rollouts, with several federal pilot programs suspended pending compliance redesign.
- Traffic Monitoring:Highway concessionaires and municipal transit authorities deploy thermal and multispectral systems for incident detection and congestion management. Edge processing reduces latency for automatic incident detection algorithms that trigger variable message signs.
- Facility Management:Commercial real estate operators integrate surveillance with access control and building automation through unified security suites. Honeywell and domestic integrators anchor these deployments through long-term maintenance contracts.
- Home Security:DIY camera kits with cloud storage and AI-powered person-vehicle-pet differentiation serve residential demand. Privacy-conscious consumers drive local storage preference, though cloud convenience retains majority share in urban condominium markets.
Public Safety commands installation volume; facility management applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Manaus Free Trade Zone tax incentives concentrate electronics assembly capacity in Amazonas state, anchoring domestic camera manufacturing and reducing import dependency for northern municipalities.
São Paulo
São Paulo's metropolitan integrated operations center mandates networked camera density increases across transit corridors and public squares. ANVISA biometric protocols govern healthcare-adjacent surveillance deployments in hospital clusters. The ABC Paulista industrial corridor hosts domestic integrators supplying edge-AI systems to smart city infrastructure.
Rio de Janeiro
Rio de Janeiro's state security secretariat prioritizes favela pacification camera networks and coastal monitoring for port security. LGPD consent architecture constrains facial recognition pilots in public spaces, suspending several federal programs. The Porto Maravilha redevelopment zone anchors commercial real estate security suites with unified building automation.
Minas Gerais
Minas Gerais military police procurement specifies five-year bundled contracts with certified National Public Security Force interoperability. State-level tender frameworks favor total-cost-of-ownership evaluations over upfront capital expenditure. Belo Horizonte's technology park clusters systems integrators serving the southeastern surveillance market.
Paraná
Paraná's state government consolidates vendor relationships around full-stack security providers through single-tender awards. Federal border control budgets prioritize corridor monitoring along the Paraguay frontier. Curitiba's urban planning legacy drives smart traffic monitoring deployments with edge processing for congestion management.
Bahia
Bahia's northern municipalities delay IP migration due to constrained capital replacement cycles despite higher long-term maintenance burdens. ANVISA data-protection protocols reshape biometric analytics integration in Salvador's hospital security systems. The state's Atlantic port complex drives maritime surveillance demand for container terminal monitoring.
Brazil Video Surveillance Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement tiers in Brazil's surveillance market. The vendor structure segments into three strategic archetypes: building-automation conglomerates leveraging cross-system integration, domestic manufacturers capturing municipal cost sensitivity, and open-architecture IP specialists reducing buyer lock-in. M&A activity concentrates on analytics software capabilities, while strategic partnerships address LGPD-compliant cloud hosting requirements.
Within the diversified conglomerate tier, Honeywell International Inc and Bosch Security Systems Incorporated occupy positions anchored by building-automation heritage. Among domestic specialists, Intelbras SA exemplifies manufacturing scale advantages in cost-sensitive municipal procurement. Axis Communications AB represents the open-architecture archetype, with Motorola Solutions Inc anchoring public safety communications integration. Chinese manufacturers Hangzhou Hikvision Digital Technology Co. Ltd and Zhejiang Dahua Technology Co. Ltd sit within the high-volume hardware tier, while Eagle Eye Networks Inc and Teledyne FLIR LLC exemplify cloud-native and thermal-specialist positioning respectively.
| Leading Market Players |
|---|
| Honeywell International Inc |
| Bosch Security Systems Incorporated |
| Hangzhou Hikvision Digital Technology Co. Ltd |
| Eagle Eye Networks Inc |
| Intelbras SA |
| Zhejiang Dahua Technology Co. Ltd |
| Teledyne FLIR LLC |
| Motorola Solutions Inc |
| Axis Communications AB |
| Others |
Pricing and Supply Chain Analysis
Captive integration into edge-AI chip design anchors both supply security and premium pricing power for Brazilian surveillance vendors navigating LGPD-mandated localization requirements. Domestic assemblers in the Manaus Free Trade Zone leverage tariff advantages to compress landed costs against fully-imported alternatives, while semiconductor sourcing decisions from Asian foundries lock in margin structures across procurement cycles.
Pricing Analysis
Short lead-time premiums for image sensors and SoCs from Taiwanese foundries compress margins for domestic integrators facing municipal procurement deadlines. Three-tier pricing structure across premium-certified, standard-compliant, and economy analog tiers reflects National Public Security Force interoperability certification levels. Pricing pressure stems from semiconductor input volatility as legacy component discontinuation accelerates. Municipal buyers in northern states exhibit highest price sensitivity, while federal security contracts tolerate premium positioning for ANVISA-compliant biometric systems.
Supply Chain Analysis
Workforce availability constraints in Vietnam and Malaysia electronics assembly hubs are diverting component finishing capacity toward Brazil's Manaus zone. Image sensors from South Korea, SoCs from Taiwan, and optical lenses from China constitute core input dependencies. Single-source vulnerability concentrates in advanced CMOS sensor supply from Korean manufacturers. Distribution runs through São Paulo-based systems integrators serving municipal and enterprise verticals with bundled installation and maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
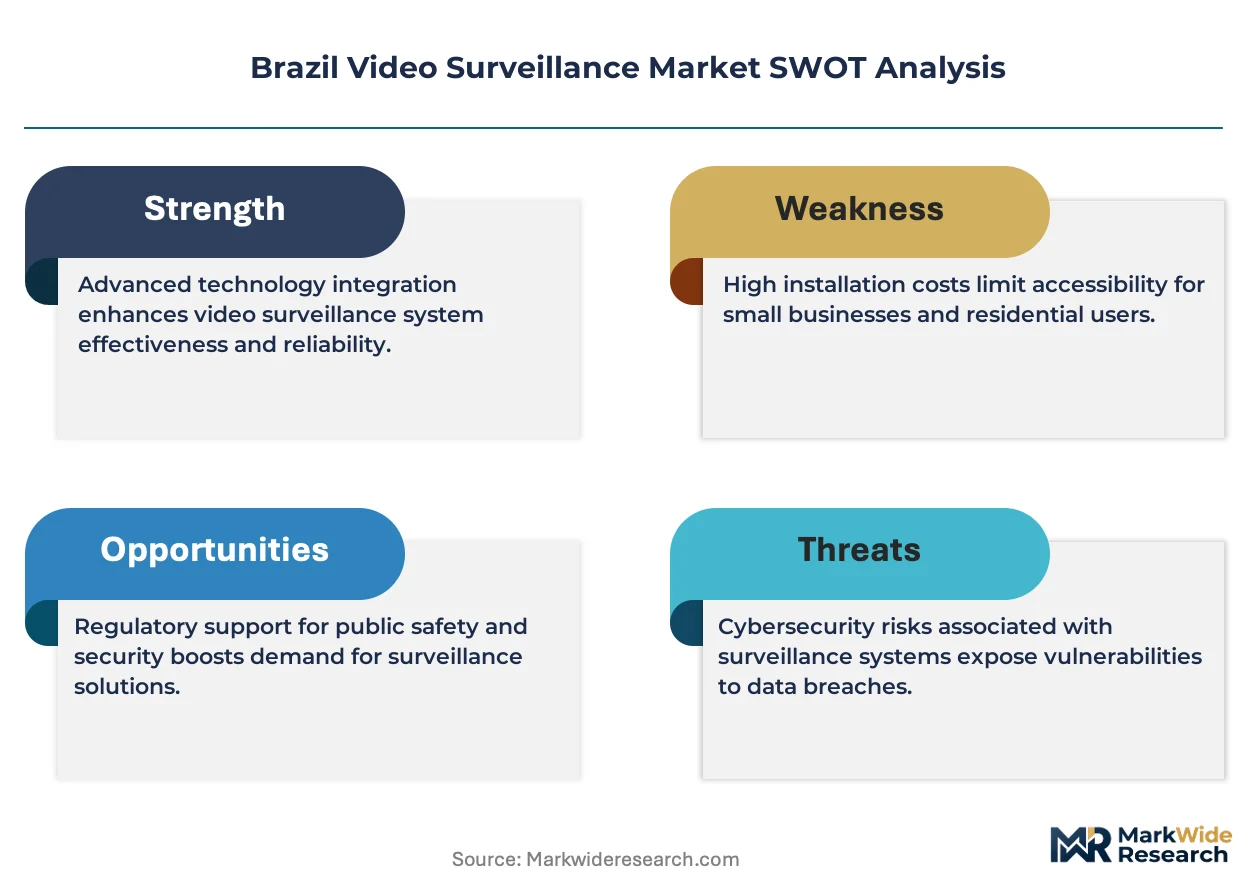
The Brazil video surveillance market functions as a cost-of-compliance story where LGPD data-residency mandates erect barrier-to-entry moats for players with certified local hosting infrastructure. ANVISA biometric protocols further deepen certification burdens that favor incumbents with established regulatory affairs capabilities.
For Market Incumbents: Deepen backward integration into edge-AI chip customization to reduce foundry dependency exposure and defend margin position against Chinese hardware competitors. Expand certified interoperability lab capacity in Belo Horizonte to compress National Public Security Force qualification timelines that currently extend product launches. Prioritize LGPD-compliant cloud hosting partnerships with local datacenter operators to capture analytics workloads migrating from international infrastructure. For New Entrants and Emerging Players: Northern municipality analog-to-IP migration delays create accessible white-space for cost-optimized retrofit solutions with hybrid coaxial-Ethernet bridging. Retail pharmacy chains deploying self-checkout monitoring represent the most penetrable mid-market segment with compressed sales cycles versus government procurement. Pursue channel partnerships with domestic integrators in Curitiba and Salvador to bypass direct certification overhead. For Investors and Strategic Acquirers: Exit pathways concentrate in analytics software specialists with ANVISA-compliant biometric engines and established federal pilot program relationships. Long-term viability hinges on regulatory compliance architecture rather than hardware scale alone across the projection horizon. Monitor ANVISA enforcement action frequency as inflection indicator for facial recognition rollout velocity and associated analytics demand.| Strategic Initiative | Industry Significance |
|---|---|
| LGPD-Compliant Cloud Hosting Partnership | Local datacenter alliances satisfy data-residency mandates that international providers cannot meet. |
| Edge-AI Chip Customization Program | On-camera inference reduces bandwidth costs for bandwidth-constrained Amazon basin deployments. |
| National Public Security Force Certification Investment | Interoperability lab capacity compresses product launch schedules in Minas Gerais and Paraná tenders. |
| Retail Loss-Prevention Analytics Platform Launch | Shelf-integrity algorithms address shrinkage in grocery and pharmacy chains with measurable ROI. |
| Amazon Basin Environmental Monitoring Joint Venture | Thermal-multispectral fusion systems serve IBAMA enforcement demand for illegal mining detection. |
Research Methodology
Multi-period observation of municipal procurement tender awards, federal security budget allocations, and datacenter capacity expansion anchored the trend analysis, supplemented by interviews with systems integrators, municipal security directors, and hospital facility managers. Secondary validation drew from ANVISA regulatory filings, LGPD enforcement actions by the national data protection authority, National Public Security Force interoperability standards, and customs import records for surveillance hardware. Bottom-up vendor revenue triangulation against top-down addressable market sizing ensured consistency across segmentation estimates.
Input-output matrices mapped camera unit shipments, software licensing volumes, and service contract values across product type, end user, technology, and application dimensions over the projection horizon. CAGRs derived from logistic adoption curves for IP migration and analog replacement cycles, calibrated against smart city infrastructure investment pipelines in São Paulo and Rio de Janeiro. Forecast inputs incorporated semiconductor lead time volatility indices and municipal fiscal capacity indicators from northern state budgets.
Revisions become necessary when ANVISA biometric protocol amendments, LGPD enforcement precedent shifts, or federal automated identification legislation materialize unexpectedly. Forecasts reflect documented assumptions regarding IP migration pace and cloud hosting capacity expansion. Material deviation in semiconductor supply availability or municipal budget execution warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
People Counting System Market
Video Surveillance Systems
United States Surveillance IP Camera Market
Video Surveillance Systems
Privacy Filters Market
Video Surveillance Systems
Video Surveillance Market
Video Surveillance Systems
China Surveillance IP Camera Market
Video Surveillance Systems
India Video Surveillance Market
Video Surveillance Systems
Security Camera Software Market
Video Surveillance Systems
Brazil Surveillance IP Cameras Market
Video Surveillance Systems
Smart Camera System Market
Video Surveillance Systems
Smart Outdoor Cameras Market
Video Surveillance Systems
North America Pedestrian Detection Systems Market
Video Surveillance Systems
Concealed Weapon Detection Systems Market
Video Surveillance Systems
Asia-Pacific Video Surveillance Storage Market
Video Surveillance Systems
Global Night Vision System and Driver Monitoring System Market
Video Surveillance Systems
AI Surveillance System Market
Video Surveillance Systems
Night Vision Camera Market