
 Night Vision System (NVS) Market | 2026-2036
Night Vision System (NVS) Market Size, Share, and Industry Trends Forecast 2026-2036
Night Vision System (NVS) Market Foresight
The defense procurement channel is fragmenting as sovereign governments diversify supplier bases beyond traditional prime contractors. FLIR Systems Inc. leverages its thermal imaging heritage to anchor long-term military contracts across NATO-aligned nations. L3Harris Technologies Inc. competes through classified program access and vertically integrated sensor production. Robert Bosch GmbH sustains automotive OEM relationships by embedding NVS modules within broader advanced driver-assistance architectures.
A night vision system is an electro-optical device that amplifies ambient light in near-infrared spectra or detects thermal radiation to produce visible imagery, typically operating at wavelengths between 700 nanometers and 14 micrometers depending on sensor technology. These systems enable human operators or autonomous platforms to perceive environments under zero-illumination conditions for military targeting, automotive safety, or surveillance missions. Goggles and scopes command the largest product volume pools, though digital technology variants are capturing margin expansion as solid-state sensors displace legacy image intensifier tubes. Thermal technology segments retain pricing power in defense applications where detection range requirements exceed three kilometers.
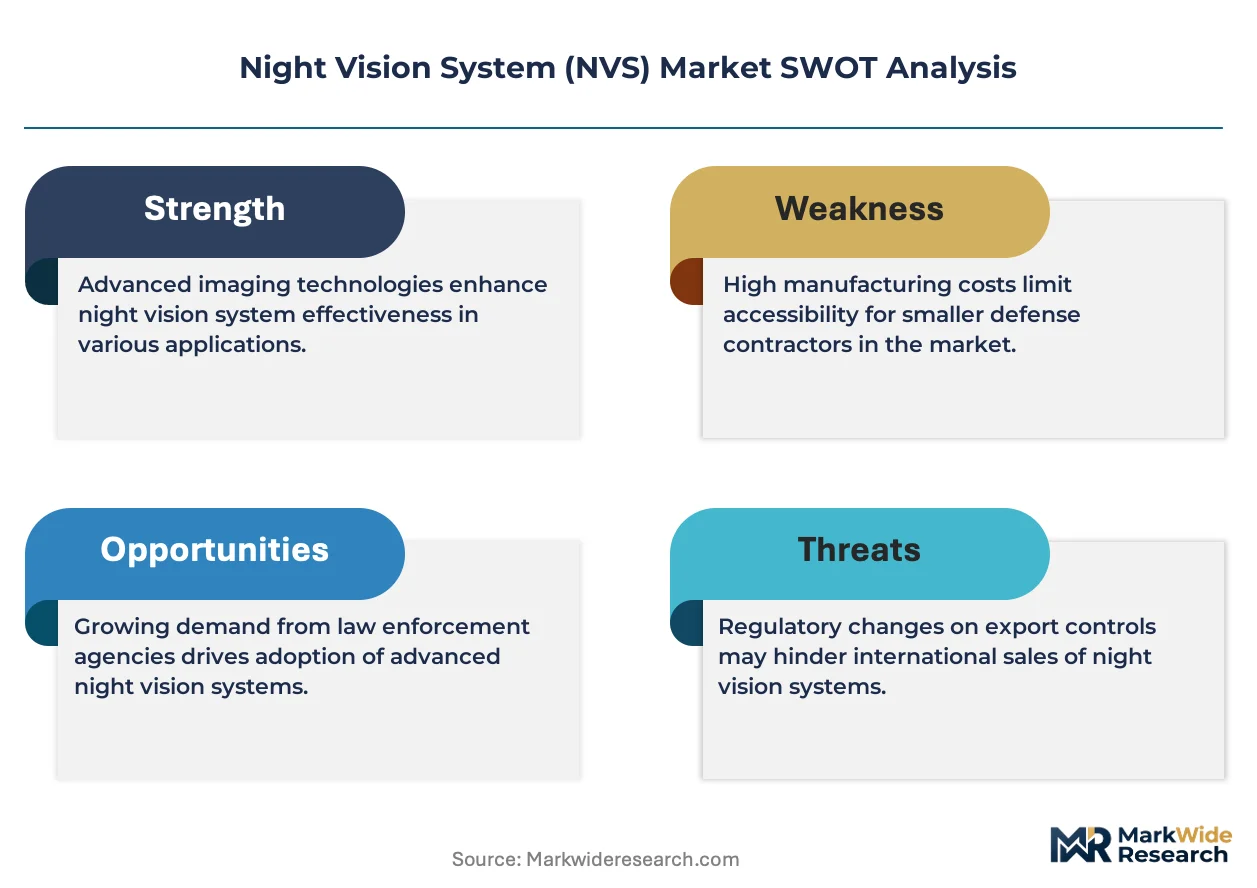
The US Department of Defense, the EU AI Act, and NATO standardization agreements collectively shape product certification pathways and cross-border sales eligibility for NVS manufacturers. FAA regulations for unmanned aerial systems and NHTSA automotive safety ratings further segment addressable markets by imposing distinct electromagnetic compatibility and reliability thresholds. Stakeholders must monitor how export control recalibrations affect component sourcing strategies and foreign military sales licensing timelines.
Market Dynamics
Defense procurement fragmentation is forcing NVS manufacturers to diversify beyond traditional prime contractor relationships, while automotive OEMs consolidate sensor fusion contracts around vertically integrated platform providers. This dual-channel pressure is compressing margins for standalone component suppliers and accelerating consolidation among mid-tier thermal imaging specialists.
Growth Catalysts
- NHTSA pedestrian safety mandates:United States regulatory pressure for advanced driver-assistance systems is embedding NVS modules into premium vehicle platforms as standard equipment.
- Thermal sensor miniaturization:Solid-state uncooled detector arrays are expanding addressable applications into commercial drones and portable surveillance equipment.
- Germany:KBA vehicle type-approval requirements for nighttime autonomous operation are creating certified demand pools for fused thermal-visible systems.
Market Restraints
- Germanium substrate pricing volatility:Optical component costs fluctuate with rare earth supply constraints from concentrated mining operations.
- ITAR export licensing friction:United States International Traffic in Arms Regulations extend procurement timelines for NATO-aligned foreign military sales.
- SWaP limitations:Size, weight, and power constraints in man-portable applications restrict thermal imager performance below military targeting thresholds.
Strategic Opportunities
- India:PLI scheme incentives for domestic electronics manufacturing are attracting NVS module assembly investments from tier-one automotive suppliers.
- Drone-based infrastructure inspection:FAA Part 107 waiver expansions for beyond-visual-line-of-sight operations are opening commercial thermal imaging contracts.
- EU AI Act compliance services:Convergence of machine-vision algorithms with thermal detection is creating adjacent revenue streams for algorithm certification and bias auditing.
Industry Challenges
- Infrared optics polishing specialization:Precision aspheric lens fabrication requires master opticians with decade-long training curves, constraining production scaling.
- ISO 9001/AS9100 dual certification complexity:Manufacturers serving both automotive and defense verticals face divergent quality management system audit timelines.
- Legacy analog video interface integration:Military platforms with MIL-STD-170 display standards require bridge electronics for digital thermal sensor compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Night Vision System (NVS) Market |
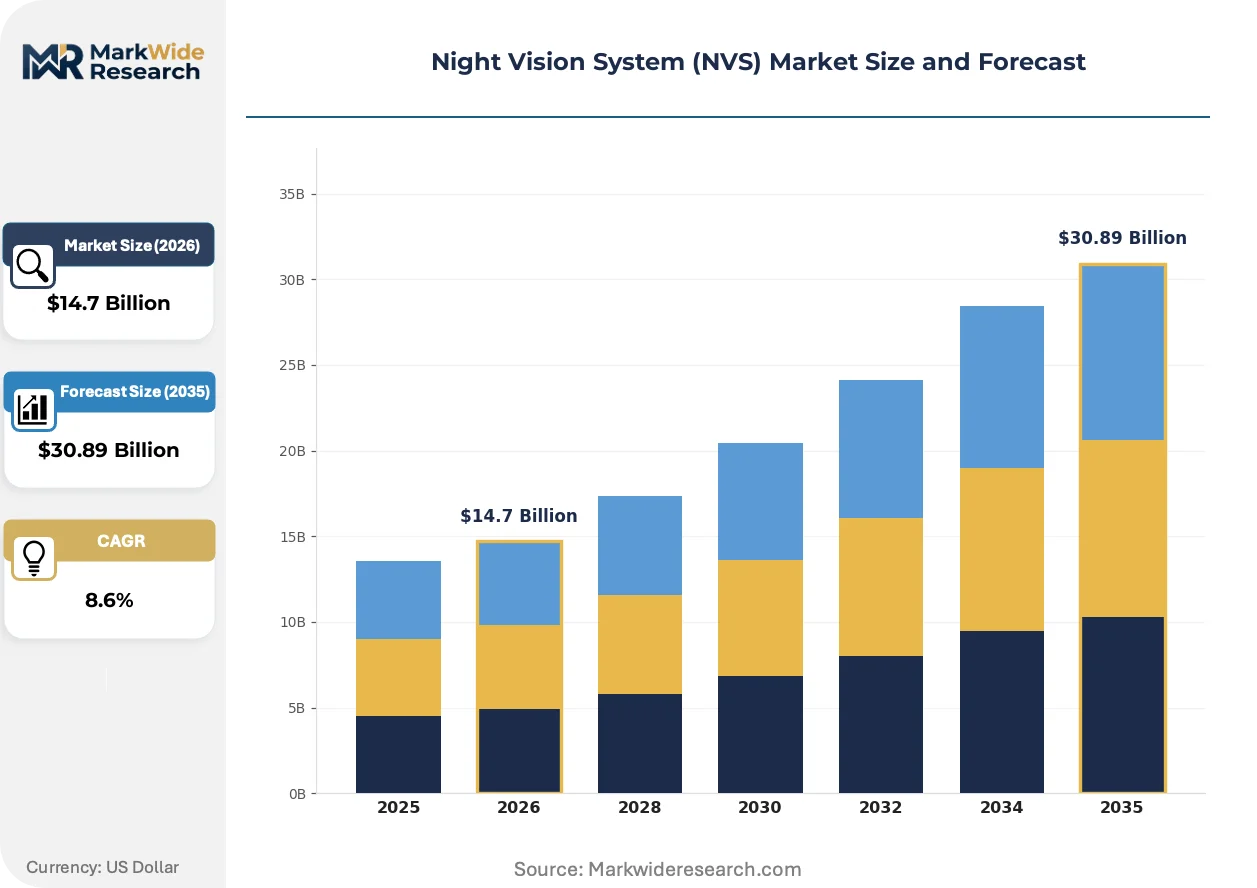
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoculars, Binoculars, Goggles, Scopes Technology: Analog, Digital, Thermal, Hybrid End User: Military, Law Enforcement, Wildlife Observation, Civilian Application: Surveillance, Search and Rescue, Defense, Hunting |
| Companies Covered | DENSO Corporation, Robert Bosch GmbH, Magna International Inc., FLIR Systems Inc., Autoliv Inc., Continental AG, Valeo SA, L3Harris Technologies Inc., Aptiv PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Night Vision System (NVS) Market Shifts & Advancements
Solid-state sensor architectures are actively displacing vacuum-tube image intensifiers across every NVS application tier. This technological transition is compressing product development cycles and redefining supplier competitive advantages around semiconductor fabrication partnerships rather than specialized tube manufacturing.
Digital focal plane arrays with on-chip analog-to-digital conversion are rendering obsolete legacy image intensifier tubes in military goggle applications. United States Special Operations Command procurement specifications now prioritize solid-state alternatives for new helmet-mounted displays. This shift is compressing the addressable market for European tube manufacturers and transferring value capture to CMOS foundry partners.
The EU AI Act risk-classification framework is redefining certification pathways for autonomous target recognition systems. Manufacturers must now document algorithmic transparency and bias mitigation for thermal-visible fusion products deployed in populated areas. German automotive OEMs are responding by segregating AI-enabled NVS modules into distinct product lines with enhanced documentation packages.
Defense procurement offices are consolidating multi-year sensor platform contracts around integrated system-of-systems providers. Traditional component vendors face displacement unless they embed NVS modules within broader situational awareness architectures. This pattern is most visible in Japan, where METI-industrial coordination is steering domestic suppliers toward fused multi-sensor offerings for maritime patrol platforms.
Night Vision System (NVS) Market Segmentation
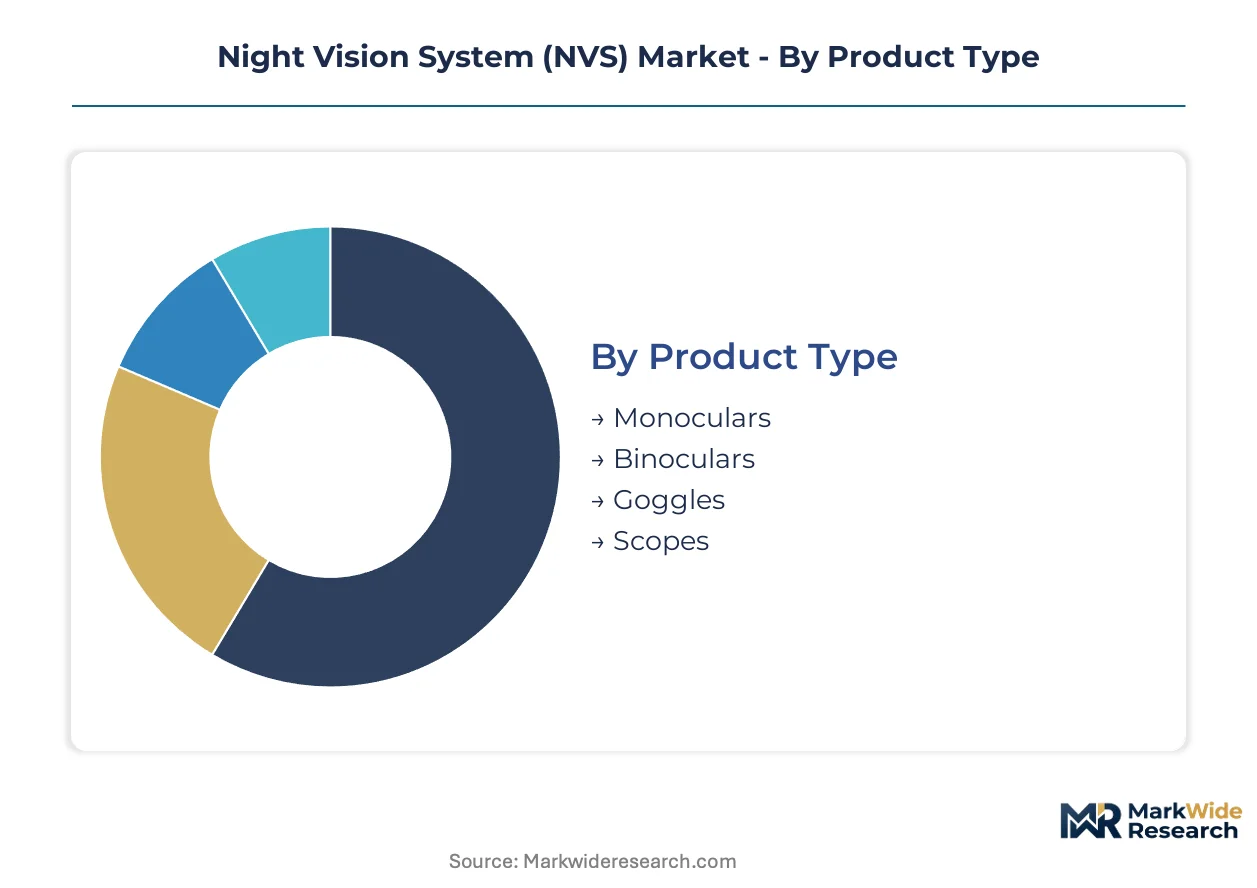
NVS product architectures diverge sharply between defense procurement cycles and consumer retail channels. Segmentation reveals how thermal imaging heritage concentrates in military contracts while solid-state miniaturization unlocks commercial portability.
Product Type:
Use-case spectrum spans helmet-mounted dismounted soldier systems through vehicle-integrated driver assistance platforms.
- Goggles:Helmet-mounted binocular configurations dominate NATO close-combat procurement specifications. United States Special Operations Command requirements prioritize solid-state alternatives over legacy image intensifier tubes, compressing development cycles for European tube manufacturers.
- Scopes:Weapon-mounted thermal weapon sights deliver detection ranges exceeding three kilometers for designated marksman applications. German KBA type-approval frameworks for nighttime autonomous operation are embedding fused thermal-visible scopes into premium automotive platforms.
- Monoculars:Single-tube designs balance SWaP constraints for man-portable surveillance in law enforcement checkpoint operations.
- Binoculars:Dual-ocular handheld units serve wildlife observation demand in United States national park concession contracts.
Established volume favors Goggles; emerging adoption favors Scopes.
Technology:
Cost tier stratification separates vacuum-tube legacy systems from semiconductor-based solid-state architectures.
- Thermal:Uncooled microbolometer arrays detect long-wave infrared radiation without cryogenic cooling. Defense applications retain pricing power where detection thresholds exceed three kilometers, though germanium substrate volatility constrains optical component scaling.
- Digital:CMOS-based digital focal plane arrays with on-chip analog-to-digital conversion displace legacy tubes across every tier. FAA Part 107 waiver expansions for beyond-visual-line-of-sight drone operations are accelerating commercial thermal imaging contracts.
- Analog:Image intensifier tubes persist in legacy military platforms requiring MIL-STD-170 display standard compatibility.
- Hybrid:Fused thermal-visible sensor architectures combine near-infrared amplification with thermal detection for automotive pedestrian safety systems.
Thermal commands premium defense pricing; Digital gains share fastest in commercial channels.
End User:
Customer type fragmentation separates classified program access from retail distribution economics.
- Military:Sovereign defense procurement offices consolidate multi-year sensor platform contracts around integrated system-of-systems providers. ITAR licensing friction extends NATO-aligned foreign military sales timelines.
- Law Enforcement:Agency-level purchasing favors portable surveillance equipment for border checkpoint and tactical response units. SWaP limitations restrict thermal imager performance below military targeting thresholds.
- Civilian:Hunting and personal security applications drive demand for cost-compact monocular units through outdoor retail channels.
- Wildlife Observation:Park concession operators and research biologists prioritize battery endurance for extended nocturnal monitoring operations.
Military procurement anchors revenue concentration; Law Enforcement represents the steepest expansion trajectory for portable systems.
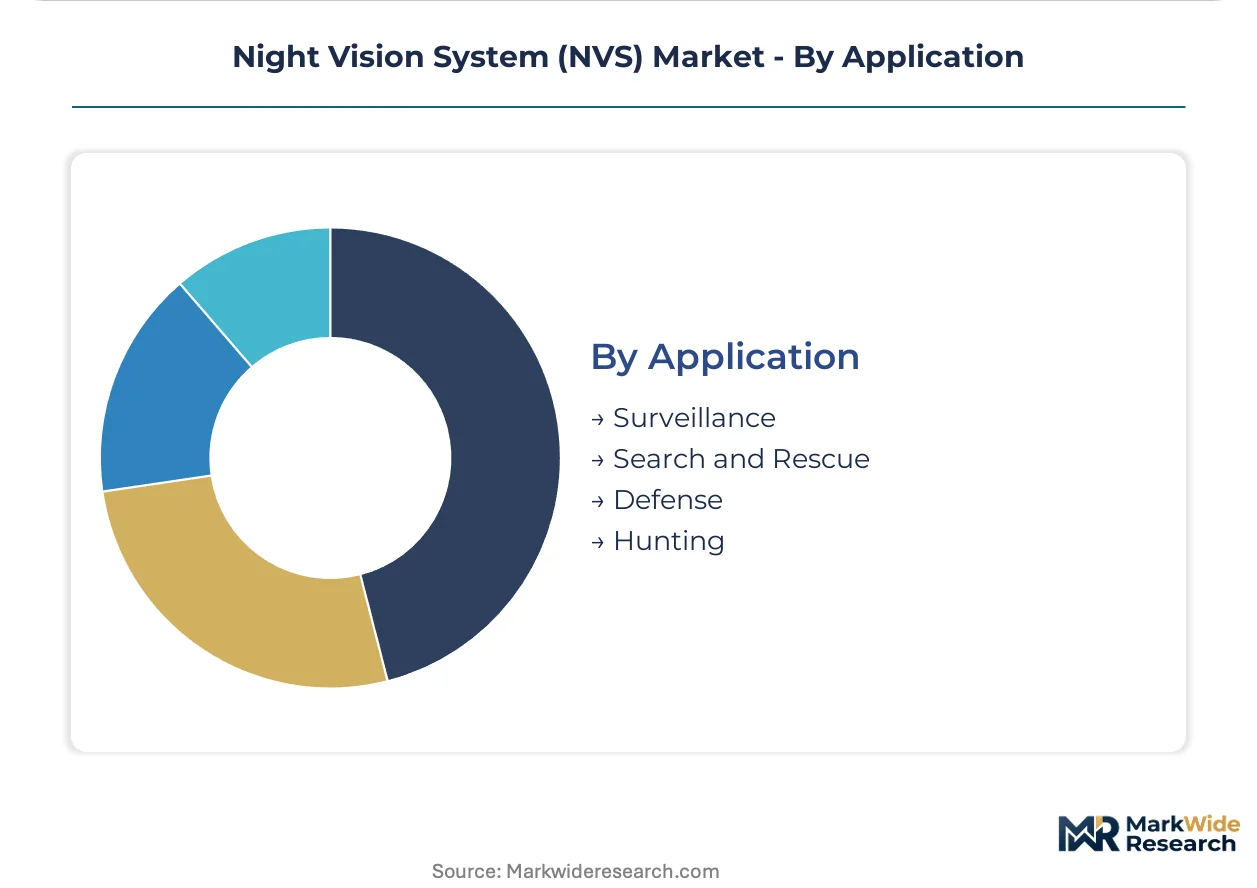
Application:
Margin structure varies with certification burden and integration complexity across deployment scenarios.
- Defense:Platform-integrated multi-sensor architectures for maritime patrol and armored vehicle targeting command highest unit economics. Japan METI-industrial coordination steers domestic suppliers toward fused multi-sensor offerings.
- Surveillance:Fixed-site perimeter security and drone-based infrastructure inspection demand diverge in sensor payload specifications. EU AI Act risk-classification frameworks impose algorithmic transparency documentation for autonomous target recognition in populated areas.
- Search and Rescue:Thermal detection of human heat signatures in zero-illumination conditions drives adoption across alpine rescue services and coastal patrol units.
- Hunting:Game detection and shot placement assistance applications concentrate in North American and European recreational markets with varying regulatory restrictions on night hunting.
Defense integration captures premium margins; Surveillance applications climb fastest on commercial drone platform expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Trans-European Transport Network corridors and Pacific submarine cable systems underpin data exchange infrastructure critical to NVS algorithm training and sensor fusion development across concentrated manufacturing zones.
United States
NHTSA pedestrian safety mandates and Pentagon multi-year sensor platform contracts drive procurement volume. FAA Part 107 waiver expansions accelerate commercial thermal imaging for beyond-visual-line-of-sight drone operations. Detroit-Warren-Dearborn automotive corridor embeds NVS modules within advanced driver-assistance architectures.
Germany
KBA vehicle type-approval requirements for nighttime autonomous operation create certified demand pools for fused thermal-visible systems. EU AI Act risk-classification frameworks impose algorithmic transparency documentation on machine-vision products. Stuttgart and Munich industrial clusters host tier-one automotive suppliers integrating NVS into premium vehicle platforms.
Japan
METI-industrial coordination steers domestic suppliers toward fused multi-sensor offerings for maritime patrol platforms. JIS standards govern electromagnetic compatibility thresholds for defense and commercial applications. Nagoya-Chubu manufacturing belt concentrates precision optics fabrication for thermal sensor assemblies.
India
PLI scheme incentives for domestic electronics manufacturing attract NVS module assembly investments from tier-one automotive suppliers. DGFT export promotion frameworks support component sourcing for NATO-aligned foreign military sales. Tamil Nadu and Karnataka electronics manufacturing clusters scale uncooled microbolometer packaging operations.
South Korea
MFDS medical device pathways and defense procurement offices consolidate sensor platform contracts around integrated system-of-systems providers. Seoul Capital Area semiconductor foundries supply CMOS digital focal plane arrays displacing legacy image intensifier tubes. Busan-Ulsan shipbuilding corridor integrates maritime patrol NVS into naval platform retrofits.
Night Vision System (NVS) Market Competitive Landscape
On the supply side, the industry is bifurcated between defense prime contractors with classified program access and automotive tier-one suppliers embedding NVS within broader sensor fusion architectures. Three strategic archetypes dominate: vertically integrated thermal imaging heritage players, automotive ADAS platform consolidators, and mid-tier specialists pivoting toward solid-state semiconductor partnerships. Competitive moves center on multi-year sensor platform contract consolidation and backward integration into optical component supply.
Within the defense heritage tier, FLIR Systems Inc. and L3Harris Technologies Inc. exemplify archetypes anchored in thermal imaging program access and classified military specifications. Robert Bosch GmbH occupies a position among automotive platform consolidators embedding NVS modules within vertically integrated advanced driver-assistance architectures.
| Leading Market Players |
|---|
| DENSO Corporation |
| Robert Bosch GmbH |
| Magna International Inc. |
| FLIR Systems Inc. |
| Autoliv Inc. |
| Continental AG |
| Valeo SA |
| L3Harris Technologies Inc. |
| Aptiv PLC |
| Others |
Supply & Pricing Matrix
Germanium substrate pricing volatility determines both pricing tier spreads and supply chain shape in the Night Vision System market. This rare earth dependency compresses margins for uncooled microbolometer manufacturers while concentrating optical component sourcing around vertically integrated defense primes.
Pricing Analysis
Volume-discount tiering structures separate NATO military procurement contracts from commercial drone and automotive ADAS volumes. Three-tier pricing stratifies across ITAR-restricted defense specifications, industrial-grade thermal modules, and consumer-portable monocular units. Cost compression in the commercial tier intensifies as solid-state CMOS sensors displace legacy image intensifier tubes. Law enforcement agencies exhibit highest price sensitivity due to budget-constrained portable equipment purchases, while classified defense programs demonstrate lowest sensitivity given detection-range performance thresholds.
Supply Chain Analysis
Contract manufacturing concentration rests with Taiwan and South Korea semiconductor foundries producing CMOS digital focal plane arrays, alongside German precision optics clusters fabricating aspheric germanium lenses. Raw material dependencies draw from Chinese rare earth processing for germanium substrates, Belgian gallium arsenide wafer suppliers, and Japanese optical glass manufacturers. Single-source vulnerability concentrates in cryogenically cooled detector cooling engines sourced from limited qualified vendors. Distribution runs through defense prime contractor integration channels for military platforms and tier-one automotive supplier networks for ADAS modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Master optician scarcity constrains production scaling for precision infrared optics, creating durable competitive moats around established defense heritage manufacturers. This capability gap separates volume leaders from aspirants across every NVS tier.
For Market Incumbents: Harden supply positions through captive germanium substrate arrangements or long-term offtake agreements with rare earth processors. Accelerate solid-state sensor roadmaps to compress development cycles before European tube manufacturers recover. Lock in multi-year NATO sensor platform contracts before procurement offices consolidate around system-of-systems providers.
For New Entrants and Emerging Players: India's PLI scheme electronics manufacturing incentives offer the most penetrable geography for NVS module assembly investments. Target commercial drone thermal imaging contracts enabled by FAA Part 107 waiver expansions for beyond-visual-line-of-sight operations. Pursue algorithm certification and bias auditing services as the go-to-market angle under EU AI Act compliance requirements.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors semiconductor fabrication partnerships over legacy tube manufacturing capabilities. Long-term viability over the coming decade hinges on CMOS foundry access and automotive ADAS platform integration relationships. Watch for Special Operations Command procurement specification shifts toward solid-state alternatives as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor Foundry Partnership | CMOS focal plane array access displaces legacy image intensifier tube supply chains. |
| Rare Earth Supply Agreement | Germanium substrate security buffers optical component cost volatility from concentrated mining. |
| EU AI Act Compliance Service | Algorithm certification revenue streams emerge from thermal-visible fusion product documentation. |
| Automotive ADAS Platform Integration | NHTSA pedestrian safety mandates embed NVS modules within tier-one supplier architectures. |
| Defense Prime Contractor Consolidation | Multi-year NATO sensor platform contracts transfer value to integrated system-of-systems providers. |
Research Methodology
A spread of perspectives from defense procurement officers, automotive platform engineers, thermal sensor R&D directors, and precision optics master opticians converged on the working assumptions underlying this analysis. Primary field engagement combined with secondary validation from SEC 10-K filings, NATO standardization agreement documentation, FAA waiver expansion records, and customs trade data for germanium substrate flows. Bottom-up unit economics and top-down market sizing triangulated across the projection horizon.
Demand-supply-balance framing anchored the analytical framework throughout the modeling period. Segmentation dimensions included product architecture, sensor technology tier, end-user procurement channel, and application certification burden. CAGRs derived from installed base replacement cycles, automotive ADAS penetration curves, and defense modernization program timelines. Forecast inputs incorporated NHTSA regulatory mandate implementation schedules and EU AI Act risk-classification enforcement phases.
Practitioners should monitor export control recalibrations, rare earth supply disruptions, and solid-state sensor yield improvements for early signals requiring forecast revision. Quarterly review of NATO procurement specification updates, KBA type-approval certification volumes, and FAA Part 107 waiver grant rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Global Video Surveillance Systems Market
Video Surveillance Systems
Japan Surveillance Camera Market
Video Surveillance Systems
Privacy Filters Market
Video Surveillance Systems
Global Night Vision System and Driver Monitoring System Market
Video Surveillance Systems
North America Crawler Camera System Market
Video Surveillance Systems
Latin America Surveillance IP Cameras Market
Video Surveillance Systems
Inspection Camera System Market
Video Surveillance Systems
Middle East and Africa Surveillance IP Cameras Market
Video Surveillance Systems
Smart Security Camera Market
Video Surveillance Systems
Latin America Video Surveillance Market
Video Surveillance Systems
Middle East and Africa Video Surveillance Market
Video Surveillance Systems
Asia-Pacific Video Surveillance Systems Market
Video Surveillance Systems
Japan Surveillance Storage Market
Video Surveillance Systems
Germany Surveillance IP Camera Market
Video Surveillance Systems
Camera Alarm System Market
Video Surveillance Systems
United Kingdom Surveillance Camera Market