
 Security and Surveillance Storage Market | 2026-2036
Security and Surveillance Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Security and Surveillance Storage Market Insights
Edge-to-cloud storage architecture is fragmenting legacy centralized deployment models across the security industry. Dell Technologies leverages its server-storage convergence portfolio to capture hybrid installation contracts. Western Digital anchors the hard disk drive segment with surveillance-optimized firmware for 24/7 write-intensive workloads. Seagate Technology competes through SkyHawk-branded drives tuned for multi-bay NVR environments.
Security and surveillance storage encompasses purpose-built data retention systems engineered for continuous video ingest, long archival windows, and forensic retrieval under write-heavy duty cycles, typically employing surveillance-rated HDDs with workload ratings exceeding 180 TB/year or enterprise SSDs for hot-tier analytics. Solid state drive adoption accelerates in facial recognition and real-time AI analytics pipelines where latency tolerance falls below 10 milliseconds. Cloud storage extends fastest among commercial end users seeking elastic capacity during incident spikes without capital-heavy on-premises expansion. Government buyers dominate hard disk drive volume through multi-petabyte on-premises installations driven by data sovereignty requirements.
FCC equipment authorization rules govern wireless camera and storage transmission gear sold into US installations, while GDPR retention-limit provisions in Europe constrain how long surveillance footage remains stored, directly shaping product feature roadmaps for automated tiering and deletion. China's GB standards and MIIT cybersecurity regulations mandate domestic encryption and local data residency for government surveillance infrastructure. Stakeholders must weigh compliance engineering investments against the architectural flexibility needed to serve multi-jurisdiction deployment contracts.
Market Dynamics
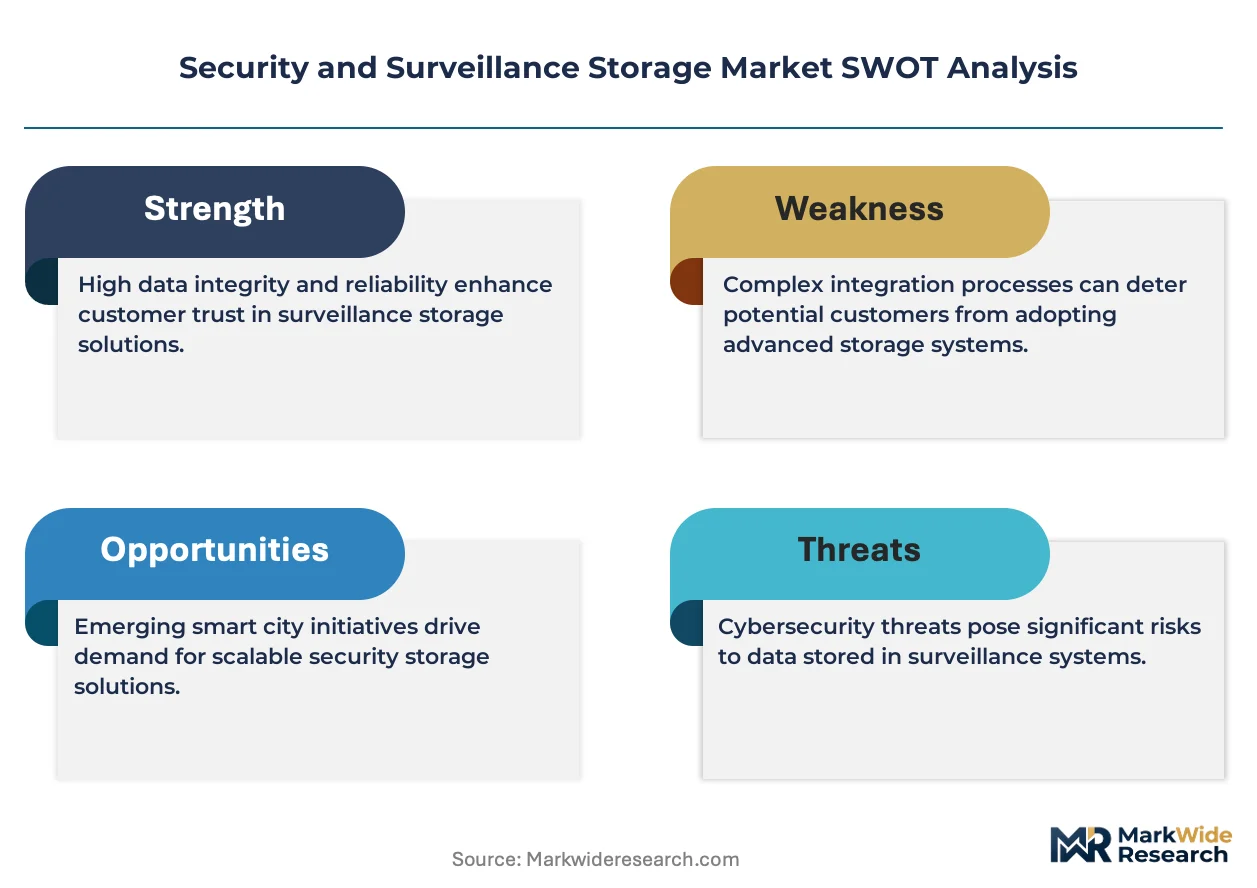
The migration from centralized NVR architectures toward distributed edge-to-cloud pipelines is fragmenting procurement patterns and forcing storage vendors to engineer interoperable firmware stacks that span on-premises, hybrid, and fully cloud-native deployments.
Growth Catalysts
- Smart city infrastructure mandates:Municipal governments in China and India are procuring exabyte-scale archival systems for urban video networks. GB standards and MIIT cybersecurity regulations in China mandate domestic encryption, accelerating local manufacturing partnerships.
- AI analytics pipeline expansion:Facial recognition and real-time behavioral analysis systems require sub-10-millisecond latency tiers that only NVMe-based solid state arrays can deliver. Law enforcement agencies in Germany and the United Kingdom are retrofitting existing camera networks with hot-tier flash storage.
- FCC equipment authorization:Wireless camera and transmission gear sold into United States installations must obtain FCC certification, creating compliance-driven replacement cycles for legacy analog infrastructure across federal and state facilities.
Market Restraints
- Hard disk supply concentration:Surveillance-optimized HDD production concentrates among three vertically integrated manufacturers with captive magnetic media facilities in Thailand and Malaysia, exposing procurement timelines to regional flooding and component allocation decisions.
- GDPR retention-limit friction:European Union data protection rules constrain footage archival windows to strictly necessary periods, compressing the addressable capacity per camera node and forcing automated tiering investments that erode margin on entry-level systems.
- Flash cost structure:NAND wafer pricing volatility and the four-to-six cost multiple over magnetic storage restricts solid state adoption to latency-critical analytics tiers, leaving bulk archival dependent on mechanical media with slower forensic retrieval.
Strategic Opportunities
- India municipal digitization:The Smart Cities Mission and PLI scheme for electronics manufacturing are creating localized assembly requirements for video retention infrastructure, favoring joint ventures with domestic system integrators over direct import models.
- Subscription-based cloud archival:Commercial end users in retail and logistics verticals are abandoning capital-heavy on-premises expansion for elastic capacity contracts that scale during incident spikes without facility construction.
- ISO/IEC 27001 convergence:Information security management certification is becoming a procurement gate for financial services and critical infrastructure operators, creating premium positioning for vendors with pre-validated compliance documentation.
Industry Challenges
- Forensic data integrity certification:Chain-of-custody requirements for courtroom-admissible footage demand write-once-read-many storage configurations with cryptographic hashing, complicating firmware development and extending product validation timelines.
- Legacy analog integration:Hybrid environments combining decades-old coaxial camera networks with modern IP infrastructure require protocol translation hardware and multi-format recording software, inflating deployment complexity and service contract scope.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Security and Surveillance Storage Market |
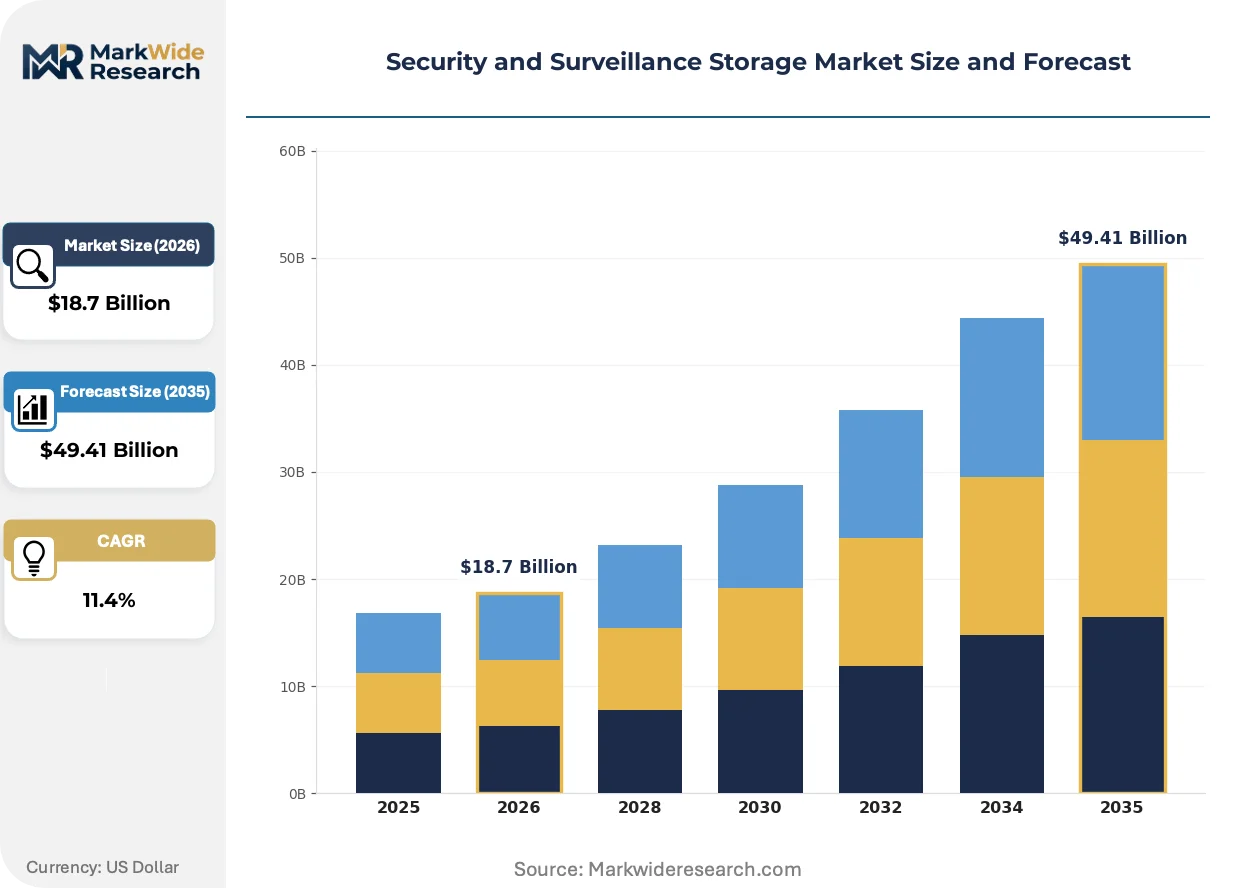
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Disk Drive, Solid State Drive, Cloud Storage, Hybrid Storage Technology: Infrared Cameras, IP Cameras, Analog Cameras, Wireless Cameras End User: Residential, Commercial, Transportation, Government Installation Type: On-premises, Cloud-based, Hybrid, Managed Services |
| Companies Covered | Dell Technologies, NetApp, Cisco Systems, Honeywell International, Western Digital, Seagate Technology, Rasilient Systems, Quantum Corporation, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Security and Surveillance Storage Market Trends and Innovations
Storage architecture is splintering across latency tiers as artificial intelligence inference moves to the edge and regulatory jurisdictions impose conflicting data residency rules on multinational operators.
Surveillance-optimized hard disk firmware is hybridizing rotational media with flash-assisted caching to sustain 24/7 write-intensive duty cycles while accelerating random read patterns for AI analytics. Large-scale municipal operators in Brazil and Saudi Arabia are piloting these hybrid drives in multi-bay NVR environments. The technology is compressing the traditional separation between bulk archival and hot-tier analytics into unified chassis designs that reduce rack space and power draw.
GDPR automated deletion mandates are forcing European manufacturers to engineer policy-driven tiering engines that migrate footage to cryptographically shredded cold storage upon retention expiration. France's CNIL has issued binding guidance on facial recognition storage limits that directly shapes product roadmaps. Commercial buyers in Germany and the Netherlands are prioritizing systems with pre-configured compliance workflows over customizable platforms that require legal review.
Consumption patterns among commercial security buyers are fragmenting procurement authority between facilities management, IT security, and legal compliance functions. Value-added distributors in the United States are responding with cross-functional presales teams that bridge technical specification and regulatory documentation. Retail and logistics verticals show the most pronounced shift, with procurement committees now mandating total-cost-of-ownership models that internalize electricity, cooling, and compliance labor over five-year horizons rather than upfront capital expenditure alone.
Security and Surveillance Storage Market Segmentation
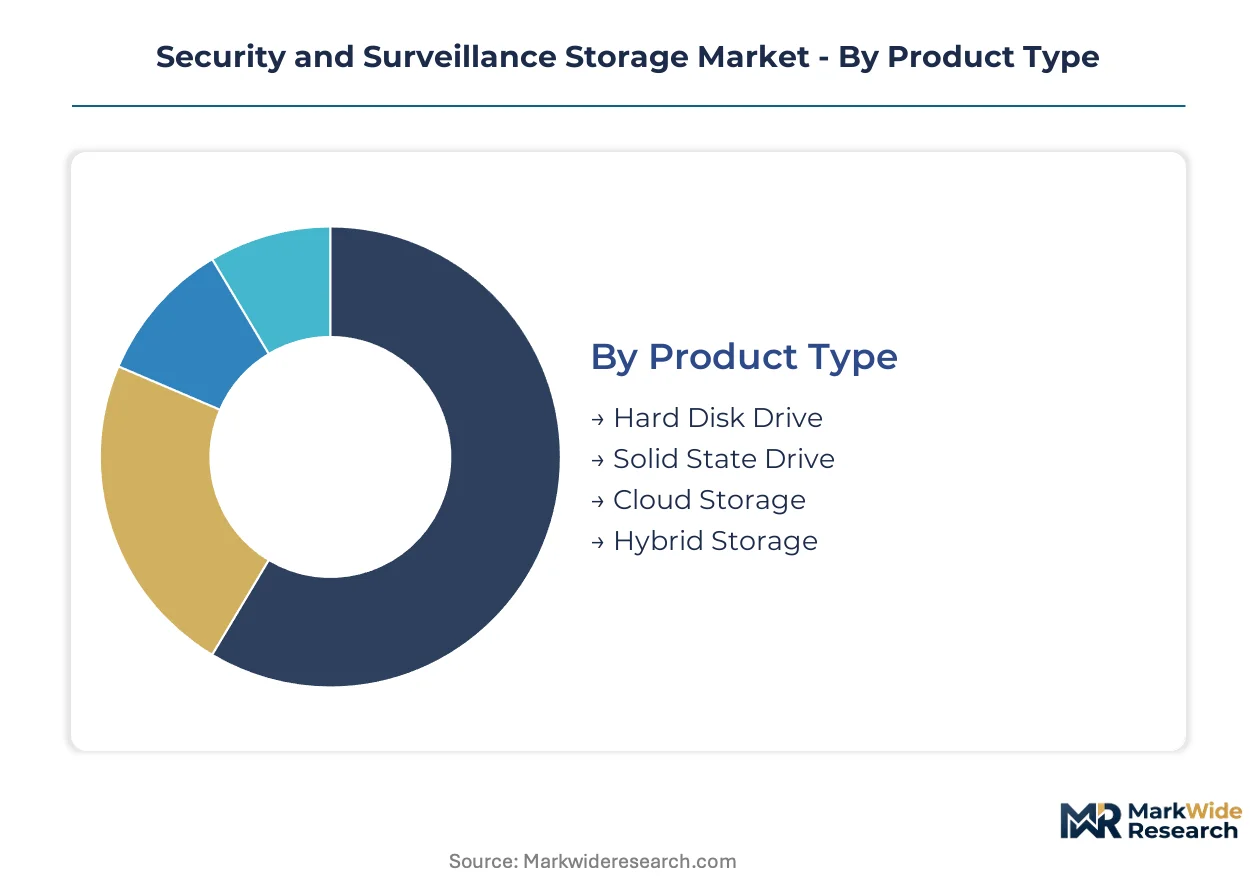
Storage procurement in security and surveillance fragments across four distinct axes: media technology, camera infrastructure, end-use verticals, and deployment architecture. Each dimension carries divergent margin profiles, service intensity requirements, and regulatory exposure that reshape vendor go-to-market priorities.
Product Type:
After-sales service intensity varies dramatically across storage media, with mechanical drives demanding predictive health monitoring and cloud tiers requiring continuous SLA management.
- Hard Disk Drive:Surveillance-optimized HDDs with workload ratings exceeding 180 TB/year dominate municipal procurement in China and India where exabyte-scale archival infrastructure requires 24/7 write endurance. Thailand and Malaysia host the vertically integrated manufacturing bases that supply these drives, exposing delivery timelines to regional climate disruptions.
- Solid State Drive:NVMe-based arrays deliver sub-10-millisecond latency for facial recognition and real-time behavioral analytics pipelines. Law enforcement agencies in Germany and the United Kingdom are retrofitting existing networks with hot-tier flash storage to support AI inference at the edge.
- Cloud Storage:Elastic capacity contracts appeal to retail and logistics operators seeking incident-spike scalability without facility construction.
- Hybrid Storage:Flash-assisted caching layered atop rotational media compresses rack space and power draw in multi-bay NVR environments.
By volume, Hard Disk Drive leads. By growth pace, Cloud Storage is ahead.
Technology:
Camera technology selection dictates storage throughput requirements and archival compression ratios, with IP networks generating tenfold data volumes over legacy analog infrastructure.
- IP Cameras:Network-based video capture streams continuous high-resolution feeds demanding tiered storage architectures with automated policy-driven migration. Smart city deployments across São Paulo and Riyadh are standardizing on IP backbones to consolidate physical security with IoT sensor networks.
- Infrared Cameras:Low-light imaging systems produce variable bit-rate streams that spike storage consumption during nighttime operational windows. Critical infrastructure operators in the United States and Saudi Arabia deploy these for perimeter monitoring with dedicated archival tiers for thermal metadata.
- Analog Cameras:Coaxial legacy infrastructure persists in cost-constrained retrofit environments requiring protocol translation hardware.
- Wireless Cameras:FCC equipment authorization mandates govern transmission gear sold into United States federal and state facilities.
IP Cameras command the largest installed base. Infrared Cameras are expanding most quickly in energy and defense applications.
End User:
Buyer sophistication and procurement authority fragmentation distinguish residential, commercial, and institutional segments, with government contracts imposing the most stringent chain-of-custody documentation.
- Government:Multi-petabyte on-premises installations driven by data sovereignty requirements and courtroom-admissible forensic standards. China's MIIT cybersecurity regulations and GB standards mandate domestic encryption and local data residency for surveillance infrastructure.
- Commercial:Retail and logistics verticals are shifting procurement committees toward total-cost-of-ownership models that internalize electricity, cooling, and compliance labor over five-year horizons.
- Transportation:Mobile and fixed transit networks require vibration-resistant storage with rapid incident retrieval capabilities.
- Residential:Consumer-grade cloud subscriptions dominate with minimal on-premises hardware and self-service support models.
Government buyers anchor HDD volume. Commercial users are gaining share fastest through cloud migration.
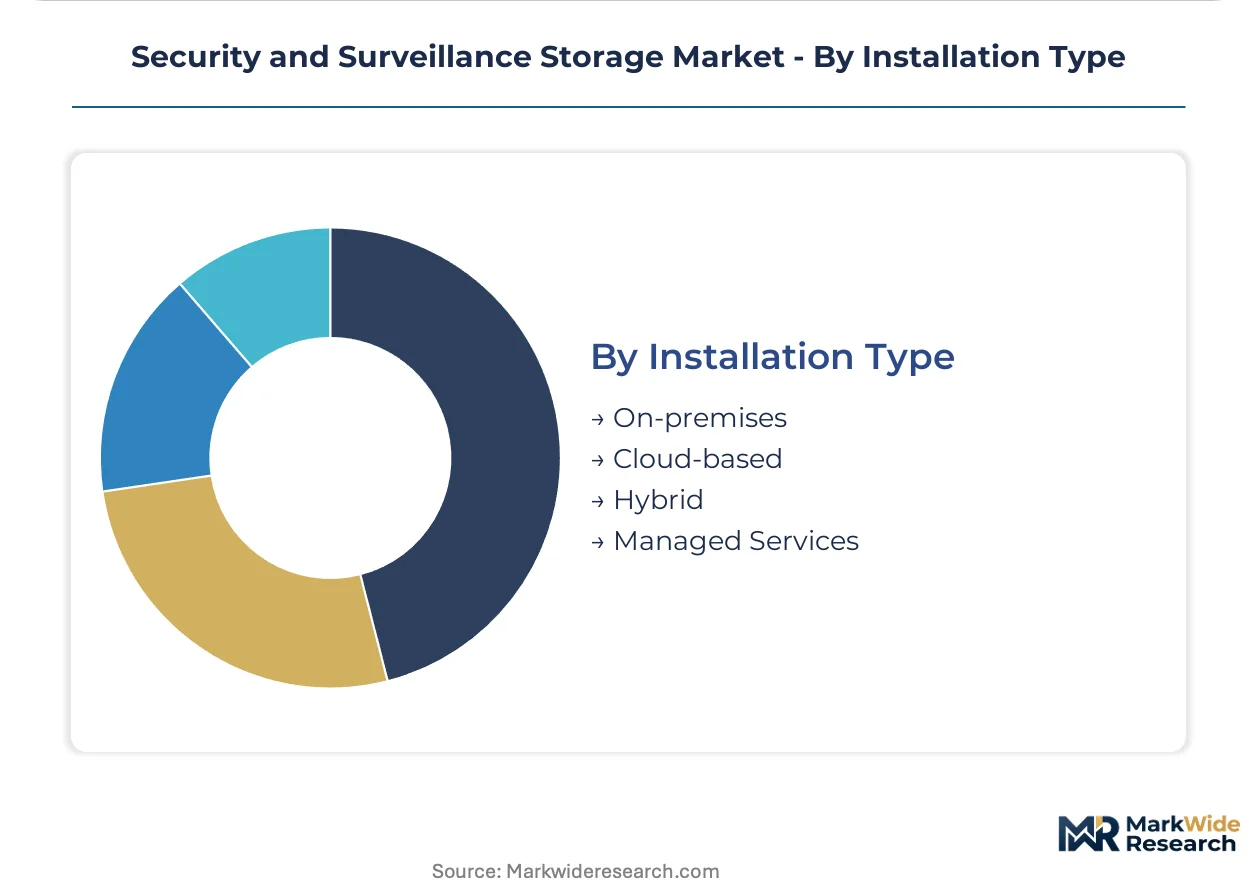
Installation Type:
Deployment architecture determines capital intensity, operational control, and regulatory compliance burden, with hybrid models gaining traction among organizations navigating data residency conflicts.
- On-premises:Physical infrastructure ownership satisfies GDPR retention-limit constraints and data sovereignty mandates in European and Chinese jurisdictions. France's CNIL has issued binding guidance on facial recognition storage limits that favor localized control.
- Hybrid:Edge-to-cloud pipelines fragment procurement patterns and force interoperable firmware stacks spanning on-premises and cloud-native tiers. Municipal operators in Brazil and Saudi Arabia are piloting unified chassis designs.
- Cloud-based:Fully managed capacity eliminates facility construction for commercial end users with elastic incident-response requirements.
- Managed Services:Outsourced operations bundle hardware, software, and compliance labor under recurring contracts.
On-premises retains the largest capacity footprint. Hybrid architectures show the steepest expansion trajectory as AI analytics migrate to the edge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand and Malaysia export surveillance-optimized hard disk drives to municipal buyers in China and India, where smart city infrastructure mandates are driving exabyte-scale procurement. Regional manufacturing concentration in Southeast Asia shapes delivery timelines for global security storage deployments.
China
Massive urban surveillance programs require multi-petabyte archival infrastructure with 24/7 write endurance. MIIT cybersecurity regulations and GB standards mandate domestic encryption and local data residency for government contracts. Shenzhen and Hangzhou host manufacturing partnerships accelerating localized system assembly.
United States
Federal and state facilities are replacing legacy analog infrastructure with IP camera networks demanding tiered storage architectures. FCC equipment authorization rules govern wireless transmission gear, creating compliance-driven replacement cycles. Texas and California data centers are expanding edge-to-cloud pipelines for law enforcement analytics.
Germany
Law enforcement agencies retrofit existing camera networks with NVMe-based flash storage for sub-10-millisecond AI inference. GDPR retention-limit provisions constrain footage archival windows, forcing automated tiering investments. Berlin and Munich municipal operators prioritize pre-configured compliance workflows over customizable platforms.
India
The Smart Cities Mission and PLI scheme for electronics manufacturing create localized assembly requirements for video retention infrastructure. Municipal governments in Delhi and Mumbai are procuring high-capacity NVR systems for urban video networks. Joint ventures with domestic system integrators are displacing direct import models.
Saudi Arabia
Critical infrastructure operators deploy infrared camera systems with dedicated archival tiers for thermal metadata. Large-scale municipal operators in Riyadh pilot hybrid drives combining rotational media with flash-assisted caching. Government procurement favors unified chassis designs reducing rack space and power draw.
Security and Surveillance Storage Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement authority between facilities management, IT security, and legal compliance functions. The vendor base spans server-storage convergence portfolios, surveillance-optimized firmware specialists, and hybrid cloud integrators. Two strategic archetypes dominate: vertically integrated drive manufacturers with captive magnetic media facilities, and converged infrastructure vendors capturing hybrid installation contracts. Competitive moves center on interoperable firmware stacks spanning on-premises and cloud-native tiers, plus predictive health monitoring services for mechanical drive deployments.
Within the drive manufacturing tier, Western Digital and Seagate Technology exemplify the vertically integrated archetype with Thailand and Malaysia-based production. Dell Technologies occupies a position among converged infrastructure vendors leveraging server-storage portfolios for hybrid deployment contracts. These three anchors represent the spectrum from component specialization to systems integration.
| Leading Market Players |
|---|
| Dell Technologies |
| NetApp |
| Cisco Systems |
| Honeywell International |
| Western Digital |
| Seagate Technology |
| Rasilient Systems |
| Quantum Corporation |
| IBM |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Southeast Asian magnetic media fabrication facilities is tightening component allocation timelines and amplifying pricing leverage for vertically integrated drive manufacturers serving municipal procurement cycles. This utilization squeeze simultaneously pressures NVR system integrators to absorb cost increases or extend delivery windows for exabyte-scale archival contracts.
Pricing Analysis
Current-generation surveillance-optimized HDDs command a four-to-six cost multiple over prior-generation archival drives, while next-generation hybrid flash-assisted units carry additional premiums for sub-10-millisecond latency tiers. Project-based pricing dominates municipal and government contracts with multi-year offtake agreements, whereas commercial buyers face subscription-tiered SaaS models for elastic cloud capacity. Price differentiation rests on workload certification grade and geographic delivery cost, with GDPR-compliant automated tiering systems carrying certification premiums. Cost compression in entry-level NVR configurations is intensifying due to flash NAND wafer volatility, though government buyers show lowest price sensitivity given data sovereignty mandates.
Supply Chain Analysis
Contract manufacturing for surveillance storage systems concentrates among Thailand and Malaysia-based vertically integrated facilities with captive magnetic media production. Component sourcing draws from Malaysian substrate fabrication, Thai final assembly operations, and Chinese controller semiconductor supply. Rare earth magnet dependencies and NAND wafer supply expose procurement timelines to commodity price volatility and regional climate disruptions. Distribution runs through value-added distributors bridging facilities management, IT security, and legal compliance functions in fragmented procurement environments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from cloud-native archival platforms that displace capital-heavy on-premises infrastructure among commercial buyers seeking elastic incident-spike capacity.
For Market Incumbents: Entrench hybrid edge-to-cloud firmware interoperability as the defensive moat against pure-play cloud entrants. Pursue backward integration into controller semiconductor supply to reduce exposure to Chinese chip allocation cycles. Anchor municipal relationships through predictive health monitoring services that extend mechanical drive replacement revenue streams. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point given localized assembly requirements under India's PLI scheme and fragmented procurement authority. Cloud-native managed services for retail and logistics verticals bypass capital barriers that favor incumbents. Partner with domestic system integrators in Delhi and Mumbai to satisfy Smart Cities Mission localization mandates. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-technology play because regulatory fragmentation across GDPR, FCC, and MIIT jurisdictions perpetuates demand for jurisdiction-specific storage architectures. Acquisition targets should display pre-validated ISO/IEC 27001 documentation and multi-jurisdiction firmware certification. Monitor NAND wafer pricing inflections as the signal for flash-assisted hybrid drive margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Firmware Stack Development | Interoperable edge-to-cloud architectures capture municipal contracts in São Paulo and Riyadh. |
| Predictive Health Monitoring Service | Continuous drive health analytics extend replacement cycles for Thailand-manufactured HDD deployments. |
| GDPR Automated Tiering Certification | Pre-configured compliance workflows satisfy France's CNIL facial recognition storage limits. |
| Joint Venture with Domestic Integrators | Localized assembly partnerships satisfy India's PLI scheme for electronics manufacturing. |
| NVMe Array Retrofit Programs | Sub-10-millisecond flash tiers capture German law enforcement AI inference upgrade cycles. |
Research Methodology
Cross-validation between primary interviews with NVR system integrators, municipal procurement officers, and surveillance storage firmware engineers anchors the qualitative findings against secondary validation. Bottom-up triangulation incorporates customs records for Thailand and Malaysia HDD exports, FCC equipment authorization filings, and MIIT cybersecurity compliance documentation. Top-down calibration draws from smart city infrastructure budget disclosures and exabyte-scale archival contract awards.
Calibration against historical procurement velocity and technology transition patterns shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include storage media technology, camera infrastructure type, end-use vertical, and deployment architecture complexity. CAGRs derive from installed base expansion rates, retention window regulatory changes, and AI analytics pipeline penetration curves. Forecast inputs incorporate NAND wafer pricing volatility indices and municipal digitization program timelines.
Practitioners should monitor MIIT cybersecurity regulation amendments and GDPR retention-limit enforcement actions for early signals of architectural demand shifts. Forecasts reflect assumptions around continued analog-to-IP camera network transitions and sustained data sovereignty requirements. Quarterly review of Southeast Asian manufacturing capacity utilization and municipal smart city budget allocations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
United Kingdom Surveillance Analog Camera Market
Video Surveillance Systems
Europe Video Surveillance Systems Market
Video Surveillance Systems
Middle East and Africa Surveillance Analog Camera Market
Video Surveillance Systems
India Video Surveillance Market
Video Surveillance Systems
Middle East and Africa Video Surveillance Market
Video Surveillance Systems
Middle East and Africa Surveillance IP Cameras Market
Video Surveillance Systems
Asia-Pacific Surveillance Storage Market
Video Surveillance Systems
Inspection Camera System Market
Video Surveillance Systems
Connected Enterprise Video Surveillance Solutions Market
Video Surveillance Systems
Germany Video Surveillance Market
Video Surveillance Systems
United States Surveillance IP Camera Market
Video Surveillance Systems
Global Mobile Video Surveillance Market
Video Surveillance Systems
AI Surveillance Camera Market
Video Surveillance Systems
Mexico Surveillance Analog Camera Market
Video Surveillance Systems
United States Surveillance Camera Market
Video Surveillance Systems
AI Surveillance System Market