
 Middle East and Africa Public Infrastructure Safety Market | 2026-2036
Middle East and Africa Public Infrastructure Safety Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Public Infrastructure Safety Market Insights
Public-private partnership channels for infrastructure safety deployment is fragmenting across the Middle East and Africa as sovereign wealth funds, municipal authorities, and private operators pursue divergent procurement models. Cisco Systems Inc. leverages its established networking infrastructure to anchor large-scale smart city integrations in Gulf states. Huawei Technologies competes on cost-optimized surveillance bundles, while Nokia specializes in mission-critical communications networks for transportation safety applications.
Middle East and Africa Public Infrastructure Safety encompasses the integrated hardware, software, and service architectures designed to protect critical public assets from physical threats, operational failures, and environmental hazards, incorporating real-time sensor networks, centralized command platforms, and automated alert protocols with sub-second response thresholds. Surveillance Systems dominates current procurement volumes as legacy analog upgrades proceed across North African municipalities. AI Monitoring represents the fastest-expanding technology segment, with margin pools concentrating in cloud-based analytics subscriptions rather than hardware sales. Emergency Response Solutions show structural growth potential where Gulf governments mandate unified dispatch platforms linking police, medical, and fire services under single command hierarchies.
Saudi Arabia's SAMR and the UAE's telecommunications regulator enforce interoperability standards that shape vendor qualification and system integration requirements across national infrastructure programs. South Africa's national standards body mandates fire safety equipment certifications that restrict market access for uncertified suppliers. Stakeholders must monitor how biometric data protection frameworks evolve across jurisdictions, as privacy-compliant access control systems will determine which technology vendors retain eligibility for government facility contracts.
Market Dynamics
Smart city mandates across Gulf Cooperation Council states are compressing procurement timelines and forcing interoperability between legacy analog surveillance and AI-native platforms, reshaping vendor qualification requirements.
Growth Catalysts
- UAE Transportation Modernization:Metro and airport authorities bundle surveillance with AI monitoring under single tender frameworks, consolidating vendor relationships and accelerating deployment cycles.
- SAMR Technical Standards:Saudi Arabia's interoperability mandates for emergency response architectures create pull-through demand for integrated command platforms linking police, medical, and fire services.
- Edge Computing Deployment:Real-time video analytics at the network edge reduces latency for threat detection, enabling sub-second alert protocols in critical infrastructure facilities.
Market Restraints
- Semiconductor Supply Concentration:GPU and specialized AI chip sourcing concentrates in East Asian foundries, exposing Gulf deployment schedules to geopolitical shipping disruptions.
- Biometric Data Friction:Evolving privacy frameworks across Middle East and Africa jurisdictions create compliance uncertainty for access control vendors deploying facial recognition systems.
- Legacy Analog Upgrade Costs:North African municipalities face capital intensity in replacing coaxial cable infrastructure with IP-based networks before AI analytics deployment.
Strategic Opportunities
- South African Fire Safety Certification:Uncertified supplier restrictions create protected margin pools for compliant equipment manufacturers serving government facility contracts.
- Cloud Analytics Subscriptions:Margin concentration shifts from hardware sales to recurring software revenue as Gulf operators adopt SaaS-based threat detection platforms.
- 5G Mission-Critical Networks:Transportation safety applications in UAE and Saudi Arabia drive demand for ultra-reliable low-latency communications replacing legacy TETRA systems.
Industry Challenges
- Cyber-Physical Integration Talent:Shortage of engineers capable of bridging operational technology and information security domains delays project commissioning.
- Interoperability Testing Timelines:Multi-vendor system certification against SAMR and UAE telecommunications standards extends procurement cycles.
- Legacy Dispatch System Migration:Unified command hierarchies require retraining emergency responders accustomed to siloed police, medical, and fire communication protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Public Infrastructure Safety Market |
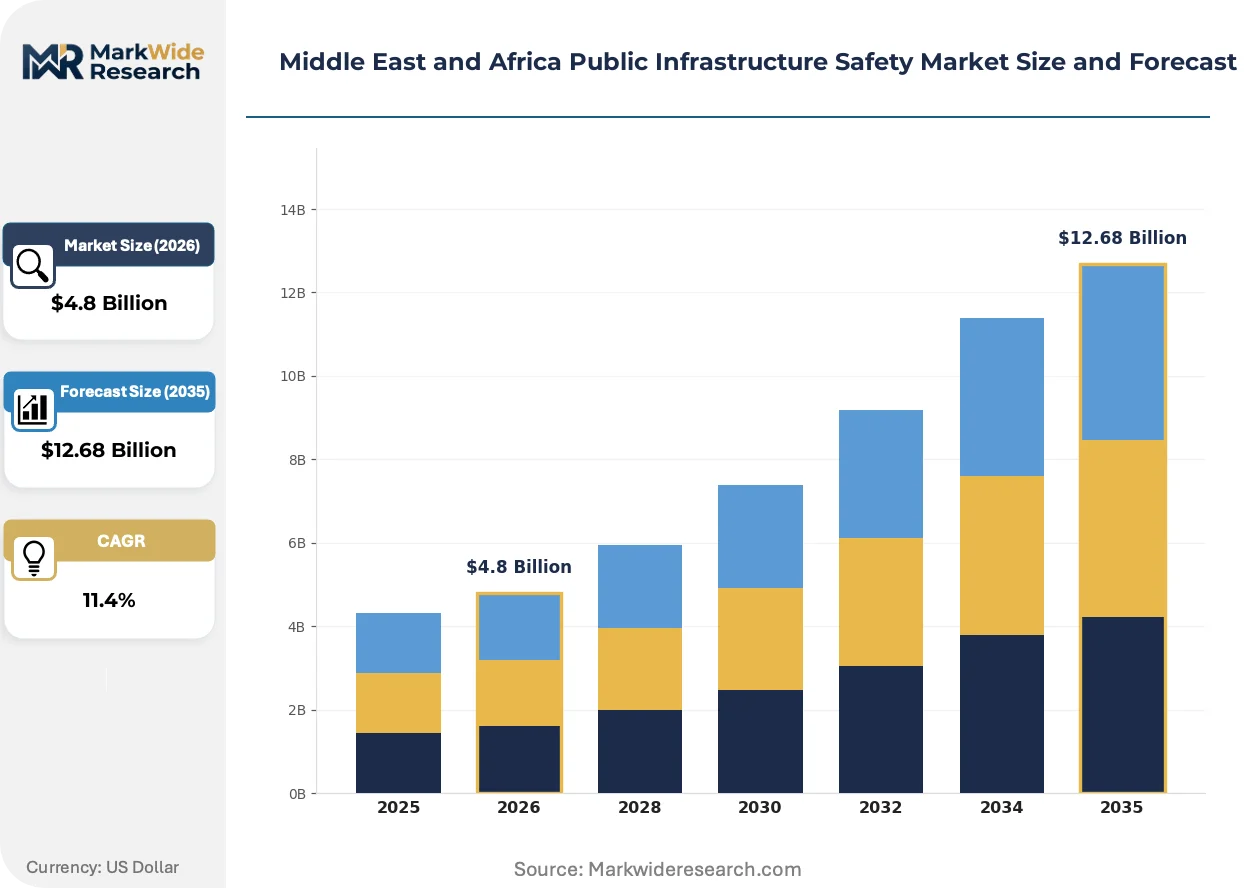
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surveillance Systems, Fire Safety Equipment, Emergency Response Solutions, Access Control Systems Technology: AI Monitoring, IoT Devices, Cloud Solutions, Biometric Systems End User: Government Facilities, Transportation Networks, Educational Institutions, Utilities Application: Disaster Management, Crime Prevention, Traffic Monitoring, Environmental Safety |
| Companies Covered | Cisco Systems Inc., NEC Corporation, Hexagon AB, Atos SE, Telefonaktiebolaget LM Ericsson, L3Harris Technologies Inc., Nokia, Huawei Technologies, Motorola Solutions, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Public Infrastructure Safety Market Trends and Innovations
AI-native monitoring architectures are collapsing the traditional separation between surveillance hardware and analytics software, compressing value capture toward platform vendors with integrated cloud stacks.
Computer vision inference at the network edge is collapsing latency thresholds for threat detection in airport and metro environments. Dubai's aviation authority deploys edge-based baggage screening analytics that process video feeds locally rather than routing to centralized data centers. This compression of response time from seconds to milliseconds is forcing legacy DVR manufacturers to partner with AI software vendors or exit transportation tenders.
Saudi Arabia's SAMR and the UAE's telecommunications regulator enforce interoperability standards that reshape vendor qualification across national infrastructure programs. Equipment suppliers must pre-certify systems against unified emergency response protocols before tender eligibility. Gulf government facilities now require documented API compatibility between competing manufacturers, accelerating consolidation toward platform-integrated vendors.
Single-tender bundling of surveillance hardware with AI monitoring and maintenance services displaces fragmented procurement across UAE transportation authorities. Metro operators in Dubai and Abu Dhabi now contract decade-long service agreements encompassing equipment refresh cycles and software updates. This shift concentrates vendor relationships and shifts technical risk from municipal buyers to integrated platform providers.
Middle East and Africa Public Infrastructure Safety Market Segmentation
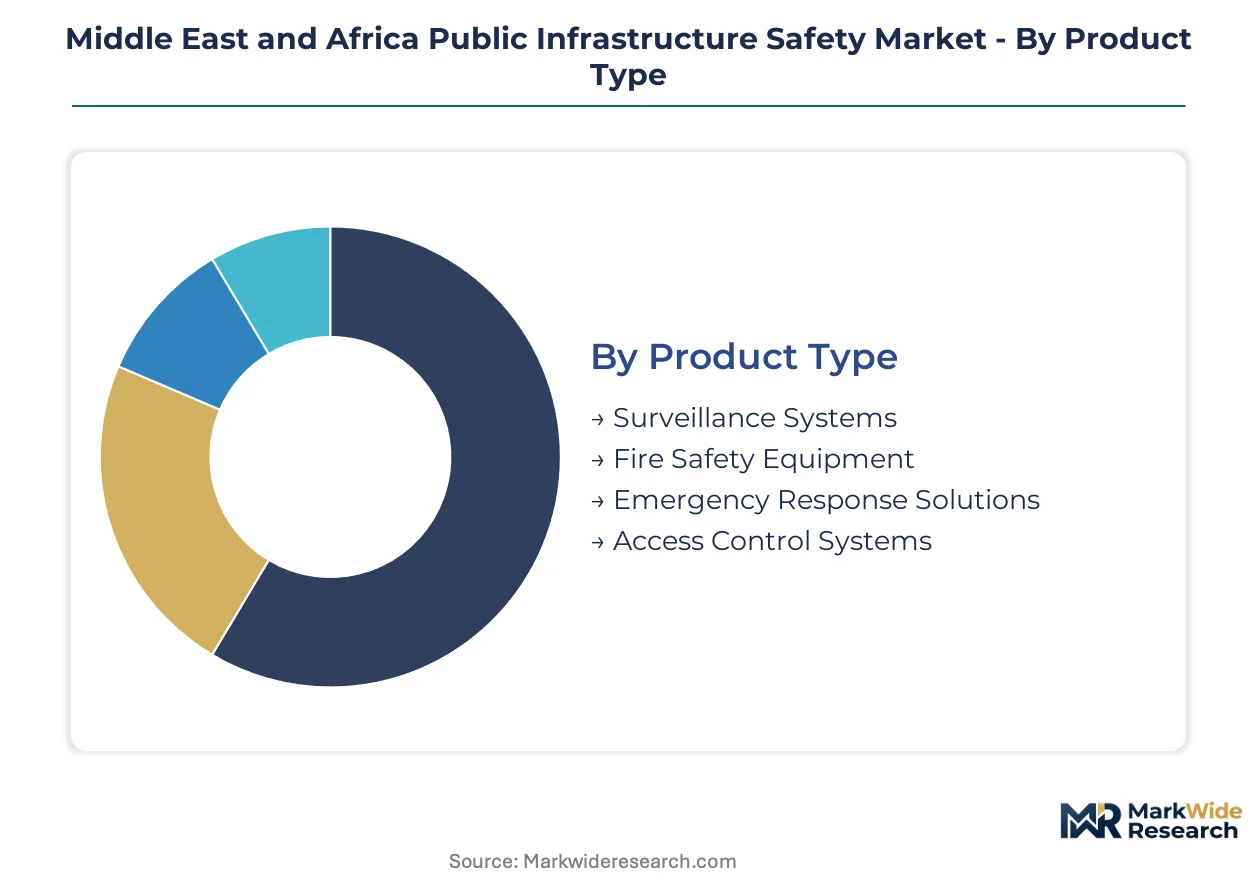
Segmentation in Middle East and Africa Public Infrastructure Safety reveals how procurement priorities diverge across technology maturity, regulatory pressure, and operational risk profiles. Understanding these splits enables vendors to align product roadmaps with the specific compliance and integration demands of Gulf smart city programs versus North African legacy upgrade cycles.
Product Type:
Mature hardware categories dominate current procurement volumes while software-integrated platforms capture expansion margins across the forecast window.
- Surveillance Systems:Analog-to-IP upgrades and multi-sensor arrays form the backbone of metro and airport security architectures in Dubai and Riyadh. Demand concentrates in UAE transportation authorities bundling decade-long service agreements with equipment refresh cycles.
- Emergency Response Solutions:Unified dispatch platforms integrate police, medical, and fire command hierarchies under single interoperability protocols mandated by SAMR technical standards. Saudi Arabia's government facilities drive pull-through demand as legacy siloed systems face mandatory replacement.
- Fire Safety Equipment:South Africa's national standards body restricts market access through certification requirements that protect compliant suppliers serving government contracts.
- Access Control Systems:Biometric deployments face friction from evolving privacy frameworks across Middle East and Africa jurisdictions.
Surveillance Systems retains volume leadership; Emergency Response Solutions holds the steepest expansion curve.
Technology:
Cost-to-performance ratios separate cloud-native deployments from edge-heavy architectures in bandwidth-constrained environments.
- AI Monitoring:Real-time video analytics at the network edge collapse latency thresholds for threat detection in airport baggage screening and metro platform monitoring. Margin pools concentrate in recurring cloud-based analytics subscriptions rather than hardware sales.
- Cloud Solutions:SaaS-based threat detection platforms shift technical risk from municipal buyers to integrated vendors across UAE single-tender frameworks. Gulf operators adopt these architectures to compress procurement timelines and force interoperability between legacy and AI-native systems.
- IoT Devices:Sensor networks for environmental hazard detection expand in Saudi smart city corridors.
- Biometric Systems:Facial recognition deployments face compliance uncertainty as data protection frameworks evolve across multiple jurisdictions.
AI Monitoring captures the premium pricing tier; Cloud Solutions is expanding most quickly through recurring revenue conversion.
End User:
Public procurement concentration versus private operator risk appetite shapes vendor qualification requirements and contract structures.
- Government Facilities:Gulf Cooperation Council states accelerate integrated safety platform procurement through sovereign wealth fund channels. SAMR and UAE telecommunications regulator mandates enforce pre-certification against unified emergency response protocols before tender eligibility.
- Transportation Networks:Metro and airport authorities in Dubai and Abu Dhabi consolidate vendor relationships through bundled surveillance-AI-maintenance tenders. Edge computing deployments for real-time analytics reduce latency to sub-second alert thresholds.
- Utilities:Critical infrastructure protection drives demand for cyber-physical integration in power and water distribution networks.
- Educational Institutions:Campus safety upgrades proceed through municipal budget allocations with slower procurement cycles.
Government Facilities anchors contract value; Transportation Networks delivers the steepest technology refresh velocity.
Application:
Regulatory mandate intensity varies sharply between life-safety domains and operational efficiency use cases.
- Disaster Management:Unified command hierarchies linking police, medical, and fire services require retraining emergency responders accustomed to siloed communication protocols. Saudi Arabia's interoperability standards reshape system integration requirements across national infrastructure programs.
- Crime Prevention:Computer vision inference at the network edge processes video feeds locally rather than routing to centralized data centers. Dubai's aviation authority deploys edge-based baggage screening analytics that compress response time from seconds to milliseconds.
- Traffic Monitoring:5G mission-critical networks replace legacy TETRA systems for ultra-reliable low-latency communications in UAE and Saudi Arabia transportation corridors.
- Environmental Safety:Sensor networks for hazard detection expand where industrial facilities interface with populated zones.
Disaster Management commands the highest integration complexity; Crime Prevention is gaining share fastest through AI-native platform displacement of legacy DVR architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Gulf Cooperation Council states where sovereign procurement compresses vendor margins, while North African municipalities absorb legacy upgrade costs that elongate deployment cycles. This asymmetry fragments vendor strategies across the Middle East and Africa Public Infrastructure Safety landscape.
Saudi Arabia
SAMR technical standards for smart city infrastructure mandate interoperable emergency response architectures linking police, medical, and fire services. Government facilities accelerate integrated safety platform procurement through sovereign wealth fund channels. Riyadh's metro authority bundles decade-long surveillance-AI-maintenance service agreements that shift technical risk to platform vendors.
United Arab Emirates
Dubai's aviation authority deploys edge-based baggage screening analytics that compress threat detection latency from seconds to milliseconds. The telecommunications regulator enforces interoperability standards that reshape vendor qualification across national infrastructure programs. Abu Dhabi metro operators consolidate vendor relationships through single-tender frameworks encompassing equipment refresh cycles.
South Africa
The national standards body mandates fire safety equipment certifications that restrict market access for uncertified suppliers serving government facility contracts. Municipal procurement proceeds through slower budget allocation cycles than Gulf sovereign channels. Johannesburg and Cape Town educational institutions drive campus safety upgrades with constrained capital deployment timelines.
Egypt
North African municipalities face capital intensity in replacing coaxial cable infrastructure with IP-based networks before AI analytics deployment. Government facilities pursue analog-to-IP surveillance upgrades through fragmented procurement frameworks. Cairo's transportation network modernization proceeds through incremental budget releases rather than bundled long-term service agreements.
Israel
Critical infrastructure protection drives demand for cyber-physical integration in power and water distribution networks. National security frameworks shape vendor qualification requirements for government facility access control systems. Tel Aviv's technology corridor concentrates edge computing deployment expertise for transportation safety applications.
Middle East and Africa Public Infrastructure Safety Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensor arrays and specialized communications hardware. Market structure consolidates around three to five full-stack vendors capable of pre-certifying against SAMR and UAE interoperability mandates, while dozens of hardware fabricators compete on cost-optimized surveillance bundles. Two strategic archetypes dominate: networking infrastructure anchors leveraging established enterprise relationships, and mission-critical communications specialists targeting transportation safety tenders. Competitive moves concentrate on multi-vendor certification partnerships and decade-long service agreement structures that displace fragmented procurement.
Within the networking infrastructure tier, Cisco Systems Inc. and Huawei Technologies occupy positions shaped by contrasting procurement channel access. Nokia exemplifies the mission-critical communications archetype, with its specialization in ultra-reliable low-latency networks for transportation safety applications. Motorola Solutions represents the integrated command platform segment where unified dispatch hierarchies displace siloed legacy systems. These three anchors illustrate how vendor qualification against Gulf interoperability standards determines tender eligibility across the Middle East and Africa Public Infrastructure Safety landscape.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| NEC Corporation |
| Hexagon AB |
| Atos SE |
| Telefonaktiebolaget LM Ericsson |
| L3Harris Technologies Inc. |
| Nokia |
| Huawei Technologies |
| Motorola Solutions |
| Others |
Pricing and Supply Chain Analysis
The Strait of Hormuz freight corridor's volatility shapes component landed costs for Gulf deployment schedules, compressing margins on standard surveillance hardware while amplifying premiums for configured-to-order emergency response platforms that absorb logistics risk into fixed-price contracts.
Pricing Analysis
The customization-premium spread between standard surveillance bundles and SAMR-certified integrated command platforms exceeds threefold across UAE transportation tenders. Project-based pricing dominates government facility procurement, with decade-long service agreements bundling equipment refresh cycles and cloud analytics subscriptions. Price differentiation rests on interoperability certification against Saudi and UAE technical standards, plus after-sales service depth. Pricing pressure stems from Huawei's cost-optimized surveillance bundles competing against Cisco's networking-anchored premiums. Municipal buyers in North Africa exhibit highest price sensitivity due to capital constraints on analog-to-IP infrastructure upgrades.
Supply Chain Analysis
Tariff exposure between East Asian semiconductor foundries and Gulf deployment sites dominates supply chain risk planning for AI chip sourcing. GPU and specialized inference processors concentrate in Taiwan, South Korea, and China, with raw material dependencies spanning silicon wafers, rare earth elements for sensor arrays, and cobalt for battery-backed edge devices. Single-source vulnerability in advanced node semiconductor fabrication threatens Saudi smart city timelines. Distribution runs through sovereign wealth fund procurement channels that consolidate vendor relationships and compress payment cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market's defensive moat derives from regulatory entrenchment: SAMR and UAE interoperability mandates create certification barriers that pre-qualify only platform-integrated vendors for national infrastructure tenders.
For Market Incumbents: Build switching-cost moats through API-locked cloud analytics subscriptions that embed technical risk transfer into decade-long service agreements. Defend against Huawei's cost-optimized surveillance bundles by deepening certification investment against evolving biometric data protection frameworks. Anchor capacity addition in Riyadh and Dubai to compress response times for emergency response platform deployment. For New Entrants and Emerging Players: Mid-market educational institutions in South Africa and Egypt represent the most penetrable entry point, as these segments operate outside sovereign wealth fund procurement concentration and absorb longer sales cycles. Municipal fire safety equipment in Johannesburg offers protected margin pools through national standards body certification requirements. Pursue partnership-based go-to-market angles with established networking infrastructure vendors lacking mission-critical communications specialization. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate-owned safety technology divisions lacking cloud-native platform integration. Long-term viability favors vendors with demonstrated SAMR pre-certification and recurring revenue conversion above hardware sales. Watch for biometric privacy framework harmonization across Gulf Cooperation Council states as the inflection signal for access control system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Interoperability Certification Investment | SAMR and UAE telecommunications regulator pre-qualification secures tender eligibility across national infrastructure programs. |
| Cloud Analytics Platform Integration | SaaS-based threat detection subscriptions shift margin capture from hardware sales toward recurring software revenue pools. |
| Edge Computing Deployment Partnership | Real-time video analytics at network edge reduces latency for Dubai aviation authority baggage screening applications. |
| Mission-Critical Communications Specialization | Ultra-reliable low-latency 5G networks displace legacy TETRA systems in UAE and Saudi Arabia transportation corridors. |
| Biometric Privacy Compliance Engineering | Data protection framework alignment preserves vendor eligibility for government facility access control contracts. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with smart city program directors at Gulf sovereign wealth funds, procurement leads at UAE metro authorities, SAMR certification engineers, and emergency response system integrators. Secondary validation drew from SAMR technical standard publications, UAE telecommunications regulator interoperability mandates, South African national standards body certification databases, and customs records of surveillance equipment imports. Bottom-up segment sizing triangulated against top-down infrastructure spending forecasts across the analysis window.
Calibration anchored volume and value outputs to documented procurement timelines for Riyadh metro and Dubai aviation authority tenders, with segmentation modeled across product type, technology deployment architecture, end-user procurement channel, and application risk profile. CAGRs derived from weighted regression of historical deployment cycles against smart city mandate acceleration. Edge computing adoption curves and cloud analytics subscription conversion rates served as industry-specific forecast inputs.
Stress conditions across semiconductor shipping disruptions, biometric privacy framework divergence, and sovereign budget reallocation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about interoperability certification timelines and emergency response protocol unification. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Critical Infrastructure Protection
GCC Protective Relay Market
Critical Infrastructure Protection
Global High Integrity Pressure Protection System (HIPPS) Market
Critical Infrastructure Protection
Counter Cyberterrorism Market
Critical Infrastructure Protection
Asia Pacific Tank Protection Market
Critical Infrastructure Protection
North America Public Infrastructure Safety Market
Critical Infrastructure Protection
Global Airport and Marine Port Security Market
Critical Infrastructure Protection
Threat Lifecycle Services Market
Critical Infrastructure Protection
Tank Protection Market
Critical Infrastructure Protection
Utilities Security Market
Critical Infrastructure Protection
Perimeter Defense System Market
Critical Infrastructure Protection
Europe Pipeline Security Market
Critical Infrastructure Protection
Critical Infrastructure Monitoring Market
Critical Infrastructure Protection
Continuous Threat Exposure Management Market
Critical Infrastructure Protection
Global Perimeter Protection Market
Critical Infrastructure Protection
Middle East and Africa Pipeline Security Market
Critical Infrastructure Protection
Smart Sandbag Market