
 Global Mobile Video Surveillance Market | 2026-2036
Global Mobile Video Surveillance Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile Video Surveillance Market Foresight
ISO 9001 quality management certification is bifurcating the competitive landscape between qualified system integrators and unverified hardware assemblers. Hangzhou Hikvision Digital Technology Co., Ltd. leverages its vertically integrated sensor manufacturing to dominate price-sensitive procurement cycles. Dahua Technology Co., Ltd. sustains R&D intensity across AI-powered video analytics. Axis Communications AB differentiates through open-platform architecture that accommodates third-party software integration.
Mobile video surveillance encompasses portable, vehicle-mounted, and body-worn camera systems engineered for real-time video capture, transmission, and storage in non-fixed environments, typically operating across 4G LTE, 5G, Wi-Fi, and satellite communication bands with IP67 or higher ingress protection ratings. These systems serve law enforcement, emergency response, and critical infrastructure protection by enabling command centers to monitor field operations without tethered network infrastructure. Body-worn cameras occupy the largest revenue pool among product types due to mandated police department deployments across multiple jurisdictions. 5G-enabled systems represent the fastest-expanding technology segment as latency requirements tighten for real-time facial recognition and behavioral analytics. Vehicle-mounted systems anchor margin concentration given the complexity of shock-resistant housings, thermal management, and multi-sensor fusion.
The Federal Communications Commission governs spectrum allocation for wireless video transmission in the United States, while the European Union's Cyber Resilience Act imposes mandatory security standards on connected surveillance devices sold within member states. China's Ministry of Industry and Information Technology administers network access licenses and data localization requirements for mobile surveillance platforms operating on domestic infrastructure. Stakeholders must monitor evolving encryption mandates and cross-border data flow restrictions that will determine which hardware-software combinations qualify for government procurement tenders.
Market Dynamics
The transition from 4G LTE to 5G transmission protocols is compressing latency tolerances and forcing hardware refresh cycles across law enforcement procurement programs.
Growth Catalysts
- Police department mandates:Jurisdictions in the United States and Germany now require body-worn camera deployment during all public interactions. This creates baseline demand that hardware vendors can forecast with precision.
- Euro 7 emission standards:Vehicle-mounted surveillance platforms in the European Union must integrate with cleaner municipal fleets. This accelerates replacement of aging diesel-powered command vehicles with electric alternatives carrying lighter surveillance payloads.
- Edge AI chipsets:On-device facial recognition and behavioral analytics reduce backhaul bandwidth requirements. Chinese manufacturers have captured cost advantages by integrating these processors directly into camera modules.
Market Restraints
- CMOS sensor supply concentration:Sony and Samsung control premium image sensor fabrication. Any disruption to Japanese or South Korean semiconductor foundries propagates directly into camera production lead times.
- GDPR compliance friction:The European Union's data protection framework imposes strict retention limits on biometric footage. This constrains cloud storage architectures that vendors prefer for recurring revenue models.
- Satellite bandwidth economics:Remote deployments in rural Australia and northern Canada face prohibitive transmission costs. Terrestrial 5G buildouts remain incomplete in these geographies.
Strategic Opportunities
- India smart city expansion:The country's Ministry of Housing and Urban Affairs has tendered for 100 integrated command centers. Mobile surveillance units represent a specified component in these proposals.
- Convergence of thermal and visible spectrum:Multi-sensor fusion enables 24-hour perimeter monitoring without artificial illumination. Border security agencies in Saudi Arabia and the United Arab Emirates have specified these capabilities in recent tenders.
- Subscription-based evidence management:Cloud platforms that chain-custody footage from capture to courtroom are displacing on-premise storage. This shifts revenue from hardware margins to recurring software licenses.
Industry Challenges
- Embedded systems firmware expertise:Real-time operating systems for camera modules require specialized engineering talent. Vendors compete aggressively for developers with RTOS and video codec optimization experience.
- Interoperability certification delays:Integration with legacy police computer-aided dispatch systems requires bespoke middleware development. Each municipal procurement imposes unique API requirements that extend deployment timelines.
- Battery thermal management:Body-worn cameras must operate across temperature extremes while maintaining IP67 sealing. Engineering teams struggle to balance runtime, weight, and heat dissipation in compact form factors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile Video Surveillance Market |
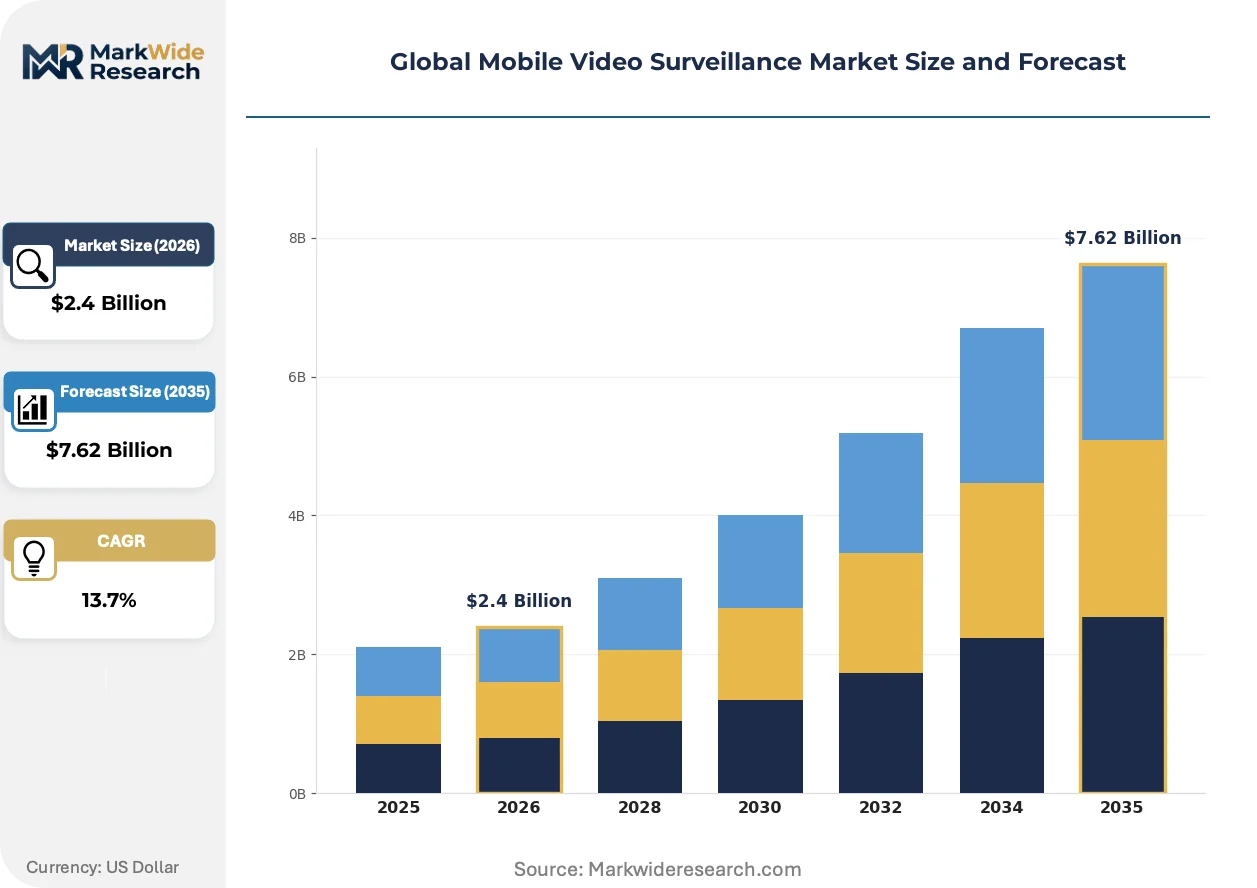
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $7.62 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Body-Worn Cameras, Vehicle-Mounted Systems, Drone Surveillance, Portable CCTV, Fixed Mobile Units Technology: 4G LTE, 5G, Wi-Fi, Satellite Communication, Radio Frequency Application: Public Safety, Law Enforcement, Border Security, Event Management, Critical Infrastructure Protection End User: Police Departments, Private Security Firms, Emergency Responders, Transportation Authorities |
| Companies Covered | Hangzhou Hikvision Digital Technology Co., Ltd., Dahua Technology Co., Ltd., Axis Communications AB, Robert Bosch GmbH, Motorola Solutions, Inc., Teledyne FLIR LLC, Hanwha Vision Co., Ltd., VIVOTEK Inc., CP Plus International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile Video Surveillance Market Shifts & Advancements
Software-defined architectures are decoupling hardware refresh cycles from feature roadmaps, allowing fielded cameras to gain capabilities through over-the-air updates rather than physical replacement.
Silicon carbide power electronics are displacing silicon-based voltage regulators in vehicle-mounted surveillance systems. Transit authorities in Germany and Japan specify these components for their superior thermal performance in engine-bay installations. The technology is displacing legacy power management modules that required active cooling, reducing overall system weight and maintenance intervals.
China's MIIT network access license requirements now mandate domestic encryption algorithms for all surveillance devices operating on public infrastructure. This fragments global product architectures, forcing multinationals to maintain separate firmware branches for Chinese deployments. Hardware vendors serving both European and Chinese markets face doubled certification costs and divergent supply chain configurations.
Evidence unbundling is accelerating as police departments separate camera hardware procurement from digital evidence management software. French and Italian municipalities now run competitive tenders for cloud storage platforms independent of device vendors. This disintermediation compresses hardware margins while elevating software specialists that can demonstrate courtroom-admissible audit trails.
Global Mobile Video Surveillance Market Segmentation
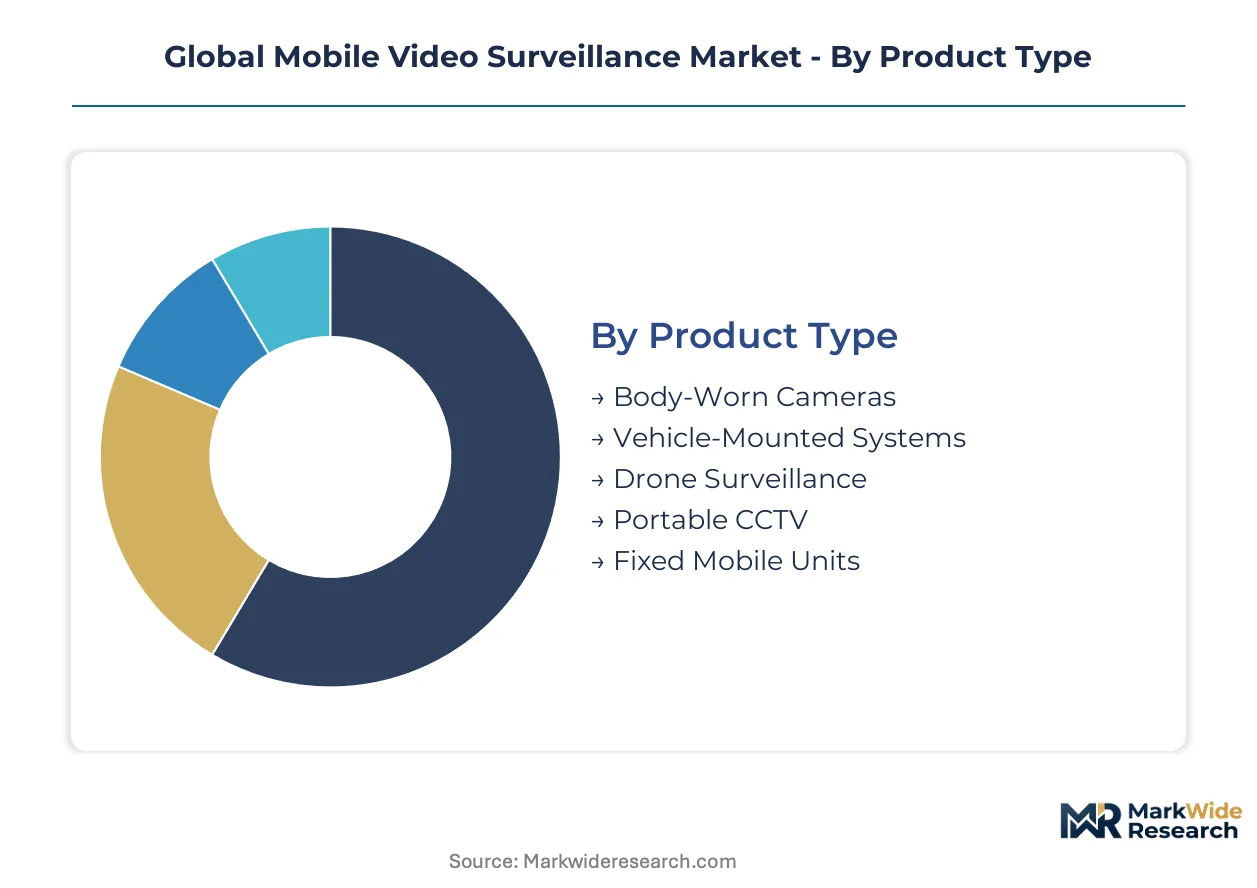
Segmentation in mobile video surveillance reveals divergent procurement rhythms across public safety hierarchies. Police departments, transportation authorities, and private security firms each impose distinct technical specifications that reshape vendor product roadmaps. Understanding these fault lines clarifies where hardware margins concentrate versus where software subscriptions displace capital expenditure.
Product Type:
Domestic procurement dominates body-worn and vehicle-mounted categories, while drone surveillance and portable CCTV flow through export channels to emerging markets with less fixed infrastructure.
- Body-Worn Cameras:Compact units with IP67 sealing and 12-hour battery endurance attach to officer uniforms for continuous recording. United States police departments mandate deployment during all public interactions, creating predictable replacement cycles tied to federal grant programs.
- Vehicle-Mounted Systems:Multi-sensor arrays integrate thermal imaging, visible spectrum cameras, and license plate recognition into shock-resistant housings. German transit authorities specify silicon carbide power electronics for engine-bay thermal tolerance, anchoring premium pricing tiers.
- Drone Surveillance:Aerial platforms with 30-minute flight endurance serve border patrol and event monitoring where ground access proves impractical.
- Portable CCTV:Rapid-deployment towers with telescopic masts protect temporary worksites and outdoor festivals across Australian mining corridors.
- Fixed Mobile Units:Trailer-mounted command centers with satellite uplinks serve rural Canada and northern Scandinavia where terrestrial coverage remains incomplete.
Body-Worn Cameras holds the largest share; momentum sits with Drone Surveillance as battery energy density improves.
Technology:
Cost tiers separate legacy 4G LTE deployments from premium 5G installations, with satellite communication commanding the highest per-bit transmission economics.
- 4G LTE:Mature transmission protocol with ubiquitous tower coverage supports standard-definition streaming at sub-$500 hardware price points. Indian smart city tenders specify 4G for cost-constrained municipal deployments.
- 5G:Millimeter-wave and sub-6 GHz bands enable sub-10 millisecond latency for real-time facial recognition. China's MIIT network access licenses mandate domestic encryption algorithms, fragmenting global firmware architectures.
- Wi-Fi:Local area connectivity serves campus security and warehouse environments where fixed infrastructure exists.
- Satellite Communication:Geostationary and low-earth orbit links bridge coverage gaps in Saudi Arabia's Empty Quarter and UAE desert perimeters.
- Radio Frequency:Proprietary bands persist in military and critical infrastructure applications requiring air-gapped networks.
4G LTE still anchors volume; 5G climbs the fastest as latency requirements tighten for behavioral analytics.
Application:
Application segmentation tracks jurisdictional authority rather than technology preference, with sovereign border agencies operating on classified procurement channels distinct from municipal police budgets.
- Public Safety:Crowd monitoring and emergency response coordination across urban centers. French municipalities now separate camera hardware tenders from cloud evidence management, compressing device margins.
- Law Enforcement:Body-worn and vehicle-mounted systems for evidentiary capture. United States departments face Civil Rights Division oversight on footage retention protocols.
- Border Security:Multi-sensor fusion for 24-hour perimeter monitoring without artificial illumination. Saudi Arabia and UAE agencies specify thermal-visible convergence in recent tenders.
- Event Management:Temporary surveillance for sports venues and political summits.
- Critical Infrastructure Protection:Power substations and telecommunications facilities in Germany and Japan.
Law Enforcement commands the largest installed base; Border Security gains share fastest on geopolitical perimeter investments.
End User:
Customer type determines procurement sophistication, with police departments running formal tender processes while private security firms negotiate direct vendor relationships.
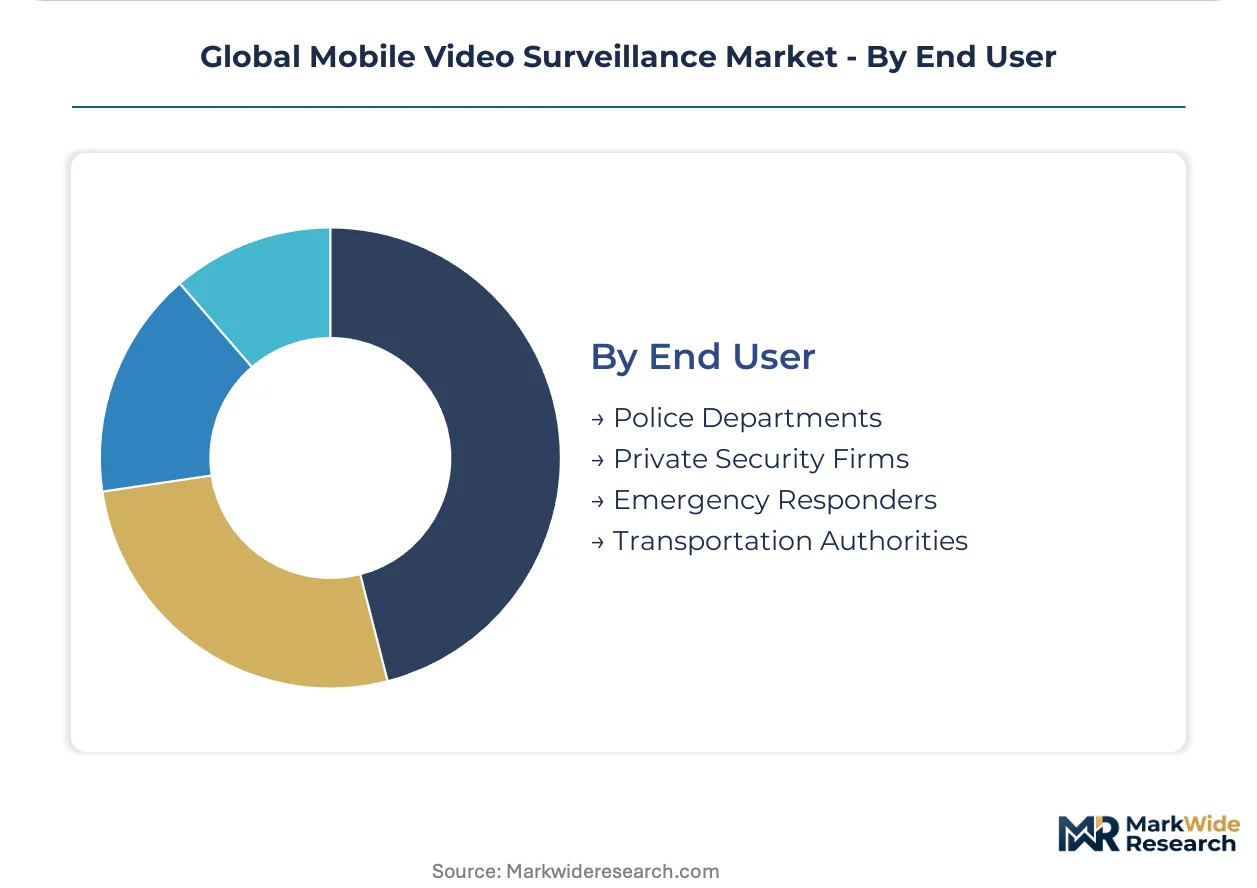
- Police Departments:Formal acquisition with chain-of-custody requirements and courtroom admissibility standards. Italian municipalities now run competitive tenders for cloud storage independent of device vendors.
- Private Security Firms:Commercial price sensitivity favors Chinese manufacturers with vertically integrated sensor production.
- Emergency Responders:Fire and medical services require ruggedized units with glove-compatible controls.
- Transportation Authorities:Rail and bus operators in Germany and Japan specify Euro 7-compliant electric vehicle integrations.
Police Departments retain the dominant share; Transportation Authorities expand most quickly on fleet electrification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer archetypes concentrate around law enforcement procurement offices, smart city authorities, and critical infrastructure operators across five sovereign markets. Each geography imposes distinct certification regimes and data sovereignty requirements that fragment vendor qualification pathways.
United States
Federal grant programs and Civil Rights Division oversight drive body-worn camera deployment across municipal police departments. The FCC governs spectrum allocation for wireless video transmission while imposing equipment authorization standards. Chicago and Los Angeles anchor procurement volume through consolidated metropolitan purchasing cooperatives.
Germany
Euro 7 emission standards accelerate replacement of diesel-powered command vehicles with electric alternatives carrying lighter surveillance payloads. The KBA certifies vehicle-mounted systems for public safety fleet integration. Bavarian and North Rhine-Westphalian transit authorities specify silicon carbide power electronics for engine-bay thermal tolerance.
China
Smart city investments and public safety modernization programs generate sustained demand for integrated command centers. MIIT administers network access licenses and mandates domestic encryption algorithms for devices operating on public infrastructure. Shenzhen and Hangzhou industrial clusters concentrate vertically integrated sensor manufacturing.
India
The Ministry of Housing and Urban Affairs has tendered for integrated command centers specifying mobile surveillance units as mandatory components. BIS certification requirements govern equipment standards for government procurement. Delhi-NCR and Mumbai metropolitan regions concentrate deployment pilots under the Smart Cities Mission.
Saudi Arabia
Geopolitical perimeter investments drive demand for multi-sensor fusion systems enabling 24-hour border monitoring without artificial illumination. The SFDA and communications authority regulate data localization for surveillance platforms. Riyadh and the Eastern Province anchor deployment along the Empty Quarter and UAE frontier corridors.
Global Mobile Video Surveillance Market Competitive Landscape
Player mix skews toward vertically integrated hardware manufacturers with captive sensor production and open-platform software specialists. The competitive structure bifurcates between price-sensitive volume players and premium-tier integrators. Three archetypes dominate: Chinese manufacturers with backward integration into CMOS supply chains, European open-architecture platform vendors, and North American system integrators with federal contracting relationships. Competitive moves concentrate on geographic certification expansion and evidence management software unbundling.
Within the vertically integrated tier, Hangzhou Hikvision Digital Technology Co., Ltd. and Dahua Technology Co., Ltd. occupy positions exemplifying cost-advantaged manufacturing at scale. Axis Communications AB represents the open-platform archetype, anchoring third-party software compatibility as a differentiation vector. These three entities collectively illustrate the geographic and architectural fault lines reshaping procurement qualification pathways.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Dahua Technology Co., Ltd. |
| Axis Communications AB |
| Robert Bosch GmbH |
| Motorola Solutions, Inc. |
| Teledyne FLIR LLC |
| Hanwha Vision Co., Ltd. |
| VIVOTEK Inc. |
| CP Plus International |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements with Japanese and South Korean sensor foundries lock in CMOS supply access while fixing cost baselines for body-worn camera manufacturers. These contracts insulate procurement officers from spot-market volatility in semiconductor substrates, though Chinese competitors with captive wafer production bypass this pricing architecture entirely.
Pricing Analysis
Cost-plus contracts indexed to silicon wafer spot prices dominate procurement between tier-one camera assemblers and sensor suppliers. Three-tier pricing structure across premium, standard, and economy levels separates Axis Communications' open-platform modules from Dahua's volume-positioned units and unbranded OEM alternatives. Price differentiation hinges on ISO 9001 certification status and FCC equipment authorization tier. Cost compression in the standard tier is intensifying because Indian smart city tenders prioritize unit economics over analytics capability. Private security firms exhibit the highest price sensitivity; German transit authorities the lowest due to Euro 7 fleet integration mandates.
Supply Chain Analysis
Inventory buffers at Sony and Samsung fabrication facilities currently extend to twenty-six weeks for premium CMOS sensors, constraining rapid scaling by non-integrated assemblers. Manufacturing concentrates in China, Japan, and South Korea, with Shenzhen and Hangzhou industrial clusters anchoring final assembly. Raw material dependencies include silicon wafers, rare-earth phosphors for night-vision modules, and lithium-polymer cells for body-worn power systems. Single-source vulnerability in Japanese image sensor foundries represents the dominant structural risk. Distribution runs through government procurement cooperatives in the United States and systems integrators in the European Union.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from software-defined evidence platforms that disintermediate hardware margins through cloud-based chain-of-custody services. Defense requires locking sensor supply and accelerating firmware unbundling.
For Market Incumbents: Secure long-term offtake agreements with Sony or Samsung foundries before capacity allocation tightens further. Accelerate in-house production of edge AI chipsets to match Chinese cost structures in behavioral analytics modules. The threat of evidence management software unbundling demands preemptive cloud platform investment to retain customer relationships beyond hardware refresh cycles. For New Entrants and Emerging Players: Evidence unbundling in French and Italian municipalities creates service-layer gaps where incumbents under-serve courtroom-admissible audit trail requirements. Target cloud storage platforms with independent certification from hardware vendors as the most penetrable segment. A go-to-market angle through GDPR-compliant data residency guarantees differentiates against Chinese competitors facing MIIT encryption fragmentation. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists with captive CMOS sensor production and established MIIT network access licenses for Chinese market entry. Long-term viability over the coming decade rests on controlling upstream image sensor supply rather than downstream software subscriptions. Watch for MIIT encryption mandate expansions beyond China's borders as the inflection signal for global firmware architecture consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Chipset Integration | On-device facial recognition reduces backhaul costs for 5G-enabled body-worn systems. |
| Silicon Carbide Power Electronics Adoption | German KBA-certified vehicle systems achieve engine-bay thermal tolerance without active cooling. |
| Cloud Evidence Platform Development | Subscription revenue displaces hardware margins in French municipal procurement patterns. |
| MIIT Network Access License Acquisition | Domestic encryption compliance unlocks Chinese smart city command center tenders. |
| Multi-Sensor Fusion R&D | Thermal-visible convergence meets Saudi SFDA specifications for 24-hour border monitoring. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with law enforcement procurement officers, systems integration specialists, and semiconductor supply chain managers; and secondary validation against FCC equipment authorization databases, MIIT network access license registries, and European smart city tender documentation. Bottom-up unit economics modeling triangulated against top-down market sizing across product type, transmission technology, and end-user segments.
Across the projection horizon, the analytical framework modeled volume and value outputs through segmentation by device form factor, network protocol generation, application jurisdiction, and geographic certification cluster. CAGRs derived from weighted average of historical procurement cycle analysis and forward-looking replacement rate assumptions. Forecast inputs included 5G infrastructure deployment timelines and sovereign data localization mandate propagation patterns.
Forecasts assume regulatory continuity in FCC spectrum allocation, GDPR retention limits, and MIIT encryption requirements; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Global Trade Surveillance Systems Market
Video Surveillance Systems
Asia Pacific Surveillance IP Camera Market
Video Surveillance Systems
North America Pedestrian Detection Systems Market
Video Surveillance Systems
Latin America Surveillance IP Cameras Market
Video Surveillance Systems
People Counting System Market
Video Surveillance Systems
US Video Surveillance Market
Video Surveillance Systems
City Surveillance Market
Video Surveillance Systems
Wearable and Body-Worn Cameras Market
Video Surveillance Systems
Middle East and Africa Video Surveillance Market
Video Surveillance Systems
Europe Video Surveillance Storage Market
Video Surveillance Systems
Europe Surveillance Camera Market
Video Surveillance Systems
India Surveillance IP Cameras Market
Video Surveillance Systems
Night Vision Outdoor Camera Market
Video Surveillance Systems
North America Crawler Camera System Market
Video Surveillance Systems
Night Vision System (NVS) Market
Video Surveillance Systems
Japan Surveillance IP Cameras Market