
 Global Medical Alert System/Personal Emergency Response System Market | 2026-2036
Global Medical Alert System/Personal Emergency Response System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Alert System/Personal Emergency Response System Market Intelligence
The European Union's Medical Device Regulation (MDR) compliance cycle is unwinding the competitive landscape by raising the barrier for new entrants. Philips Lifeline (Connect America) leverages its established brand and healthcare partnerships to navigate these stringent requirements. ADT Health sustains its market position through a strong focus on home security integration and national brand recognition in the United States. Meanwhile, Medical Guardian differentiates through a direct-to-consumer model emphasizing customizable device options and service plans.
A medical alert system, or personal emergency response system (PERS), is an electronic device designed to summon aid during an emergency. These systems feature a wearable transmitter that communicates wirelessly with a base unit or mobile device, connecting to a monitoring center via cellular or landline networks. Wearable devices with automatic fall detection represent the fastest-growing product category, outperforming static home-based systems. Cellular-based technology is now the standard for new systems, providing superior mobility and resilience over landline connections.
Regulatory oversight from bodies like the U.S. Food and Drug Administration (FDA) and compliance with Europe's Medical Device Regulation (MDR) govern device classification and marketing. In Japan, the Pharmaceutical and Medical Devices Agency (PMDA) sets standards for product safety and effectiveness, influencing market access for foreign and domestic manufacturers. Future competitive advantage will hinge on a provider's ability to integrate predictive analytics for proactive health monitoring rather than just reactive emergency response.
Market Dynamics
The transition from reactive emergency alerts to proactive health monitoring is the central force shaping the market. This shift is driven by sensor technology advancements and healthcare system demands for preventative care models that can monitor chronic conditions and predict adverse events before they occur.
Growth Catalysts
- Technology Integration:Automatic fall detection algorithms and GPS tracking enhance user safety, providing critical data to responders and boosting mobile system adoption.
- Demographic Shifts:A growing senior population in developed nations like Japan and Germany creates a sustained user base prioritizing independent living.
- Healthcare Incentives:Reimbursement policies for remote patient monitoring encourage providers to recommend PERS to reduce hospital readmissions.
Market Restraints
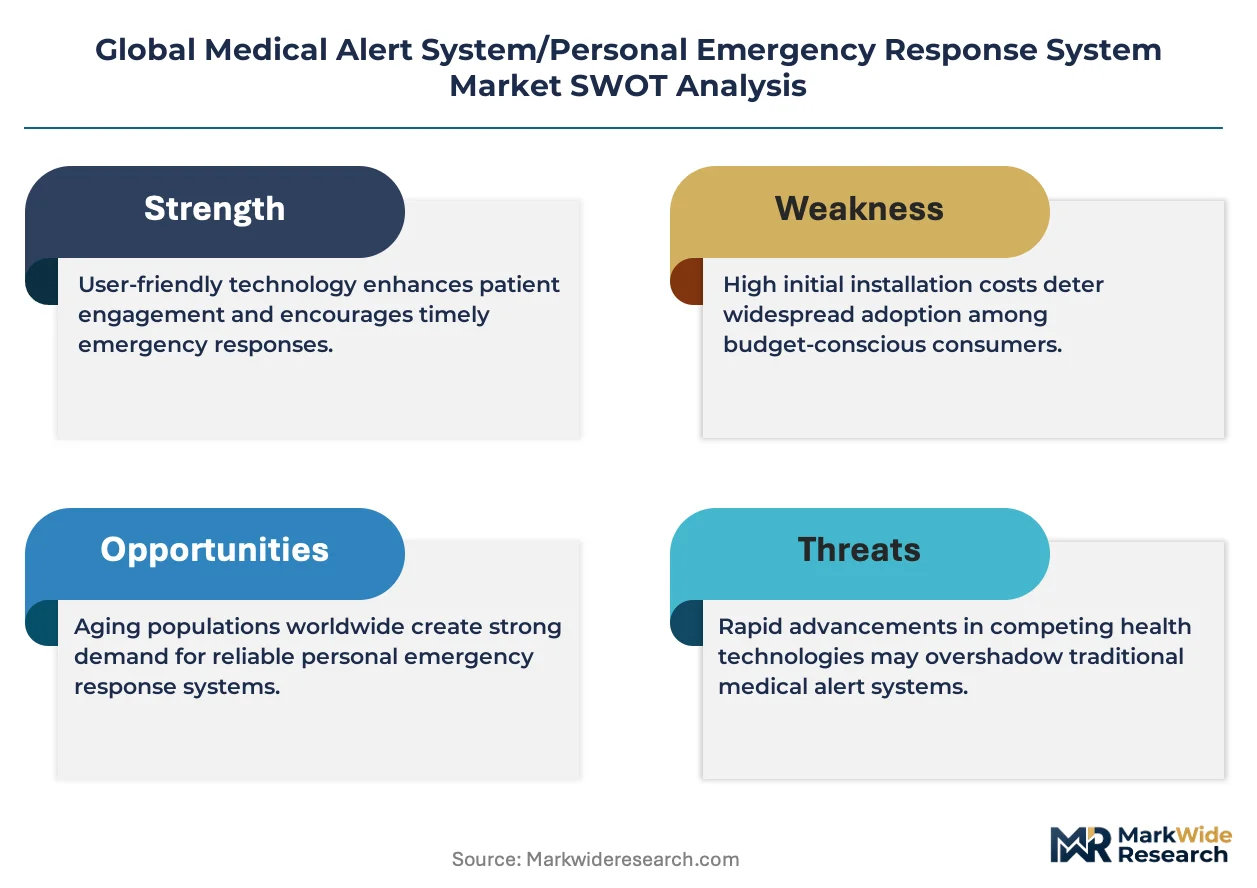
- Cost Barriers:High upfront device costs and ongoing monthly subscription fees present a significant hurdle for seniors living on fixed incomes.
- Algorithm Inaccuracy:False positives from automatic fall detection systems can lead to user frustration and a lack of trust, resulting in non-adherence.
- Regulatory Burden:The European Union's stringent Medical Device Regulation (MDR) increases compliance costs and lengthens time-to-market for new manufacturers.
Strategic Opportunities
- Telehealth Integration:Embedding PERS into telehealth platforms enables continuous health monitoring and virtual consultations, creating new service revenue streams.
- Underserved Geographies:Market expansion into Latin America and Eastern Europe, which have rising disposable incomes, offers significant first-mover advantages.
- Specialized Applications:Developing systems for conditions like epilepsy or dementia opens niche markets beyond general senior care.
Industry Challenges
- Data Security:Protecting sensitive personal health information from cyberattacks while ensuring HIPAA compliance is a constant operational challenge.
- System Interoperability:Ensuring seamless data exchange between PERS devices and the fragmented landscape of electronic health record (EHR) systems is a technical hurdle.
- User Adherence:Overcoming technophobia and design stigma among elderly users to ensure consistent device usage is critical for effectiveness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Alert System/Personal Emergency Response System Market |
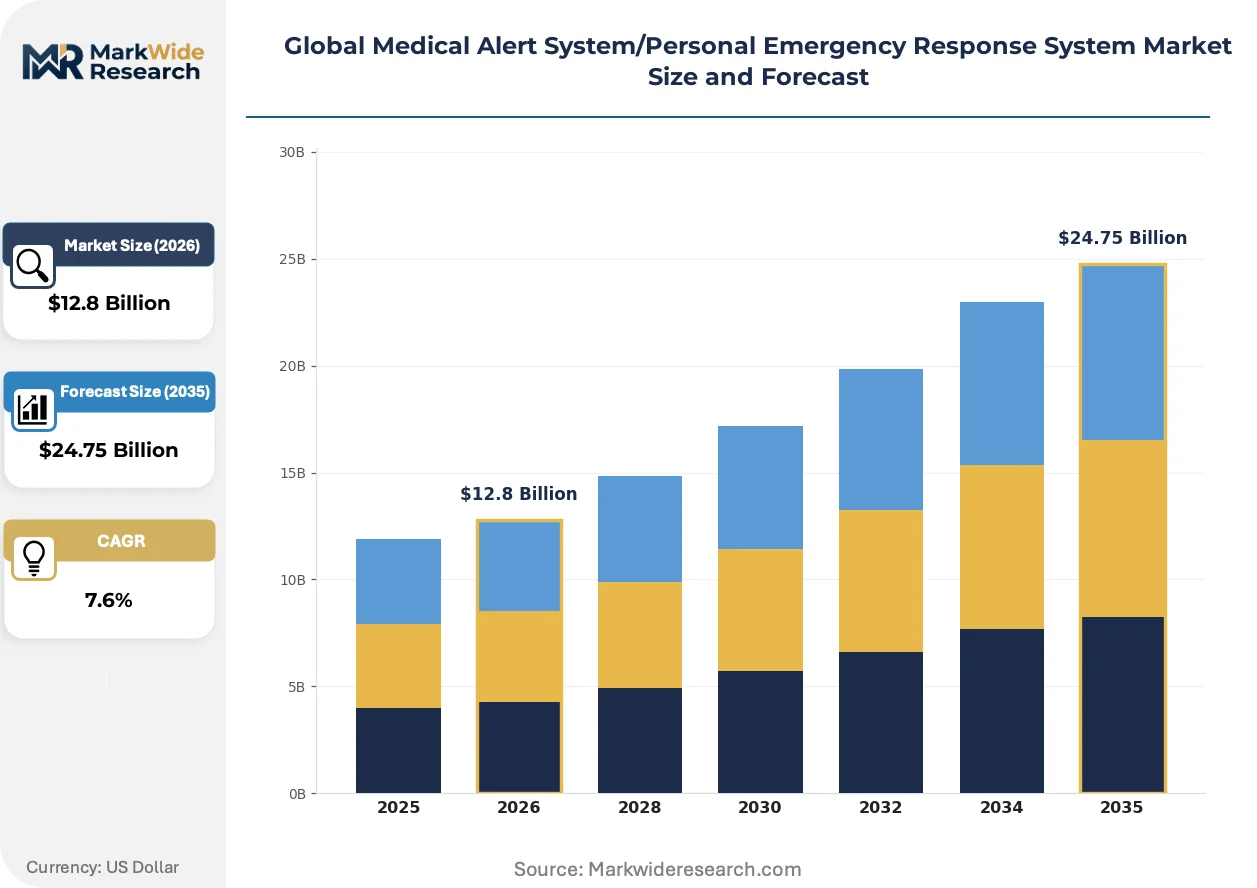
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $24.75 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Systems, Wearable Devices, Smartphone Apps, Home-Based Systems Technology: Cellular, Landline, Wi-Fi, Bluetooth End User: Seniors, Patients with Disabilities, Caregivers, Medical Facilities Service Type: Monitoring Services, Emergency Response Services, Maintenance Services, Installation Services |
| Companies Covered | ADT Health, LifeStation, Medical Guardian, Medical Alert, Lively (Best Buy), Bay Alarm Medical, MobileHelp, LogicMark, Philips Lifeline (Connect America), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Alert System/Personal Emergency Response System Market Strategic Shifts & Innovations
The convergence of consumer electronics aesthetics with medical-grade reliability is reshaping device design. User expectations, influenced by smartphones and wearables, now demand discreet, stylish, and user-friendly systems over traditionally clinical-looking devices. This is forcing a fundamental shift in product development priorities across the industry.
System-on-a-chip (SoC) designs integrate cellular modems, GPS, and processors into a single component. Style-conscious seniors are rapidly adopting these in wearable pendants and watches. This integration is miniaturizing the core electronics, enabling more discreet and comfortable form factors that improve user adherence.
The U.S. Federal Communications Commission's (FCC) managed phase-out of 3G cellular networks is a significant market force. This mandate compels PERS providers to migrate entire device portfolios to 4G LTE or 5G-ready hardware. The landline and legacy cellular system segments are most affected, accelerating their obsolescence.
A direct-to-consumer (DTC) sales model is gaining prominence over traditional B2B channels that rely on healthcare provider referrals. This shift disintermediates home health agencies, placing purchasing decisions directly with users and their families through online marketing. The DTC approach is most visible in the United States market.
Global Medical Alert System/Personal Emergency Response System Market Segmentation
The Global Medical Alert System/Personal Emergency Response System market demonstrates diverse segmentation across product types, underlying technologies, end-user demographics, and service offerings. Understanding these segments is crucial for providers to tailor solutions, address specific user needs, and navigate evolving regulatory landscapes with precision.
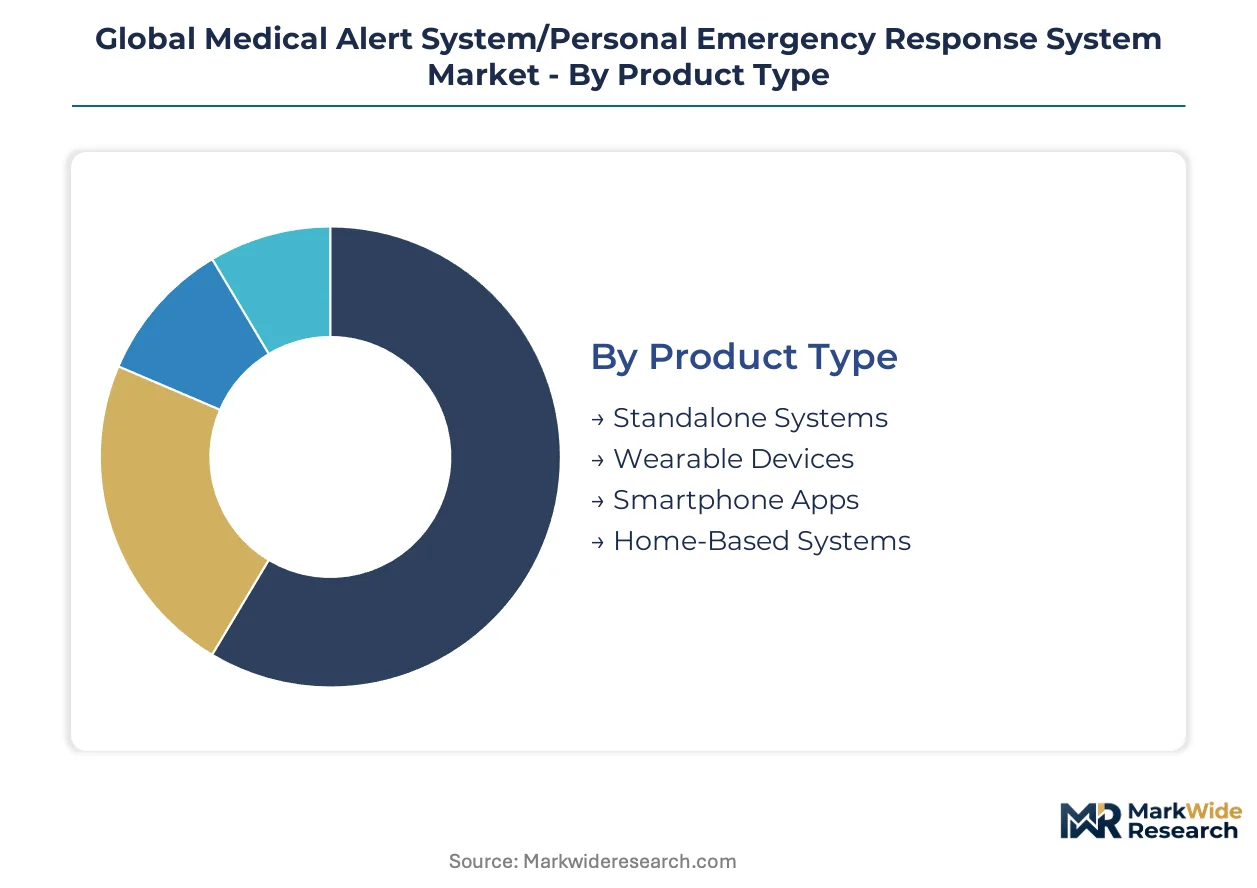
Product Type:
The product type segment experiences significant substitution pressure, particularly as advanced wearable devices displace traditional home-based and standalone systems with enhanced mobility and functionality.
- Wearable Devices:These compact, discreet units include pendants, watches, or clips, often integrating GPS and fall detection sensors. Demand from seniors seeking independent living drives their adoption, particularly in the United States and Japan, due to their mobility and real-time emergency response capabilities.
- Home-Based Systems:Comprising a base unit connected to a landline or cellular network and a wearable button, these systems provide localized emergency assistance. Their established presence and lower initial cost appeal to users preferring stationary monitoring within their residences, especially in rural areas.
- Standalone Systems:These portable devices operate independently, typically with integrated cellular connectivity for on-the-go emergency calls.
- Smartphone Apps:Leveraging existing smartphone capabilities, these applications offer emergency alerts and monitoring features, appealing to tech-savvy users.
Home-Based Systems retain volume leadership; Wearable Devices hold the steepest expansion curve.
Technology:
Technology segmentation reflects varying operational costs and infrastructure requirements, influencing the pricing and accessibility of medical alert solutions across different user demographics.
- Cellular:Utilizing 4G LTE or 5G networks, this technology provides ubiquitous connectivity for mobile PERS devices, eliminating the need for a landline. Its superior mobility and resilience against landline outages make it the standard for new system deployments, especially in urban centers.
- Landline:These systems connect to a traditional telephone line for communication with monitoring centers, representing an older, established technology. Their lower data transmission costs historically made them accessible, particularly for fixed-location home systems in regions with robust landline infrastructure.
- Wi-Fi:Integrating with home wireless networks, Wi-Fi connectivity supports localized data transmission and device updates within a residence.
- Bluetooth:This short-range wireless technology enables communication between wearable devices and a base unit or smartphone, enhancing local connectivity.
Cellular technology dominates market share; Wi-Fi is rapidly gaining traction for integrated home health solutions.
End User:
The end-user segmentation highlights the diverse applications of medical alert systems, from supporting independent living for the elderly to providing specialized care for individuals with chronic conditions.
- Seniors:This demographic represents the largest user base, seeking to maintain independent living while ensuring immediate access to emergency assistance. Demand is particularly strong in developed nations like Germany and Japan, where aging populations prioritize safety and autonomy.
- Medical Facilities:Hospitals, nursing homes, and assisted living centers deploy these systems to enhance patient safety and staff response times within controlled environments. Their integration with existing healthcare infrastructure supports efficient patient monitoring and emergency protocols.
- Patients with Disabilities:Individuals with physical or cognitive impairments utilize these systems for enhanced safety and to summon aid during critical events.
- Caregivers:Family members or professional caregivers use these systems to monitor loved ones remotely and receive alerts in case of emergencies.
Seniors drive the largest user base; Medical Facilities present significant growth potential for integrated solutions.
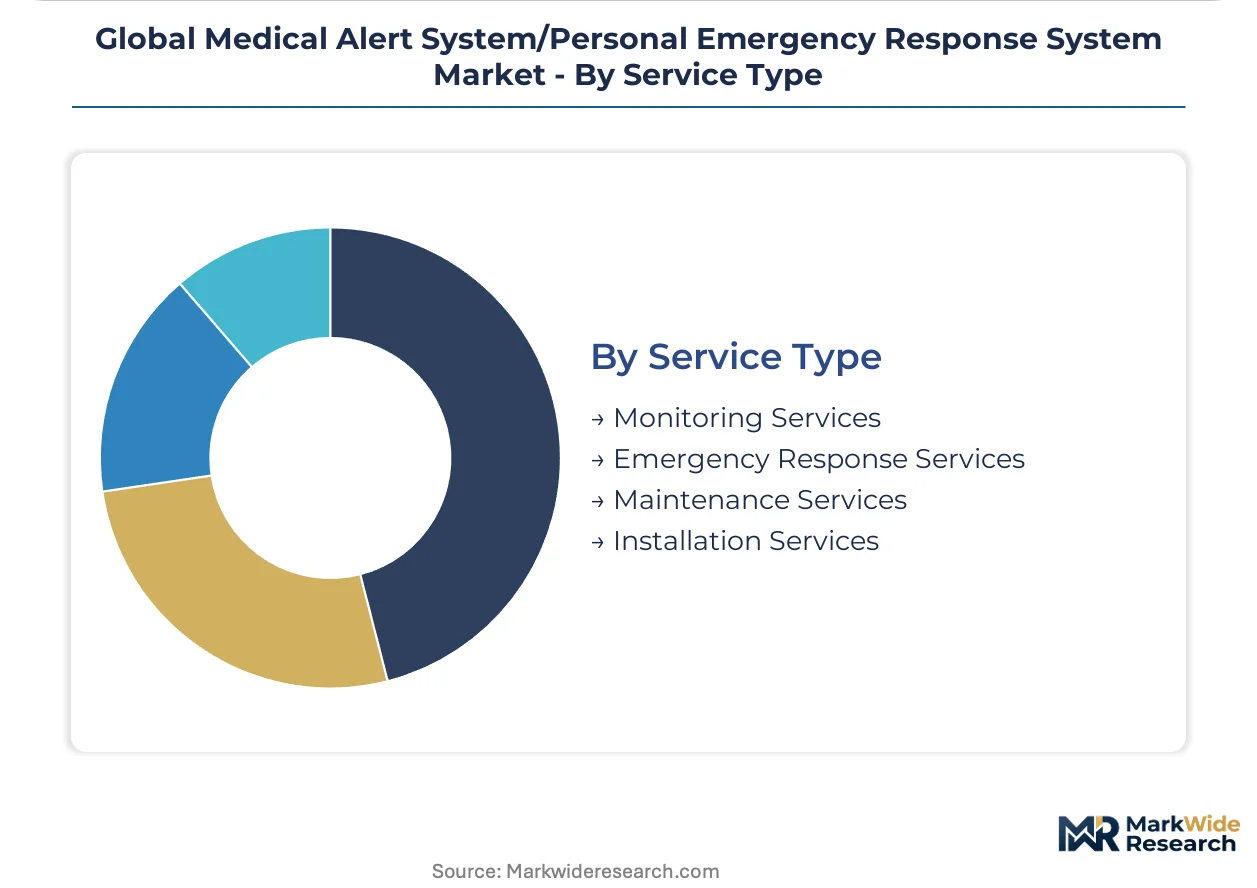
Service Type:
Service type segmentation reflects the various components of the medical alert system value chain, from core emergency response to ongoing maintenance and support.
- Monitoring Services:This core offering involves 24/7 professional oversight by a call center, dispatching emergency services upon alert activation. Recurring subscription fees for these services form a significant revenue stream, essential for sustained market operations.
- Emergency Response Services:Directly linked to monitoring, these services involve the actual dispatch of paramedics, police, or designated contacts when an alert is triggered. Rapid response capabilities are a primary differentiator for providers, particularly in critical situations.
- Maintenance Services:These services ensure the continued functionality and reliability of devices through regular checks, battery replacements, and software updates.
- Installation Services:Providers offer professional setup of home-based systems, ensuring correct configuration and user training for optimal performance.
Monitoring Services form the foundation of recurring revenue; Emergency Response Services are increasingly critical for user safety and satisfaction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement policies for remote patient monitoring significantly influence regional market development, encouraging providers to recommend medical alert systems. These policies aim to reduce hospital readmissions and support preventative care models, particularly benefiting aging populations. Technology advancements in fall detection and GPS tracking further drive adoption across key global markets.
United States
Demand for advanced medical alert systems stems from a large senior population prioritizing independent living and robust healthcare infrastructure. The U.S. Food and Drug Administration (FDA) regulates these devices, ensuring product safety and effectiveness for consumers. Major technology and healthcare clusters in California and Massachusetts drive innovation in wearable device design and telehealth integration.
Japan
Japan's rapidly aging demographic creates substantial demand for personal emergency response systems, supporting seniors' autonomy at home. The Pharmaceutical and Medical Devices Agency (PMDA) sets stringent standards for device approval, influencing market access for both domestic and foreign manufacturers. Tokyo and Osaka serve as key centers for medical technology development and market penetration.
Germany
An established healthcare system and a growing elderly population fuel the adoption of medical alert systems, particularly those with proactive health monitoring features. Compliance with Europe's Medical Device Regulation (MDR) is mandatory for market entry, impacting development costs and timelines. Munich and Berlin are significant hubs for medical technology research and digital health solution providers.
United Kingdom
The National Health Service (NHS) and various social care initiatives promote the use of assistive technologies, including medical alert systems, to support independent living. The UK's Medicines and Healthcare products Regulatory Agency (MHRA) oversees device safety and performance, aligning with European standards. London and Manchester demonstrate strong activity in health tech startups and service innovation.
Canada
Government initiatives supporting senior care and home-based health services stimulate the market for personal emergency response systems across the country. Health Canada regulates medical devices, ensuring they meet safety and efficacy requirements before market introduction. Toronto and Vancouver are emerging as centers for digital health innovation and connected care solutions.
Global Medical Alert System/Personal Emergency Response System Market Key Industry Players
Listed leaders compete with private specialists across service delivery models and technological innovation, defining market structure. The landscape exhibits a tiered structure, with established players alongside niche providers focusing on specific user needs. Strategic archetypes include integrated security providers, direct-to-consumer specialists, and traditional medical device manufacturers. Dominant competitive moves involve strategic partnerships with healthcare providers and continuous portfolio diversification into advanced wearable technologies.
On the premium-tier vector, Philips Lifeline (Connect America) leverages its established brand and healthcare partnerships to navigate stringent regulatory requirements, particularly in Europe. ADT Health occupies a position through its strong focus on home security integration and national brand recognition in the United States. Medical Guardian exemplifies a direct-to-consumer model, emphasizing customizable device options and service plans for a broader user base.
| Leading Market Players |
|---|
| ADT Health |
| LifeStation |
| Medical Guardian |
| Medical Alert |
| Lively (Best Buy) |
| Bay Alarm Medical |
| MobileHelp |
| LogicMark |
| Philips Lifeline (Connect America) |
| Others |
Cost & Logistics Intelligence
Cellular technology's displacement of landline connections reshapes the medical alert system supply chain by altering component demand and influencing pricing for new, mobile-centric devices. This transition drives innovation in miniaturized electronics.
Pricing Analysis
Certification level (FDA/MDR-grade) creates the primary spread in medical alert system pricing. The dominant pricing model is subscription-tiered, driven by recurring monitoring services. Price differentiation stems from brand recognition and the level of integrated features like fall detection. Pricing softness reflects cost barriers for seniors on fixed incomes, making this demographic the most price-sensitive, while medical facilities prioritize feature sets over lowest cost.
Supply Chain Analysis
China and Taiwan anchor the supply of integrated System-on-a-chip (SoC) designs and cellular modems essential for modern medical alert systems. The supply chain draws from critical components like GPS modules and advanced sensors. Single-source vulnerability for specialized electronics components represents a structural risk. Distribution runs through a dual model, with direct-to-consumer sales gaining prominence alongside established B2B channels targeting healthcare providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical alert system market presents a significant service-attach opportunity, with monitoring services and telehealth integration expanding faster than hardware sales. This shift emphasizes recurring revenue streams over one-time device purchases.
For Market Incumbents: Compound existing healthcare partnerships and brand recognition to navigate stringent regulatory requirements like Europe's MDR. Migrating entire device portfolios to 4G LTE or 5G-ready hardware addresses the FCC's 3G phase-out threat. Investing in predictive analytics for proactive health monitoring differentiates against reactive emergency response systems. Control over distribution channels ensures sustained market presence.
For New Entrants and Emerging Players: Differentiate on customizable device options and service plans targeting specific niche markets like epilepsy or dementia care. Market expansion into underserved geographies such as Latin America and Eastern Europe offers significant first-mover advantages. A direct-to-consumer sales model emphasizing user-friendly design provides a penetrable segment for tech-savvy seniors. Leverage telehealth integration for continuous health monitoring.
For Investors and Strategic Acquirers: The market sits at a sustained growth phase that favors technology-integrated specialists capable of transitioning to proactive health monitoring. Long-term viability hinges on providers' ability to combine medical-grade reliability with consumer electronics aesthetics. Target acquisition profiles include firms with strong intellectual property in predictive analytics or established direct-to-consumer channels. Widespread reimbursement policies for remote patient monitoring serve as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| 4G/5G Migration | Ensures regulatory compliance and enhances device mobility for users. |
| Predictive Analytics Integration | Enables proactive health monitoring, moving beyond reactive emergency response. |
| Telehealth Platform Partnership | Creates new service revenue streams and supports continuous virtual consultations. |
| Direct-to-Consumer Channel Expansion | Increases market reach by placing purchasing decisions directly with users. |
| Specialized Application Development | Opens niche markets for conditions like epilepsy or dementia beyond general senior care. |
Research Approach
Initial hypotheses were tested against primary input from medical device engineers, healthcare administrators, PERS providers, and geriatric care specialists, then refined through iterative analysis. This approach combined in-depth interviews with secondary validation from sources like FDA filings, PMDA standards, and industry reports. Bottom-up data aggregation and top-down market sizing ensured robust triangulation of findings.
Variance decomposition across product types, underlying technologies, end-user demographics, and service offerings informed the analytical framework over the projection horizon. This model estimated market growth, with CAGRs derived from historical trends and projected demographic shifts. Aging population demographics and evolving healthcare reimbursement policies for remote patient monitoring served as key forecast inputs.
Material uncertainties — unforeseen regulatory shifts, rapid technological obsolescence, or significant economic downturns — sit outside the modeled envelope. Forecasts reflect assumptions documented at the time of analysis. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Safety
Road Safety Market
Personal Safety
Bulletproof Vest Market
Personal Safety
Asia-Pacific People Screening Market
Personal Safety
Fall Detection System Market
Personal Safety
Smart Personal Safety and Security Device Market
Personal Safety
Life Jacket Market
Personal Safety
Pedestrian Protection Airbag Market
Personal Safety
Rearward Facing Type Child Safety Seats Market
Personal Safety
Global Personal Emergency Response Systems (PERS) Market
Personal Safety
Pepper Sprays Market
Personal Safety
Smart Home Safety Market
Personal Safety
Body Armor and Personal Protection Market
Personal Safety
Personal Safety Apps for Women Market
Personal Safety
Personal Safety Alarms Market
Personal Safety
Global Self Defense Products Market
Personal Safety
Concealable Vest Market