
 LAMEA Wireless Broadband in Public Safety Market | 2026-2036
LAMEA Wireless Broadband in Public Safety Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Wireless Broadband in Public Safety Market Insights
Project finance structures with long-term leasing arrangements for network infrastructure are reshaping competitive entry in LAMEA public safety broadband. Motorola Solutions Inc. leverages its installed base of mission-critical radio systems to extend into LTE deployments. Ericsson anchors large-scale network buildouts through equipment supply partnerships with regional carriers. Huawei Technologies Co. Ltd. competes aggressively on total cost of ownership for 5G base stations across Latin American markets.
Wireless broadband in public safety denotes high-reliability cellular and satellite data networks engineered for sub-50 millisecond latency, 99.999% availability, and AES-256 encryption to support real-time video, biometric transmission, and command coordination during emergencies. LTE technology dominates current procurement budgets due to proven interoperability with existing Land Mobile Radio systems, while 5G segments attract the fastest upgrade interest from agencies seeking network slicing for priority traffic. Application demand concentrates in emergency response and disaster management where video streaming and geolocation data require guaranteed bandwidth, with crime prevention analytics emerging as a secondary growth vector.
Brazil's ANATEL, Mexico's IFT, and South Africa's ICASA shape equipment certification and spectrum access rules that determine vendor eligibility across the region. CE marking requirements under EU-negotiated trade agreements influence procurement specifications for several LAMEA government buyers. Stakeholders must monitor spectrum harmonization negotiations between national regulators and 3GPP standard evolution to align capital cycles with interoperability mandates.
Market Dynamics
Spectrum harmonization pressure between Brazil's ANATEL and Mexico's IFT is compressing vendor certification timelines while accelerating multi-country procurement frameworks across Latin American public safety agencies.
Growth Catalysts
- ANATEL Public Safety Band Allocation:Brazil's 700 MHz spectrum reservation for first responders eliminates interference conflicts and enables dedicated network slices for emergency traffic prioritization.
- Real-Time Video Analytics:Police departments in Mexico City and São Paulo deploy edge-computing cameras requiring guaranteed bandwidth, pulling fiber-backhauled LTE upgrades into station procurement cycles.
- Land Mobile Radio Interoperability Mandates:Legacy P25 and TETRA system replacement schedules in South Africa and Chile synchronize with broadband infrastructure refresh windows, bundling vendor selection decisions.
Market Restraints
- Import Tariff Volatility:Brazilian customs duties on Chinese-manufactured 5G base stations fluctuate with trade policy shifts, destabilizing total cost of ownership calculations for municipal budgets.
- Single-Source Critical Components:AES-256 encryption chip fabrication concentrates in Taiwanese foundries, exposing LAMEA network operators to semiconductor supply disruption.
- Power Infrastructure Gaps:Unreliable grid electricity in rural Colombian and Peruvian deployment zones necessitates diesel generator backup, adding operational complexity and emissions compliance burdens.
Strategic Opportunities
- Argentina Underpenetration:Federal police modernization programs in Buenos Aires and Córdoba remain early-stage, offering first-mover positioning for integrated LTE-LMR hybrid systems ahead of 2027 budget cycles.
- Satellite-Cellular Convergence:Low-earth orbit backhaul integration with terrestrial LTE cores addresses coverage gaps in Amazon basin and Andean terrain where fiber deployment is economically prohibitive.
- Mexico IFT Rapid Deployment Framework:Streamlined equipment authorization for public safety bands reduces certification timelines from 18 months to 6 months, accelerating competitive entry for new infrastructure vendors.
Industry Challenges
- Mission-Critical Network Engineering Talent:Sub-50 millisecond latency design and 99.999% availability architecture require specialized RF engineers scarce in regional labor markets.
- Legacy LMR Integration Complexity:Hybrid operation between existing TETRA voice systems and new LTE data cores demands proprietary gateway development, extending deployment timelines and testing cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Wireless Broadband in Public Safety Market |
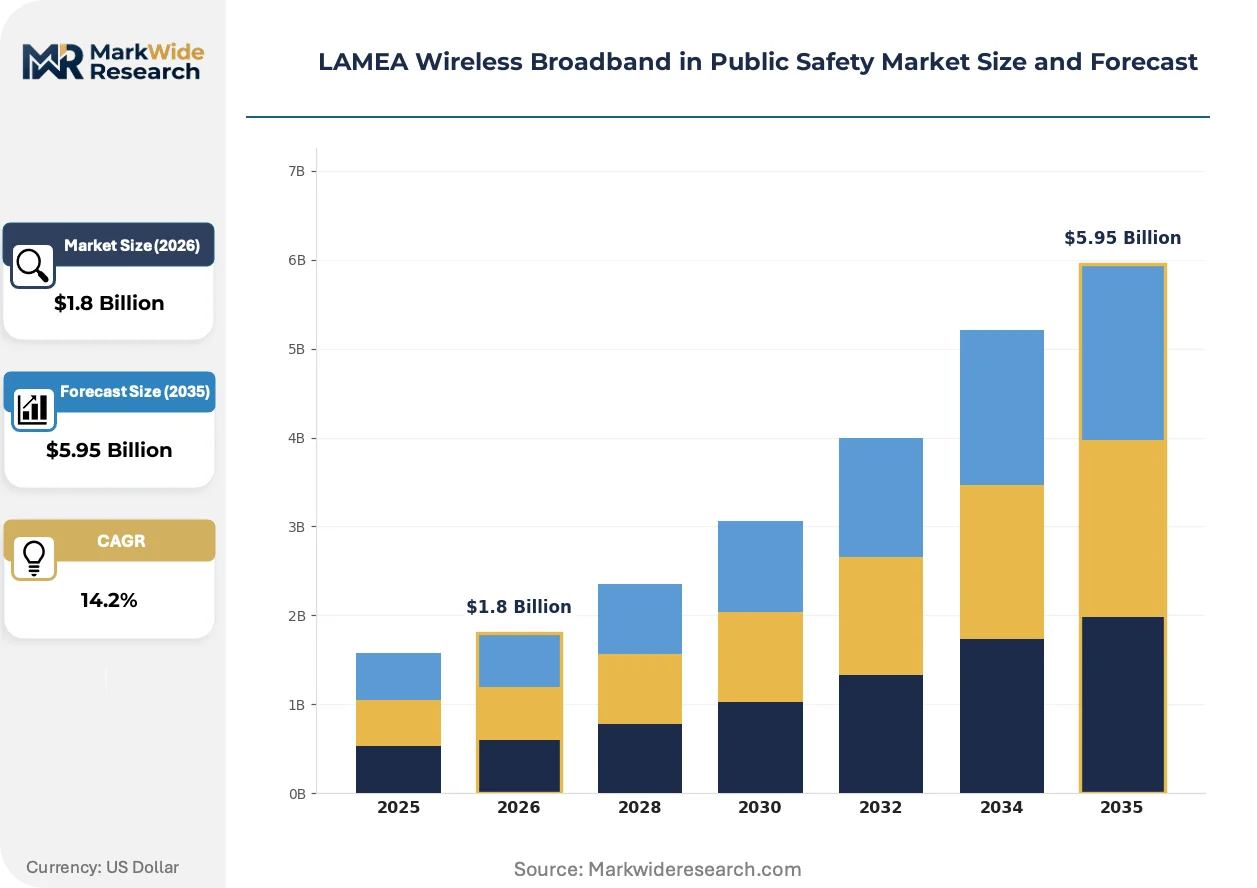
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LTE, 5G, Satellite, Fixed Wireless Application: Emergency Response, Disaster Management, Crime Prevention, Traffic Management End User: Police Departments, Fire Departments, Ambulance Services, Government Agencies Deployment: Private Network, Public Network, Hybrid Network, Cloud-Based Solutions |
| Companies Covered | Motorola Solutions Inc., Ericsson, Nokia Corporation, Huawei Technologies Co. Ltd., AT&T Inc., Cisco Systems Inc., Verizon Communications, ZTE Corporation, Airbus Group Inc., Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Wireless Broadband in Public Safety Market Trends and Innovations
Network function virtualization is collapsing hardware dependency in public safety infrastructure, while regulatory pressure on encryption standards and shifting procurement accountability reshape vendor relationships across the region.
Software-defined radio cores are virtualizing baseband processing functions that previously required dedicated hardware appliances. Colombian and Chilean state police agencies pilot these architectures in mobile command vehicles, collapsing deployment footprints from rack-mounted systems to single-server configurations. This compression is virtualizing the traditional equipment supply chain, enabling over-the-air feature updates that displace truck-roll maintenance models.
Brazil's ANATEL encryption certification requirements now mandate post-quantum cryptographic readiness for networks handling biometric data transmission. Equipment vendors must pre-integrate lattice-based algorithms into LTE and 5G cores, extending development cycles by 8-12 months. Federal emergency response agencies in São Paulo and Rio de Janeiro delay procurement decisions until certification compliance is demonstrated, freezing competitive selection processes.
Municipal governments increasingly bundle 10-year network operations contracts with initial infrastructure deployment, transferring availability risk to private operators. This accountability shift concentrates vendor selection around demonstrated mean-time-between-failure metrics rather than equipment specifications alone. Brazilian state-level public safety departments lead this transition, with Minas Gerais and Bahia structuring performance-based payments tied to guaranteed uptime thresholds.
LAMEA Wireless Broadband in Public Safety Market Segmentation
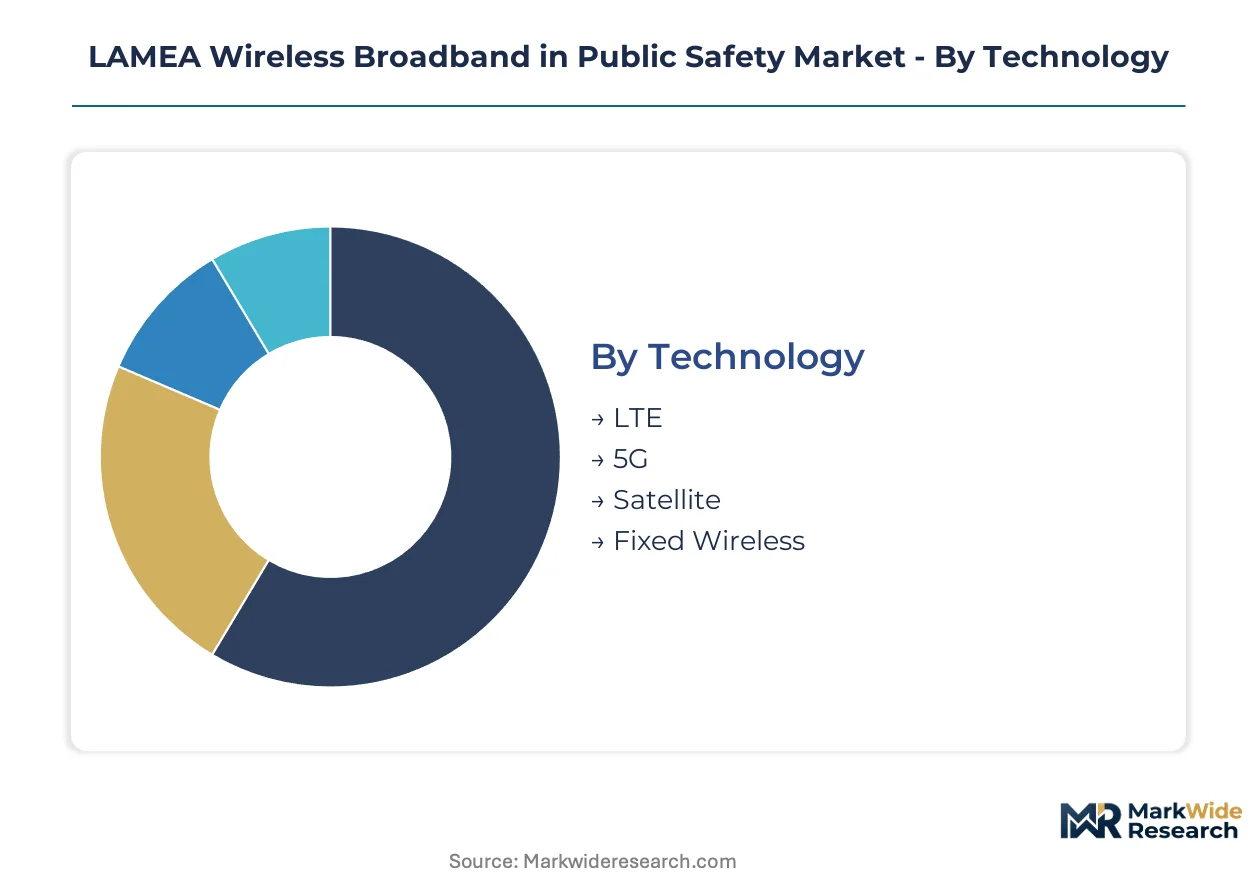
Technology refresh cycles vary dramatically across LAMEA public safety broadband, with network infrastructure turning over every 7-10 years while application software updates cycle quarterly. Procurement patterns concentrate budgets where interoperability mandates force coordinated upgrades across multiple agencies.
Technology:
LTE equipment dominates current procurement with proven certification timelines, while 5G infrastructure attracts the fastest upgrade interest from agencies seeking network slicing capabilities. Satellite and fixed wireless occupy longer replacement cycles due to specialized deployment constraints.
- LTE:Fourth-generation cellular technology delivers proven interoperability with existing Land Mobile Radio systems through standardized mission-critical push-to-talk protocols. Brazilian state police agencies in São Paulo and Minas Gerais prioritize LTE for its established vendor ecosystem and ANATEL certification pathway.
- 5G:Fifth-generation networks enable sub-10 millisecond latency and network slicing for guaranteed emergency traffic bandwidth. Mexico City metropolitan police accelerate 5G pilot programs for real-time video analytics, though equipment authorization delays through IFT compress deployment timelines.
- Satellite:Geostationary and low-earth orbit constellations provide backhaul where terrestrial fiber deployment is economically prohibitive in Amazon basin and Andean terrain.
- Fixed Wireless:Point-to-point microwave links bridge coverage gaps in rural Colombian and Peruvian deployment zones with diesel-dependent power infrastructure.
LTE dominates installed base. 5G is where expansion concentrates.
Application:
Budget allocation tracks incident frequency and federal mandate priority, with emergency response commanding the largest recurring allocations while crime prevention analytics attract discretionary technology refresh spending.
- Emergency Response:Real-time coordination systems for first responders require guaranteed bandwidth for voice, video, and biometric data transmission during active incidents. Brazilian federal emergency agencies structure procurement around 99.999% availability thresholds with performance-based payment terms.
- Disaster Management:Rapidly deployable communication networks for natural disaster scenarios integrate satellite backhaul with mobile LTE cores in hardened vehicle configurations. Chilean national emergency office leads regional adoption following seismic event response requirements.
- Crime Prevention:Edge-computing camera networks with AI-powered analytics demand sustained uplink capacity for video streaming to central command.
- Traffic Management:Intelligent transportation systems coordinate signal timing and incident response through dedicated public safety spectrum allocations.
Emergency Response dominates installed base. Crime Prevention is where expansion concentrates.
End User:
Procurement centralization varies by governance structure, with federal agencies managing cross-jurisdictional networks while municipal departments control station-level equipment decisions.
- Police Departments:Law enforcement agencies drive the largest equipment volumes through body-worn camera programs and mobile data terminal deployments. São Paulo and Rio de Janeiro state police coordinate multi-billion dollar modernization initiatives with ANATEL-mandated encryption standards.
- Fire Departments:Structural fire response units prioritize ruggedized devices with thermal imaging integration and hazardous environment certification.
- Ambulance Services:Emergency medical transport operators require seamless hospital handoff protocols and telemedicine video capabilities.
- Government Agencies:Federal coordination bodies manage cross-agency interoperability gateways and national emergency communication frameworks.
Police Departments dominate installed base. Government Agencies is where expansion concentrates.
Deployment:
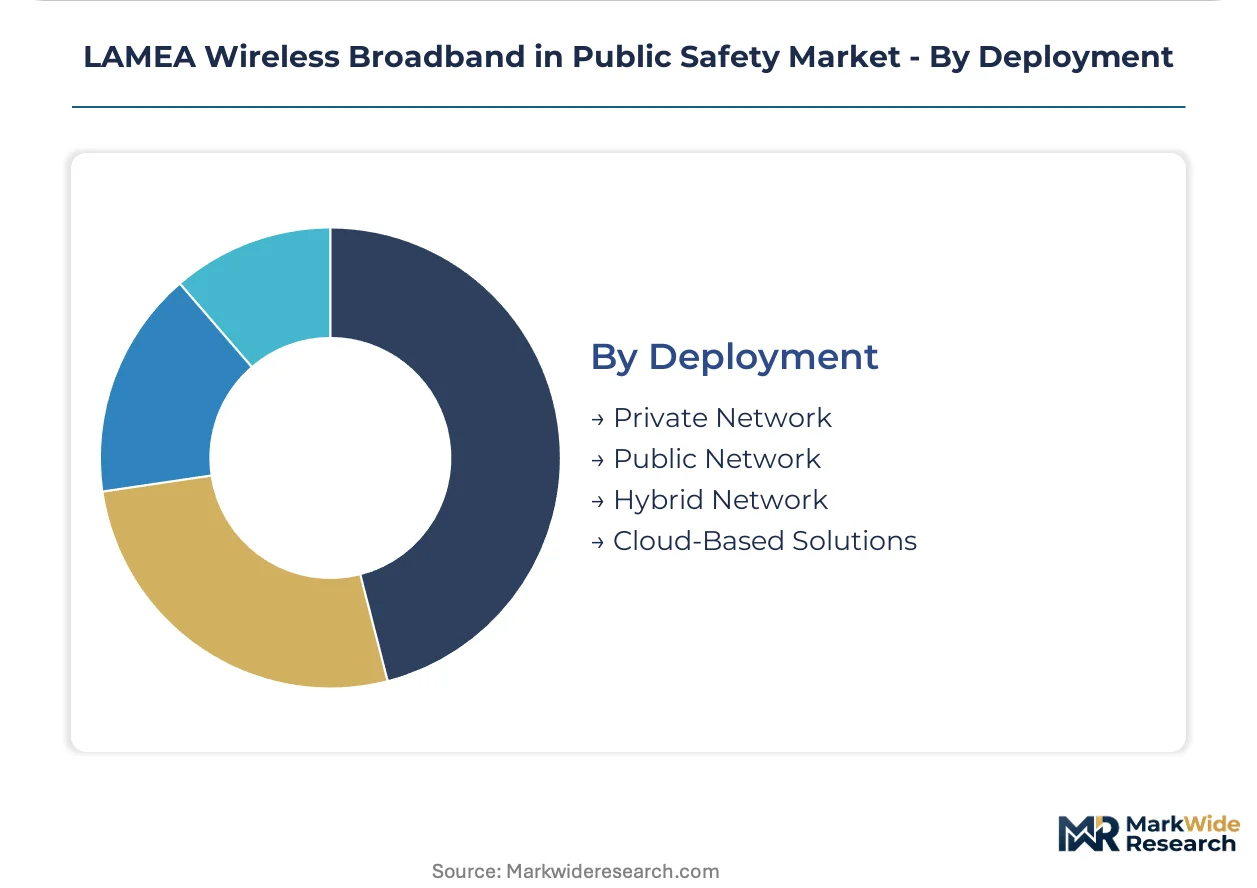
Operating model selection reflects risk transfer preferences, with availability guarantees becoming the primary vendor selection criterion as municipal governments shift accountability to private operators.
- Private Network:Dedicated infrastructure owned and operated by public safety agencies ensures exclusive spectrum access and security control. South African ICASA regulations favor this model for critical infrastructure protection mandates.
- Public Network:Commercial carrier service agreements with priority access mechanisms reduce capital requirements but introduce dependency on consumer network congestion management.
- Hybrid Network:Combined private LTE cores with commercial roaming capabilities balance control with coverage extension during cross-border operations.
- Cloud-Based Solutions:Virtualized network functions hosted in sovereign data centers enable rapid scaling without physical infrastructure deployment.
Private Network dominates installed base. Hybrid Network is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands premium pricing for mission-critical LTE infrastructure while Colombian procurement budgets constrain vendor margins. Mexico's federal coordination frameworks concentrate demand at national scale. South Africa's ICASA regulations fragment procurement across provincial boundaries.
Brazil
ANATEL's 700 MHz spectrum reservation for first responders drives dedicated network procurement across São Paulo and Rio de Janeiro state police agencies. The regulator's encryption certification mandates post-quantum cryptographic readiness, extending equipment authorization timelines. Minas Gerais and Bahia structure performance-based 10-year operations contracts that transfer availability risk to private operators.
Mexico
Mexico City metropolitan police accelerate 5G pilot programs for real-time video analytics requiring guaranteed bandwidth. IFT's Rapid Deployment Framework compresses equipment authorization from 18 months to 6 months for public safety bands. Federal emergency agencies coordinate cross-jurisdictional networks through the national emergency communication framework.
South Africa
ICASA regulations favor private network ownership models for critical infrastructure protection mandates. Legacy P25 and TETRA system replacement schedules synchronize with broadband infrastructure refresh windows. Provincial procurement fragmentation across Gauteng, Western Cape, and KwaZulu-Natal complicates vendor scale economics.
Chile
The national emergency office leads regional adoption of rapidly deployable satellite-LTE hybrid networks following seismic event response requirements. Land Mobile Radio interoperability mandates bundle vendor selection decisions across federal and municipal agencies. Santiago metropolitan region concentrates edge-computing camera deployments for disaster management coordination.
Argentina
Federal police modernization programs in Buenos Aires and Córdoba remain early-stage, offering first-mover positioning for integrated LTE-LMR hybrid systems. Budget cycle delays until 2027 freeze competitive selection processes. Unreliable grid electricity in rural deployment zones necessitates diesel generator backup, adding operational complexity.
LAMEA Wireless Broadband in Public Safety Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying encryption chips and RF modules. The vendor base consolidates around three tiers: established mission-critical radio incumbents extending into LTE, telecommunications equipment manufacturers supplying network infrastructure, and satellite operators providing backhaul coverage. Strategic moves concentrate on long-term leasing arrangements for network infrastructure and performance-based operations contracts transferring availability risk to private operators.
Within the mission-critical systems tier, Motorola Solutions Inc. and Ericsson exemplify contrasting competitive approaches. The former leverages installed base relationships to extend into LTE deployments; the latter anchors large-scale network buildouts through equipment supply partnerships with regional carriers. Huawei Technologies Co. Ltd. occupies a position competing on total cost of ownership metrics for 5G base stations across Latin American markets, though import tariff volatility destabilizes municipal budget calculations.
| Leading Market Players |
|---|
| Motorola Solutions Inc. |
| Ericsson |
| Nokia Corporation |
| Huawei Technologies Co. Ltd. |
| AT&T Inc. |
| Cisco Systems Inc. |
| Verizon Communications |
| ZTE Corporation |
| Airbus Group Inc. |
| Others |
Pricing and Supply Chain Analysis
The Panama Canal shipping corridor's congestion-driven rate volatility feeds directly into Brazilian and Mexican procurement budgets, amplifying cost spreads between turnkey LTE deployments and modular 5G upgrades while compressing margins for vendors without regional manufacturing footprints.
Pricing Analysis
The customization-premium spread between configured-to-order mission-critical LTE cores and standard commercial-off-the-shelf equipment runs wide in this market, with ANATEL-certified encryption modules commanding substantial premiums over baseline configurations. Price differentiation hinges on certification grade under Brazil's post-quantum cryptographic mandates and volume scale of state-level bundled procurements. Cost compression in standard-tier equipment is intensifying because Huawei's total-cost-of-ownership positioning forces incumbent vendors to absorb certification timeline risks. Municipal police departments exhibit the highest price sensitivity due to constrained annual budgets, while federal emergency agencies prioritize availability guarantees over unit economics.
Supply Chain Analysis
Upstream feedstock for AES-256 encryption chips draws from Taiwanese foundry capacity, with RF power amplifiers and baseband processors sourcing from South Korean and Chinese manufacturing clusters. Raw material dependencies span gallium nitride substrates, high-purity silicon carbide, and specialized ceramic packaging. Single-source vulnerability concentrates in post-quantum cryptographic IP licensing, where NIST-standard algorithm implementations remain tethered to a handful of security vendors. Distribution runs through authorized regional systems integrators who manage ANATEL and IFT certification workflows for end-user agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Federal procurement consolidation across Brazil and Mexico is shifting buyer power toward state-level coordinators, fragmenting vendor access to individual municipal departments and compressing pricing leverage for equipment suppliers without established government relationships.
For Market Incumbents: Entrench position through captive supply of encryption chip fabrication capacity, backward integration into sovereign data center operations across São Paulo and Mexico City to meet latency mandates, and exclusive long-term leasing arrangements that transfer availability risk while locking out modular competitors seeking entry via equipment-only sales.
For New Entrants and Emerging Players: Build out satellite-cellular convergence capabilities targeting Amazon basin coverage gaps where fiber economics fail, prioritize Argentina's federal police modernization ahead of 2027 budget cycles, and pursue rapid IFT certification under Mexico's streamlined six-month framework to establish reference deployments before incumbent refresh windows close.
For Investors and Strategic Acquirers: ANATEL's post-quantum cryptographic readiness mandate reshapes the acquisition landscape toward vendors with pre-integrated lattice-based algorithm portfolios and demonstrated mean-time-between-failure metrics. Target acquisition archetypes include specialized RF engineering boutiques with sub-50 millisecond latency design credentials and satellite backhaul operators with hardened mobile command vehicle integration experience. The signal to watch is provincial procurement fragmentation in South Africa, where ICASA regulations may consolidate toward national frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Cryptographic Certification | ANATEL's lattice-based algorithm mandate extends development cycles and freezes competitive selection until compliance is demonstrated. |
| Performance-Based Operations Contracting | Brazilian state police in Minas Gerais and Bahia transfer availability risk to private operators through 10-year bundled agreements. |
| Satellite-Cellular Convergence Buildout | Low-earth orbit backhaul integration addresses coverage gaps in Andean terrain and Amazon basin where terrestrial fiber deployment is economically prohibitive. |
| Legacy LMR Interoperability Gateway Development | Hybrid operation between existing TETRA voice systems and new LTE data cores demands proprietary solutions that extend deployment timelines. |
| Rapid Deployment Framework Exploitation | Mexico's IFT authorization compression from 18 months to 6 months accelerates competitive entry for infrastructure vendors with pre-certified equipment portfolios. |
Research Methodology
Desk research of ANATEL regulatory filings, IFT equipment authorization databases, and ICASA licensing records preceded structured interviews with mission-critical network engineers at state police agencies, procurement directors at federal emergency coordination bodies, RF systems architects at regional carriers, and satellite backhaul specialists serving Amazon basin deployments. Secondary validation drew from 3GPP standard evolution documentation, national spectrum allocation decrees, and customs trade data on base station imports. Bottom-up equipment shipment tracking and top-down public budget appropriation analysis were triangulated to reconcile volume estimates.
Assumptions around spectrum harmonization progress, encryption certification timeline compression, and satellite launch cadence for low-earth orbit constellations were held fixed across baseline scenarios while tariff volatility and semiconductor supply disruption were modeled as stress variables. Segmentation dimensions included technology generation, application priority tier, end-user governance level, and deployment operating model. CAGRs were derived from logistic diffusion curves fitted to procurement cycle data and interoperability mandate synchronization schedules. Industry-specific inputs incorporated P25 and TETRA replacement timelines, edge-computing camera deployment densities, and diesel generator dependency rates for rural coverage extensions.
Stress conditions across import duty fluctuation bands, encryption chip foundry utilization thresholds, and grid reliability indices in Colombian and Peruvian deployment zones were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory timeline adherence and equipment certification pathway completion. Cross-checking against national emergency communication framework budget appropriations and state-level public safety modernization program announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Safety
Safe City Market
Public Safety
Counter Terror and Public Safety Technology Market
Public Safety
Middle East Crime and Combat Market
Public Safety
Global Public Safety Analytics Market
Public Safety
US Mass Notification Systems Market
Public Safety
AI for Public Security and Safety Market
Public Safety
Latin America Public Safety Market
Public Safety
Global Public Safety and Security Market
Public Safety
Crime Risk Report Market
Public Safety
Europe Wireless Broadband in Public Safety Market
Public Safety
Asia-Pacific Public Safety Market
Public Safety
Public Safety LTE Market
Public Safety
Crowd Management System Market
Public Safety
Public Safety in-Building Wireless Distributed Antenna System (DAS) Market
Public Safety
Global Public Safety in Building Wireless Das System Market
Public Safety
Global IoT for Public Safety Market