
 Veterinary Imaging Systems Market | 2026-2036
Veterinary Imaging Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Imaging Systems Market Analytics
Veterinary equipment distribution is fragmenting as regional distributors lose ground to manufacturer-direct sales and specialized veterinary purchasing cooperatives. IDEXX Laboratories leverages its in-house reference laboratory network to bundle imaging hardware with diagnostic services. GE HealthCare anchors its position through AI-enabled ultrasound platforms designed for equine and small-animal applications. Esaote specializes in portable MRI configurations that serve mobile imaging services and rural veterinary practices.
Veterinary imaging systems comprise radiographic, tomographic, and sonographic equipment engineered for non-invasive anatomical and functional assessment of animal patients, with digital detector arrays typically achieving spatial resolution below 150 micrometers for small-animal radiography. Ultrasound dominates installed base volumes due to lower capital requirements and minimal facility shielding needs, while CT scan generates premium margins from complex oncology and orthopedic caseloads at tertiary referral hospitals. Cloud-based solutions are expanding fastest as practices seek remote specialist consultation and teleradiology workflow integration.
FDA Center for Veterinary Medicine oversees device safety labeling, while USDA Animal and Plant Health Inspection Service regulates imaging agents used in food-producing animals, creating dual compliance pathways for manufacturers. The EU Veterinary Medicines Regulation and MDR framework impose parallel conformity requirements for equipment sold across European veterinary markets. Stakeholders must monitor evolving AI diagnostic software classification rules that could reclassify algorithm-enhanced imaging platforms as regulated veterinary devices.
Market Dynamics
AI diagnostic software is collapsing the traditional radiologist-referral workflow as cloud-native platforms enable real-time image interpretation at point-of-care, forcing equipment manufacturers to bundle algorithmic capabilities or surrender margin to software vendors.
Growth Catalysts
- USDA APHIS imaging agent regulations:Mandatory residue testing protocols for food-producing animals drive repeat scan volumes at large-animal veterinary practices.
- Companion animal oncology caseloads:Pet insurance reimbursement for CT-guided biopsies and radiation planning expands hardware utilization rates at tertiary centers.
- Portable ultrasound miniaturization:Battery-powered handheld devices with wireless Doppler penetrate ambulatory equine and mobile farm services previously unreachable by cart-based systems.
Market Restraints
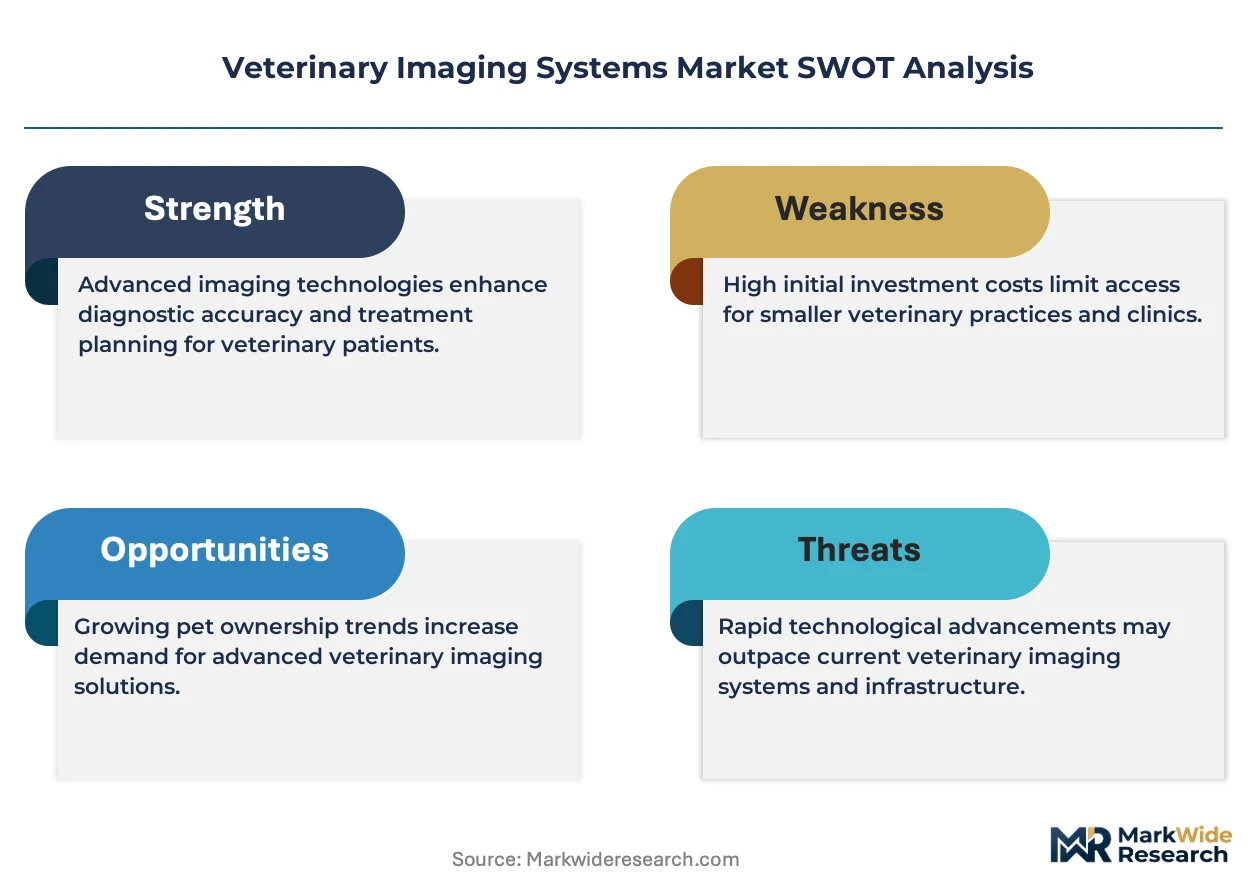
- Helium supply concentration:MRI magnet cooling dependency on US Bureau of Land Management helium auctions creates price volatility and forced downtime risk for rural veterinary installations.
- FDA Center for Veterinary Medicine software classification uncertainty:Pending guidance on AI-enabled diagnostic algorithms threatens compliance timelines and R&D investment clarity.
- CT shielding capex burden:Lead-lined vault construction costs and municipal permitting delays extend clinic expansion timelines by 8-14 months in most US jurisdictions.
Strategic Opportunities
- Brazil ANVISA fast-track pathway:Expedited registration for veterinary devices with existing US FDA clearance accelerates Latin American market entry for imaging OEMs.
- Teleradiology workflow integration:Cloud PACS architectures with automated case routing enable specialist networks to serve dispersed general practices without physical presence.
- Equine sports medicine convergence:Lameness localization demand from Thoroughbred racing stables and FEI competition veterinary requirements drives premium ultrasound and standing MRI adoption.
Industry Challenges
- Veterinary radiologist workforce scarcity:Board-certified diagnostic imaging specialists cluster at academic institutions, creating case backlogs and delayed report turnaround at private referral hospitals.
- Legacy CR-to-DR upgrade friction:Computed radiography cassette systems at established practices face parts obsolescence and software incompatibility with modern PACS architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Imaging Systems Market |
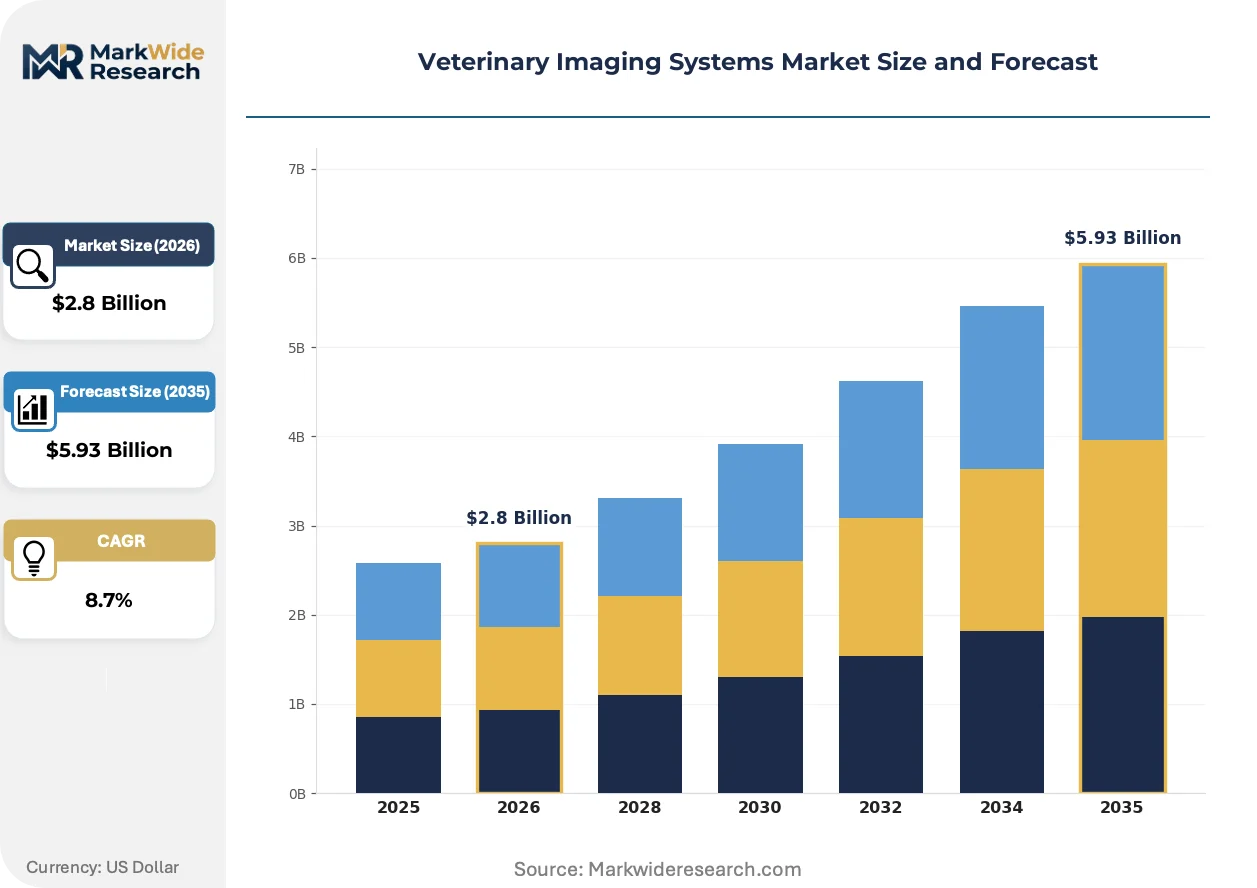
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray, Ultrasound, MRI, CT Scan Application: Diagnostics, Surgery, Orthopedics, Cardiology End User: Veterinary Clinics, Animal Hospitals, Research Laboratories, Mobile Imaging Services Technology: Digital Imaging, Analog Imaging, Portable Systems, Cloud-Based Solutions |
| Companies Covered | IDEXX Laboratories, Inc., GE HealthCare, Esaote S.p.A., Siemens Healthineers AG, Canon Inc., Fujifilm Holdings Corporation, Mindray Medical International Limited, Carestream Health, Agfa-Gevaert Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Imaging Systems Market Evolving Landscape
Software-defined imaging architectures are dissolving the boundary between hardware acquisition and diagnostic interpretation, compressing value capture toward algorithm developers and cloud infrastructure providers.
Photon-counting detector technology is collapsing the dose-resolution tradeoff that previously constrained small-animal CT throughput. Tertiary referral hospitals in the United States and Japan are replacing energy-integrating detectors with cadmium telluride arrays that halve anesthesia time per oncology staging study. The structural consequence is collapsing premium pricing power for conventional CT platforms as performance differentiation narrows.
The EU AI Act and MDR framework are tightening conformity assessment requirements for machine-learning-enabled diagnostic software. Manufacturers must now compile clinical validation dossiers for algorithm outputs classifiable as medical devices, extending time-to-market by 12-18 months. Veterinary-specific AI modules face particular scrutiny where human medical equivalence claims blur regulatory boundaries.
Subscription-based equipment access is displacing outright purchase at independent companion animal practices. IDEXX Laboratories and specialized veterinary finance entities now bundle hardware, maintenance, and cloud PACS under per-scan or monthly fee structures. This shift concentrates most acutely in Germany and the United Kingdom where practice consolidation creates credit-constrained buyers seeking operational expenditure treatment.
Veterinary Imaging Systems Market Segmentation
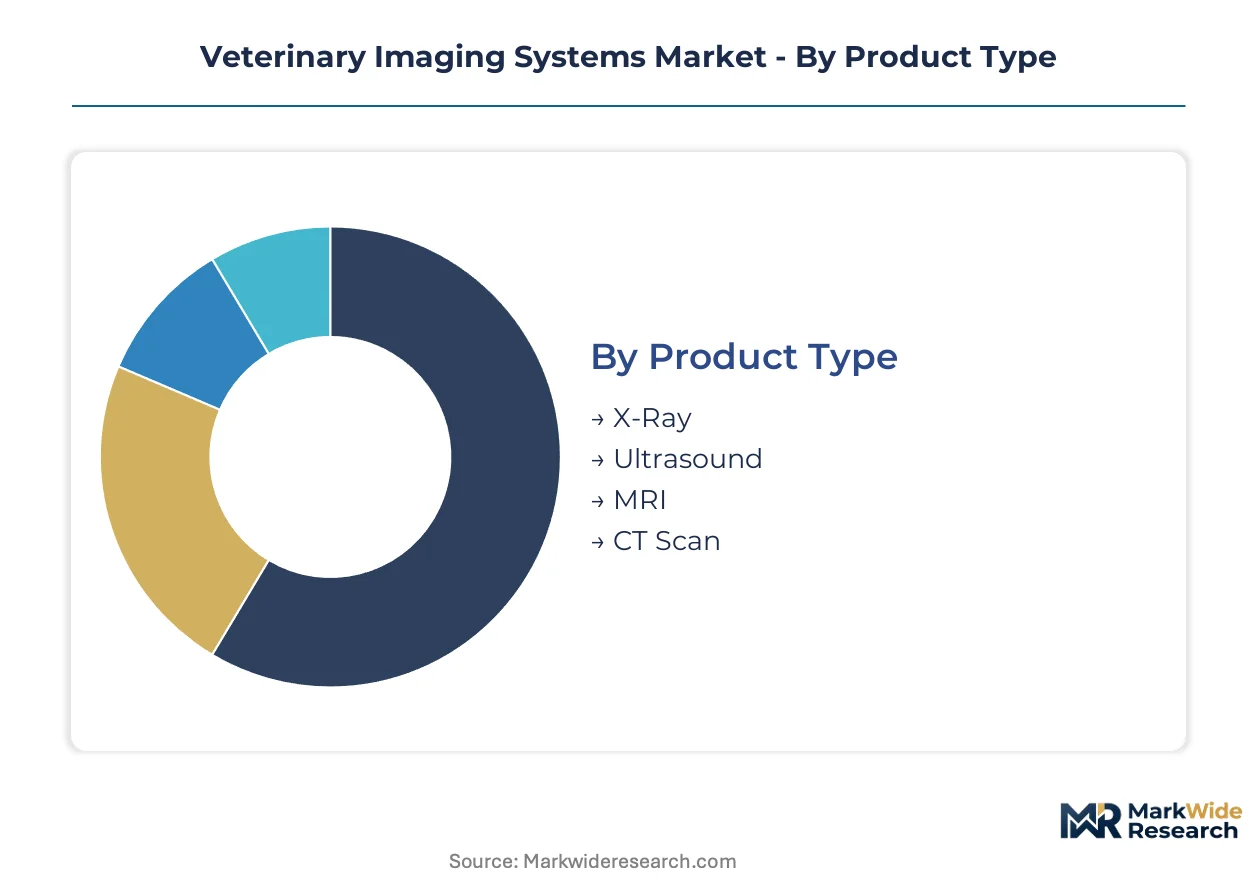
Veterinary imaging segmentation reveals stark replacement-cycle divergences between capital-intensive modalities and consumable-heavy platforms. Equipment refresh timelines stretch from seven-year MRI magnet cycles to eighteen-month handheld ultrasound turnovers, reshaping vendor revenue recognition and service contract structures.
Product Type:
Replacement velocity separates modalities into two distinct cohorts: portable ultrasound systems turn over fastest as battery degradation and probe connector wear drive ambulatory practices toward frequent upgrades, while MRI and CT platforms anchor decade-long depreciation schedules at tertiary referral centers.
- X-Ray:Digital detector arrays with cesium iodide scintillators achieve sub-150 micrometer spatial resolution for small-animal skeletal imaging. Companion animal clinics in the United States concentrate demand as pet insurance reimbursement for trauma radiography expands hardware utilization rates.
- Ultrasound:Battery-powered handheld devices with wireless Doppler penetrate ambulatory equine and mobile farm services previously unreachable by cart-based systems. Germany and the United Kingdom show fastest expansion where practice consolidation creates credit-constrained buyers seeking operational expenditure treatment.
- MRI:Superconducting magnets requiring liquid helium cooling face forced downtime risk from US Bureau of Land Management auction price volatility.
- CT Scan:Photon-counting cadmium telluride detectors halve anesthesia time per oncology staging study at Japanese and US tertiary hospitals.
Ultrasound dominates installed base. CT scan is where expansion concentrates.
Application:
Margin profiles diverge sharply across clinical use cases, with oncology staging and orthopedic surgical planning commanding premium pricing while routine wellness screening compresses toward commodity economics.
- Diagnostics:Cloud-native AI platforms enable real-time image interpretation at point-of-care, collapsing traditional radiologist-referral workflows. Demand clusters at general practices in Japan and Germany seeking teleradiology integration without specialist physical presence.
- Surgery:Intraoperative imaging with C-arm fluoroscopy guides orthopedic implant placement and soft-tissue tumor resection. United States academic veterinary medical centers drive adoption as residency training programs mandate advanced surgical imaging exposure.
- Orthopedics:Weight-bearing CT and standing MRI configurations address lameness localization in Thoroughbred racing stables.
- Cardiology:Spectral Doppler and tissue velocity imaging assess valvular insufficiency and cardiomyopathy in aging companion animal populations.
Diagnostics captures volume leadership. Surgery represents the fastest-growing trajectory.
End User:
Procurement sophistication varies dramatically across facility types, with research laboratories demanding ISO-calibrated quantitative imaging while mobile services prioritize ruggedized portability over absolute resolution.
- Veterinary Clinics:Independent companion animal practices in the United Kingdom and Germany increasingly favor subscription-based equipment access bundling hardware, maintenance, and cloud PACS under per-scan fee structures.
- Animal Hospitals:Tertiary referral centers with board-certified radiologists concentrate CT and MRI caseloads for complex oncology and orthopedic staging. FDA Center for Veterinary Medicine oversight of device safety labeling shapes procurement compliance requirements.
- Research Laboratories:Preclinical imaging for pharmaceutical toxicology studies demands calibrated quantitative biomarkers and GLP-compliant documentation.
- Mobile Imaging Services:Portable MRI and ultrasound configurations serve rural veterinary practices unreachable by fixed installations.
Veterinary clinics dominate installed base. Mobile imaging services are expanding most quickly.
Technology:
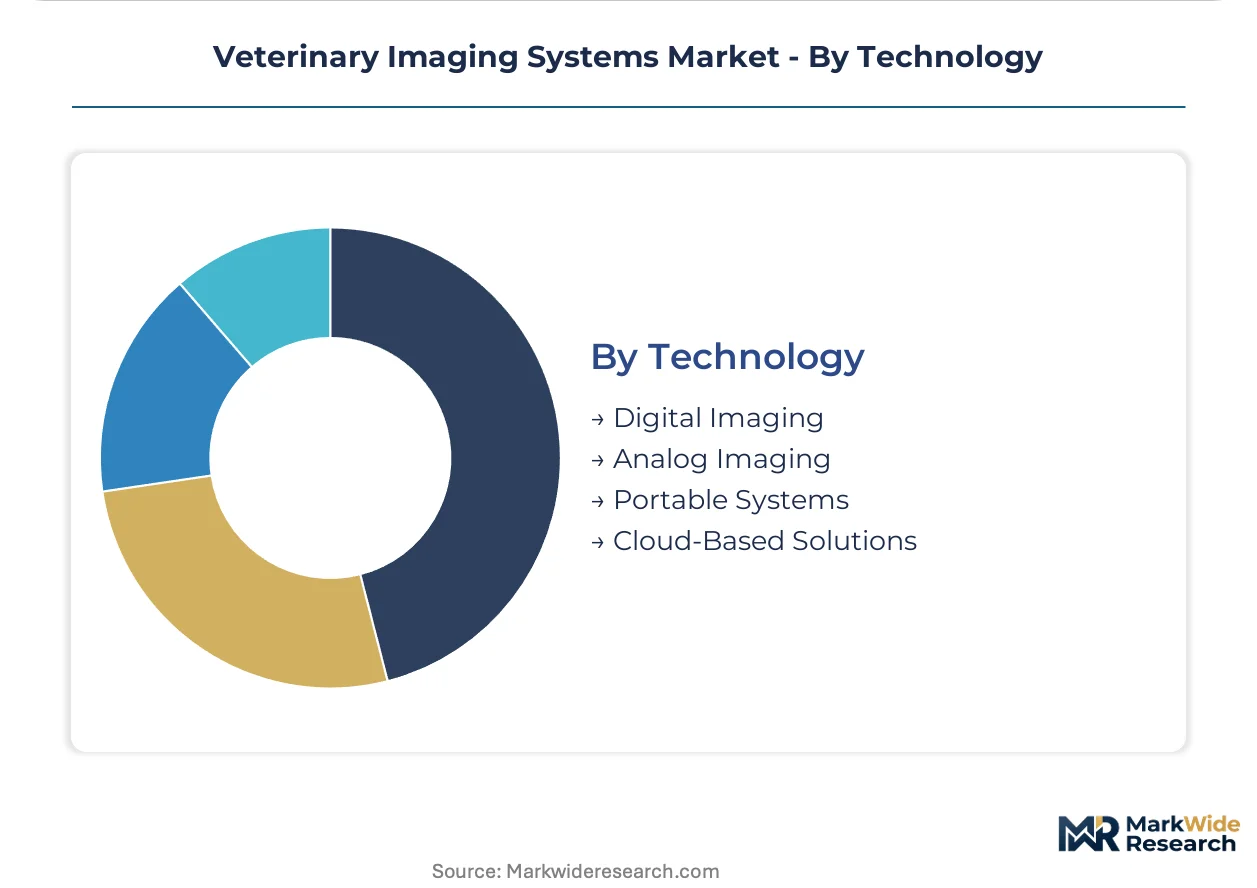
Architecture transitions are compressing value capture toward algorithm developers and cloud infrastructure providers as software-defined imaging dissolves traditional hardware-interpretation boundaries.
- Digital Imaging:Direct radiography panels with thin-film transistor backplanes replace computed radiography cassette systems facing parts obsolescence. EU MDR framework and EU AI Act impose parallel conformity requirements for equipment sold across European veterinary markets.
- Cloud-Based Solutions:Automated case routing enables specialist networks to serve dispersed general practices without physical presence, addressing veterinary radiologist workforce scarcity at private referral hospitals.
- Analog Imaging:Legacy film-screen systems persist in price-sensitive emerging markets with limited PACS infrastructure.
- Portable Systems:Miniaturized electronics and solid-state batteries enable ambulatory deployment previously impossible with cart-based architectures.
Digital imaging dominates installed base. Cloud-based solutions represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA and USDA oversight of veterinary device safety and radiopharmaceutical use tightens compliance requirements in the United States, while EU MDR and AI Act frameworks reshape European conformity pathways for algorithm-enhanced imaging platforms.
United States
Companion animal clinics expand imaging adoption as pet insurance penetration deepens reimbursement pools for CT-guided biopsies. FDA Center for Veterinary Medicine oversees device safety labeling while USDA APHIS regulates imaging agents for food-producing animals. Tertiary referral hospital networks concentrate in metropolitan corridors across Massachusetts, North Carolina, and California.
Germany
Practice consolidation creates credit-constrained buyers seeking subscription-based equipment access bundling hardware and cloud PACS. EU MDR framework and EU AI Act impose parallel conformity assessment requirements for machine-learning-enabled diagnostic software. Industrial clusters in Bavaria and North Rhine-Westphalia host specialized veterinary purchasing cooperatives displacing regional distributors.
Japan
Aging companion animal populations drive cardiology and oncology staging demand at academic veterinary medical centers. METI standards and PMDA oversight shape procurement compliance for imported imaging platforms. Tokyo and Osaka metropolitan areas concentrate board-certified diagnostic imaging specialists facing case backlogs at private referral hospitals.
United Kingdom
Independent companion animal practices favor operational expenditure treatment through per-scan fee structures. EU Veterinary Medicines Regulation maintains influence on cross-border equipment standards despite post-Brexit regulatory divergence. Greater London and Southeast England clusters anchor teleradiology workflow integration serving dispersed general practices.
Brazil
ANVISA fast-track pathway expedites registration for veterinary devices with existing US FDA clearance, accelerating Latin American market entry. Large-animal veterinary practices respond to mandatory residue testing protocols for food-producing animals. São Paulo and Minas Gerais states concentrate mobile imaging services penetrating rural veterinary markets unreachable by fixed installations.
Veterinary Imaging Systems Market Competitive Landscape
On the supply side, the industry is consolidating around bundled diagnostic service models as manufacturer-direct sales and specialized purchasing cooperatives displace fragmented regional distribution networks. Strategic archetypes include laboratory-integrated platform vendors, imaging pure-plays with AI-enabled modalities, and diversified industrial conglomerates with veterinary divisions. Dominant competitive moves encompass vertical integration into reference laboratory networks and cloud-native algorithm licensing partnerships.
Within the laboratory-integrated tier, IDEXX Laboratories exemplifies bundled hardware and diagnostic service positioning. Among diversified health technology conglomerates, GE HealthCare and Siemens Healthineers occupy positions spanning human and veterinary imaging modalities. Esaote S.p.A. represents specialized European imaging pure-plays with portable MRI configurations serving mobile veterinary services.
| Leading Market Players |
|---|
| IDEXX Laboratories, Inc. |
| GE HealthCare |
| Esaote S.p.A. |
| Siemens Healthineers AG |
| Canon Inc. |
| Fujifilm Holdings Corporation |
| Mindray Medical International Limited |
| Carestream Health |
| Agfa-Gevaert Group |
| Others |
Value Network & Pricing Analysis
US Bureau of Land Management helium auctions concentrate liquid helium supply for MRI magnet cooling, tethering margin pools at tertiary veterinary hospitals to federal mineral lease policy volatility and forcing equipment financiers to price forced-downtime risk into service contracts.
Pricing Analysis
Volume-discount tiering structures separate subscription-based per-scan arrangements for consolidated practice chains from capital purchase models at independent clinics. Three-tier pricing structure across premium, standard, and economy levels differentiates photon-counting CT platforms from energy-integrating detectors and legacy CR systems. Cost compression in economy-tier digital radiography intensifies because parts obsolescence for cassette-based systems accelerates replacement cycles. Independent companion animal practices in Germany and the United Kingdom exhibit highest price sensitivity, while US tertiary referral hospitals with pet insurance reimbursement pools show lowest.
Supply Chain Analysis
Extended payment terms from specialized veterinary finance entities now reach 36-48 months for MRI platforms, compressing manufacturer cash conversion cycles and forcing OEMs to secure supply-chain finance facilities against receivables. Manufacturing concentrates in the United States, Germany, and Japan for superconducting magnets, digital detector arrays, and AI-enabled ultrasound electronics. Cadmium telluride semiconductor substrates and liquid helium for cryogenic cooling draw from concentrated mining and gas separation operations. Single-source vulnerability for helium feedstock from the US Federal Helium Reserve threatens magnet uptime guarantees. Distribution runs through manufacturer-direct sales teams and specialized veterinary purchasing cooperatives displacing fragmented regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary imaging sits at an inflection where FDA Center for Veterinary Medicine AI software classification guidance will restructure competitive advantage toward algorithm developers and away from hardware-centric incumbents.
For Market Incumbents: Insulate service contract revenue against point-of-care AI disruption by embedding cloud-native interpretation tools directly into hardware bundles, and secure backward integration into reference laboratory networks to lock diagnostic workflow continuity. The threat of algorithm vendors capturing margin from standalone software licensing demands captive control over teleradiology infrastructure. For New Entrants and Emerging Players: Mobile imaging services in rural Brazil and ambulatory equine practices in Kentucky represent the most penetrable entry points, with battery-powered handheld ultrasound configurations bypassing the CT shielding capex burden that blocks clinic expansion. A go-to-market angle through veterinary purchasing cooperatives in Germany and the United Kingdom accesses credit-constrained buyers seeking operational expenditure treatment without competing against IDEXX's bundled laboratory-imaging platform. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed veterinary practice consolidators seeking to standardize imaging equipment across acquired clinic networks. Long-term viability hinges on AI diagnostic software classification clarity from FDA and USDA, with cloud PACS architectures representing the most defensible infrastructure layer. The signal to watch is FDA guidance publication on algorithm-enhanced platforms, which will determine whether hardware manufacturers retain value capture or surrender margin to software vendors.| Strategic Initiative | Industry Significance |
|---|---|
| AI Diagnostic Software Integration | Bundles real-time interpretation into hardware platforms, collapsing radiologist-referral workflows at point-of-care. |
| Subscription-Based Equipment Access | Converts capital expenditure to operational expenditure for credit-constrained practices in Germany and the United Kingdom. |
| Helium Supply Risk Mitigation | Secures magnet cooling feedstock against US Bureau of Land Management auction price volatility and forced downtime. |
| Teleradiology Workflow Integration | Enables specialist networks to serve dispersed general practices without physical presence, addressing radiologist scarcity. |
| Portable System Miniaturization | Penetrates ambulatory equine and mobile farm services previously unreachable by cart-based ultrasound architectures. |
Research Methodology
A standing panel of veterinary practice owners, biomedical equipment procurement managers, teleradiology network operators, and FDA regulatory affairs specialists provided ongoing calibration across primary interview rounds, validated against secondary sources including USDA APHIS imaging agent guidance documents, FDA Center for Veterinary Medicine device labeling databases, EU MDR conformity assessment records, and patent filings for photon-counting detector technology. Bottom-up equipment installation counts and top-down diagnostic service revenue estimates were triangulated to cross-validate market sizing.
Scenario-bracketing framed projections across regulatory clarity and AI software adoption trajectories without year-specific anchoring. Segmentation dimensions spanned modality type, application category, end-user facility tier, and technology architecture across the projection horizon. CAGRs derived from fitted growth curves applied to replacement-cycle dynamics and insurance reimbursement expansion patterns. Forecast inputs incorporated pet insurance penetration curves, practice consolidation rates, and helium supply auction pricing volatility.
Stress conditions across FDA software classification timeline uncertainty, helium supply disruption severity, and AI diagnostic accuracy validation thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory pathway clarity and reimbursement policy stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Radiology As a Service Market
Medical Imaging
US Digital Radiology Market
Medical Imaging
Mobile Vascular Imaging Market
Medical Imaging
Global Picture Archiving Communications System Market
Medical Imaging
Global Mini C-Arm Market
Medical Imaging
Global Electroretinography Market
Medical Imaging
Brazil Digital Radiology Market
Medical Imaging
France Digital Radiology Market
Medical Imaging
Germany Computed Tomography Market
Medical Imaging
Medical Imaging Market
Medical Imaging
Medical Imaging Informatics Market
Medical Imaging
Global Digital Radiography Market
Medical Imaging
South America MRI Market
Medical Imaging
Perfusion Imaging Market
Medical Imaging
Spain Diagnostic Imaging Equipment Market
Medical Imaging
Veterinary CT Imaging Market