
 Combination Anti-Diabetes Drugs Market | 2026-2036
Combination Anti-Diabetes Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Combination Anti-Diabetes Drugs Market Outlook
Indian active pharmaceutical ingredient producers is repositioning capacity toward combination diabetes drug intermediates, responding to contract manufacturing inquiries from Western markets. Eli Lilly and Company leverages its GLP-1 manufacturing infrastructure to sustain leadership in injectable combination therapies. Novo Nordisk A/S anchors European supply through captive peptide production facilities in Denmark. Sanofi Aventis competes across oral and injectable portfolios through differentiated insulin-secretagogue combinations.
Combination anti-diabetes drugs contain two or more distinct pharmacological agents—such as metformin paired with DPP-4 inhibitors or SGLT2 inhibitors—formulated into single-dosage units that target multiple metabolic pathways simultaneously. These formulations reduce pill burden and improve glycemic control adherence among patients requiring polypharmacy. GLP-1 Agonist combinations command premium positioning due to superior HbA1c reduction and cardiovascular outcome benefits, while Metformin Combinations occupy the volume base as first-line oral therapy. Injectable delivery modes capture the fastest growth trajectory, driven by weekly GLP-1 receptor agonist combinations displacing daily oral regimens in Type 2 Diabetes management.
The FDA evaluates combination diabetes therapies through integrated glucose-lowering efficacy and cardiovascular safety endpoints, elevating trial complexity for new entrants. EMA's MDR-aligned pharmacovigilance requirements and the EU Green Deal's pharmaceutical waste directives are reshaping manufacturing compliance costs across European production networks. Stakeholders must monitor evolving CMS reimbursement thresholds for combination products versus component monotherapies, as coverage determinations will dictate prescribing economics in the United States.
Market Dynamics
Fixed-dose combination therapies are compressing prescribing economics by collapsing multi-pill regimens into single-dosage units, forcing hospital formulary committees to rewrite reimbursement protocols and manufacturing networks to retool for complex co-formulation processes.
Growth Catalysts
- FDA Accelerated Approval Pathways:Compressed development timelines for cardiovascular outcome trials are bringing GLP-1 combination therapies to market faster than traditional glucose-lowering efficacy studies.
- German Reimbursement Policy:Statutory health insurance funds favor multi-mechanism oral therapies, concentrating demand for DPP-4 and SGLT2 inhibitor combinations in ambulatory care settings.
- Peptide Manufacturing Infrastructure:Captive production facilities in Denmark and Indianapolis are scaling weekly injectable output to displace daily oral regimens in Type 2 diabetes management.
Market Restraints
- Cardiovascular Safety Trial Costs:Integrated HbA1c and MACE endpoint requirements from FDA and EMA inflate clinical development budgets for new combination entrants.
- Active Pharmaceutical Ingredient Concentration:Indian intermediate producers control 60-70% of metformin-DPP-4 combination starting materials, creating geographic supply vulnerability.
- Biosimilar Substitution Pressure:Insulin-secretagogue combinations face pricing compression as follow-on biologics erode originator margins in European tenders.
Strategic Opportunities
- Underpenetrated Oral-Injectable Transition:Weekly GLP-1 receptor agonist combinations remain below 15% penetration in Medicare Part D formularies, creating white space for formulary access expansion.
- EU Green Deal Pharmaceutical Waste Directives:Sustainable manufacturing incentives are rewarding Danish and German facilities with lower compliance cost structures for combination peptide production.
- Fixed-Dose Triple Therapy:Metformin-SGLT2 inhibitor-GLP-1 agonist co-formulations represent the next formulation frontier as polypharmacy adherence data accumulates.
Industry Challenges
- Peptide Chemist Talent Scarcity:GLP-1 combination manufacturing requires specialized solid-phase synthesis expertise that outpaces European and North American technical training pipeline output.
- Legacy Insulin Portfolio Cannibalization:Sales forces face internal conflict when promoting weekly injectable combinations that displace established daily insulin regimens from the same manufacturer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Combination Anti-Diabetes Drugs Market |
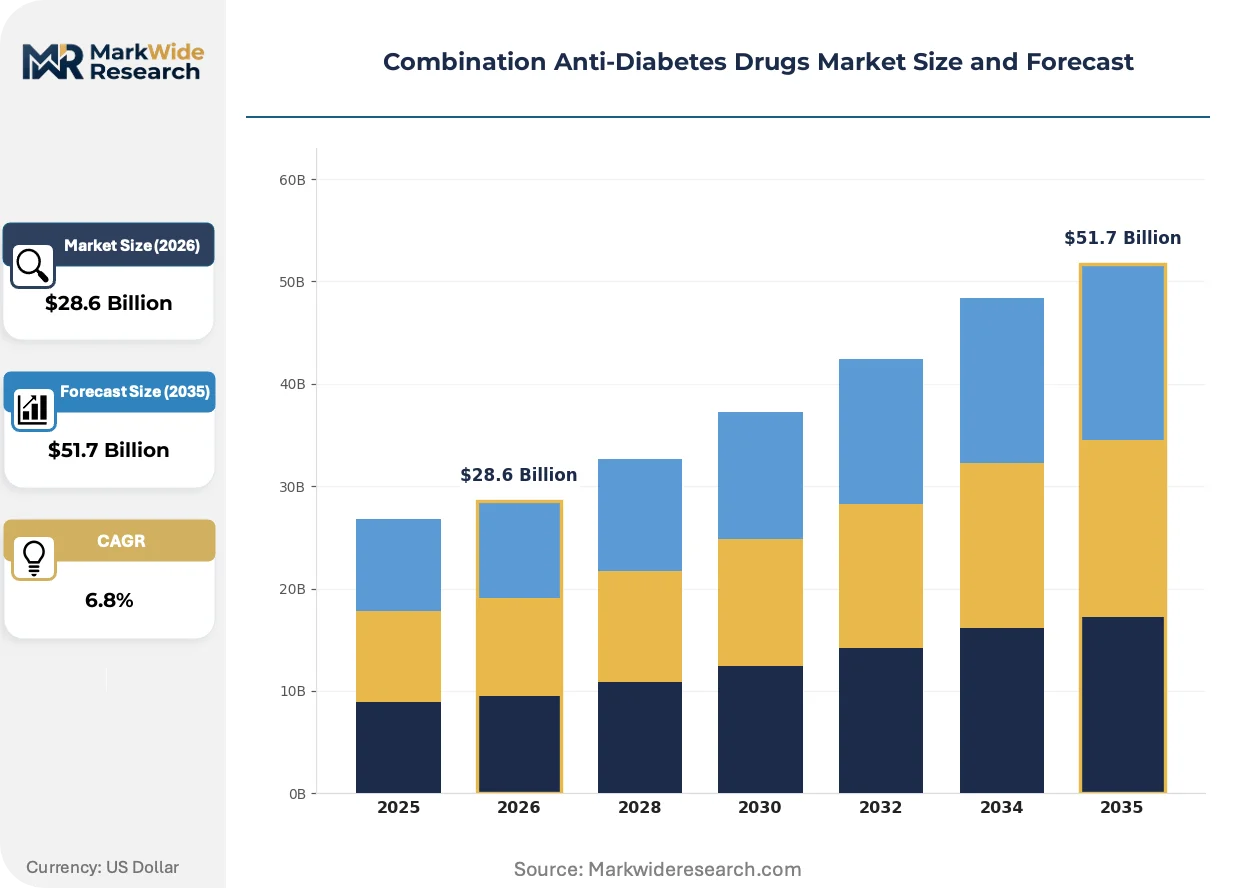
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GLP-1 Agonists, SGLT2 Inhibitors, DPP-4 Inhibitors, Metformin Combinations Therapy Area: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Prediabetes Delivery Mode: Injectable, Oral, Transdermal, Inhalable End User: Hospitals, Clinics, Home Care Settings, Pharmacies |
| Companies Covered | Eli Lilly and Company, Sanofi Aventis, Novo Nordisk A/S, AstraZeneca PLC, Glenmark Pharmaceuticals Limited, Merck & Co., Inc., Boehringer Ingelheim, Takeda Pharmaceutical, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Combination Anti-Diabetes Drugs Market Strategic Shifts
Weekly injectable delivery systems are rewriting adherence protocols and manufacturing scale requirements across the combination therapy landscape, compressing the innovation cycle from clinical validation to formulary placement.
Dual-mechanism peptide-small molecule co-formulation is consolidating manufacturing complexity into single-device platforms. Eli Lilly and Novo Nordisk are scaling fill-finish capacity for fixed-ratio GLP-1/insulin combinations at triple the pace of oral solid dose expansion. This consolidation is collapsing the traditional separation between biologic and small-molecule supply chains, forcing contract manufacturers to acquire peptide synthesis capabilities or exit the diabetes category entirely.
EMA's MDR-aligned pharmacovigilance requirements are elevating post-market surveillance obligations for combination products with cardiovascular outcome claims. Manufacturers must now maintain active registries tracking MACE events for 5-10 years post-approval, adding 12-18% to total cost of goods. German and French regulators are enforcing these mandates most stringently, pushing combination sponsors toward centralized European safety databases.
Hospital procurement committees are unbundling pharmacy benefit management from therapeutic area purchasing, creating direct contracting channels for combination therapies. Integrated delivery networks in Texas and California are negotiating risk-sharing arrangements based on HbA1c attainment rather than per-unit pricing. This reconfiguration is most visible in Medicare Advantage plans, where star rating incentives align payer and provider interests around glycemic control outcomes.
Combination Anti-Diabetes Drugs Market Segmentation
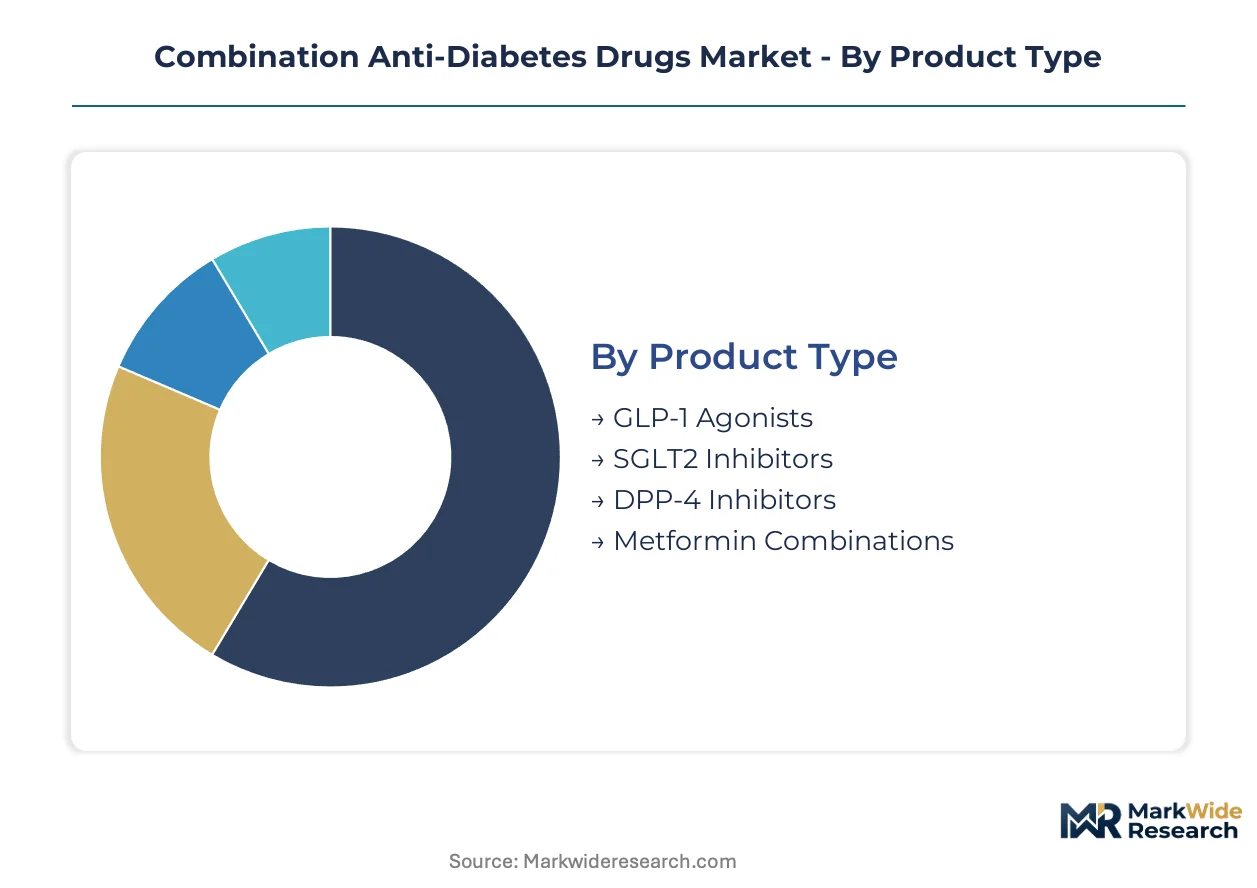
Combination anti-diabetes drugs fragment across pharmacological mechanisms, patient populations, and administration routes that each trigger distinct FDA cardiovascular outcome requirements. Manufacturers must align formulation complexity with the specific approval burden each segment carries.
Product Type:
EMA and FDA cardiovascular safety thresholds vary sharply across these pharmacological classes, with peptide-based therapies facing the most extensive MACE endpoint documentation.
- GLP-1 Agonists:Weekly injectable peptides combining glucagon-like peptide-1 receptor activation with insulin sensitization. Demand clusters in Medicare Advantage plans where HbA1c attainment incentives reward superior cardiovascular outcomes. The FDA mandates integrated glucose-lowering and MACE endpoint trials that extend development timelines.
- SGLT2 Inhibitors:Oral small molecules that pair sodium-glucose cotransporter-2 blockade with metformin or DPP-4 inhibitors. German statutory health insurance funds concentrate procurement for these combinations in ambulatory diabetes management. EMA pharmacovigilance registries track renal and cardiovascular events for 5-10 years post-approval.
- DPP-4 Inhibitors:Dipeptidyl peptidase-4 blockers co-formulated with metformin for first-line oral therapy.
- Metformin Combinations:Volume-leading fixed-dose pairings anchoring polypharmacy reduction strategies.
Metformin Combinations sit at the top of the volume ranking, with GLP-1 Agonists climbing the fastest.
Therapy Area:
Patient population segments diverge sharply in reimbursement eligibility and clinical trial design complexity across US, German, and Danish healthcare systems.
- Type 2 Diabetes:The dominant addressable population requiring multi-mechanism glycemic control. CMS reimbursement thresholds for combination products versus component monotherapies dictate prescribing economics in United States hospital systems. Weekly GLP-1 injectable combinations displace daily oral regimens as prior authorization barriers ease.
- Type 1 Diabetes:Insulin-dependent patients with limited combination therapy penetration due to autoimmune etiology. Danish and German pediatric endocrinology centers drive off-label use of adjunctive non-insulin agents. FDA labeling restrictions constrain formal indication expansion.
- Gestational Diabetes:Pregnancy-specific glucose management with restricted pharmacological options.
- Prediabetes:Pre-diagnostic intervention segment with emerging pharmacological prevention protocols.
Type 2 Diabetes commands absolute volume leadership, while Prediabetes shows the steepest expansion trajectory as prevention frameworks mature.
Delivery Mode:
Manufacturing infrastructure investments separate high-complexity biologic delivery from commoditized oral solid dose production.
- Injectable:Weekly GLP-1 receptor agonist combinations in pre-filled pen devices. Eli Lilly and Novo Nordisk scale fill-finish capacity at triple the pace of oral expansion. Peptide synthesis expertise scarcity in European and North American technical training pipelines constrains output growth.
- Oral:Fixed-dose tablets compressing metformin-DPP-4 and metformin-SGLT2 pairings into single administrations. Indian API producers control 60-70% of starting material supply for these combinations.
- Transdermal:Patch-based delivery systems with limited commercial penetration in diabetes management.
- Inhalable:Pulmonary insulin and adjunctive agent delivery with restricted formulary access.
Oral delivery maintains volume dominance, with Injectable gaining share fastest as adherence protocols shift toward weekly administration.
End User:
Procurement authority concentration determines pricing power and formulary access speed across institutional and retail channels.
- Hospitals:Integrated delivery networks in Texas and California unbundle pharmacy benefit management to negotiate risk-sharing arrangements based on glycemic outcomes. Formulary committees rewrite reimbursement protocols as fixed-dose combinations collapse multi-pill regimens.
- Home Care Settings:Medicare Part D beneficiaries accessing weekly injectable therapies through mail-order specialty pharmacies. Star rating incentives align payer and provider interests around HbA1c attainment.
- Clinics:Ambulatory diabetes centers in Germany concentrating demand for multi-mechanism oral therapies.
- Pharmacies:Retail dispensing points with limited influence over prescriber selection of combination products.
Hospitals sit at the top of the volume ranking, with Home Care Settings climbing the fastest as self-administration protocols expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates European demand for multi-mechanism oral therapies, while the United States drives premium positioning for weekly injectable combinations through Medicare Advantage reimbursement incentives.
United States
Hospital systems in Texas and California unbundle pharmacy benefit management to negotiate risk-sharing arrangements based on HbA1c attainment. FDA accelerated approval pathways compress cardiovascular outcome trial timelines for GLP-1 combination entrants. Indianapolis anchors North American peptide manufacturing infrastructure through captive production facilities scaling weekly injectable output.
Germany
Statutory health insurance funds favor fixed-dose DPP-4 and SGLT2 inhibitor combinations in ambulatory diabetes management. EMA MDR-aligned pharmacovigilance requirements enforce 5-10 year post-market cardiovascular event registries. Bavaria concentrates formulation R&D as manufacturers adapt to EU Green Deal pharmaceutical waste directives.
India
Active pharmaceutical ingredient producers in Gujarat and Maharashtra reposition capacity toward combination diabetes drug intermediates responding to Western contract manufacturing inquiries. CDSCO alignment with ICH guidelines streamlines bioequivalence study requirements for fixed-dose generics. Hyderabad anchors complex chemistry outsourcing as European sponsors seek cost-efficient starting material supply.
Denmark
Peptide manufacturing infrastructure concentrates demand for GLP-1 receptor agonist combinations displacing daily oral regimens. Danish regulators enforce stringent EMA pharmacovigilance mandates for cardiovascular outcome claims. Copenhagen-Zealand corridor hosts captive biologic production facilities supplying European hospital networks.
United Kingdom
NHS Integrated Care Systems evaluate combination therapies through cost-per-QALY thresholds favoring metformin-based fixed-dose entries. MHRA post-Brexit regulatory autonomy permits accelerated access schemes for cardiovascular-benefit diabetes combinations. Greater London procurement committees pilot outcome-based contracting for glycemic control attainment.
Combination Anti-Diabetes Drugs Market Competitive Environment
Danish and Indianapolis-based producers anchor the premium injectable tier; Indian and European specialists hold volume positions in oral fixed-dose formulations. The market structures around three strategic archetypes: captive peptide manufacturers with backward-integrated supply chains, diversified pharmaceutical conglomerates spanning oral and injectable portfolios, and contract research organizations enabling complex co-formulation development. Competitive moves concentrate on fill-finish capacity expansion for weekly delivery devices and pharmacovigilance database centralization to satisfy EMA post-market surveillance mandates.
Within the captive biologic manufacturing tier, Novo Nordisk A/S and Eli Lilly and Company exemplify scale-driven infrastructure deployment. Sanofi Aventis occupies a diversified position spanning insulin-secretagogue combinations across administration modes. These three anchors represent contrasting geographic production strategies—Nordic peptide synthesis specialization, Midwestern US biologic manufacturing concentration, and transatlantic oral-injectable portfolio breadth.
| Leading Market Players |
|---|
| Eli Lilly and Company |
| Sanofi Aventis |
| Novo Nordisk A/S |
| AstraZeneca PLC |
| Glenmark Pharmaceuticals Limited |
| Merck & Co., Inc. |
| Boehringer Ingelheim |
| Takeda Pharmaceutical |
| Sanofi |
| Others |
Value Chain & Pricing Dynamics
Captive biologic manufacturers with backward-integrated peptide synthesis operations command pricing power through supply security guarantees, while Indian API specialists compete on metformin-DPP-4 intermediate cost structures that reshape oral combination economics. German statutory reimbursement floors and FDA cardiovascular trial cost burdens segment the market into premium injectable tiers and commoditized oral fixed-dose entries.
Pricing Analysis
Capacity additions in Denmark and Indianapolis are reshaping price floors for weekly GLP-1 combinations as Eli Lilly and Novo Nordisk scale fill-finish output. Three-tier pricing structure across premium GLP-1 agonist combinations, standard SGLT2 inhibitor pairings, and economy metformin-DPP-4 generics segments buyer access. Cost compression in the oral tier intensifies because Indian API producers expanded intermediate supply, while Medicare Advantage HbA1c attainment incentives reduce price sensitivity for injectable regimens.
Supply Chain Analysis
Dual-sourcing requirements from European hospital procurement committees mandate qualified supply from both Danish peptide facilities and Indian small-molecule intermediate producers. Manufacturing concentrates in Denmark for GLP-1 agonist combinations, India for metformin-DPP-4 starting materials, and Germany for oral solid dose formulation. Supply chain risk centers on single-source vulnerability for specialized solid-phase synthesis expertise, as European and North American technical training pipelines lag demand. Distribution runs through hospital integrated delivery networks in Texas and California, mail-order specialty pharmacies for Medicare Part D beneficiaries, and German ambulatory care clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where German reimbursement floors for oral combinations exceed US Medicare net pricing, while Danish manufacturing proximity to European hospital networks captures premium positioning for injectable therapies.
For Market Incumbents: Anchor peptide manufacturing capacity in the Copenhagen-Zealand corridor to exploit EU Green Deal compliance advantages over US-based competitors. Defend against biosimilar substitution pressure in European insulin-secretagogue tenders by securing 5-10 year pharmacovigilance registry contracts with German and French regulators. Prioritize backward integration into GLP-1 starting materials to reduce exposure to Indian intermediate supply concentration. For New Entrants and Emerging Players: Medicare Part D formularies with sub-15% weekly GLP-1 penetration represent the most penetrable access point for combination entrants lacking established hospital contracts. Target risk-sharing arrangements with Texas and California integrated delivery networks that unbundle pharmacy benefit management from therapeutic area purchasing. Pursue CDSCO-aligned bioequivalence pathways through Hyderabad contract research organizations to accelerate fixed-dose generic market entry. For Investors and Strategic Acquirers: Valuations sit cheapest among Indian API producers repositioning capacity toward combination diabetes intermediates, as Western contract manufacturing inquiries outpace local financing availability. Mid-cap peptide synthesis specialists with captive European facilities offer superior long-term viability given EMA MDR-aligned pharmacovigilance mandates that extend post-market surveillance obligations. Monitor CMS reimbursement threshold determinations for combination products versus component monotherapies as the inflection signal for US prescribing economics.| Strategic Initiative | Industry Significance |
|---|---|
| Peptide Manufacturing Scale-Up | Weekly GLP-1 output expansion in Denmark and Indianapolis displaces daily oral regimens. |
| Cardiovascular Outcome Trial Advancement | FDA integrated HbA1c and MACE endpoint studies compress development timelines for new entrants. |
| EU Green Deal Manufacturing Transition | Sustainable production incentives reward Danish facilities with lower compliance cost structures. |
| Fixed-Dose Triple Therapy Development | Metformin-SGLT2 inhibitor-GLP-1 co-formulation represents the next adherence frontier. |
| Pharmacovigilance Database Centralization | EMA 5-10 year MACE registries add cost but create regulatory moats for compliant sponsors. |
Study Parameters
Multiple input streams — formulary database audits, FDA and EMA regulatory filings, and hospital procurement contract analysis — were reconciled against primary interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists. Secondary validation drew from ClinicalTrials.gov cardiovascular outcome trial records, CMS Medicare Part D claims patterns, German statutory health insurance reimbursement schedules, and Indian CDSCO bioequivalence study disclosures. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Historical prescription volume trajectories were cross-referenced against panel input from hospital pharmacy directors and ambulatory care clinicians to construct the analytical framework across the projection horizon. Segmentation dimensions modeled include pharmacological mechanism, administration route, patient population, and regional regulatory cluster. CAGRs were derived from trend extrapolation adjusted for therapy displacement dynamics, with specific inputs capturing weekly injectable penetration rates and oral generic substitution elasticities.
Underlying measurement precision varies by segment; GLP-1 agonist combinations with established cardiovascular outcome claims carry tighter precision than emerging triple-therapy formulations. Forecasts reflect assumptions around FDA accelerated approval pathway continuity, German reimbursement policy stability, and Indian API export capacity expansion. Deviation in CMS combination product reimbursement thresholds would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Global Smart Diabetes Management Market
Diabetes Care
India Oral Anti-Diabetic Drug Market
Diabetes Care
Italy Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Disposable Insulin-Delivery Device Market
Diabetes Care
Asia-Pacific Diabetes Care Devices Market
Diabetes Care
Glycated Albumin Market
Diabetes Care
Global Pet Diabetes Care Market
Diabetes Care
South Africa Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Antidiabetics Market
Diabetes Care
Vietnam Diabetes Care Devices Market
Diabetes Care
Middle East and Africa Insulin Infusion Pumps Market
Diabetes Care
Alternatives for Injectable Diabetes Care Market
Diabetes Care
Asia Pacific Diabetes Pen Market
Diabetes Care
Italy Oral Anti-Diabetic Drug Market
Diabetes Care
Continuous Glucose Monitoring Market
Diabetes Care
US Continuous Glucose Monitoring Market