
 Latin America Pharmaceutical Glass Packaging Market | 2026-2036
Latin America Pharmaceutical Glass Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Pharmaceutical Glass Packaging Market Insights
ANVISA's updated GMP mandates for sterile pharmaceutical products is repositioning the cost-of-entry calculus for glass packaging suppliers across Latin America. Gerresheimer AG leverages its molded glass expertise to anchor production capacity near Brazilian pharmaceutical clusters. SCHOTT AG sustains technology leadership through controlled borosilicate forming processes that meet elevated thermal-shock specifications. Vitro Glass Containers competes on regional logistics networks, operating furnaces that reduce lead times to Mexican contract manufacturers.
Pharmaceutical glass packaging denotes primary containers fabricated from borosilicate or soda-lime glass, engineered to meet hydrolytic resistance Class I or II per USP <660> and thermal expansion coefficients below 5.0 × 10⁻⁶ K⁻¹ for parenteral applications. These vessels function as chemically inert barriers that prevent ion exchange, maintain sterility, and preserve drug efficacy throughout shelf life. Vials capture the dominant share of value across Latin America, driven by mRNA vaccine cold-chain requirements and oncology injectable portfolios. Ampoules represent a mature segment with thinning margins, while bottles for oral liquids generate stable replacement demand from regional generic pharmaceutical companies.
Brazil's ANVISA, Mexico's COFEPRIS, and Argentina's ANMAT collectively enforce pharmacopeial compliance that shapes glass sourcing decisions, with COFEPRIS aligning Type II DMFs to FDA standards for export-oriented facilities. ISO 9001 and GMP certifications function as non-negotiable qualifiers for supplier qualification programs at multinational pharmaceutical companies. Stakeholders must monitor evolving biologic drug portfolios and corresponding container closure integrity requirements to align capacity investments with formulation pipeline shifts.
Market Dynamics
ANVISA's barrier-performance mandates for borosilicate containers are compressing supplier qualification timelines while elevating capital requirements for glass furnace upgrades across Brazil's pharmaceutical corridor.
Growth Catalysts
- mRNA cold-chain infrastructure:Vaccine fill-finish facilities in São Paulo and Mexico City are expanding borosilicate vial procurement to meet ultra-low-temperature stability requirements.
- Type II DMF alignment:COFEPRIS harmonization with FDA standards enables Mexican contract manufacturers to serve export markets without redundant container qualification cycles.
- Oncology injectable pipelines:Multinational drugmakers are scaling glass primary packaging purchases for biologic portfolios targeting Latin American therapeutic markets.
Market Restraints
- Borosilicate raw material concentration:Specialized silica and alumina sourcing concentrates among European and North American chemical suppliers, exposing Brazilian converters to currency-driven input cost volatility.
- Controlled forming equipment scarcity:Precision borosilicate molding lines require 18-24 month lead times from German and Japanese capital equipment manufacturers.
- Soda-lime substitution pressure:Oral liquid generics manufacturers in Argentina continue specifying lower-cost soda-lime bottles despite hydrolytic resistance limitations for sensitive formulations.
Strategic Opportunities
- Colombian pharmaceutical manufacturing:Bogotá's emerging vaccine production cluster lacks qualified regional glass suppliers, creating first-mover positioning for certified borosilicate converters.
- Container closure integrity convergence:Integration of elastomeric closure testing with glass forming processes enables suppliers to offer validated ready-to-use vial systems.
- ANMAT accelerated approval pathways:Argentina's streamlined biologic licensing is attracting fill-finish investment that will require Class I hydrolytic resistance packaging.
Industry Challenges
- ISO 15378 auditor scarcity:GMP certification for primary packaging materials faces backlog at accredited bodies serving Latin America, extending supplier qualification timelines.
- Legacy furnace reconfiguration:Soda-lime glass producers seeking borosilicate capability must rebuild melting infrastructure without interrupting existing oral liquid bottle contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Pharmaceutical Glass Packaging Market |
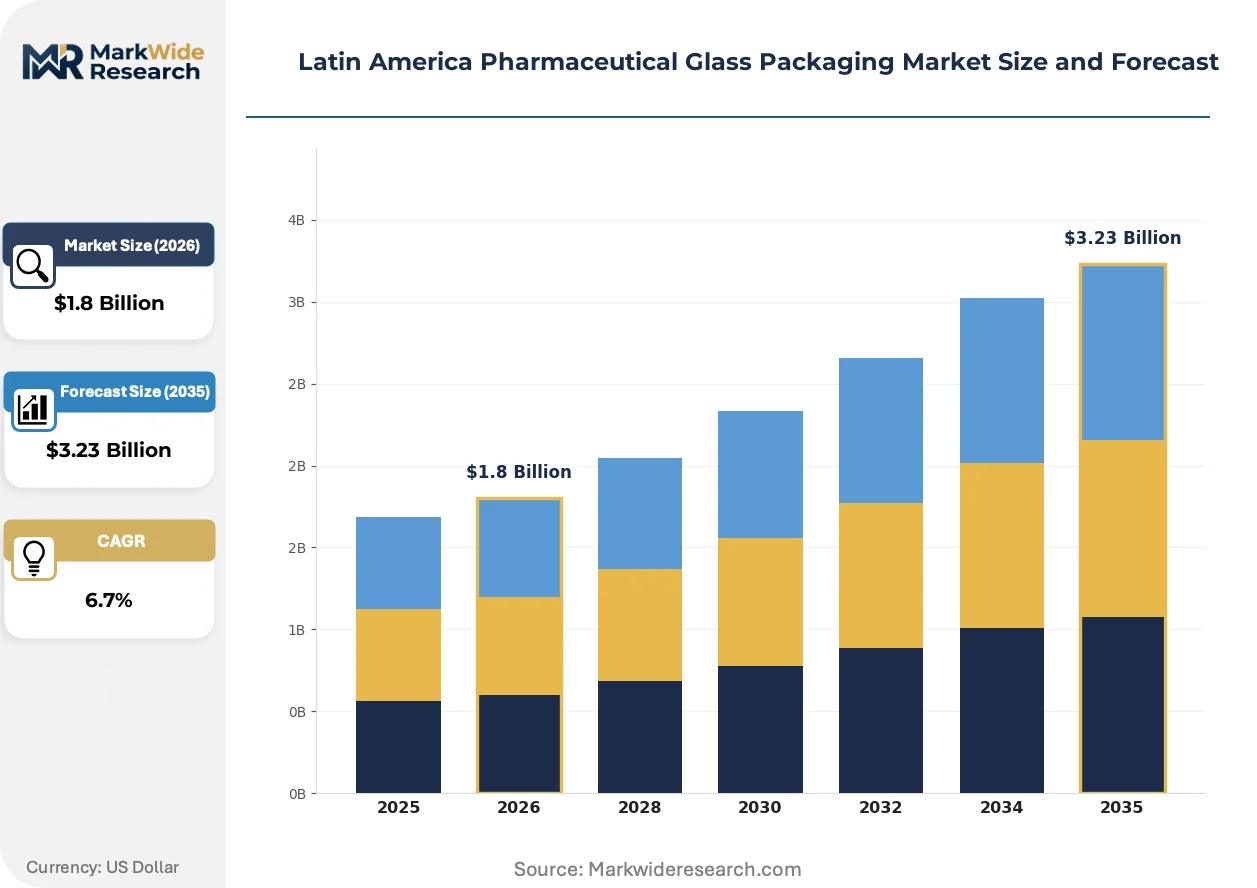
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vials, Ampoules, Bottles, Jars Packaging Type: Injectable Packaging, Solid Packaging, Liquid Packaging, Flexible Packaging End User: Pharmaceutical Companies, Contract Manufacturers, Research Laboratories, Drug Distributors Certification: CER (Conformité Européenne), ISO 9001, GMP, FDA Approval |
| Companies Covered | West Pharmaceutical Services Inc, Aptar Group Inc, Gerresheimer AG, Corning Incorporated, Becton Dickinson & Company, Vitro Glass Containers, SGD Pharma, O-I Glass Inc, SCHOTT AG, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Pharmaceutical Glass Packaging Market Trends and Innovations
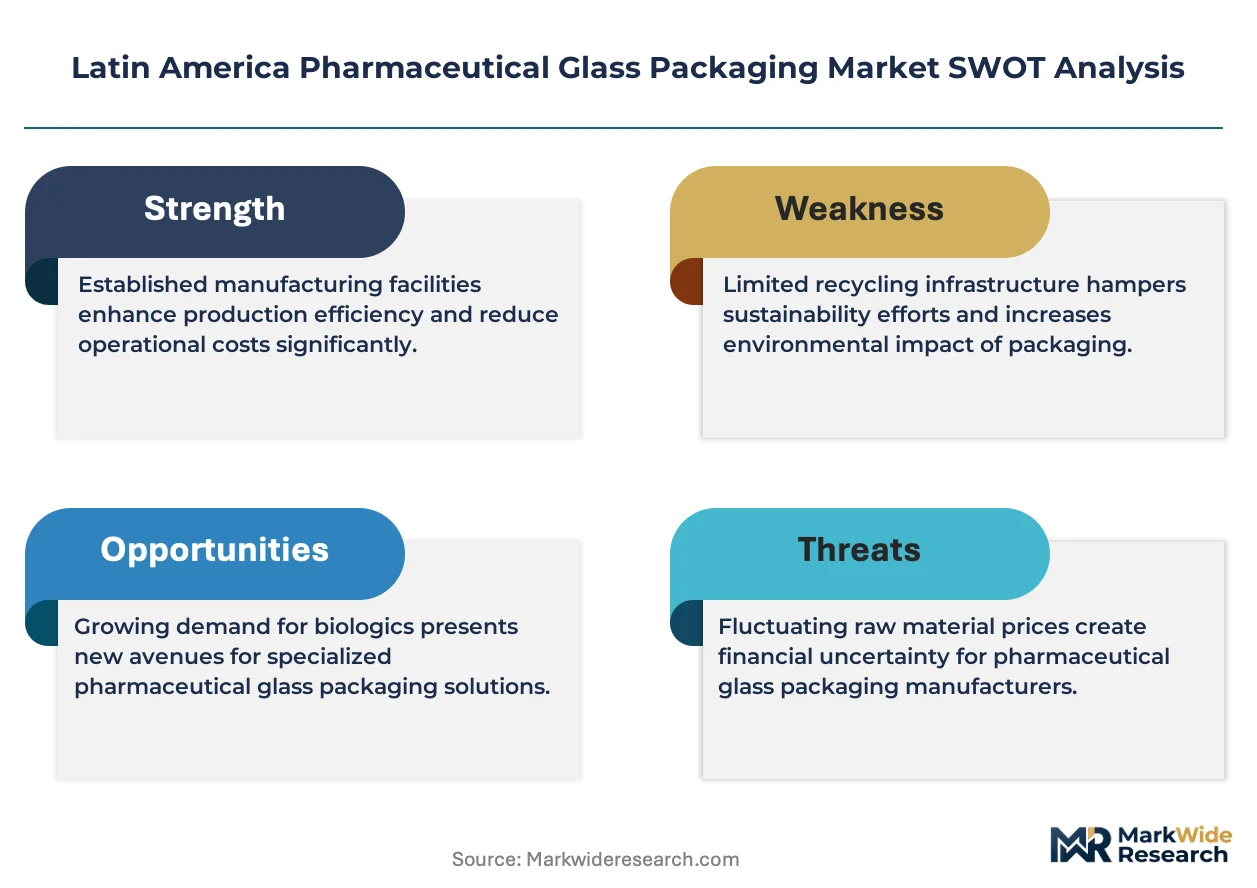
Glass packaging technology in Latin America is bifurcating between premium borosilicate systems for parenterals and cost-optimized soda-lime solutions for oral solids, with regulatory compliance becoming the primary differentiation axis.
Ready-to-use (RTU) sterilized vial systems are consolidating procurement patterns among multinational injectable manufacturers. These pre-sterilized, nested container formats eliminate depyrogenation and sterilization steps at fill-finish sites. Brazilian biologics contractors are adopting RTU formats to compress batch turnaround times. This technology is consolidating supplier relationships around integrated closure-and-container providers capable of validated sterilization and packaging.
ANVISA's updated GMP mandates for sterile pharmaceutical products are forcing container qualification protocol revisions across Brazilian manufacturing sites. The regulation now requires documented barrier-performance testing for all primary packaging materials used in parenteral applications. Domestic generic injectable producers are responding by retrofitting quality laboratories with hydrolytic resistance and thermal-shock testing equipment.
Direct sourcing from glass converters is displacing distributor-mediated procurement among large pharmaceutical manufacturers in Mexico and Brazil. Multinational drugmakers are establishing approved supplier programs that bypass regional packaging distributors. This pattern concentrates volume with furnace operators capable of direct technical service and lot-traceability documentation. The shift is most visible in São Paulo's pharmaceutical corridor, where fill-finish facilities now specify mill-direct borosilicate vial supply.
Latin America Pharmaceutical Glass Packaging Market Segmentation
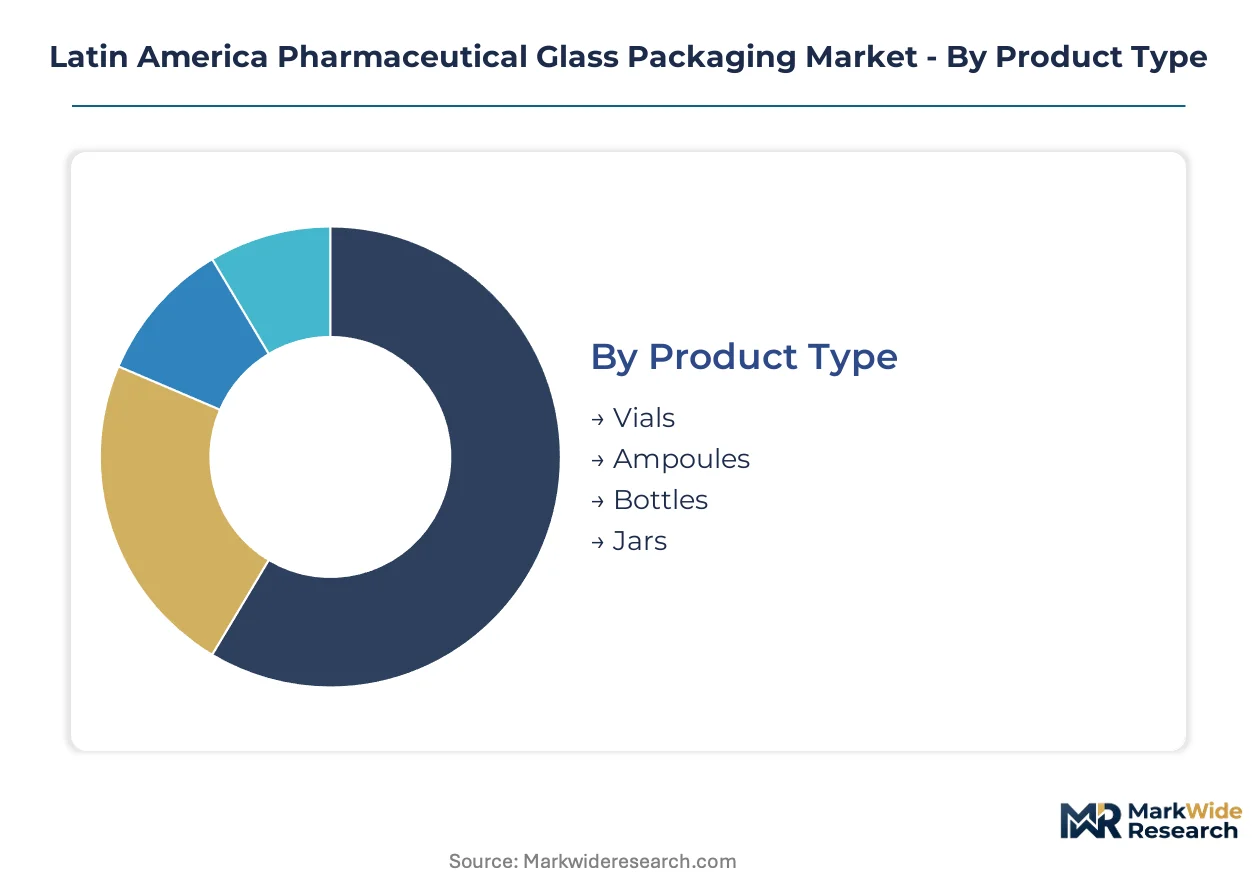
Pharmaceutical glass packaging segmentation in Latin America reflects divergent technical requirements between parenteral biologics and oral solid formulations. ANVISA's barrier-performance mandates are compressing the supplier base for certified segments while opening arbitrage opportunities in lower-specification categories.
Product Type:
Material specification drives buyer selection, with thermal expansion coefficients and hydrolytic resistance classes separating premium from commodity procurement.
- Vials:Borosilicate containers engineered to USP <660> Class I hydrolytic resistance and thermal expansion below 5.0 × 10⁻⁶ K⁻¹. São Paulo's mRNA vaccine fill-finish facilities are scaling borosilicate vial procurement for ultra-low-temperature stability requirements.
- Ampoules:Single-dose glass containers formed from Type I borosilicate or neutral soda-lime for parenteral applications. Mexican contract manufacturers are phasing ampoule procurement toward RTU-ready formats to eliminate on-site depyrogenation.
- Bottles:Soda-lime or borosilicate vessels for oral liquid and solid dosage forms. Argentina's generic pharmaceutical companies generate stable replacement demand for lower-cost soda-lime bottles despite hydrolytic limitations.
- Jars:Wide-mouth glass containers for ointments, creams, and bulk API storage. Brazilian compounding pharmacies and regional drug distributors specify amber soda-lime jars for light-sensitive topical formulations.
Vials lead on scale; ampoules lead on momentum as RTU conversion accelerates.
Packaging Type:
Application temperature requirements and sterility assurance levels determine glass grade specification and supplier qualification intensity.
- Injectable Packaging:Primary containers for parenteral drugs requiring terminal sterilization or aseptic processing. ANVISA's updated GMP mandates are elevating barrier-performance testing requirements for all Brazilian sterile injectable facilities.
- Liquid Packaging:Bottles and vials for oral and topical liquid pharmaceuticals. COFEPRIS-aligned Type II DMF standards enable Mexican manufacturers to serve export markets without redundant container qualification cycles.
- Solid Packaging:Wide-mouth bottles and jars for tablets, capsules, and powders. Colombia's emerging pharmaceutical manufacturing cluster is sourcing amber glass bottles for humidity-sensitive solid dosage forms.
- Flexible Packaging:Glass primary containers combined with elastomeric or polymeric secondary systems. Brazilian biologics contractors are adopting nested RTU vial formats to compress batch turnaround times.
Injectable packaging commands the steepest expansion trajectory; solid packaging maintains the largest installed base.
End User:
Procurement scale and technical service requirements separate direct mill relationships from distributor-mediated supply.
- Pharmaceutical Companies:Multinational drugmakers with internal fill-finish capabilities. Direct sourcing from glass converters is displacing distributor channels among large manufacturers in São Paulo's pharmaceutical corridor.
- Contract Manufacturers:Third-party fill-finish and packaging service providers. Mexico City's contract manufacturing organizations are consolidating volume with furnace operators capable of validated sterilization and lot-traceability documentation.
- Research Laboratories:Clinical trial material packaging and small-batch API containment. Argentine research institutions are qualifying borosilicate vials for ANMAT-accelerated biologic licensing pathways.
- Drug Distributors:Wholesale and retail pharmaceutical supply chain intermediaries. Regional distributors in Bogotá are sourcing amber glass bottles for repackaging and private-label oral solid distribution.
Pharmaceutical companies lead on scale; contract manufacturers lead on momentum as outsourcing expands.
Certification:
Regulatory alignment with export market requirements determines supplier qualification timelines and capital recovery horizons.
- GMP:Good Manufacturing Practice certification for primary packaging materials. ISO 15378 auditor scarcity at accredited bodies serving Latin America is extending supplier qualification timelines for Brazilian converters.
- ISO 9001:Quality management system certification functioning as a baseline qualifier. Mexican glass producers are upgrading quality infrastructure to maintain ISO 9001 alongside COFEPRIS Type II DMF alignment.
- FDA Approval:United States Food and Drug Administration facility and product registration. Brazilian borosilicate converters seeking FDA approval are rebuilding melting infrastructure to meet elevated thermal-shock specifications.
- CER (Conformité Européenne):European conformity marking for medical device packaging. Argentine exporters to Mercosur-EU trade corridors are qualifying CE-marked glass containers to bypass redundant technical barriers.
GMP certification leads on scale; FDA approval leads on momentum as export orientation intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled glass-forming technicians and pharmaceutical packaging engineers concentrate in Brazil's São Paulo corridor and Mexico's central highlands, anchoring Latin America's production capacity for borosilicate primary containers.
Brazil
mRNA vaccine cold-chain infrastructure and oncology biologics fill-finish expansion are scaling borosilicate vial procurement. ANVISA's updated GMP mandates for sterile pharmaceutical products now require documented barrier-performance testing for all parenteral packaging materials. São Paulo's pharmaceutical corridor hosts multinational drugmakers operating injectable facilities that specify mill-direct supply relationships.
Mexico
Contract manufacturing organizations serving export markets are consolidating volume with furnace operators capable of validated sterilization documentation. COFEPRIS alignment with FDA Type II DMF standards enables Mexican manufacturers to bypass redundant container qualification cycles for US-bound shipments. Mexico City's fill-finish cluster is phasing ampoule procurement toward ready-to-use formats to eliminate on-site depyrogenation steps.
Argentina
Generic pharmaceutical companies generate stable replacement demand for lower-cost soda-lime bottles despite hydrolytic resistance limitations for sensitive formulations. ANMAT's accelerated approval pathways for biologic licensing are attracting fill-finish investment requiring Class I hydrolytic resistance packaging. Buenos Aires and Córdoba host research institutions qualifying borosilicate vials for clinical trial material containment.
Colombia
Bogotá's emerging vaccine production cluster lacks qualified regional glass suppliers, creating positioning opportunities for certified borosilicate converters. The country's national pharmaceutical regulator enforces pharmacopeial compliance standards that shape glass sourcing decisions for imported active pharmaceutical ingredients. Regional drug distributors in Bogotá source amber glass bottles for repackaging and private-label oral solid distribution.
Chile
Specialty pharmaceutical importers and compounding pharmacies drive demand for amber soda-lime jars protecting light-sensitive topical formulations. Chile's national health authority maintains alignment with USP standards for primary packaging materials used in sterile applications. Santiago's pharmaceutical distribution hub concentrates procurement of imported borosilicate containers for biologic cold-chain logistics.
Latin America Pharmaceutical Glass Packaging Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Latin America's pharmaceutical glass packaging market, creating a tiered structure where technology leadership and regional logistics capabilities determine supplier selection. The vendor base clusters around three strategic archetypes: multinational borosilicate technology leaders with controlled forming expertise, regional furnace operators competing on lead times and mill-direct relationships, and integrated container-closure providers offering validated ready-to-use systems. Dominant competitive moves include backward integration into raw material sourcing to secure specialized silica supply and geographic co-location with pharmaceutical manufacturing clusters to compress logistics cycles.
Among Germany-based fabricators, Gerresheimer AG and SCHOTT AG exemplify the technology-driven tier, leveraging controlled borosilicate forming processes to meet elevated thermal-shock specifications demanded by ANVISA's barrier-performance mandates. Vitro Glass Containers represents the regional logistics archetype, with furnace operations positioned to reduce lead times to Mexican contract manufacturers. These three entities anchor distinct competitive positions without overlapping strategic emphasis, allowing each to defend margin structures through differentiated value propositions rather than direct price confrontation.
| Leading Market Players |
|---|
| West Pharmaceutical Services Inc |
| Aptar Group Inc |
| Gerresheimer AG |
| Corning Incorporated |
| Becton Dickinson & Company |
| Vitro Glass Containers |
| SGD Pharma |
| O-I Glass Inc |
| SCHOTT AG |
| Others |
Pricing and Supply Chain Analysis
ANVISA's barrier-performance mandates for sterile pharmaceutical products gate both qualified supply and premium-tier pricing access across Latin America's pharmaceutical glass packaging market. Brazilian fill-finish facilities now demand documented hydrolytic resistance testing, compressing the supplier base capable of commanding borosilicate vial premiums while exposing soda-lime converters to margin compression in oral liquid segments.
Pricing Analysis
Bundled sterilization and closure integration services command 15-25% premiums over unbundled vial-only supply in São Paulo's pharmaceutical corridor. Three-tier pricing structure across premium, standard, and economy levels separates FDA-approved borosilicate converters from ISO 9001-certified regional operators and uncertified soda-lime bottle producers. Price differentiation hinges on GMP certification tier and validated lot-traceability documentation. Cost compression in standard-tier supply is intensifying because Mexican contract manufacturers are consolidating volume with mill-direct furnace operators. Generic pharmaceutical companies in Argentina exhibit highest price sensitivity, while multinational biologics manufacturers in Brazil demonstrate lowest sensitivity due to container closure integrity requirements.
Supply Chain Analysis
Direct-to-multinational channels handle hyperscale buyer demand across São Paulo and Mexico City fill-finish clusters, while distributor-mediated supply serves mid-tier generic manufacturers. Geographic supply concentration centers on Germany and Japan for precision borosilicate forming equipment, with European and North American chemical suppliers dominating specialized silica and alumina inputs. Raw material dependencies draw from high-purity silica sand, boron oxide, and alumina for thermal-shock-resistant formulations. Single-source vulnerability in German-Japanese capital equipment creates 18-24 month reconfiguration delays for furnace upgrades. Distribution runs through validated cold-chain logistics partners for mRNA vaccine vial delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where ANVISA's GMP mandate shift toward barrier-performance documentation is repositioning procurement toward premium-certified suppliers. The demand trajectory favors converters with validated sterilization capabilities over commodity soda-lime producers.
For Market Incumbents: Lock in mill-direct relationships with São Paulo's mRNA vaccine fill-finish facilities before Colombian and Argentine biologics clusters mature. Backward integration into specialized boron oxide sourcing secures margin structure against currency-driven input volatility. Priority defensive moves include ISO 15378 auditor capacity expansion to compress qualification timelines, and furnace co-location near Mexico City's contract manufacturing organizations to eliminate cross-border logistics exposure. For New Entrants and Emerging Players: COFEPRIS alignment with FDA Type II DMF standards in Mexico opens a window for certified borosilicate converters to capture export-oriented contract manufacturing volume. Bogotá's vaccine production cluster presents the most penetrable geography given absent regional furnace capacity. Ready-to-use sterilized vial systems offer the strongest go-to-market angle, enabling first-mover positioning as integrated closure-and-container providers before incumbent retrofit completion. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap borosilicate specialists with GMP certification backlog because ANVISA's barrier-performance mandates are consolidating procurement around qualified suppliers faster than organic capacity expansion permits. Long-term viability over a 5-10 year horizon favors converters with dual Brazil-Mexico furnace footprints and validated sterilization infrastructure. Acquisition target archetype: ISO 15378-certified regional operators with unfilled capacity near emerging Colombian and Argentine pharmaceutical clusters. The signal to watch is ANMAT accelerated biologic licensing volume as inflection indicator for Class I hydrolytic resistance packaging demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Sourcing | Captive boron oxide supply insulates Brazilian converters from euro-denominated input volatility. |
| Ready-to-Use Sterilization Capability Investment | Validated nested vial formats compress batch turnaround times for São Paulo biologics contractors. |
| Geographic Co-location with Pharmaceutical Clusters | Furnace positioning near Mexico City eliminates cross-border lead times for COFEPRIS-aligned exporters. |
| ISO 15378 Certification Expansion | GMP auditor capacity buildup reduces supplier qualification timelines amid accredited body scarcity. |
| Container Closure Integration Development | Elastomeric closure testing convergence enables validated system offerings to multinational drugmakers. |
Research Methodology
Coverage spans Brazil, Mexico, Argentina, Colombia, and Chile, with primary inputs from each market's pharmaceutical manufacturing corridor. Primary interviews with fill-finish operations directors, regulatory affairs managers at ANVISA and COFEPRIS, glass converter plant managers, and procurement leads at multinational drugmakers combined with secondary validation from FDA Type II DMF filings, ANVISA GMP inspection records, pharmaceutical trade customs data, and ISO certification registries. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Granularity-level framing applied country-level regulatory cluster differentiation alongside product-type segmentation and end-user procurement scale tiers. Analytical framework modeled value expansion across the projection horizon through treatment line prioritization, dosage form thermal requirements, administration route sterility assurance levels, and regional regulatory alignment patterns. CAGRs derived from pharmaceutical pipeline tracking and container qualification cycle analysis, with mRNA cold-chain infrastructure buildout and oncology biologics portfolio scaling as key forecast inputs.
Revisions become necessary when ANVISA barrier-performance mandate enforcement intensity shifts, COFEPRIS-FDA alignment protocols change, or Colombian vaccine production cluster investment accelerates beyond current trajectories. Forecasts reflect documented assumptions regarding regulatory timeline adherence and capital equipment delivery schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Europe Pharmaceutical Vials Market
Pharmaceutical Equipment
Global Pharmaceutical Contract Manufacturing and Contract Research Market
Pharmaceutical Equipment
Global Pharmacy Automation Systems Market
Pharmaceutical Equipment
Pharmaceutical Track and Trace Systems Market
Pharmaceutical Equipment
Pharmaceutical Automation Market
Pharmaceutical Equipment
Pharmaceutical Stability and Storage Services Market
Pharmaceutical Equipment
Flip Top Vials Market
Pharmaceutical Equipment
Lyophilization Equipment Market
Pharmaceutical Equipment
Closed Funnel Ampoules Market
Pharmaceutical Equipment
North America Pharmacy Automation Market
Pharmaceutical Equipment
China Pharmaceutical Warehousing Market
Pharmaceutical Equipment
Tablet Press Market
Pharmaceutical Equipment
Asia-Pacific CDMO Market
Pharmaceutical Equipment
Medication Dispenser Market
Pharmaceutical Equipment
Japan Contract Development and Manufacturing Organization Market
Pharmaceutical Equipment
Radiopharmaceutical Synthesizer Market