
 Europe Pharmaceutical Glass Vials and Ampoules Market | 2026-2036
Europe Pharmaceutical Glass Vials and Ampoules Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pharmaceutical Glass Vials and Ampoules Market Insights
CE marking under the EU MDR is reorganizing competitive access across the Europe pharmaceutical glass vials and ampoules landscape. Gerresheimer AG leverages its integrated borosilicate production network to control supply continuity for high-value biologics. SGD S.A. anchors French manufacturing capacity while competing on specialty ampoule geometries for injectable therapies. Bormioli Pharma S.p.A. specializes in multi-chamber vial designs that differentiate its portfolio for complex drug-delivery applications.
Europe pharmaceutical glass vials and ampoules constitute chemically resistant containers fabricated from borosilicate or soda-lime glass, engineered to meet pharmacopeial standards for hydrolytic resistance and thermal shock tolerance, serving as primary packaging for sterile injectable and biologic formulations. Type I borosilicate glass dominates margin pools due to its inertness with parenteral solutions, while pre-filled syringes represent the fastest-growing product configuration as pharmaceutical companies seek to reduce medication errors and accelerate administration workflows. Type III glass occupies the economy tier for non-reactive oral and topical preparations where regulatory stringency permits lower chemical durability.
EMA pharmacopeial standards, EU MDR device classification rules, and REACH chemical compliance obligations collectively shape material selection, supplier qualification timelines, and documentation burdens across the value chain. The F-Gas Regulation indirectly pressures manufacturers to decarbonize melting furnaces, adding capital intensity to capacity expansion decisions. Stakeholders must monitor how the EU AI Act's quality-system requirements will interact with automated visual inspection protocols for defect detection.
Market Dynamics
EU MDR device classification rules are reorganizing supplier qualification timelines across European pharmaceutical glass packaging networks, forcing manufacturers to rebuild documentation systems and accelerate material traceability investments.
Growth Catalysts
- Biologics pipeline expansion:European biotech firms are scaling sterile injectable production for monoclonal antibodies and cell therapies, creating sustained pull for Type I borosilicate vials with demonstrated hydrolytic resistance.
- F-Gas Regulation furnace upgrades:The EU's fluorinated gas phase-down is compelling glass manufacturers to install electric melting capacity, indirectly improving batch consistency and reducing particulate contamination risks.
- Heidelberg-Ludwigshafen cluster concentration:Germany's pharmaceutical manufacturing corridor generates dense demand for just-in-time vial supply, rewarding regional production footprints with logistics cost advantages.
Market Restraints
- Borosilicate raw material concentration:Specialty glass-grade sand and boron supply chains concentrate among limited European chemical suppliers, exposing converters to input cost volatility and force majeure risks.
- REACH chemical compliance burdens:ECHA substance registration requirements extend documentation obligations to trace additives and surface treatments, lengthening new product qualification cycles by 12-18 months.
- Pre-filled syringe substitution:Pharmaceutical companies are redirecting sterile injectable volumes toward polymer-based pre-filled syringe formats for certain therapeutic categories, compressing addressable glass vial demand in outpatient administration settings.
Strategic Opportunities
- Multi-chamber vial designs:Complex drug-delivery applications requiring lyophilized powder and diluent separation present white space for differentiated container geometries serving European biologics formulators.
- Polish and Czech manufacturing expansion:Central European locations offer lower energy costs and skilled labor pools for secondary processing operations, enabling cost-competitive supply to Western European pharmaceutical clusters.
- EU AI Act quality system integration:Automated visual inspection systems that satisfy forthcoming AI-driven quality assurance mandates will qualify suppliers for premium-tier vendor status with EMA-regulated drug manufacturers.
Industry Challenges
- Specialized furnace engineering talent:Electric melting technology migration requires scarce expertise in oxy-fuel combustion replacement and thermal process control, constraining capacity expansion timelines.
- EU MDR technical documentation assembly:CE marking dossiers for pharmaceutical container devices demand extensive biocompatibility and clinical evidence, creating compliance backlogs for mid-scale converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pharmaceutical Glass Vials and Ampoules Market |
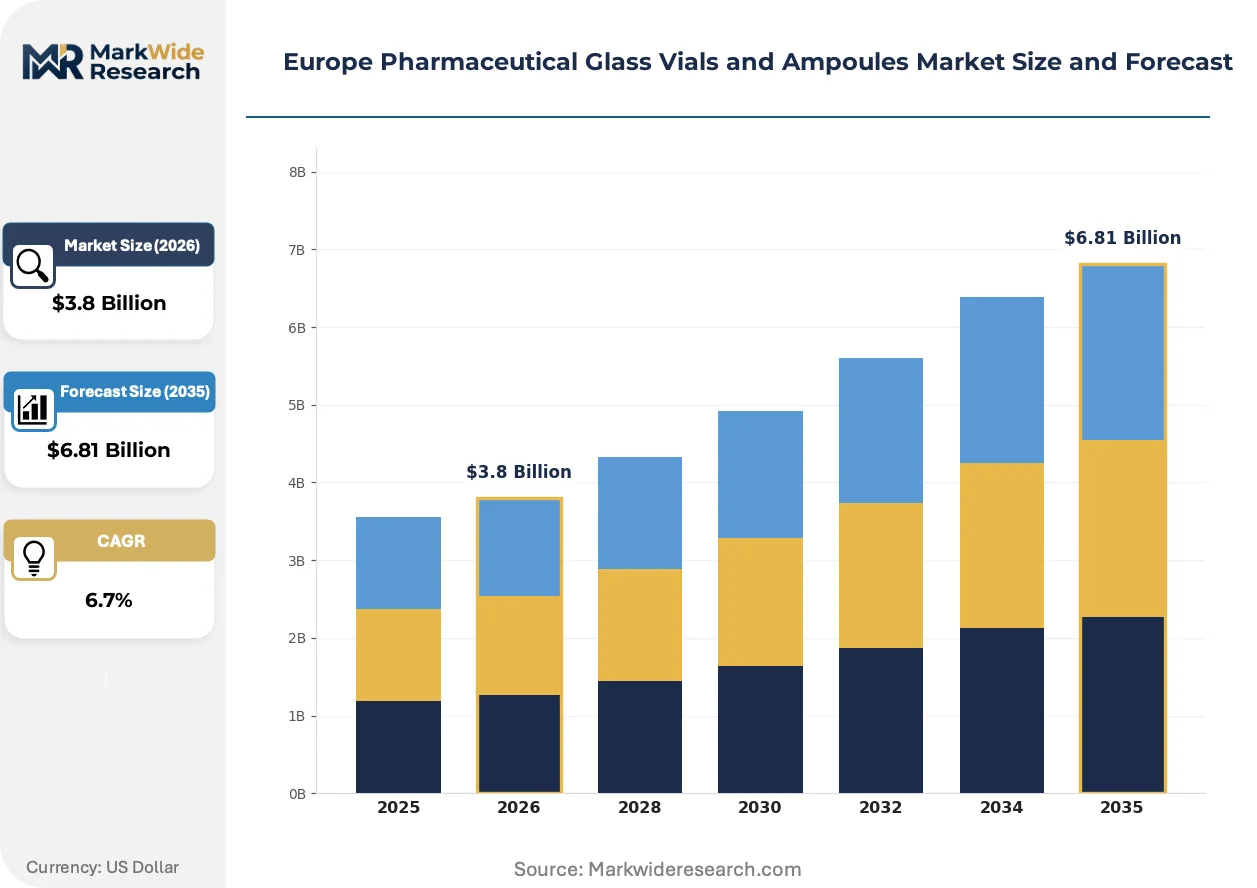
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vials, Ampoules, Cartridges, Pre-filled Syringes Material: Type I Glass, Type II Glass, Type III Glass, Borosilicate Capacity: 1 ml, 5 ml, 10 ml, 20 ml End User: Hospitals, Clinics, Biotech Firms, Pharmaceutical Companies |
| Companies Covered | SGD S.A., Bormioli Pharma S.p.A., Gerresheimer AG, Soffieria Bertolini S.p.A., NAFVSM B.V., Stevanato Group, DWK Life Sciences, Origin Pharma Packaging, Scott Pharma (Scott AG), Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pharmaceutical Glass Vials and Ampoules Market Trends and Innovations
European pharmaceutical glass packaging is undergoing material and process transformation as regulatory stringency intersects with biologics manufacturing complexity. Three developments are restructuring competitive positioning.
Ready-to-use (RTU) sterilized vial formats are displacing conventional bulk-supply arrangements across European fill-finish operations. Contract manufacturing organizations in Germany and Switzerland are adopting RTU configurations to eliminate in-house washing and depyrogenation steps. This shift is compressing equipment capital requirements for drug sponsors while elevating supplier quality system burdens.
REACH authorization procedures for boron compounds are tightening raw material sourcing constraints across European glass melting operations. ECHA's sunset date scheduling for certain boron substance categories is forcing converters to qualify alternative glass compositions or secure supply continuity agreements. Specialty ampoule manufacturers serving parenteral oncology applications face the most acute reformulation timelines.
Consolidated procurement by European Big Pharma is displacing fragmented purchasing patterns across the vial supply base. Sanofi, Roche, and Novo Nordisk are centralizing container sourcing through preferred supplier frameworks with multi-year volume commitments. This concentration is visible most acutely in Denmark and France, where single-source negotiations now govern 60-70% of annual vial requirements for major biologics facilities.
Europe Pharmaceutical Glass Vials and Ampoules Market Segmentation
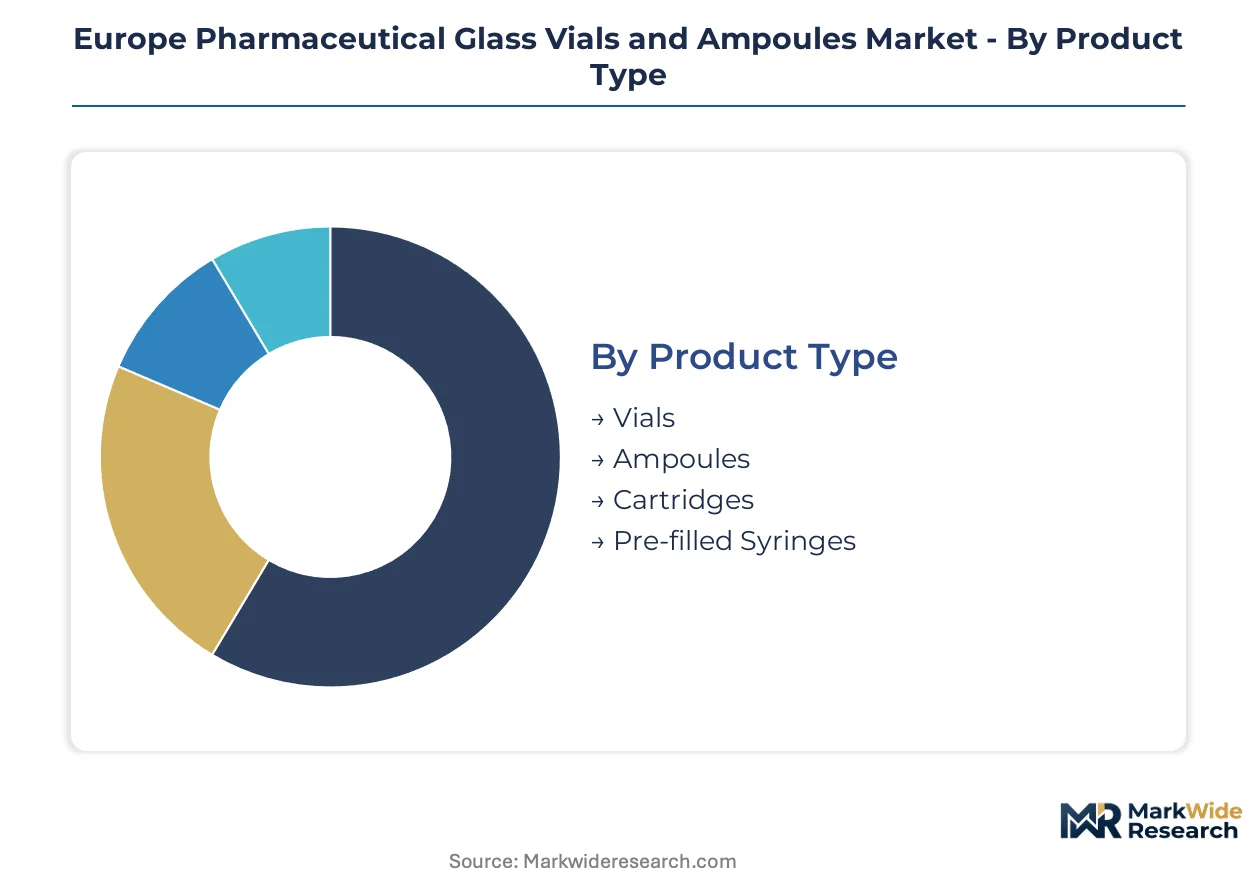
Pharmaceutical glass packaging procurement in Europe fragments across material chemistry, container geometry, and end-use workflow requirements. Each segmentation axis carries distinct margin implications and regulatory qualification burdens that reshape supplier-customer contracting terms.
Product Type:
Vials dominate margin pools through their indispensability for biologics storage, while pre-filled syringes command premium positioning through workflow integration value.
- Vials:Cylindrical containers with crimp or screw closures engineered for parenteral drug stability across freeze-thaw cycles. Heidelberg-Ludwigshafen pharmaceutical clusters generate dense demand for 2R-10R ISO formats serving monoclonal antibody fill-finish operations.
- Ampoules:Single-dose glass containers with scored necks for snap-open administration, specified for emergency injectables and anesthetic agents. French oncology formulators concentrate pull for Type I borosilicate ampoules with reduced particle shedding profiles.
- Cartridges:Pen-injector compatible cylinders with elastomeric piston seals, serving diabetes and growth hormone delivery systems.
- Pre-filled Syringes:Sterile drug-device combination products integrating plunger-rod systems for immediate administration.
Vials hold installed capacity. Pre-filled syringes are rotating up the share rankings.
Material:
Type I borosilicate glass captures value concentration through EMA pharmacopeial requirements for hydrolytic resistance, while Type III serves cost-sensitive oral applications.
- Type I Glass:Borosilicate composition with low alkali extraction, mandatory for parenteral and ophthalmic preparations per European Pharmacopoeia 3.2.1. REACH authorization pressures on boron compounds are forcing converters to secure supply continuity agreements with specialty chemical suppliers.
- Type II Glass:Soda-lime glass with surface dealkalization treatment, occupying the mid-tier for less sensitive injectable applications. German generic injectables manufacturers specify Type II for multi-dose vial formats where cost containment outweighs maximum chemical inertness.
- Type III Glass:Standard soda-lime composition for oral solid and liquid preparations where hydrolytic resistance requirements permit lower durability specifications.
- Borosilicate:Premium-grade material with thermal shock tolerance for lyophilization cycles and autoclave sterilization protocols.
Type I glass holds installed capacity. Pre-filled syringe demand is rotating up the share rankings.
Capacity:
10 ml formats concentrate revenue through their ubiquity in biologics dosing, while 1 ml vials expand through precision medicine applications.
- 1 ml:Micro-volume containers for potent biologics, pediatric formulations, and ophthalmic injections. Swiss contract manufacturing organizations specify 1 ml ISO 13926-2 formats for high-concentration monoclonal antibody presentations requiring precise dosing control.
- 5 ml:Standard intermediate volume for antibiotic and vaccine presentations across European hospital networks.
- 10 ml:Workhorse capacity for multi-dose biologics and infusion preparations, dominating fill-finish line configurations.
- 20 ml:Large-format containers for diluents, contrast media, and bulk API storage in compounding pharmacy settings.
10 ml holds installed capacity. 1 ml formats are rotating up the share rankings.
End User:
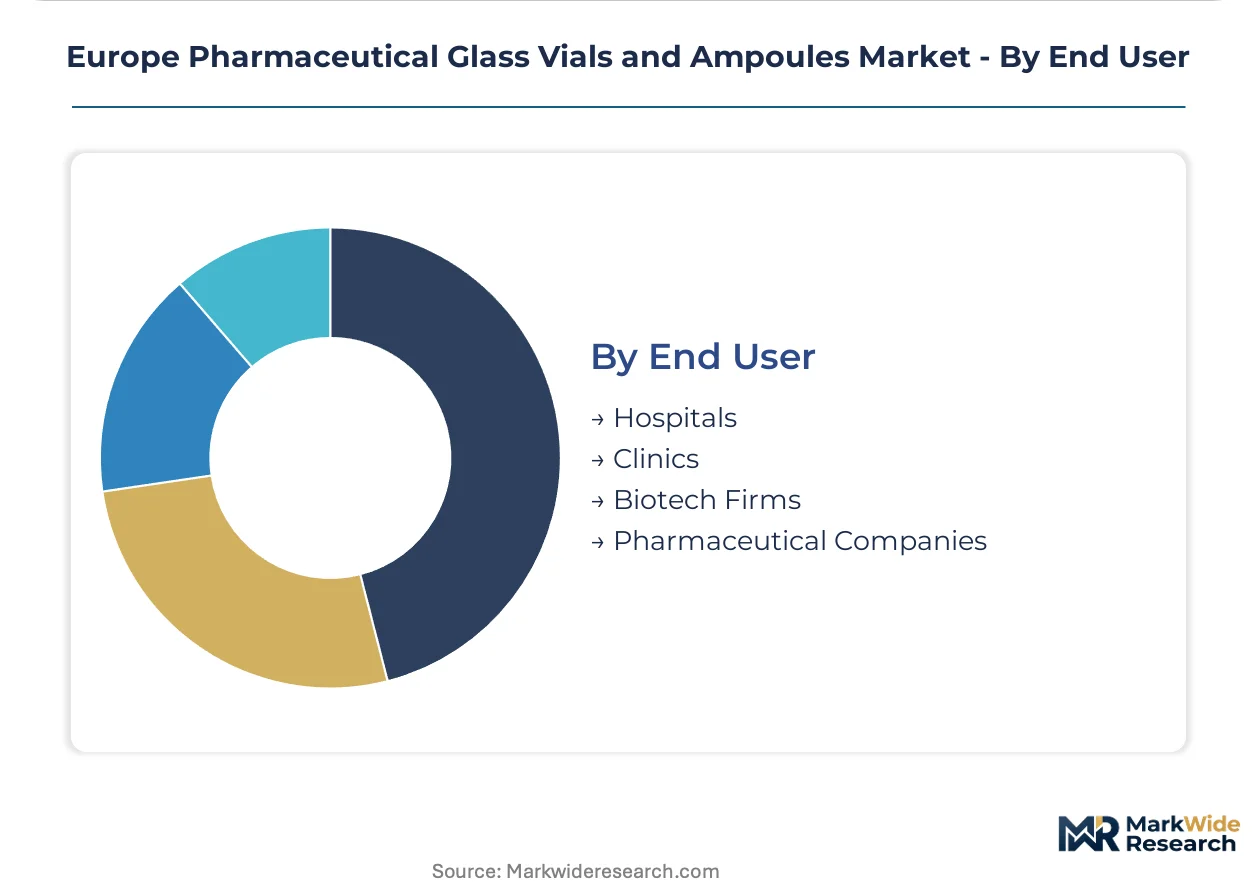
Pharmaceutical companies command pricing power through consolidated procurement frameworks, while biotech firms drive specification innovation for novel modalities.
- Pharmaceutical Companies:Integrated drug manufacturers with centralized container sourcing through multi-year preferred supplier agreements. Roche, Novo Nordisk, and Sanofi procurement teams negotiate EMA-compliant supply frameworks covering 60-70% of annual European vial requirements.
- Biotech Firms:Emerging therapy developers scaling cell and gene therapy manufacturing. Heidelberg and Basel clusters generate concentrated demand for ready-to-use sterile vial formats that compress in-house processing timelines.
- Hospitals:Institutional purchasers of generic injectables and emergency medications through regional procurement consortia.
- Clinics:Outpatient settings sourcing pre-filled formats for specialty therapeutic administration.
Pharmaceutical companies hold installed capacity. Biotech firms are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU MDR and EMA quality guidelines are reorganizing manufacturing footprints across European pharmaceutical glass packaging networks, with CE marking requirements accelerating facility upgrades in major production corridors.
Germany
Heidelberg-Ludwigshafen pharmaceutical clusters generate dense demand for Type I borosilicate vials serving monoclonal antibody fill-finish operations. The F-Gas Regulation compels furnace electrification at glass melting facilities, improving batch consistency for high-value biologics. Baden-Württemberg converters specialize in ready-to-use sterile formats that eliminate in-house depyrogenation for regional contract manufacturers.
France
Paris-region oncology formulators concentrate pull for reduced-particle ampoule geometries in parenteral chemotherapy applications. ANSM pharmacovigilance requirements extend documentation obligations to surface treatment traceability, lengthening supplier qualification cycles. Lyon-based glass converters anchor specialty capacity for emergency injectables serving hospital networks across the Rhône corridor.
Italy
Lombardy pharmaceutical manufacturers specify multi-chamber vial designs for lyophilized powder and diluent separation in complex drug-delivery applications. REACH authorization pressures on boron compounds force converters to secure supply continuity agreements with ECHA-registered chemical suppliers. Piacenza-area fabricators differentiate on molded glass precision for high-viscosity biologic formulations.
Switzerland
Basel biotech clusters drive specification innovation for cell therapy manufacturing containers with demonstrated thermal shock tolerance. Swissmedic device classification rules align with EU MDR frameworks, streamlining cross-border supplier qualifications for German and French drug sponsors. Zürich contract manufacturing organizations adopt ISO-standard vial formats to compress fill-finish validation timelines.
Poland
Lower energy costs and skilled labor pools attract secondary processing investments from Western European glass packaging networks. Polish converters supply value-added vial treatments to Heidelberg and Basel pharmaceutical clusters through just-in-time logistics arrangements. Warsaw-region facilities specialize in washing and sterilization services that reduce capital burdens for mid-scale biotech sponsors.
Europe Pharmaceutical Glass Vials and Ampoules Market Competitive Landscape
Listed leaders compete with private specialists across capital access and strategic flexibility dimensions. The supplier base organizes around three tiers: integrated borosilicate producers controlling upstream material flows, regional converters competing on geometry specialization, and service-oriented fabricators emphasizing sterilization and logistics integration. Consolidated procurement by European Big Pharma is compressing vendor counts, while electric furnace technology migration favors players with captive engineering expertise.
Among Germany-based AG-structured manufacturers, Gerresheimer AG occupies a position exemplifying integrated production network control. French S.A.-incorporated specialists include SGD S.A., which represents the regional geometry-specialist archetype. Italy-based S.p.A. entities such as Bormioli Pharma S.p.A. anchor the multi-chamber design differentiation vector. These three corporate forms illustrate how legal structure correlates with strategic positioning across CE marking compliance, REACH documentation depth, and EMA pharmacopeial alignment.
| Leading Market Players |
|---|
| SGD S.A. |
| Bormioli Pharma S.p.A. |
| Gerresheimer AG |
| Soffieria Bertolini S.p.A. |
| NAFVSM B.V. |
| Stevanato Group |
| DWK Life Sciences |
| Origin Pharma Packaging |
| Scott Pharma (Scott AG) |
| Others |
Pricing and Supply Chain Analysis
CE marking under the EU MDR gates both supplier qualification timelines and price differentiation tiers across European pharmaceutical glass packaging networks, forcing converters to absorb documentation costs that separate premium-certified from standard-grade offerings.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers across the European market. Three-tier pricing structure across premium, standard, and economy levels reflects EMA pharmacopeial alignment, with Type I borosilicate commanding the top tier for parenteral applications. Cost compression in the economy tier intensifies as pharmaceutical companies consolidate procurement through preferred supplier frameworks. Biotech firms exhibit the least price sensitivity, prioritizing supply continuity and documentation depth over unit cost.
Supply Chain Analysis
Germany and Italy anchor primary glass melting capacity for pharmaceutical-grade borosilicate across Europe. Specialty glass-grade sand and boron compounds draw from concentrated European chemical suppliers, creating single-source vulnerability for converters. REACH authorization procedures on boron substances present regulatory restriction risk extending qualification timelines. Distribution runs through just-in-time logistics arrangements serving Heidelberg-Ludwigshafen and Basel pharmaceutical clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric furnace engineering expertise represents the critical capability gap constraining capacity expansion timelines across European pharmaceutical glass packaging networks, with technology migration outpacing available thermal process control talent.
For Market Incumbents: Compound defensive positioning through backward integration into borosilicate raw material sourcing and accelerated CE marking dossier assembly. Pre-filled syringe substitution from polymer formats threatens glass vial volumes in outpatient settings. Captive electric melting technology development secures capacity expansion timelines against scarce engineering talent pools. For New Entrants and Emerging Players: Ready-to-use sterile vial washing and depyrogenation services represent the most penetrable service-layer gap where incumbents under-serve mid-scale biotech sponsors. Polish and Czech secondary processing locations offer the most accessible geographic entry point. Target contract manufacturing organizations in Basel and Heidelberg with just-in-time logistics integration as the primary go-to-market angle. For Investors and Strategic Acquirers: EU AI Act quality system requirements reshape the acquisition landscape toward automated visual inspection capabilities that satisfy forthcoming AI-driven defect detection mandates. Long-term viability centers on suppliers with demonstrated EMA pharmacopeial alignment and electric furnace technology migration progress. Watch for CE marking compliance backlogs at mid-scale converters as the signal indicating distressed acquisition opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Furnace Technology Migration | F-Gas Regulation compliance secures melting capacity continuity for EMA-regulated biologics supply. |
| Multi-Chamber Vial Design Development | Complex drug-delivery geometries differentiate portfolios for European lyophilized powder formulators. |
| REACH Authorization Continuity Agreements | Boron compound supply security protects Type I glass margin pools against ECHA sunset scheduling. |
| Ready-to-Use Sterile Format Expansion | RTU configurations eliminate depyrogenation capital burdens for Heidelberg contract manufacturers. |
| Automated Visual Inspection Integration | AI-driven quality systems qualify suppliers for premium-tier vendor status with EMA-regulated drug sponsors. |
Research Methodology
The analysis maps Type I borosilicate vials, Type II treated glass, Type III soda-lime formats, and pre-filled syringe configurations, each validated through plant managers at melting facilities, procurement leads at German pharmaceutical manufacturers, regulatory affairs specialists navigating EU MDR compliance, and EMA quality auditors. Primary interview findings triangulate against EMA submission databases, REACH substance registration records, F-Gas Regulation implementation reports, and European Pharmacopoeia hydrolytic resistance standards. Bottom-up volume builds from facility-level capacity assessments reconcile with top-down demand projections from biologics pipeline tracking.
Consistency checks validate volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include material chemistry grade, container geometry, capacity specification, and end-user procurement archetype. CAGRs derive from compound growth trajectory analysis incorporating biologics manufacturing expansion rates, electric furnace conversion timelines, and regulatory qualification cycle extensions. Industry-specific forecast inputs include EMA pharmacopeial revision schedules and EU MDR device classification implementation progress.
Forecasts assume regulatory continuity in EU MDR, REACH, and F-Gas frameworks; material policy shifts would require re-modeling supply qualification timelines and furnace technology migration assumptions. Specific risks that could revise projections include accelerated ECHA boron substance sunset scheduling, faster-than-anticipated pre-filled syringe substitution rates, and electric furnace engineering talent shortages extending capacity expansion delays. Recalibration cycles align with material shifts in EMA guideline revisions and EU AI Act quality system implementation milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
China Pharmaceutical Warehousing Market
Pharmaceutical Equipment
Pharmaceutical Manufacturing Market
Pharmaceutical Equipment
Aseptic Negative Pressure Pharmaceutical Isolators Market
Pharmaceutical Equipment
North America and Europe Pharmaceutical Stability & Storage Services Market
Pharmaceutical Equipment
Sterile Fill-Finish Process Simulation and Media Fill Test Equipment Market
Pharmaceutical Equipment
Pharmaceutical CDMO Market
Pharmaceutical Equipment
Europe Formulation Development Outsourcing Market
Pharmaceutical Equipment
Flip Top Vials Market
Pharmaceutical Equipment
Middle East and Africa Pharmacy Automation Market
Pharmaceutical Equipment
Global Pharmacy Automation Systems Market
Pharmaceutical Equipment
North America Unit Dose Manufacturing Market
Pharmaceutical Equipment
Pharmaceutical Anti-Counterfeiting Technologies Market
Pharmaceutical Equipment
Europe Pharmaceutical Isolator Market
Pharmaceutical Equipment
Drug Infusion System Market
Pharmaceutical Equipment
Malaysia Pharmacy Automation Market
Pharmaceutical Equipment
Pharmaceutical Stability and Storage Services Market