
 Europe Formulation Development Outsourcing Market | 2026-2036
Europe Formulation Development Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Formulation Development Outsourcing Market Insights
Switzerland is reshaping competitive dynamics in European formulation outsourcing through Lonza Group's biologics-focused capacity expansions and Evonik's lipid nanoparticle specialization. Catalent Inc leverages integrated clinical-to-commercial pathways across multiple European sites. Recipharm AB anchors Nordic and Continental European demand with its multi-technology manufacturing network.
Formulation development outsourcing encompasses the systematic design, optimization, and characterization of drug delivery systems including solubility enhancement, excipient selection, and process scale-up from laboratory to commercial batch sizes. Pre-formulation services and analytical testing together constitute the largest service revenue pools, while nanotechnology and liposomal formulation represent the fastest-expanding technology segments driven by biologic and nucleic acid therapeutic pipelines. Pharmaceutical companies dominate end-user demand, though biotechnology firms represent the most rapidly growing sponsor category as virtual development models proliferate across Europe.
The European Medicines Agency's quality guidelines, REACH chemical safety frameworks, and the EU Good Manufacturing Practice directives collectively elevate compliance burdens that favor established outsourcing partners with dedicated regulatory affairs capabilities. Switzerland's Swissmedic and the United Kingdom's Medicines and Healthcare products Regulatory Agency maintain distinct post-Brexit pathways, fragmenting submission strategies for pan-European programs. Stakeholders must evaluate whether to consolidate outsourcing relationships with multi-jurisdictional providers or segment regulatory packages across specialized national partners.
Market Dynamics
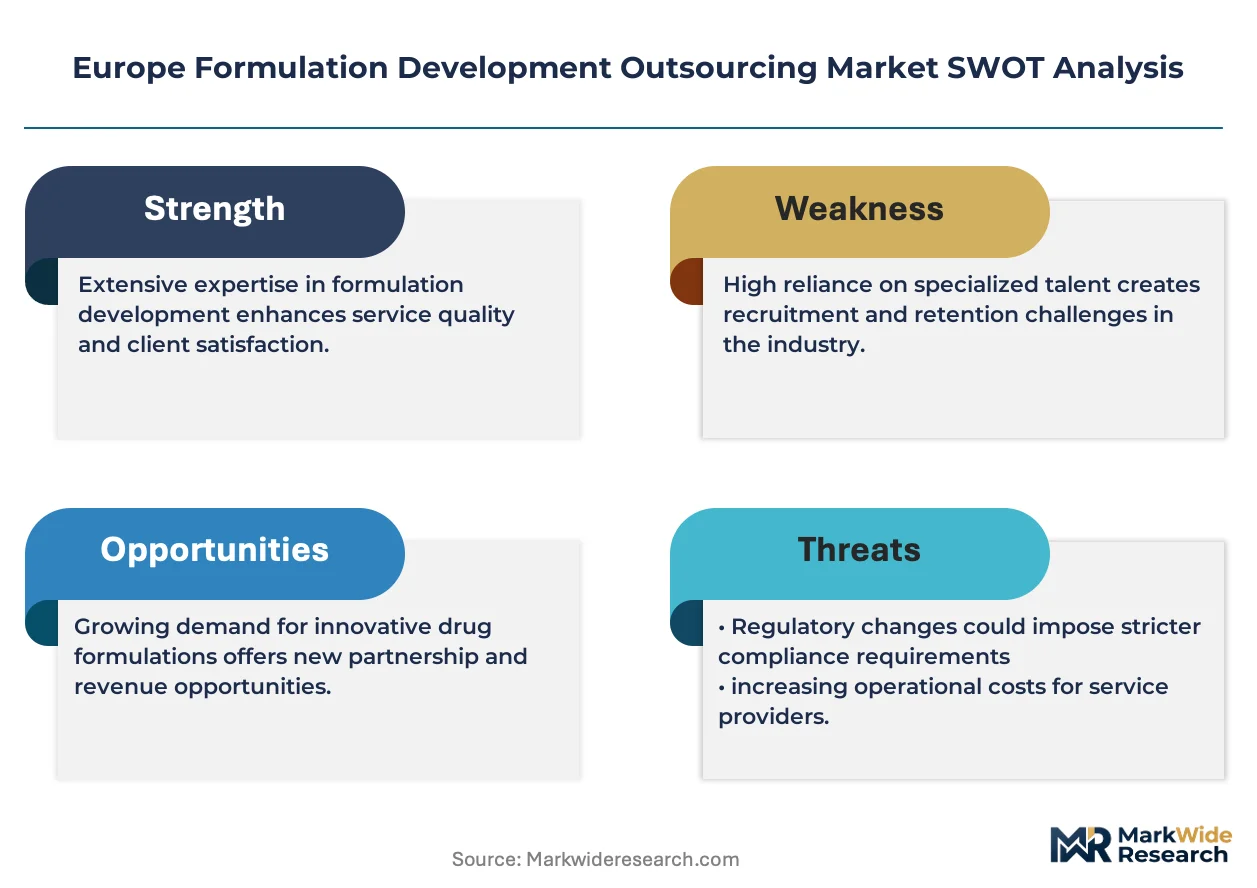
Complex biologic and nucleic acid therapeutics are fragmenting formulation expertise across specialized CDMOs, as EMA quality guidelines and REACH compliance requirements exceed in-house capabilities at mid-sized pharmaceutical sponsors.
Growth Catalysts
- REACH chemical safety frameworks:Stringent substance registration requirements are redirecting toxicology and excipient qualification work toward contract partners with dedicated regulatory affairs teams.
- Lipid nanoparticle delivery systems:mRNA and gene therapy pipelines are expanding demand for specialized nanotechnology formulation capabilities concentrated in Swiss and German CDMO clusters.
- Virtual biotechnology firms:Asset-light development models across France and the Netherlands are eliminating captive formulation infrastructure in favor of outsourced pre-formulation and stability testing services.
Market Restraints
- High-purity excipient supply concentration:Specialized lipid and polymer inputs for complex formulations depend on a limited supplier base concentrated in Switzerland and Germany.
- EU Medical Device Regulation convergence:Drug-device combination products face dual compliance pathways that extend qualification timelines and raise outsourcing qualification costs.
- Analytical equipment capex intensity:Advanced characterization tools for biologics stability testing require substantial capital commitment, limiting mid-tier CDMO expansion.
Strategic Opportunities
- United Kingdom post-Brexit regulatory autonomy:MHRA's independent marketing authorization pathway is creating demand for UK-based formulation partners serving pan-European submission strategies.
- Continuous manufacturing technology:Integration of process analytical technology with traditional batch formulation is enabling real-time release testing and reduced scale-up risk.
- EU Green Deal solvent reduction mandates:Regulatory pressure to eliminate chlorinated solvents is accelerating adoption of supercritical fluid and aqueous-based formulation platforms.
Industry Challenges
- Formulation scientist talent scarcity:Specialized expertise in amorphous solid dispersion and hot-melt extrusion is concentrated among senior practitioners approaching retirement in Germany and Switzerland.
- Technology transfer complexity:Moving projects between discovery-phase biotech sponsors and commercial-scale CDMOs generates reproducibility failures and timeline overruns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Formulation Development Outsourcing Market |
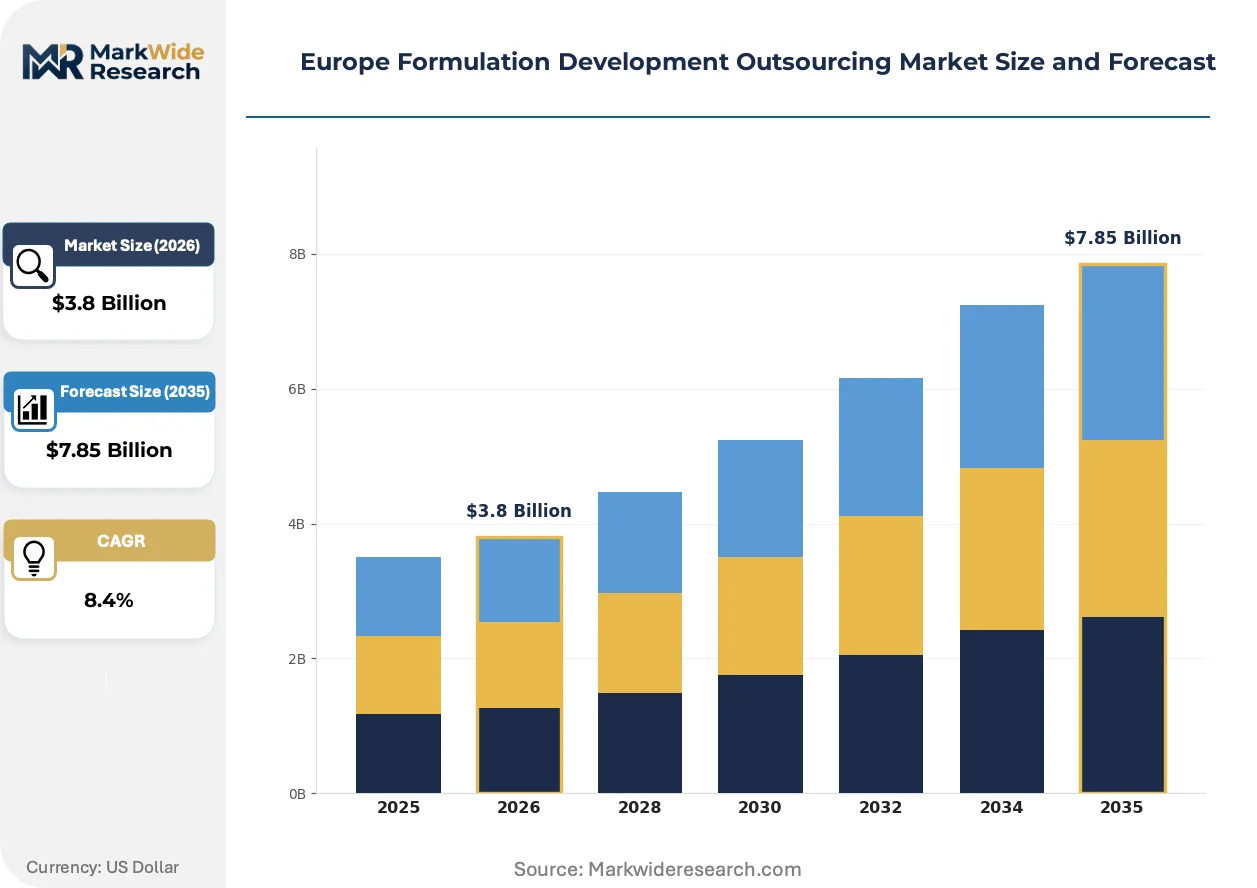
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Pre-formulation, Formulation Development, Analytical Testing, Stability Studies End User: Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations, Academic Institutions Form: Liquid, Solid, Semi-solid, Powder Technology: Nanotechnology, Microencapsulation, Liposomal Formulation, Drug Delivery Systems |
| Companies Covered | Lonza Group, Catalent Inc, Recipharm AB, Evonik, Aenova Group, Fareva Holding SA, Boehringer Ingelheim Group, Intertek Group plc, SGS S.A., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Formulation Development Outsourcing Market Trends and Innovations
Digital integration of formulation workflows with real-time analytical feedback is compressing development timelines and reshaping sponsor-CDMO collaboration models across European development hubs.
Artificial intelligence platforms for excipient selection and solubility prediction are digitizing traditional trial-and-error approaches in pre-formulation. Mid-sized pharmaceutical sponsors in France and the Netherlands are adopting these tools at accelerating pace. The technology is digitizing compoundability assessment, reducing API consumption during early-stage screening by an order of magnitude.
EMA's revised quality guidelines on nitrosamine impurities are forcing reformulation of established oral solid dosage forms across the European portfolio. The industrial consequence is a wave of retrospective risk assessments and specification tightening for contract manufacturers. High-volume generic producers in Spain and Italy are responding by consolidating analytical testing with formulation partners possessing dedicated contamination control capabilities.
Biotechnology sponsors are unbundling integrated development contracts into discrete phase-gated engagements with multiple specialized providers. Virtual development models are displacing single-CDMO relationships in favor of best-of-breed segmentation across pre-formulation, clinical manufacturing, and commercial supply. This pattern is most visible among UK and Swedish gene therapy developers optimizing capital efficiency through milestone-based outsourcing structures.
Europe Formulation Development Outsourcing Market Segmentation
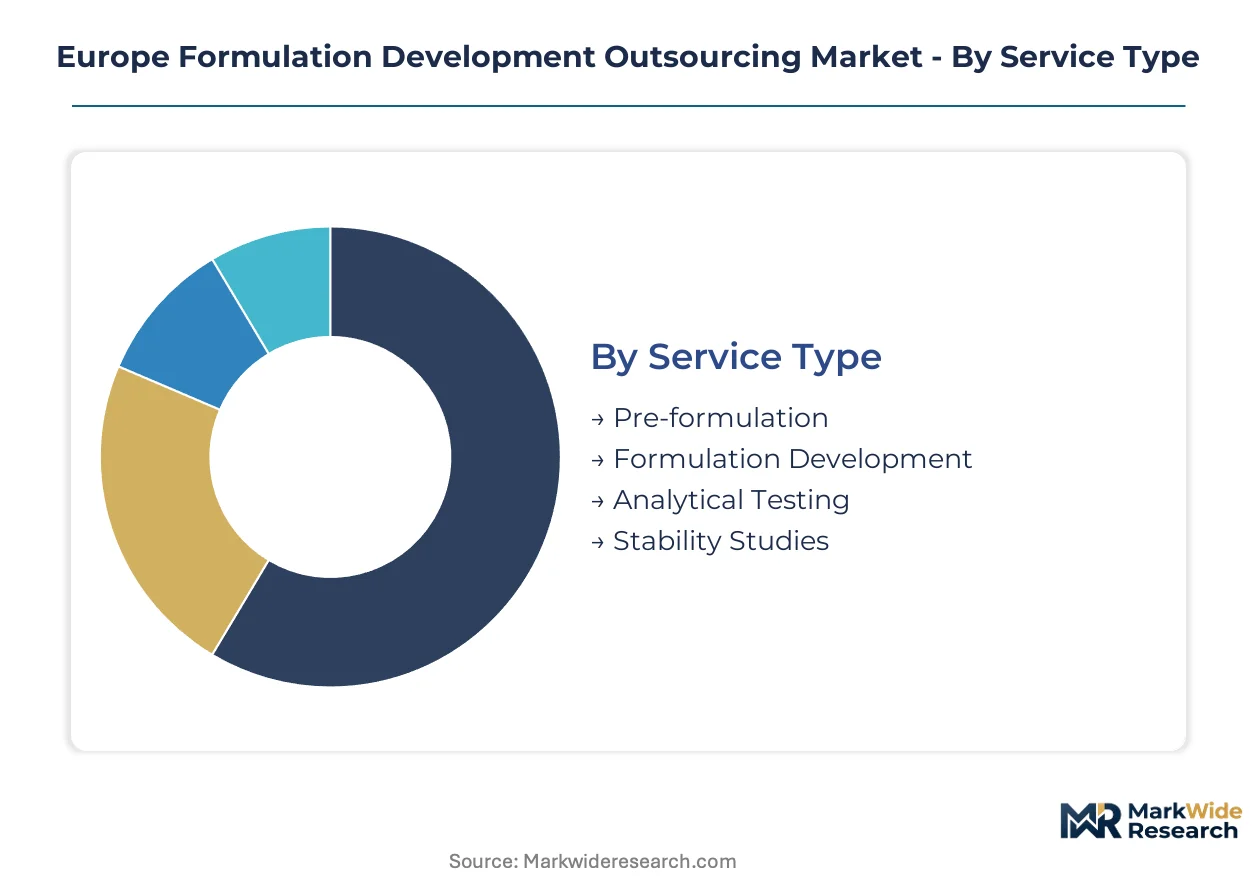
Service differentiation across the European formulation outsourcing landscape determines project economics and partnership durability. Cycle times vary dramatically by engagement type, with pre-formulation screening completing in weeks while stability programs extend across years.
Service Type:
Pre-formulation services turn over fastest with compressed discovery timelines, while stability studies lock in multi-year recurring revenue through protocol-driven extensions.
- Pre-formulation:Solubility profiling, salt screening, and polymorph characterization establish compoundability before API commitment. German biotech sponsors concentrate demand here as virtual models eliminate captive early-stage infrastructure.
- Formulation Development:Excipient selection, process design, and scale-up optimization constitute the core revenue pool. Complex biologics and nucleic acid programs in Swiss CDMO clusters drive specialization in lipid nanoparticle and amorphous dispersion platforms.
- Analytical Testing:Method development, validation, and release testing support regulatory submission packages. REACH-compliant impurity profiling and nitrosamine risk assessment are redirecting volume toward partners with dedicated contamination control capabilities.
- Stability Studies:ICH-guided long-term and accelerated storage protocols generate predictable recurring revenue. Post-Brexit MHRA divergence from EMA guidelines is fragmenting protocol design for sponsors pursuing parallel UK-EU filings.
Formulation Development anchors the volume base while Analytical Testing gains share at the steepest rate.
End User:
Customer type stratifies by outsourcing maturity, with established pharmaceutical sponsors running integrated programs and emerging biotechs purchasing discrete phase-gated services.
- Pharmaceutical Companies:Large-cap sponsors leverage formulation partnerships to supplement in-house capacity during pipeline surges or complex molecule transitions. French and Italian generics producers are consolidating analytical and reformulation work following EMA nitrosamine guidance revisions.
- Biotechnology Firms:Asset-light developers in the United Kingdom and Netherlands represent the most rapidly expanding sponsor category. Milestone-based engagement structures are displacing traditional master service agreements as capital efficiency pressures intensify.
- Contract Research Organizations:CROs subcontract specialized formulation capabilities to extend service portfolios without fixed infrastructure investment. Swiss and German CRO clusters are deepening partnerships with dedicated CDMOs to preserve client relationships across development phases.
- Academic Institutions:University spinouts and publicly funded research programs generate episodic demand for pre-formulation and proof-of-concept manufacturing. EU Horizon funding requirements increasingly mandate industrial partnership, channeling academic projects toward established commercial providers.
Pharmaceutical Companies retain the largest contract value while Biotechnology Firms expand engagement frequency most rapidly.
Form:
Physical state determines equipment requirements, regulatory pathway, and manufacturing scale-up complexity across the development trajectory.
- Liquid:Parenteral solutions, suspensions, and emulsions demand aseptic processing capabilities and container-closure integrity validation. mRNA and gene therapy pipelines are concentrating demand for sterile liquid formulation in German and Swiss CDMO networks.
- Solid:Tablets, capsules, and granules remain the dominant dosage form for small-molecule programs. EMA nitrosamine impurity mandates are forcing retrospective reformulation of established oral solid portfolios across Spanish and Italian generic manufacturers.
- Semi-solid:Creams, ointments, and gels require specialized homogenization and rheological characterization. Dermatology-focused sponsors in France are segmenting semi-solid development toward partners with dedicated topical manufacturing suites.
- Powder:Inhalation-grade and oral powder formulations demand precise particle engineering and content uniformity control. Dry powder inhaler development for respiratory programs is gaining traction among UK-based biotech sponsors.
Solid dosage forms sustain the installed capacity base while Liquid formulations climb the fastest on biologics expansion.
Technology:
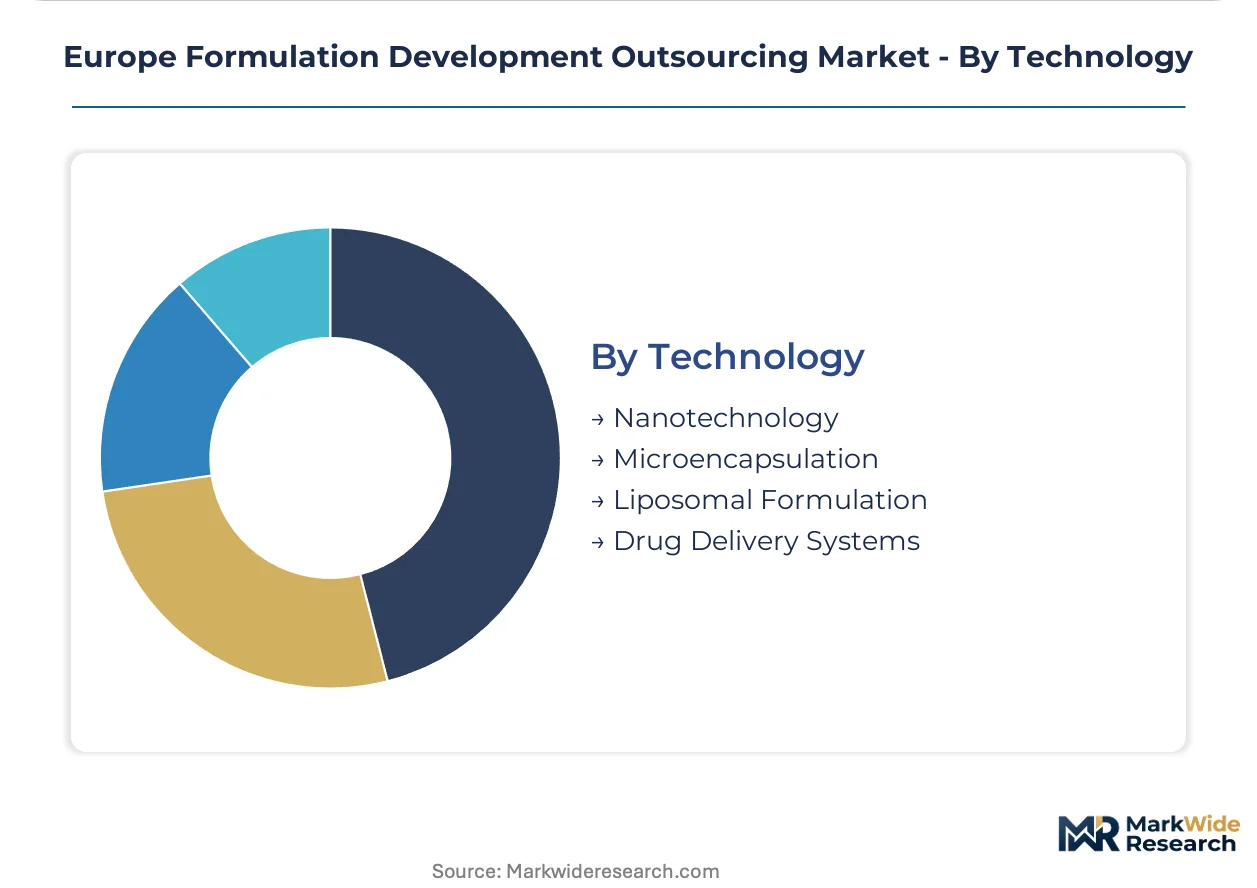
Platform specialization fragments the competitive landscape as complex molecules exceed conventional formulation capabilities.
- Nanotechnology:Lipid nanoparticles, polymeric nanoparticles, and nanocrystals enable solubility enhancement and targeted delivery. mRNA vaccine validation has accelerated platform adoption across European nucleic acid therapeutic developers.
- Microencapsulation:Spray-drying and coacervation techniques protect sensitive APIs and enable modified release profiles. Taste-masking applications for pediatric formulations are sustaining demand among Continental European sponsors.
- Liposomal Formulation:Phospholipid vesicle systems improve bioavailability and reduce toxicity for oncology and antifungal programs. Swiss CDMOs with dedicated lipid handling capabilities are capturing specialized demand from gene therapy pipelines.
- Drug Delivery Systems:Integrated device-formulation combinations including auto-injectors and implantable depots face dual EMA-MDR compliance pathways. Drug-device convergence is extending qualification timelines and raising outsourcing partner selection thresholds.
Drug Delivery Systems command premium pricing while Nanotechnology expands most quickly on nucleic acid therapeutic investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA quality guidelines and REACH compliance frameworks anchor formulation outsourcing demand across the European continent, with regulatory stringency varying between centralized EU pathways and national authorization routes.
Germany
Virtual biotechnology firms in Munich and Heidelberg are eliminating captive formulation infrastructure in favor of outsourced pre-formulation services. The country's chemical safety authority enforces stringent substance registration requirements that redirect toxicology work toward contract partners. The Rhine-Main and Upper Bavaria clusters concentrate lipid nanoparticle expertise serving mRNA therapeutic developers.
Switzerland
Gene therapy pipelines from Basel-based sponsors are expanding demand for specialized nanotechnology formulation capabilities. Swissmedic maintains distinct marketing authorization pathways that fragment submission strategies for pan-European programs. The Greater Zurich and Basel regions host integrated CDMO networks offering analytical and stability testing alongside formulation development.
United Kingdom
Asset-light developers in Cambridge and London are adopting milestone-based outsourcing structures for nucleic acid therapeutic programs. MHRA's independent regulatory pathway post-Brexit is creating demand for UK-based formulation partners serving parallel EU-UK filings. The Golden Triangle biotech corridor anchors specialized demand for sterile liquid formulation and dry powder inhaler development.
France
Paris and Lyon-based generics producers are consolidating analytical testing and reformulation work following EMA nitrosamine guidance revisions. ANSM enforces national pharmacovigilance standards that elevate quality benchmarks for contract manufacturers. The Île-de-France and Auvergne-Rhône-Alpes regions concentrate dermatology-focused semi-solid formulation expertise.
Netherlands
Leiden and Utrecht biotechnology clusters are displacing single-CDMO relationships in favor of best-of-breed segmentation across development phases. The Dutch Medicines Evaluation Board aligns with EMA centralized procedures while maintaining national competence for certain authorization types. The Randstad metropolitan region hosts virtual development firms purchasing discrete phase-gated formulation services.
Europe Formulation Development Outsourcing Market Competitive Landscape
Capability concentration sits with specialized technology providers; scale advantage sits with integrated manufacturing networks. The European formulation outsourcing structure fragments across three tiers: global CDMOs with multi-site European footprints, mid-cap specialists dominating single technology platforms, and regional service providers anchoring national sponsor relationships. Dominant competitive moves include capacity expansion in lipid nanoparticle platforms and strategic partnerships bridging pre-formulation through commercial supply.
Within the integrated manufacturing tier, Lonza Group and Catalent Inc exemplify archetypes combining biologics-focused capacity with regulatory affairs capabilities spanning multiple jurisdictions. Recipharm AB occupies a position anchoring Nordic and Continental European demand through multi-technology manufacturing networks. These three entities represent the spectrum from Swiss-centered biologics specialization to US-originated global CDMO scale to Swedish-rooted regional integration.
| Leading Market Players |
|---|
| Lonza Group |
| Catalent Inc |
| Recipharm AB |
| Evonik |
| Aenova Group |
| Fareva Holding SA |
| Boehringer Ingelheim Group |
| Intertek Group plc |
| SGS S.A. |
| Others |
Pricing and Supply Chain Analysis
The Rhine-Alpine freight corridor's cost volatility transmits directly into excipient procurement economics, amplifying price spreads between Swiss-German lipid suppliers and peripheral European compounders while forcing sponsors toward tiered service contracts that internalize logistics risk.
Pricing Analysis
Geographic price spreads between Basel-Zurich CDMO clusters and Spanish-Italian generic manufacturers exceed 40 percent for comparable lipid nanoparticle formulation services. Project-based pricing with milestone triggers dominates complex biologics engagements, while standardized oral solid development runs on fixed-fee structures. REACH compliance certification and dedicated regulatory affairs capabilities command substantial premiums over transactional analytical providers. Biotechnology sponsors in the Netherlands and United Kingdom exhibit acute price sensitivity, whereas gene therapy developers prioritize speed-to-clinic over unit economics.
Supply Chain Analysis
Tariff exposure between Switzerland and the European Union threatens seamless excipient flows for lipid and polymer inputs specialized in nucleic acid delivery systems. High-purity phospholipid and synthetic lipid production concentrates in Switzerland, Germany, and the Netherlands, drawing from a limited base of GMP-qualified chemical manufacturers. Single-source vulnerability pervades hot-melt extrusion equipment and advanced particle characterization instrumentation. Distribution runs through integrated CDMO networks that bundle formulation, analytical testing, and stability services under unified quality agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat structure where EMA regulatory entrenchment and multi-year stability study contracts generate switching costs that protect incumbent positions against price-based competition.
For Market Incumbents: Entrench market position through backward integration into high-purity excipient supply and dedicated capacity expansion in lipid nanoparticle platforms serving mRNA therapeutic pipelines. Emerging virtual biotechnology firms with milestone-based contracting models threaten traditional master service agreement economics, necessitating investment in real-time analytical capabilities that compress development timelines.
For New Entrants and Emerging Players: Pursue white-space opportunities in post-Brexit MHRA regulatory pathway services and aqueous-based formulation platforms responding to EU Green Deal solvent reduction mandates. The United Kingdom's independent authorization system offers the most penetrable geography for specialized regulatory affairs capabilities. A go-to-market angle anchored in discrete pre-formulation screening contracts with Cambridge-London gene therapy developers bypasses incumbent scale advantages.
For Investors and Strategic Acquirers: Mid-cap CDMOs with nanotechnology platform specialization and established EMA submission track records represent the most attractive acquisition archetype for portfolio diversification. Long-term viability hinges on regulatory entrenchment depth rather than capacity scale alone. The signal to watch is consolidation velocity among Netherlands-based virtual developers seeking integrated partners capable of spanning pre-formulation through commercial supply.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Affairs Capability Expansion | EMA and MHRA dual-pathway expertise secures pan-European sponsor contracts. |
| Lipid Nanoparticle Platform Investment | mRNA and gene therapy pipelines concentrate demand in Swiss-German clusters. |
| Continuous Manufacturing Technology Adoption | Process analytical technology integration enables real-time release testing protocols. |
| Strategic Partnership with Virtual Biotech | Milestone-based structures align capital efficiency pressures with CDMO revenue stability. |
| Green Solvent Transition Program | Supercritical fluid and aqueous platforms respond to EU Green Deal compliance mandates. |
Research Methodology
Cross-validation between primary interviews with formulation development directors, regulatory affairs leads, CDMO procurement officers, and biotechnology C-suite executives anchors the qualitative findings, while secondary validation draws from EMA quality guideline publications, REACH substance registration databases, Swissmedic authorization records, and ClinicalTrials.gov protocol disclosures. Bottom-up service-type demand modeling and top-down market sizing triangulate volume estimates.
Calibration against historical capacity utilization rates and sponsor outsourcing penetration patterns shapes the analytical framework across the projection horizon. Segmentation dimensions span service type, end-user category, dosage form, and technology platform, with CAGRs derived from weighted average growth assumptions across German, Swiss, and UK regulatory clusters. Forecast inputs incorporate virtual biotechnology firm formation rates and EMA nitrosamine guidance implementation timelines.
Sensitivities concentrate around REACH substance restriction expansions, MHRA-EMA regulatory divergence acceleration, and lipid excipient supply concentration risks. Forecasts reflect documented assumptions regarding sponsor outsourcing maturity and CDMO capacity expansion cadence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
North America Unit Dose Manufacturing Market
Pharmaceutical Equipment
Europe Pharmaceutical Isolator Market
Pharmaceutical Equipment
Asia-Pacific CDMO Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Packaging Market
Pharmaceutical Equipment
Automated Radiosynthesis Modules Market
Pharmaceutical Equipment
Pharmaceutical CDMO Market
Pharmaceutical Equipment
Pharmaceutical Equipment Market
Pharmaceutical Equipment
Prefilled Formalin Vials Market
Pharmaceutical Equipment
Global Pharmacy Automation Systems Market
Pharmaceutical Equipment
Pharmaceutical Storage and Material Handling Equipment Market
Pharmaceutical Equipment
Pharmaceutical Sterilization Equipment Market
Pharmaceutical Equipment
North America and Europe Pharmaceutical Stability & Storage Services Market
Pharmaceutical Equipment
Europe Pharmaceutical Vials Market
Pharmaceutical Equipment
Global Contract Development and Manufacturing Organization (CDMO) Outsourcing Market
Pharmaceutical Equipment
Investigational New Drug CDMO Market
Pharmaceutical Equipment
India Contract Manufacturing Organization (CMO) Market