
 Global Needle Free Injection Systems Market | 2026-2036
Global Needle Free Injection Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Needle Free Injection Systems Market Foresight
A capital-intensity divergence between large device manufacturers and emerging platform developers is reorganizing competitive hierarchy in needle-free delivery. PharmaJet leverages its spring-powered platform to anchor institutional procurement channels across North American health systems. Portal Instruments sustains electromechanical miniaturization leadership that differentiates its programmable dose engines from conventional jet injector architectures. Antares Pharma competes through gas-powered precision systems that occupy specialty pharmaceutical partnerships.
Needle-free injection systems use pressurized gas, mechanical springs, or electromechanical force to propel liquid or powder formulations through skin without penetrating needles, typically achieving delivery velocities of 100-200 meters per second for intradermal or intramuscular deposition. Jet injectors dominate current hospital procurement due to established reimbursement pathways, while electromechanical devices represent the fastest-expanding technology segment as programmable dose control attracts biologics manufacturers seeking reduced cold-chain waste. Spring-powered devices retain cost advantages in mass vaccination campaigns where single-use disposability governs procurement economics.
FDA 510(k) clearance pathways and EMA Medical Device Regulation (MDR) conformity requirements shape product development timelines and clinical evidence burdens for manufacturers seeking multi-jurisdictional approval. EPA and OSHA sharps disposal regulations in the United States, alongside EU F-Gas restrictions on propellant gases, directly influence device design specifications and material selection for gas-powered systems. Stakeholders must monitor evolving WHO prequalification standards for needle-free platforms intended for emerging market immunization programs.
Market Dynamics
Pharma and biologics manufacturers are compressing cold-chain dependency through electromechanical dose precision, forcing device developers to abandon legacy spring architectures for programmable liquid delivery engines that reduce refrigeration waste.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated clearance timelines for sharps-alternative devices are pulling hospital procurement committees toward jet injector platforms over conventional syringe systems.
- WHO prequalification momentum:Emerging market immunization programs in Nigeria and Bangladesh are specifying needle-free delivery in tender documents, creating institutional demand pull.
- EMA MDR conformity alignment:Harmonized clinical evidence requirements across EU member states are reducing redundant testing burdens for multi-jurisdictional device launches.
Market Restraints
- Gas propellant input volatility:EU F-Gas Regulation restrictions on hydrofluorocarbon propellants are constraining supply availability and elevating formulation costs for pneumatic delivery systems.
- Electromechanical component concentration:Precision micro-pump manufacturing clusters in Germany and Japan create geographic supply vulnerability for programmable dose engine developers.
- Jet stream dispersion limitation:Velocity inconsistency across skin types limits intradermal deposition accuracy, restricting adoption in pediatric and geriatric patient segments.
Strategic Opportunities
- India CDSCO fast-track channel:The country's national pharmaceutical regulator offers abbreviated review pathways for devices addressing domestic vaccination scale targets.
- Biologics self-administration:Rheumatology and endocrinology patients are driving home-use demand for pen-format electromechanical injectors with Bluetooth dose logging.
- Japan METI carbon-neutral procurement:Government hospital purchasing mandates now weight lifecycle emissions, favoring spring-powered disposables over gas-dependent alternatives.
Industry Challenges
- Biocompatibility certification timelines:ISO 10993 testing protocols for novel polymer nozzles extend development cycles by 14-18 months.
- Electromechanical firmware integration:Legacy hospital EMR systems lack API compatibility with connected dose-tracking devices, forcing custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Needle Free Injection Systems Market |
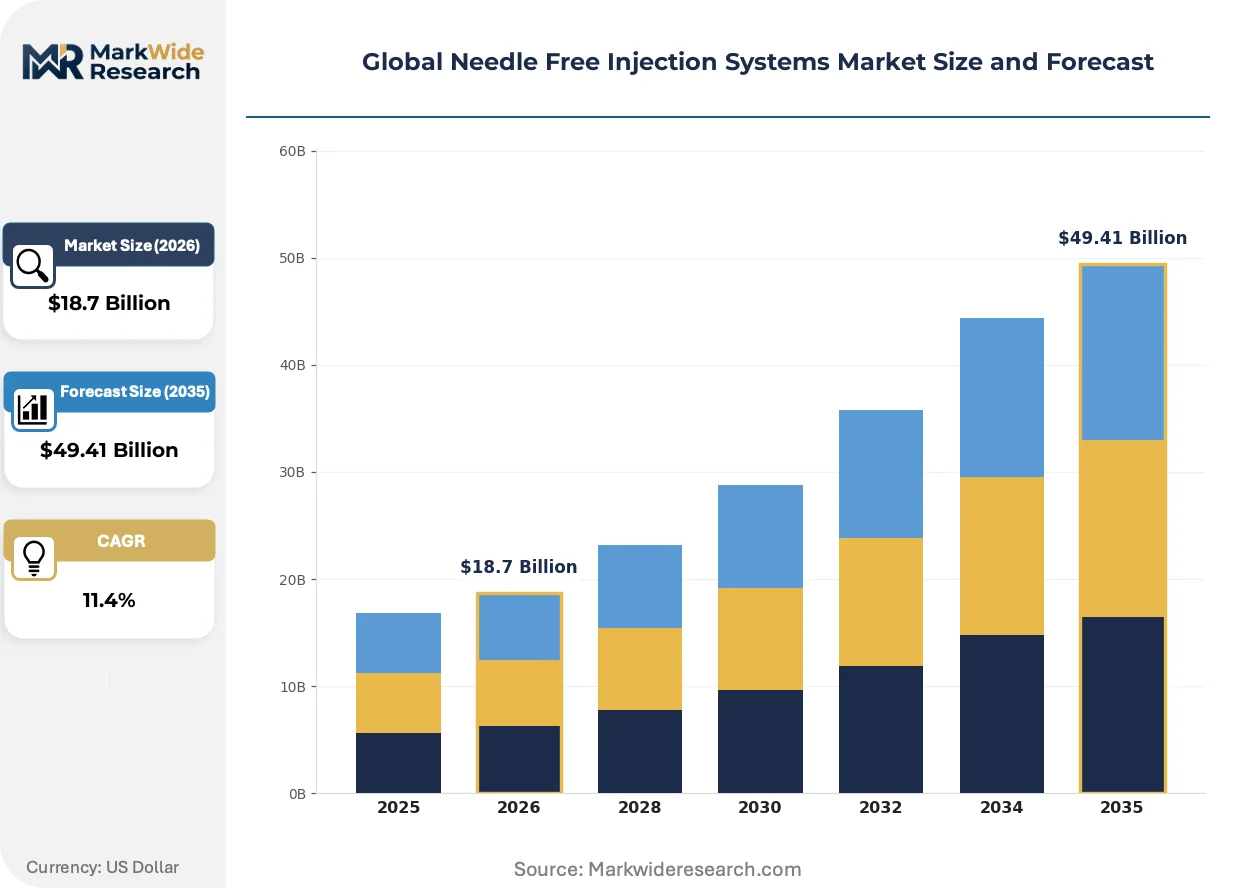
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jet Injectors, Spring Powered Devices, Gas Powered Systems, Electronic Injectors, Manual Injectors Technology: Spring Mechanism, Compressed Gas, Electromechanical, Ultrasonic, Magnetic Drive Application: Vaccination, Insulin Delivery, Dermatology, Pain Management, Allergy Treatment End User: Hospitals, Clinics, Specialty Pharmacies, Home Healthcare, Diagnostic Centers |
| Companies Covered | PharmaJet, Portal Instruments, Medical International Technology, NuGen Medical Devices, Crossject, Antares Pharma, INOVIO Pharmaceuticals, Bioject Medical Technologies, Zogenix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Needle Free Injection Systems Market Shifts & Advancements
Device architectures are fragmenting along precision-versus-scale tradeoffs, with electromechanical miniaturization diverging from single-use disposable economics and reshaping how manufacturers segment their R&D portfolios.
Programmable piezoelectric micropumps are bifurcating the precision injection landscape. Biologics formulators at temperature-sensitive peptide manufacturers are adopting these engines for sub-milliliter dose accuracy. The technology is compressing cold-chain infrastructure requirements by enabling room-temperature-stable biologic delivery that was previously needle-dependent.
EMA Medical Device Regulation post-market surveillance mandates are tightening adverse event reporting obligations. Manufacturers must now maintain electronic data capture systems for device malfunctions across all EU distribution channels. Electromechanical platform developers face disproportionate compliance burdens compared to passive spring-powered alternatives due to software validation requirements.
Hospital procurement committees are consolidating supplier relationships around full-service device-and-consumable contracts. Group purchasing organizations in the United States are displacing standalone device tenders with multi-year agreements bundling training, maintenance, and disposables. This concentration is most visible in integrated delivery networks across Texas and Florida, where standardization mandates now cover needle-free platforms alongside traditional syringe systems.
Global Needle Free Injection Systems Market Segmentation
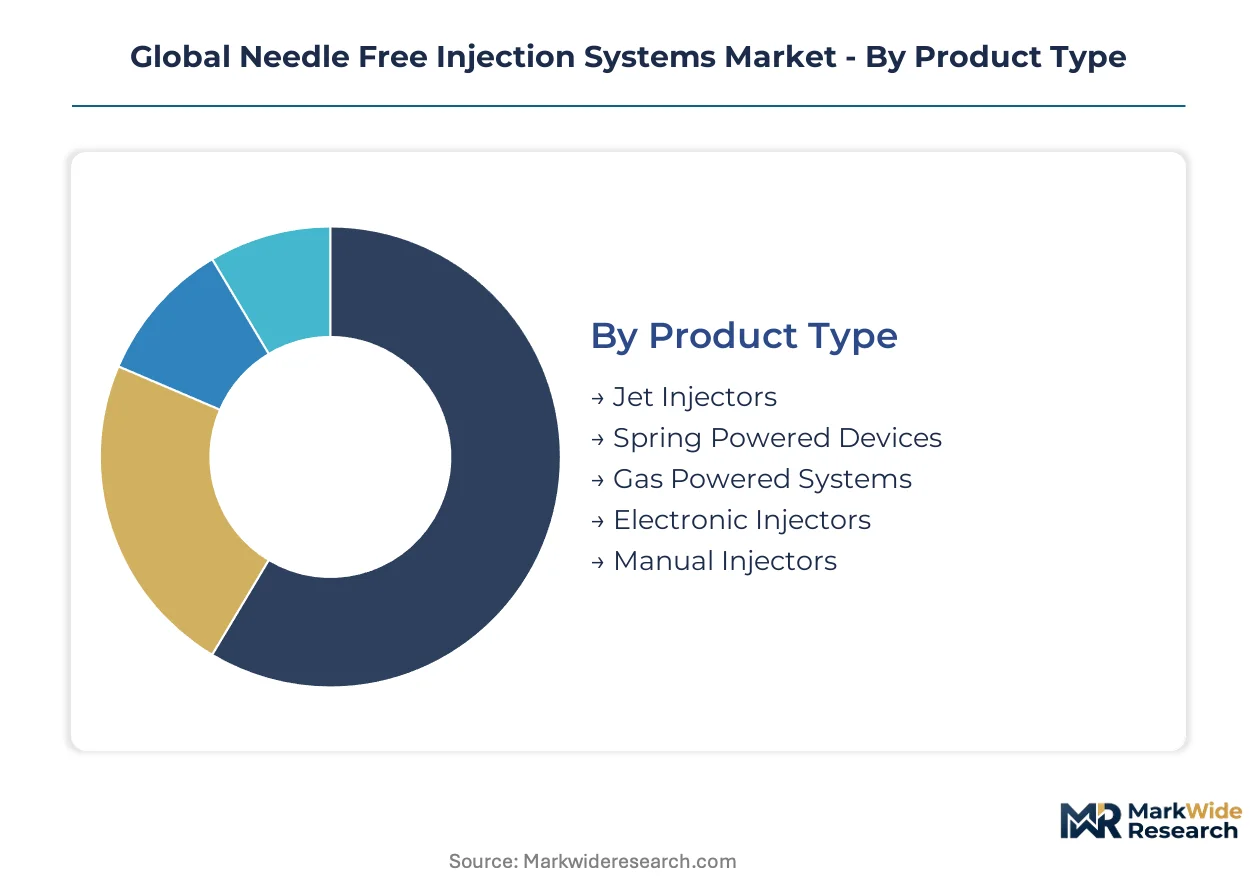
Device architecture and delivery mechanism choices determine reimbursement pathways, cold-chain requirements, and procurement economics across institutional and home-use settings. Segmentation reveals where programmable precision commands premium positioning versus where disposable scale economics dominate purchasing decisions.
Product Type:
Margin pools concentrate in electromechanical platforms where biologics manufacturers pay premiums for dose precision, while spring-powered devices compete on unit economics in mass vaccination tenders.
- Jet Injectors:These systems deploy pressurized liquid streams at 100-200 meters per second to penetrate skin without needles, achieving intramuscular or intradermal deposition. Hospital procurement committees in Texas and Florida integrated delivery networks specify these for sharps-free safety compliance, with FDA 510(k) clearance pathways accelerating adoption over conventional syringe systems.
- Electronic Injectors:Programmable piezoelectric micropumps enable sub-milliliter dose accuracy for temperature-sensitive biologics, compressing cold-chain infrastructure requirements by enabling room-temperature-stable delivery. Rheumatology and endocrinology patients in Germany and Japan are driving home-use demand for Bluetooth-connected pen-format devices with dose logging capabilities.
- Spring Powered Devices:Mechanical spring mechanisms deliver cost advantages in mass vaccination campaigns where single-use disposability governs procurement economics, particularly in Nigeria and Bangladesh immunization programs.
- Gas Powered Systems:Compressed gas propulsion occupies specialty pharmaceutical partnerships, though EU F-Gas Regulation restrictions on hydrofluorocarbon propellants constrain supply availability and elevate formulation costs.
- Manual Injectors:Hand-powered mechanical systems serve limited applications where electrical infrastructure is unavailable, primarily in rural clinic settings across emerging markets.
Jet injectors hold installed capacity across North American health systems. Electronic injectors are rotating up the share rankings as biologics formulators abandon legacy architectures.
Technology:
Technology choice maps directly to supply chain vulnerability, with precision manufacturing clusters in Germany and Japan creating geographic concentration risk for electromechanical developers.
- Electromechanical:Miniaturized programmable dose engines attract biologics manufacturers seeking reduced cold-chain waste through precision liquid delivery. These systems face disproportionate EMA MDR compliance burdens due to software validation requirements compared to passive alternatives.
- Spring Mechanism:Established mechanical architectures anchor institutional procurement channels with proven reliability and lower unit costs, favored in Japan METI carbon-neutral procurement mandates for lifecycle emissions advantages.
- Compressed Gas:Pneumatic delivery depends on propellant supply chains subject to EU regulatory restrictions, elevating cost volatility for manufacturers.
- Ultrasonic:Acoustic wave propulsion remains developmental for specific dermatology applications where tissue trauma minimization is prioritized.
- Magnetic Drive:Electromagnetic force systems occupy niche research applications with limited commercial deployment to date.
Spring mechanism technology retains volume leadership. Electromechanical platforms are climbing the fastest as programmable control becomes non-negotiable for biologics delivery.
Application:
Application segmentation reveals divergent regulatory and reimbursement pathways, with vaccination programs specifying needle-free delivery in tender documents while chronic disease management drives home-use adoption.
- Vaccination:Mass immunization programs in Nigeria and Bangladesh are specifying needle-free delivery in procurement tenders, creating institutional demand pull through WHO prequalification momentum. Spring-powered disposables dominate this segment for single-use economics.
- Insulin Delivery:Diabetes patients require frequent subcutaneous administration, making pen-format electromechanical injectors with connectivity features attractive for home healthcare settings in Germany and Japan.
- Dermatology:Intradermal deposition accuracy needs limit adoption where velocity inconsistency across skin types creates technical constraints.
- Pain Management:Opioid and non-opioid analgesic delivery through needle-free systems addresses sharps safety in hospital and clinic environments.
- Allergy Treatment:Immunotherapy administration benefits from reduced needle anxiety, particularly in pediatric patient segments.
Vaccination holds installed capacity through institutional procurement. Insulin delivery is gaining share fastest as chronic disease self-administration expands.
End User:
End-user concentration determines contract structure, with group purchasing organizations displacing standalone device tenders in favor of multi-year bundled agreements.
- Hospitals:Integrated delivery networks consolidate supplier relationships around full-service device-and-consumable contracts covering training, maintenance, and disposables. Standardization mandates in Texas and Florida now encompass needle-free platforms alongside traditional syringe systems.
- Home Healthcare:Patients with rheumatology and endocrinology conditions drive demand for connected pen-format devices with Bluetooth dose logging, requiring EMR API compatibility that forces custom middleware development.
- Clinics:Outpatient facilities balance cost constraints with sharps safety requirements, often selecting spring-powered alternatives.
- Specialty Pharmacies:Biologics dispensing channels prioritize cold-chain compression through precision electromechanical platforms.
- Diagnostic Centers:Limited injection needs restrict adoption to specific testing protocols requiring intradermal delivery.
Hospitals hold installed capacity through GPO concentration. Home healthcare is rotating up the share rankings as self-administration expands beyond traditional clinical settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States buyers demonstrate lowest price elasticity for connected electromechanical platforms, while emerging market procurement in Nigeria and Bangladesh prioritizes spring-powered disposables. Germany and Japan occupy the middle ground, where METI carbon-neutral mandates and EMA MDR compliance costs reshape supplier selection criteria.
United States
Integrated delivery networks in Texas and Florida consolidate supplier relationships around full-service device-and-consumable contracts. FDA 510(k) pathway streamlining accelerates hospital procurement committee decisions toward jet injector platforms. Group purchasing organizations in the Southeast displace standalone tenders with multi-year bundled agreements covering training and maintenance.
Germany
Rheumatology and endocrinology patients drive home-use demand for Bluetooth-connected pen-format electromechanical injectors. EMA Medical Device Regulation post-market surveillance mandates tighten adverse event reporting obligations for software-enabled platforms. Precision micro-pump manufacturing clusters in Baden-Württemberg create geographic supply concentration for programmable dose engine developers.
Japan
METI carbon-neutral procurement mandates now weight lifecycle emissions in government hospital purchasing decisions. PMDA regulatory alignment with international standards reduces redundant testing burdens for multi-jurisdictional device launches. Osaka-based biologics formulators adopt piezoelectric micropumps to compress cold-chain infrastructure requirements.
Nigeria
WHO prequalification momentum specifies needle-free delivery in national immunization program tender documents. The country's national pharmaceutical regulator offers abbreviated review pathways for devices addressing domestic vaccination scale targets. Spring-powered disposables dominate procurement economics in mass vaccination campaigns across northern and southern regions.
Bangladesh
Institutional demand pull from emerging market immunization programs creates procurement volume for single-use disposable platforms. The central drug regulatory authority fast-tracks approvals for sharps-alternative devices meeting WHO prequalification standards. Dhaka-based distribution channels concentrate last-mile delivery logistics for rural clinic deployments.
Global Needle Free Injection Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with electromechanical miniaturization specialists commanding premium positioning while spring-powered fabricators compete on unit economics. The vendor base organizes around three strategic archetypes: precision platform developers, mass-scale disposable manufacturers, and specialty pharmaceutical partnership specialists. Dominant competitive moves include strategic partnerships with biologics formulators and portfolio diversification into connected dose-tracking capabilities.
Among North American precision platform developers, PharmaJet and Portal Instruments exemplify divergent technology commitments within the electromechanical segment, while Antares Pharma occupies a position bridging specialty pharmaceutical partnerships and gas-powered delivery architectures. These three anchors represent how competitive positioning fragments along precision-versus-scale tradeoffs, with each archetype facing distinct regulatory compliance burdens and procurement channel access patterns.
| Leading Market Players |
|---|
| PharmaJet |
| Portal Instruments |
| Medical International Technology |
| NuGen Medical Devices |
| Crossject |
| Antares Pharma |
| INOVIO Pharmaceuticals |
| Bioject Medical Technologies |
| Zogenix |
| Others |
Supply & Pricing Matrix
Spring-powered disposables displacing gas-dependent architectures in Japan METI procurement are redrawing component sourcing maps from German precision clusters toward Southeast Asian contract manufacturers, compressing landed costs while fragmenting supplier bargaining power across electromechanical and mechanical platform developers.
Pricing Analysis
After-sales service contracts covering training, maintenance, and disposables now drive lifetime value capture in hospital procurement. Three-tier pricing structure across premium electromechanical platforms, standard jet injectors, and economy spring-powered disposables reflects FDA 510(k) certification tier and connectivity feature bundling. Cost compression in gas-powered systems intensifies because EU F-Gas Regulation constrains hydrofluorocarbon propellant availability. Mass vaccination programs in Nigeria and Bangladesh exhibit highest price sensitivity, while United States integrated delivery networks demonstrate lowest elasticity for connected platforms.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg ports constrain just-in-time delivery windows for German precision micro-pump manufacturers serving programmable dose engine developers. Electromechanical component supply concentrates in Germany, Japan, and South Korea, drawing from piezoelectric ceramics, precision-machined nozzles, and medical-grade polymer feedstocks. Single-source vulnerability in Baden-Württemberg micro-pump clusters elevates geographic concentration risk. Distribution runs through hospital group purchasing organizations and emerging market government tender channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Needle-free injection systems occupy an early-cycle expansion phase as WHO prequalification momentum and FDA 510(k) pathway streamlining accelerate institutional procurement conversion from conventional syringe systems.
For Market Incumbents: Compound installed base advantages by deepening backward integration into precision nozzle manufacturing and securing multi-year GPO contracts with Texas and Florida integrated delivery networks. Gas propellant input volatility from EU F-Gas Regulation restrictions threatens margin stability in pneumatic platforms. Certification investment in ISO 10993 biocompatibility protocols defends positioning against emerging spring-powered competitors.
For New Entrants and Emerging Players: Anchor in home healthcare self-administration for rheumatology and endocrinology patients, where Bluetooth-connected pen-format electromechanical injectors face limited incumbent saturation. Pediatric and geriatric dermatology applications remain underpenetrated due to velocity inconsistency constraints. Pursue India CDSCO fast-track channel approvals to capture national vaccination scale targets with abbreviated regulatory timelines.
For Investors and Strategic Acquirers: The market sits at a platform-consolidation phase that favors electromechanical miniaturization specialists with programmable dose engine capabilities and established biologics manufacturer partnerships. Long-term viability hinges on cold-chain compression demand from temperature-sensitive peptide formulators. Watch FDA 510(k) clearance velocity for connected dose-tracking devices as inflection indicator for home healthcare adoption acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Biologics Manufacturer Partnership | Programmable dose precision attracts rheumatology and endocrinology formulators seeking reduced refrigeration waste. |
| Hospital System Partnership | GPO consolidation in Texas and Florida mandates bundled device-and-consumable contracts with training inclusion. |
| Software Companion Development | Bluetooth dose logging requires EMR API compatibility that forces custom middleware investment. |
| CE Marking Pathway | EMA MDR software validation requirements impose disproportionate compliance burdens on electromechanical platforms. |
| Reimbursement Strategy | FDA 510(k) clearance accelerates hospital procurement committee decisions toward sharps-alternative platforms. |
Research Methodology
Desk research of FDA 510(k) filings, EMA MDR submissions, WHO prequalification databases, and hospital procurement tender documents preceded structured interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads at device manufacturers. Secondary validation drew from EPA sharps disposal regulations, EU F-Gas restriction notices, and Japan METI carbon-neutral procurement mandates. Bottom-up device shipment modeling and top-down healthcare expenditure allocation provided triangulation across the analysis window.
Variance decomposition across product type, technology mechanism, application segment, and end-user channel informed the analytical framework. CAGRs derived from installed base growth rates, replacement cycle assumptions, and penetration elasticity parameters. Cold-chain infrastructure investment trends and biologics formulation pipeline data served as industry-specific forecast inputs throughout the projection horizon.
Underlying assumptions cover WHO prequalification momentum continuation, FDA 510(k) pathway stability, and EU F-Gas Regulation enforcement trajectory, with deviation risk concentrated in electromechanical component supply disruptions and EMR integration timeline delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Disposable Negative Pressure Wound Therapy Devices Market
Diagnostic and Therapeutic Devices
Automated Immunoassay Analyzers Market
Diagnostic and Therapeutic Devices
Global Exosome Diagnostic and Therapeutic Market
Diagnostic and Therapeutic Devices
Fully Automated Coagulometer Market
Diagnostic and Therapeutic Devices
One-Step ELISA Market
Diagnostic and Therapeutic Devices
Leukocytapheresis Device Market
Diagnostic and Therapeutic Devices
Global Acute Ischemic Stroke Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Vacuum Therapy Devices Market
Diagnostic and Therapeutic Devices
RF Microneedling Market
Diagnostic and Therapeutic Devices
Smart Drug Delivery Systems Market
Diagnostic and Therapeutic Devices
Phototherapy Device Market
Diagnostic and Therapeutic Devices
Magnetic Therapy Devices Market
Diagnostic and Therapeutic Devices
Anti Neurofilament L Antibody Market
Diagnostic and Therapeutic Devices
Pelvic Congestion Syndrome Treatment Market
Diagnostic and Therapeutic Devices
Robotic Surgery System Haptic Feedback Test Platforms Market
Diagnostic and Therapeutic Devices
Dental Surgical and Diagnostic Devices Market