
 Pharmaceutical Equipment Testing Market | 2026-2036
Pharmaceutical Equipment Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Equipment Testing Market Analysis
Germany's expansion of biopharmaceutical manufacturing corridors is reconfiguring equipment validation requirements across Europe. Thermo Fisher Scientific leverages its chromatography platform dominance to anchor service contracts with multinational drug makers. SGS competes through its network of GMP-certified laboratories spanning Basel and Frankfurt. Eurofins Scientific differentiates by integrating analytical instruments with proprietary compliance software for batch release testing.
Pharmaceutical equipment testing encompasses the verification, calibration, and qualification of machinery used in drug manufacturing, including performance parameters such as sterilization validation, particulate monitoring, and cleanroom integrity certification. The primary purpose is ensuring that production equipment meets GMP standards and produces consistent, contaminant-free pharmaceutical products. Chromatography systems command the largest installed base among technology segments due to their ubiquity in impurity profiling and stability studies. Mass spectrometry represents the fastest-expanding technology category as complex biologics require molecular-level characterization. Quality Assurance applications absorb the majority of service spending, driven by mandatory batch release protocols and ongoing stability monitoring requirements.
FDA enforcement of 21 CFR Part 11 electronic records standards and EMA's updated Annex 15 on qualification and validation are compelling manufacturers to upgrade legacy equipment with automated testing capabilities. The EU AI Act introduces new verification requirements for machine-learning-enabled diagnostic and production tools, creating additional compliance layers for equipment software validation. Stakeholders must monitor how convergence between pharmaceutical manufacturing and digital quality systems reshapes competency requirements for testing service providers.
Market Dynamics
FDA enforcement of 21 CFR Part 11 and EMA's Annex 15 revisions are forcing biologics manufacturers to replace manual validation with automated continuous process verification systems, compressing equipment replacement cycles and elevating service provider technical requirements.
Growth Catalysts
- EMA Annex 15 Qualification Mandates:European sterile injectable manufacturers must implement enhanced equipment qualification protocols, expanding demand for thermal mapping and cleanroom integrity certification services across Germany, Switzerland, and France.
- Biologics Manufacturing Cluster Expansion:mRNA and cell therapy production corridors in Basel, Boston, and Singapore require specialized chromatography system validation and mass spectrometry qualification at scale.
- Continuous Manufacturing Adoption:Real-time release testing architectures demand integrated process analytical technology validation, creating recurring revenue streams for equipment testing providers.
Market Restraints
- Specialized Engineering Talent Scarcity:Shortages of qualified validation engineers with combined GMP and automation expertise constrain service provider capacity expansion in Germany and Switzerland.
- High-Purity Reference Material Costs:Volatility in certified standard and reagent supply chains elevates operating costs for analytical instrument calibration services.
- Legacy Equipment Interoperability Limits:Decades-old stainless steel bioreactor installations lack digital interfaces compatible with modern electronic batch record systems, delaying validation automation.
Strategic Opportunities
- India Biopharma Manufacturing Surge:CDSCO's tightened GMP inspections and export-oriented facility investments create demand for international-standard equipment qualification services in Hyderabad and Bangalore corridors.
- AI-Enabled Predictive Maintenance:Machine learning algorithms applied to chromatography and filtration equipment performance data enable condition-based validation scheduling, reducing unplanned downtime.
- Single-Use Technology Validation:Disposable bioreactor and filtration assembly qualification represents an emerging service category distinct from traditional stainless steel equipment protocols.
Industry Challenges
- Multi-Site Standardization Complexity:Harmonizing validation protocols across geographically distributed manufacturing networks while accommodating local regulatory variations strains quality system architecture.
- Cybersecurity Qualification Requirements:FDA's emphasis on data integrity and electronic records security necessitates specialized IT/OT system validation expertise that traditional equipment testing providers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Equipment Testing Market |
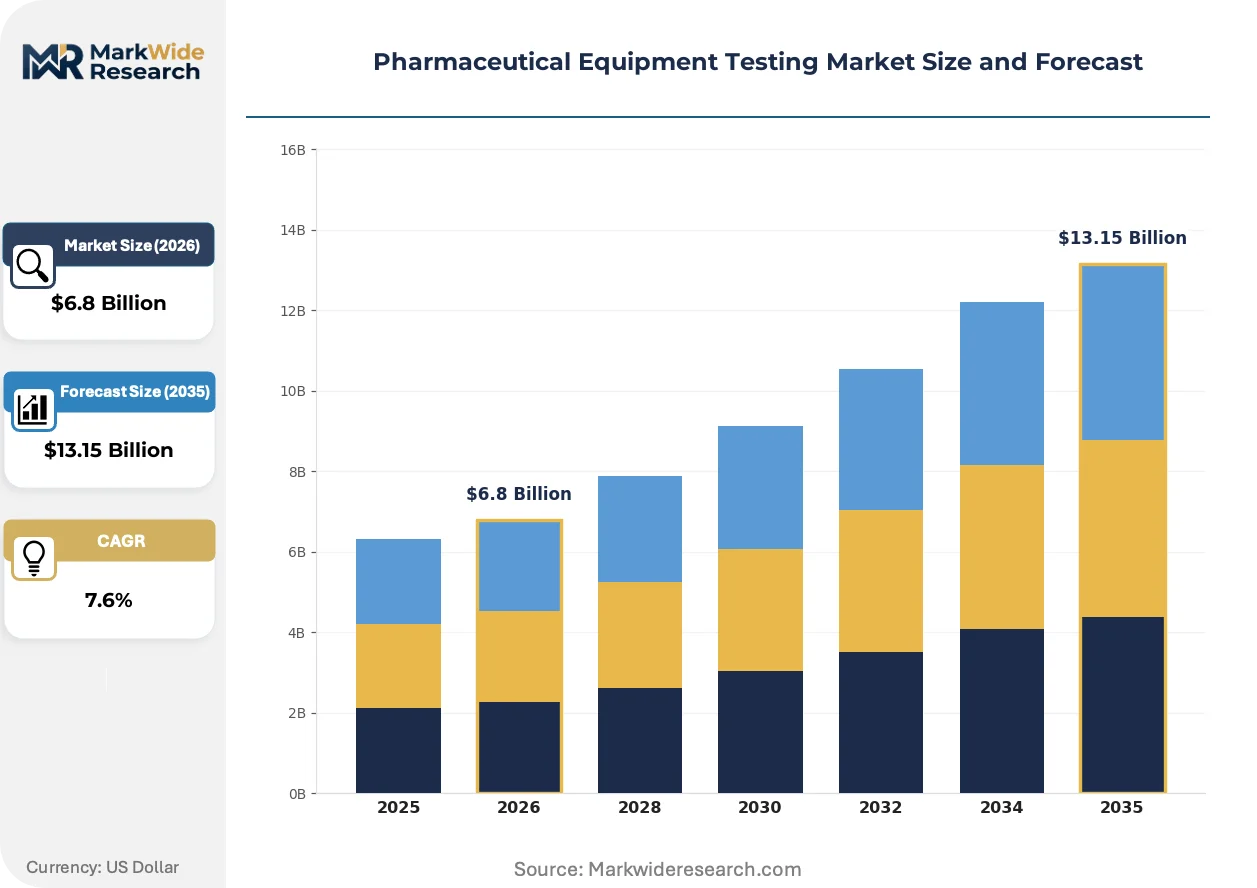
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analytical Instruments, Quality Control Equipment, Detection Systems, Measuring Devices Technology: Chromatography, Mass Spectrometry, Electrophoresis, Spectroscopy Application: Drug Development, Quality Assurance, Product Validation, Compliance Testing End User: Pharmaceutical Manufacturers, Research Institutions, Regulatory Agencies, Quality Assurance Labs |
| Companies Covered | TASI Group, West Pharmaceutical Services, Edwards Analyticals, Thermo Fisher Scientific, SGS, Intertek Group, Eurofins Scientific, Charles River Laboratories, Pace Analytical Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Equipment Testing Market Emerging Trajectories
Digital quality systems are converging with physical equipment validation, creating integrated platforms that automate documentation, compress batch release timelines, and enable real-time regulatory reporting across distributed manufacturing networks.
Process Analytical Technology (PAT) frameworks embed spectroscopic and chromatographic sensors directly into bioreactor and purification skids, enabling in-line monitoring of critical quality attributes. Biologics manufacturers in Germany and Switzerland are deploying PAT at commercial scale, displacing offline laboratory testing for release decisions. This architecture is digitizing equipment validation from episodic qualification events to continuous verification against statistical process control limits.
EMA's updated Annex 15 on qualification and validation, effective across all EU member states, mandates enhanced documentation of equipment lifecycle management and periodic review frequencies. The regulation compels manufacturers to demonstrate ongoing performance verification rather than one-time qualification, expanding recurring service contract scopes. Sterile injectable producers in Ireland, Belgium, and Italy are restructuring supplier relationships to secure multi-year validation partnerships.
Biopharma procurement teams are unbundling equipment purchase and validation service contracts, selecting specialized testing providers independent of original equipment manufacturers. This disintermediation concentrates in the United States, where large-cap drug makers leverage validation expertise as a competitive differentiator in supplier selection. Third-party qualification specialists now compete directly with OEM service organizations for multi-site framework agreements.
Pharmaceutical Equipment Testing Market Segmentation
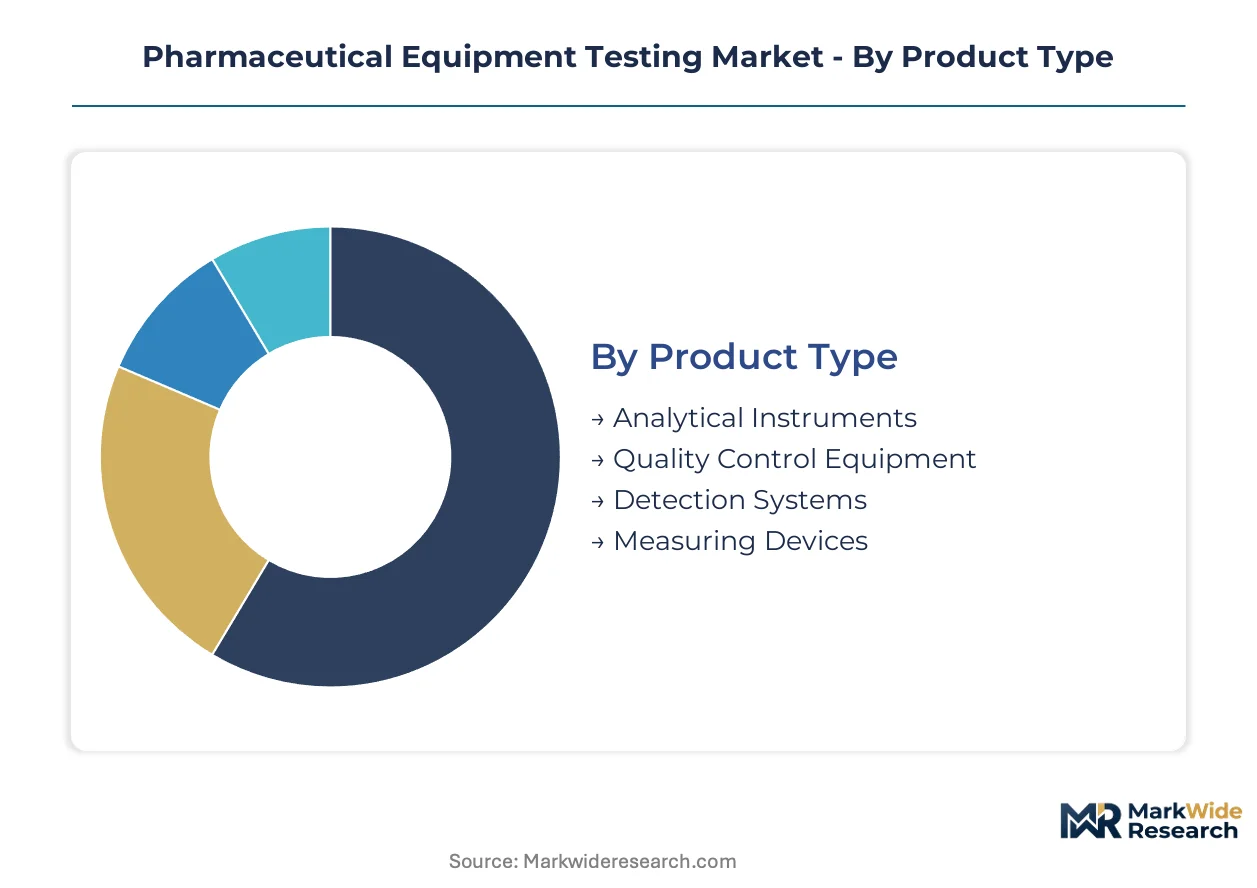
Equipment testing services exhibit divergent margin profiles across product categories, with analytical instruments demanding continuous calibration contracts while detection systems rely on episodic recertification. Segmentation reveals where service providers can anchor recurring revenue versus project-based engagements.
Product Type:
After-sales-service intensity varies dramatically across equipment categories, with analytical instruments generating multi-year calibration contracts while measuring devices produce transactional replacement demand.
- Analytical Instruments:Chromatography systems and mass spectrometers require quarterly performance verification and annual requalification under FDA 21 CFR Part 11 protocols. Biologics manufacturers in Germany and Switzerland contract directly with specialized validation engineers for multi-site instrument harmonization.
- Quality Control Equipment:Particle counters and environmental monitors demand continuous certification cycles tied to batch release schedules. Sterile injectable producers in the United States structure three-year service agreements covering thermal mapping and cleanroom integrity verification.
- Detection Systems:Microbial and endotoxin detection platforms require less frequent recalibration but face replacement pressure from rapid microbiological methods.
- Measuring Devices:Pressure gauges and temperature sensors operate on simpler replacement cycles with lower technical service attachment rates.
By volume, Measuring Devices leads. By growth pace, Analytical Instruments is ahead.
Technology:
Technology selection dictates capital intensity and technical competency requirements for testing providers, with mass spectrometry demanding PhD-level analytical chemists while electrophoresis operates on standardized protocols.
- Chromatography:High-performance liquid chromatography and gas chromatography systems constitute the installed base backbone for impurity profiling and stability studies. EMA Annex 15 revisions in Europe are extending qualification documentation requirements for these systems across Ireland, Belgium, and Italy.
- Mass Spectrometry:LC-MS and GC-MS platforms enable molecular-level characterization of complex biologics including mRNA and cell therapies. Singapore's emerging biologics corridor is deploying these systems at commercial scale with integrated PAT validation architectures.
- Electrophoresis:Capillary and gel-based separation methods serve protein purity verification with established qualification protocols.
- Spectroscopy:UV-Vis, IR, and Raman systems support raw material identification with lower service intensity than chromatography platforms.
Chromatography holds the largest installed base. Mass Spectrometry is climbing the fastest.
Application:
Application focus determines regulatory exposure and contract duration, with quality assurance absorbing majority spending through mandatory batch release protocols.
- Quality Assurance:Batch release testing, stability monitoring, and ongoing process verification command the largest service expenditure share. FDA enforcement of data integrity standards is compelling United States manufacturers to automate documentation workflows.
- Drug Development:Method validation and technology transfer for clinical trial materials require specialized analytical expertise with project-based contracting.
- Product Validation:Equipment qualification and process validation support new facility startups and technology transfers.
- Compliance Testing:Regulatory inspection preparation and remediation services spike around FDA and EMA audit cycles.
Quality Assurance dominates current spending. Drug Development is gaining share fastest.
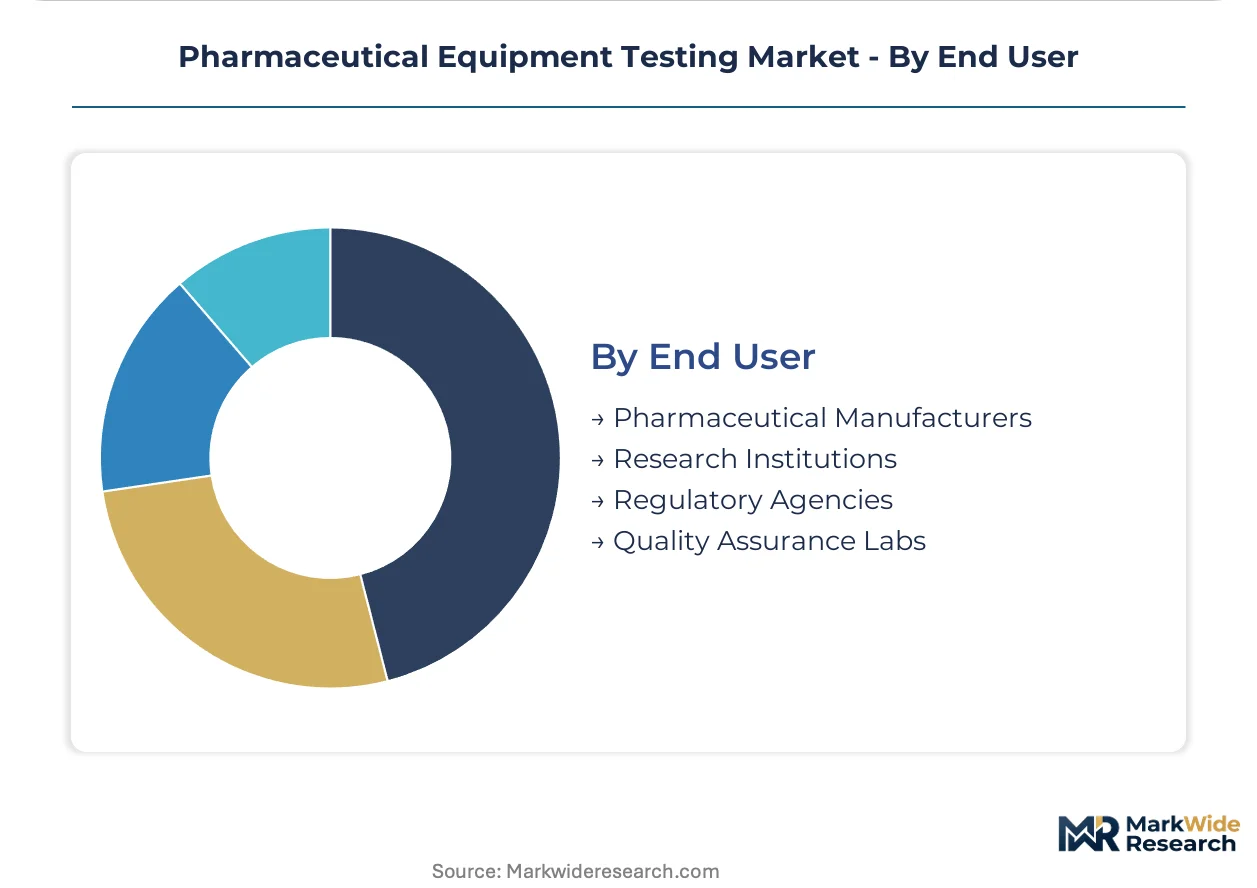
End User:
End-user structure shapes procurement authority and contract complexity, with pharmaceutical manufacturers consolidating multi-site frameworks while research institutions fragment across individual PIs.
- Pharmaceutical Manufacturers:Large-cap drug makers unbundle equipment purchase from validation services, selecting third-party specialists over OEM service organizations. Boston's mRNA production cluster exemplifies this disintermediation trend.
- Quality Assurance Labs:Independent testing facilities serving multiple clients demand flexible scheduling and rapid turnaround capabilities.
- Research Institutions:University and government labs operate on grant-funded cycles with episodic equipment qualification needs.
- Regulatory Agencies:Government reference laboratories require metrological traceability and inter-laboratory comparison programs.
Pharmaceutical Manufacturers anchor demand volume. Quality Assurance Labs are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA enforcement of 21 CFR Part 11 electronic records standards anchors North American demand for automated validation systems. The EMA's Annex 15 revisions and the EU AI Act create parallel compliance pressures across European manufacturing corridors.
United States
Boston's mRNA production cluster and New Jersey's sterile injectable corridor drive demand for continuous process verification systems. FDA intensification of data integrity inspections compels manufacturers to replace manual validation with automated electronic batch records. Large-cap drug makers in the Northeast are unbundling equipment purchase from validation services, selecting third-party specialists over OEM service organizations.
Germany
Biopharmaceutical manufacturing expansion across Baden-Württemberg and Bavaria reconfigures equipment qualification requirements. EMA Annex 15 mandates enhanced documentation of equipment lifecycle management, compelling manufacturers to demonstrate ongoing performance verification. Heidelberg and Munich production clusters are restructuring supplier relationships to secure multi-year validation partnerships with specialized service providers.
Switzerland
Basel's cell therapy and biologics corridor requires specialized chromatography system validation at commercial scale. Swissmedic alignment with EMA qualification protocols tightens validation documentation standards for sterile injectable producers. The country's precision manufacturing heritage attracts multinational drug makers seeking GMP-certified laboratory networks for batch release testing.
India
Hyderabad and Bangalore biopharma corridors are expanding export-oriented facility investments under CDSCO's tightened GMP inspection regime. The country's national pharmaceutical regulator is harmonizing domestic standards with FDA and EMA requirements for international market access. Contract manufacturers in Telangana and Karnataka are contracting international-standard equipment qualification services to meet European and American importer specifications.
Singapore
The city-state's emerging biologics manufacturing hub deploys mass spectrometry platforms with integrated PAT validation architectures. Government investment in pharmaceutical infrastructure attracts cell therapy and mRNA producers seeking ASEAN market access. Jurong Island production facilities are adopting real-time release testing systems that digitize equipment validation from episodic qualification to continuous verification.
Pharmaceutical Equipment Testing Market Vendor Landscape
Full-service validation conglomerates and specialized analytical laboratories split the market into distinct capability tiers. The vendor base concentrates around three strategic archetypes: chromatography platform anchor firms, GMP-certified laboratory network operators, and integrated compliance software developers. Consolidation pressures favor multi-site framework agreements over transactional project contracting. Capacity expansion and technology licensing represent the dominant competitive moves as providers seek to automate documentation workflows.
Within the full-service tier, Thermo Fisher Scientific and SGS exemplify divergent geographic anchoring strategies. Thermo Fisher leverages its chromatography platform dominance to secure multi-year service contracts with multinational drug makers across North America and Europe. SGS occupies a position as a laboratory network operator, spanning Basel and Frankfurt with GMP-certified facilities. Eurofins Scientific represents the integration archetype, combining analytical instruments with proprietary compliance software for batch release testing workflows.
| Leading Market Players |
|---|
| TASI Group |
| West Pharmaceutical Services |
| Edwards Analyticals |
| Thermo Fisher Scientific |
| SGS |
| Intertek Group |
| Eurofins Scientific |
| Charles River Laboratories |
| Pace Analytical Services |
| Others |
Supply Flow & Price Mechanics
Basel's precision manufacturing corridor anchors European capacity for chromatography system validation, concentrating technical expertise that translates into pricing power for multi-site service contracts. German and Swiss validation engineers command premium rates for continuous process verification, while Indian contract manufacturers in Hyderabad face compressed margins competing on international qualification standards.
Pricing Analysis
Validation service rates diverge sharply between Western Europe and South Asia, with Basel and Frankfurt corridors extracting 40-60% premiums over Bangalore and Hyderabad for equivalent chromatography qualification work. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth: FDA 21 CFR Part 11-compliant automated documentation commands top rates, manual protocols with paper trails occupy mid-tier, and basic calibration without regulatory filing support sits at economy level. Pricing pressure stems from CDSCO's tightened GMP inspections in India, which forces domestic providers to invest in international-standard capabilities without matching rate recovery. Research institutions and small CDMOs exhibit highest price sensitivity, while large-cap biologics manufacturers in Boston and New Jersey prioritize technical competency over cost minimization.
Supply Chain Analysis
Export-control restrictions on high-performance mass spectrometry components from US and EU sources limit equipment availability for analytical service providers in emerging biopharma corridors. Supply concentrates in Germany, Switzerland, and the United States for precision chromatography columns and certified reference standards, with Singapore and India dependent on these sources for qualification-grade consumables. Raw material dependencies include high-purity solvents, traceable calibration gases, and GMP-certified reagent kits subject to batch-specific documentation. Single-source vulnerability runs through Swiss and German column manufacturers for ultra-high-pressure liquid chromatography systems. Distribution runs through OEM-authorized service networks and independent validation specialists competing for multi-site framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous process verification systems represent a high-growth disruption as FDA and EMA mandates compress equipment replacement cycles and elevate technical barriers for service providers.
For Market Incumbents: Build switching-cost moats through proprietary compliance software integration that locks in batch release testing workflows across customer manufacturing networks. Thermo Fisher Scientific's chromatography platform anchoring exemplifies this approach. Defend against disintermediation by unbundling equipment purchase from validation services through multi-year partnership structures. Capacity addition in Singapore's Jurong Island biologics corridor captures emerging demand from cell therapy and mRNA producers seeking ASEAN market access. For New Entrants and Emerging Players: Single-use technology validation for disposable bioreactor assemblies represents the most penetrable entry point, as established providers lack specialized protocols distinct from stainless steel equipment qualification. India's Hyderabad and Bangalore corridors offer white-space opportunity where CDSCO's tightened inspections create demand for international-standard services without entrenched incumbent relationships. Go-to-market positioning should emphasize rapid turnaround for thermal mapping and cleanroom integrity certification, addressing pain points from EMA Annex 15 documentation burdens. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because equipment validation becomes more specialized as biologics manufacturing advances and digital quality systems converge with physical asset management. Acquisition targets should display GMP-certified laboratory networks spanning multiple regulatory jurisdictions with demonstrated competency in PAT-enabled continuous verification. The signal to watch is FDA enforcement intensity around 21 CFR Part 11 data integrity standards, which accelerates replacement of manual validation with automated systems and expands addressable market for qualified service providers.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Predictive Maintenance | Machine learning applied to chromatography performance data reduces unplanned downtime for Basel biologics manufacturers. |
| Multi-Site Validation Framework Agreements | Three-year service contracts spanning Germany, Switzerland, and Ireland secure recurring revenue from sterile injectable producers. |
| Single-Use Technology Qualification | Disposable bioreactor validation protocols capture emerging demand from mRNA and cell therapy production corridors. |
| PAT Integration Services | Real-time release testing architectures digitize equipment validation from episodic qualification to continuous verification. |
| Cybersecurity Qualification Expertise | IT/OT system validation capabilities address FDA data integrity requirements that traditional equipment testing providers lack. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 21 CFR Part 11 guidance documents, EMA Annex 15 qualification protocols, and GMP inspection databases. Interviews with validation engineering directors, regulatory affairs leads at biologics manufacturers, procurement managers at CDMOs, and service provider account executives informed demand-side dynamics. Secondary sources include SEC filings from publicly traded testing conglomerates, Swissmedic and CDSCO regulatory notices, and industry association technical standards. Bottom-up equipment installation counts and top-down service revenue estimates were triangulated to anchor market sizing.
Forecast inputs span analytical instrument installed base growth, biologics manufacturing capacity expansion by corridor, and regulatory enforcement intensity indices across FDA, EMA, and CDSCO jurisdictions. Segmentation modeling incorporates product type, technology platform, application focus, and end-user procurement authority. CAGRs were derived from regression analysis against historical validation service spending and projected equipment replacement cycles. Industry-specific inputs include mRNA and cell therapy manufacturing buildouts, continuous manufacturing adoption rates, and AI-enabled diagnostic tool verification requirements under the EU AI Act.
Stress conditions across regulatory enforcement intensity, reference material supply volatility, and qualified engineering talent availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EMA Annex 15 implementation timelines and FDA data integrity inspection priorities. Material shifts in biologics manufacturing technology platforms or harmonization of international GMP standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Global Central Fill Pharmacy Automation Market
Pharmaceutical Equipment
Automated Drug Kiosk Market
Pharmaceutical Equipment
ASEAN Contract Development and Manufacturing Organization (CDMO) Market
Pharmaceutical Equipment
Depyrogenation Oven Market
Pharmaceutical Equipment
Global Pharmaceutical Granulation Equipment Market
Pharmaceutical Equipment
Radiochemical Synthesizers Market
Pharmaceutical Equipment
Automated Radiosynthesis Modules Market
Pharmaceutical Equipment
Investigational New Drug CDMO Market
Pharmaceutical Equipment
Tablet Press Market
Pharmaceutical Equipment
Flip Top Vials Market
Pharmaceutical Equipment
Vial Adaptors for Reconstitution Drug Market
Pharmaceutical Equipment
Prefilled Formalin Vials Market
Pharmaceutical Equipment
Fill-Finish Pharmaceutical Contract Manufacturing Market
Pharmaceutical Equipment
Aseptic Negative Pressure Pharmaceutical Isolators Market
Pharmaceutical Equipment
North America Pharmacy Automation Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Packaging Market