
 Lyophilization Equipment Market | 2026-2036
Lyophilization Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Lyophilization Equipment Market Analysis
The gap between conventional shelf freeze-drying and continuous processing is narrowing as equipment makers race to cut cycle times and energy use. GEA Group leverages its pharmaceutical systems portfolio to anchor large-scale tray dryer installations across European biologics facilities. Thermo Fisher Scientific sustains R&D intensity in controlled nucleation technologies that shorten primary drying phases. Tofflon Science and Technology Group dominates batch system exports into Asia-Pacific contract manufacturing markets with cost-engineered platforms.
Lyophilization equipment refers to vacuum-based systems that remove water from heat-sensitive materials by sublimation, typically operating at shelf temperatures between −50°C and +60°C and chamber pressures below 0.1 mbar to preserve biological activity. The primary commercial purpose centers on stabilizing injectable pharmaceuticals, vaccines, and enzymes for multi-year shelf life without refrigeration. Tray freeze dryers occupy the mature revenue core where replacement cycles and capacity expansions in established pharma markets generate predictable demand. Continuous freeze dryers represent the fastest-growing technology segment as manufacturers seek to de-bottleneck parenteral drug production and reduce batch-to-batch variability. Enhanced nucleation technology concentrates margin pools by enabling precise ice crystal formation that cuts drying time and improves product uniformity.
FDA validation requirements for aseptic processing and EMA Annex 1 revisions on contamination control are forcing equipment upgrades that integrate isolator barriers and automated clean-in-place systems. The EU Green Deal and REACH chemical safety frameworks are also pressing manufacturers to reduce solvent use and energy consumption in freeze-drying operations. Stakeholders must monitor whether continuous lyophilization platforms can achieve regulatory acceptance for commercial biologics production faster than incumbent batch systems can retrofit nucleation controls.
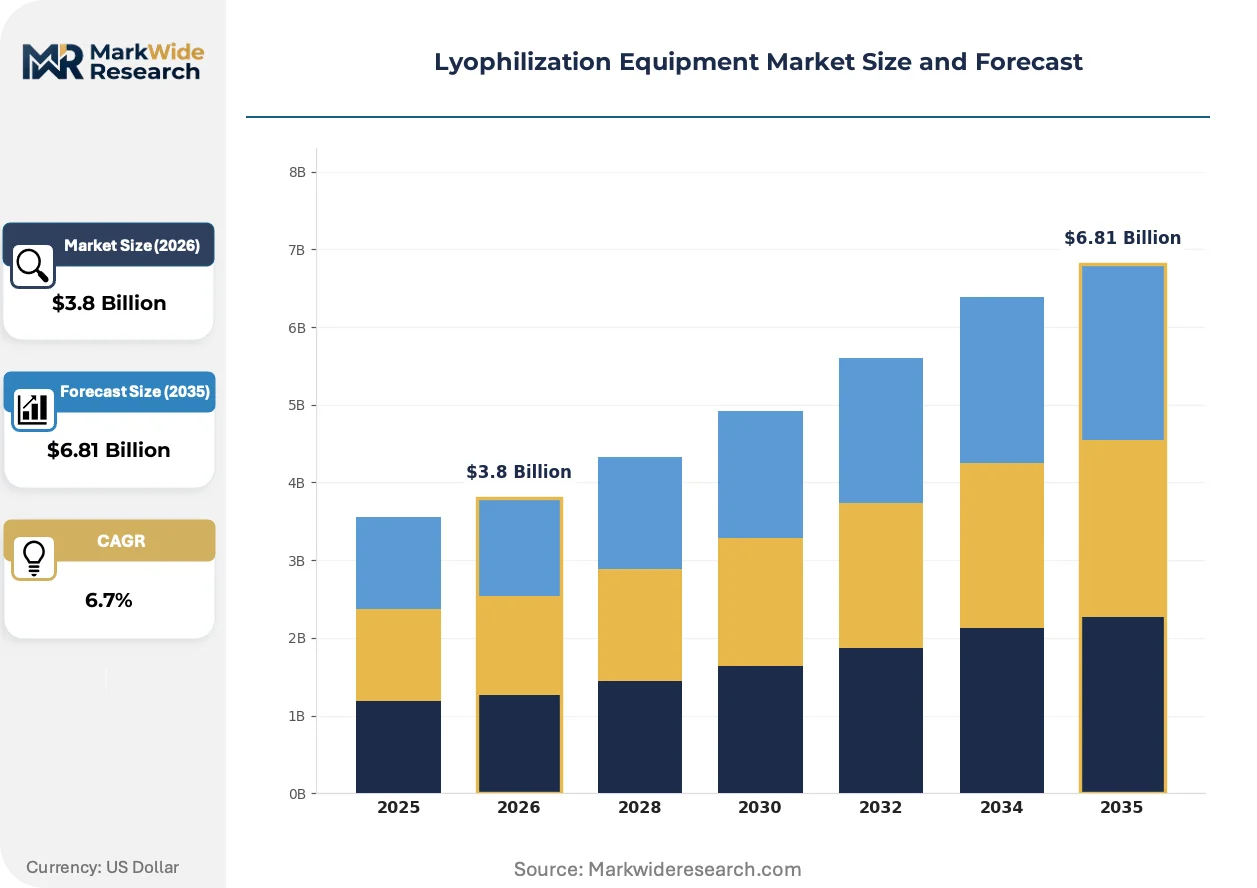
Market Dynamics
Continuous lyophilization platforms are compressing batch cycle times and forcing incumbent equipment makers to retrofit nucleation controls or cede share to specialized continuous processing vendors.
Growth Catalysts
- EMA Annex 1 revisions:New contamination control mandates are accelerating replacement demand for legacy tray dryers across European parenteral manufacturing facilities.
- Biologics capacity buildouts:Contract manufacturing organizations in Germany, the United States, and China are commissioning dedicated lyophilization suites to capture outsourced freeze-drying volumes.
- Controlled nucleation technology:Precise ice crystal formation protocols are shortening primary drying phases and improving batch uniformity for heat-sensitive vaccines.
Market Restraints
- Stainless steel and refrigeration component costs:Volatility in nickel prices and specialized compressor supply is squeezing margins on large-scale tray dryer installations.
- Validation protocol complexity:FDA stability requirements for parenteral drugs are extending commissioning timelines for new freeze-drying equipment by 8-14 months.
- Substitute stabilization methods:Spray-drying and aqueous two-phase systems are capturing share in oral solid dosage applications where injectable-grade stability is not required.
Strategic Opportunities
- Cell and gene therapy manufacturing:Viral vector and mRNA producers require small-batch, flexible lyophilization systems that incumbent platforms poorly serve.
- EU Green Deal compliance:Energy efficiency mandates are creating replacement pull for heat pump-based shelf systems that cut electricity consumption versus conventional refrigeration.
- Asia-Pacific contract manufacturing:Cost-engineered batch system exports are penetrating Indian and Southeast Asian CMO markets where capital constraints favor modular equipment.
Industry Challenges
- Process analytical technology integration:Embedding PAT sensors into isolator-barrier lyophilizers requires rare cross-functional expertise in both pharmaceutical validation and automation engineering.
- Clean-in-place system retrofitting:Legacy tray dryers in established facilities cannot accommodate automated CIP without structural chamber modifications that disrupt ongoing production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lyophilization Equipment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tray Freeze Dryers, Batch Freeze Dryers, Manifold Freeze Dryers, Continuous Freeze Dryers Technology: Conventional, Vacuum, Enhanced Nucleation, Novel End User: Pharmaceuticals, Biotechnology, Food Industry, Research Institutions Application: Biologics, Vaccines, Enzymes, Plasma |
| Companies Covered | GEA Group, Martin Christ Gefriertrocknungsanlagen GmbH, Thermo Fisher Scientific, Azbil Telstar SL, Labconco Corporation, Millrock Technology, Tofflon Science and Technology Group, SP Industries, Zirbus Technology GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lyophilization Equipment Market Emerging Trajectories
Equipment differentiation is pivoting from mechanical reliability to cycle-time compression and energy efficiency as pharmaceutical manufacturers face margin pressure on sterile injectables.
Continuous freeze-drying technology is collapsing the traditional batch-size economics that governed lyophilization capacity planning for decades. Large-scale parenteral manufacturers in Belgium and Switzerland are piloting continuous lines that integrate directly with aseptic filling isolators. The technology is collapsing the distinction between upstream formulation and downstream processing, enabling real-time release testing that eliminates quarantine inventory.
REACH chemical safety frameworks and the EU F-Gas Regulation are phasing down hydrofluorocarbon refrigerants in industrial freeze-drying equipment. European equipment makers are accelerating heat pump and CO₂-based refrigeration retrofits to maintain CE marking compliance. Pharmaceutical facilities in the Netherlands and Denmark are absorbing premium pricing for compliant systems to avoid production shutdowns during refrigerant phase-out periods.
Service contract unbundling is fragmenting the traditional full-service equipment procurement model. Large CMOs in the United States are separating hardware purchases from validation, maintenance, and spare parts agreements to optimize total cost of ownership. The shift is most visible among multi-site operators in North Carolina and Massachusetts who negotiate pan-facility service frameworks independent of original equipment vendors.
Lyophilization Equipment Market Segmentation
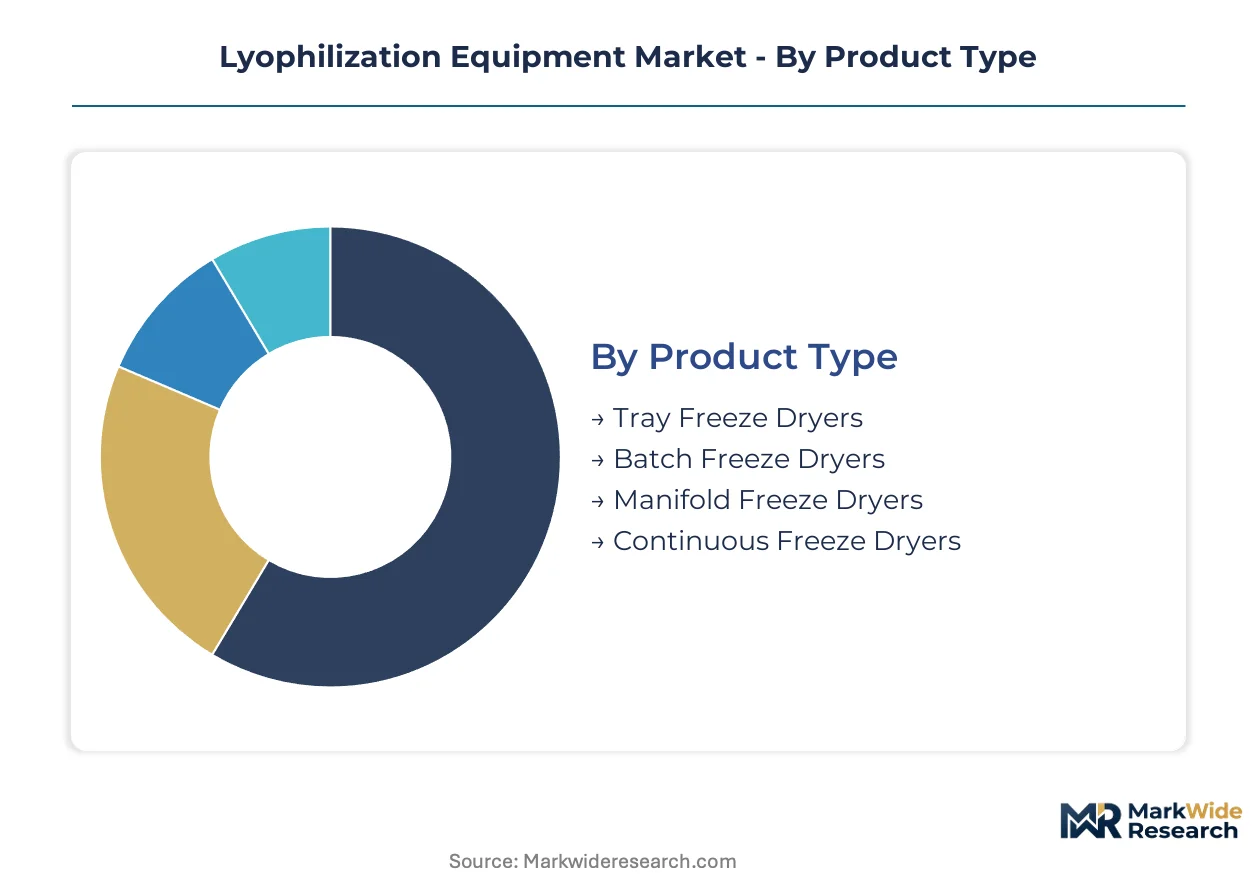
Lyophilization equipment segmentation reveals divergent capital cycles across product architectures. Cycle times for batch systems stretch across 15-20 year replacement horizons, while continuous platforms compress to 7-10 year technology refresh windows as nucleation control advances.
Product Type:
Cycle-time compression varies sharply across dryer architectures, with continuous platforms turning over fastest and tray systems slowest due to embedded base inertia.
- Tray Freeze Dryers:Shelf-based systems with fixed tray configurations dominate established pharmaceutical facilities in Germany and the United States. Replacement demand concentrates where FDA validation protocols for parenteral drugs force upgrades of legacy stainless steel chambers that cannot accommodate isolator barriers.
- Continuous Freeze Dryers:Rotary belt or tunnel configurations integrate directly with aseptic filling lines, collapsing batch quarantine periods. Belgian and Swiss biologics manufacturers pilot these systems to enable real-time release testing, though EMA commercial validation frameworks remain unsettled.
- Batch Freeze Dryers:Modular chamber systems serve contract manufacturing organizations in China and India where capital constraints favor scalable, cost-engineered platforms over integrated continuous lines.
- Manifold Freeze Dryers:Compact laboratory-scale units with external flask connections support research institutions and early-phase biologics development requiring small-batch flexibility.
Tray freeze dryers anchor the volume base while continuous freeze dryers gain share at the steepest rate.
Technology:
Margin stratification follows nucleation precision, with premium tiers commanding pricing power from cycle-time reduction while conventional systems compete on installed base service revenue.
- Enhanced Nucleation:Controlled ice crystal formation via pressurization-depressurization cycles or ultrasonic seeding cuts primary drying time by 30-50% for heat-sensitive vaccines. Thermo Fisher Scientific and GEA Group concentrate R&D here to defend positioning against continuous platform entrants.
- Conventional:Standard shelf freezing without nucleation control serves generic injectable manufacturers where cost minimization outweighs cycle-time optimization. Demand concentrates in Indian and Southeast Asian contract manufacturing markets.
- Vacuum:Deep sub-atmospheric pressure systems below 0.05 mbar preserve biological activity in enzyme and plasma applications where residual moisture specifications tighten.
- Novel:Emerging approaches including atmospheric freeze-drying and microwave-assisted sublimation remain pre-commercial, capturing pilot funding from cell and gene therapy producers seeking alternatives to thermal degradation risks.
Conventional technology anchors the volume base while enhanced nucleation gains share at the steepest rate.
End User:
Customer procurement patterns split between validated pharmaceutical installations with 18-month commissioning timelines and research institutions prioritizing equipment flexibility over throughput.
- Pharmaceuticals:Sterile injectable manufacturers in the United States and Europe drive replacement cycles as EMA Annex 1 contamination control mandates force isolator retrofits incompatible with legacy tray dryer geometries.
- Biotechnology:Viral vector and mRNA producers require small-batch, single-use-compatible systems that incumbent platforms poorly serve, creating entry points for specialized vendors.
- Food Industry:Specialty coffee and nutraceutical processors in Japan and South Korea adopt lyophilization for premium product differentiation, though volumes remain fractional versus pharmaceutical demand.
- Research Institutions:Academic and government laboratories in Germany and Switzerland purchase manifold and small-batch systems for early-phase formulation development without commercial scale requirements.
Pharmaceuticals anchors the volume base while biotechnology gains share at the steepest rate.
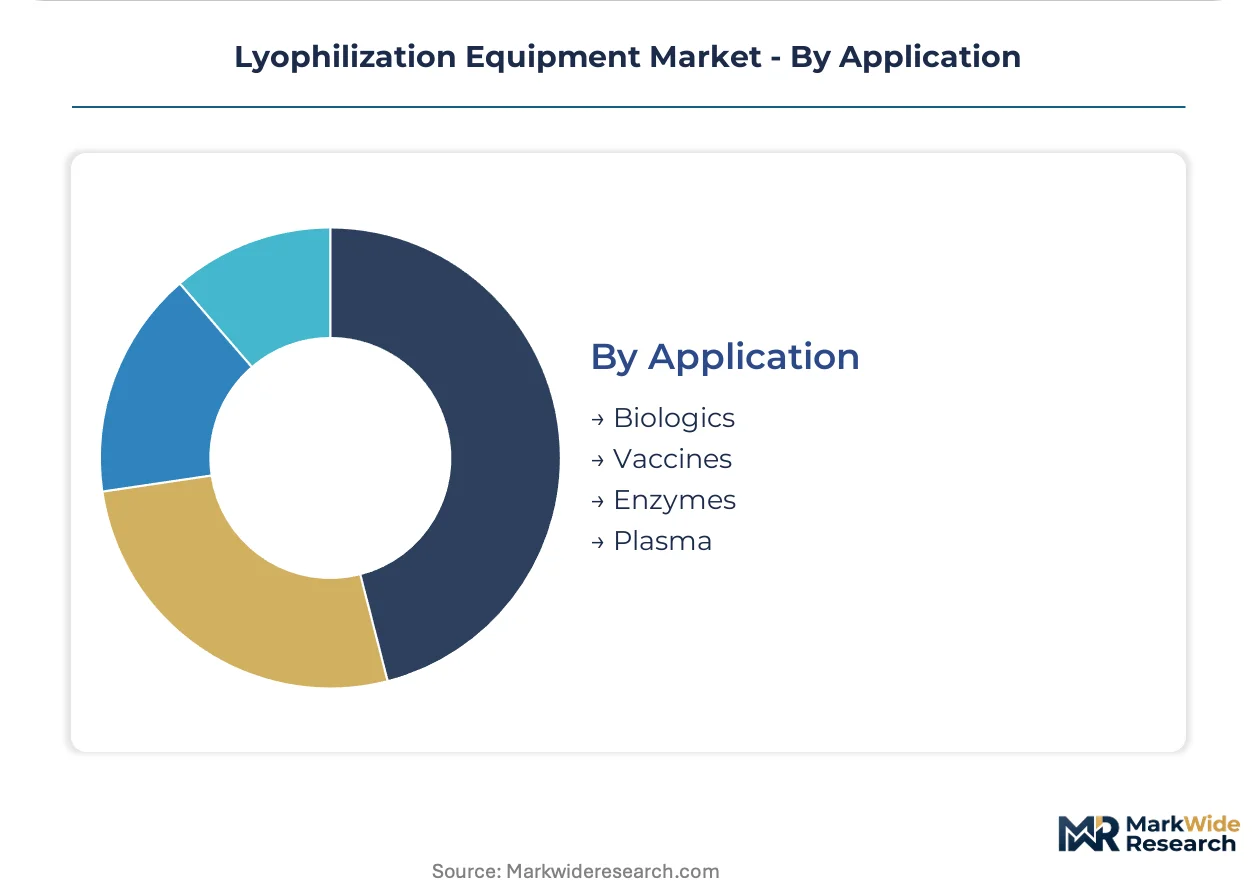
Application:
Stability requirements diverge across biological categories, with live-attenuated vaccines demanding the tightest moisture specifications and plasma derivatives tolerating broader process windows.
- Vaccines:Live-attenuated and mRNA formulations require ultra-low residual moisture below 1% to maintain potency across multi-year shelf life. FDA stability protocols for parenteral vaccines drive nucleation control adoption to prevent thermal degradation during primary drying.
- Biologics:Monoclonal antibodies and fusion proteins dominate capacity utilization in German and United States contract manufacturing facilities, where batch sizes scale to 100,000+ vials per cycle.
- Enzymes:Industrial and diagnostic enzyme producers prioritize activity preservation over speed, accepting longer cycle times to avoid denaturation of protein structures.
- Plasma:Blood fractionation facilities in Switzerland and Austria process immunoglobulin and albumin with established tray dryer configurations, where regulatory filing inertia slows continuous platform adoption despite cycle-time advantages.
Biologics anchors the volume base while vaccines gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German equipment manufacturers export lyophilization systems to contract manufacturing facilities across the United States and China, while Chinese fabricators supply cost-engineered batch platforms to Southeast Asian markets.
United States
Biologics capacity buildouts in North Carolina and Massachusetts drive demand for large-scale tray dryer installations. FDA validation protocols for parenteral drugs extend equipment commissioning timelines by 8-14 months. Multi-site CMOs in the Research Triangle negotiate pan-facility service frameworks independent of original equipment vendors.
Germany
EMA Annex 1 contamination control mandates force isolator retrofits incompatible with legacy stainless steel chamber geometries. The EU F-Gas Regulation accelerates heat pump refrigeration retrofits to maintain CE marking compliance. Bavarian biologics facilities absorb premium pricing for compliant systems to avoid production shutdowns.
China
Contract manufacturing organizations in Jiangsu and Zhejiang provinces commission dedicated lyophilization suites to capture outsourced freeze-drying volumes. NMPA stability requirements for biologics tighten validation protocols around freeze-drying cycles. Tofflon Science and Technology Group anchors domestic batch system production for Asia-Pacific export markets.
Switzerland
Swissmedic oversight of sterile injectable manufacturing drives adoption of controlled nucleation technologies. Blood fractionation facilities in Bern and Basel process immunoglobulin with established tray dryer configurations. Belgian and Swiss biologics manufacturers pilot continuous lines that integrate directly with aseptic filling isolators.
India
CDSCO regulatory filings for generic injectables concentrate demand in conventional batch systems without nucleation controls. Contract manufacturers in Hyderabad and Ahmedabad favor modular, cost-engineered platforms over integrated continuous lines. Capital constraints in Indian CMO markets sustain demand for scalable equipment with shorter depreciation cycles.
Lyophilization Equipment Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base clusters around three strategic archetypes: diversified industrial conglomerates with pharmaceutical systems portfolios, pure-play freeze-drying specialists with deep application expertise, and emerging Asian fabricators competing on cost-engineered platforms. Dominant competitive moves include strategic partnerships for nucleation technology licensing and geographic expansion into contract manufacturing growth corridors.
Among diversified industrial conglomerates, GEA Group and Thermo Fisher Scientific exemplify the integrated systems approach. Tofflon Science and Technology Group anchors the cost-engineered platform tier for Asia-Pacific export markets. Martin Christ Gefriertrocknungsanlagen GmbH and Zirbus Technology GmbH occupy positions within the German specialist fabricator cluster. Azbil Telstar SL and Labconco Corporation represent regional specialists with concentrated presence in European and North American research markets respectively.
| Leading Market Players |
|---|
| GEA Group |
| Martin Christ Gefriertrocknungsanlagen GmbH |
| Thermo Fisher Scientific |
| Azbil Telstar SL |
| Labconco Corporation |
| Millrock Technology |
| Tofflon Science and Technology Group |
| SP Industries |
| Zirbus Technology GmbH |
| Others |
Supply Flow & Price Mechanics
German refrigeration compressor fabrication concentrates upstream capability for lyophilization shelf systems, anchoring margin capture in European equipment vendors while Asian fabricators compete downstream on modular batch platform economics.
Pricing Analysis
Next-generation continuous freeze-drying platforms command 40-60% premiums over conventional tray systems, while prior-generation equipment without nucleation controls faces accelerating price erosion. Three-tier pricing structure across premium, standard, and economy levels separates isolator-integrated systems from modular batch units and refurbished legacy installations. Pricing pressure stems from nickel price volatility in stainless steel chambers and extended FDA validation timelines that delay revenue recognition. Generic injectable manufacturers in India exhibit highest price sensitivity, whereas Belgian biologics facilities absorb premiums for real-time release capability.
Supply Chain Analysis
Specialized refrigeration compressors and high-grade stainless steel feed lyophilization equipment fabrication, with component sourcing concentrated in Germany, Japan, and China. Nickel and specialized alloys for vacuum chambers draw from mining operations in Indonesia and Russia, while precision valves and sensors rest on Japanese and German component tiers. Single-source vulnerability runs through semiconductor-based process analytical technology sensors embedded in next-generation systems. Distribution runs through direct OEM sales for large pharmaceutical installations and regional distributors for research-scale equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lyophilization equipment markets sit at a platform-economics inflection where continuous processing interoperability with aseptic filling lines is collapsing traditional batch-size procurement logic.
For Market Incumbents: Insulate installed base revenue by retrofitting controlled nucleation modules onto legacy tray dryers before continuous platform vendors capture EMA validation pathways. Backward integration into refrigeration compressor supply secures margin against nickel price volatility. Prioritize isolator barrier certification investments to defend positioning against emerging continuous processing specialists. For New Entrants and Emerging Players: Small-batch flexible systems for viral vector and mRNA producers represent the most penetrable entry point, as incumbent platforms poorly serve cell and gene therapy manufacturing workflows. Asia-Pacific contract manufacturing markets favor cost-engineered modular equipment where capital constraints block integrated continuous line adoption. Lead with nucleation technology licensing partnerships rather than full-system fabrication to accelerate regulatory credibility. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed pharmaceutical services conglomerates seeking to monetize freeze-drying equipment divisions. Long-term viability hinges on nucleation control IP and continuous platform regulatory acceptance velocity. Watch FDA guidance documents on real-time release testing for lyophilized biologics as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Controlled Nucleation Technology Licensing | GEA Group and Thermo Fisher Scientific defend positioning against continuous platform entrants through ice crystal formation IP. |
| Isolator Barrier Retrofit Programs | EMA Annex 1 contamination control mandates force upgrades incompatible with legacy tray dryer geometries across European facilities. |
| Heat Pump Refrigeration Transition | EU F-Gas Regulation compliance requires CO₂-based and heat pump retrofits to maintain CE marking for European sales. |
| Asia-Pacific Modular Platform Expansion | Tofflon Science and Technology Group captures contract manufacturing growth in Jiangsu and Zhejiang provinces with cost-engineered systems. |
| Process Analytical Technology Integration | Embedding PAT sensors enables real-time release testing that eliminates quarantine inventory for Belgian biologics manufacturers. |
Methodological Framework
Operator-level perspectives from freeze-drying equipment procurement managers, pharmaceutical manufacturing engineers, regulatory affairs specialists, and contract manufacturing organization executives anchored the qualitative base. Primary interview insights combined with secondary validation from FDA 510(k) filings, EMA marketing authorization applications, NMPA biologics registrations, and equipment vendor SEC disclosures. Customs data on lyophilization system trade flows and bottom-up capacity buildout tracking across North Carolina, Bavaria, and Jiangsu provinces supported top-down market sizing triangulation.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning dryer architecture, nucleation technology tier, end-user category, and application stability requirements. CAGRs derived from equipment replacement cycle analysis, capacity expansion announcements, and regulatory timeline modeling. Forecast inputs incorporated EMA Annex 1 implementation schedules, EU F-Gas Regulation phase-out deadlines, and NMPA biologics stability protocol evolution.
Stress conditions across nickel price volatility, FDA validation timeline extensions, and continuous platform regulatory acceptance velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding replacement cycle compression and technology substitution thresholds. Cross-checking against pharmaceutical capital expenditure disclosures and CMO facility commissioning announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Pharmaceutical Manufacturing Market
Pharmaceutical Equipment
Global Pharmaceutical Granulation Equipment Market
Pharmaceutical Equipment
Middle East and Africa Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Pharmaceutical Sterilization Equipment Market
Pharmaceutical Equipment
ASEAN Contract Development and Manufacturing Organization (CDMO) Market
Pharmaceutical Equipment
Lyophilization Equipment and Services Market
Pharmaceutical Equipment
Automated Radiosynthesis Modules Market
Pharmaceutical Equipment
Investigational New Drug CDMO Market
Pharmaceutical Equipment
Global Rotary Tablet Press Market
Pharmaceutical Equipment
Sterile Fill-Finish Process Simulation and Media Fill Test Equipment Market
Pharmaceutical Equipment
CMO/CDMO Market
Pharmaceutical Equipment
Europe Pharmaceutical Isolator Market
Pharmaceutical Equipment
Pharmaceutical Anti-Counterfeiting Technologies Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Packaging Market
Pharmaceutical Equipment
Asia-Pacific CDMO Market
Pharmaceutical Equipment
Pharmaceutical Incubators Market