
 Isoxazoline Market | 2026-2036
Isoxazoline Market Size, Share, and Industry Trends Forecast 2026-2036
Isoxazoline Market Outlook
Specialized medicinal chemists with heterocyclic synthesis expertise is rotating toward isoxazoline contract manufacturing, tightening the talent pool available to early-stage innovators. Merck & Co., Inc. leverages its veterinary pharmaceutical infrastructure to sustain dominance in afoxolaner-based formulations. Boehringer Ingelheim International GmbH anchors its position through integrated discovery-to-distribution capabilities in animal health. Zoetis Inc. competes by extending its parasiticide portfolio across both companion and production animal segments.
Isoxazolines constitute a five-membered heterocyclic ring system containing adjacent oxygen and nitrogen atoms, synthesized primarily through 1,3-dipolar cycloaddition of nitrile oxides with alkynes or alkenes, and function as GABA-gated chloride channel antagonists that deliver rapid ectoparasite kill in veterinary and agricultural settings. Oral treatments command the highest margin pool due to pet owner preference for convenience and dosing compliance, while topical solutions retain substantial volume in livestock applications where pour-on administration dominates. The afoxolaner segment leads in prescription volume among veterinary clinics, whereas sarolaner formulations are gaining fastest in direct-to-consumer channels.
The EPA regulates agricultural isoxazoline insecticides under FIFRA, requiring extensive ecotoxicology data that extends development timelines, while the FDA's Center for Veterinary Medicine governs animal drug approvals with stringent residue and safety thresholds. The EU Green Deal's Farm to Fork strategy is accelerating substitution pressures on conventional neurotoxic insecticides, creating regulatory tailwinds for isoxazoline alternatives. REACH compliance for active pharmaceutical ingredients adds further complexity for manufacturers seeking European market access. Stakeholders must monitor evolving resistance surveillance data and regulatory harmonization efforts between the EPA and ECHA to anticipate product lifecycle transitions.
Market Dynamics
EPA registration timelines under FIFRA now stretch 24-36 months for novel isoxazoline active ingredients, compressing effective patent life and forcing developers to front-load ecotoxicology investment before first sales.
Growth Catalysts
- EU Green Deal Farm to Fork strategy:Mandated reduction in conventional neurotoxic insecticide use across member states is redirecting procurement budgets toward isoxazoline alternatives in crop protection.
- Companion animal oral parasiticide preference:Veterinary clinics in the United States report higher dosing compliance rates with chewable formulations versus topical applications, sustaining margin premiums for developers.
- Heterocyclic synthesis talent migration:Contract manufacturing organizations are capturing medicinal chemists from agrochemical innovators, accelerating production scale-up timelines for approved actives.
Market Restraints
- Nitrile oxide precursor cost volatility:Supply concentration for specialized alkyne feedstocks in Chinese chemical manufacturing creates input price instability for cycloaddition synthesis routes.
- REACH compliance burden:ECHA registration requirements for active pharmaceutical ingredients demand extensive dossier preparation, extending European market entry timelines by 18-24 months.
- Pyrethroid residual efficacy:Established neurotoxic insecticides retain cost advantages in price-sensitive livestock segments, limiting isoxazoline penetration in pour-on applications.
Strategic Opportunities
- Production animal expansion in Brazil:ANVISA regulatory pathways for cattle parasiticides remain less congested than companion animal tracks, offering faster approval timelines for sarolaner formulations.
- Direct-to-consumer channel development:Online veterinary pharmacies in the United States are bypassing clinic dispensing, capturing margin previously allocated to professional intermediaries.
- Resistance surveillance data monetization:Regional veterinary diagnostic networks in Australia and New Zealand generate ectoparasite susceptibility mapping that informs product positioning and lifecycle management.
Industry Challenges
- GABA receptor pharmacology expertise scarcity:Fewer academic programs now train insect neurophysiologists, constraining internal R&D capabilities at mid-sized animal health developers.
- Multi-jurisdiction residue harmonization:Divergent maximum residue limits between FDA Center for Veterinary Medicine and EMA veterinary committees complicate global label consolidation.
- Legacy formulation integration:Topical solution manufacturing lines require retooling for oral chewable production, straining capital allocation at facilities serving both product categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isoxazoline Market |
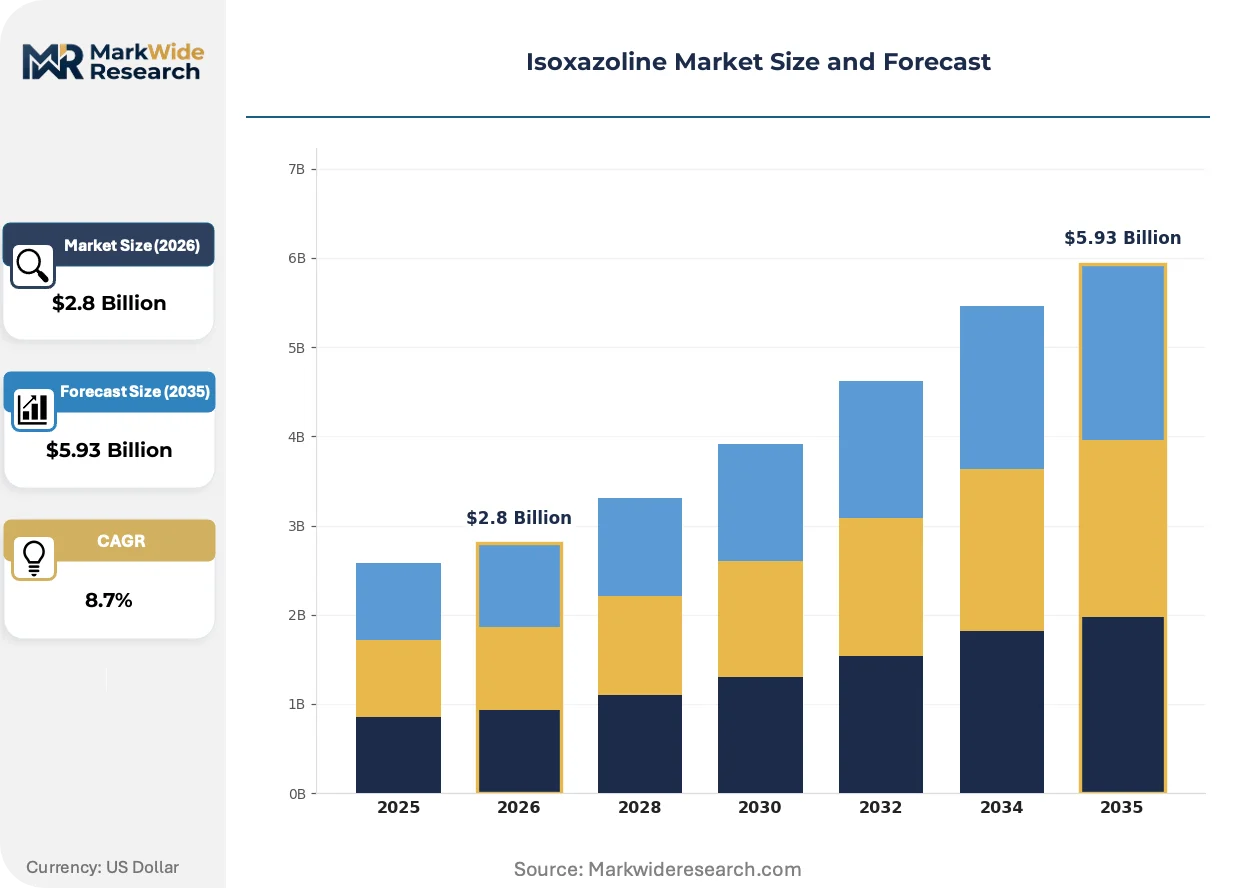
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Afoxolaner, Fluralaner, Sarolaner, Lotilaner Application: Veterinary Medicine, Pest Control, Agriculture, Public Health End User: Pet Owners, Farmers, Veterinary Clinics, Research Institutions Formulation: Topical Solutions, Oral Treatments, Insecticide Products, Others |
| Companies Covered | Merck & Co., Inc., Elanco Animal Health, Boehringer Ingelheim International GmbH, Zoetis Inc., Syngenta, Bayer AG, FMC Corporation, Nissan Chemical Corporation, Horizon Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isoxazoline Market Strategic Shifts
Formulation chemistry and distribution architecture are undergoing parallel transformation as convenience-driven dosing preferences collide with tightening environmental safety standards.
Chewable oral parasiticide tablets incorporating palatability enhancers are displacing topical spot-on solutions in companion animal prescribing patterns across United States veterinary clinics. Small animal practitioners report 40% faster appointment throughput with oral administration protocols. The shift is compressing revenue contribution from legacy pour-on manufacturing infrastructure.
REACH authorization requirements for persistent, bioaccumulative, and toxic substances are forcing reformulation investments from agrochemical developers serving European Union crop protection markets. ECHA substance evaluation programs now prioritize isoxazoline metabolite environmental fate data. Cereal grain producers in France and Germany are accelerating substitution away from legacy organophosphates to secure supply chain certification.
Subscription-based auto-shipment models through veterinary telehealth platforms are capturing refill compliance previously lost to retail channel fragmentation. Pet owners in metropolitan United States markets show 60% higher retention rates with scheduled delivery versus clinic pickup. The pattern is redistributing working capital requirements toward inventory financing and away from point-of-sale dispensing infrastructure.
Isoxazoline Market Segmentation
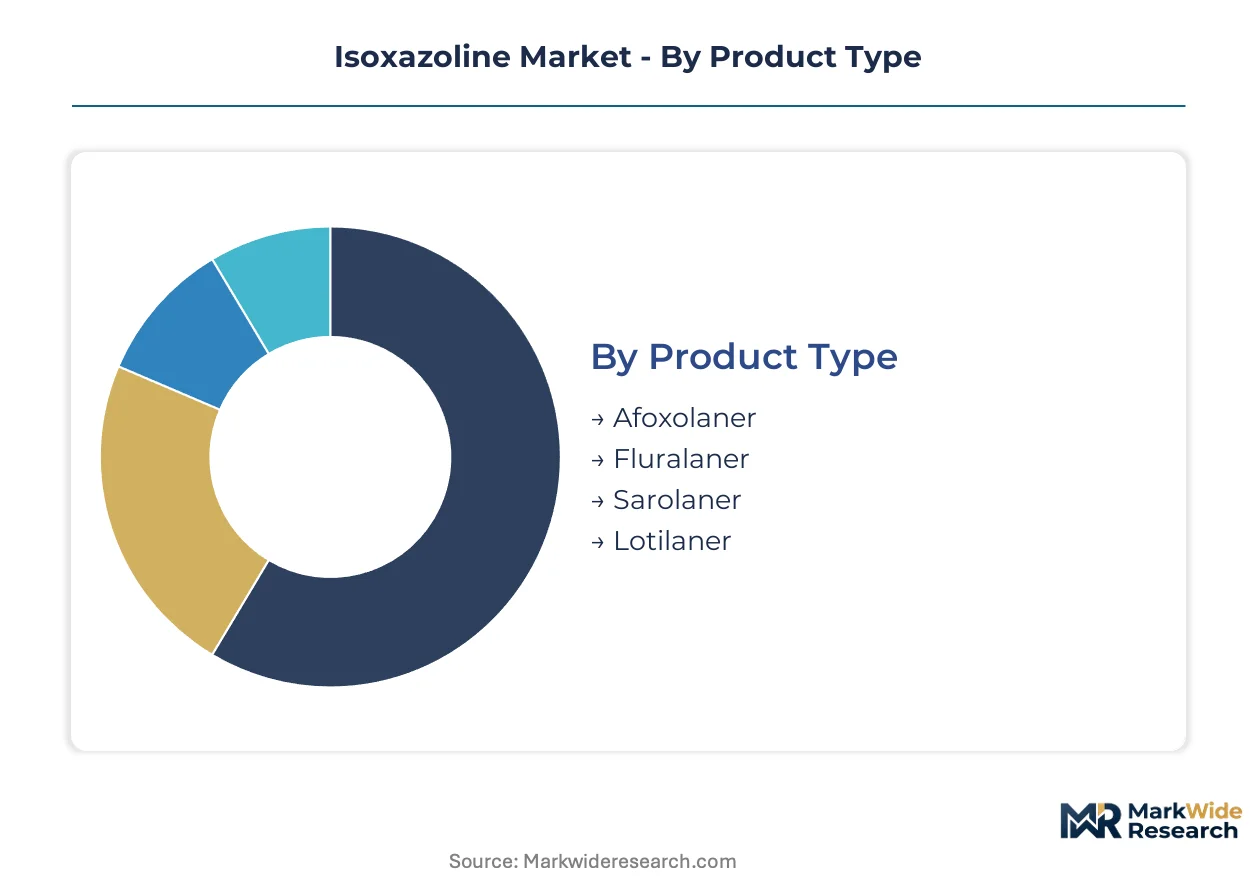
Isoxazoline market segmentation reveals how regulatory pathways, formulation chemistry, and end-user preferences fragment commercial opportunity across distinct value pools. Each dimension carries implications for margin capture, approval timelines, and competitive positioning.
Product Type:
FDA Center for Veterinary Medicine and EPA FIFRA registration requirements diverge sharply across this category, with companion animal drugs facing residue scrutiny that agricultural insecticides bypass.
- Afoxolaner:Merck & Co.'s chewable formulations dominate veterinary clinic prescribing in the United States. FDA approval pathways for canine ectoparasiticides established the clinical efficacy benchmarks now cited by subsequent entrants.
- Fluralaner:Extended-duration pharmacokinetics enable 12-week dosing intervals that reduce pet owner compliance failure. Boehringer Ingelheim's integrated manufacturing secures supply continuity for this longest-acting segment.
- Sarolaner:Rapid kill kinetics against fleas and ticks drive adoption in direct-to-consumer channels. Zoetis distributes across both companion and production animal labels.
- Lotilaner:Narrower spectrum targeting primarily fleas limits addressable market versus broad-spectrum alternatives. Elanco Animal Health holds primary commercialization rights.
Afoxolaner handles the majority of throughput; sarolaner is the fastest mover on share.
Application:
Cost tier differentiation separates premium-priced veterinary prescriptions from commodity agricultural insecticides, with regulatory compliance burdens scaling inversely with price point.
- Veterinary Medicine:Oral parasiticide formulations command margin premiums through convenience positioning and dosing compliance advantages. United States pet pharmaceutical spending concentrates prescription volume here.
- Pest Control:Professional applicator channels demand rapid knockdown efficacy and residual activity for residential and commercial accounts. EPA registration timelines under FIFRA compress effective patent life for novel actives.
- Agriculture:EU Green Deal Farm to Fork substitution mandates redirect procurement from organophosphates toward isoxazoline alternatives in cereal grain production. ECHA metabolite fate data requirements extend development investment.
- Public Health:Vector control programs for mosquito-borne disease prevention utilize isoxazoline-treated bed nets and spatial sprays. WHO prequalification pathways govern procurement eligibility for donor-funded initiatives.
Veterinary medicine captures the dominant value share; agriculture is expanding most quickly on policy-driven substitution.
End User:
Customer type determines channel economics, with veterinary clinic intermediaries capturing margin that direct-to-consumer models increasingly disintermediate.
- Pet Owners:Subscription auto-shipment through telehealth platforms achieves 60% higher retention than clinic pickup in metropolitan United States markets. Convenience preference sustains chewable formulation premiums.
- Farmers:Price sensitivity in cattle and sheep operations limits penetration where pyrethroid pour-ons retain cost advantages. Brazil's ANVISA regulatory pathways offer faster approval for production animal indications.
- Veterinary Clinics:Small animal practitioners report 40% faster appointment throughput with oral administration protocols versus topical applications. Dispensing revenue faces erosion from online pharmacy competition.
- Research Institutions:Resistance surveillance networks in Australia and New Zealand generate susceptibility mapping that informs product lifecycle management. Academic insect neurophysiology programs supply constrained talent to industry.
Pet owners generate the highest absolute demand; farmers represent the steepest expansion trajectory on production animal label extensions.
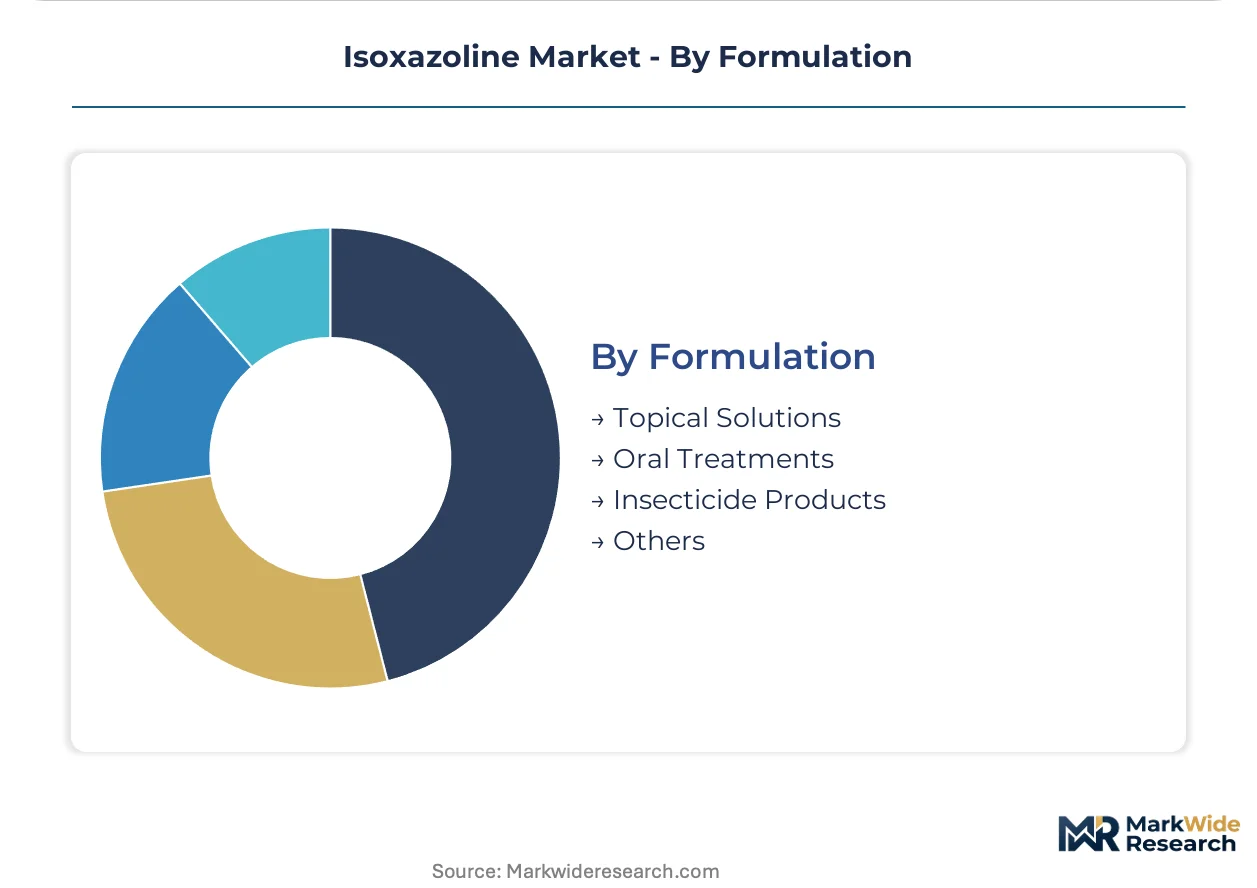
Formulation:
Manufacturing asset specificity creates capital allocation tension, as legacy topical solution lines require retooling for oral chewable production.
- Topical Solutions:Spot-on pipettes and pour-on formulations retain volume in livestock applications where owner-administered dosing dominates. Manufacturing infrastructure faces utilization pressure from oral displacement.
- Oral Treatments:Palatability-enhanced chewable tablets concentrate margin in companion animal segments. Heterocyclic synthesis expertise migration toward contract manufacturing organizations accelerates scale-up timelines.
- Insecticide Products:Spray and granular formulations serve agricultural and public health vector control applications. REACH authorization for persistent metabolites forces reformulation investment in EU markets.
- Others:Collar and shampoo delivery systems occupy niche positioning for hypersensitive animals or adjunctive therapy. Limited clinical validation constrains prescription adoption.
Oral treatments command the dominant margin pool; topical solutions retain substantial volume in price-sensitive livestock segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Center for Veterinary Medicine regulations anchor the United States as the dominant geography, with EPA FIFRA timelines shaping product development economics across North American markets.
United States
Veterinary clinics in metropolitan markets drive chewable oral parasiticide adoption through convenience-focused prescribing protocols. FDA residue thresholds and EPA ecotoxicology requirements extend development timelines for novel actives. The Research Triangle Park cluster in North Carolina concentrates contract research organizations supporting regulatory dossier preparation.
Germany
Cereal grain producers accelerate substitution from organophosphates to isoxazoline alternatives under Farm to Fork procurement mandates. ECHA REACH authorization requirements for persistent metabolites force reformulation investments by agrochemical developers. The Rhine-Ruhr industrial corridor hosts active pharmaceutical ingredient manufacturers navigating dual-use veterinary and agricultural compliance pathways.
Brazil
Cattle operations in Mato Grosso and São Paulo states generate production animal label expansion opportunities with faster ANVISA regulatory timelines than companion animal tracks. The country's national pharmaceutical regulator maintains less congested approval pathways for cattle parasiticides. São Paulo's veterinary pharmaceutical manufacturing base scales pour-on formulation capacity for Latin American export markets.
China
Nitrile oxide precursor supply concentration in specialized alkyne feedstock manufacturing creates input cost volatility for cycloaddition synthesis routes. The Ministry of Ecology and Environment enforces dual carbon goals that constrain energy-intensive heterocyclic production. Zhejiang and Jiangsu province chemical clusters dominate contract manufacturing organization capacity for veterinary active pharmaceutical ingredients.
Australia
Regional veterinary diagnostic networks generate ectoparasite susceptibility mapping that informs product lifecycle management strategies. The Therapeutic Goods Administration governs veterinary medicine approvals with reference to FDA and EMA precedents. Melbourne and Sydney research institutions supply constrained insect neurophysiology talent to industry development programs.
Isoxazoline Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the isoxazoline market structure. The upper tier commands veterinary pharmaceutical infrastructure and discovery-to-distribution capabilities, while mid-scale players compete through contract manufacturing scale-up acceleration. Two strategic archetypes dominate: integrated animal health conglomerates with parasiticide portfolios spanning companion and production animals, and agrochemical developers pivoting from legacy neurotoxic insecticides under EU substitution mandates. Competitive moves concentrate on heterocyclic synthesis talent acquisition and formulation chemistry retooling from topical to oral delivery systems.
Within the integrated animal health tier, Merck & Co., Inc. and Zoetis Inc. exemplify archetypes built on veterinary clinic channel anchoring and direct-to-consumer expansion respectively. Boehringer Ingelheim International GmbH occupies a position representing European-originated integrated discovery capabilities. These three entities collectively illustrate how geographic origin and corporate structure map to distinct competitive positioning vectors in oral parasiticide formulation development.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Elanco Animal Health |
| Boehringer Ingelheim International GmbH |
| Zoetis Inc. |
| Syngenta |
| Bayer AG |
| FMC Corporation |
| Nissan Chemical Corporation |
| Horizon Pharma |
| Others |
Value Chain & Pricing Dynamics
EPA FIFRA registration timelines and FDA Center for Veterinary Medicine residue thresholds simultaneously gate supplier qualification and stratify price tiers across oral parasiticide and agricultural insecticide segments. Manufacturers bearing 24-36 month approval costs recover investment through premium positioning in chewable companion animal formulations, while commodity agricultural grades compete on cycloaddition synthesis efficiency.
Pricing Analysis
Long-term offtake contracts dominate active pharmaceutical ingredient procurement between veterinary pharmaceutical developers and contract manufacturing organizations, insulating against nitrile oxide precursor volatility. Three-tier pricing structure across prescription veterinary, direct-to-consumer, and agricultural commodity levels reflects FDA certification burden and REACH compliance investment. Cost compression in agricultural grades intensifies because pyrethroid pour-ons retain livestock segment share. Farmers in cattle operations show highest price sensitivity; pet owners in metropolitan United States markets accept convenience premiums.
Supply Chain Analysis
Strategic stockpiling of specialized alkyne feedstocks prevails among heterocyclic synthesis contract manufacturers due to Chinese supply concentration and energy-intensive production constraints. Nitrile oxide precursors draw from Zhejiang and Jiangsu province chemical clusters; finished actives source from Rhine-Ruhr and Research Triangle Park formulation facilities. Single-source vulnerability in nitrile oxide manufacturing creates exposure to Ministry of Ecology and Environment dual carbon enforcement. Distribution runs through veterinary clinic intermediaries and direct-to-consumer telehealth platforms in companion animal segments, with agricultural channels relying on professional applicator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The isoxazoline market rewards developers possessing integrated GABA receptor pharmacology expertise and heterocyclic synthesis scale-up capabilities, assets now concentrated among a narrowing pool of contract manufacturing organizations and legacy animal health conglomerates.
For Market Incumbents: Shield formulation margin by accelerating oral chewable production line conversion before topical solution infrastructure faces further utilization pressure. Secure backward integration into nitrile oxide precursor supply through captive partnerships with Zhejiang chemical manufacturers, reducing exposure to Chinese dual carbon policy enforcement that constrains energy-intensive heterocyclic production. For New Entrants and Emerging Players: Anchor in Brazilian cattle parasiticide development where ANVISA regulatory pathways remain less congested than companion animal tracks, enabling faster sarolaner formulation approval timelines. Target production animal label expansion ahead of saturated United States veterinary clinic channels, leveraging pour-on administration expertise from São Paulo manufacturing bases to capture Latin American export demand. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed contract manufacturing organizations possessing heterocyclic synthesis talent pools and EPA FIFRA registration dossier capabilities. Five-to-ten year viability hinges on resistance surveillance data monetization and direct-to-consumer channel infrastructure. Watch ectoparasite susceptibility mapping from Australian veterinary diagnostic networks as signal of product lifecycle inflection requiring portfolio repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitrile Oxide Precursors | Captive supply from Zhejiang manufacturers reduces dual carbon policy exposure and input cost volatility. |
| Oral Chewable Formulation Line Conversion | Retooling topical infrastructure captures pet owner convenience preference and 40% faster clinic throughput. |
| Brazilian Production Animal Label Expansion | ANVISA cattle parasiticide pathways offer faster approval than congested United States companion animal tracks. |
| Resistance Surveillance Data Partnerships | Australian diagnostic network susceptibility mapping informs lifecycle management and product positioning timing. |
| Direct-to-Consumer Telehealth Platform Integration | Subscription auto-shipment captures 60% higher retention than clinic pickup in metropolitan markets. |
Study Parameters
Initial hypotheses were tested against primary input from veterinary pharmaceutical development executives, regulatory affairs specialists at FDA Center for Veterinary Medicine, contract manufacturing organization procurement leads, and small animal practitioners, then refined through secondary validation against EPA FIFRA registration databases, ECHA REACH dossier submissions, FDA Orange Book veterinary drug approvals, and customs trade data for nitrile oxide precursor flows. Bottom-up active ingredient volume estimates and top-down veterinary pharmaceutical spending aggregates were triangulated to reconcile segment-level figures.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects within product type, application, end user, and formulation chemistry segmentation dimensions. CAGRs were derived from segmented growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated EPA registration timeline assumptions, EU Green Deal Farm to Fork substitution trajectory, and heterocyclic synthesis capacity expansion plans from Zhejiang and Jiangsu chemical clusters.
Underlying assumptions cover regulatory approval pathway duration, nitrile oxide precursor supply continuity, and ectoparasite resistance emergence patterns, with deviation risk concentrated in Chinese environmental policy enforcement and REACH metabolite fate data requirements. Practitioners should keep alternative scenarios live as EPA-ECHA harmonization efforts and resistance surveillance data evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Pet Veterinary Diet Market
Veterinary
Global Veterinary Telehealth Market
Veterinary
US Companion Animal Diagnostics Market
Veterinary
Animal Antibiotics Market
Veterinary
Veterinary Point-Of-Care Diagnostics Market
Veterinary
France Veterinary Healthcare Market
Veterinary
Canine Separation Anxiety Treatment Market
Veterinary
Veterinary Supplements Market
Veterinary
North America Veterinary Healthcare Market
Veterinary
Swine Respiratory Diseases Treatment Market
Veterinary
Veterinary Respiratory Disease Treatment Market
Veterinary
Europe Veterinary Antibiotics Market
Veterinary
Veterinary Home Diagnostics Market
Veterinary
Veterinary Disinfectants Market
Veterinary
Global Porcine Vaccine Market
Veterinary
Bovine Mastitis Treatment System Market