
 Veterinary Thermography Market | 2026-2036
Veterinary Thermography Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Thermography Market Outlook
Aftermarket service revenue from software updates and thermal calibration is narrowing as manufacturers bundle recurring analytics into upfront hardware contracts. FLIR Systems leverages its defense-industry sensor heritage to dominate high-resolution veterinary camera supply. Thermoteknix Systems Ltd. anchors its position through ruggedized designs purpose-built for farm and stable environments. Digatherm specializes in species-specific thermal databases that differentiate its diagnostic platform from generic imaging tools.
Veterinary thermography employs infrared detectors measuring emitted radiation in the 7-14 micrometer wavelength band to map superficial temperature distributions across animal integument, primarily enabling early detection of inflammation, lameness, and circulatory dysfunction before visible clinical signs manifest. Thermal cameras capture this data with typical thermal sensitivity below 50 millikelvin, while software solutions apply proprietary algorithms to normalize readings against ambient conditions and coat characteristics. Handheld devices occupy the largest installed base due to their maneuverability around restrained and unrestrained animals, though software solutions represent the fastest-expanding margin pool as clinics shift toward subscription-based diagnostic support. Research applications remain comparatively mature, constrained by limited funding for veterinary-specific imaging studies relative to human medical counterparts.
The FDA Center for Veterinary Medicine oversees diagnostic device marketing claims, compelling manufacturers to substantiate efficacy data or limit promotional language to non-diagnostic positioning. ISO 18434 standards for thermographic condition monitoring provide voluntary benchmarks that quality-conscious clinics increasingly reference during procurement evaluations. Stakeholders must monitor how veterinary telemedicine regulations evolve, as remote thermal image interpretation by off-site specialists could unlock rural market penetration or trigger new licensure requirements that reshape service delivery models.
Market Dynamics
Veterinary thermography is experiencing a structural inflection as diagnostic workflows migrate from episodic imaging toward continuous monitoring architectures. The convergence of cloud-native software platforms with handheld thermal hardware is compressing the traditional separation between image acquisition and clinical interpretation.
Growth Catalysts
- Equine Sports Medicine Expansion:Thoroughbred racing circuits in Kentucky and Texas are mandating pre-competition thermal screening protocols, creating institutional demand for standardized imaging systems.
- FDA Center for Veterinary Medicine Guidance Evolution:Clarified marketing pathways for diagnostic claims are enabling manufacturers to position thermography as a clinical decision-support tool rather than screening-only technology.
- Cloud-Based Image Archiving:Subscription telemetry platforms allow multi-site veterinary networks to centralize thermal data repositories, reducing per-clinic infrastructure burdens.
Market Restraints
- Indium Gallium Arsenide Detector Costs:High-resolution focal plane arrays remain import-dependent for most manufacturers, exposing margins to rare earth supply volatility.
- Interpretation Skill Concentration:Certified veterinary thermographers cluster disproportionately in North American and Western European academic centers, limiting service scalability.
- ISO 18434 Compliance Burden:Voluntary thermographic condition monitoring standards require substantial calibration documentation that smaller practices struggle to maintain.
Strategic Opportunities
- Rural Telemedicine Corridors:Regulatory frameworks governing remote image interpretation by off-site specialists are stabilizing, unlocking penetration into underserved agricultural regions.
- Production Animal Integration:Dairy and feedlot operators are piloting automated thermal monitoring for mastitis and respiratory detection, expanding beyond companion animal applications.
- Species-Specific Algorithm Licensing:Proprietary thermal pattern databases for exotic and wildlife species represent uncaptured value pools distinct from generic equine and canine datasets.
Industry Challenges
- Veterinary Radiologist Training Pipeline:Cross-certification requirements for thermal interpretation lack standardization across state veterinary boards, creating credentialing friction.
- Legacy Practice Management System Integration:Thermal imaging platforms require custom API development to synchronize with entrenched electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Thermography Market |
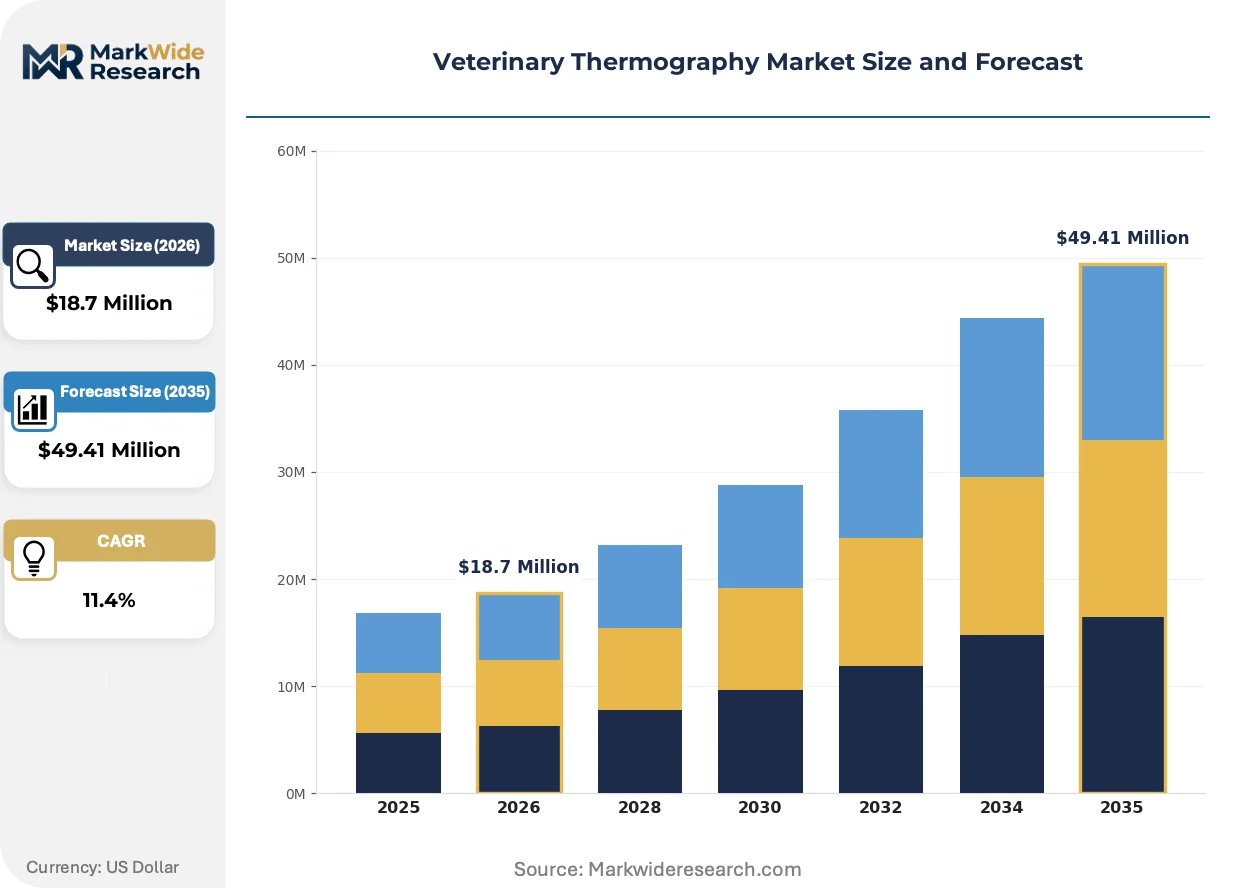
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $49.41 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Thermal Cameras, Software Solutions, Accessories Application: Diagnostics, Pain Management, Performance Monitoring, Research End User: Veterinary Clinics, Research Organizations, Animal Shelters, Mobile Services Technology: Infrared Imaging, Digital Thermography, Software Analysis, Image Processing |
| Companies Covered | FLIR Systems, Infrared Cameras Inc., Thermoteknix Systems Ltd., ICI Infrared Cameras Inc., Digatherm, Meditherm Inc., VetTherm, Infratec GmbH, Testo SE & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Thermography Market Strategic Shifts
Diagnostic workflows are fragmenting across acquisition, interpretation, and archiving layers, with each layer attracting specialized technology providers. This modularization is accelerating vendor repositioning and partnership formations.
Artificial intelligence-assisted pattern recognition is virtualizing the diagnostic interpretation layer that historically required specialist consultation. Large animal hospitals in the United States are deploying cloud-native algorithms that flag thermal anomalies automatically, reducing specialist review queues by half. This virtualization is compressing the value chain between hardware manufacturers and end-user clinics, marginalizing standalone interpretation services.
EMA's evolving posture on software-as-a-medical-device classification is forcing European manufacturers to substantiate algorithm training datasets across multiple species. The industrial consequence is a documentation burden that favors established players with historical image libraries. German and French veterinary schools are responding by launching multi-institutional validation consortia to pool thermal datasets.
Subscription-based diagnostic support is displacing perpetual licensing for thermal analysis software. Mixed-animal practices in Australia and Canada are consolidating vendor relationships around integrated hardware-software contracts that bundle calibration, updates, and remote specialist access. This bundling concentrates procurement authority at the network level rather than individual clinic ownership.
Veterinary Thermography Market Segmentation
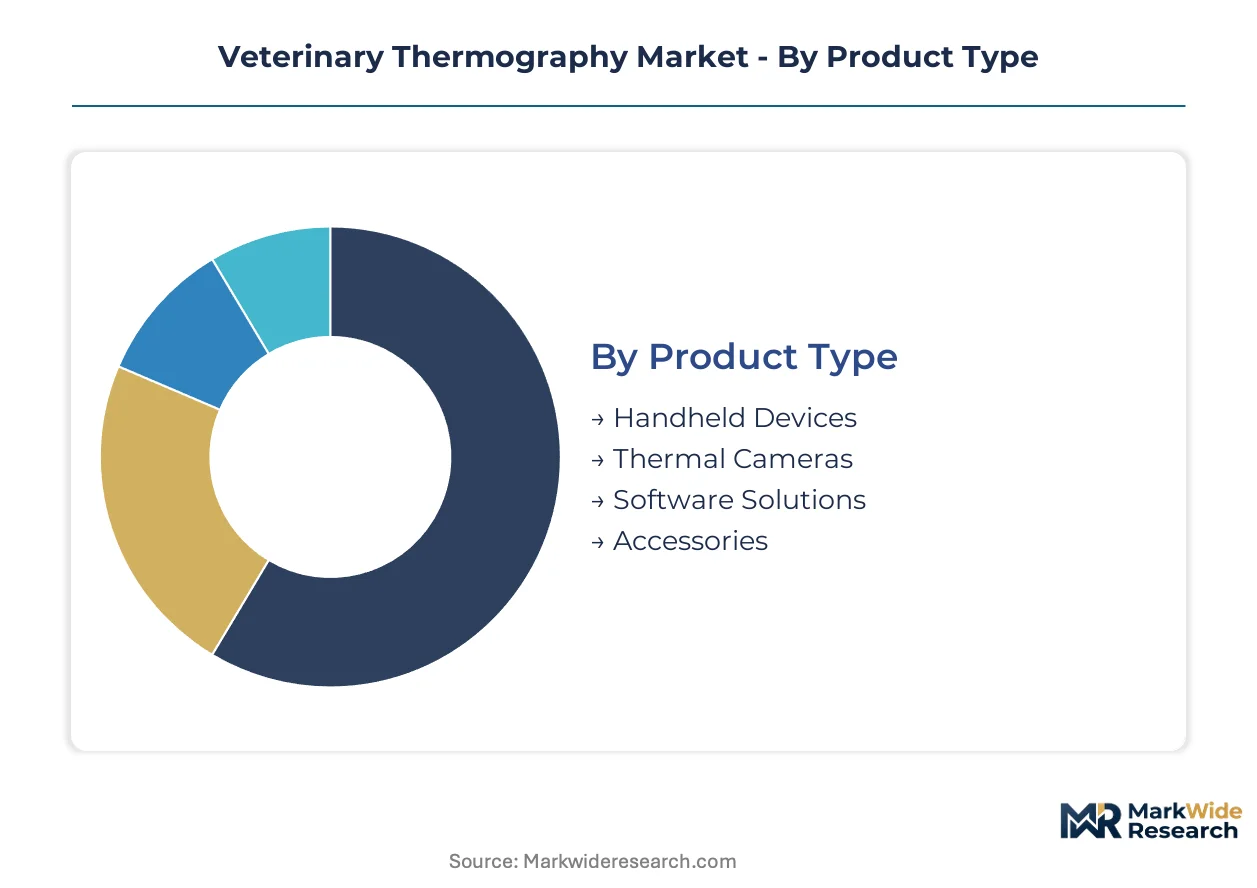
Veterinary thermography segments exhibit sharply divergent replacement cycles, with hardware platforms requiring multi-year capital commitments while software layers refresh annually. Understanding these temporal patterns illuminates where procurement budgets concentrate and where vendor switching costs accumulate.
Product Type:
Handheld devices and thermal cameras turn over on 5-7 year depreciation schedules, whereas software solutions refresh through monthly or annual subscription renewals, creating fundamentally different customer lock-in dynamics.
- Handheld Devices:Portable thermal acquisition units with maneuverable form factors designed for restrained and unrestrained animal positioning. Demand concentrates across Texas and Kentucky equine corridors where pre-competition screening protocols mandate institutional deployment.
- Thermal Cameras:Fixed-mount or tripod-based systems delivering sub-50 millikelvin thermal sensitivity for clinical stationary imaging. Research organizations in North American academic centers anchor procurement volumes for longitudinal inflammation studies.
- Software Solutions:Cloud-native platforms applying proprietary algorithms to normalize thermal readings against ambient conditions and coat characteristics. Multi-site veterinary networks in Australia and Canada are consolidating around bundled hardware-software contracts that embed recurring analytics.
- Accessories:Calibration targets, protective housings, and species-specific positioning aids. Farm and stable operators prioritize ruggedized designs purpose-built for dusty, high-humidity environments.
Handheld devices anchor the volume base while software solutions gain share at the steepest rate.
Application:
Pain management applications command premium pricing due to repeat-visit revenue models, whereas research applications face constrained funding pipelines relative to human medical imaging counterparts.
- Diagnostics:Early detection of inflammation, lameness, and circulatory dysfunction before visible clinical signs manifest. Thoroughbred racing circuits are mandating standardized thermal screening, institutionalizing demand across competitive equine venues.
- Pain Management:Thermal tracking of treatment response across musculoskeletal and neuropathic conditions. Specialty equine hospitals leverage continuous monitoring architectures to document rehabilitation progression.
- Performance Monitoring:Pre- and post-exertion thermal mapping to optimize training loads and detect overuse patterns. Professional sport horse facilities integrate automated screening into daily barn workflows.
- Research:Controlled studies validating thermal correlation with histopathological findings. Limited veterinary-specific imaging funding constrains expansion relative to companion animal clinical applications.
Diagnostics commands the installed base while pain management expands most quickly as clinics adopt subscription-based outcome tracking.
End User:
Veterinary clinics and mobile services operate on divergent capital intensity models, with fixed facilities amortizing equipment over higher patient volumes while mobile operators prioritize lightweight, rapid-deployment hardware.
- Veterinary Clinics:Fixed-site facilities integrating thermal imaging into standard diagnostic workflows. Mixed-animal practices are displacing perpetual software licenses with subscription contracts that bundle calibration and remote specialist access.
- Research Organizations:Academic and institutional laboratories conducting species-specific validation studies. German and French veterinary schools are launching multi-institutional consortia to pool thermal datasets for algorithm training.
- Animal Shelters:Non-profit and municipal facilities employing thermography for intake health screening and outbreak detection. Budget constraints favor lower-resolution systems with simplified interpretation interfaces.
- Mobile Services:Ambulatory providers delivering on-farm and at-event thermal screening. Rural telemedicine corridors are stabilizing regulatory frameworks for remote image interpretation, unlocking agricultural region penetration.
Veterinary clinics anchor the volume base while mobile services gain share at the steepest rate.
Technology:
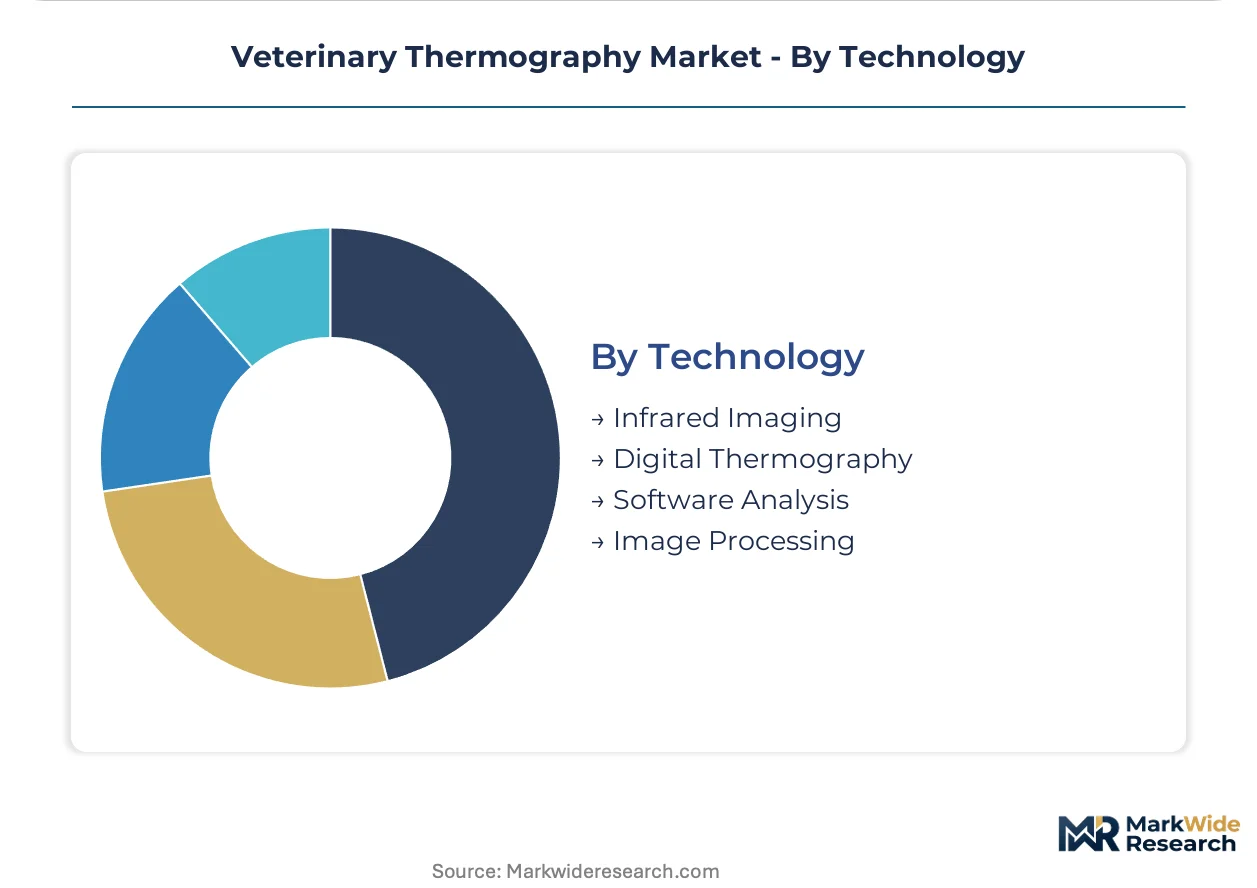
Infrared imaging hardware requires substantial upfront capital and rare earth supply exposure, while software analysis layers scale with minimal marginal cost and attract recurring revenue multiples.
- Infrared Imaging:Detector arrays capturing emitted radiation in the 7-14 micrometer wavelength band. Indium gallium arsenide focal plane arrays remain import-dependent for most manufacturers, exposing margins to supply volatility.
- Digital Thermography:Solid-state sensor platforms with embedded processing for real-time temperature mapping. Handheld configurations dominate due to maneuverability advantages around restrained animals.
- Software Analysis:Algorithmic platforms applying artificial intelligence-assisted pattern recognition to flag thermal anomalies automatically. Large animal hospitals in the United States are deploying cloud-native systems that reduce specialist review queues.
- Image Processing:Post-acquisition enhancement, normalization, and comparative overlay tools. ISO 18434 compliance documentation requirements favor established vendors with historical calibration libraries.
Infrared imaging anchors the volume base while software analysis gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across veterinary thermography markets. United States buyers absorb premium hardware costs through bundled software contracts, while emerging market clinics prioritize lower-resolution entry systems with simplified interfaces.
United States
Thoroughbred racing circuits in Kentucky and Texas mandate standardized pre-competition thermal screening, institutionalizing demand across competitive equine venues. The FDA Center for Veterinary Medicine clarified marketing pathways for diagnostic claims, enabling manufacturers to position thermography as clinical decision-support. Large animal hospitals in California deploy cloud-native algorithms that flag thermal anomalies automatically, reducing specialist review queues.
Germany
German veterinary schools anchor multi-institutional validation consortia pooling thermal datasets for algorithm training across equine and production animal species. The EMA's evolving posture on software-as-a-medical-device classification forces manufacturers to substantiate training datasets across multiple species. Bavarian dairy operators pilot automated thermal monitoring for mastitis detection, expanding applications beyond companion animals.
United Kingdom
Specialty equine hospitals in Newmarket leverage continuous monitoring architectures to document rehabilitation progression across musculoskeletal conditions. ISO 18434 compliance documentation requirements favor established vendors with historical calibration libraries. London-based mixed-animal practices displace perpetual software licenses with subscription contracts bundling calibration and remote specialist access.
Australia
Rural telemedicine corridors stabilize regulatory frameworks for remote image interpretation by off-site specialists, unlocking agricultural region penetration. The Therapeutic Goods Administration oversees diagnostic device classification for veterinary applications. Queensland mixed-animal practices consolidate vendor relationships around integrated hardware-software contracts that embed recurring analytics.
Canada
Health Canada regulates veterinary diagnostic device marketing claims, compelling efficacy substantiation or non-diagnostic promotional positioning. Ontario dairy and feedlot operators pilot automated thermal monitoring for respiratory detection in production herds. Alberta mobile veterinary services prioritize lightweight rapid-deployment hardware for on-farm screening across dispersed agricultural operations.
Veterinary Thermography Market Competitive Environment
Capability concentration sits with defense-industry heritage players possessing rare earth supply relationships; scale advantage sits with diversified instrumentation conglomerates with established veterinary distribution channels. The market structures around three tiers: premium sensor specialists, mid-market ruggedized hardware fabricators, and software-centric analytics platforms. Consolidation pressure runs through bundled hardware-software contracts that raise switching costs for multi-site veterinary networks. Geographic expansion and species-specific algorithm licensing represent the dominant competitive vectors as generic thermal databases commoditize.
Within the defense-heritage tier, FLIR Systems leverages sensor manufacturing scale accumulated through military contract execution. Thermoteknix Systems Ltd. exemplifies the ruggedized fabrication archetype with form factors purpose-built for farm and stable environments. Digatherm occupies a specialist position anchored on proprietary thermal pattern databases that differentiate diagnostic platforms from generic imaging tools. These three represent distinct capability positions rather than direct substitutability.
| Leading Market Players |
|---|
| FLIR Systems |
| Infrared Cameras Inc. |
| Thermoteknix Systems Ltd. |
| ICI Infrared Cameras Inc. |
| Digatherm |
| Meditherm Inc. |
| VetTherm |
| Infratec GmbH |
| Testo SE & Co. KGaA |
| Others |
Value Chain & Pricing Dynamics
Trans-Pacific air freight corridors connecting Shenzhen and Memphis absorb elevated fuel surcharges that cascade through detector assembly costs, compressing margins for manufacturers without captive rare earth sourcing while enabling premium pricing tiers for those with integrated supply control.
Pricing Analysis
Software subscription tiers anchored by calibration and remote specialist access now drive lifetime value capture, displacing transactional hardware-only sales. Three-tier pricing structure across premium, standard, and economy levels separates FLIR's defense-heritage sensor bundles from Thermoteknix's ruggedized farm-grade systems and entry-level shelter devices. Pricing pressure stems from bundled hardware-software contracts that concentrate procurement authority at multi-site veterinary networks. Mobile services in Alberta and Queensland exhibit highest price sensitivity due to capital constraints, while Kentucky equine hospitals absorb premiums for sub-50 millikelvin thermal sensitivity.
Supply Chain Analysis
Contract manufacturing for infrared detector arrays concentrates at Teledyne FLIR's Santa Barbara foundry and selected Taiwanese EMS providers with cleanroom capacity for focal plane assembly. German and Japanese precision optics houses supply germanium lenses, while Chinese rare earth processors control indium and gallium refinement. Single-source vulnerability runs through indium gallium arsenide substrate supply from Chinese state-owned refiners. Distribution runs through veterinary equipment distributors with field service capabilities, bypassing general medical imaging channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary thermography is crossing into platform economics as cloud-native algorithms virtualize diagnostic interpretation, with interoperability between thermal hardware and practice management systems becoming the decisive ecosystem battleground.
For Market Incumbents: Build switching-cost moats through embedded calibration telemetry that locks multi-site networks into recurring revenue streams. Acquire species-specific thermal database specialists before algorithm commoditization erodes differentiation. Defend against software-only entrants by deepening hardware-software bundling that raises replacement costs for installed handheld devices.
For New Entrants and Emerging Players: Brazilian and Argentine agricultural corridors present underpenetrated production animal monitoring opportunities where regulatory frameworks for remote interpretation remain nascent. Target dairy cooperative procurement committees with mastitis detection pilots that demonstrate ROI through reduced antibiotic use. Pursue white-label partnerships with established veterinary distributors lacking thermal imaging portfolios.
For Investors and Strategic Acquirers: Specialist algorithm developers with validated exotic species thermal pattern libraries offer asymmetric upside as wildlife and zoo medicine applications expand. Long-term viability hinges on regulatory clearance velocity across FDA Center for Veterinary Medicine and EMA software-as-medical-device pathways. Monitor FDA guidance publication cadence on diagnostic claims substantiation as inflection indicator for valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Species-Specific Algorithm Licensing | Captures uncaptured value pools in exotic and wildlife veterinary applications beyond generic equine datasets. |
| Cloud-Native Platform Integration | Compresses diagnostic interpretation layers and reduces specialist review queues at large animal hospitals. |
| Rural Telemedicine Corridor Expansion | Unlocks agricultural region penetration as regulatory frameworks for remote image interpretation stabilize. |
| Production Animal Monitoring Pilot Programs | Expands addressable market beyond companion animals into dairy mastitis and feedlot respiratory detection. |
| Multi-Institutional Validation Consortia | Pools thermal datasets across German and French veterinary schools to satisfy EMA algorithm training documentation. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA Center for Veterinary Medicine guidance documents, ISO 18434 calibration standards, and equine sports medicine protocol filings across Kentucky and Texas racing commissions. Primary interviews incorporated thermal camera procurement leads at mixed-animal practices, biomedical engineers at large animal hospitals, and distribution channel managers at veterinary equipment suppliers. Secondary validation drew from customs import records for indium gallium arsenide detectors, SEC filings of defense-heritage sensor manufacturers, and veterinary telemedicine regulatory dockets. Bottom-up unit economics for handheld devices and software subscriptions were triangulated against top-down market sizing through veterinary clinic density estimates.
Forecast inputs span product type segmentation across handheld devices, thermal cameras, software solutions, and accessories; application segmentation across diagnostics, pain management, performance monitoring, and research; and end-user segmentation across veterinary clinics, research organizations, animal shelters, and mobile services. CAGRs were derived through logistic adoption curves for cloud-native software and replacement cycle analysis for hardware depreciation schedules. Species-specific algorithm validation timelines and FDA diagnostic claims pathway evolution were modeled as scenario-weighted inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by software-only entrants or defense-industry sensor specialists pivoting into veterinary verticals would shift outcomes beyond modeled ranges. Quarterly review of FDA guidance publication velocity, EMA software-as-medical-device classification rulings, and indium spot pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Global Veterinary MRI Market
Veterinary
Spain Veterinary Healthcare Market
Veterinary
Feline Atopic Dermatitis Treatment Market
Veterinary
Veterinary Tables Market
Veterinary
Global Animal Vaccine Market
Veterinary
Canine Flu Therapeutics Market
Veterinary
Global Canine Influenza Vaccine Market
Veterinary
Global Animal Parasiticides Market
Veterinary
Mexico Veterinary Healthcare Market
Veterinary
Global Pet Obesity Management Market
Veterinary
Wearable Sensors for Animal Health Management Market
Veterinary
Global Veterinary Telehealth Market
Veterinary
Veterinary Antimicrobial Susceptibility Testing Market
Veterinary
Europe Veterinary Antibiotics Market
Veterinary
Asia-Pacific Veterinary Healthcare Market
Veterinary
United Kingdom Veterinary Healthcare Market