
 Animal Antibiotics Market | 2026-2036
Animal Antibiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Antibiotics Market Analytics
Veterinary Feed Directive compliance is redrawing competitive access for US-labeled products. Zoetis Services LLC leverages its diagnostic-to-therapeutic portfolio to sustain integrated livestock health programs. Boehringer Ingelheim International GmbH anchors European regulatory positioning through its EMA-authorized manufacturing network. Elanco Animal Health differentiates via channel control across North American veterinary clinics and farm-direct distribution.
Animal antibiotics comprise antimicrobial compounds administered to livestock and companion animals for therapeutic, prophylactic, or growth-promotion purposes, with formulations typically requiring specific mg/kg dosage calibration and withdrawal period adherence before slaughter. Tetracyclines occupy the largest production volume tier due to broad-spectrum efficacy and low manufacturing cost, while macrolides command premium positioning in respiratory disease protocols for cattle and swine. Injectable delivery mode leads in clinical veterinary settings where precise dosing and rapid bioavailability prove critical, whereas oral administration dominates animal farm applications for herd-scale metaphylaxis.
FDA's Veterinary Feed Directive, EMA's antimicrobial resistance strategy, and WHO's advisory on medically important antimicrobials collectively constrain product registration and label claims across major jurisdictions. These frameworks shift demand toward prescription-only veterinary oversight and narrow the pipeline for new growth-promotion indications. Stakeholders must monitor evolving residue tolerance thresholds and withdrawal period extensions that could disqualify existing inventory from export-certified supply chains.
Market Dynamics
Intensive livestock operations in Brazil, the United States, and China are expanding antimicrobial consumption as producers pursue tighter mortality control and faster weight gain in confined feeding systems. This production model intensification is colliding with tightening residue monitoring and prescription requirements across export markets.
Growth Catalysts
- Export Certification Demands:Brazil's beef and poultry processors require verified withdrawal compliance to access EU and Middle Eastern markets, pulling veterinary oversight services into integrated supply contracts.
- Metaphylaxis Protocols:Respiratory disease outbreaks in US cattle feedlots drive preventive antibiotic administration at herd scale, particularly macrolide-based regimens for bovine respiratory disease complexes.
- Companion Animal Expansion:Pet insurance penetration in urban China and South Korea is elevating therapeutic antibiotic use in small animal clinics beyond agricultural applications.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing for tetracyclines and penicillins clusters in Zhejiang and Shandong provinces, exposing formulators to single-source disruption risks.
- Regulatory Friction:EMA's antimicrobial resistance strategy is narrowing label indications for growth-promotion claims, forcing portfolio re-registration investments without revenue expansion.
- Substitution Threat:Phytogenic feed additives and probiotic formulations are capturing metaphylaxis budgets in European swine operations as antibiotic-free certification premiums widen.
Strategic Opportunities
- Vietnam and Indonesia Livestock Modernization:Backyard farm consolidation into commercial operations creates first-mover positioning for prescription veterinary service networks.
- Diagnostic-Therapeutic Integration:Rapid on-farm pathogen identification is enabling targeted antibiotic selection, reducing broad-spectrum overuse while preserving therapeutic efficacy.
- US Veterinary Feed Directive Compliance Services:Software platforms tracking prescription documentation and withdrawal calendars are penetrating independent feedlot operations previously served by generic distributors.
Industry Challenges
- Veterinary Prescriber Shortage:Rural areas in Australia's Queensland and the US Great Plains lack sufficient accredited veterinarians to meet FDA's Veterinary Feed Directive oversight mandates.
- Residue Testing Infrastructure:Export-certified slaughter facilities in Argentina and Uruguay require capital investment in high-performance liquid chromatography equipment to verify compliance with EU maximum residue limits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Antibiotics Market |
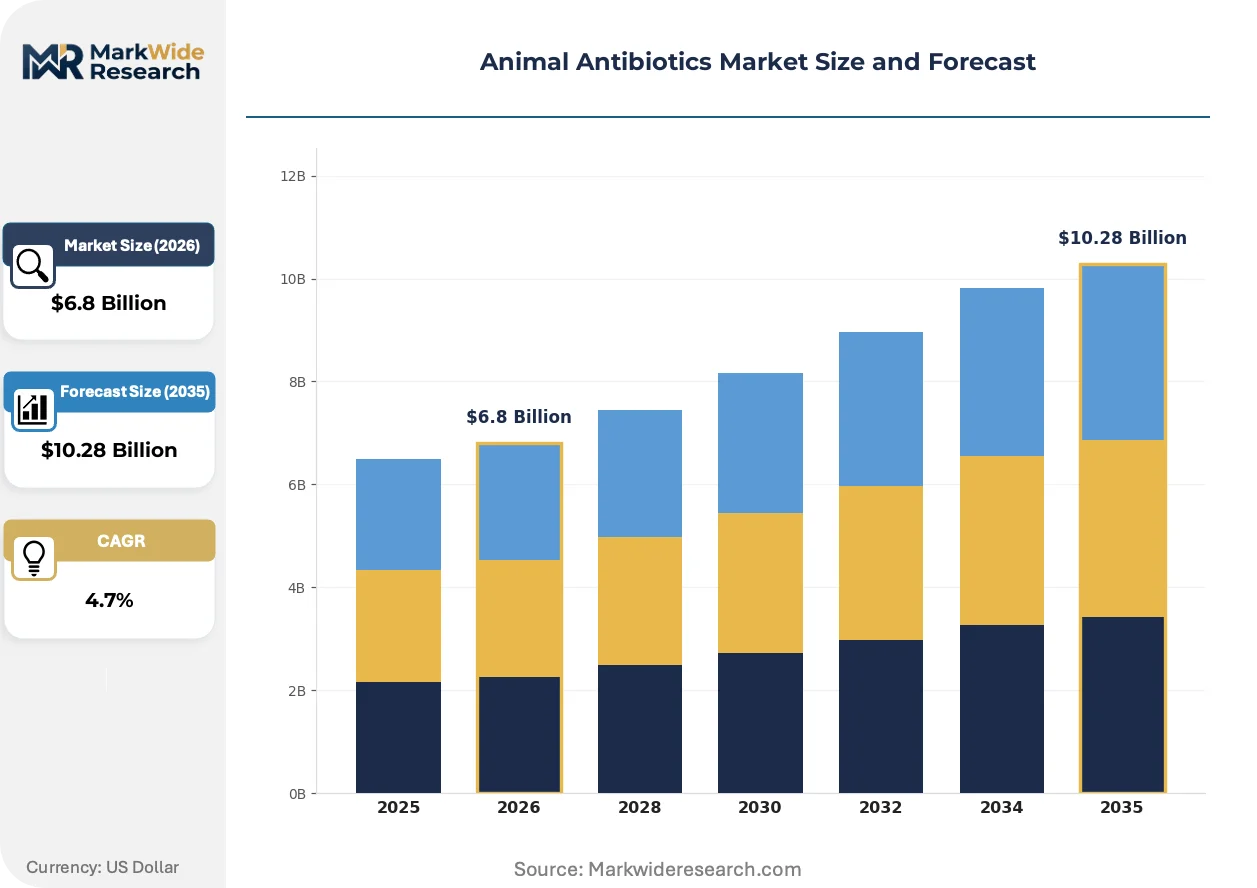
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tetracyclines, Penicillins, Macrolides, Sulfonamides End User: Veterinary Clinics, Animal Farms, Research Institutions, Government Agencies Delivery Mode: Injectable, Oral, Topical, Intramammary Animal Type: Cattle, Poultry, Swine, Aquatic Animals |
| Companies Covered | Zoetis Services LLC, Boehringer Ingelheim International GmbH, Elanco Animal Health, Merck & Co. Inc., Phibro Animal Health Corporation, Virbac, Vetoquinol, Ceva Santé Animale, Dechra Pharmaceuticals PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Antibiotics Market Evolving Landscape
Precision livestock technologies are compressing the gap between disease detection and therapeutic intervention, reducing reliance on prophylactic mass medication. These innovations are restructuring competitive advantage around data integration rather than compound chemistry alone.
Long-acting injectable formulations with extended release kinetics are displacing repeated oral dosing in cattle metaphylaxis programs. Large-scale feedlot operators in Texas and Alberta are adopting single-dose macrolide protocols to reduce labor costs and handling stress. This shift is compressing demand for medicated feed additives while elevating formulation complexity as a supplier differentiator.
EMA's revised guidelines on categorization of antibiotics for veterinary use are reclassifying highest-priority critically important antimicrobials into prescription-only frameworks with mandatory susceptibility testing. This regulatory tightening is elevating diagnostic laboratory capacity requirements across European member states. Respiratory disease protocols in French and German cattle operations are most affected, with practitioners shifting toward culture-guided therapy selection.
Integrated supply chain verification is reshaping procurement relationships between protein processors and antibiotic suppliers. Major Brazilian beef exporters are requiring batch-level traceability from active ingredient through administration record. This audit intensity is most visible in Mato Grosso and Pará production belts, where slaughterhouses now specify approved supplier lists tied to residue testing compliance histories rather than price-based tendering.
Animal Antibiotics Market Segmentation
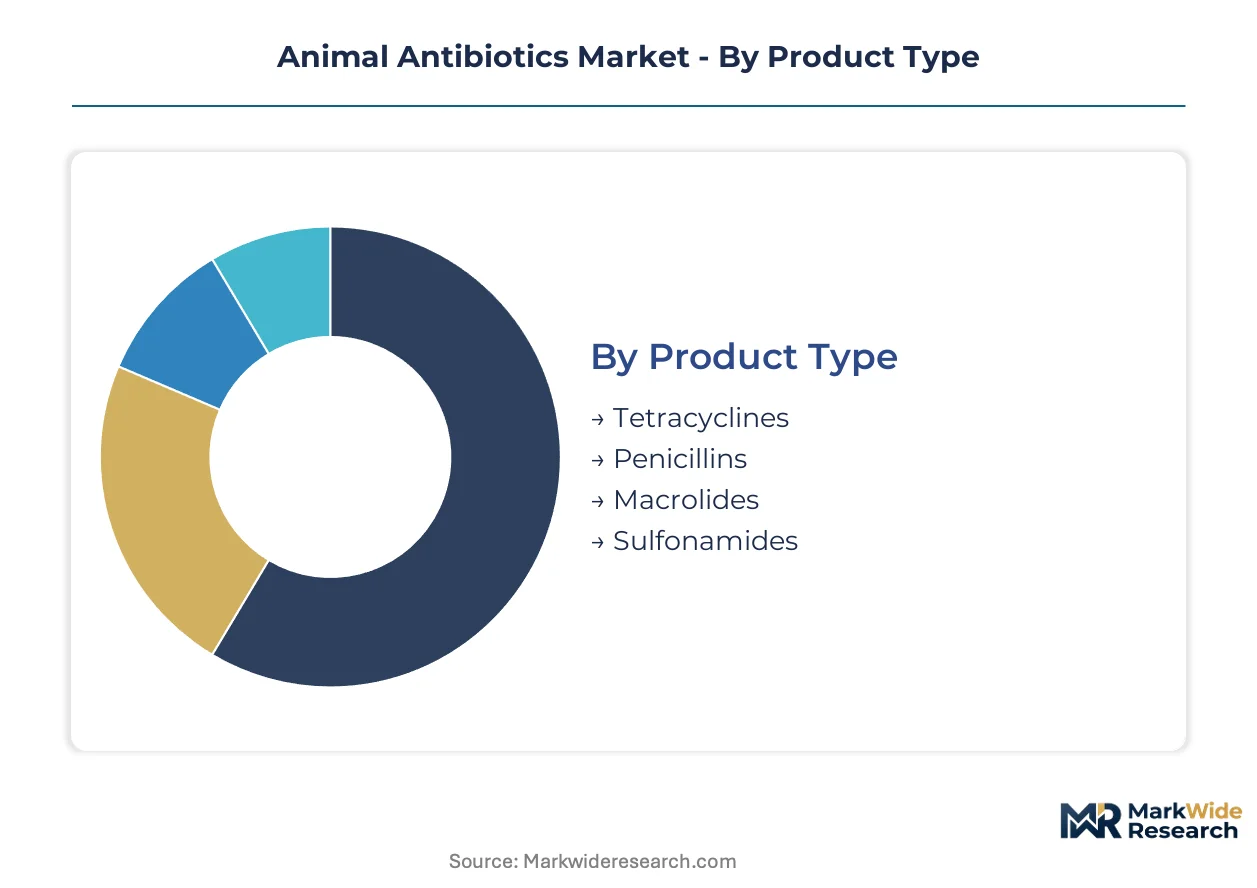
Antibiotic segmentation in animal health reflects divergent pressure points from regulatory restriction, residue compliance, and substitute competition. Each category maps distinct vulnerability profiles that reshape procurement priorities across veterinary and agricultural channels.
Product Type:
Phytogenic substitutes and probiotic alternatives are eroding growth-promotion demand most aggressively in tetracycline and penicillin formulations, while macrolides retain therapeutic insulation through respiratory protocol entrenchment.
- Tetracyclines:Broad-spectrum bacteriostatic compounds derived from chlortetracycline and oxytetracycline cores dominate production volume through low synthesis cost and feed-grade formulation flexibility. Demand concentrates in Brazilian cattle feedlots and US swine operations where metaphylaxis protocols still permit mass administration, though EMA's antimicrobial resistance strategy is narrowing label claims across European member states.
- Penicillins:Beta-lactam antibiotics including procaine and benzathine penicillin G variants serve mastitis therapy and systemic gram-positive infections in dairy herds. Procurement clusters in India's cooperative dairy sector and Germany's Bavarian milk production belt, constrained by stringent withdrawal period enforcement for export-certified milk powder supply chains.
- Macrolides:Tilmicosin and tulathromycin formulations command premium positioning in bovine respiratory disease complexes through single-dose injectable efficacy.
- Sulfonamides:Potentiated sulfonamide combinations retain niche utility in coccidiosis protocols and enteric infections where resistance surveillance remains manageable.
Tetracyclines retain volume leadership; macrolides hold the steepest expansion curve.
End User:
Channel structure determines prescription oversight intensity and diagnostic integration depth, with farm-direct operations facing the steepest compliance cost escalation.
- Animal Farms:Commercial livestock operations in Texas feedlots and Mato Grosso beef complexes drive herd-scale metaphylaxis procurement, increasingly bundled with veterinary oversight services to satisfy FDA Veterinary Feed Directive and export certification requirements. Software platforms tracking withdrawal calendars are penetrating independent operations previously served by generic distributors.
- Veterinary Clinics:Small animal and large animal practices in South Korea's urban centers and Australia's Queensland regions anchor therapeutic antibiotic dispensing, elevated by pet insurance penetration and companion animal expenditure growth. Prescriber shortages in rural US Great Plains and Queensland constrain service expansion.
- Research Institutions:Academic veterinary schools and pharmaceutical development centers maintain controlled antibiotic access for resistance surveillance and novel formulation trials.
- Government Agencies:National veterinary services and disease control authorities stockpile strategic reserves for emergency outbreak response and regulatory enforcement sampling.
Animal farms absorb the largest procurement tonnage; veterinary clinics generate the highest margin per dose administered.
Delivery Mode:
Formulation selection pivots on labor economics versus bioavailability precision, with long-acting technologies reshaping cattle operation workflows.
- Injectable:Long-acting parenteral formulations with extended release kinetics displace repeated dosing in Alberta and Texas feedlots, reducing handling stress and labor allocation. Single-dose macrolide protocols elevate formulation complexity as a supplier differentiator against generic oral alternatives.
- Oral:Medicated feed additives and water-soluble powders dominate swine and poultry operations in Vietnam and Indonesia where backyard farm consolidation creates first-mover positioning for prescription veterinary service networks.
- Topical:Ointment and spray formulations serve localized skin and wound infections in companion animal clinics and equine operations.
- Intramammary:Dry cow and lactating cow infusion products target mastitis prevention and treatment in dairy herds across the Netherlands and New Zealand.
Injectable formats command premium positioning; oral administration retains scale advantage in emerging market expansion.
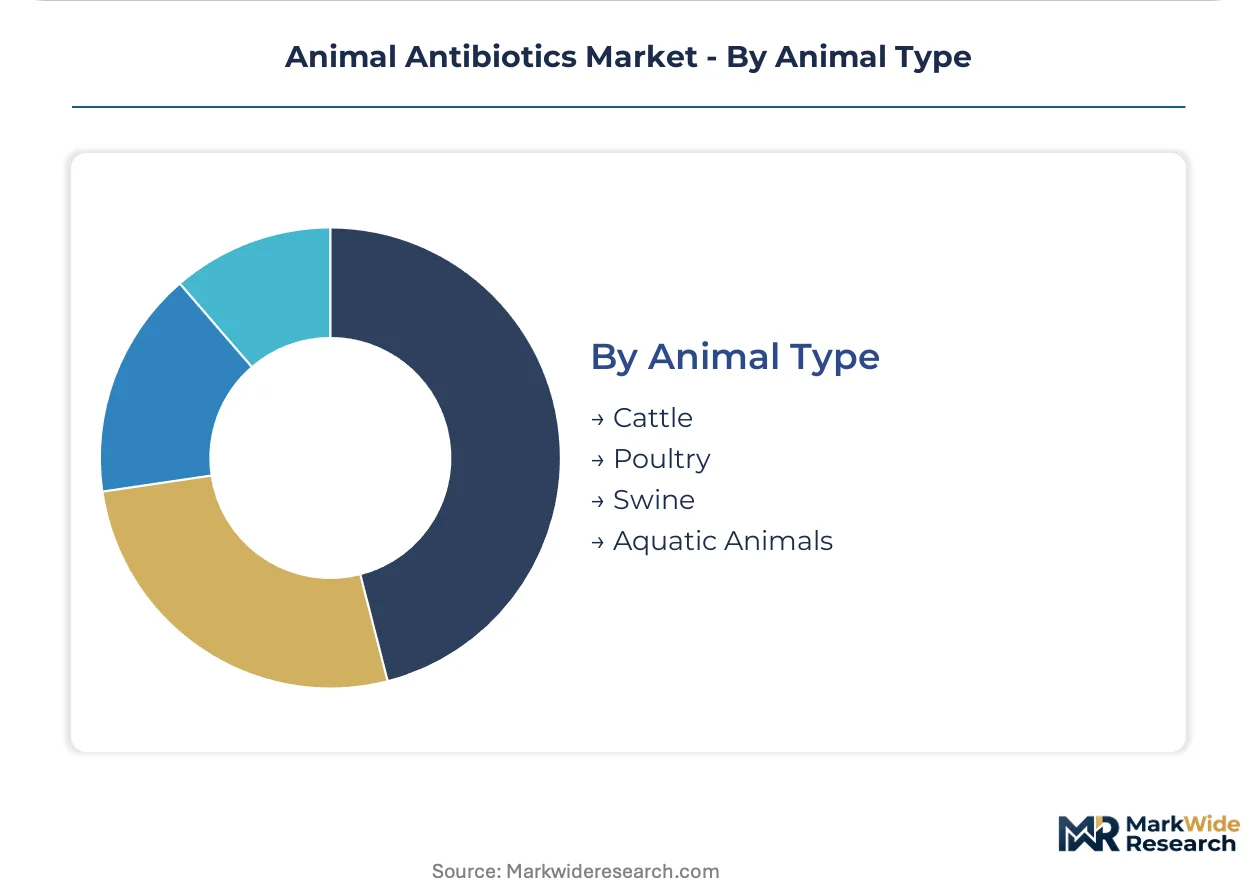
Animal Type:
Species-specific physiology and production intensity dictate antibiotic selection, residue tolerance thresholds, and withdrawal period architecture.
- Cattle:Bovine respiratory disease complexes and liver abscess prevention drive macrolide and tetracycline consumption in North American feedlots, while EU-aligned operations in Ireland and Poland shift toward reduced metaphylaxis under EMA guidelines. Residue testing infrastructure investments at export-certified slaughter facilities constrain supplier qualification.
- Poultry:Broiler and layer operations in Brazil's Pará production belt and Thailand's integrated supply chains face antibiotic-free certification premiums that redirect budgets toward phytogenic alternatives, though therapeutic use persists in necrotic enteritis outbreaks.
- Swine:Post-weaning diarrhea protocols and respiratory disease control in Danish and Spanish operations navigate tightening growth-promotion restrictions through diagnostic-guided therapy selection.
- Aquatic Animals:Shrimp and finfish aquaculture in Vietnam and Indonesia presents emerging demand for approved aquatic formulations, constrained by limited regulatory pathways and environmental persistence concerns.
Cattle anchors current revenue concentration; poultry faces the most acute substitution pressure from antibiotic-free certification programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's Veterinary Feed Directive and EMA's antimicrobial resistance strategy are redrawing procurement compliance costs across major livestock-producing jurisdictions. Brazil's beef export belt and US cattle feedlots face divergent regulatory friction as residue testing requirements intensify. China's veterinary pharmaceutical sector navigates tightening environmental standards for active pharmaceutical ingredient synthesis.
United States
Texas and Kansas feedlot operators drive macrolide consumption for bovine respiratory disease complexes under metaphylaxis protocols. The FDA's Veterinary Feed Directive mandates veterinary oversight for medically important antibiotics in feed, elevating prescription documentation requirements. Independent feedlots in the Texas Panhandle are adopting software platforms tracking withdrawal calendars to maintain EU export certification eligibility.
Brazil
Mato Grosso and Pará slaughterhouses require batch-level antibiotic traceability for beef and poultry shipments to Middle Eastern and European markets. ANVISA coordinates with the Ministry of Agriculture on residue monitoring protocols aligned with Codex Alimentarius standards. Integrated protein processors in São Paulo state are specifying approved supplier lists tied to compliance histories rather than price-based tendering.
China
Zhejiang and Shandong provinces concentrate tetracycline and penicillin active pharmaceutical ingredient manufacturing for domestic livestock operations and export formulation. The Ministry of Agriculture and Rural Affairs has tightened veterinary drug residue limits in animal-derived foods under revised national food safety standards. Backyard farm consolidation in Sichuan and Henan provinces is pulling commercial-scale veterinary service networks into previously fragmented swine production.
Germany
Bavarian dairy cooperatives anchor penicillin procurement for mastitis therapy, constrained by stringent withdrawal period enforcement for export-certified milk powder supply chains. EMA's categorization guidelines reclassify highest-priority critically important antimicrobials into prescription-only frameworks with mandatory susceptibility testing. Diagnostic laboratory capacity in Lower Saxony cattle operations is expanding to support culture-guided therapy selection under tightened respiratory disease protocols.
Australia
Queensland beef feedlots and New South Wales dairy herds drive therapeutic antibiotic demand amid prescriber shortages in rural production belts. The Australian Pesticides and Veterinary Medicines Authority maintains residue tolerance thresholds aligned with Codex and EU maximum residue limits. Export-certified slaughter facilities in Victoria require high-performance liquid chromatography infrastructure investments to verify compliance with premium market access requirements.
Animal Antibiotics Market Competitive Landscape
Player mix skews toward integrated pharmaceutical conglomerates with human health heritage, supplemented by dedicated animal health specialists and regional formulation houses. Market structure concentrates around three archetypes: diversified life science majors leveraging cross-species R&D platforms, pure-play veterinary pharmaceutical developers, and contract manufacturers serving generic distributors. Competitive positioning hinges on regulatory registration depth, diagnostic-therapeutic integration, and channel control across veterinary clinics versus farm-direct distribution.
Within the diversified pharmaceutical tier, Zoetis Services LLC and Boehringer Ingelheim International GmbH exemplify archetypes built on regulatory registration breadth and manufacturing network scale. Elanco Animal Health occupies a position bridging integrated livestock health programs with North American distribution infrastructure. These entities represent contrasting strategic postures: one anchored in diagnostic-to-therapeutic portfolio coherence, the other in European regulatory positioning through EMA-authorized production networks, and the third in channel control across veterinary clinics and farm-direct routes.
| Leading Market Players |
|---|
| Zoetis Services LLC |
| Boehringer Ingelheim International GmbH |
| Elanco Animal Health |
| Merck & Co. Inc. |
| Phibro Animal Health Corporation |
| Virbac |
| Vetoquinol |
| Ceva Santé Animale |
| Dechra Pharmaceuticals PLC |
| Others |
Value Network & Pricing Analysis
EU export certification requirements gate both supplier qualification and price differentiation simultaneously, forcing batch-level traceability investments that stratify procurement relationships across Brazilian beef complexes and US feedlot operations.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with FDA Veterinary Feed Directive compliance and EU maximum residue limit alignment commanding 15-25% price premiums over generic alternatives. Contract-based long-term offtake dominates large processor relationships in Mato Grosso and Texas, while spot procurement persists among independent feedlots. Price differentiation hinges on diagnostic-therapeutic bundling and withdrawal calendar software integration. Cost compression in standard oral formulations is intensifying because phytogenic substitutes capture metaphylaxis budgets; independent feedlots in the US Great Plains show highest price sensitivity, whereas integrated Brazilian protein processors prioritize compliance reliability over unit cost.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for tetracycline and penicillin active pharmaceutical ingredients sourced from Zhejiang and Shandong provinces. Manufacturing concentration in China, India, and Germany feeds global formulation networks, with chlortetracycline cores, benzathine penicillin G variants, and macrolide intermediates anchoring input dependencies. Single-source vulnerability from Zhejiang province API clusters exposes formulators to disruption. Distribution runs through veterinary clinic networks in companion animal channels and farm-direct routes for livestock metaphylaxis, with software-enabled prescription documentation penetrating independent operations previously served by generic distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary prescriber capacity constraints and diagnostic laboratory infrastructure gaps are concentrating competitive advantage around integrated livestock health service capabilities rather than compound chemistry alone.
For Market Incumbents: Compound regulatory registration depth with diagnostic-therapeutic integration to defend against phytogenic substitution in European swine operations. Deepen backward integration into active pharmaceutical ingredient sourcing to mitigate Zhejiang province concentration risk. Channel control across North American veterinary clinics preserves margin position as farm-direct procurement faces prescriber shortage constraints. For New Entrants and Emerging Players: Anchor in Vietnam and Indonesia livestock modernization, where backyard farm consolidation creates first-mover positioning for prescription veterinary service networks. Target aquatic animal formulations in shrimp and finfish aquaculture, where limited regulatory pathways constrain incumbent penetration. Go-to-market through rapid on-farm pathogen identification platforms enables targeted antibiotic selection without broad-spectrum portfolio requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across diagnostic-therapeutic integration platforms as EMA prescription-only frameworks mandate susceptibility testing infrastructure. Long-term viability favors acquirers of veterinary clinic networks with prescriber density in rural production belts. Watch prescriber shortage resolution in Australia's Queensland and the US Great Plains as inflection indicator for farm-direct channel expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic-Therapeutic Integration | EMA prescription-only frameworks elevate rapid pathogen identification as competitive differentiator. |
| Long-Acting Injectable Formulation Development | Single-dose macrolide protocols in Alberta and Texas feedlots reduce labor costs and handling stress. |
| Prescription Documentation Software Deployment | FDA Veterinary Feed Directive compliance penetrates independent feedlots previously served by generic distributors. |
| API Manufacturing Backward Integration | Zhejiang province concentration risk drives captive supply strategies for tetracycline and penicillin cores. |
| Veterinary Clinic Network Acquisition | Prescriber density in rural US Great Plains and Queensland constrains service expansion without consolidation. |
Research Methodology
Initial hypotheses were tested against primary input from veterinary pharmaceutical executives, regulatory affairs specialists at EMA and FDA, feedlot operations managers, and companion animal clinic directors, and refined through secondary validation. Veterinary drug registration databases, FDA Veterinary Feed Directive compliance filings, ANVISA residue monitoring protocols, and customs trade data for active pharmaceutical ingredient flows anchored source material. Bottom-up procurement volume estimates from Brazilian beef complexes and US feedlot operations were triangulated against top-down market sizing from pharmaceutical manufacturer disclosures.
Variance decomposition across product type, animal species, delivery mode, and end-user channel structured the analytical framework over the projection horizon. Modeled segmentation captured tetracycline, penicillin, macrolide, and sulfonamide categories across cattle, poultry, swine, and aquatic animal applications. CAGRs were derived from regression-adjusted growth rates incorporating regulatory restriction timelines and substitution elasticity parameters. Forecast inputs included EMA antimicrobial resistance strategy implementation pace and phytogenic feed additive penetration curves in European swine operations.
Material uncertainties — regulatory withdrawal period extensions, API supply disruption events, and prescriber shortage resolution timelines — sit outside the modeled envelope. Forecasts reflect assumptions about EMA guideline adherence and FDA enforcement intensity that could accelerate or delay market transitions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
ASEAN Poultry Vaccines Market
Veterinary
Veterinary Supplements Market
Veterinary
Veterinary Disinfectants Market
Veterinary
Mexico Veterinary Healthcare Market
Veterinary
Veterinary Equipment and Supplies Market
Veterinary
Global Animal Parasiticides Market
Veterinary
Vet Software Market
Veterinary
Bovine Respiratory Disease Treatment Market
Veterinary
Global Pet Obesity Management Market
Veterinary
Australia Veterinary Healthcare Market
Veterinary
Asia-Pacific Veterinary Healthcare Market
Veterinary
United Kingdom Veterinary Healthcare Market
Veterinary
Veterinary Antibiotics Market
Veterinary
Germany Veterinary Healthcare Market
Veterinary
Pet Hypothyroidism Therapy Market
Veterinary
US Companion Animal Diagnostics Market