
 Veterinary CRO and CDMO Market | 2026-2036
Veterinary CRO and CDMO Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary CRO and CDMO Market Insights
Market Context
The capital-intensity divergence between fully integrated mammalian facilities and modular bioprocessing suites is reorganizing competitive tiers in veterinary outsourcing. Charles River Laboratories leverages its captive biologics capacity across North American sites to anchor long-term vaccine development contracts for livestock and companion animal clients. Labcorp Drug Development sustains global central laboratory networks that compete on multispecies biomarker validation speed. Lonza differentiates through microbial expression platforms purpose-built for veterinary recombinant protein manufacturing at kilogram scale.
Technical Definition and Structural Segments
Veterinary CRO and CDMO services encompass contract research operations and manufacturing organizations that conduct GLP-compliant toxicology studies, efficacy trials, regulatory dossier preparation, and GMP production of animal health active pharmaceutical ingredients and finished dosage forms, typically requiring species-specific pharmacokinetic modeling and batch release testing under 21 CFR Part 511 or VICH guidelines. Preclinical services and clinical trials together absorb the dominant share of outsourced spending as biopharmaceutical companies divest in vivo capabilities, while regulatory affairs contracts are expanding fastest due to divergent national submission requirements for novel veterinary biologics. The hybrid delivery model is gaining traction against traditional on-site arrangements as sponsors seek to balance audit access with geographic flexibility in trial execution.
Regulatory Frame and Outlook
The FDA Center for Veterinary Medicine enforces GLP standards under 21 CFR Part 58 for safety studies supporting New Animal Drug Applications, while EMA's Committee for Medicinal Products for Veterinary Use coordinates centralized marketing authorizations across EU member states under Regulation 2019/6. China's NMPA now mandates local clinical data for imported veterinary vaccines, forcing CDMOs to establish captive trial capacity or partner with domestic CROs. Stakeholders must monitor how divergent bioequivalence standards between FDA and EMA shape portfolio geography decisions before committing to fixed manufacturing assets.
Market Dynamics
The FDA's tightening GLP enforcement under 21 CFR Part 58 is compressing timelines for multispecies toxicology studies, forcing sponsors to consolidate outsourced trials with captive-capability CDMOs rather than fragmented vendor networks.
Growth Catalysts
- Companion animal vaccine outsourcing:Pharmaceutical developers are divesting in vivo capabilities and contracting GLP-compliant toxicology studies to specialized CROs with captive biologics manufacturing.
- EMA's revised veterinary guidance:Centralized marketing authorizations under Regulation 2019/6 are creating demand for regulatory dossier preparation services that bridge divergent national requirements.
- China's local clinical data mandate:NMPA requirements for imported veterinary vaccines are accelerating partnerships between foreign CDMOs and domestic CROs to establish captive trial capacity.
Market Restraints
- High-species facility capex:GLP-compliant large animal housing and surgical suites for livestock trials require capital intensity that limits new entrant participation.
- Recombinant protein input volatility:Microbial expression platforms face supply concentration risk for specialized fermentation media and single-use bioreactor components.
- VICH guideline divergence:Regional bioequivalence standard misalignment between FDA and EMA creates regulatory friction that extends dossier preparation timelines.
Strategic Opportunities
- Hybrid delivery models:Sponsors seek geographic flexibility in trial execution, creating white space for CROs combining on-site audit access with distributed investigator networks.
- Regulatory affairs expansion:Divergent national submission requirements for novel veterinary biologics represent the fastest-growing contract segment as sponsors outsource dossier complexity.
- Biomarker validation services:Multispecies pharmacokinetic modeling capabilities are concentrating demand with central laboratory networks that compete on analytical speed.
Industry Challenges
- GLP auditor scarcity:Qualified study directors with multispecies toxicology expertise face recruitment gaps that constrain trial startup velocity.
- Batch release testing bottlenecks:21 CFR Part 511 compliance requirements for animal health products create certification timeline compression at GMP manufacturing sites.
- Legacy system integration:Electronic data capture platforms for veterinary trials require reconfiguration to interface with sponsor pharmacovigilance databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary CRO and CDMO Market |
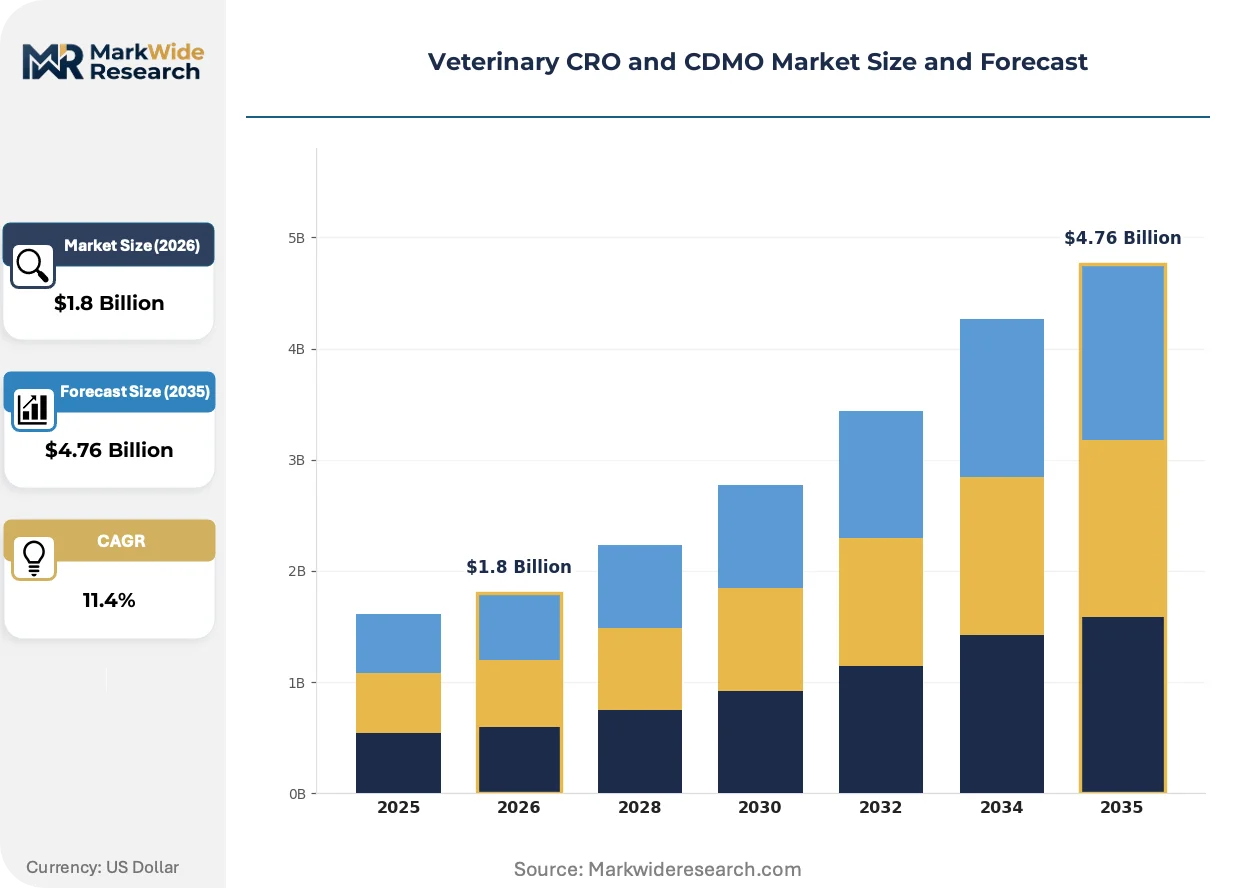
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Preclinical Services, Clinical Trials, Regulatory Affairs, Data Management Delivery Model: On-Site, Off-Site, Hybrid, Remote Product Type: Pharmaceuticals, Vaccines, Diagnostics, Therapeutics End User: Animal Hospitals, Research Institutions, Biopharmaceutical Companies, Veterinary Clinics |
| Companies Covered | Charles River Laboratories, Argenta, Labcorp Drug Development, Clinvet, KLIFOVET GmbH, Inotiv, Vetio Animal Health, Lonza, Aenova Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary CRO and CDMO Market Trends and Innovations
Modular bioprocessing suites are reorganizing competitive tiers in veterinary outsourcing, enabling CDMOs to reconfigure production lines between mammalian and microbial platforms without facility reconstruction.
Single-use bioreactor systems with disposable contact surfaces are supplanting stainless steel vessels in kilogram-scale veterinary recombinant protein manufacturing. Mid-cap CDMOs are adopting these platforms to reduce cross-contamination risk between livestock and companion animal batches. The technology is compressing facility changeover timelines from weeks to days, enabling campaign-based production economics previously unavailable at this scale.
EMA's Committee for Medicinal Products for Veterinary Use is harmonizing centralized marketing authorization procedures across EU member states under Regulation 2019/6. This consolidation reduces duplicate dossier submissions but intensifies documentation requirements for novel biologics. Sponsors are responding by front-loading regulatory affairs contracts to navigate centralized procedures before committing to fixed manufacturing assets.
Biopharmaceutical sponsors are unbundling after-sales regulatory support from manufacturing contracts and procuring standalone pharmacovigilance services. This procurement model evolution disrupts traditional full-service CDMO arrangements and creates specialized vendor tiers. The shift is most visible in Germany, where sponsors maintain separate contracts for GMP production and post-market surveillance to satisfy BfArM inspection protocols.
Veterinary CRO and CDMO Market Segmentation
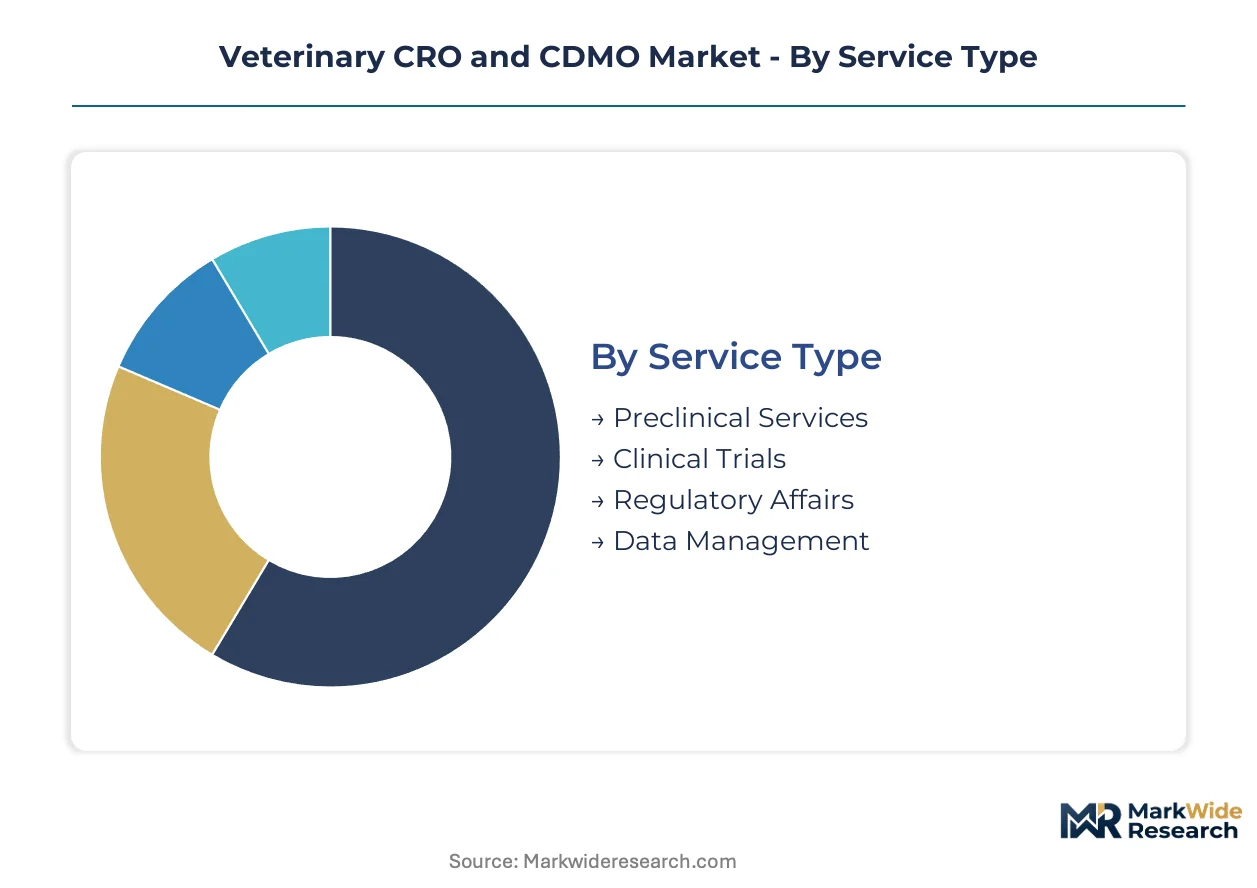
Veterinary outsourcing contracts fragment across service modalities, delivery configurations, product categories, and sponsor types. Each segmentation axis reveals distinct procurement patterns and margin structures that reshape vendor selection criteria.
Service Type:
Preclinical and clinical capabilities flow through different commercial channels, with toxicology studies commanding captive-site premiums while regulatory contracts distribute across specialist consultancies.
- Preclinical Services:GLP-compliant toxicology studies, pharmacokinetic modeling, and multispecies safety assessments conducted in dedicated vivarium facilities. Demand concentrates with biopharmaceutical sponsors divesting in vivo capabilities in the United States and Germany, driven by FDA and EMA enforcement tightening under 21 CFR Part 58 and Regulation 2019/6.
- Clinical Trials:Efficacy studies, field trials, and investigator-initiated research across livestock and companion animal populations. Sponsors in China are expanding outsourced clinical capacity to satisfy NMPA local data mandates for imported veterinary vaccines.
- Regulatory Affairs:Dossier preparation, submission management, and post-market surveillance support. Contract volume is climbing fastest as divergent national requirements for novel biologics outpace sponsor internal capabilities.
- Data Management:Electronic data capture, statistical analysis, and pharmacovigilance database integration for trial documentation and safety reporting.
By volume, Preclinical Services leads. By expansion trajectory, Regulatory Affairs is climbing the fastest.
Delivery Model:
Cost tier differentiation separates premium on-site audit access from economy remote configurations, with hybrid models capturing mid-tier sponsor budgets.
- On-Site:Full-service execution at CRO/CDMO facilities with sponsor audit rights and real-time protocol oversight. High capital intensity limits participation to established vendors with captive biologics capacity.
- Hybrid:Distributed investigator networks combined with centralized laboratory and regulatory functions. This model is gaining share fastest as sponsors balance geographic flexibility with quality assurance requirements.
- Off-Site:Contracted execution at third-party facilities or academic research centers without CRO direct operational control.
- Remote:Virtual monitoring, decentralized data collection, and cloud-based project management reducing sponsor travel burden.
By revenue concentration, On-Site still dominates. By contract velocity, Hybrid is pulling ahead.
Product Type:
Application focus drives facility specialization, with vaccine manufacturing requiring microbial expression platforms and therapeutics demanding mammalian cell culture suites.
- Pharmaceuticals:Small-molecule active pharmaceutical ingredients and finished dosage forms for animal health indications. Production concentrates at CDMOs with GMP-certified chemical synthesis and formulation capabilities.
- Vaccines:Live attenuated, inactivated, and recombinant veterinary vaccines requiring dedicated bioprocessing suites. China's NMPA local clinical data mandate is accelerating partnerships between foreign manufacturers and domestic CROs.
- Therapeutics:Monoclonal antibodies, recombinant proteins, and gene therapy vectors for companion animal disease management.
- Diagnostics:Reference laboratory services, point-of-care test development, and companion animal biomarker validation.
By manufacturing throughput, Pharmaceuticals maintains scale leadership. By sponsor investment intensity, Vaccines is expanding most quickly.
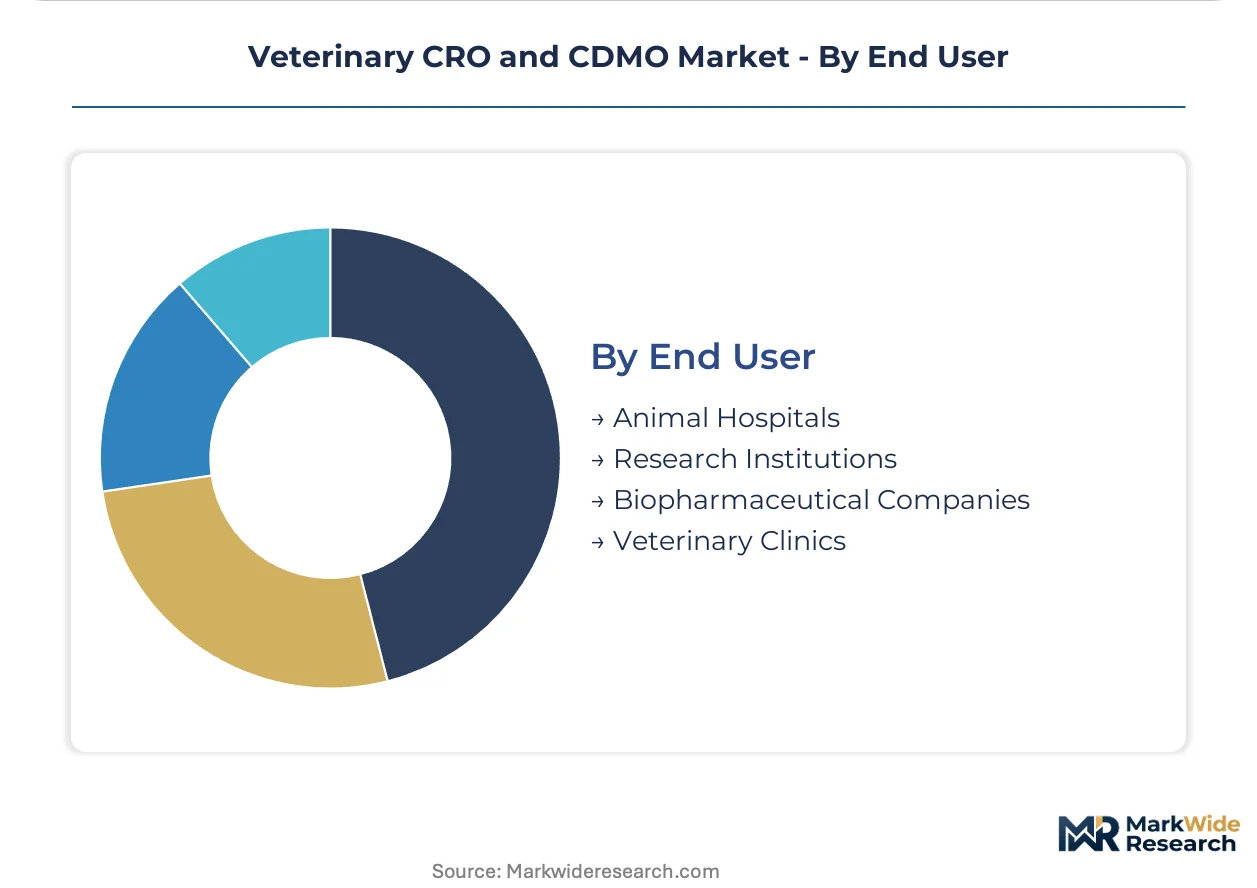
End User:
Customer type determines contract structure, with biopharmaceutical companies procuring integrated development programs while veterinary clinics purchase discrete diagnostic services.
- Biopharmaceutical Companies:Full-service outsourcing of discovery-to-registration programs for novel animal health products. Sponsors in Germany increasingly unbundle manufacturing from pharmacovigilance to satisfy BfArM inspection protocols.
- Research Institutions:Academic and government laboratory contracts for investigator-initiated studies and reference standard development.
- Animal Hospitals:Reference laboratory partnerships and clinical trial site networks for companion animal studies.
- Veterinary Clinics:Point-of-care diagnostic procurement and post-market surveillance data collection services.
By contract value, Biopharmaceutical Companies anchor demand. By site expansion rate, Animal Hospitals is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Switzerland exhibit the lowest price elasticity for GLP-compliant toxicology services, while sponsors in China and India prioritize cost efficiency in clinical trial execution. This divergence shapes facility investment patterns across major contract research clusters.
United States
FDA Center for Veterinary Medicine enforcement under 21 CFR Part 58 drives sponsor consolidation with captive-capability providers. The agency's tightened GLP timelines compress multispecies study schedules. Massachusetts and North Carolina host the densest concentrations of biologics manufacturing campuses serving companion animal vaccine developers.
Germany
BfArM inspection protocols push sponsors toward unbundled procurement of GMP production and pharmacovigilance services. EMA's Committee for Medicinal Products for Veterinary Use coordinates centralized marketing authorizations under Regulation 2019/6. The Rhine-Main and Upper Bavaria regions concentrate Europe's largest contract manufacturing facilities for veterinary recombinant proteins.
China
NMPA mandates for local clinical data on imported veterinary vaccines accelerate partnerships between foreign CDMOs and domestic CROs. The country's national pharmaceutical regulator now requires captive trial capacity establishment for market access. Shanghai and Suzhou anchor the fastest-expanding multispecies toxicology facility networks in Asia-Pacific.
Switzerland
Swissmedic harmonization with EMA centralized procedures attracts regulatory dossier preparation contracts for novel veterinary biologics. The regulator's alignment with VICH guidelines reduces submission friction for sponsors targeting EU markets. Basel and Zurich host specialized microbial expression platforms purpose-built for kilogram-scale veterinary protein manufacturing.
United Kingdom
Post-Brexit divergence from EMA centralized procedures creates demand for standalone UK marketing authorization submissions. The Veterinary Medicines Directorate maintains GLP recognition agreements with OECD member states. Cambridge and Oxfordshire clusters concentrate reference laboratory services for companion animal biomarker validation.
Veterinary CRO and CDMO Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in veterinary outsourcing. The upper tier combines captive biologics manufacturing with GLP-compliant toxicology capacity across multiple continents. Mid-scale CDMOs compete through modular bioprocessing suites that reconfigure between mammalian and microbial platforms. Dominant competitive moves include strategic partnerships to establish local clinical trial capacity in China and portfolio diversification into standalone regulatory affairs services.
Within the integrated tier, Charles River Laboratories and Labcorp Drug Development exemplify the convergence of central laboratory networks with multispecies study execution. Lonza occupies a position representing microbial expression specialization at production scale. These three anchors demonstrate how geographic footprint breadth and platform technology depth define competitive positioning in sponsor procurement decisions.
| Leading Market Players |
|---|
| Charles River Laboratories |
| Argenta |
| Labcorp Drug Development |
| Clinvet |
| KLIFOVET GmbH |
| Inotiv |
| Vetio Animal Health |
| Lonza |
| Aenova Group |
| Others |
Pricing and Supply Chain Analysis
Kilogram-scale microbial expression capacity in Switzerland and Germany anchors price floors for veterinary recombinant protein manufacturing, while fragmented toxicology housing economics in China and India compress margins for GLP-compliant multispecies studies. Sponsors in the United States and Germany absorb premium pricing for captive-site audit access, whereas cost-sensitive buyers in Asia-Pacific drive procurement toward hybrid delivery models with distributed investigator networks.
Pricing Analysis
Post-market pharmacovigilance service contracts now drive lifetime value in veterinary outsourcing as sponsors unbundle after-sales regulatory support from manufacturing agreements. Three-tier pricing structure across premium, standard, and economy levels separates GLP-certified toxicology suites with multispecies surgical capacity from modular bioprocessing facilities and remote data management services. Price differentiation hinges on FDA 21 CFR Part 58 certification tier and geographic proximity to sponsor headquarters. Cost compression in standard-tier clinical trial execution is intensifying because NMPA local data mandates force redundant capacity buildout. Biopharmaceutical sponsors in Germany exhibit the lowest price elasticity, while veterinary clinics in China and India prioritize economy-tier diagnostic procurement.
Supply Chain Analysis
Single-use bioreactor component supply from South Korea and Japan underwrites campaign-based production economics for mid-scale veterinary CDMOs reconfiguring between mammalian and microbial platforms. Active pharmaceutical ingredient synthesis draws from India and China for small-molecule veterinary therapeutics, while recombinant protein expression rests on German and Swiss fermentation media supply. Single-source vulnerability concentrates in specialized cell culture media formulations subject to customs inspection delays at Rotterdam and Shanghai ports. Distribution runs through captive logistics networks controlled by integrated CRO/CDMOs with North American and European campus clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary CRO and CDMO procurement is restructuring around recurring regulatory affairs revenue streams that expand faster than one-time manufacturing contracts, as EMA centralized procedures and NMPA local data mandates force sustained dossier management relationships.
For Market Incumbents: Fortify GLP auditor retention through captive training pipelines addressing qualified study director scarcity that constrains trial startup velocity. Deepen backward integration into single-use bioreactor component supply to mitigate input volatility from South Korean and Japanese suppliers. Defend against modular bioprocessing disruptors by locking long-term vaccine development contracts with livestock and companion animal sponsors seeking campaign-based production flexibility. For New Entrants and Emerging Players: Differentiate on hybrid delivery models combining centralized laboratory networks with distributed investigator access in China and India where NMPA clinical data mandates create white space. Target regulatory affairs contract expansion as the fastest-growing segment, exploiting divergent national submission requirements for novel veterinary biologics that outpace sponsor internal capabilities. Pursue partnership-first go-to-market positioning with domestic CROs to establish captive trial capacity without full GLP facility capex burden. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors CDMOs with reconfigurable bioprocessing suites capable of switching between mammalian cell culture and microbial expression without facility reconstruction. Long-term viability rests on regulatory complexity deepening rather than harmonizing across FDA, EMA, and NMPA jurisdictions. Acquisition target archetype: mid-scale players with established China partnerships for local clinical data generation. Watch EMA-FDA bioequivalence standard divergence as the signal indicating portfolio geography commitment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Affairs Capability Buildout | EMA's Regulation 2019/6 intensifies documentation requirements for novel veterinary biologics submissions. |
| China Partnership Structuring | NMPA local clinical data mandates force foreign CDMOs into domestic CRO alliances for market access. |
| Modular Bioprocessing Suite Investment | Reconfigurable platforms enable campaign-based economics for livestock and companion animal batch switching. |
| GLP Auditor Training Pipeline | Qualified study director scarcity constrains multispecies toxicology trial startup velocity across North America. |
| Pharmacovigilance Service Unbundling | German sponsors now separate GMP production from post-market surveillance to satisfy BfArM inspection protocols. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 21 CFR Part 511 filings, EMA centralized marketing authorization submissions, and NMPA veterinary vaccine registration data. Primary interviews engaged regulatory affairs directors at biopharmaceutical sponsors, GLP study directors at contract toxicology facilities, and procurement leads at animal health manufacturing campuses across the United States, Germany, and China. Bottom-up triangulation against top-down trade flow analysis validates service-type revenue allocation across preclinical, clinical, regulatory affairs, and manufacturing segments.
Segmentation dimensions modeled include service modality, delivery configuration, product category, and sponsor type across the projection horizon. CAGRs derive from time-series analysis of outsourced spending patterns correlated with biopharmaceutical divestment of in vivo capabilities and regulatory enforcement tightening under 21 CFR Part 58 and Regulation 2019/6. Industry-specific forecast inputs incorporate NMPA local clinical data mandate implementation pace and EMA centralized procedure adoption rates.
Material uncertainties — regulatory divergence between FDA and EMA bioequivalence standards, single-use bioreactor component supply interruptions, and GLP auditor recruitment gaps — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as VICH guideline harmonization negotiations and China's veterinary import policy evolution unfold.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary Respiratory Disease Treatment Market
Veterinary
Global Veterinary MRI Market
Veterinary
US Surgical Pet Collar Market
Veterinary
Veterinary Home Diagnostics Market
Veterinary
Animal Microchip Implant Market
Veterinary
Clostridium Vaccine (Animal Health) Market
Veterinary
Veterinary Thermography Market
Veterinary
Animal Drug Compounding Market
Veterinary
Pet Light Therapy Devices Market
Veterinary
Veterinary Antibiotics Market
Veterinary
USA Animal Model Market
Veterinary
Global Animal Vaccine Market
Veterinary
Veterinary Contract Development and Manufacturing Organizations (CDMO) Market
Veterinary
Global Porcine Vaccine Market
Veterinary
Global Canine Influenza Vaccine Market
Veterinary
CBD Pet Market