
 Veterinary Supplements Market | 2026-2036
Veterinary Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Supplements Market Outlook
Companion animal owners are unwinding the historical dominance of livestock producers in veterinary supplement procurement. Zoetis leverages its pharmaceutical heritage to anchor credibility in prescription-adjacent supplement categories. Nutramax Laboratories specializes in joint health formulations with clinically tested active ingredients, while Mars Incorporated extends its retail distribution muscle to capture shelf space across veterinary clinics and pet specialty stores.
Veterinary supplements comprise orally administered nutritional additives containing defined concentrations of vitamins, minerals, probiotics, or omega fatty acids, manufactured through spray-drying, microencapsulation, or cold-press compaction to preserve bioactivity through shelf life. These products modulate physiological function in target species rather than treating diagnosed disease. Probiotics and fatty acids occupy the fastest-expanding margin pools as pet owners seek digestive and dermatological solutions. Chews dominate formulation preferences among dog owners, while powders retain stronger traction in equine applications where dosing flexibility matters.
The FDA Center for Veterinary Medicine and the Association of American Feed Control Officials jointly govern ingredient safety and labeling claims in the United States, while the EU's Feed Additives Regulation mandates pre-market authorization for novel supplement substances entering European distribution. Compliance costs are rising as jurisdictions demand clinical substantiation for structure-function claims previously accepted on formulation precedent alone. Stakeholders must monitor evolving substantiation thresholds to determine whether to pursue pharmaceutical-style trials or reformulate around established ingredient monographs.
Market Dynamics
Companion animal owners now drive procurement decisions that livestock producers once dominated, while the EU Green Deal and F-Gas Regulation force reformulation of ingredient sourcing and packaging sustainability across European supply chains.
Growth Catalysts
- EU F-Gas Regulation compliance:Manufacturers retrofitting production lines for low-carbon refrigerants in spray-drying operations unlock premium positioning in European veterinary channels.
- Microencapsulation technology:Process innovations preserving omega fatty acid bioactivity through shelf life enable condition-specific formulations targeting dermatological and cognitive health.
- United States premiumization:Canine and feline households expand spending on prescription-adjacent supplement categories, deepening per-pet expenditure on joint and digestive health.
Market Restraints
- Clinical substantiation costs:FDA Center for Veterinary Medicine and AAFCO now demand trial data for structure-function claims previously accepted on formulation precedent, elevating compliance expenditure.
- Marine lipid supply concentration:Omega-3 fatty acid raw material sourcing clusters in Peruvian and Norwegian fisheries, exposing formulators to catch volatility and geopolitical friction.
- Probiotic strain stability:Viability degradation during pelleting and extrusion processes limits shelf-life claims and complicates multi-strain formulation development.
Strategic Opportunities
- Equine powder formulations:Dosing flexibility preferences among horse owners in competitive and recreational stables remain underpenetrated by condition-specific SKUs.
- EU Feed Additives Regulation pre-market pathways:Novel postbiotic substances securing EFSA authorization gain first-mover advantage in digestive health positioning.
- Veterinary clinic direct-to-consumer channels:Telehealth platforms and subscription models bypass traditional retail markups, capturing recurring revenue from chronic condition management.
Industry Challenges
- Formulation chemist scarcity:Cross-species metabolic expertise spanning companion animals, livestock, and equines concentrates in a narrow talent pool, inflating compensation and slowing product development cycles.
- Cold-chain infrastructure gaps:Probiotic and live culture distribution requires temperature-controlled logistics that veterinary wholesale networks in emerging markets lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Supplements Market |
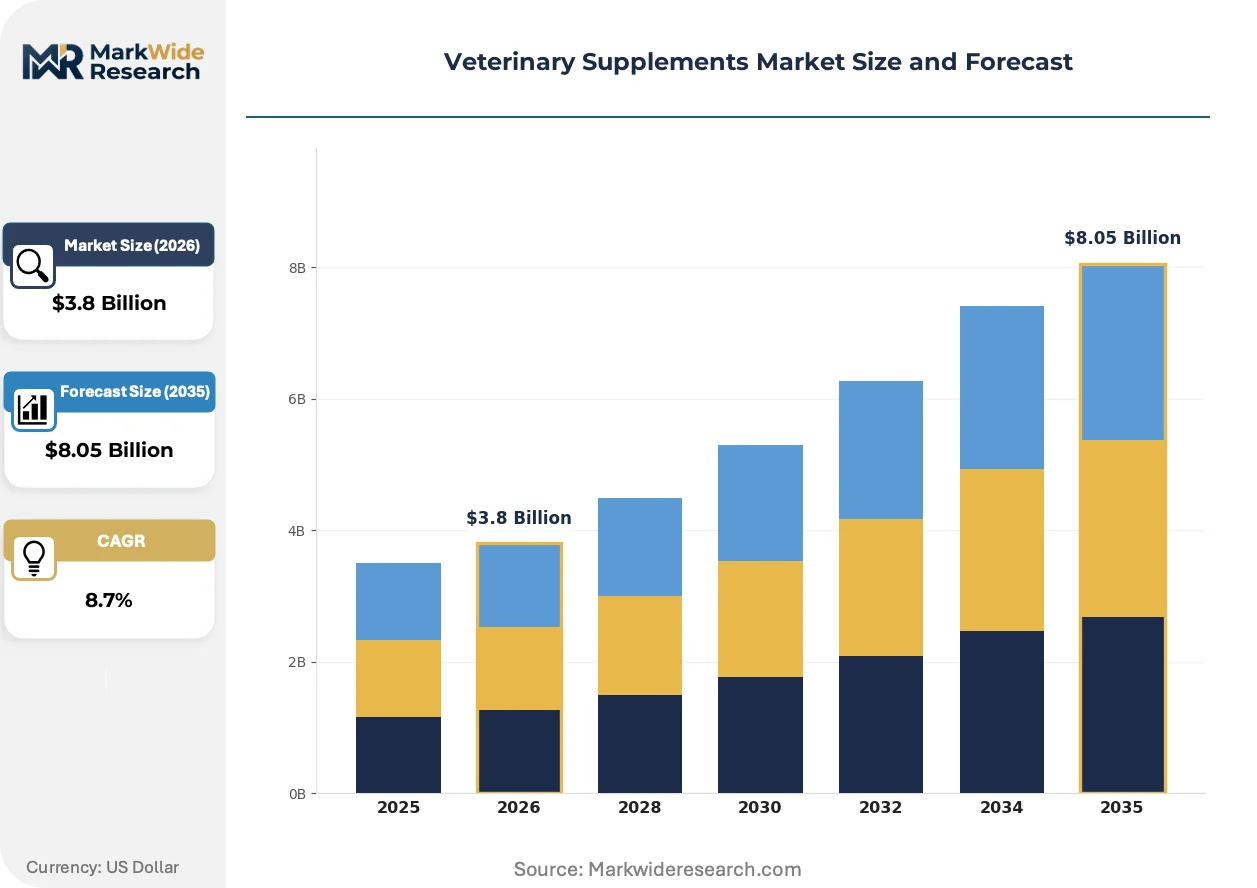
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Probiotics, Fatty Acids Animal Type: Dogs, Cats, Horses, Birds Formulation: Pills, Powders, Liquids, Chews Sales Channel: Online Stores, Veterinary Clinics, Pet Shops, Distributors |
| Companies Covered | Zoetis, Elanco, Virbac, Boehringer Ingelheim, Vetoquinol, Nestlé Purina PetCare, Mars Incorporated, Nutramax Laboratories, H&H Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Supplements Market Strategic Shifts
Manufacturing technology and regulatory architecture are restructuring competitive advantage in veterinary supplements, separating formulators with clinical substantiation capabilities from commodity ingredient assemblers.
Microencapsulation is bifurcating the omega fatty acid segment. Spray-congealing and complex coacervation processes now protect lipid oxidation in chewable matrices. Premium canine supplement brands adopt these processes to extend shelf-life claims from 12 to 24 months. This technology compression is squeezing out formulators reliant on unprotected oil-in-powder blends.
EU Green Deal sustainability mandates are reshaping packaging and sourcing decisions. The F-Gas Regulation phases down hydrofluorocarbon use in manufacturing, forcing spray-drying facility retrofits. Feed Additives Regulation pre-market authorization timelines for novel ingredients now stretch 18-24 months. European manufacturers respond by consolidating around established EFSA monographs rather than pioneering new actives.
Subscription-based replenishment is displacing episodic retail purchasing among companion animal owners. Direct-to-consumer platforms capture recurring revenue from chronic condition management, particularly joint and cognitive health protocols. Veterinary clinics in the United States increasingly white-label these services, eroding traditional pet specialty store foot traffic.
Veterinary Supplements Market Segmentation
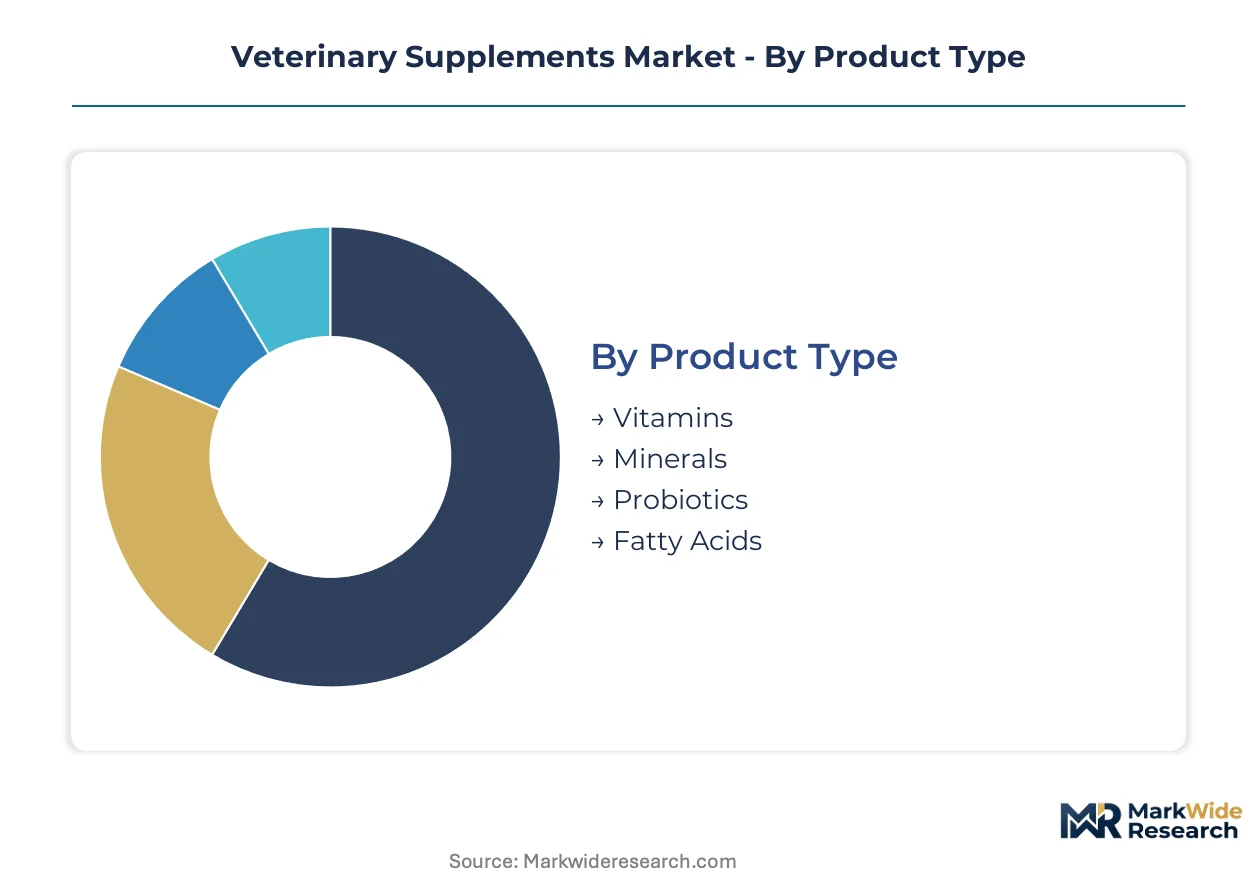
Veterinary supplements segment across four intersecting dimensions that determine formulation priorities, regulatory pathways, and margin capture. Product chemistry and animal metabolism dictate manufacturing complexity, while channel access shapes pricing architecture and customer retention economics.
Product Type:
FDA Center for Veterinary Medicine and AAFCO apply differentiated substantiation thresholds across nutritional categories, elevating compliance costs for novel bioactives relative to established vitamin monographs.
- Probiotics:Live microbial cultures require cold-chain integrity through distribution and strain-specific stability validation. Demand concentrates in canine digestive health applications where veterinary endorsement drives premium positioning.
- Fatty Acids:Omega-3 and omega-6 concentrates derived from marine and plant sources modulate dermatological and cognitive function. Peruvian and Norwegian fisheries supply the bulk of EPA/DHA raw material, exposing formulators to catch seasonality and quota restrictions.
- Vitamins:Water-soluble and fat-soluble micronutrient blends address deficiency correction in companion and production animals.
- Minerals:Chelated and inorganic trace element formulations support skeletal development and metabolic enzyme function.
Established volume favors vitamins; emerging adoption favors probiotics.
Animal Type:
Companion animal households command per-unit expenditure multiples exceeding livestock applications, concentrating R&D investment toward canine and feline metabolic pathways.
- Dogs:Joint health formulations with glucosamine and chondroitin dominate SKU proliferation, while cognitive support supplements targeting senior animals gain veterinary clinic placement.
- Cats:Palatability challenges drive novel delivery format innovation, with microencapsulated powders and liquid toppers outpacing tablet acceptance.
- Horses:Competitive and recreational stables demand dosing flexibility that powder formulations provide, though condition-specific premix penetration remains limited.
- Birds:Avian metabolic specificity constrains ingredient selection, with calcium and vitamin A formulations addressing common deficiency patterns.
Canine applications generate the steepest expansion trajectory; equine segments present underpenetrated white space.
Formulation:
Manufacturing technology selection determines bioactivity preservation, shelf-life claims, and palatability engineering costs across species-specific consumption behaviors.
- Chews:Extruded and cold-pressed matrices incorporate palatants and protect actives through microencapsulation. Canine owners prefer this format for administration compliance.
- Powders:Dosing flexibility and mixing versatility suit equine and multi-pet households where weight-based titration matters.
- Pills:Compression and coating technologies enable precise unit dosing for clinical protocols requiring exact active concentrations.
- Liquids:Emulsion stability challenges limit shelf-life claims, though this format penetrates feline and avian applications where solid refusal is common.
Chews capture the premium margin pool; powders retain volume concentration in veterinary and farm supply channels.
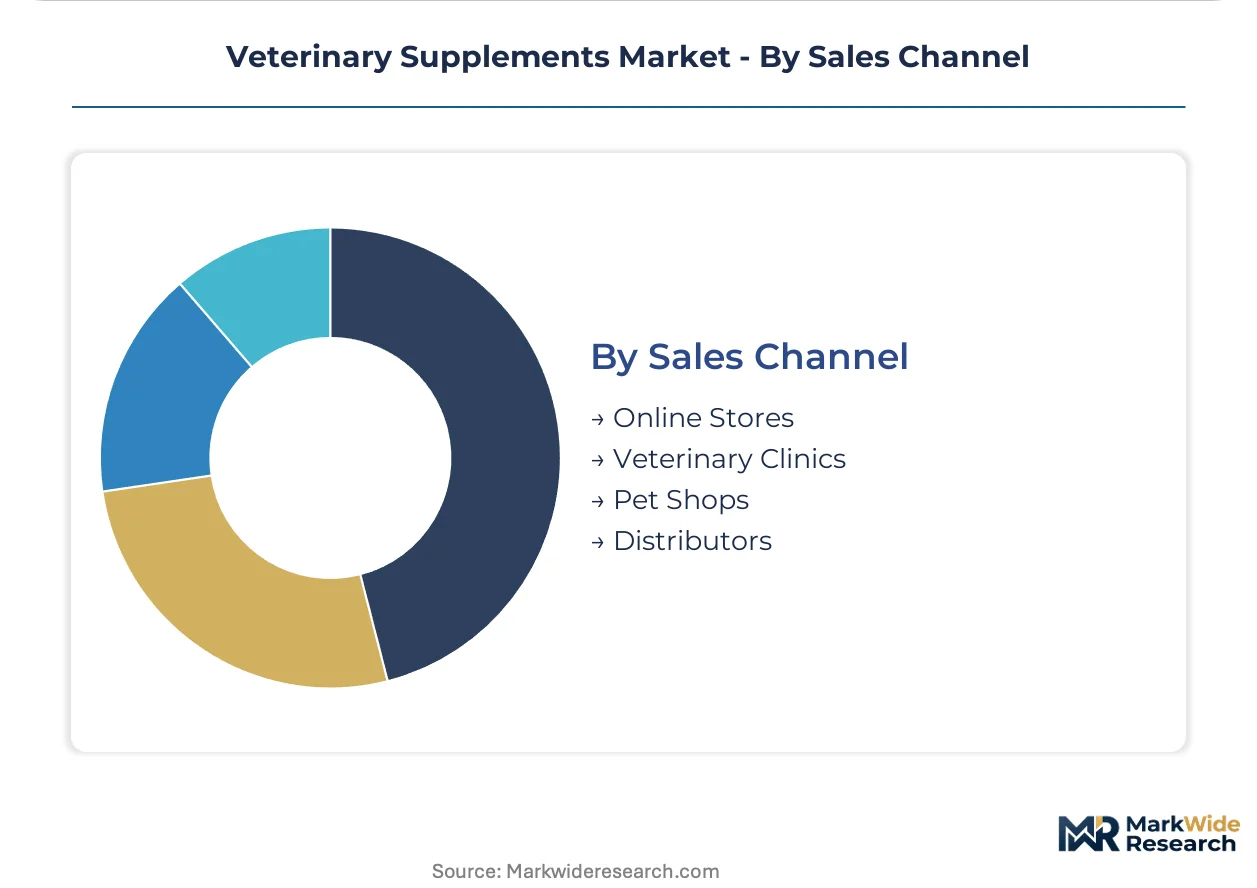
Sales Channel:
Channel selection determines customer acquisition economics, subscription attach rates, and regulatory labeling flexibility for structure-function claims.
- Veterinary Clinics:Prescription-adjacent positioning and professional endorsement support premium pricing for condition-specific protocols.
- Online Stores:Direct-to-consumer platforms enable subscription replenishment and bypass retail markup extraction, capturing recurring revenue from chronic condition management.
- Pet Shops:Specialty retail provides tactile evaluation and impulse purchase conversion for novel format introductions.
- Distributors:Wholesale networks service farm supply and equine stable accounts where volume purchasing and credit terms drive procurement decisions.
Veterinary clinics defend the highest per-unit margins; online channels expand fastest in absolute customer acquisition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites European distribution of probiotic formulations, while Union Pacific's refrigerated rail network connects Midwest manufacturing clusters to West Coast export terminals serving Asian markets.
United States
Canine and feline households drive per-pet expenditure on joint health and cognitive support protocols. The FDA Center for Veterinary Medicine and AAFCO jointly enforce escalating substantiation requirements for structure-function claims. Kansas City and Omaha anchor spray-drying operations supplying veterinary clinic channels nationwide.
Germany
Premium equine stables in Lower Saxony and Bavaria demand dosing-flexible powder formulations for competitive performance animals. The EU F-Gas Regulation mandates low-carbon refrigerant retrofits in manufacturing facilities. Munich-based distributors consolidate procurement for veterinary clinics across Central Europe.
China
Urban companion animal ownership in Shanghai and Beijing expands demand for imported omega fatty acid formulations. SAMR and GB standards govern feed additive safety and novel ingredient registration. Yangtze River Delta manufacturing clusters specialize in microencapsulation technology for export markets.
United Kingdom
Veterinary clinic consolidation in London and Southeast England concentrates procurement power for prescription-adjacent supplement categories. Post-Brexit divergence from EU Feed Additives Regulation creates parallel authorization pathways for novel ingredients. Cambridge-area biotech firms develop strain-specific probiotic stability testing protocols.
Brazil
Expanding middle-class pet ownership in São Paulo and Rio de Janeiro deepens demand for premium canine wellness products. ANVISA regulates veterinary supplement safety and labeling claims with escalating clinical substantiation requirements. São Paulo state hosts South America's largest spray-drying capacity for marine lipid processing.
Veterinary Supplements Market Competitive Environment
Listed leaders compete with private specialists across pharmaceutical heritage and retail distribution capabilities. The market structures around three tiers: animal health conglomerates with prescription drug adjacencies, consumer packaged goods giants leveraging retail shelf access, and focused laboratories specializing in condition-specific formulations. Competitive moves concentrate on clinical substantiation investments for regulatory pre-clearance and direct-to-consumer platform development capturing subscription revenue.
Within the pharmaceutical heritage tier, Zoetis and Elanco occupy positions anchoring credibility in veterinary clinic channels through prescription-adjacent supplement portfolios. Mars Incorporated and Nestlé Purina PetCare represent the consumer packaged goods archetype, extending retail distribution muscle across pet specialty stores and mass-market channels. Nutramax Laboratories exemplifies the focused laboratory model, concentrating R&D investment on clinically tested active ingredients for joint health applications.
| Leading Market Players |
|---|
| Zoetis |
| Elanco |
| Virbac |
| Boehringer Ingelheim |
| Vetoquinol |
| Nestlé Purina PetCare |
| Mars Incorporated |
| Nutramax Laboratories |
| H&H Group |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts for Peruvian and Norwegian marine lipids lock in supply access and price visibility for omega-3 concentrate formulators, insulating premium veterinary supplement producers from catch seasonality while anchoring cost structures for mid-tier competitors exposed to spot market volatility.
Pricing Analysis
Volume-discount tiering structures separate prescription-adjacent clinical protocols from mass-market retail SKUs, with veterinary clinic channels commanding premium positioning through professional endorsement while online direct-to-consumer subscriptions compress margins via recurring revenue models. Price differentiation hinges on clinical substantiation depth and cold-chain certification grade. Pricing pressure intensifies in standard-tier powders as commodity ingredient assemblers compete on EPA/DHA concentration claims. Livestock and equine segments exhibit highest price sensitivity; canine cognitive health protocols show lowest.
Supply Chain Analysis
Inventory lead times for probiotic strains extend 8-14 weeks due to viability validation requirements, constraining just-in-time replenishment for multi-strain formulations. Raw material sourcing concentrates in Peru, Norway, and China for marine lipids, with Yangtze River Delta microencapsulation technology feeding global chewable production. Supply chain risk centers on single-source vulnerability for high-purity EPA/DHA concentrates. Distribution runs through temperature-controlled veterinary wholesale networks in developed markets and emerging-market distributor partnerships with limited cold-chain infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary supplements function as a service-attach opportunity where subscription replenishment platforms and telehealth protocol management expand faster than standalone product sales, embedding hardware-like supplement SKUs into recurring chronic care relationships.
For Market Incumbents: Fortify clinical substantiation pipelines against escalating FDA Center for Veterinary Medicine and AAFCO evidentiary thresholds, prioritizing pharmaceutical-style trial investment for structure-function claims previously accepted on formulation precedent. Deepen backward integration into captive omega-3 refining capacity to offset Peruvian catch volatility and secure margin control.
For New Entrants and Emerging Players: EFSA Feed Additives Regulation fast-track pathways for novel postbiotic substances unlock first-mover positioning in European digestive health segments with 18-24 month authorization timelines creating defensive moats. Target underpenetrated equine powder formulations in German and US competitive stables where dosing flexibility preferences outpace condition-specific SKU availability. Deploy white-label veterinary clinic partnerships to bypass retail shelf access barriers.
For Investors and Strategic Acquirers: Focused laboratories with clinically tested active ingredient portfolios and established EFSA monograph libraries represent priority acquisition targets, offering regulatory pre-clearance assets that compress time-to-market for platform rollups. Subscription attach rates and telehealth integration depth signal platform viability across the analysis window.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Substantiation Investment | FDA and AAFCO trials for structure-function claims defend premium positioning against commodity competitors. |
| Microencapsulation Technology Licensing | Spray-congealing process access from Yangtze River Delta clusters extends shelf-life claims to 24 months. |
| Veterinary Clinic White-Label Partnership | Direct-to-consumer subscription platforms capture recurring revenue from chronic joint and cognitive protocols. |
| Marine Lipid Backward Integration | Captive refining of Peruvian and Norwegian EPA/DHA concentrates insulates margin from catch quota restrictions. |
| EU F-Gas Regulation Compliance Retrofit | Low-carbon refrigerant conversion in spray-drying facilities unlocks premium channel access across European markets. |
Study Parameters
Cross-validation between primary interviews with veterinary clinic procurement managers, formulation chemists, and distribution channel heads and secondary sources including FDA CVM submission databases, EFSA Feed Additives Register entries, and AAFCO ingredient definition proceedings anchors the qualitative findings. Bottom-up SKU-level analysis triangulates against top-down manufacturer capacity assessments across spray-drying and microencapsulation facilities.
Sensitivity analysis around marine lipid price volatility and probiotic strain stability degradation rates tests forecast robustness across the projection horizon. Segmentation dimensions span product chemistry, animal metabolism, formulation technology, and channel access, with CAGRs derived from installed base expansion and per-pet expenditure trajectory modeling. Regulatory authorization timelines and cold-chain infrastructure development pace serve as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under sustained companion animal premiumization and EU Green Deal compliance enforcement; material deviation in clinical substantiation cost curves or marine fishery quota allocations would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Canine Arthritis Market
Veterinary
Veterinary Ultrasound Market
Veterinary
Veterinary Intravenous (IV) Solutions Market
Veterinary
Canine Separation Anxiety Treatment Market
Veterinary
Orthopedic Dog Bed Market
Veterinary
Global Veterinary Holters Market
Veterinary
Global Animal Sedative Market
Veterinary
Global Veterinary Rapid Test Market
Veterinary
Veterinary Thermography Market
Veterinary
Bovine Mastitis Treatment System Market
Veterinary
Veterinary Disinfectants Market
Veterinary
Europe Veterinary Vaccine Market
Veterinary
Companion Animal Vaccines Market
Veterinary
Global Veterinary Artificial Insemination Market
Veterinary
Veterinary Progesterone Testing Market
Veterinary
France Veterinary Healthcare Market