
 Global Animal Vaccine Market | 2026-2036
Global Animal Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Animal Vaccine Market Foresight
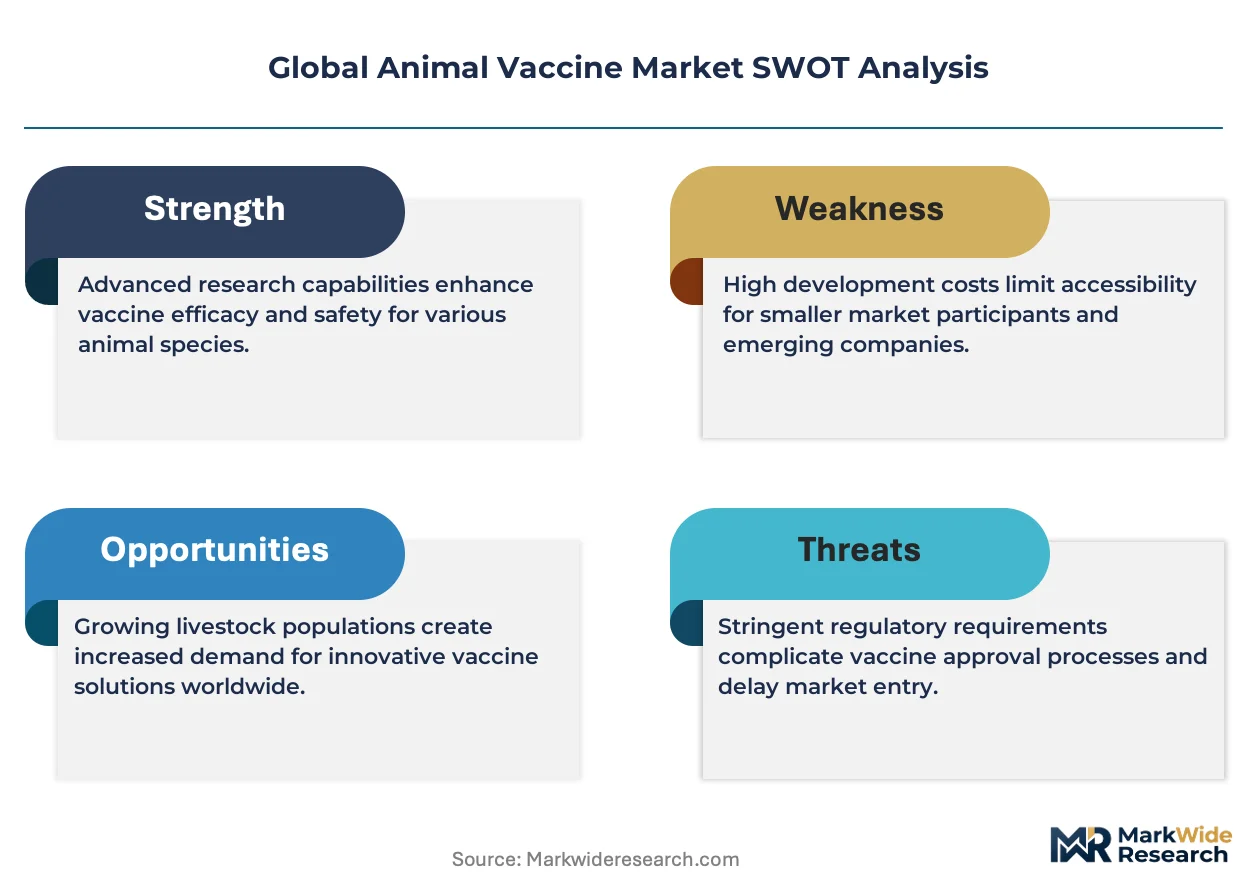
mRNA platform technology is expanding from human pharmaceuticals into veterinary applications, reducing development timelines for emerging zoonotic threats. Zoetis leverages its multi-species manufacturing network across North America and Europe to sustain supply security for livestock and companion animal portfolios. Boehringer Ingelheim anchors its position through deep R&D investment in vector-based platforms for swine and poultry respiratory diseases. Merck Animal Health differentiates by controlling distribution through direct veterinary clinic partnerships in developed markets.
Animal vaccines are biological preparations containing attenuated, inactivated, or recombinant antigenic material designed to stimulate adaptive immunity in non-human species, with formulations typically requiring adjuvant systems and cold-chain preservation between 2°C and 8°C to maintain titer potency. Their primary purpose is preventing infectious disease in food-producing and companion animals, thereby reducing antimicrobial use and securing protein supply chains. Live Attenuated vaccines occupy the largest value share due to durable cellular immunity and single-dose convenience in ruminant programs, while Recombinant platforms represent the fastest-expanding category as precision antigen engineering enables DIVA-compliant differentiation between infected and vaccinated animals. Injectable administration dominates volume because of reliable dosing accuracy, though Oral delivery is gaining structural importance in mass aquaculture and free-range poultry settings where handling stress must be minimized.
The USDA Center for Veterinary Biologics enforces potency and purity standards that shape product registration timelines and label claims for US-marketed vaccines, while EMA's Committee for Medicinal Products for Veterinary Use coordinates batch release protocols across EU member states. India's CDSCO and the country's national veterinary regulator impose parallel import licensing and local stability testing requirements that condition market access for multinational suppliers. Stakeholders must monitor how evolving regulatory convergence on nucleic acid platform safety will determine which manufacturing technologies receive accelerated approval pathways versus extended field efficacy requirements.
Market Dynamics
mRNA platform migration from human to veterinary applications is compressing development timelines for emerging zoonotic threats while forcing incumbents to retool manufacturing assets or risk obsolescence in the next product cycle.
Growth Catalysts
- EMA Cold-Chain Standards:Tightened distribution requirements for thermolabile biologicals are accelerating investment in validated cold-chain infrastructure across European logistics networks.
- India National Livestock Health Missions:Government-funded programs are widening vaccine access through dairy cooperatives, creating structured procurement channels for multivalent ruminant formulations.
- Foot-and-Mouth Disease Eradication:Brazilian livestock farmers are scaling preventive immunization programs, generating sustained demand for high-potency adjuvanted vaccines.
Market Restraints
- Adjuvant Input Volatility:Saponin and oil-emulsion adjuvant raw materials face price instability due to concentrated botanical extraction sourcing.
- Cold-Chain Infrastructure Gaps:Last-mile temperature control failures in tropical climates degrade titer potency before administration.
- DIVA Compliance Complexity:Differentiation between infected and vaccinated animals requires precision antigen engineering that extends regulatory review timelines.
Strategic Opportunities
- Aquaculture Oral Delivery:Mass vaccination of free-range fish stocks through feed-administered formulations eliminates handling stress and labor costs.
- USDA Accelerated Pathways:The Center for Veterinary Biologics is streamlining nucleic acid platform safety reviews for emergency zoonotic threats.
- Companion Animal mRNA:Precision cancer vaccines for canine oncology represent untapped white space with premium pricing potential.
Industry Challenges
- Vector Platform Talent Scarcity:Shortage of molecular biologists trained in viral vector construction limits R&D throughput for swine and poultry respiratory programs.
- Batch Release Bottlenecks:EMA Committee for Medicinal Products for Veterinary Use coordination across member states creates variable approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Animal Vaccine Market |
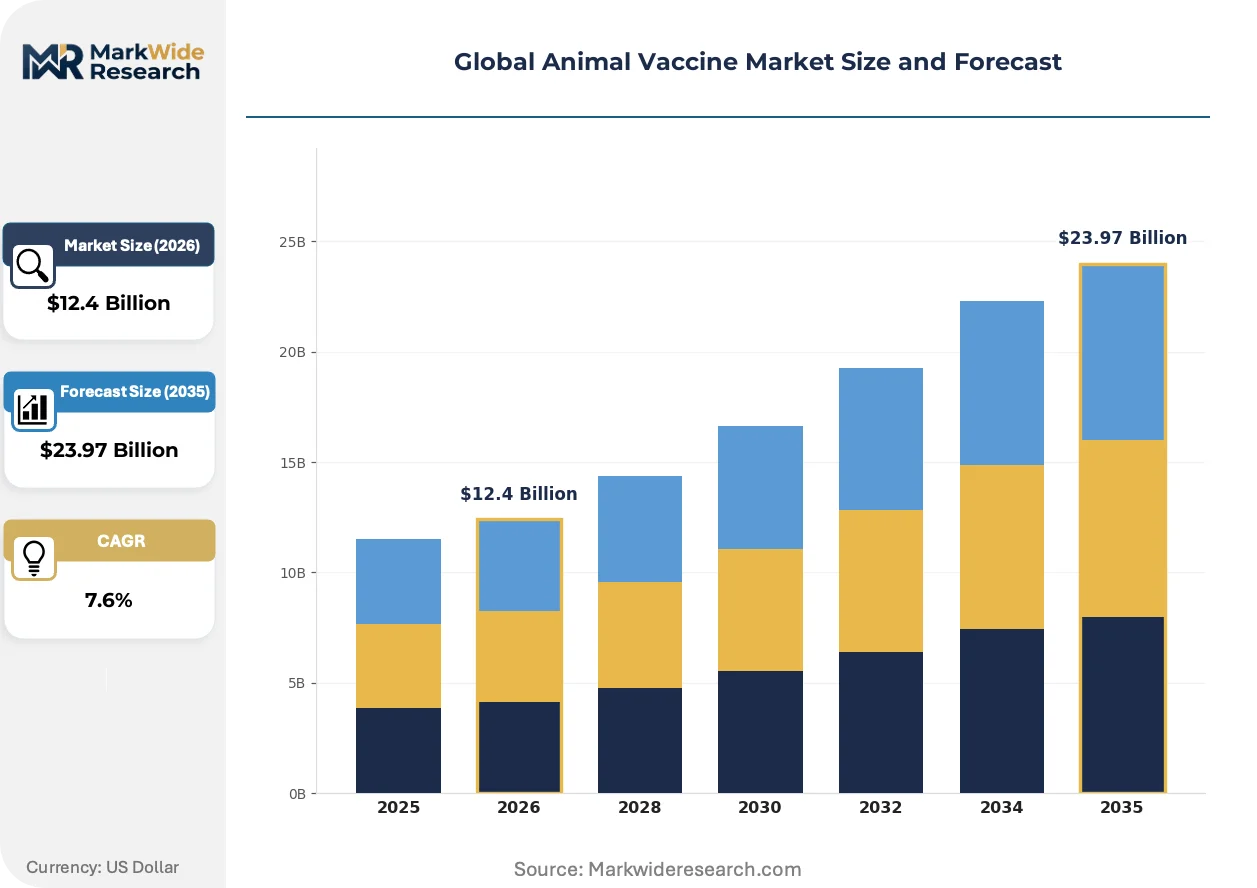
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $23.97 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Live Attenuated, Inactivated, Subunit, Recombinant, Toxoid Target Species: Companion Animals, Poultry, Aquatic Animals, Livestock, Equines Vaccination Method: Injectable, Oral, Nasal, Topical, Aerosol End User: Veterinary Clinics, Research Institutions, Pharmaceutical Manufacturers, Livestock Farmers, Zoos |
| Companies Covered | Zoetis, Boehringer Ingelheim, Merck Animal Health, Elanco Animal Health, Ceva Santé Animale, Virbac, Bayer, Phibro Animal Health Corporation, Biogénesis Bagó, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Animal Vaccine Market Shifts & Advancements
Platform technology convergence and regulatory pathway evolution are redistributing competitive advantage away from traditional attenuated vaccine incumbents toward nucleic acid and vector-based specialists with modular manufacturing capabilities.
Recombinant antigen engineering is expanding into veterinary applications as precision tools enable marker vaccine designs that satisfy DIVA compliance requirements. Poultry integrators in Brazil and Thailand are adopting these platforms to maintain export eligibility under OIE guidelines. This shift is compressing the competitive moat previously held by live attenuated incumbents with decades of field efficacy data.
REACH and RoHS substance restrictions are forcing reformulation of legacy adjuvant systems across European manufacturing operations. EMA guidance on residual host cell protein thresholds is tightening purity specifications for recombinant products. Vector-based platform developers are responding by investing in chemically defined production media to preempt regulatory rejection.
Dairy cooperatives in India are consolidating procurement decisions under state veterinary officers, displacing fragmented individual farmer purchasing. This buyer concentration is shifting pricing power toward volume-committed suppliers with cold-chain distribution partnerships. The structural change is most visible in Gujarat and Maharashtra, where cooperative-managed vaccination camps now account for the majority of multivalent ruminant doses administered.
Global Animal Vaccine Market Segmentation
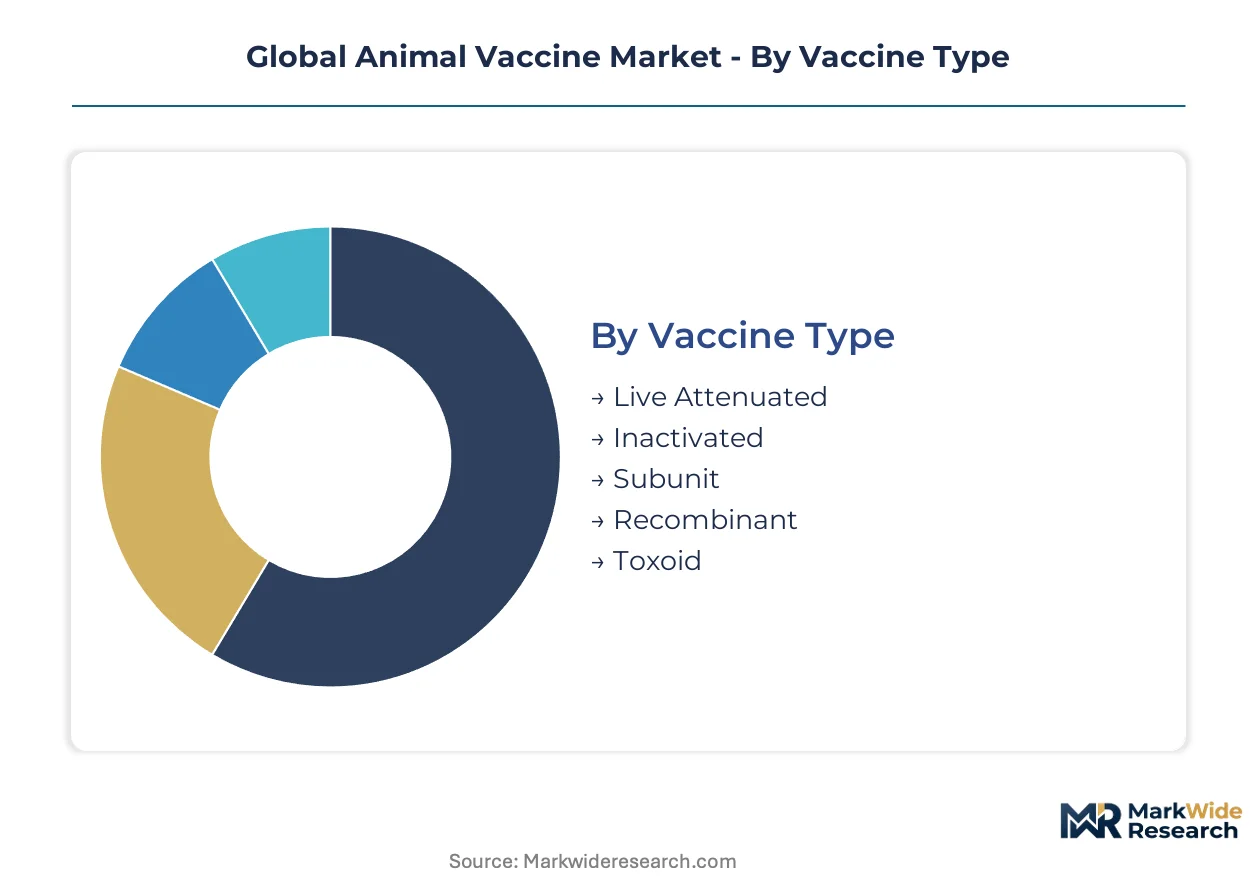
Segmentation in animal vaccines reveals how formulation technology, species-specific disease economics, and administration logistics create distinct competitive arenas with divergent margin profiles and regulatory pathways.
Vaccine Type:
Integration depth varies sharply: live attenuated and inactivated platforms function as standalone immunization systems, while recombinant and subunit technologies embed into precision diagnostic-DIVA workflows requiring companion assay infrastructure.
- Live Attenuated:Formulations contain weakened pathogen strains that replicate briefly to stimulate cellular and humoral immunity without causing disease. Brazilian livestock farmers deploy these in national foot-and-mouth eradication campaigns where single-dose convenience reduces labor costs in extensive grazing systems.
- Recombinant:Precision antigen engineering enables marker vaccine designs that differentiate infected from vaccinated animals through companion serological tests. Poultry integrators in Thailand adopt these platforms to maintain OIE export eligibility, compressing the competitive advantage of legacy attenuated incumbents.
- Inactivated:Killed pathogen preparations require adjuvant enhancement and multi-dose regimens for durable protection.
- Subunit:Purified protein or polysaccharide antigens eliminate risk of reversion to virulence in sensitive populations.
- Toxoid:Formalin-inactivated exotoxins generate antitoxin immunity against clostridial diseases in ruminants.
Volume placements concentrate in Live Attenuated; the steepest expansion trajectory belongs to Recombinant.
Target Species:
Cost tier stratification separates premium-priced companion animal oncology vaccines from commodity-scale livestock prophylaxis, with aquaculture occupying an emerging middle tier where feed-administered delivery commands formulation premiums.
- Livestock:Cattle, swine, and small ruminant programs drive the largest absolute dose volumes through government-funded eradication initiatives and cooperative procurement channels. India's national livestock health missions channel multivalent formulations through Gujarat and Maharashtra dairy cooperatives, consolidating fragmented farmer purchasing under state veterinary officers.
- Companion Animals:Canine and feline vaccines command pricing multiples over food-animal equivalents, with mRNA platform developers targeting precision cancer immunotherapy as untapped white space.
- Poultry:Intensive vertical integration favors mass-administration formats and respiratory disease focus.
- Aquatic Animals:Oral delivery through feed eliminates handling stress in net-pen and pond systems.
- Equines:Performance and breeding stock sustain premium tetanus, influenza, and herpesvirus protocols.
Revenue concentrates in Livestock; margin expansion is climbing the fastest in Companion Animals.
Vaccination Method:
Application context dictates method selection: injectable formats dominate where dosing accuracy and regulatory traceability are paramount, while oral and aerosol routes gain ground in settings where animal handling stress degrades welfare metrics and labor economics.
- Injectable:Parenteral administration via subcutaneous or intramuscular routes ensures precise antigen delivery and reliable immune response. USDA Center for Veterinary Biologics potency standards reinforce injectable dominance in US-licensed products where label claims require documented titer preservation.
- Oral:Feed-administered or drinking-water formulations enable mass vaccination without physical restraint. Free-range poultry operations and aquaculture net-pen systems in Brazil and Thailand are adopting these methods to minimize cortisol-mediated immunosuppression and labor injury risk.
- Nasal:Mucosal delivery stimulates local IgA immunity for respiratory pathogens.
- Topical:Skin-patch or pour-on applications suit parasite-vector control combinations.
- Aerosol:Nebulized administration reaches large poultry house populations simultaneously.
Volume placements concentrate in Injectable; the fastest uptake is gaining share in Oral.
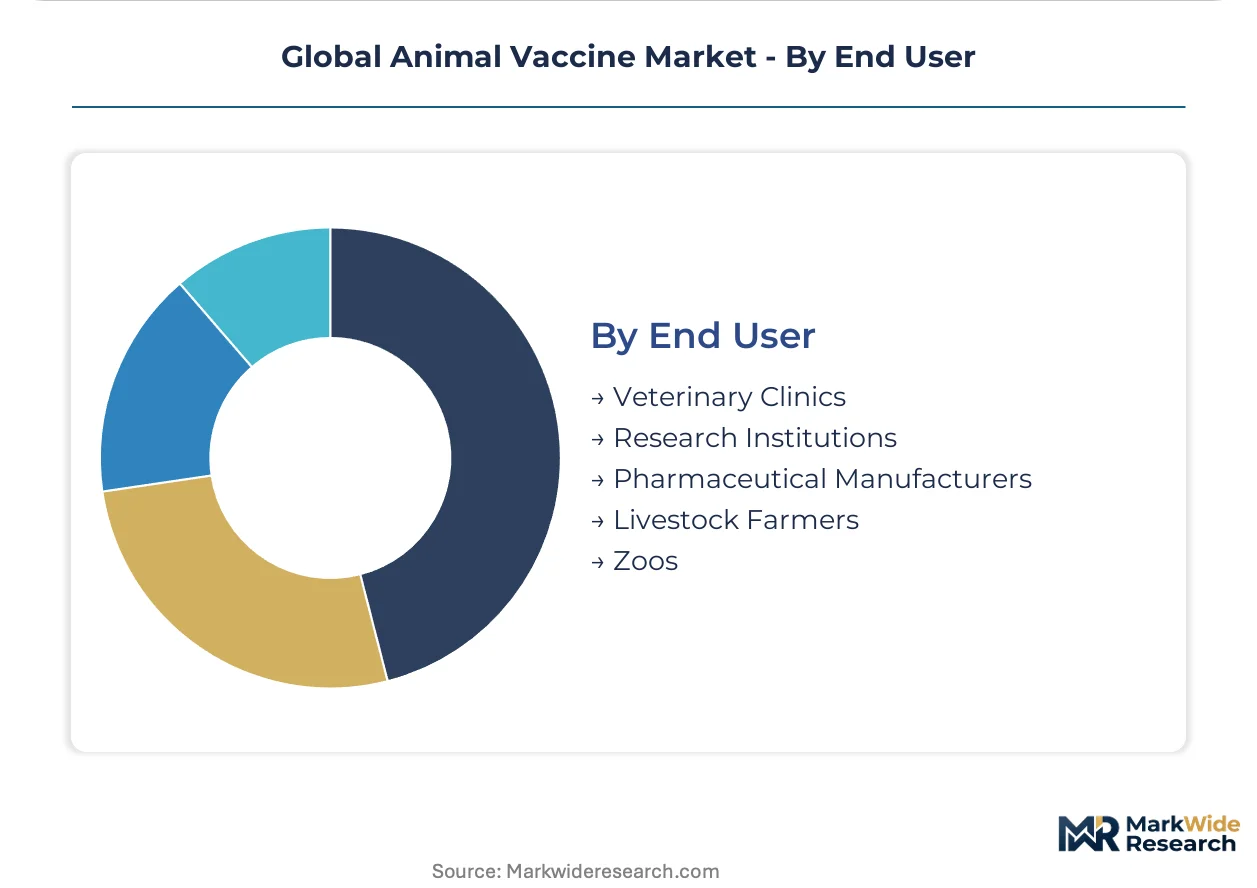
End User:
Customer type determines procurement scale and technical support intensity: livestock farmers and poultry integrators purchase through volume-committed distribution partnerships, while veterinary clinics sustain premium pricing through direct prescriber relationships and cold-chain custody guarantees.
- Veterinary Clinics:Small-animal and equine practices control companion animal vaccine selection through prescriber authority and client education. Merck Animal Health anchors its position through direct clinic partnerships in developed markets, capturing premium pricing via cold-chain integrity guarantees and staff training programs.
- Livestock Farmers:Dairy and beef operations in Brazil, India, and the European Union purchase through cooperative procurement or government tender channels. EMA cold-chain distribution standards for thermolabile biologicals are accelerating validated logistics investment across European veterinary networks serving this segment.
- Research Institutions:Academic and government laboratories drive early-stage platform validation and field efficacy trials.
- Pharmaceutical Manufacturers:Contract production and bulk antigen supply relationships support outsourced manufacturing.
- Zoos:Exotic species collections require customized formulations and import licensing for non-standard species.
Volume placements concentrate in Livestock Farmers; the premium expansion belongs to Veterinary Clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Brazil, India, and Germany concentrate vaccine manufacturing capacity through tax-advantaged status and streamlined regulatory pathways. National livestock health programs and export-oriented veterinary biologics clusters drive demand localization across these jurisdictions.
United States
The USDA Center for Veterinary Biologics enforces potency standards that shape registration timelines for domestic and imported products. Kansas and Iowa host dense livestock production corridors where feedlot operators purchase multivalent respiratory vaccines through veterinary distributor networks. Merck Animal Health maintains direct clinic partnerships across developed coastal markets.
Brazil
Livestock farmers in Mato Grosso and São Paulo states scale preventive immunization against foot-and-mouth disease through cooperative procurement channels. ANVISA coordinates with state agricultural secretariats to validate cold-chain distribution for thermolabile biologicals. The São Paulo metropolitan cluster anchors Latin America's largest veterinary pharmaceutical manufacturing base.
India
Government-funded national livestock health missions channel multivalent ruminant formulations through Gujarat and Maharashtra dairy cooperatives. CDSCO imposes parallel import licensing and local stability testing requirements that condition market access for multinational suppliers. Punjab's dairy belt concentrates demand for brucellosis and hemorrhagic septicemia programs.
Germany
EMA's Committee for Medicinal Products for Veterinary Use coordinates batch release protocols across EU member states from its Amsterdam and London liaison offices. Lower Saxony's dense swine production regions generate sustained demand for porcine reproductive and respiratory syndrome vaccines. Bavarian biotechnology clusters specialize in recombinant platform development for DIVA-compliant marker vaccines.
Thailand
Poultry integrators in the Central Plains and Eastern Economic Corridor adopt recombinant platforms to maintain OIE export eligibility for processed chicken products. The national veterinary regulator enforces alignment with ASEAN harmonized standards for avian influenza vaccination. Bangkok-based logistics hubs coordinate temperature-controlled distribution to Indonesian and Vietnamese markets.
Global Animal Vaccine Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated pharmaceutical conglomerates commanding livestock portfolios while focused biologics firms capture companion animal premiums. The structure tilts toward consolidation among species-spanning manufacturers with captive antigen production and multi-continent distribution networks. Three archetypes dominate: human-health spin-offs with veterinary divisions, family-owned animal health pure-plays, and emerging platform-technology specialists. Capacity expansion and strategic technology licensing represent the primary competitive moves as nucleic acid platforms compress development timelines.
Among human-health spin-offs with veterinary divisions, Zoetis and Boehringer Ingelheim exemplify the integrated archetype with multi-species manufacturing networks spanning North America and Europe. Merck Animal Health occupies a distinct position through its emphasis on direct veterinary clinic relationships in developed markets, anchoring premium pricing via cold-chain custody guarantees and prescriber education programs.
| Leading Market Players |
|---|
| Zoetis |
| Boehringer Ingelheim |
| Merck Animal Health |
| Elanco Animal Health |
| Ceva Santé Animale |
| Virbac |
| Bayer |
| Phibro Animal Health Corporation |
| Biogénesis Bagó |
| Others |
Supply & Pricing Matrix
Premium-mid-economy pricing differentiation between companion animal oncology mRNA platforms and commodity livestock multivalent formulations manifests in divergent supply chain configurations, with cold-chain custody requirements and adjuvant raw material sourcing driving cost structures across tiers.
Pricing Analysis
Volume placements concentrate in injectable live attenuated platforms for ruminant programs, while margin expansion climbs fastest in recombinant companion animal vaccines with DIVA-compliant diagnostic pairing. Pricing stratifies across premium, standard, and economy tiers based on formulation complexity and cold-chain validation certification. Cost compression in commodity livestock segments intensifies because dairy cooperative procurement consolidation in India and Brazil forces volume-discount negotiations. Veterinary clinics in developed markets exhibit least price sensitivity due to prescriber authority and pet owner willingness-to-pay for premium immunotherapy.
Supply Chain Analysis
India's CDSCO local stability testing requirements and Brazil's ANVISA cold-chain validation mandates are reshaping sourcing patterns for multinational suppliers. Manufacturing concentration rests on Germany, the United States, and India for recombinant platform production and fill-finish operations. Saponin adjuvant feedstock draws from concentrated botanical extraction in South America and Southeast Asia, while oil-emulsion components hinge on refined petroleum derivatives. Single-source vulnerability in saponin botanical supply creates formulation bottleneck risk. Distribution runs through veterinary distributor networks in livestock corridors and direct clinic partnerships in companion animal segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained adjuvant raw material availability and validated cold-chain capacity shortages prop pricing power for incumbents with captive manufacturing infrastructure.
For Market Incumbents: Cement market position by deepening backward integration into saponin extraction and oil-emulsion adjuvant production to neutralize input volatility. Add fill-finish capacity in Lower Saxony and São Paulo metropolitan clusters to preempt EMA and ANVISA distribution bottlenecks. Vector platform talent scarcity limits R&D throughput for respiratory programs; acquire molecular biology specialists with viral vector construction expertise. For New Entrants and Emerging Players: Capture white space in aquaculture oral delivery formulations for Brazilian and Thai net-pen operators seeking handling-stress reduction. Target canine oncology mRNA precision vaccines where premium pricing multiples exceed livestock commodity benchmarks. Pursue USDA accelerated pathway partnerships for emergency zoonotic nucleic acid platforms to compress regulatory timelines versus field efficacy requirements. For Investors and Strategic Acquirers: Re-rating potential sits with modular manufacturing specialists given mRNA platform migration compressing development timelines. Long-term viability favors platform-technology firms with chemically defined production media capabilities over legacy attenuated incumbents. Watch EMA-EMA Committee for Medicinal Products for Veterinary Use batch release protocol harmonization as inflection indicator for regulatory pathway efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adjuvant Production | Captive saponin extraction neutralizes botanical supply volatility threatening formulation costs. |
| Cold-Chain Infrastructure Expansion | Validated logistics investment across European networks satisfies EMA thermolabile distribution standards. |
| mRNA Platform Technology Licensing | Modular manufacturing capabilities compress development timelines for emerging zoonotic threats. |
| DIVA-Compliant Diagnostic Pairing | Companion serological test bundling sustains premium pricing in OIE-export poultry integrator segments. |
| Direct Veterinary Clinic Partnerships | Prescriber authority and cold-chain custody guarantees anchor premium positioning in developed markets. |
Research Methodology
Independent corroboration across regulatory submission databases, customs trade records, and veterinary procurement contracts underwrites the qualitative findings. Primary interviews with vaccine development executives, regulatory affairs leads at EMA and USDA, dairy cooperative procurement officers, and veterinary clinic practice managers combined with secondary validation from FDA Center for Veterinary Biologics filings, EMA Committee for Medicinal Products for Veterinary Use batch release protocols, and CDSCO import licensing records. Bottom-up dose-volume modeling and top-down market sizing triangulate value estimates across segments.
Rate-of-change decomposition across the analysis window isolates volume drivers from price-mix effects in livestock versus companion animal segments. The analytical framework models vaccine type, target species, administration method, and end-user channel dimensions throughout the forecast period. CAGRs derive from segment-level growth rate reconciliation against macro livestock population trends and government immunization program budget trajectories. Adjuvant input cost indices and cold-chain infrastructure investment pipelines inform margin projection sensitivity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory convergence on nucleic acid platform safety standards and zoonotic disease emergence frequency. Forecasts reflect documented assumptions regarding cooperative procurement consolidation rates and EMA batch release timeline harmonization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
US Surgical Pet Collar Market
Veterinary
Rabies Veterinary Vaccines Market
Veterinary
Veterinary CRO and CDMO Market
Veterinary
Pet Hypothyroidism Therapy Market
Veterinary
Veterinary Antimicrobial Susceptibility Testing Market
Veterinary
Veterinary Wound Sprays Market
Veterinary
Global Porcine Vaccine Market
Veterinary
Spain Veterinary Healthcare Market
Veterinary
Spay and Neuter Market
Veterinary
Global Animal Sedative Market
Veterinary
Mexico Veterinary Healthcare Market
Veterinary
Orthopedic Dog Bed Market
Veterinary
Japan Veterinary Healthcare Market
Veterinary
Global Orthopedic Veterinary Implants Market
Veterinary
France Veterinary Healthcare Market
Veterinary
Clonorchiasis Market