
 Global Animal Antimicrobials and Antibiotics Market | 2026-2036
Global Animal Antimicrobials and Antibiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Animal Antimicrobials and Antibiotics Market Analysis
Modular dosing formats are shifting buyer preference across the animal health sector, with premix concentrates and water-soluble granules replacing bulk powder transactions. Zoetis Inc. leverages its manufacturing scale to dominate injectable cephalosporin supply chains. Boehringer Ingelheim anchors European ruminant antibiotic demand through specialized vaccine-antibiotic bundling programs. Elanco Animal Health differentiates via channel control over veterinary clinic networks in North American livestock regions.
Animal antimicrobials and antibiotics comprise therapeutically active compounds—tetracyclines, penicillins, macrolides, and aminoglycosides—formulated for administration through oral, injectable, topical, or intrauterine routes to treat or prevent bacterial infections in food-producing and companion animals. These agents function through mechanisms including protein synthesis inhibition, cell wall disruption, or nucleic acid interference, with potency measured by minimum inhibitory concentration against target pathogens. Tetracyclines occupy the largest product category due to broad-spectrum efficacy and cost-efficient mass production, while macrolides represent the fastest-expanding segment driven by respiratory disease management in dense poultry and swine operations. End-user demand concentrates in poultry and swine sectors where intensive confinement elevates infection pressure, with aquaculture emerging as a specialized growth pocket requiring water-stable formulations.
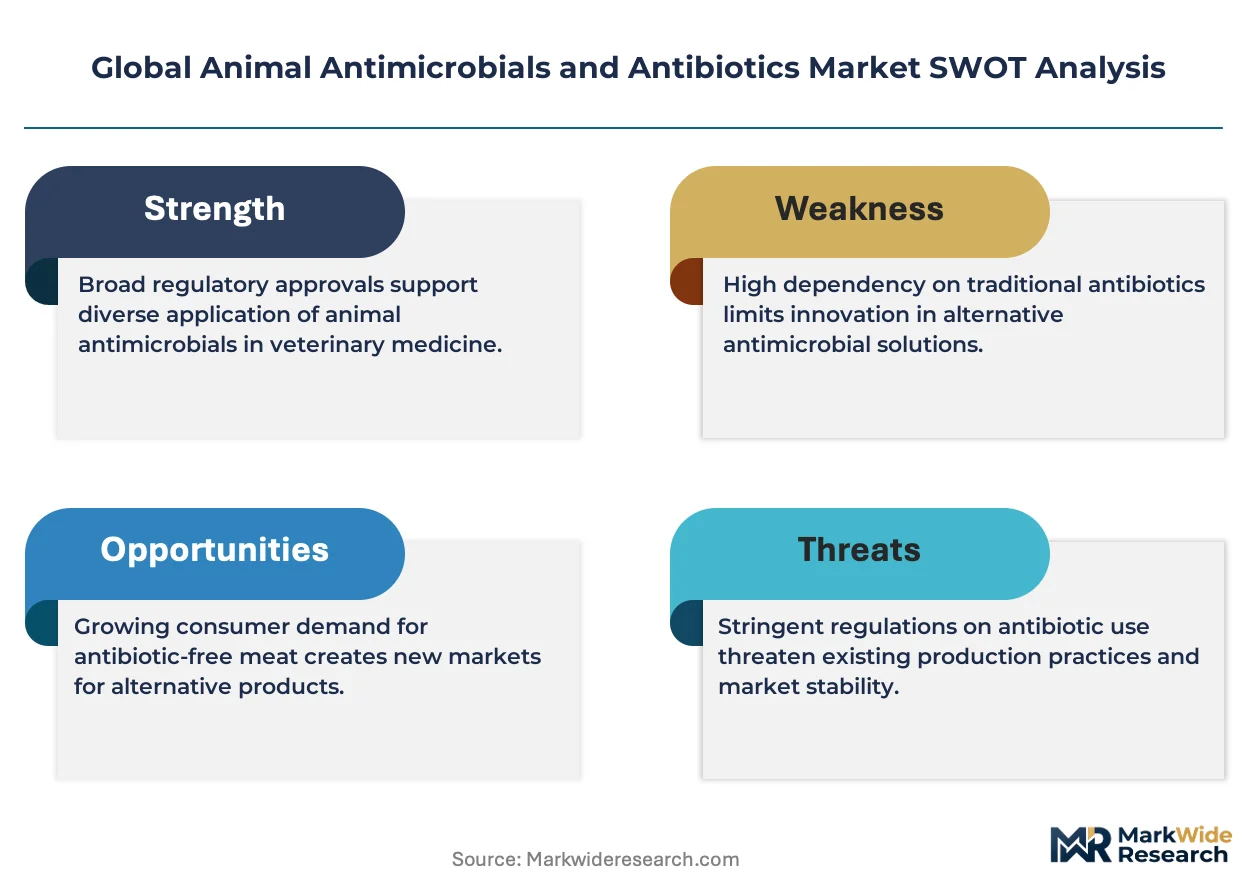
The FDA's Veterinary Feed Directive reshapes US market access by mandating veterinary oversight for medically important antibiotics in feed. EMA's revised guidelines on antimicrobial resistance further tighten residue monitoring across EU member states, compelling reformulation investments. China's Ministry of Agriculture and Rural Affairs enforces withdrawal period compliance through GB standards testing at slaughter facilities. Stakeholders must monitor regulatory divergence between jurisdictions while calibrating product portfolios toward precision-delivery technologies that satisfy evolving compliance thresholds.
Market Dynamics
Antimicrobial resistance surveillance networks are compressing product lifecycles across veterinary pharmaceutical portfolios, forcing manufacturers to accelerate reformulation cycles while maintaining residue compliance across divergent national testing protocols.
Growth Catalysts
- Brazil's integrated broiler sector:Vertical coordination across São Paulo and Paraná production clusters accelerates veterinary pharmaceutical uptake through centralized procurement.
- FDA Veterinary Feed Directive:Mandatory veterinary oversight for medically important antibiotics in feed redirects investment toward precision-delivery technologies and diagnostic bundling.
- Water-soluble granule formulations:These dosing formats reduce labor costs in intensive swine operations and enable real-time medication adjustments via automated drinking systems.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient manufacturing clusters in Zhejiang and Jiangsu provinces create single-point vulnerability for tetracycline and penicillin derivatives.
- EU Veterinary Medicines Regulation:Prophylactic use restrictions eliminate historical revenue streams and compplicate portfolio rebalancing toward therapeutic-only indications.
- Residue testing infrastructure gaps:Slaughter facility laboratory capacity constraints in secondary Brazilian and Chinese provinces delay batch release and extend working capital cycles.
Strategic Opportunities
- Vietnam aquaculture expansion:Pangasius and shrimp intensification creates demand for water-stable formulations currently undersupplied by terrestrial-focused manufacturers.
- Vaccine-antibiotic bundling:Metaphylaxis protocols in North American cattle feedlots favor integrated health program suppliers over standalone antibiotic vendors.
- GB standards harmonization:China's Ministry of Agriculture and Rural Affairs enforcement of withdrawal period compliance creates first-mover advantage for residue-mapping service providers.
Industry Challenges
- Pharmacovigilance data integration:Veterinary clinic networks lack interoperable adverse event reporting systems, complicating post-market surveillance obligations under EMA guidelines.
- Multi-jurisdictional registration:Divergent residue limit standards between FDA, EMA, and China's NMPA extend product launch timelines and inflate regulatory affairs headcount requirements.
- Cold chain integrity for biologic-antibiotic combinations:Temperature excursions during last-mile distribution to remote livestock operations degrade efficacy and trigger compliance documentation failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Animal Antimicrobials and Antibiotics Market |
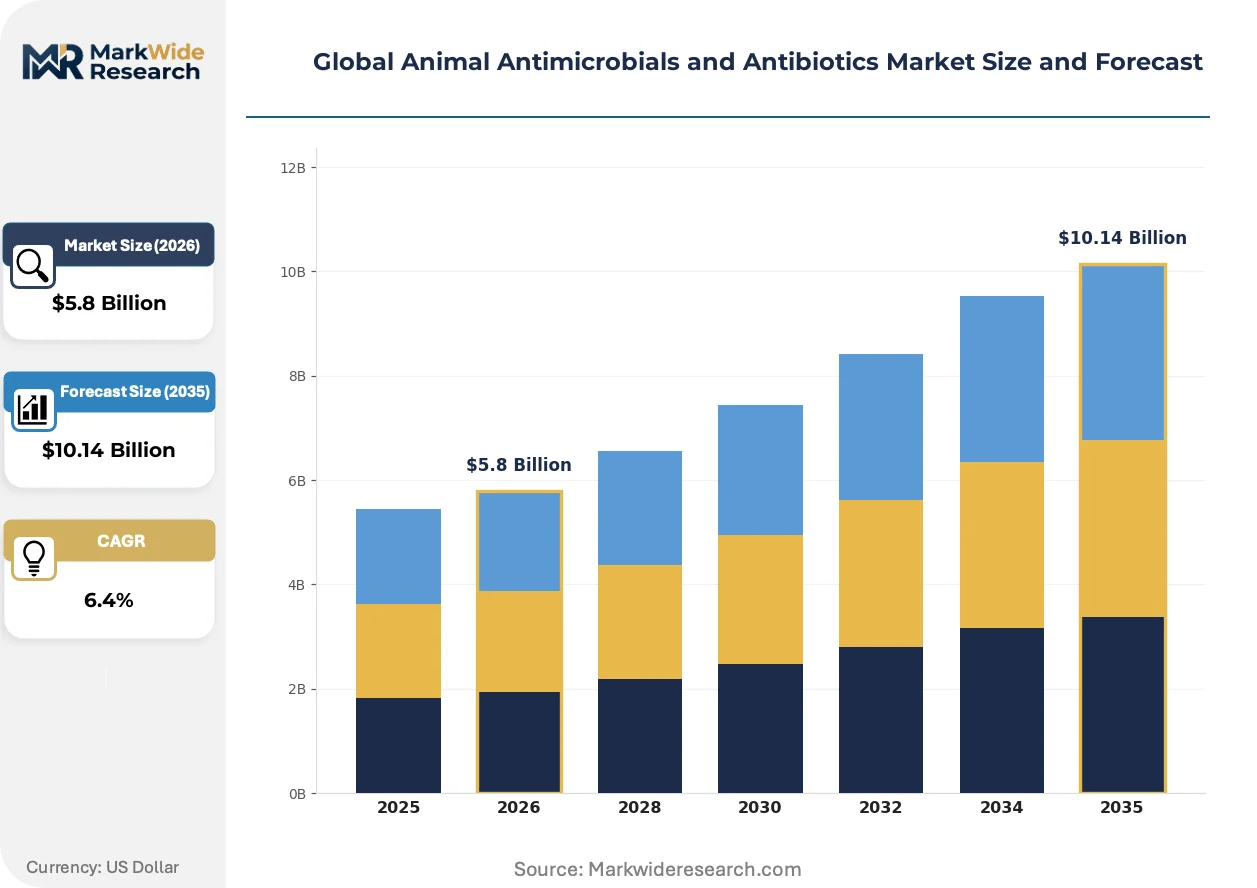
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tetracyclines, Penicillins, Macrolides, Aminoglycosides End User: Poultry, Swine, Ruminants, Aquaculture Administration Route: Oral, Injectable, Topical, Intrauterine Geographical Segment: Developed Markets, Developing Markets, Emerging Markets, Others |
| Companies Covered | Zoetis Inc., Boehringer Ingelheim, Elanco Animal Health, Merck & Co., Phibro Animal Health, Virbac, Vetoquinol, Ceva Santé Animale, Dechra Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Animal Antimicrobials and Antibiotics Market Emerging Trajectories
Precision livestock monitoring systems are rewiring how antimicrobial interventions are triggered, replacing calendar-based protocols with real-time pathogen detection and individual animal health scoring.
Pharmacogenomic dosing platforms are unifying diagnostic testing with treatment selection in poultry operations. Integrators in Thailand and Mexico deploy these systems to reduce empirical antibiotic use. The technology is unifying veterinary decision-making with supply chain traceability requirements, compressing the gap between detection and targeted intervention.
EMA's revised antimicrobial resistance guidelines tighten residue monitoring across member states. Slaughter facilities in Germany and Poland now deploy rapid screening assays for macrolide and cephalosporin traces. Tetracycline manufacturers face reformulation investments to meet descending maximum residue limits in pork and poultry matrices.
Buyer consolidation among North American protein processors alters procurement leverage. Large integrators now mandate vendor-managed inventory for veterinary pharmaceuticals, shifting working capital burdens upstream. This concentration is most visible in the US Midwest, where three beef packers control antibiotic formularies for contracted feedlots.
Global Animal Antimicrobials and Antibiotics Market Segmentation
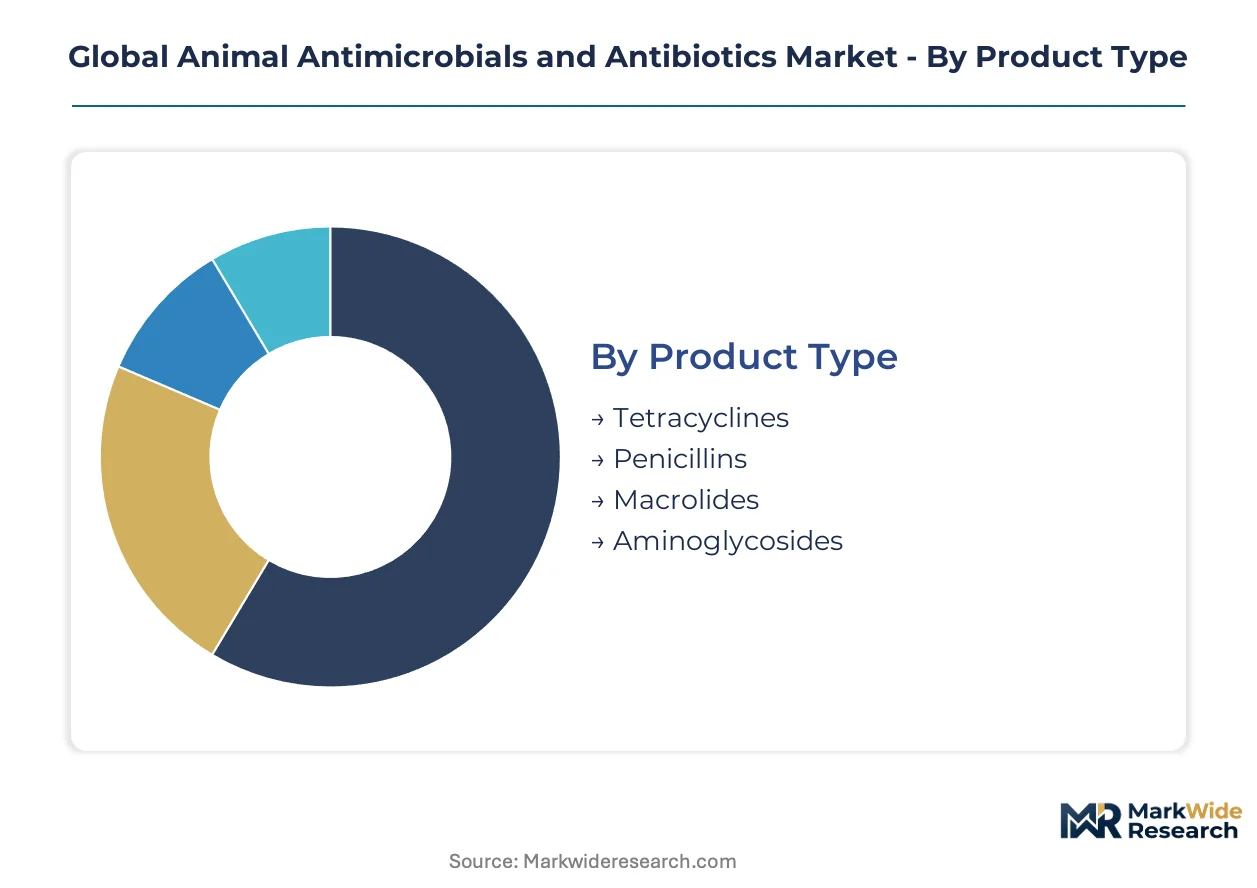
Segmentation in animal antimicrobials reveals divergent margin structures across chemical classes and species applications. Route of administration determines cold chain requirements and veterinary labor intensity, while geographic tiers reflect regulatory maturity rather than pure income levels.
Product Type:
Volume leaders dominate through feed-grade manufacturing scale, while premium niches command higher margins through respiratory specialization.
- Tetracyclines:Broad-spectrum bacteriostatic agents inhibit protein synthesis across gram-positive and gram-negative pathogens. Demand concentrates in Brazilian and Chinese swine operations where cost-efficient mass prophylaxis remains economically rational despite tightening residue protocols.
- Macrolides:These 14- to 16-membered lactone rings deliver superior lung tissue penetration for respiratory pathogens. North American cattle feedlots and Southeast Asian poultry integrators drive uptake as metaphylaxis protocols replace mass medication with targeted herd health interventions.
- Penicillins:Beta-lactam cell wall synthesis inhibitors retain dominance in mastitis therapy for dairy operations across Germany and the Netherlands.
- Aminoglycosides:Irreversible protein synthesis blockers serve narrow therapeutic niches in equine and companion animal practice where nephrotoxicity constraints limit agricultural use.
Today's leader: Tetracyclines. Tomorrow's challenger: Macrolides.
End User:
Species-specific disease pressure and confinement density determine antibiotic throughput per animal unit.
- Poultry:Intensive broiler houses in São Paulo and Paraná production clusters generate concentrated demand for respiratory and enteric disease management through automated drinking water medication systems.
- Swine:Post-weaning multisystemic wasting syndrome drives injectable cephalosporin and macrolide consumption in Danish and Spanish farrow-to-finish operations.
- Ruminants:Metaphylaxis at feedlot arrival anchors antibiotic use in US High Plains and Alberta beef production systems.
- Aquaculture:Water-stable formulations for pangasius and shrimp operations in Vietnam's Mekong Delta represent the steepest expansion trajectory as terrestrial manufacturers adapt to aquatic pharmacokinetics.
Species concentration: Poultry holds volume primacy. Aquaculture offers the most rapid growth runway.
Administration Route:
Delivery modality shapes labor economics, bioavailability requirements, and regulatory documentation burdens.
- Oral:Feed premixes and water-soluble granules dominate mass medication in integrated poultry and swine systems, with automated dosing equipment reducing veterinary labor costs.
- Injectable:Long-acting formulations command premium positioning in cattle feedlots and dairy operations where individual animal handling costs favor extended withdrawal period coverage.
- Topical:Intramammary infusions and wound treatments serve specialized dairy and equine applications with limited scale potential.
- Intrauterine:Postpartum uterine therapies address retained placenta protocols in dairy herds across France and northern Italy.
Route hierarchy: Oral delivery sustains volume leadership. Injectable formats capture value concentration.
Geographical Segment:
Regulatory stringency and veterinary infrastructure maturity create tiered market access conditions.
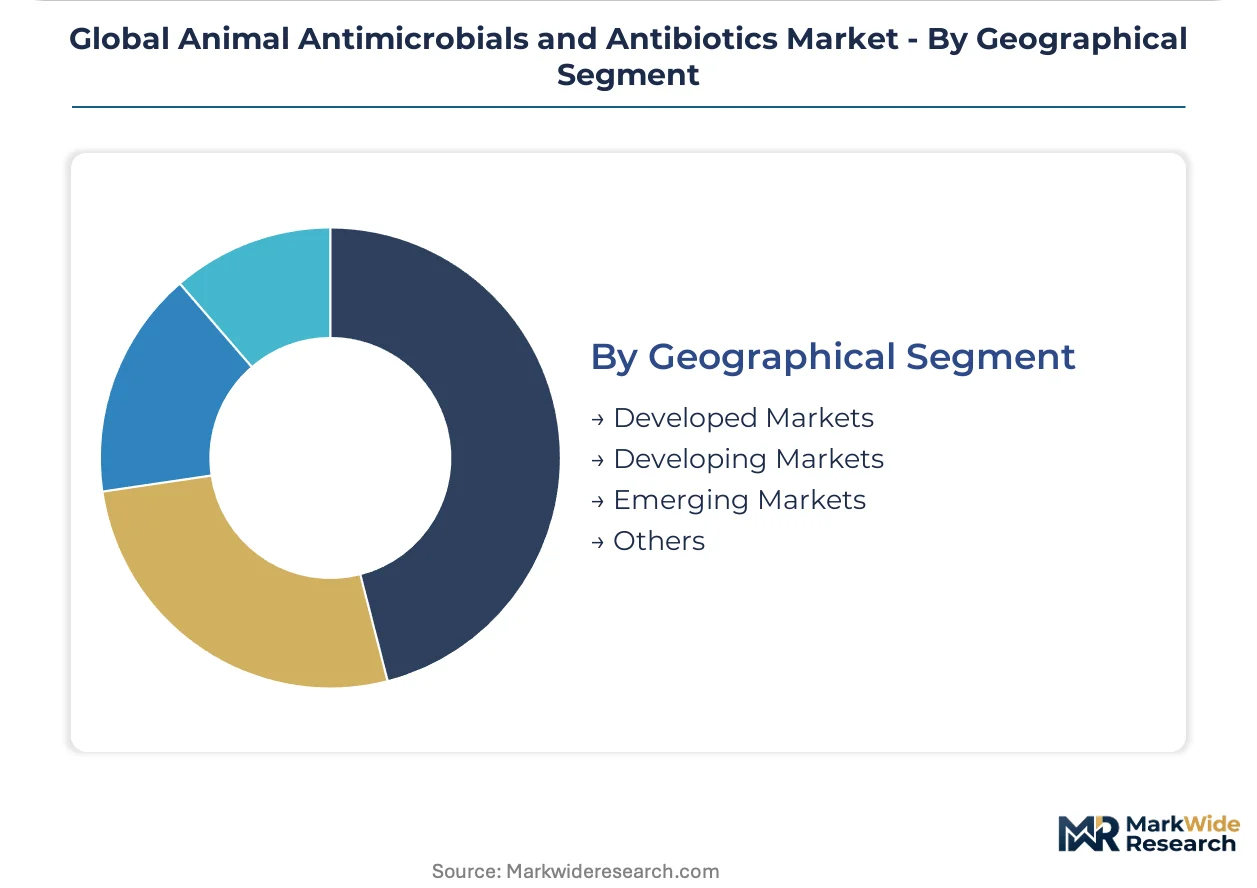
- Developed Markets:FDA Veterinary Feed Directive and EMA antimicrobial resistance guidelines mandate veterinary oversight and residue monitoring, redirecting portfolios toward precision therapeutics and diagnostic bundling.
- Developing Markets:Brazil's integrated broiler sector and Mexico's poultry integrators combine vertical coordination with evolving compliance frameworks, creating transitional demand for reformulated products.
- Emerging Markets:Vietnam's aquaculture expansion and Indonesia's poultry intensification drive volume growth where laboratory infrastructure for residue testing remains uneven.
- Others:Fragmented veterinary distribution in sub-Saharan Africa and Central Asia limits branded pharmaceutical penetration.
Geographic momentum: Emerging markets expand fastest. Developed markets dictate regulatory standards that reshape global product design.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The animal antimicrobials industry traces its modern scale to post-war pharmaceutical manufacturing expansion in the United States and Europe, where veterinary divisions of human drug companies pioneered mass production of tetracycline feed additives for intensive livestock operations.
United States
Metaphylaxis protocols in High Plains cattle feedlots and vertical integration across Midwest pork operations sustain antibiotic throughput. The FDA's Veterinary Feed Directive mandates veterinary oversight for medically important antibiotics in feed, redirecting procurement toward precision-delivery technologies. Kansas and Texas feedlot clusters now require vendor-managed inventory systems from pharmaceutical suppliers.
Brazil
Integrated broiler operations across São Paulo and Paraná production clusters generate concentrated demand for respiratory disease management through automated drinking water systems. ANVISA enforces residue monitoring alignment with EU export standards, compelling reformulation investments. The São Paulo state veterinary laboratory network expanded rapid screening capacity for macrolide traces in poultry matrices.
China
Swine restocking cycles and aquaculture intensification in Guangdong and Jiangsu provinces drive volume demand for water-stable formulations. The Ministry of Agriculture and Rural Affairs enforces GB standards withdrawal period compliance through slaughter facility testing. Zhejiang province API manufacturing clusters supply tetracycline and penicillin derivatives to domestic formulators.
Germany
Dairy mastitis therapy in Lower Saxony and Bavaria retains penicillin dominance amid strict residue protocols. EMA antimicrobial resistance guidelines mandate pharmacovigilance integration across veterinary clinic networks. The Lower Saxony state laboratory coordinates rapid cephalosporin screening for pork export certification.
Vietnam
Pangasius and shrimp intensification in the Mekong Delta creates demand for aquatic pharmacokinetics expertise currently undersupplied by terrestrial manufacturers. The national pharmaceutical regulator enforces evolving import registration for water-stable formulations. Can Tho province processing clusters now require antibiotic residue documentation for EU market access.
Global Animal Antimicrobials and Antibiotics Market Vendor Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and regulatory documentation capabilities, with injectable long-acting cephalosporins commanding price multiples over feed-grade tetracyclines. The vendor base stratifies into three tiers: diversified human-animal pharmaceutical conglomerates, specialized veterinary-only manufacturers, and regional formulators dependent on imported APIs. Consolidation pressures intensify as residue testing infrastructure investments and multi-jurisdictional registration costs exclude smaller competitors. Dominant competitive moves include vaccine-antibiotic bundling programs and backward integration into precision livestock monitoring technologies.
Within the diversified pharmaceutical tier, Zoetis Inc. and Boehringer Ingelheim occupy positions exemplifying scale-driven manufacturing and European ruminant specialization respectively. Elanco Animal Health represents the veterinary-dedicated archetype with channel control over North American clinic networks. These three entities anchor competitive dynamics through divergent geographic anchoring and species-specific portfolio weighting.
| Leading Market Players |
|---|
| Zoetis Inc. |
| Boehringer Ingelheim |
| Elanco Animal Health |
| Merck & Co. |
| Phibro Animal Health |
| Virbac |
| Vetoquinol |
| Ceva Santé Animale |
| Dechra Pharmaceuticals |
| Others |
Supply Flow & Price Mechanics
Veterinary pharmacology expertise clusters in the Netherlands and Denmark concentrate formulation science talent, creating labor-cost differentials that separate premium long-acting injectables from commodity feed-grade antibiotics across pricing tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement in animal antimicrobials. Injectable cephalosporins with extended withdrawal period coverage command premium positioning through veterinary labor savings, while feed-grade tetracyclines compete on manufacturing scale. Price differentiation rests on residue certification tier and cold chain integrity documentation. Pricing pressure stems from API import cost volatility in Brazilian reals and Chinese yuan. Large integrated poultry operators in São Paulo demonstrate lowest price sensitivity; independent swine producers in secondary Chinese provinces exhibit highest.
Supply Chain Analysis
Reverse-logistics flows for temperature-compromised biologic-antibiotic combinations remain underdeveloped, forcing destruction of degraded inventory rather than refurbishment. Active pharmaceutical ingredient manufacturing concentrates in Zhejiang and Jiangsu provinces of China, with secondary clusters in India and the United States. Formulation depends on tetracycline fermentation feedstocks, cephalosporin semi-synthetic intermediates, and specialized excipients for water-stable granules. Single-source vulnerability in Chinese API clusters exposes formulators to regulatory inspection disruptions. Distribution runs through veterinary clinic networks in developed markets and direct-to-producer channels in Brazil's integrated broiler sector.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Animal antimicrobials function as a stable compounder anchored by irreplaceable therapeutic demand in intensive livestock operations confronting antimicrobial resistance surveillance expansion.
For Market Incumbents: Extend diagnostic bundling capabilities to capture veterinary clinic network loyalty before precision livestock monitoring platforms commoditize standalone antibiotic sales. Consolidate backward integration into water-soluble granule formulation capacity in Vietnam to preempt terrestrial manufacturers adapting to aquatic pharmacokinetics. API supply concentration in Chinese provinces poses substitution risk from Indian fermentation capacity expansion.
For New Entrants and Emerging Players: Capture residue-mapping service contracts in China's GB standards enforcement environment where first-mover data advantages compound. White-space exists in pangasius-specific formulations for Vietnam's Mekong Delta processing clusters and in automated drinking system integration for Brazilian broiler houses. Go-to-market through veterinary distributor partnerships in Indonesia's poultry intensification zones bypasses direct regulatory registration burdens.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional formulators with captive API access and established multi-jurisdictional dossiers. Long-term viability over the projection horizon rests on regulatory compliance infrastructure rather than pure manufacturing scale. Watch EMA pharmacovigilance data integration mandates as the inflection signal separating documentation-capable assets from stranded inventory.
| Strategic Initiative | Industry Significance |
|---|---|
| Vaccine-Antibiotic Bundling Programs | Metaphylaxis protocols in North American cattle feedlots favor integrated suppliers over standalone vendors. |
| Precision Livestock Monitoring Integration | Real-time pathogen detection platforms compress the gap between detection and targeted antibiotic intervention. |
| Water-Stable Formulation Development | Aquaculture expansion in Vietnam's Mekong Delta creates demand currently undersupplied by terrestrial manufacturers. |
| Residue-Mapping Service Provision | China's Ministry of Agriculture and Rural Affairs enforcement of GB standards creates first-mover data advantages. |
| Multi-Jurisdictional Registration Investment | Divergent FDA, EMA, and NMPA residue limits extend launch timelines and inflate regulatory affairs requirements. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement captured perspectives from veterinary pharmaceutical executives, regulatory affairs specialists at ANVISA and EMA, procurement managers at Brazilian integrated broiler operations, and residue testing laboratory directors in Germany and Poland. Secondary validation drew from FDA Veterinary Feed Directive filings, EMA antimicrobial resistance guideline revisions, China's GB standards documentation, customs trade data for tetracycline and cephalosporin API flows, and SEC 10-K disclosures from diversified animal health conglomerates. Bottom-up demand modeling triangulated against top-down macroeconomic indicators across the analysis window.
Segment-weighting approaches applied differential growth assumptions by chemical class, species application, and administration route. The analytical framework modeled tetracyclines, macrolides, penicillins, and aminoglycosides separately with distinct bioavailability and residue compliance trajectories. Species segmentation captured poultry, swine, ruminant, and aquaculture demand pools with varying intensification rates. CAGRs were derived from regression analysis of historical volume trends against regulatory event timing. Forecast inputs incorporated veterinary clinic network expansion rates and precision livestock monitoring adoption curves.
Regulatory enforcement intensity, API supply disruption events, and antimicrobial resistance surveillance network expansion are the dominant revision risks to modeled trajectories. Forecasts reflect documented assumptions regarding residue limit stability and veterinary infrastructure investment continuity. Practitioners should monitor EMA pharmacovigilance integration mandates, Chinese GB standards testing capacity buildout, and Brazilian ANVISA inspection frequency for early signals of trajectory deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Global Veterinary Drugs Market
Veterinary
Global Veterinary Artificial Insemination Market
Veterinary
India Veterinary Healthcare Market
Veterinary
Swine Respiratory Diseases Treatment Market
Veterinary
Veterinary Biologicals Biobank Market
Veterinary
Bovine Mastitis Treatment System Market
Veterinary
Global Veterinary MRI Market
Veterinary
Australia Veterinary Healthcare Market
Veterinary
Veterinary Tables Market
Veterinary
Global Dog Vaccines Market
Veterinary
Pet Cancer Therapeutics Market
Veterinary
Isoxazoline Market
Veterinary
Asia-Pacific Veterinary Healthcare Market
Veterinary
Orthopedic Dog Bed Market
Veterinary
Veterinary Vaccine Adjuvants Market
Veterinary
Japan Veterinary Healthcare Market