
 France Veterinary Healthcare Market | 2026-2036
France Veterinary Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
France Veterinary Healthcare Market Analysis
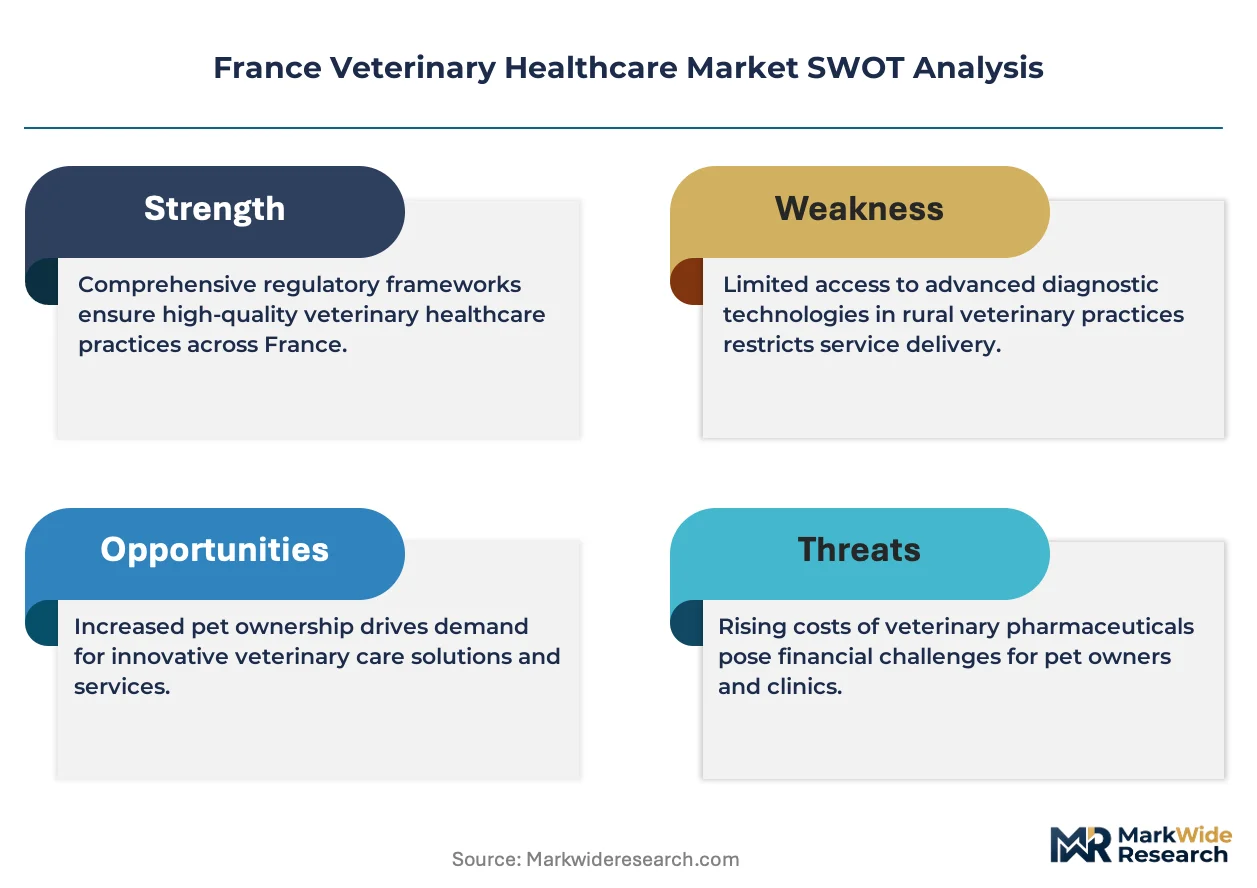
The capital-intensity divergence between biologics manufacturers and generic pharmaceutical suppliers is rotating competitive dynamics across the French veterinary landscape. Virbac SA leverages its vertically integrated production campus in Carros to sustain margin control over vaccine and pharmaceutical exports. Zoetis Inc. anchors its European R&D footprint through dedicated companion animal oncology programs near Paris. IDEXX Laboratories dominates the diagnostics layer, controlling reference laboratory networks that extend real-time pathology services to independent veterinary clinics nationwide.
France veterinary healthcare encompasses the prevention, diagnosis, and treatment of disease in companion animals, livestock, and exotic species through pharmaceuticals, biologicals, and diagnostic services, with products manufactured under GMP conditions requiring cold-chain stability between 2°C and 8°C for biologics. Its primary purpose is maintaining animal health standards that protect food safety, zoonotic disease containment, and companion animal longevity. The pharmaceuticals segment occupies the deepest margin pools as chronic condition management in aging pets drives recurring prescription volumes. Vaccines compete on national tender frameworks for livestock producers while nutraceuticals extend into preventive wellness protocols among premium companion animal owners. Injectable delivery modes lead in clinical settings due to bioavailability requirements, though oral formulations gain traction in home-administered parasite control.
ANSM oversees veterinary pharmacovigilance and marketing authorization pathways, while the EU Green Deal's Farm to Fork strategy is reducing antimicrobial usage thresholds in livestock production. France's national antibiotic resistance plan mandates prescription tracking for veterinary fluoroquinolones, reshaping product portfolios toward narrow-spectrum alternatives. Stakeholders must monitor how evolving EMA environmental risk assessments for veterinary medicinal products will reshape manufacturing compliance costs and formulation R&D priorities.
Market Dynamics
Pet humanization in Paris, Lyon, and Marseille is compressing diagnostic service timelines as urban households demand same-day pathology results for companion animals. ANSM pharmacovigilance mandates for veterinary biologics are simultaneously extending pre-market authorization durations, creating operational friction for manufacturers.
Growth Catalysts
- EU Green Deal antimicrobial thresholds:Livestock producers are pivoting toward narrow-spectrum alternatives and preventive vaccines, expanding biologicals demand.
- Companion animal oncology protocols:Veterinary clinics in Ile-de-France are integrating molecular diagnostics into routine cancer management workflows.
- Paris reference laboratory density:Real-time pathology networks are reducing diagnostic turnaround from days to hours for independent practitioners.
Market Restraints
- Cold-chain infrastructure gaps:Rural Auvergne-Rhône-Alpes clinics lack consistent 2°C to 8°C storage for temperature-sensitive biologics.
- Fluoroquinolone prescription tracking:France's national antibiotic resistance plan mandates granular documentation, increasing administrative burden on livestock veterinarians.
- Reference laboratory concentration:IDEXX's nationwide network dominance limits price competition in diagnostic services.
Strategic Opportunities
- Occitanie livestock vaccine tender frameworks:Regional agricultural cooperatives are consolidating procurement, creating volume contracts for preventive biologicals.
- Point-of-care diagnostic miniaturization:Portable hematology analyzers are enabling home-visit veterinarians to bypass centralized lab dependency.
- Nutraceutical preventive protocols:Premium companion animal owners in Bordeaux and Nantes are subscribing to monthly wellness supplement deliveries.
Industry Challenges
- Veterinary pathologist recruitment:France produces insufficient board-certified diagnosticians to staff expanding reference laboratory networks.
- EMA environmental risk assessment compliance:Reformulated product dossiers require 18-24 month resubmission cycles, delaying portfolio refreshes.
- Legacy practice management system integration:Independent clinics struggle to connect ANSM-mandated prescription tracking with existing software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Veterinary Healthcare Market |
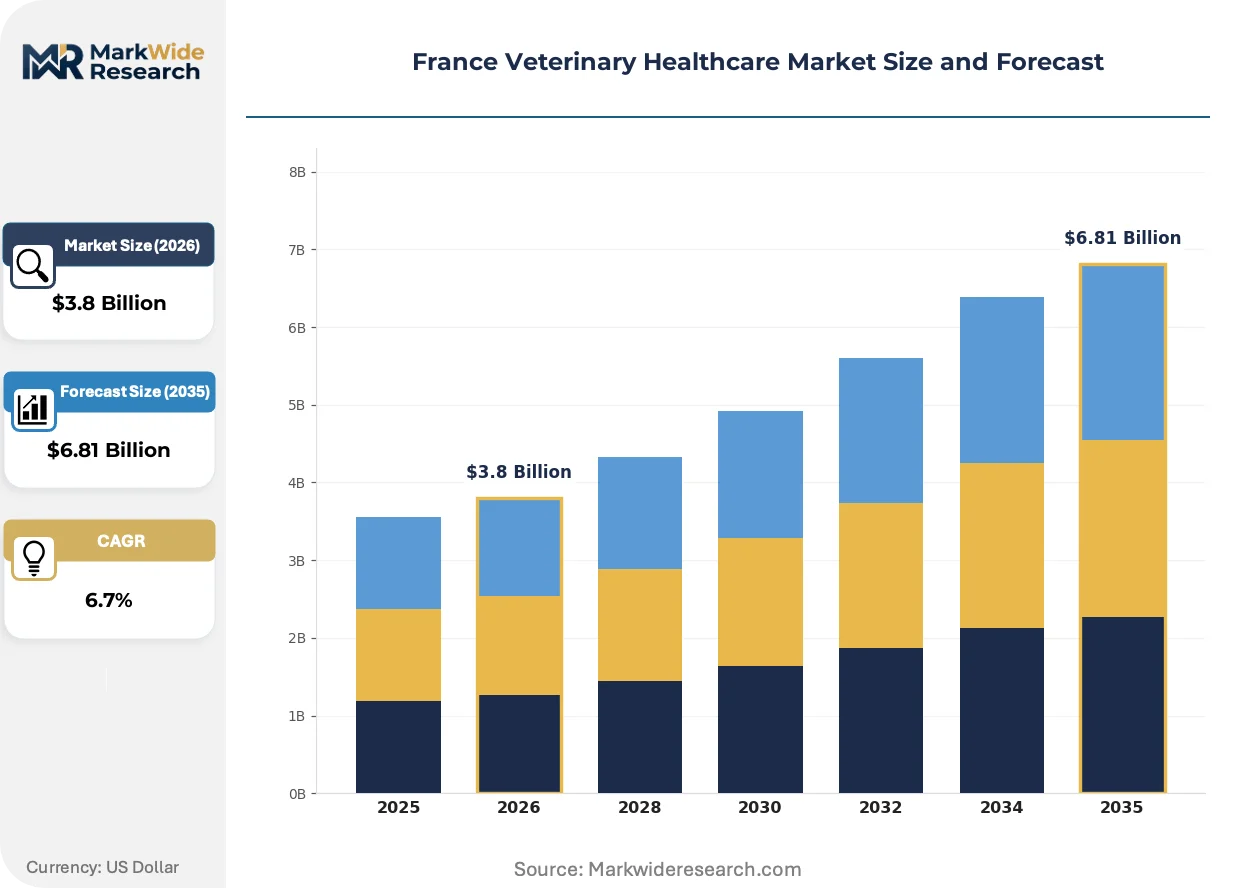
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Vaccines, Medicated Feed, Nutraceuticals End User: Veterinary Clinics, Animal Hospitals, Pet Owners, Livestock Farmers Delivery Mode: Injectable, Oral, Topical, Inhalation Animal Type: Companion Animals, Livestock, Aquatic Animals, Exotic Pets |
| Companies Covered | Virbac SA, IDEXX Laboratories, Zoetis Inc., Merck & Co., Inc., Vetoquinol SA, Boehringer Ingelheim International GmbH, Elanco Animal Health, Mars Petcare, Ceva Animal Health, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Veterinary Healthcare Market Emerging Trajectories
Diagnostic modality convergence and regulatory data requirements are compressing product development timelines while fragmenting service delivery models across French veterinary practice structures.
Point-of-care hematology and biochemistry analyzers are miniaturizing benchtop laboratory functions into handheld devices. Mobile veterinary services in Provence-Alpes-Côte d'Azur are adopting these units for immediate pre-surgical screening. The technology is miniaturizing diagnostic workflows that previously required centralized lab submission, enabling same-visit treatment decisions.
ANSM's tightened pharmacovigilance reporting for veterinary biologics is mandating real-time adverse event documentation. Manufacturers must now integrate post-market surveillance into distribution logistics. Companion animal vaccine producers are restructuring field service teams to capture clinic-level reaction data within 48-hour windows.
Subscription-based preventive care plans are displacing transactional service billing in urban companion animal practices. Younger pet owners in Lille and Strasbourg prefer fixed monthly payments covering vaccinations, parasiticides, and wellness exams. This model concentrates patient retention with single-practice relationships while compressing competitor switching.
France Veterinary Healthcare Market Segmentation
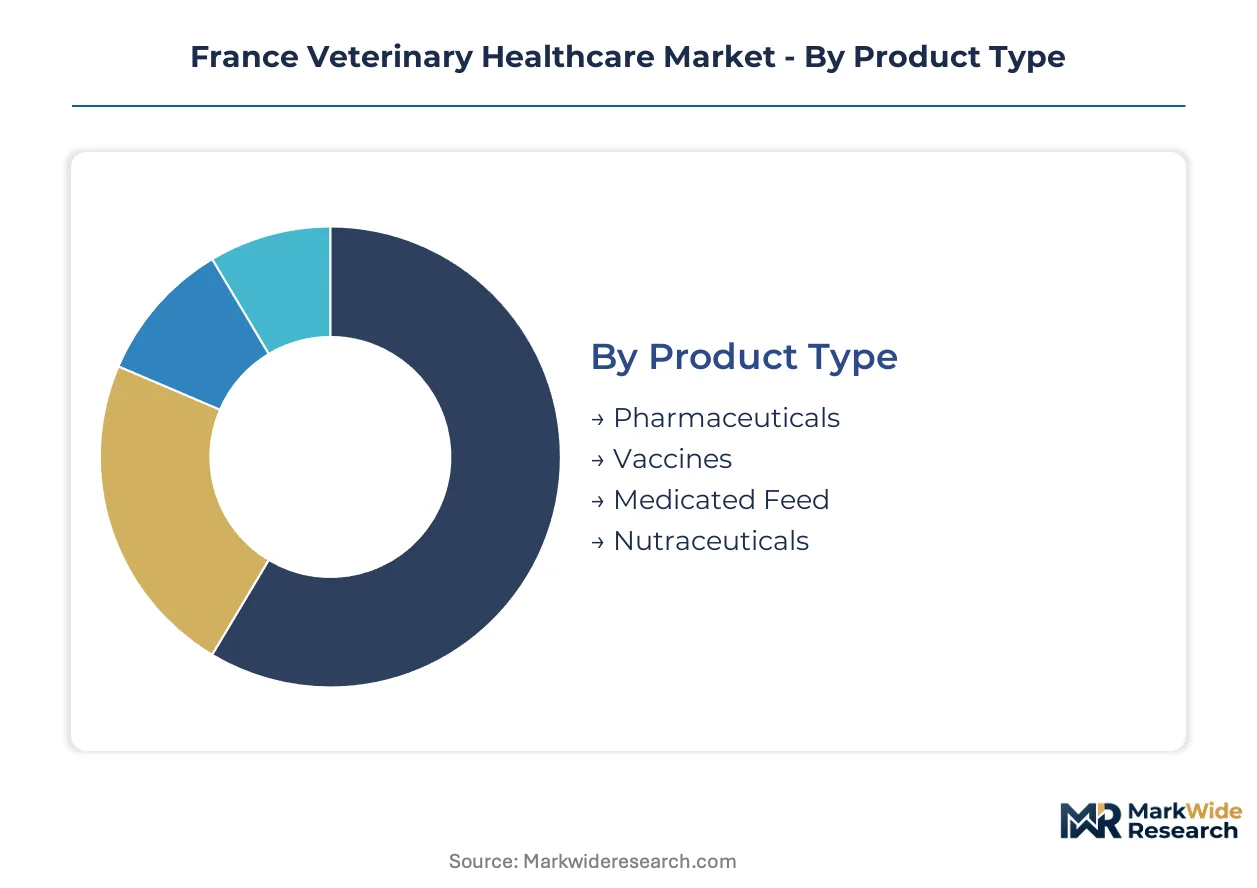
France veterinary healthcare segments flow through distinct regulatory and distribution pathways. ANSM authorization requirements vary sharply between biologics and pharmaceuticals, while cold-chain logistics constrain rural penetration for temperature-sensitive products.
Product Type:
Channel-mix dynamics split sharply between prescription-controlled veterinary clinics and direct agricultural procurement. Pharmaceuticals and vaccines route through licensed practitioners under ANSM oversight, while medicated feed and nutraceuticals reach livestock cooperatives and retail pet channels with lighter documentation burdens.
- Pharmaceuticals:Small-molecule therapeutics for chronic condition management in aging companion animals drive recurring prescription volumes. Demand concentrates in Paris and Lyon urban clinics where pet humanization sustains premium pricing for dermatology and cardiology protocols. ANSM's fluoroquinolone tracking mandates reshape portfolios toward narrow-spectrum alternatives.
- Vaccines:Temperature-sensitive biologicals requiring 2°C to 8°C stability through distribution. Livestock producers in Occitanie and Nouvelle-Aquitaine purchase through regional cooperative tender frameworks, while companion animal vaccines flow via clinic inventory systems. Cold-chain gaps in rural Auvergne-Rhône-Alpes limit penetration.
- Medicated Feed:Antimicrobial and coccidiostat formulations integrated into livestock nutrition programs. EU Green Deal thresholds are reducing inclusion rates, forcing reformulation toward ionophore alternatives and phytogenic additives.
- Nutraceuticals:Preventive wellness supplements including omega fatty acids, probiotics, and joint support compounds. Bordeaux and Nantes households subscribe to monthly delivery services, bypassing clinical channels entirely.
By volume, pharmaceuticals lead. By growth pace, nutraceuticals are expanding most quickly.
End User:
Cost-tier stratification separates premium service delivery from commodity procurement. Urban companion animal owners absorb diagnostic-intensive care models while livestock farmers prioritize unit-economics at scale.
- Veterinary Clinics:Independent practices in Ile-de-France and Provence-Alpes-Côte d'Azur anchor companion animal service delivery. These facilities integrate IDEXX reference laboratory networks and point-of-care analyzers for same-day pathology.
- Animal Hospitals:Multi-specialty centers in Paris and Lyon performing orthopedic surgery, oncology, and emergency critical care. Capital equipment intensity and specialist veterinarian staffing create high fixed-cost structures.
- Pet Owners:Direct-to-consumer channels expanding through online pharmacies and subscription wellness plans. Younger demographics in Lille and Strasbourg prefer fixed monthly payments covering preventive care bundles.
- Livestock Farmers:Cattle, swine, and poultry producers purchasing through cooperative procurement frameworks. Occitanie agricultural consolidations are creating volume contracts for preventive biologicals and feed additives.
Clinics capture the highest revenue per transaction. Pet owners represent the steepest expansion trajectory as direct channels fragment traditional practice relationships.
Delivery Mode:
Application requirements dictate formulation chemistry and administration setting. Injectable and oral routes dominate distinct therapeutic categories with minimal substitution elasticity.
- Injectable:Parenteral formulations maximizing bioavailability for vaccines, antibiotics, and anesthetic protocols. Clinical administration mandates veterinary supervision, concentrating volume in practice settings.
- Oral:Tablets, suspensions, and feed-additive formats for home-administered parasite control and chronic medication. Palatability engineering and precise dosing compliance drive formulation R&D priorities.
- Topical:Transdermal parasiticides and dermatological treatments. Spot-on formulations for flea and tick control dominate companion animal retail channels with minimal veterinary gatekeeping.
- Inhalation:Aerosolized therapies for respiratory conditions in equine and exotic species. Limited addressable market constrains manufacturer investment relative to other delivery modes.
Injectables generate the deepest margins. Oral formulations are gaining share fastest as home-administered chronic protocols expand.
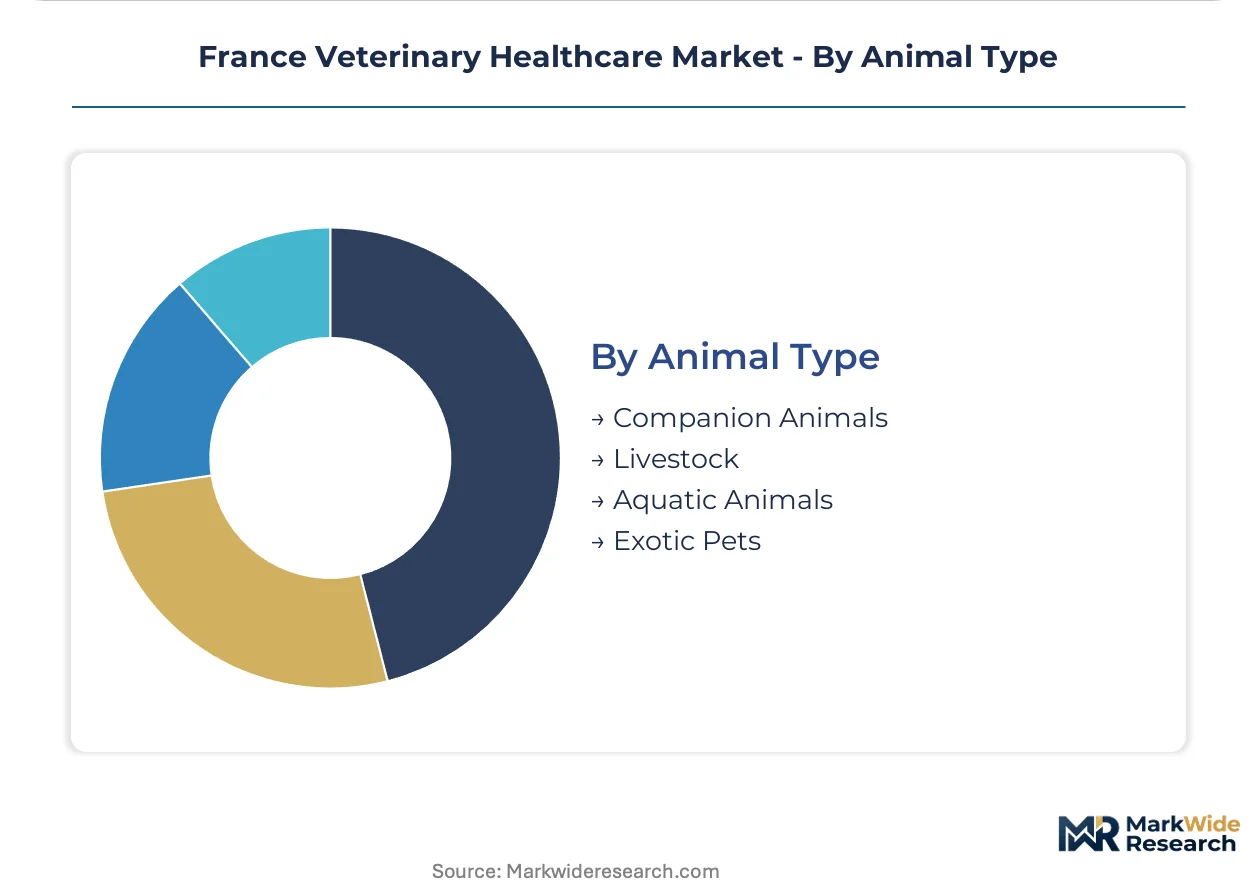
Animal Type:
Customer-type divergence splits between emotionally-driven companion animal expenditure and production-economic livestock decisions. Regulatory frameworks and disease risk profiles differ fundamentally across categories.
- Companion Animals:Dogs and cats receiving preventive, diagnostic, and therapeutic services in urban clinical settings. Pet humanization in Marseille and Nice sustains premium oncology and dental procedure adoption.
- Livestock:Cattle, swine, and poultry populations under national food safety and antibiotic stewardship regulations. France's national antibiotic resistance plan mandates prescription tracking for veterinary fluoroquinolones in production animals.
- Aquatic Animals:Farmed fish and shellfish in coastal Brittany and Mediterranean operations. Vaccine development for viral hemorrhagic septicemia and photobacteriosis addresses emerging production threats.
- Exotic Pets:Reptiles, birds, and small mammals requiring specialized diagnostic and surgical capabilities. Limited veterinarian training availability constrains service accessibility outside major urban centers.
Companion animals dominate value generation. Aquatic animals show the steepest growth trajectory as marine aquaculture expands along Atlantic and Mediterranean coastlines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Île-de-France commands premium pricing for companion animal oncology and diagnostic services while Auvergne-Rhône-Alpes livestock producers operate under tighter margin constraints. This pricing-power asymmetry reflects urban pet humanization intensity versus rural production economics.
Île-de-France
Paris and inner-ring municipalities concentrate France's highest-value veterinary transactions, with pet owners absorbing premium pricing for molecular diagnostics and specialized surgery. ANSM pharmacovigilance mandates for veterinary biologics extend pre-market authorization timelines for manufacturers serving this cluster. The Carros production campus in nearby Provence-Alpes-Côte d'Azur supplies temperature-stable vaccines to Île-de-France clinics through cold-chain logistics networks.
Auvergne-Rhône-Alpes
Lyon anchors companion animal service expansion while surrounding rural departments depend on livestock vaccine procurement through cooperative frameworks. France's national antibiotic resistance plan mandates prescription tracking for veterinary fluoroquinolones, increasing administrative burden on cattle and swine veterinarians. Cold-chain infrastructure gaps in rural clinics limit 2°C to 8°C biologics penetration outside Lyon proper.
Provence-Alpes-Côte d'Azur
Mobile veterinary services in Marseille and Nice adopt point-of-care hematology analyzers for same-visit treatment decisions. The EU Green Deal's Farm to Fork strategy is reducing antimicrobial usage thresholds for regional livestock producers. Virbac SA's vertically integrated Carros campus manufactures vaccines and pharmaceuticals for export, anchoring manufacturing employment in Alpes-Maritimes.
Occitanie
Regional agricultural cooperatives consolidate livestock vaccine procurement into volume contracts for preventive biologicals. ANSM oversees marketing authorization pathways for veterinary medicinal products distributed through these frameworks. Toulouse and Montpellier veterinary schools supply diagnosticians to expanding reference laboratory networks nationwide.
Nouvelle-Aquitaine
Bordeaux households subscribe to monthly nutraceutical delivery services, bypassing clinical channels for preventive wellness. EMA environmental risk assessments for veterinary medicinal products reshape manufacturing compliance costs for suppliers serving this direct-to-consumer segment. The Atlantic coastline supports emerging marine aquaculture vaccine demand for viral hemorrhagic septicemia protection.
France Veterinary Healthcare Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the French veterinary landscape. Diagnostic service networks and biologics manufacturers occupy distinct competitive tiers with minimal overlap in capabilities. The market structures around three archetypes: vertically integrated pharmaceutical manufacturers, reference laboratory network operators, and diversified animal health conglomerates. M&A activity concentrates on point-of-care diagnostic capabilities while strategic partnerships address cold-chain distribution gaps in rural territories.
Among France-based pharmaceutical specialists, Virbac SA and Vetoquinol SA exemplify the integrated manufacturing archetype with captive production assets. IDEXX Laboratories anchors the diagnostic services tier through reference laboratory network control. These three entities represent the dominant competitive anchors without implying specific strategic actions or market positions beyond their visible industry roles.
| Leading Market Players |
|---|
| Virbac SA |
| IDEXX Laboratories |
| Zoetis Inc. |
| Merck & Co., Inc. |
| Vetoquinol SA |
| Boehringer Ingelheim International GmbH |
| Elanco Animal Health |
| Mars Petcare |
| Ceva Animal Health, Inc. |
| Others |
Supply Flow & Price Mechanics
Forty-eight to seventy-two hour cold-chain stability requirements for ANSM-authorized biologics concentrate inventory risk with distributors serving rural Auvergne-Rhône-Alpes clinics, compressing margin pools for temperature-sensitive vaccines while amplifying pricing power for reference laboratory networks in Paris and Lyon that bypass logistics constraints through real-time pathology infrastructure.
Pricing Analysis
The customization-premium spread between configured-to-order companion animal oncology protocols and standard preventive care packages separates Île-de-France clinics from commodity livestock services. Three-tier pricing structure across premium, standard, and economy levels reflects molecular diagnostic integration, specialist veterinarian certification, and after-hours emergency availability. Pricing pressure stems from IDEXX's nationwide reference laboratory network dominance limiting competitive bidding among independent practitioners. Livestock farmers in Occitanie exhibit highest price sensitivity due to cooperative procurement consolidation, while urban pet owners in Marseille and Nice absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Inbound logistics costs through Mediterranean port corridors and refrigerated trucking networks from Virbac's Carros campus shape distribution economics for temperature-sensitive biologicals. Manufacturing concentration in France, Belgium, and Germany feeds formulation chemistry and sterile fill-finish capacity for the domestic market. Active pharmaceutical ingredient sourcing draws from Swiss and Italian specialty chemical producers, creating single-source vulnerability for narrow-spectrum antibiotic precursors. Distribution runs through veterinary wholesale cooperatives and direct clinic consignment for companion animal products, with regional agricultural federations consolidating livestock vaccine procurement into tender-based volume contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting around diagnostic data interoperability as IDEXX reference laboratory networks and point-of-care analyzer ecosystems consolidate patient records across independent Île-de-France practices, creating switching-cost moats that reshape competitive dynamics for pharmaceutical and service suppliers.
For Market Incumbents: Compound diagnostic service density through captive reference laboratory capacity additions in Provence-Alpes-Côte d'Azur and Occitanie, defending against point-of-care miniaturization threats that enable mobile veterinary services to bypass centralized lab dependency. Deepen backward integration into cold-chain logistics infrastructure to offset margin compression from ANSM pharmacovigilance compliance cost inflation. For New Entrants and Emerging Players: Rural exotic pet service accessibility gaps in secondary cities outside Paris, Lyon, and Marseille offer penetrable white-space where board-certified specialist veterinarian scarcity constrains incumbent coverage. Target home-visit veterinary segments adopting portable hematology analyzers for same-visit treatment decisions, leveraging subscription-based preventive care plan bundling as the go-to-market angle to secure recurring revenue before clinical relationship lock-in. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across point-of-care diagnostic manufacturing as semiconductor miniaturization reduces analyzer production costs, improving return thresholds for mid-scale equipment specialists. Acquisition focus should center on veterinary software platforms integrating ANSM-mandated prescription tracking with practice management systems, with regulatory compliance automation spend serving as the inflection signal for platform consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Partnership | Secures 2°C to 8°C biologics distribution integrity for rural clinic penetration in Auvergne-Rhône-Alpes. |
| Point-of-Care Diagnostic Launch | Enables mobile veterinary services in Marseille and Nice to bypass IDEXX laboratory network dependency. |
| Subscription Care Plan Rollout | Locks patient retention with fixed monthly payments covering vaccinations and wellness exams in Lille. |
| Specialist Veterinarian Recruitment Program | Addresses pathologist scarcity constraining reference laboratory network expansion nationwide. |
| ANSM Compliance Software Integration | Automates pharmacovigilance reporting for biologics adverse events within 48-hour windows. |
Methodological Framework
A spread of perspectives from veterinary practice owners, pharmaceutical regulatory affairs leads, reference laboratory operations directors, and livestock cooperative procurement managers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through ANSM marketing authorization databases, EMA environmental risk assessment filings, and EU Green Deal Farm to Fork strategy implementation reports. Bottom-up clinic service revenue modeling and top-down pharmaceutical manufacturer shipment data triangulated market sizing across the projection horizon.
Segmentation dimensions modeled span product type, end user category, delivery mode, and animal type, with regional regulatory cluster differentiation capturing ANSM versus EMA pathway variations. CAGRs were derived through trend extrapolation of companion animal oncology protocol adoption and livestock antimicrobial reduction trajectories, cross-referenced with cold-chain logistics capacity expansion plans and veterinary school graduate supply forecasts.
Forecasts assume regulatory continuity in ANSM pharmacovigilance frameworks and EU Green Deal antimicrobial thresholds; material policy shifts such as accelerated fluoroquinolone restrictions or revised environmental risk assessment timelines would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Bovine Respiratory Disease Treatment Market
Veterinary
OTC Cat Medicines Market
Veterinary
Pet Light Therapy Devices Market
Veterinary
Japan Veterinary Healthcare Market
Veterinary
Global Cattle Vaccines Market
Veterinary
Veterinary Home Diagnostics Market
Veterinary
Veterinary Endodontics Market
Veterinary
Global Veterinary Electrosurgery Market
Veterinary
Veterinary Anesthesia Drugs Market
Veterinary
CBD Pet Market
Veterinary
Veterinary Respiratory Disease Treatment Market
Veterinary
Wearable Sensors for Animal Health Management Market
Veterinary
Bovine Mastitis Market
Veterinary
India Veterinary Healthcare Market
Veterinary
Veterinary Tables Market
Veterinary
Global Animal Intestinal Health Market