
 Global Canine Atopic Dermatitis Market | 2026-2036
Global Canine Atopic Dermatitis Market Size, Share, and Industry Trends Forecast 2026-2036
Global Canine Atopic Dermatitis Market Foresight
Veterinary dermatology specialist availability is bifurcating market access between metropolitan corridors and rural zones. Zoetis Inc. leverages its biologics manufacturing infrastructure to sustain cytokine inhibitor supply chains across North American specialty hospitals. Dechra Pharmaceuticals anchors European distribution through its established veterinary pharmacy network, while Virbac competes in the Asia-Pacific corridor with localized formulation capabilities.
Canine atopic dermatitis constitutes a chronic pruritic inflammatory skin disease mediated by type I and type IV hypersensitivity reactions to environmental allergens, with diagnosis requiring intradermal testing or serum allergen-specific IgE detection alongside compatible clinical signs. Immunotherapy segments command premium positioning due to disease-modifying efficacy and recurring administration protocols, whereas topical treatments occupy volume-driven channels through over-the-counter accessibility in pet specialty stores. The fatty acid supplement category navigates margin compression from human nutraceutical crossovers, while telemedicine platforms extend distribution reach into home care settings previously underserved by brick-and-mortar veterinary pharmacies.
FDA Center for Veterinary Medicine oversight shapes biologic approval timelines and label claims for monoclonal antibody therapies, while EMA veterinary product standards govern European market entry for allergen-specific immunotherapy formulations. The EU Green Deal chemical sustainability frameworks are forcing reformulation of topical corticosteroid vehicles and excipient sourcing across manufacturing networks. Stakeholders must monitor evolving pharmacovigilance requirements for long-duration biologic therapies as regulatory divergence between FDA and EMA pathways complicates global product registration strategies.
Market Dynamics
The FDA Center for Veterinary Medicine's streamlined biologic approval pathways are compressing time-to-market for monoclonal antibody therapies while concentrating manufacturing investment among multi-species pharmaceutical platforms.
Growth Catalysts
- Companion Animal Drug Approval Modernization:FDA's expanded conditional approval mechanisms accelerate cytokine inhibitor commercialization, reducing development-to-launch intervals for novel biologics targeting IL-31 and IL-4/13 pathways.
- Pet Insurance Penetration:Reimbursement coverage for allergen-specific immunotherapy in Germany, Japan, and the United States removes cost barriers that previously limited referral dermatology access.
- Telemedicine Platform Integration:Remote consultation infrastructure extends specialty diagnosis capabilities into secondary veterinary markets previously underserved by board-certified dermatologists.
Market Restraints
- Allergen Extract Supply Concentration:European immunotherapy manufacturers depend on a limited network of allergen extract suppliers, creating vulnerability to raw material batch variability and geographic sourcing disruption.
- Biologic Cold Chain Complexity:Monoclonal antibody therapies require continuous refrigerated distribution from manufacturing facilities through specialty hospital pharmacies, elevating logistics costs and spoilage risk.
- Diagnostic Test Standardization Gaps:Discordance between intradermal testing and serum IgE detection methodologies produces inconsistent immunotherapy formulation decisions, undermining treatment efficacy confidence.
Strategic Opportunities
- Home Administration Formulation Development:Subcutaneous biologic delivery systems enabling owner-administered dosing outside clinical settings expand addressable market beyond referral hospital catchment areas.
- EU Green Deal Chemical Sustainability:Regulatory pressure on topical corticosteroid excipient sourcing creates first-mover advantage for manufacturers reformulating with bio-based vehicle alternatives.
- Japan Veterinary Specialty Hospital Expansion:Underpenetrated metropolitan markets outside Tokyo and Osaka present expansion targets for immunotherapy protocol standardization and dermatology referral networks.
Industry Challenges
- Veterinary Dermatology Specialist Scarcity:Board-certified practitioner training programs produce insufficient graduates to match referral demand growth, creating diagnostic bottleneck and treatment delay.
- Biologics Pharmacovigilance Infrastructure:Long-duration monoclonal antibody safety monitoring requires adverse event reporting systems that most general practice veterinary clinics lack capacity to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Canine Atopic Dermatitis Market |
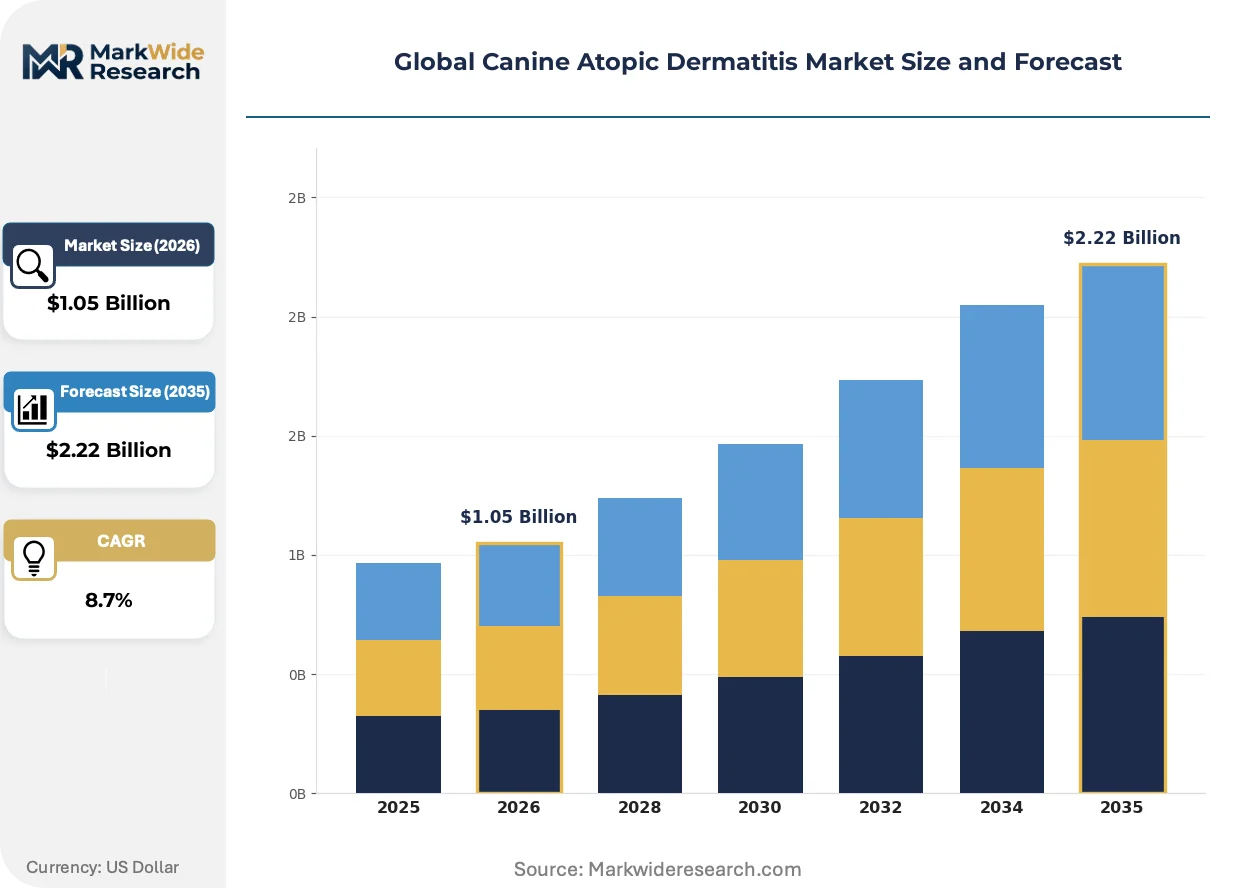
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.22 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Treatments, Immunotherapy, Antihistamines, Corticosteroids, Fatty Acid Supplements, Antibiotics Application: Skin Inflammation Management, Allergy Relief, Secondary Infection Control, Itch Reduction, Immune Modulation, Moisturization Therapy End User: Veterinary Clinics, Specialty Animal Hospitals, Pet Care Clinics, Animal Dermatologists, Grooming Centers, Home Care Distribution Channel: Veterinary Pharmacies, Online Retailers, Pet Specialty Stores, Animal Health Distributors, Direct Sales, Telemedicine Platforms |
| Companies Covered | Zoetis Inc., Elanco Animal Health, Boehringer Ingelheim, Merck Animal Health, Virbac, Ceva Santé Animale, Dechra Pharmaceuticals, Vetoquinol, PetIQ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Canine Atopic Dermatitis Market Shifts & Advancements
Monoclonal antibody engineering is fragmenting the chronic management paradigm for allergic skin disease, shifting therapeutic emphasis from symptomatic suppression toward cytokine pathway interruption.
Canine-specific monoclonal antibodies targeting IL-31 and the IL-4/13 receptor complex are decomposing the historical dominance of corticosteroid and cyclosporine protocols in specialty hospital formularies. Veterinary dermatologists in metropolitan United States and German referral centers are incorporating these biologics as first-line interventions for moderate-to-severe atopic cases. The technology is decomposing conventional pharmaceutical margin structures by commanding premium pricing while reducing concurrent medication requirements and specialist revisit frequency.
EMA veterinary product standards for allergen-specific immunotherapy are tightening formulation consistency requirements and extract potency verification protocols. Manufacturers must now demonstrate batch-to-batch equivalence through standardized allergen unit measurements rather than protein nitrogen unit approximations. European immunotherapy suppliers are responding by consolidating production into centralized manufacturing facilities with enhanced analytical chemistry capabilities and quality control documentation systems.
Pet owner purchasing behavior is fragmenting across channel types, with home care product selection increasingly occurring through telemedicine-integrated e-commerce platforms rather than clinic-dispensed pharmacy inventory. Subscription-based auto-ship models for fatty acid supplements and topical maintenance therapies are displacing episodic retail purchasing in United States and United Kingdom urban markets. This channel shift is most pronounced among millennial and Gen Z pet owners in coastal United States metropolitan statistical areas where veterinary telehealth adoption rates exceed national averages.
Global Canine Atopic Dermatitis Market Segmentation
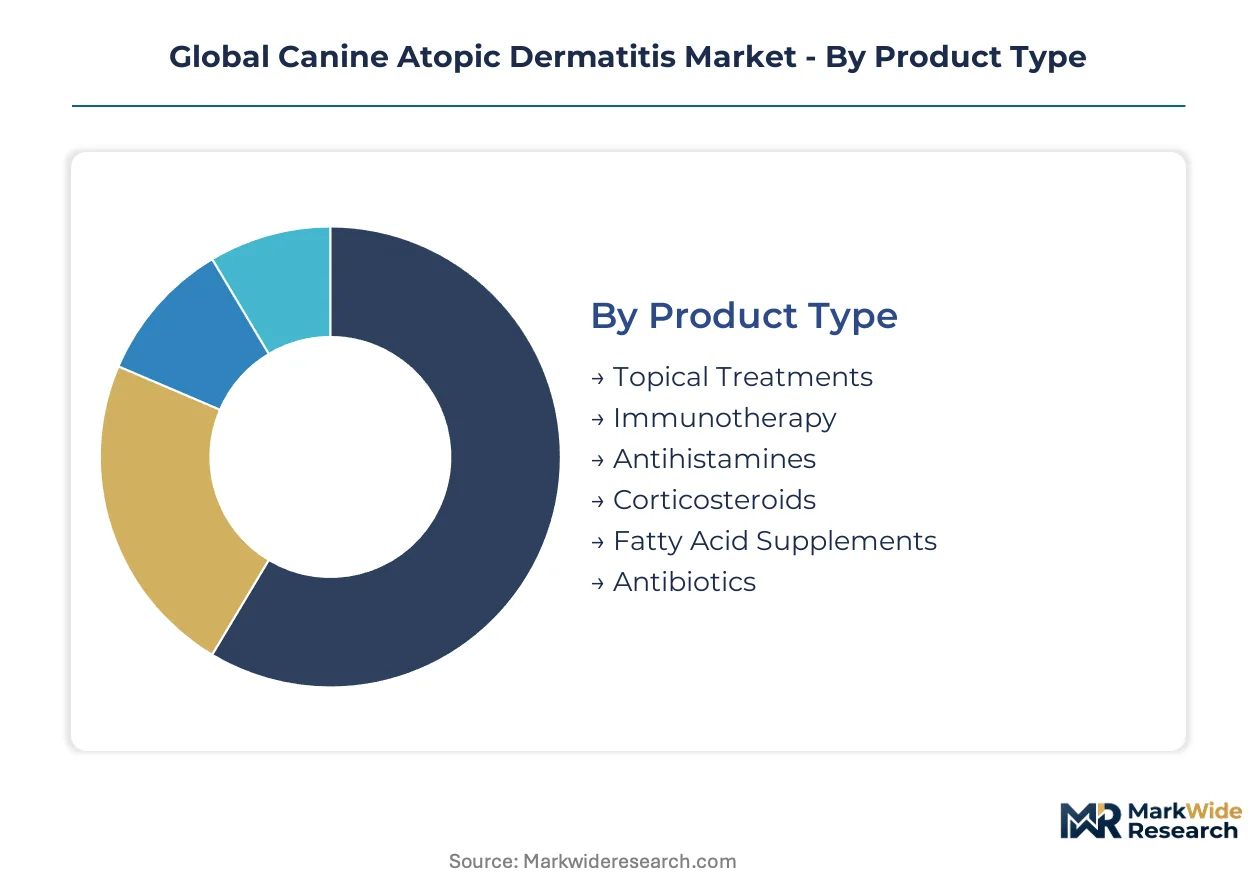
Channel fragmentation across veterinary and consumer pathways demands granular segmentation to map how biologics, immunotherapy, and maintenance therapies reach distinct purchaser profiles. Product type and distribution channel interdependencies determine margin capture and protocol adherence rates.
Product Type:
Biologics and immunotherapy concentrate through specialty hospital channels with cold-chain requirements, while topical and nutritional products disperse through retail and direct-to-consumer pathways.
- Topical Treatments:Emollient and medicated shampoos, sprays, and spot-on formulations provide symptomatic relief through barrier repair and localized anti-inflammatory action. Volume concentrates in United States and United Kingdom pet specialty retail where millennial owners favor subscription auto-ship models for maintenance therapy.
- Immunotherapy:Allergen-specific immunotherapy formulations modify disease trajectory through gradual desensitization protocols requiring precise extract potency standardization. Demand clusters in German and Japanese metropolitan specialty hospitals where pet insurance reimbursement removes cost barriers to referral dermatology.
- Antihistamines:Oral H1-receptor antagonists occupy over-the-counter channels with limited efficacy in canine species due to histamine-independent pruritus pathways.
- Corticosteroids:Systemic and topical glucocorticoid formulations face regulatory pressure under EU Green Deal chemical sustainability frameworks forcing excipient reformulation.
- Fatty Acid Supplements:Omega-3 and omega-6 nutraceuticals navigate margin compression from human supplement manufacturer crossovers into veterinary positioning.
- Antibiotics:Antimicrobial therapy addresses secondary pyoderma complications through clinic-dispensed protocols with growing stewardship constraints from FDA Center for Veterinary Medicine.
Topical treatments dominate installed base. Immunotherapy is where expansion concentrates.
Application:
Cost tier stratification separates acute intervention from chronic management, with biologic therapies commanding premium positioning against commodity symptomatic relief.
- Skin Inflammation Management:Broad-spectrum anti-inflammatory protocols address erythema, lichenification, and excoriation through combination therapy approaches. Protocol adoption concentrates in United States metropolitan referral centers with board-certified dermatologist availability.
- Allergy Relief:Environmental allergen mitigation through immunotherapy and biologic cytokine inhibition targets underlying hypersensitivity mechanisms rather than symptomatic suppression.
- Secondary Infection Control:Antimicrobial intervention for Malassezia and bacterial pyoderma complications follows diagnostic cytology confirmation in clinical settings.
- Itch Reduction:Pruritus interruption through IL-31 pathway biologics is displacing corticosteroid dependence in moderate-to-severe atopic presentations.
- Immune Modulation:Cyclosporine and emerging JAK inhibitor protocols occupy mid-tier positioning between biologics and corticosteroids.
- Moisturization Therapy:Barrier repair formulations support home care compliance between specialist revisit intervals.
Itch reduction applications capture premium pricing. Skin inflammation management represents the broadest addressable volume tier.
End User:
Specialist availability bifurcates access between metropolitan corridors with board-certified dermatologists and general practice settings managing cases without referral capability.
- Veterinary Clinics:General practice settings initiate diagnostic workup and first-line therapy before referral escalation, serving as gatekeepers to specialty care pathways.
- Specialty Animal Hospitals:United States and German academic and private referral centers concentrate immunotherapy formulation and biologic administration with dedicated dermatology departments.
- Pet Care Clinics:Wellness-focused facilities in suburban United States markets emphasize preventive dermatology and nutritional counseling.
- Animal Dermatologists:Board-certified practitioners in Tokyo, London, and New York metropolitan statistical areas command diagnostic bottleneck positions with wait-list constraints.
- Grooming Centers:Bathing and coat maintenance services extend topical therapy compliance through medicated shampoo application.
- Home Care:Owner-administered subcutaneous biologic delivery systems are expanding this segment beyond traditional clinic-dependent models.
Specialty animal hospitals dominate biologic revenue. Home care is where patient volume expansion concentrates.
Distribution Channel:
Telemedicine integration is restructuring channel economics by collapsing diagnosis and fulfillment into single-platform experiences for geographically dispersed pet owners.
- Veterinary Pharmacies:Clinic-dispensed inventory captures compliance through immediate fulfillment but faces margin pressure from online price transparency.
- Online Retailers:Chewy and Amazon pet health verticals aggregate fatty acid supplement and topical maintenance volume through subscription mechanics.
- Pet Specialty Stores:Petco and PetSmart in-store veterinary clinics bridge retail convenience with professional consultation for mild atopic presentations.
- Animal Health Distributors:Dechra and Virbac logistics networks maintain cold-chain integrity for immunotherapy extracts across European and Asia-Pacific corridors.
- Direct Sales:Manufacturer field forces target specialty hospital formularies with biologic therapy clinical education and inventory management support.
- Telemedicine Platforms:Fuzzy and Bond Vet remote consultation infrastructure extends dermatology access into secondary United States markets with limited specialist density.
Veterinary pharmacies dominate immunotherapy distribution. Telemedicine platforms are gaining share fastest in coastal United States metropolitan statistical areas.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes biologic therapies at per-capita rates exceeding Germany and Japan combined, while European markets favor allergen-specific immunotherapy protocols with longer treatment durations and lower acute intervention frequency.
United States
FDA conditional approval pathways compress monoclonal antibody launch timelines, with IL-31 and IL-4/13 inhibitors reaching specialty hospital formularies within 18-month windows. Pet insurance reimbursement for dermatology referrals exceeds 40% coverage in coastal metropolitan statistical areas. Boston and New York corridor academic veterinary centers train the majority of board-certified dermatologists entering private referral practice.
Germany
Universal pet health insurance mandates eliminate cost barriers to allergen-specific immunotherapy, producing the highest European protocol completion rates. EMA veterinary product standards enforce batch-to-batch extract potency verification through standardized allergen unit measurements. Munich and Hanover metropolitan clusters concentrate European immunotherapy manufacturing with centralized analytical chemistry capabilities.
Japan
PMDA streamlined veterinary biologic review parallels FDA pathways, accelerating cytokine inhibitor registration for metropolitan specialty hospitals. Pet insurance penetration in Tokyo and Osaka exceeds 30%, though secondary cities remain underserved by board-certified dermatologists. Nagoya and Fukuoka referral centers are expanding immunotherapy protocol standardization into previously underpenetrated markets.
United Kingdom
Telemedicine platform adoption in London and Southeast England extends dermatology access beyond brick-and-mortar referral hospital catchment areas. Veterinary Medicines Directorate pharmacovigilance requirements shape biologic adverse event reporting infrastructure. Manchester and Birmingham metropolitan statistical areas concentrate general practice gatekeepers managing pre-referral diagnostic workup.
France
ANSM oversight of veterinary biologics aligns with EMA centralized procedures, though national pharmacy dispensing regulations limit direct-to-consumer channels. Paris and Lyon specialty hospitals anchor immunotherapy formulation networks with extract sourcing from centralized European suppliers. Regional veterinary schools in Toulouse and Nantes produce insufficient dermatology specialists to match referral demand growth.
Global Canine Atopic Dermatitis Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multi-species pharmaceutical platforms commanding biologic manufacturing scale while regional formulators retain immunotherapy extract expertise. The market structure separates cold-chain biologic distributors from retail-accessible topical and nutritional product suppliers. Three archetypes dominate: vertically integrated animal health conglomerates with human pharmaceutical heritage, European veterinary pharmacy specialists with extract formulation depth, and telemedicine-integrated direct-to-consumer platforms. Competitive moves concentrate on M&A for biologic pipeline access and strategic partnerships for telemedicine distribution reach.
Among integrated animal health conglomerates, Zoetis Inc. and Elanco Animal Health exemplify the vertically integrated archetype with multi-species manufacturing infrastructure spanning cytokine inhibitor production. Virbac occupies a position within the European veterinary pharmacy specialist tier, with formulation capabilities anchored in regional extract sourcing networks. These three companies represent distinct competitive vectors: biologic scale, immunotherapy depth, and geographic specialization.
| Leading Market Players |
|---|
| Zoetis Inc. |
| Elanco Animal Health |
| Boehringer Ingelheim |
| Merck Animal Health |
| Virbac |
| Ceva Santé Animale |
| Dechra Pharmaceuticals |
| Vetoquinol |
| PetIQ |
| Others |
Supply & Pricing Matrix
Multi-species pharmaceutical manufacturing scale in North America and Europe anchors price floors for monoclonal antibody therapies while concentrating cold-chain logistics investment among integrated animal health conglomerates. Capacity utilization at biologics facilities in the United States and Germany directly shapes immunotherapy extract pricing and distribution economics across specialty hospital networks.
Pricing Analysis
Long-term offtake agreements between allergen extract suppliers and European immunotherapy manufacturers dominate contract structures, insulating formulation costs from spot-market volatility in raw material sourcing. Three-tier pricing structure across premium biologics, standard immunotherapy protocols, and economy topical maintenance separates IL-31 inhibitor therapies from allergen-specific desensitization courses and over-the-counter fatty acid supplements. Pricing pressure stems from pet insurance reimbursement ceilings in Germany and Japan that cap specialist referral fees. General practice veterinary clinics exhibit highest price sensitivity due to uninsured client bases, while metropolitan specialty hospitals command lowest sensitivity through insured referral pipelines.
Supply Chain Analysis
Allergen extract batch consistency from centralized European manufacturing facilities in Germany and the Netherlands underwrites immunotherapy formulation reliability across EMA-regulated markets. Monoclonal antibody production draws from mammalian cell culture capacity concentrated in the United States, Ireland, and Singapore, with active pharmaceutical ingredient sourcing tethered to multi-species biologics platforms. Single-source vulnerability in cold-chain distribution from manufacturing sites to specialty hospital pharmacies elevates spoilage risk for temperature-sensitive cytokine inhibitors. Distribution runs through animal health distributor networks maintaining refrigerated logistics integrity, with Dechra and Virbac anchoring European and Asia-Pacific corridors respectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA conditional approval pathway compression for veterinary biologics signals high-growth disruption, with monoclonal antibody launch timelines collapsing below historical pharmaceutical development baselines.
For Market Incumbents: Fortify biologics manufacturing scale through captive supply of mammalian cell culture capacity in North America and Europe, insulating against contract manufacturing organization bottlenecks. Deepen backward integration into allergen extract sourcing networks to neutralize European supplier concentration risk. Prioritize cold-chain logistics control through direct distribution partnerships with specialty hospital networks, defending margin position against telemedicine platform disintermediation. For New Entrants and Emerging Players: Differentiate on home-administration formulation development for subcutaneous biologic delivery, capturing owner-managed therapy segments beyond referral hospital catchment areas. Target underpenetrated Japanese metropolitan markets outside Tokyo and Osaka where board-certified dermatologist scarcity creates diagnostic bottlenecks. Pursue telemedicine-integrated direct-to-consumer channels for fatty acid supplement and topical maintenance categories, leveraging subscription auto-ship mechanics pioneered in United States coastal markets. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors European veterinary pharmacy specialists with immunotherapy extract depth and analytical chemistry capabilities over commodity topical manufacturers facing nutraceutical margin compression. Long-term viability hinges on biologics pipeline access and regulatory approval velocity rather than distribution scale alone. Monitor FDA Center for Veterinary Medicine conditional approval grant rates as inflection indicator for cytokine inhibitor competitive intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Biologics Manufacturing Scale-Up | Cold-chain capacity expansion in North America secures IL-31 inhibitor supply continuity for specialty hospitals. |
| Allergen Extract Sourcing Consolidation | Backward integration into European extract networks neutralizes batch variability risk for immunotherapy formulations. |
| Telemedicine Platform Partnership | Remote consultation infrastructure extends dermatology access into secondary United States markets with limited specialist density. |
| Home Administration Formulation Development | Owner-managed subcutaneous delivery expands addressable market beyond brick-and-mortar referral hospital boundaries. |
| EU Green Deal Compliance Transition | Bio-based excipient reformulation for topical corticosteroids creates first-mover positioning in sustainability-driven procurement. |
Research Methodology
A spread of perspectives from veterinary dermatology specialists, animal health procurement managers, biologics manufacturing executives, and pet insurance reimbursement officers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through FDA Center for Veterinary Medicine filings, EMA veterinary product registration databases, and pet insurance claims data from Germany and Japan. Bottom-up product-level volume estimates triangulated against top-down market sizing from animal health distributor revenue disclosures and specialty hospital formulary adoption metrics.
Segmentation dimensions modeled span product type, application, end user, and distribution channel across the analysis window, with geographic regulatory clusters treated as distinct forecast inputs. CAGRs derived from spline interpolation between base-year observations and terminal-year assumptions, calibrated to biologics launch velocity, immunotherapy protocol completion rates, and telemedicine platform penetration curves. Forecast inputs incorporated pet insurance reimbursement expansion trajectories, board-certified dermatologist training pipeline outputs, and cold-chain logistics cost indices.
The analysis sits within stated boundaries; outcomes outside sustained FDA conditional approval pathway efficiency and stable allergen extract supply from European manufacturing hubs would require recalibration. Forecasts reflect documented assumptions regarding biologics adoption curves and specialty hospital referral volume elasticity. Practitioners should keep alternative scenarios live as regulatory divergence between FDA and EMA pathways and veterinary dermatology specialist scarcity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Global Veterinary Drugs Market
Veterinary
Global Companion Animal Specialty Drugs Market
Veterinary
Veterinary Excipients Market
Veterinary
CBD Pet Market
Veterinary
Europe Veterinary Healthcare Market
Veterinary
Global Veterinary Electrosurgery Market
Veterinary
Vet Software Market
Veterinary
Canine Flu Therapeutics Market
Veterinary
Global Animal Intestinal Health Market
Veterinary
Veterinary Software Market
Veterinary
Germany Veterinary Healthcare Market
Veterinary
Europe Veterinary Vaccine Market
Veterinary
Isoxazoline Market
Veterinary
Companion Animal Arthritis Market
Veterinary
Veterinary Equipment and Supplies Market
Veterinary
Europe Veterinarians Market