
 Veterinary Home Diagnostics Market | 2026-2036
Veterinary Home Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Home Diagnostics Market Analytics
North American contract manufacturers of lateral flow cassettes is rebalancing capacity toward companion animal channels as human diagnostics demand stabilizes. IDEXX Laboratories leverages captive distribution through veterinary software networks to sustain recurring consumable revenue. Zoetis anchors its position through backward integration into bioreagent production, while Heska Corporation competes on instrument placement density in independent clinic networks.
Veterinary home diagnostics comprise portable analytical systems and consumable reagents designed for specimen collection, processing, and result interpretation outside clinical settings, typically operating with sample volumes under 200 microliters and turnaround times below 15 minutes. These tools enable pet owners and field veterinarians to detect infectious agents, monitor chronic metabolic conditions, and adjust therapeutic regimens without laboratory infrastructure. Test kits and point-of-care testing platforms lead current revenue contribution due to low capital requirements and broad indication coverage, while monitoring devices for chronic conditions represent the fastest-expanding margin pool as subscription-style consumable models take hold. Software solutions that integrate telemedicine triage with automated result reporting are attracting venture investment, though biochemical analyzers remain a mature segment dominated by refurbished instrument cycles.
FDA Center for Veterinary Medicine oversees device clearance for at-home use, while USDA APHIS regulates diagnostics for reportable diseases, creating dual compliance pathways that shape product development timelines and label claims. ISO 13485 quality management standards and CLIA-waived designations further constrain market access for new entrants lacking regulatory infrastructure. Stakeholders must monitor evolving telemedicine prescribing rules and state-level veterinary practice acts that determine whether home-generated data can legally trigger treatment decisions without clinician examination.
Market Dynamics
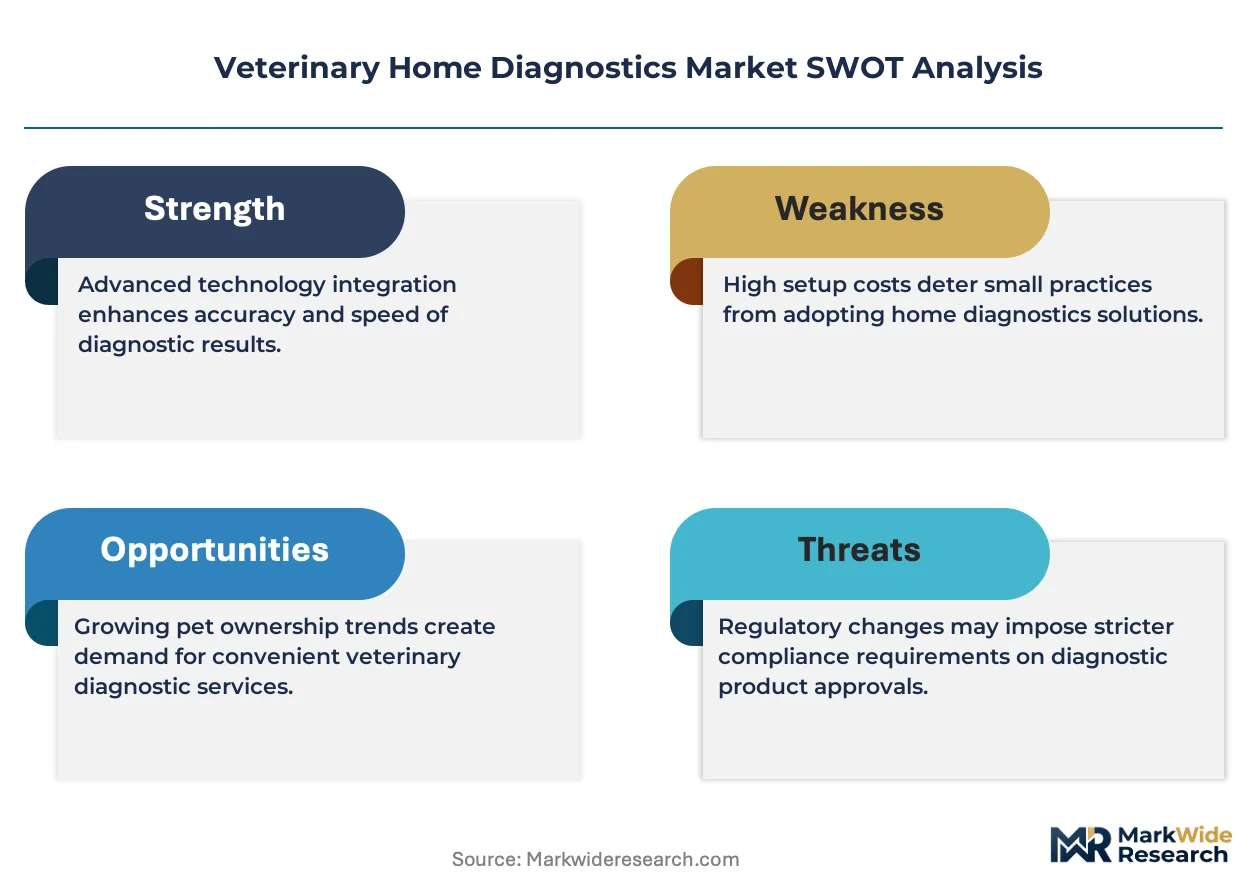
Companion animal owners are displacing clinic visits with at-home specimen collection, forcing manufacturers to redesign consumables for untrained users while telemedicine platforms scramble to integrate result data into prescribing workflows.
Growth Catalysts
- CLIA-waived immunoassay designations:US FDA streamlined pathways for waived complexity tests accelerate shelf placement in retail pharmacy channels previously closed to veterinary devices.
- Microfluidic cartridge miniaturization:Sample volume requirements below 50 microliters enable capillary blood draws from cats and small-breed dogs without veterinary phlebotomy training.
- Subscription consumable models:Chronic disease monitoring in diabetic pets generates recurring revenue streams that attract venture financing for connected glucose meter platforms.
Market Restraints
- Bioreagent supply concentration:Polyclonal antibody production for canine and feline targets clusters in Chinese contract manufacturers, exposing kit assemblers to customs delays and cold-chain interruptions.
- Dual regulatory friction:USDA APHIS reportable-disease overlap with FDA device jurisdiction forces redundant validation studies for vector-borne pathogen tests, extending development timelines.
- Laboratory service substitution:Reference laboratories in university veterinary schools offer competitive turnaround times and specialist interpretation that undercut premium pricing for home screening panels.
Strategic Opportunities
- Equine and livestock extension:Production animal segments remain underpenetrated by home diagnostics, presenting first-mover advantages for portable progesterone and infectious disease platforms in Australia and Brazil.
- Telemedicine prescribing rule alignment:State-level veterinary practice act reforms in California, Texas, and Florida increasingly permit treatment decisions based on owner-generated laboratory data without mandatory physical examination.
- AI-enabled image interpretation:Smartphone-based urinalysis strip readers combining computer vision with cloud-based classification algorithms reduce hardware costs while expanding test menu breadth.
Industry Challenges
- Quality control talent scarcity:ISO 13485 implementation for lateral flow manufacturing requires personnel with human diagnostics experience who command salary premiums in tight labor markets.
- Legacy practice management integration:Independent veterinary clinics operate fragmented software stacks that resist API connectivity with home testing data portals, forcing manual result entry and delayed care coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Home Diagnostics Market |
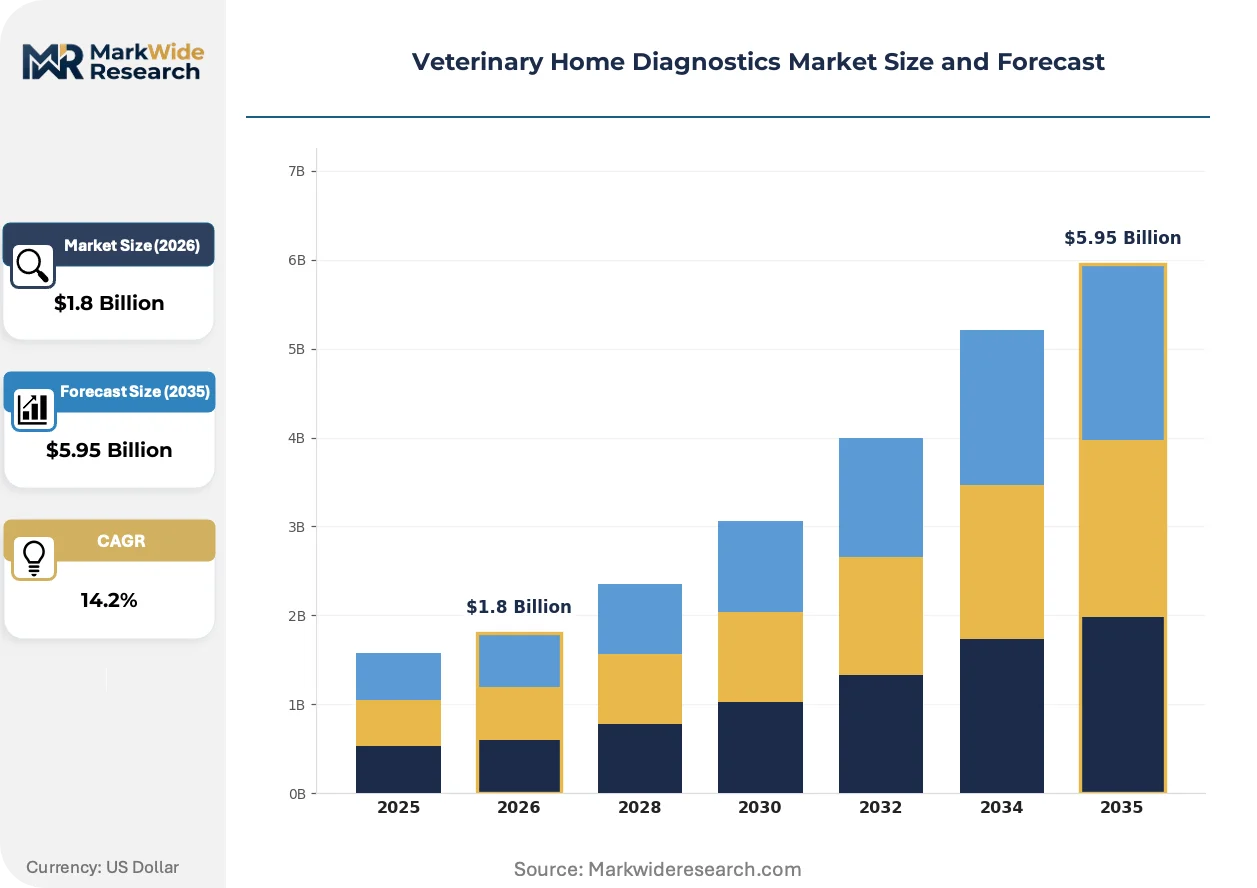
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Test Kits, Monitoring Devices, Software Solutions, Assays Application: Infectious Diseases, Chronic Conditions, Nutritional Monitoring, Health Screening End User: Pet Owners, Veterinary Clinics, Animal Shelters, Research Institutions Technology: Biochemical Analyzers, Immunoassays, Microarrays, Point-of-Care Testing |
| Companies Covered | IDEXX Laboratories, Inc., Zoetis, Inc., Heska Corporation, BioNote Inc., Ring Biotechnology Co., Ltd., Wondfo USA Co., Ltd., Affordable Pet Labs, Forte Healthcare Ltd., Vitrosens Biotechnology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Home Diagnostics Market Evolving Landscape
Device architectures are fragmenting into interoperable components that separate specimen handling from analytical detection, enabling firmware updates and test menu expansion without hardware replacement cycles.
Lateral flow cassette manufacturing is modularizing around universal reader platforms that accept swappable reagent inserts for distinct analytes. Mid-sized distributors in Germany and the United Kingdom are consolidating procurement around these open-architecture systems to reduce instrument inventory carrying costs. The approach compresses capital deployment for clinic networks while accelerating manufacturer conversion to consumable-centric revenue models.
EU MDR Article 10 technical documentation requirements for in-vitro diagnostic devices are extending to veterinary applications previously exempt from clinical performance studies. Kit manufacturers serving European Economic Area markets must now compile post-market surveillance data comparable to human IVD standards. Smaller developers lacking regulatory affairs infrastructure are withdrawing SKUs rather than absorbing compliance costs, concentrating shelf space among established players.
Pet insurance reimbursement policies in Japan and South Korea are expanding coverage for preventive screening panels, altering owner willingness-to-pay calculations at retail. Insurers partner with telemedicine platforms to pre-authorize home test kit purchases, embedding diagnostics into wellness program workflows. Channel intermediaries including online pet pharmacies are capturing margin previously retained by clinic dispensing, forcing manufacturers to manage multi-price-list complexity across direct-to-consumer and professional segments.
Veterinary Home Diagnostics Market Segmentation
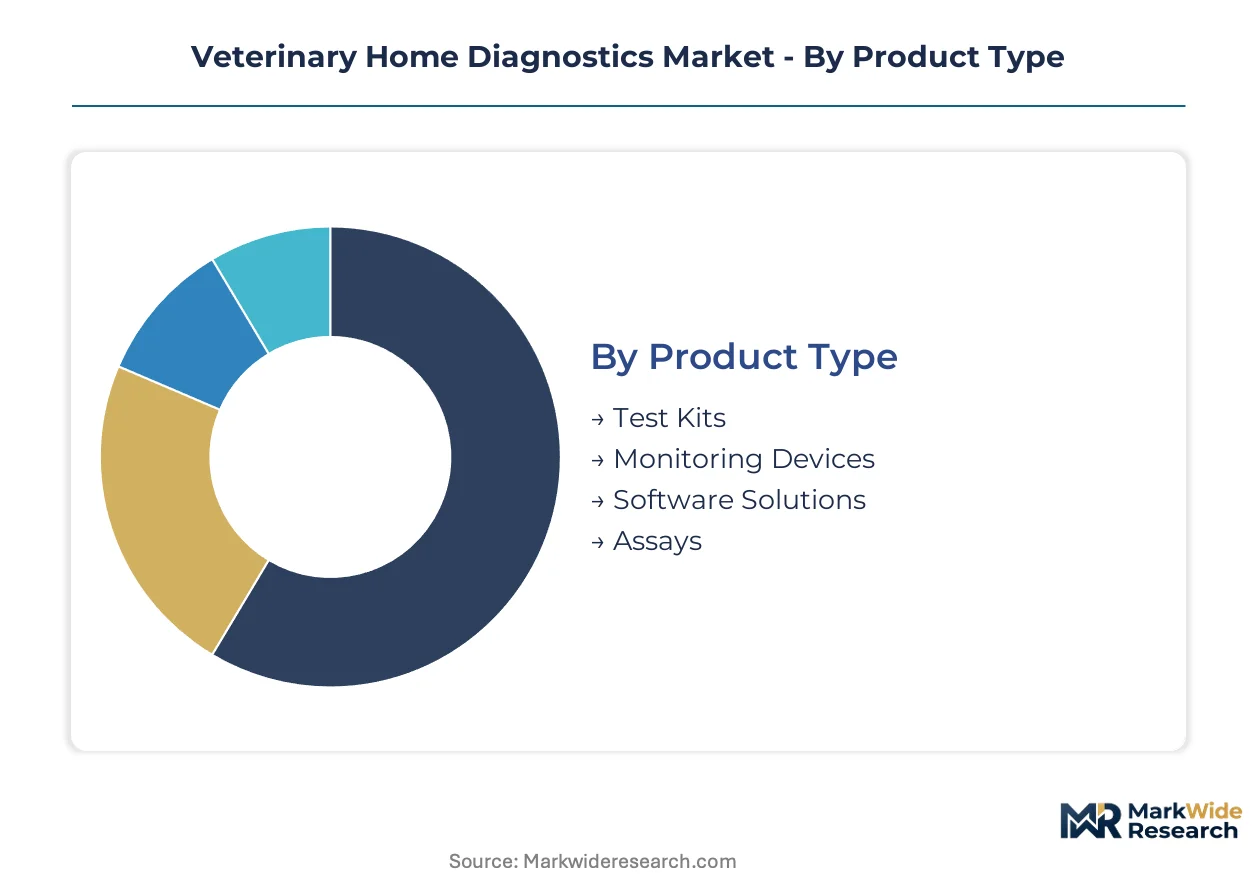
Segmentation in veterinary home diagnostics reveals how supply chain configurations align with distinct user capabilities and specimen complexity. Manufacturers configure production lines differently for untrained pet owners versus clinical professionals, while technology choices determine regulatory pathway costs and speed-to-market.
Product Type:
Supply concentration clusters around consumable formats that minimize capital barriers for new entrants while locking in recurring revenue through reagent replenishment.
- Test Kits:Lateral flow cassettes and immunoassay strips dominate current shelf placement, with manufacturing concentrated among North American contract producers rebalancing capacity from human diagnostics. Pet owners in the United States drive volume through retail pharmacy channels enabled by CLIA-waived designations.
- Monitoring Devices:Connected glucose meters and chronic disease platforms attract venture financing through subscription consumable models, with firmware-updateable architectures separating specimen handling from analytical detection to extend hardware lifecycles.
- Software Solutions:Telemedicine-integrated result reporting platforms scramble to embed into prescribing workflows.
- Assays:Bioreagent production for canine and feline targets concentrates in Chinese contract manufacturers.
Test kits absorb the bulk of installed capacity; monitoring devices are expanding most quickly.
Application:
Application segmentation tracks how specimen source and disease urgency reshape distribution economics and margin structure.
- Infectious Diseases:Vector-borne pathogen panels face dual regulatory friction from USDA APHIS reportable-disease overlap with FDA device jurisdiction, forcing redundant validation studies that extend development timelines and favor established players with regulatory infrastructure.
- Chronic Conditions:Diabetic monitoring in companion animals generates recurring revenue streams through capillary blood draw devices requiring under 50 microliter sample volumes, with telemedicine platforms in California, Texas, and Florida increasingly permitting treatment decisions without mandatory physical examination.
- Nutritional Monitoring:Metabolic panel demand concentrates among specialty breed owners.
- Health Screening:Preventive panels gain insurance reimbursement traction in Japan and South Korea.
Chronic conditions capture the steepest expansion trajectory; infectious diseases retain the largest addressable patient base.
End User:
End user segmentation exposes capability gaps that force industrial design tradeoffs between simplicity and analytical breadth.
- Pet Owners:Untrained users demand sub-15-minute turnaround times and sub-200-microliter sample volumes, with microfluidic cartridge miniaturization enabling capillary draws from cats and small-breed dogs without veterinary phlebotomy training.
- Veterinary Clinics:Independent practice networks resist API connectivity with home testing data portals, fragmenting care coordination and preserving instrument placement density as a competitive moat.
- Animal Shelters:High-throughput screening requirements favor batch-processed immunoassay platforms.
- Research Institutions:Custom assay development contracts sustain niche bioreagent producers.
Veterinary clinics anchor professional segment revenue; pet owners are climbing the fastest as telemedicine prescribing rules align with owner-generated data.
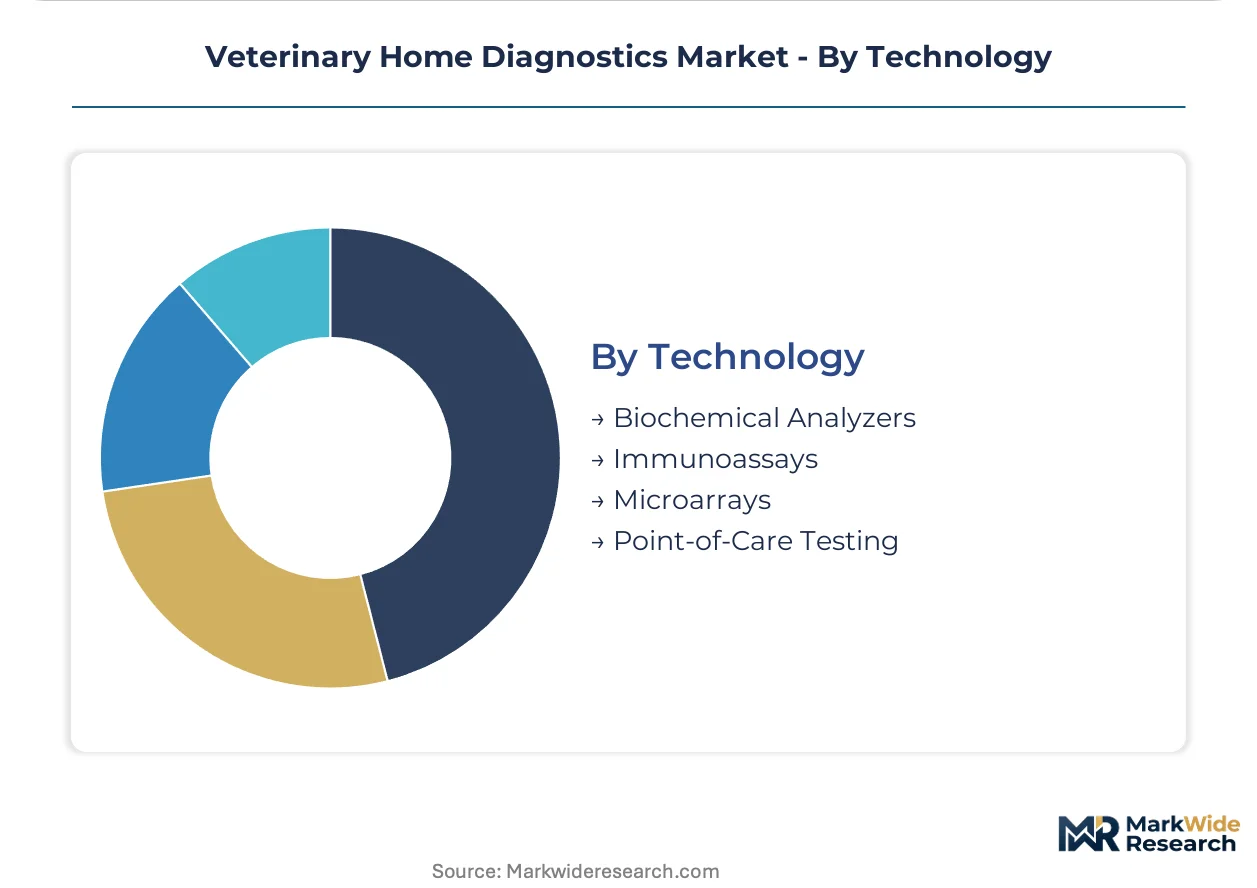
Technology:
Technology segmentation maps capital intensity against menu expandability and regulatory pathway efficiency.
- Point-of-Care Testing:Immunoassay platforms with waived complexity designations accelerate shelf placement in retail channels previously closed to veterinary devices, with universal reader architectures accepting swappable reagent inserts to compress capital deployment for clinic networks.
- Biochemical Analyzers:Refurbished instrument cycles dominate a mature segment where mid-sized distributors in Germany and the United Kingdom consolidate procurement around open-architecture systems.
- Immunoassays:Polyclonal antibody supply concentration exposes kit assemblers to customs delays.
- Microarrays:Higher analytical multiplexing remains cost-prohibitive for home deployment.
Point-of-care testing commands the dominant share of new capital deployment; biochemical analyzers are gaining share fastest through refurbished channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese bioreagent production clusters supply polyclonal antibodies for canine and feline immunoassay targets, anchoring raw material availability for kit assemblers worldwide while exposing supply chains to customs delays and cold-chain vulnerabilities.
United States
Companion animal owners drive CLIA-waived test kit volume through retail pharmacy channels, with FDA Center for Veterinary Medicine streamlining waived complexity designations previously closed to veterinary devices. California, Texas, and Florida veterinary practice act reforms increasingly permit treatment decisions based on owner-generated laboratory data without mandatory physical examination.
Germany
Mid-sized distributors consolidate procurement around open-architecture biochemical analyzer systems to reduce instrument inventory carrying costs, with EU MDR Article 10 technical documentation requirements extending to veterinary applications previously exempt from clinical performance studies. Bavarian contract manufacturers rebalanced lateral flow cassette capacity from human diagnostics toward companion animal channels as human demand stabilized.
China
Polyclonal antibody production for veterinary diagnostic targets concentrates in contract manufacturing clusters, with SAMR quality management oversight shaping export documentation requirements. Zhengzhou and Suzhou bioreagent facilities face cold-chain interruption risks that propagate through kit assembler supply schedules.
Japan
Pet insurance reimbursement policies expand coverage for preventive screening panels, altering owner willingness-to-pay calculations at retail through METI-coordinated telemedicine platform partnerships. Tokyo and Osaka insurers pre-authorize home test kit purchases, embedding diagnostics into wellness program workflows.
Brazil
Production animal segments remain underpenetrated by home diagnostics, presenting first-mover advantages for portable progesterone and infectious disease platforms in São Paulo and Minas Gerais cattle operations. ANVISA regulatory pathways for animal health devices require parallel validation studies that extend product registration timelines.
Veterinary Home Diagnostics Market Competitive Landscape
Global majors compete with regional champions across regulatory infrastructure and distribution network density, creating a tiered structure where captive software integration and backward bioreagent control separate sustainable positions from commodity kit assembly. The vendor base spans three strategic archetypes: integrated platform owners with captive distribution, specialized consumable manufacturers with contract assembly relationships, and telemedicine-anchored service providers bundling diagnostics into subscription workflows. M&A activity concentrates on bioreagent production assets and veterinary software networks, while capacity expansion targets microfluidic cartridge miniaturization for sub-50-microliter sample requirements.
Within the integrated platform tier, IDEXX Laboratories and Zoetis exemplify archetypes combining instrument placement density with recurring consumable revenue models. Heska Corporation occupies a position among independent clinic network specialists competing on hardware footprint rather than software ecosystem breadth. These three Delaware-incorporated entities anchor competitive dynamics across North American veterinary practice management systems.
| Leading Market Players |
|---|
| IDEXX Laboratories, Inc. |
| Zoetis, Inc. |
| Heska Corporation |
| BioNote Inc. |
| Ring Biotechnology Co., Ltd. |
| Wondfo USA Co., Ltd. |
| Affordable Pet Labs |
| Forte Healthcare Ltd. |
| Vitrosens Biotechnology |
| Others |
Value Network & Pricing Analysis
EU MDR Article 10 technical documentation requirements for in-vitro diagnostic devices now extend to veterinary applications, gating qualified supply access to manufacturers with regulatory infrastructure and compressing premium-tier pricing to established players absorbing compliance costs.
Pricing Analysis
Service bundling separates warranty-inclusive instrument placements from unbundled consumable-only transactions, with subscription consumable models for chronic disease monitoring commanding recurring revenue premiums. Price differentiation hinges on CLIA-waived certification tier and firmware-updateable hardware architecture, with refurbished biochemical analyzer cycles intensifying cost compression in the mid-market segment. Veterinary clinics demonstrate lowest price sensitivity due to captive software integration, while independent pet owners gravitate toward retail pharmacy channels with stripped-down service levels.
Supply Chain Analysis
Direct-to-veterinary-clinic channels handle instrument placement density, while retail pharmacy and online pet pharmacy intermediaries manage test kit volume. Polyclonal antibody production for canine and feline targets concentrates in Chinese contract manufacturing clusters around Zhengzhou and Suzhou, with North American lateral flow cassette producers rebalancing capacity from human diagnostics. Cold-chain interruption risks propagate through kit assembler schedules, exposing downstream partners to customs delay vulnerability at bioreagent import nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary home diagnostics is consolidating toward integrated platform owners with captive distribution, as EU MDR compliance costs and dual FDA-USDA validation friction force smaller developers to withdraw SKUs rather than absorb regulatory infrastructure investment.
For Market Incumbents: Anchor recurring revenue through backward integration into bioreagent production, securing polyclonal antibody supply against Chinese contract manufacturer concentration risk. Prioritize firmware-updateable instrument architectures that extend hardware lifecycles while accelerating consumable conversion, defending against refurbished biochemical analyzer substitution from mid-sized distributors consolidating procurement in Germany and the United Kingdom. For New Entrants and Emerging Players: Telemedicine platforms scrambling to integrate result data into prescribing workflows represent the most penetrable channel partner type, particularly in California, Texas, and Florida where practice act reforms permit treatment decisions without mandatory physical examination. Target equine and livestock extension in Brazil and Australia with portable progesterone platforms, leveraging first-mover positioning in production animal segments where home diagnostics remain underpenetrated. For Investors and Strategic Acquirers: State-level veterinary practice act reform permitting telemedicine prescribing from owner-generated data is the leading indicator that subscription consumable models will capture expanding margin pools. Acquisition targets should concentrate on bioreagent production assets with SAMR export documentation capabilities and veterinary software networks with API connectivity infrastructure, with periodic monitoring of pet insurance reimbursement policy expansion in Japan and South Korea as demand-pull signals.| Strategic Initiative | Industry Significance |
|---|---|
| Microfluidic Cartridge Miniaturization | Sub-50-microliter sample volumes enable capillary draws from cats and small-breed dogs without veterinary phlebotomy training. |
| CLIA-Waived Designation Pathway | FDA Center for Veterinary Medicine streamlined access accelerates shelf placement in retail pharmacy channels previously closed to veterinary devices. |
| Backward Bioreagent Integration | In-house polyclonal antibody production insulates kit assemblers from Chinese contract manufacturer cold-chain interruption risks. |
| Telemedicine Platform Partnership | Integration with prescribing workflows in California, Texas, and Florida captures treatment decision authority from owner-generated laboratory data. |
| Open-Architecture Reader Deployment | Universal platforms accepting swappable reagent inserts compress capital deployment for clinic networks while accelerating consumable-centric revenue conversion. |
Research Methodology
Document review covered FDA 510(k) and USDA APHIS regulatory filings, EU MDR technical documentation databases, and veterinary practice act legislative records, complemented by interviews with veterinary diagnostic product managers, regulatory affairs specialists at animal health device manufacturers, telemedicine platform integration engineers, and procurement directors at independent clinic networks. Secondary validation drew from SAMR export documentation logs, ISO 13485 certification registries, and pet insurance reimbursement policy filings. Bottom-up instrument placement and consumable volume estimates triangulated against top-down market sizing from channel shipment data.
Segment-level projections across product type, application, end user, and technology dimensions fed into analytical framework outputs spanning the projection horizon. CAGRs derived from regression against companion animal ownership trajectories, CLIA-waived designation velocity, and telemedicine prescribing rule adoption curves. Model inputs incorporated microfluidic cartridge miniaturization adoption rates, lateral flow cassette manufacturing capacity rebalancing patterns, and bioreagent supply concentration indices.
Caveats apply where FDA-USDA jurisdictional overlap clarifications, EU MDR enforcement intensity variations, or telemedicine prescribing rule rollbacks could materially shift the outlook. Forecasts embed assumptions regarding cold-chain logistics stability, customs processing efficiency at Chinese export nodes, and state-level veterinary practice act reform momentum. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Otc Pet Medication Market
Veterinary
Global Veterinary Artificial Insemination Market
Veterinary
Global Veterinary Care Market
Veterinary
Swine Respiratory Diseases Treatment Market
Veterinary
Australia Veterinary Healthcare Market
Veterinary
Global Animal Sedative Market
Veterinary
Veterinary Vaccine Adjuvants Market
Veterinary
Homeopathic Veterinary Medicines Market
Veterinary
Bovine Mastitis Treatment System Market
Veterinary
Global Animal Parasiticides Market
Veterinary
Veterinary Consumables Market
Veterinary
Bovine Respiratory Disease Treatment Market
Veterinary
Vet Software Market
Veterinary
Veterinary Parasiticides Market
Veterinary
Veterinary Biomarkers Market
Veterinary
Canine Separation Anxiety Treatment Market