
 Knotless Suture Anchors Market | 2026-2036
Knotless Suture Anchors Market Size, Share, and Industry Trends Forecast 2026-2036
Knotless Suture Anchors Market Foresight
A capital-intensity divergence between integrated implant manufacturers and specialized arthroscopy firms is reorganizing competitive tiers in knotless suture anchors. Arthrex leverages in-house fiber and anchor production to control supply continuity for sports medicine suites. Stryker anchors its position through broad orthopedic portfolios that bundle anchors with visualization systems. Smith & Nephew competes via specialized soft-tissue repair lines targeting ambulatory settings.
Knotless suture anchors are implantable fixation devices manufactured from PEEK, titanium, or bioabsorbable polymers, designed to secure tendons and ligaments to bone without traditional knot-tying, typically featuring threaded or press-fit designs with eyelet configurations for suture passage. PEEK anchors currently dominate hospital procurement due to radiolucency and pull-out strength parity with metal alternatives, while bioabsorbable variants are gaining traction in pediatric and revision cases where long-term implant retention raises concerns. The arthroscopic technique segment leads procedure volumes, though hybrid approaches combining mini-open exposure with arthroscopic fixation are expanding as surgeons address massive retracted cuff tears.
FDA 510(k) premarket notification requirements and EU MDR technical documentation obligations govern implant biocompatibility and mechanical testing standards for knotless anchors, with FDA pushing toward more rigorous comparative effectiveness data for substantial equivalence determinations. Japan's PMDA and China's NMPA maintain separate clinical evaluation pathways that delay entry for firms lacking regional trial infrastructure. Stakeholders must monitor evolving regulator demands for real-world performance registries as payers shift toward value-based reimbursement for outpatient shoulder procedures.
Market Dynamics
Arthroscopic technique refinement is compressing procedure times and expanding treatable tear patterns, forcing anchor manufacturers to redesign eyelet geometries and suture management systems for tighter working corridors.
Growth Catalysts
- FDA 510(k) pathway streamlining:Substantial equivalence determinations for knotless anchor iterations accelerate commercialization timelines compared with premarket approval routes, incentivizing incremental design improvements.
- Ambulatory surgical center expansion:United States outpatient shoulder repair volumes outpace hospital-based procedures, creating dedicated inventory demand for same-day discharge protocols.
- Bioabsorbable polymer advancement:PLGA and PLLA copolymer degradation profiles now match tendon-bone healing windows, opening pediatric and revision case applications where metal retention risks complications.
Market Restraints
- PEEK raw material concentration:Medical-grade polyetheretherketone resin production concentrates among three European chemical suppliers, exposing anchor manufacturers to allocation disruptions.
- EU MDR technical documentation burden:Clinical evaluation requirements for substantial equivalence under the Medical Device Regulation extend review timelines and inflate regulatory compliance costs for mid-tier firms.
- Allograft tendon substitution:Bridge graft techniques for massive cuff tears reduce anchor count per procedure in select academic medical center practices.
Strategic Opportunities
- Japan PMDA clinical trial infrastructure:Firms establishing regional investigator networks gain priority review status for novel anchor designs targeting the aging population's rotator cuff pathology burden.
- Reverse shoulder arthroplasty hybrid fixation:Glenoid baseplate supplemental anchor fixation creates procedural overlap demand distinct from primary cuff repair applications.
- Remote surgical training platforms:Virtual reality simulation for arthroscopic knotless anchor placement expands addressable surgeon training markets beyond traditional fellowship programs.
Industry Challenges
- Biomechanical testing standardization:Absence of unified ASTM protocols for cyclic loading and pull-out strength comparison complicates competitive performance claims and procurement evaluation.
- Surgeon retraining requirements:Transition from knotted to knotless fixation demands cadaveric lab investment and proctoring support that strains medical education budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Knotless Suture Anchors Market |
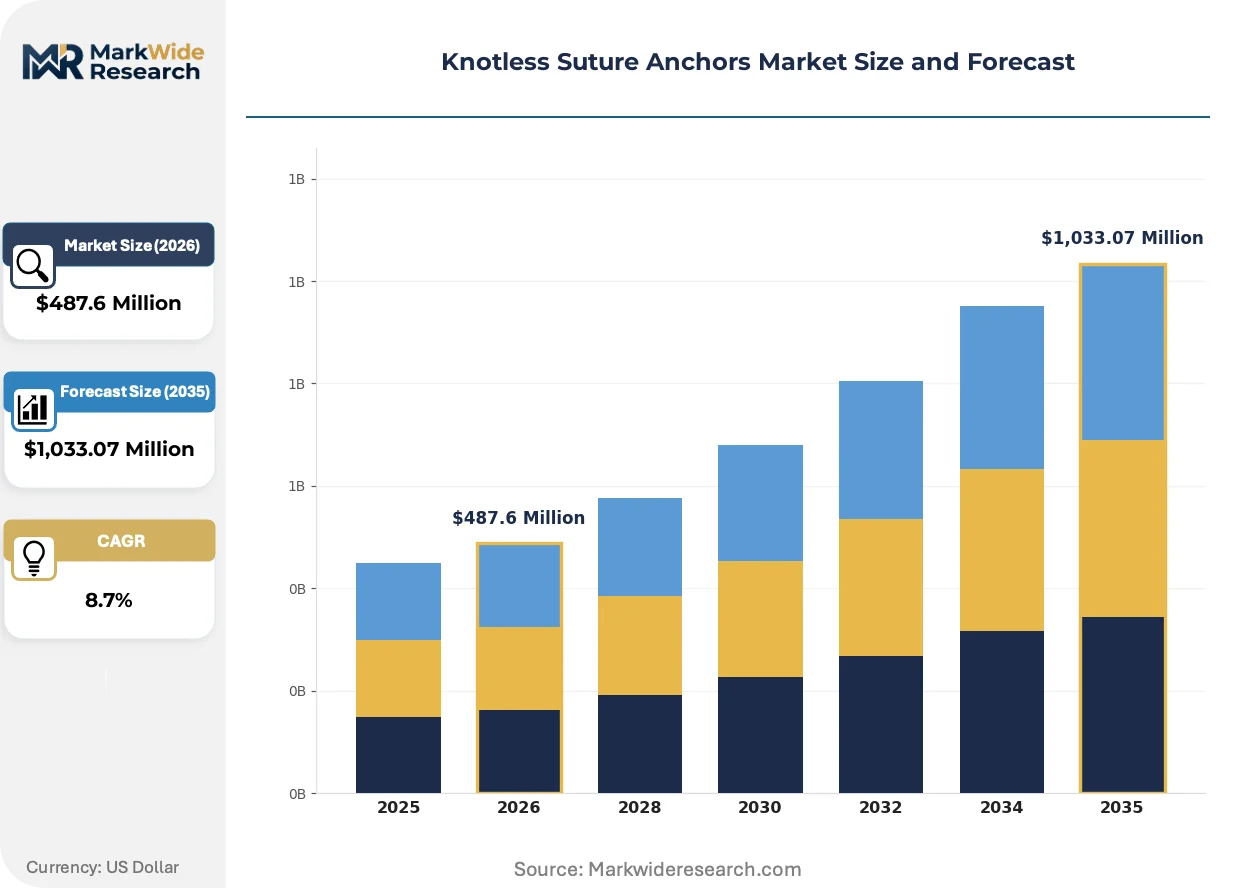
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PEEK Anchors, Titanium Anchors, Bioabsorbable Anchors, Multifunctional Anchors Application: Orthopedic Surgery, Sports Medicine, General Surgery, Dental Procedures End User: Hospitals, Ambulatory Surgical Centers, Orthopedic Clinics, Rehabilitation Centers Technique: Arthroscopic Technique, Open Technique, Mini-Open Technique, Hybrid Technique |
| Companies Covered | Zimmer Biomet, DePuy Synthes, Arthrex, Johnson & Johnson, In2Bones Global, Stryker, Smith & Nephew, Parcus Medical, CONMED Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Knotless Suture Anchors Market Shifts & Advancements
Material science convergence with digital surgical planning is redefining anchor selection criteria, shifting competitive advantage from mechanical specifications toward integrated system compatibility.
High-strength suture tape constructs is supplanting traditional braided polyethylene in rotator cuff repairs, distributing load across broader bone-implant interfaces. Sports medicine surgeons at academic medical centers are adopting tape-based fixation for massive tears previously considered irreparable. This transition is compressing demand for conventional eyelet designs optimized for round suture passage.
EU MDR Article 10 post-market clinical follow-up requirements now mandate systematic implant performance tracking across member states. Manufacturers must establish quality management systems capable of capturing real-world failure modes and revision triggers. Smaller anchor specialists lacking European notified body relationships face market access delays extending twelve to eighteen months beyond historical CE marking timelines.
Hospital procurement committees are consolidating orthopedic implant contracts into multi-year bundled agreements spanning anchors, sutures, and arthroscopy visualization systems. Independent ambulatory surgery centers respond through group purchasing organization membership to recover volume pricing leverage. This channel consolidation is most pronounced in the United States, where health system merger activity concentrates purchasing authority among ten to fifteen regional networks.
Knotless Suture Anchors Market Segmentation
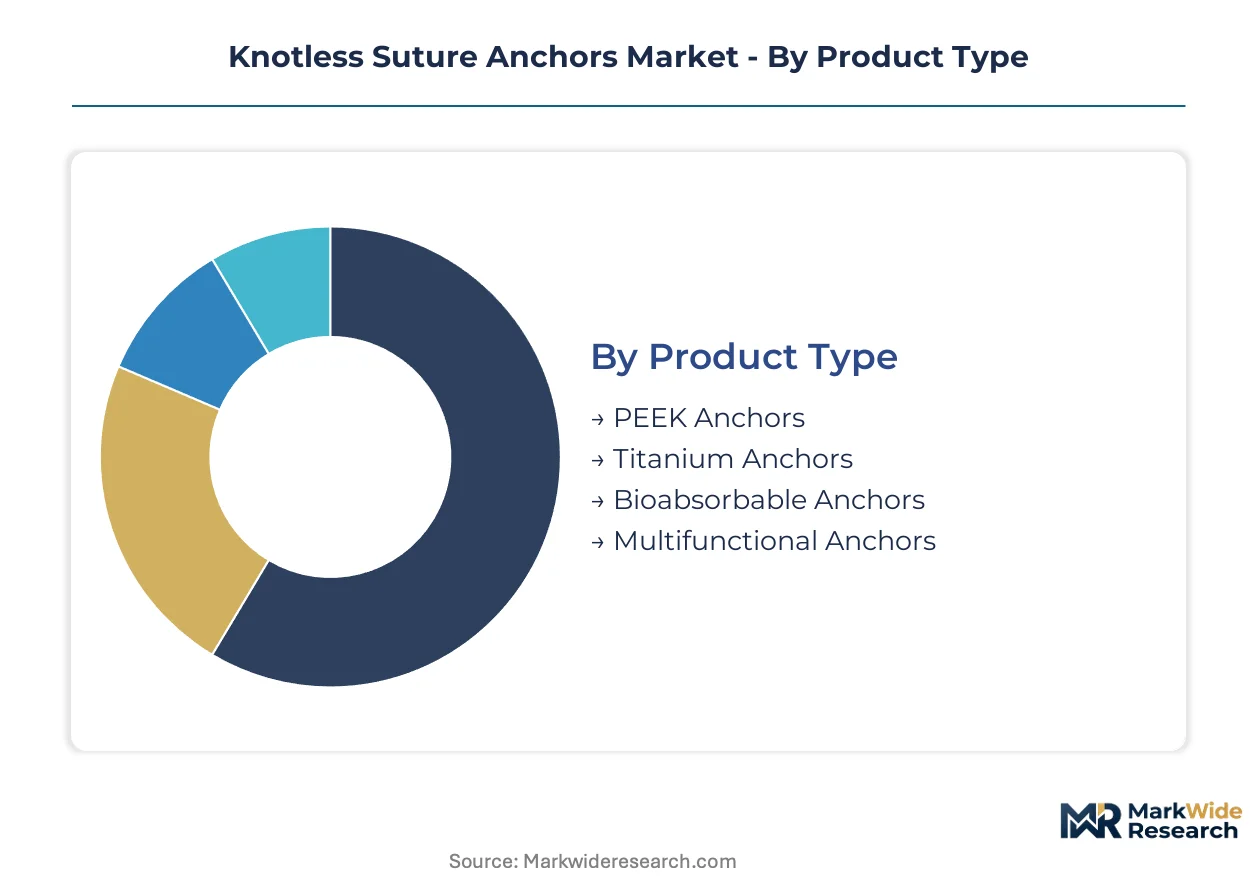
Segmentation in knotless suture anchors reveals how procurement channels, reimbursement pathways, and surgeon training requirements fragment demand across distinct customer profiles. Manufacturers must align product portfolios with specific facility capabilities and procedure volumes rather than pursuing undifferentiated distribution.
Product Type:
PEEK anchors flow predominantly through hospital procurement committees with radiolucency requirements, while bioabsorbable variants target specialized pediatric and revision centers with distinct inventory protocols.
- PEEK Anchors:Polyetheretherketone polymer construction delivers radiolucent imaging compatibility and pull-out strength matching titanium alternatives. United States hospital systems with high arthroscopy volumes dominate procurement, driven by radiology department demands for post-operative MRI clarity without metal artifact.
- Bioabsorbable Anchors:PLGA and PLLA copolymer formulations degrade in alignment with tendon-bone healing windows. Pediatric orthopedic departments at academic medical centers in Germany and Japan are expanding adoption, constrained by premium pricing relative to permanent implants and surgeon skepticism toward degradation kinetics.
- Titanium Anchors:Metal construction suits revision cases requiring radiopaque confirmation of placement depth.
- Multifunctional Anchors:Integrated suture management and depth-limiting features target high-volume sports medicine practices.
By volume, PEEK anchors lead hospital procurement. By growth pace, bioabsorbable variants are expanding most quickly in pediatric applications.
Application:
Cost tier differentiation separates high-reimbursement sports medicine procedures from lower-margin general surgery applications where suture anchors compete with traditional fixation methods.
- Orthopedic Surgery:Rotator cuff repair, labral reconstruction, and glenohumeral instability procedures constitute the procedural core. United States ambulatory surgical centers with dedicated shoulder specialists generate concentrated demand, supported by favorable outpatient reimbursement codes for arthroscopic techniques.
- Sports Medicine:Athlete-specific protocols emphasize rapid return-to-play timelines and biologically active fixation surfaces. FIFA and IOC medical commission guidelines influence product selection at elite training facilities in Switzerland and Qatar, where sponsor relationships with implant manufacturers shape procurement.
- General Surgery:Hernia mesh fixation and soft tissue approximation applications utilize lower-profile anchor designs.
- Dental Procedures:Maxillofacial trauma and orthodontic anchorage represent niche volume with specialized regulatory pathways.
Orthopedic surgery captures the highest absolute procedure volume. Sports medicine claims the steepest expansion trajectory as professional league medical budgets increase.
End User:
Customer type fragmentation creates distinct sales force requirements, with hospital systems demanding bundled contracting and ambulatory centers prioritizing inventory turnover and same-day availability.
- Hospitals:Integrated delivery networks consolidate orthopedic implant purchasing across multiple facilities, negotiating multi-year agreements that bundle anchors with arthroscopy equipment and visualization systems. Ten to fifteen United States regional health systems now control the majority of hospital-based anchor procurement.
- Ambulatory Surgical Centers:Freestanding facilities prioritize just-in-time inventory and disposable instrument compatibility. Group purchasing organization membership allows independent ASCs in Texas, Florida, and California to recover volume pricing leverage against consolidated health system competition.
- Orthopedic Clinics:Office-based surgical suites with limited procedure volumes drive demand for smaller pack quantities.
- Rehabilitation Centers:Post-operative monitoring and secondary intervention sites influence revision anchor demand indirectly.
Ambulatory surgical centers are gaining share fastest as outpatient shoulder migration accelerates. Hospitals retain the largest installed base of arthroscopy suites.
Technique:
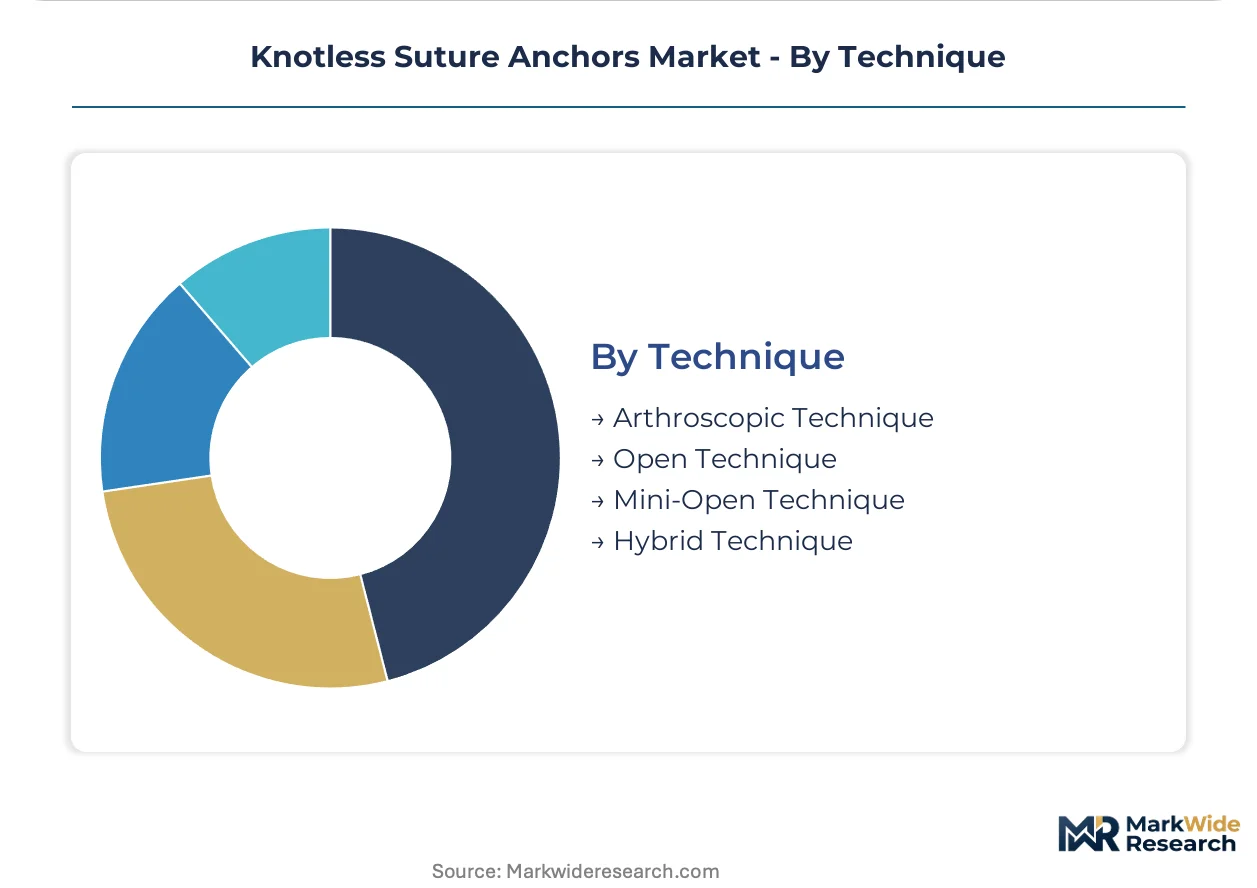
Maturity curves vary dramatically, with arthroscopic approaches now standard for routine tears while hybrid techniques address complex pathology previously considered irreparable.
- Arthroscopic Technique:Fully endoscopic fixation through standard posterior and anterior portals dominates routine supraspinatus and infraspinatus repairs. Surgeon training programs at Mayo Clinic, Hospital for Special Surgery, and Andrews Sports Medicine have standardized arthroscopic anchor placement curricula, creating generational preference for knotless systems among recently graduated fellows.
- Hybrid Technique:Mini-open exposure combined with arthroscopic fixation addresses massive retracted cuff tears requiring direct tendon mobilization. Academic medical centers in Boston and Philadelphia are expanding hybrid procedure volumes as patient selection criteria broaden, demanding anchors compatible with both arthroscopic and open instrument sets.
- Open Technique:Traditional incision-based fixation persists in revision scenarios with extensive scar tissue.
- Mini-Open Technique:Limited exposure approaches without arthroscopic assistance retain niche application in resource-constrained settings.
Arthroscopic technique leads by procedure count. Hybrid technique is climbing the fastest as massive tear treatment protocols evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States, where ambulatory surgical center reimbursement rates exceed European hospital procurement benchmarks by substantial margins. Germany and Japan maintain premium positioning through specialized orthopedic clusters. China and Brazil represent volume expansion corridors with diverging regulatory pathways.
United States
FDA 510(k) clearance pathways compress commercialization timelines for knotless anchor iterations. Ambulatory surgical centers in Texas, Florida, and California generate concentrated demand for same-day discharge protocols. The Hospital for Special Surgery in New York anchors clinical training networks that shape surgeon preference for arthroscopic knotless systems.
Germany
EU MDR technical documentation requirements extend review timelines for substantial equivalence determinations. Industrial clusters in Bavaria and Baden-Württemberg host orthopedic device manufacturing facilities serving Central European procurement networks. Heidelberg and Berlin academic medical centers pioneer hybrid technique protocols for massive cuff tears.
Japan
PMDA clinical trial infrastructure demands regional investigator networks for priority review status. Aging population demographics drive rotator cuff pathology volumes in Kanto and Kansai metropolitan areas. Osaka-based sports medicine institutes influence anchor selection criteria for elite athlete protocols across East Asia.
China
NMPA maintains separate clinical evaluation pathways that delay market entry without domestic trial infrastructure. Yangtze River Delta medical centers expand arthroscopy suite capacity for shoulder procedures. Shanghai procurement committees consolidate orthopedic implant purchasing across municipal hospital networks.
Brazil
ANVISA regulatory frameworks govern import licensing for orthopedic implants with extended documentation requirements. São Paulo and Rio de Janeiro concentrate sports medicine practice volumes for professional football medical services. Private hospital networks in Southeast Brazil drive premium anchor demand outside public procurement systems.
Knotless Suture Anchors Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics. Integrated orthopedic conglomerates command bundled contracting leverage across hospital systems. Specialized arthroscopy firms compete through surgeon training relationships and technique-specific product development. Mid-tier manufacturers pursue group purchasing organization access to penetrate ambulatory surgical center channels.
Within the integrated orthopedic tier, Zimmer Biomet and Stryker occupy positions defined by broad implant portfolios spanning joint reconstruction and sports medicine. Arthrex exemplifies the specialized arthroscopy archetype, anchoring competitive positioning through in-house fiber and anchor production capabilities. Johnson & Johnson's DePuy Synthes unit represents the diversified medical technology conglomerate model with cross-category procurement influence.
| Leading Market Players |
|---|
| Zimmer Biomet |
| DePuy Synthes |
| Arthrex |
| Johnson & Johnson |
| In2Bones Global |
| Stryker |
| Smith & Nephew |
| Parcus Medical |
| CONMED Corporation |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day lead times for medical-grade PEEK resin translate directly into pricing power asymmetry between integrated anchor manufacturers and specialized assemblers. Knotless suture anchor procurement committees exploit this inventory vulnerability to extract volume concessions from mid-tier suppliers lacking backward integration into polymer supply.
Pricing Analysis
The customization-premium spread between standard PEEK anchors and patient-specific bioabsorbable configurations reaches three-to-one multiples. Transactional per-unit pricing dominates hospital procurement, with differentiation driven by FDA 510(k) clearance tier and radiolucency certification grade. Cost compression in standard titanium anchors intensifies as Chinese manufacturers penetrate group purchasing organization channels. Ambulatory surgical centers exhibit highest price sensitivity, while academic medical centers prioritize performance specifications over unit economics.
Supply Chain Analysis
European chemical conglomerates in Germany, Belgium, and the Netherlands control medical-grade PEEK resin production, creating single-source vulnerability for anchor manufacturers. Raw material dependencies center on polyetheretherketone polymer, high-strength polyethylene suture fiber, and precision-machined titanium blanks. Tariff exposure on Chinese-sourced titanium feedstock compounds margin pressure. Distribution runs through orthopedic implant distributors holding consignment inventory at hospital systems and ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Knotless suture anchor demand follows elective procedure cyclicality, with rotator cuff repair volumes contracting during economic downturns as patients defer non-urgent interventions.
For Market Incumbents: Fortify supply continuity through captive PEEK resin relationships or qualified secondary polymer sources. Secure FDA 510(k) clearance for next-generation bioabsorbable formulations before EU MDR technical documentation burdens escalate compliance costs. Defend hospital procurement committee positions by bundling anchors with arthroscopy visualization systems. For New Entrants and Emerging Players: Anchor in ambulatory surgical center channels where group purchasing organization membership lowers barrier-to-entry versus consolidated health system contracting. Target pediatric orthopedic departments at German and Japanese academic medical centers with bioabsorbable anchor lines. Pursue proctoring partnerships with fellowship training programs to build surgeon preference early in career development. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because hospital procurement consolidation and EU MDR compliance costs will force mid-tier anchor specialists toward acquisition. Target firms with established European notified body relationships and proprietary suture management intellectual property. Monitor ambulatory surgical center case migration rates as inflection indicator for channel shift timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Accelerates CE marking timelines for bioabsorbable anchor portfolios competing against PEEK incumbents. |
| Hospital System Partnership | Locks in multi-year bundled contracts spanning anchors, sutures, and arthroscopy equipment at Mayo Clinic-scale institutions. |
| Backward Integration into PEEK Polymer | Insulates Arthrex-scale manufacturers from European chemical supplier allocation disruptions. |
| Reimbursement Strategy | Secures favorable outpatient procedure codes for ambulatory surgical center shoulder repairs in United States markets. |
| Software Companion Development | Enables virtual reality surgical training platforms for arthroscopic knotless anchor placement beyond fellowship programs. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with orthopedic surgeons, hospital purchasing committee chairs, biomedical engineers, and group purchasing organization contract managers; and secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and arthroscopy device trade customs data. Bottom-up procedure volume estimates triangulated against top-down implant manufacturer revenue segmentation.
Across the projection horizon, the analytical framework modeled demand by material type, application specialty, end-user facility tier, and surgical technique complexity. CAGRs derived from procedure volume elasticity to ambulatory surgical center expansion and bioabsorbable polymer adoption curves. Industry-specific inputs included rotator cuff repair incidence by age demographic and health system merger activity concentrating purchasing authority.
Material uncertainties — regulatory delays at Japan's PMDA, PEEK resin supply disruptions, and allograft substitution for massive cuff tears — sit outside the modeled envelope. Forecasts reflect assumptions about outpatient migration and bioabsorbable degradation profile reliability. Practitioners should keep alternative scenarios live as EU MDR post-market clinical follow-up requirements and United States payer reimbursement policies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Skin Rejuvenation Devices Market
Medical Devices
Positive Air Pressure Devices Market
Medical Devices
Italy Minimally Invasive Surgery Devices Market
Medical Devices
Sinus Implants Market
Medical Devices
Global Hemostasis Valves Market
Medical Devices
Global Endotracheal Tubes Market
Medical Devices
Saudi Arabia Minimally Invasive Surgery Devices Market
Medical Devices
Mobile Operating Rooms Market
Medical Devices
Orthodontic Headgear Market
Medical Devices
Europe Ultrasound Devices Market
Medical Devices
North America Neurostimulation Devices Market
Medical Devices
Radial Head Resection Implant Market
Medical Devices
Clinical Trinocular Microscopes Market
Medical Devices
Pectus Bar Market
Medical Devices
Veterinary Injectable Devices Market
Medical Devices
Radiotherapy Positioning Devices Market