
 Europe Foot Orthotic Insoles Market | 2026-2036
Europe Foot Orthotic Insoles Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Foot Orthotic Insoles Market Insights
Podiatric specialist availability is bifurcating the Europe Foot Orthotic Insoles Market into regions with adequate clinical access and those facing practitioner shortages. Bauerfeind leverages its German manufacturing base to dominate Central European distribution. Ottobock SE & Co. KGaA anchors the high-end custom segment through its prosthetics heritage and clinical partnerships. Superfeet Worldwide Inc competes in the sports application layer with specialized arch support designs.
Foot orthotic insoles are biomechanical devices engineered from foam, gel, plastic, or carbon fiber composites to redistribute plantar pressure, correct gait abnormalities, and absorb shock during ambulation. Manufacturing employs heat-molding, CAD/CAM milling, or selective laser sintering for custom geometries tailored to individual plantar scans. Prefabricated insoles occupy the volume tier through pharmacy and online retail channels, while 3D printed variants capture premium positioning via orthopedic clinics. Carbon fiber materials sustain margin pools in the post-surgery segment where rigidity and durability command price premiums.
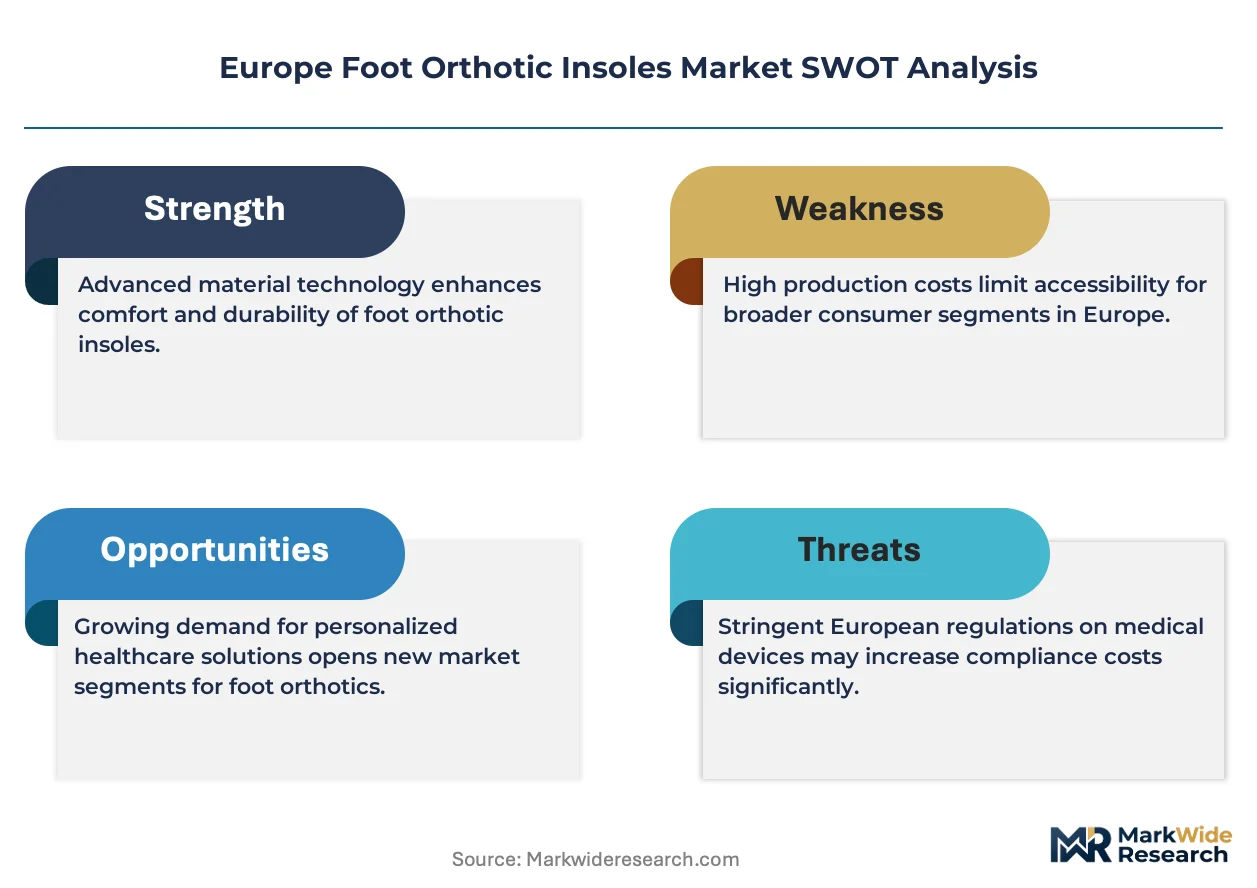
The EU Medical Device Regulation and CE marking framework govern material biocompatibility and clinical claims across member states, with EMA-aligned notified bodies conducting conformity assessments for custom devices. Germany's KBA-equivalent medical device regulator, the BfArM, enforces additional post-market surveillance that elevates compliance costs for smaller manufacturers. Stakeholders must monitor how the EU AI Act intersects with emerging gait-analysis software embedded in smart insole systems.
Market Dynamics
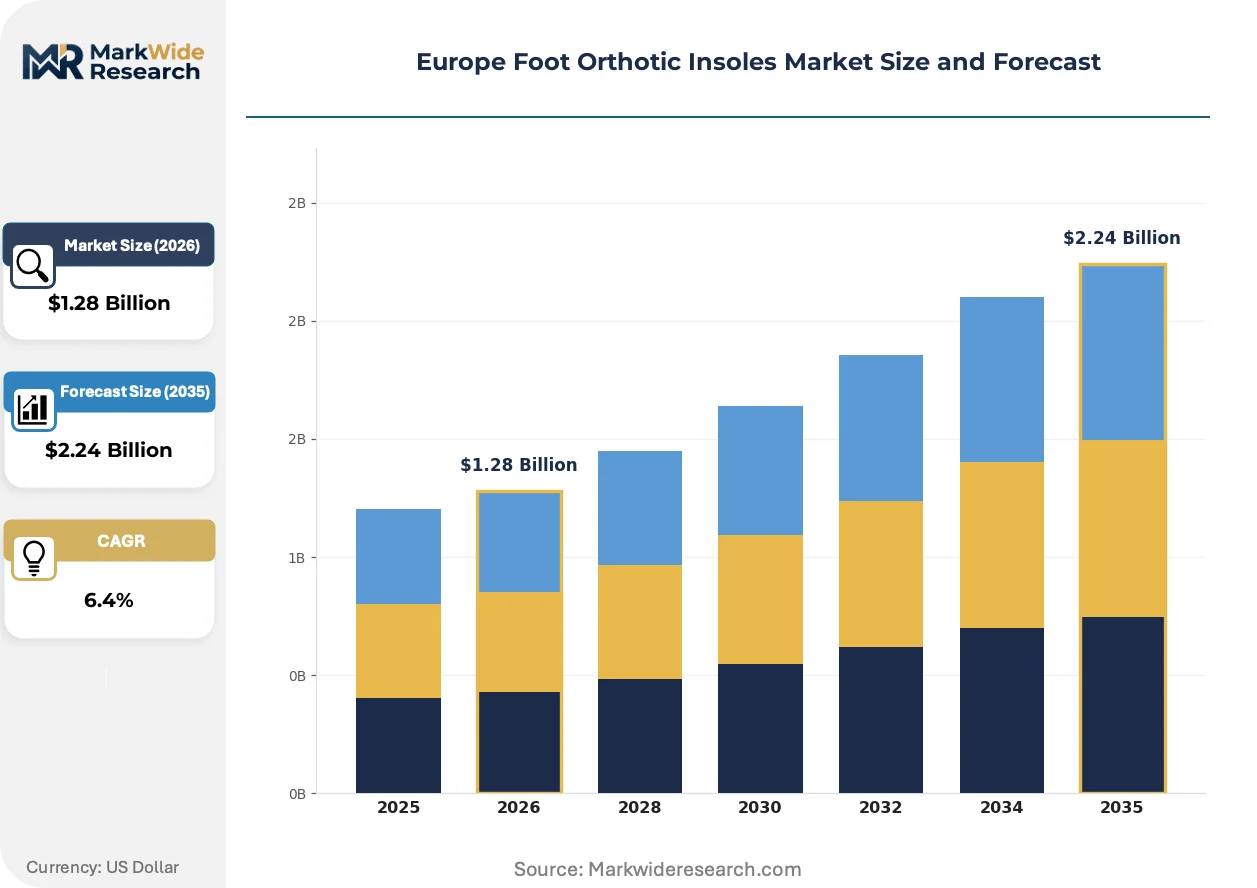
The EU Medical Device Regulation (MDR) is forcing wholesale reformulation of material sourcing and clinical evidence requirements, compressing margins for manufacturers while accelerating consolidation among notified body-dependent suppliers.
Growth Catalysts
- EU MDR Compliance Thresholds:Stricter CE marking requirements under the Medical Device Regulation are filtering out low-quality imports, creating protected market space for compliant domestic manufacturers in Germany and France.
- Carbon Fiber Composite Adoption:Post-surgical rehabilitation protocols increasingly specify rigid carbon fiber insoles for metatarsal fracture recovery, pulling premium material demand through orthopedic clinic networks.
- Podiatrist Density in Germany:The country's 4,000+ practicing podiatrists generate consistent referral volumes that sustain custom insole fabrication demand unmatched elsewhere in Europe.
Market Restraints
- Ethylene-Vinyl Acetate Price Volatility:Foam insole producers face margin erosion from petrochemical feedstock fluctuations that resist downstream price pass-through in pharmacy retail channels.
- Notified Body Bottleneck Concentration:Only 12 EU MDR-designated notified bodies remain operational for custom device certification, creating 18-month approval queues that freeze product launches.
- Prefabricated Gel Substitutes:Mass-market gel insoles priced at one-tenth custom equivalents capture price-sensitive diabetic foot care demand in Southern European retail pharmacies.
Strategic Opportunities
- Poland's Underserved Clinical Infrastructure:The country's podiatrist-to-population ratio remains one-third of Germany's, creating whitespace for clinic-partnership distribution models.
- EU AI Act Gait Analysis Integration:Embedded pressure-sensor insoles with automated pathology flagging qualify for streamlined CE marking under emerging software-as-medical-device pathways.
- Direct-to-Consumer 3D Scanning:Smartphone plantar scanning applications enable remote custom fitting, bypassing traditional orthopedic clinic gatekeepers in Nordic markets with dispersed populations.
Industry Challenges
- CAD/CAM Technician Scarcity:Custom fabrication facilities in Italy and Spain report 14-month hiring cycles for operators proficient in selective laser sintering equipment.
- Biocompatibility Testing Backlogs:ISO 10993 cytotoxicity validation queues at EMA-aligned laboratories extend product development timelines by 8-10 months for novel foam formulations.
- Legacy ERP Integration:Mid-sized manufacturers struggle to reconcile MDR-mandated post-market surveillance data streams with 1990s-era inventory management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Foot Orthotic Insoles Market |
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.24 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Insole Type: Custom, Prefabricated, Semi-Custom, 3D Printed Material: Foam, Gel, Plastic, Carbon Fiber Application: Diabetic Care, Sports, Everyday Use, Post-Surgery Distribution Channel: Online Retail, Pharmacies, Hospitals, Orthopedic Clinics |
| Companies Covered | Ottobock SE & Co. KGaA, Superfeet Worldwide Inc, Bauerfeind, Össur hf, Implus Footcare LLC, Hanger Inc., Algeo Limited, Aetrex Inc., Foot Science International, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Foot Orthotic Insoles Market Trends and Innovations
Selective laser sintering is collapsing the cost differential between custom and prefabricated insoles, while regulatory digitization and channel fragmentation simultaneously reshape competitive positioning across the value chain.
Additive manufacturing of nylon-12 powder composites is decomposing the traditional volume-premium segmentation that separated mass-market foam from bespoke carbon fiber. German orthopedic clinics now deploy desktop SLS units for same-day custom fabrication, compressing patient wait times from three weeks to four hours. This capability is decomposing the historical monopoly of centralized fabrication labs on complex geometry production.
The EU AI Act's risk-classification framework for software-as-medical-device is forcing gait-analysis algorithm developers to restructure clinical validation protocols. Embedded insole pressure-mapping systems now require prospective clinical trials for CE marking, elevating development costs for smart insole entrants. Post-surgical monitoring applications in German rehabilitation centers face the steepest compliance burden under these emerging requirements.
Pharmacy chains in France and Belgium are unbundling professional fitting services from product sales, training retail staff to operate 3D foot scanners for self-service custom ordering. This bypasses traditional podiatrist gatekeepers while capturing margin that previously flowed to clinical intermediaries. The model is compressing most aggressively in urban catchments where podiatrist appointment availability lags patient demand by 6-8 weeks.
Europe Foot Orthotic Insoles Market Segmentation
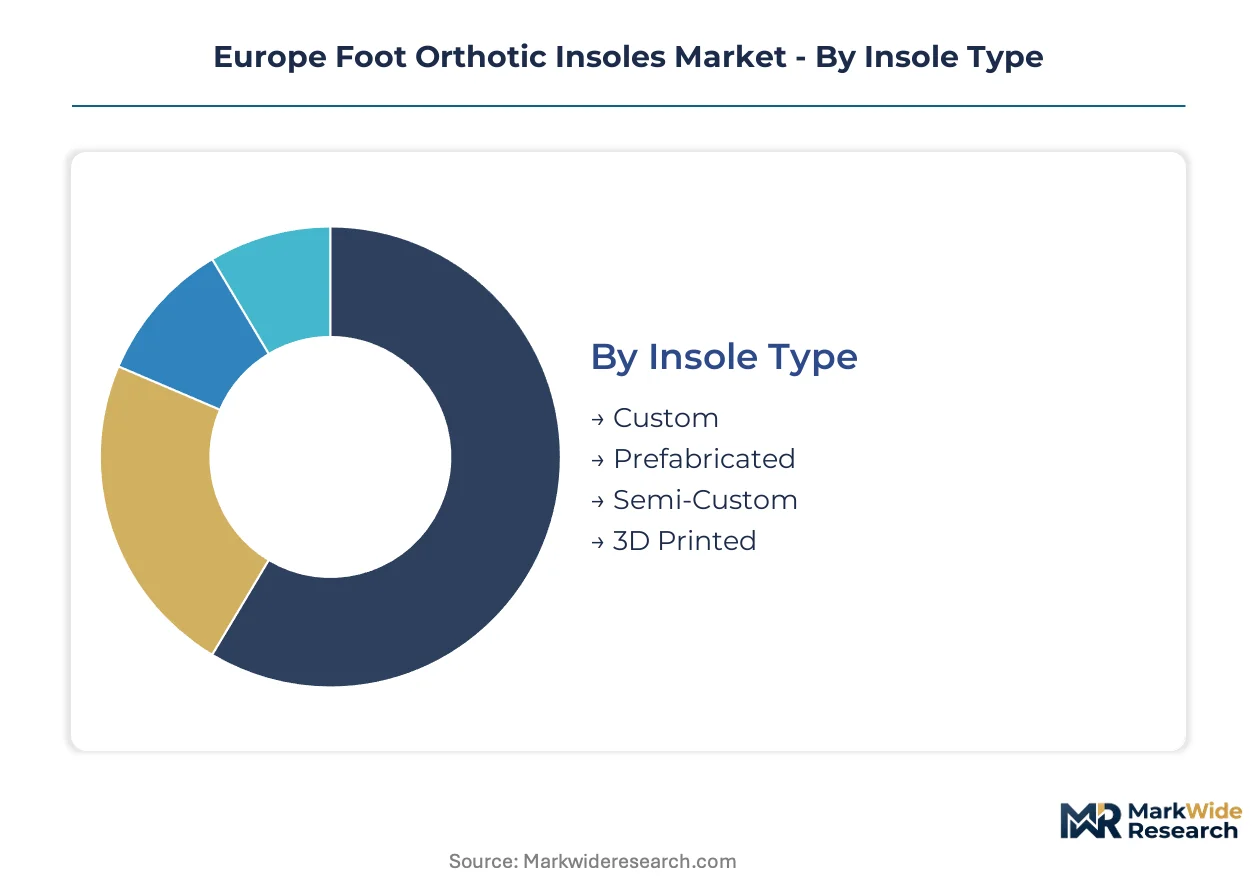
Foot orthotic insoles fragment across four structural dimensions that determine pricing power, regulatory burden, and channel access. Each segmentation axis maps to distinct manufacturing capabilities and clinical validation requirements under EU MDR frameworks.
Insole Type:
Channel-mix dynamics split sharply: custom and 3D printed variants flow exclusively through orthopedic clinics and hospital outpatient departments, while prefabricated units dominate pharmacy and online retail volume.
- Custom:Heat-molded or CAD/CAM milled devices fabricated from individual plantar scans. German orthopedic clinics generate the densest referral volumes, where podiatrist density sustains premium positioning against MDR compliance costs.
- Prefabricated:Mass-produced foam and gel insoles stocked in pharmacy chains across France and Belgium. Price compression from ethylene-vinyl acetate feedstock volatility limits margin expansion in this tier.
- Semi-Custom:Modular systems with adjustable arch supports and heat-trimmable bases. Retail staff in Nordic markets increasingly manage fitting without clinical intermediaries.
- 3D Printed:Selective laser sintering of nylon-12 composites enables same-day fabrication in German clinic settings. Desktop SLS units are collapsing traditional three-week fulfillment cycles to under four hours.
By volume, Prefabricated leads. By growth pace, 3D Printed is expanding most quickly.
Material:
Cost tiers stratify from commodity petrochemical derivatives to aerospace-grade composites, with carbon fiber commanding 8-12x unit economics of standard foam formulations.
- Foam:Ethylene-vinyl acetate and polyurethane variants constitute the volume base. Southern European retail pharmacies in Italy and Spain move the highest unit volumes at entry price points.
- Carbon Fiber:Rigid composite laminates specified for post-metatarsal fracture rehabilitation. German rehabilitation centers and orthopedic networks pull premium material demand through clinical procurement channels.
- Gel:Viscoelastic silicone polymers targeting diabetic pressure redistribution. Mass-market substitutes capture price-sensitive segments in pharmacy retail.
- Plastic:Thermoplastic polyolefin shells for semi-rigid support applications. Injection molding economies sustain mid-tier positioning between foam and carbon fiber.
By revenue concentration, Carbon Fiber dominates premium pools. By unit velocity, Foam maintains the steepest shipment volumes.
Application:
End-use specialization determines clinical validation depth: post-surgical and diabetic segments face ISO 10993 biocompatibility mandates, while sports applications emphasize performance metrics over regulatory documentation.
- Post-Surgery:Rigid orthotic protocols for metatarsal and calcaneal fracture recovery. German hospital systems specify carbon fiber composites for load-bearing rehabilitation phases.
- Sports:Dynamic arch support engineered for repetitive impact absorption. Specialized designs from performance-oriented manufacturers target running and cycling segments in Benelux markets.
- Diabetic Care:Pressure-mapping insoles for neuropathic foot ulcer prevention. Southern European pharmacy channels compete with low-cost gel substitutes in price-sensitive markets.
- Everyday Use:General comfort and mild biomechanical correction for occupational standing. Online retail penetration is highest in Nordic countries with dispersed populations.
By clinical revenue per patient, Post-Surgery leads. By addressable population expansion, Diabetic Care is gaining share fastest.
Distribution Channel:
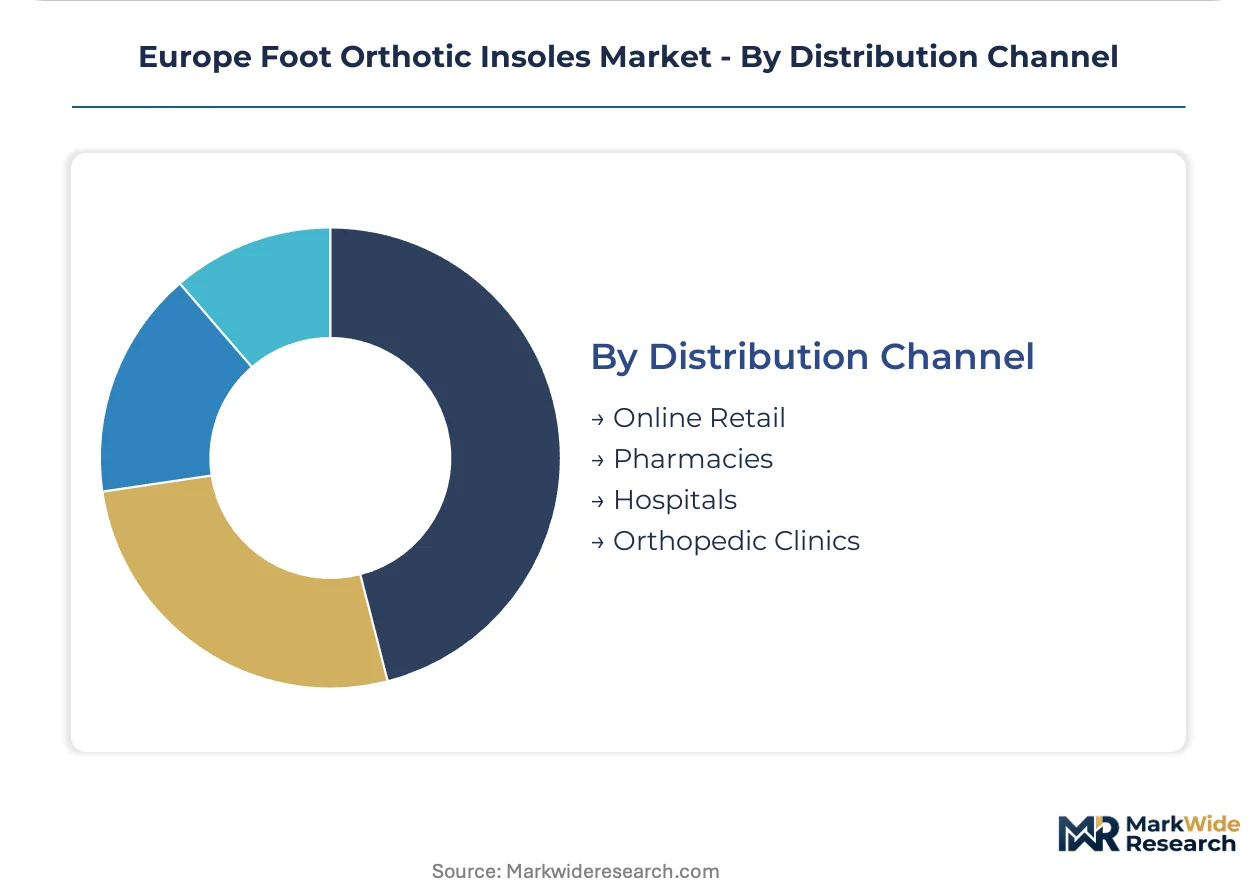
Channel fragmentation is accelerating: pharmacy chains in France and Belgium are unbundling professional fitting from product sales, while orthopedic clinics defend custom fabrication margins through MDR-mandated clinical oversight.
- Orthopedic Clinics:Gatekeepers for custom and 3D printed segments with podiatrist-directed fitting. Germany's 4,000+ practicing podiatrists sustain unmatched referral density.
- Online Retail:Direct-to-consumer platforms with smartphone scanning applications bypassing traditional clinical intermediaries. Nordic markets show highest adoption due to geographic dispersion.
- Pharmacies:Self-service retail with trained staff operating 3D foot scanners in urban French and Belgian catchments. Six-to-eight-week podiatrist appointment lags drive this substitution.
- Hospitals:Post-surgical rehabilitation procurement through centralized medical device committees. German rehabilitation centers specify rigid carbon fiber protocols for fracture recovery.
By custom product value, Orthopedic Clinics dominate. By volume velocity, Pharmacies maintain the broadest reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The BfArM anchors the dominant geography through post-market surveillance mandates that elevate compliance costs for custom device manufacturers. Germany's orthopedic clinic density and podiatrist referral networks sustain premium fabrication demand unmatched elsewhere in Europe. France, Belgium, and the Netherlands concentrate retail pharmacy innovation, while Poland presents clinical infrastructure whitespace.
Germany
Over 4,000 practicing podiatrists generate consistent referral volumes for custom and 3D printed insole fabrication. The BfArM enforces additional post-market surveillance beyond baseline EU MDR requirements, compressing margins for smaller notified body-dependent suppliers. Bavaria and North Rhine-Westphalia host dense clusters of orthopedic clinics deploying desktop selective laser sintering units for same-day patient fulfillment.
France
Pharmacy chains in Paris and Lyon catchments unbundle professional fitting from product sales, training retail staff to operate 3D foot scanners for self-service custom ordering. The ANSM oversees material biocompatibility standards for diabetic care applications. Six-to-eight-week podiatrist appointment lags in urban Île-de-France drive substitution toward pharmacy-based scanning models.
Belgium
Retail pharmacy networks in Brussels and Antwerp accelerate channel fragmentation through trained staff-managed 3D scanning installations. CE marking requirements under EU MDR filter low-quality imports, protecting compliant domestic distribution. The Flanders region concentrates semi-custom modular system adoption where retail fitting substitutes for clinical intermediaries.
Netherlands
Dispersed populations in rural Friesland and Gelderland drive direct-to-consumer platform adoption with smartphone plantar scanning applications. The Dutch Health and Youth Care Inspectorate aligns with EMA-notified body frameworks for custom device oversight. Randstad urban corridors maintain traditional orthopedic clinic gatekeeping for post-surgical rehabilitation protocols.
Poland
Podiatrist-to-population ratios at one-third of German levels create whitespace for clinic-partnership distribution models in Warsaw and Kraków. EU MDR compliance thresholds filter non-compliant imports, opening protected market space for domestic manufacturers. The country's underserved clinical infrastructure presents partnership opportunities for German and French fabricators seeking geographic expansion.
Europe Foot Orthotic Insoles Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the value chain. German orthopedic specialists and prosthetics heritage firms anchor the premium custom segment through clinical partnerships and MDR-mandated fabrication oversight. Scale-driven foam producers compete on pharmacy retail penetration and ethylene-vinyl acetate formulation efficiency. Consolidation pressures concentrate among notified body-dependent suppliers facing 18-month approval queues, while strategic partnerships between clinic networks and fabrication technology providers reshape distribution economics.
Among German-based manufacturers, Bauerfeind and Ottobock SE & Co. KGaA occupy positions exemplifying the premium custom archetype through prosthetics heritage and dense clinical referral networks. Superfeet Worldwide Inc represents the specialized sports application layer with performance-oriented positioning. These three anchors illustrate how geographic manufacturing concentration, clinical partnership depth, and application specialization stratify competitive positioning under tightening EU MDR compliance frameworks.
| Leading Market Players |
|---|
| Ottobock SE & Co. KGaA |
| Superfeet Worldwide Inc |
| Bauerfeind |
| Össur hf |
| Implus Footcare LLC |
| Hanger Inc. |
| Algeo Limited |
| Aetrex Inc. |
| Foot Science International |
| Others |
Pricing and Supply Chain Analysis
Selective laser sintering of nylon-12 composites is displacing centralized carbon fiber fabrication in German orthopedic clinics, simultaneously collapsing patient fulfillment cycles from three weeks to four hours and eroding the traditional premium that rigid post-surgical insoles commanded over prefabricated foam alternatives.
Pricing Analysis
German custom insoles command 8-12x unit economics over Southern European pharmacy-grade foam, with carbon fiber laminates sustaining premium positioning through MDR-mandated clinical oversight while ethylene-vinyl acetate feedstock volatility compresses mass-market margins. Price differentiation hinges on certification tier under EU MDR frameworks and podiatrist-directed fitting density. Cost compression in the prefabricated tier intensifies as gel substitutes capture diabetic foot care demand. Price-sensitive buyers concentrate in Italian and Spanish retail pharmacies, while German rehabilitation centers show lowest sensitivity to rigid composite pricing.
Supply Chain Analysis
Inventory lead times for custom devices stretch 14-18 months at EMA-aligned notified bodies, forcing manufacturers to buffer with prefabricated stock in pharmacy channels. Supply concentrates in Germany for carbon fiber composites and desktop SLS fabrication, Italy and Spain for foam injection molding, and China for nylon-12 powder feedstock. Raw material dependencies span ethylene-vinyl acetate petrochemical derivatives, aerospace-grade carbon fiber laminates, and biocompatible silicone polymers. Single-source vulnerability concentrates in the 12 remaining EU MDR-designated notified bodies. Distribution runs through orthopedic clinic networks for premium tiers and pharmacy chains for volume segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gait-analysis software subscriptions and remote fitting services are expanding faster than hardware sales, creating recurring-revenue attach opportunities that offset MDR compliance cost compression in device manufacturing.
For Market Incumbents: Consolidate fabrication capacity around desktop SLS deployments in Bavaria and North Rhine-Westphalia to defend against same-day fulfillment competitors. Acquire notified body queue positions through strategic partnerships with German orthopedic clinic networks, as 18-month approval bottlenecks freeze product launches for non-compliant entrants. Vertical integration into nylon-12 powder sourcing reduces feedstock cost exposure. For New Entrants and Emerging Players: Differentiate on smartphone plantar scanning applications that bypass traditional podiatrist gatekeepers in Nordic markets with dispersed populations. Target Poland's underserved clinical infrastructure where podiatrist-to-population ratios sit at one-third of German levels. Pursue clinic-partnership distribution models in Warsaw and Kraków rather than competing head-to-head with established German fabrication networks. For Investors and Strategic Acquirers: EU MDR implementation reshapes the acquisition landscape by filtering non-compliant imports and creating protected market space for domestic manufacturers with notified body relationships. Five-to-ten year viability favors mid-cap specialists with backward integration into selective laser sintering equipment and captive clinical referral networks. Watch Poland's podiatrist density as the inflection signal for geographic expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Desktop SLS Fabrication Deployment | German orthopedic clinics compress patient fulfillment from three weeks to four hours, eroding centralized lab margins. |
| Smartphone Scanning Application Launch | Nordic direct-to-consumer platforms bypass six-to-eight-week podiatrist appointment lags in urban catchments. |
| Notified Body Partnership Agreement | Strategic queue positioning accelerates CE marking for gait-analysis software under EU AI Act risk-classification frameworks. |
| Poland Clinic Network Partnership | Underserved podiatrist infrastructure in Warsaw and Kraków creates whitespace for German fabrication expansion. |
| Carbon Fiber Composite Backward Integration | In-house production of rigid laminates secures post-surgical procurement contracts from German rehabilitation centers. |
Research Methodology
A standing panel of orthopedic clinic directors, podiatrists, notified body auditors, and pharmacy chain procurement managers provided ongoing calibration across primary interview cycles. Secondary validation drew from BfArM post-market surveillance databases, EMA MDR implementation reports, German orthopedic association membership directories, and EU AI Act draft guidance documents. Bottom-up patient volume modeling triangulated against top-down spending estimates from national health insurance reimbursement schedules.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled insole type, material grade, application severity, and distribution channel as core segmentation dimensions. CAGRs derived from patient referral trend extrapolation, MDR compliance cost trajectory analysis, and additive manufacturing adoption curve fitting. Forecast inputs incorporated podiatrist density projections, ethylene-vinyl acetate feedstock price bands, and desktop SLS equipment installation rates.
Material uncertainties — notified body capacity constraints, EU AI Act final implementation timing, and carbon fiber aerospace supply competition — sit outside the modeled envelope. Forecasts reflect assumptions about MDR compliance cost pass-through and clinical referral network stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Intracranial Pressure (ICP) Monitoring Devices Market
Medical Devices
Carotid Stents Market
Medical Devices
Middle East and Africa Medical Device Reprocessing Market
Medical Devices
SPG Microstimulator System Market
Medical Devices
Foot Suction Unit Market
Medical Devices
Expandable Interbody Fusion System Market
Medical Devices
Medical Mobility Aid Market
Medical Devices
Chordal Suture Systems Market
Medical Devices
Global Angioplasty Balloons Market
Medical Devices
Foot and Ankle Allograft Market
Medical Devices
Electrical Stimulation Devices (Esds) Market
Medical Devices
Homecare Medical Devices Market
Medical Devices
France Ophthalmic Devices Market
Medical Devices
Knotless Suture Anchors Market
Medical Devices
Organ Care Systems (OCS) Market
Medical Devices
Specimen Retrieval Market