
 Hemoconcentrators Market | 2026-2036
Hemoconcentrators Market Size, Share, and Industry Trends Forecast 2026-2036
Hemoconcentrators Market Analysis
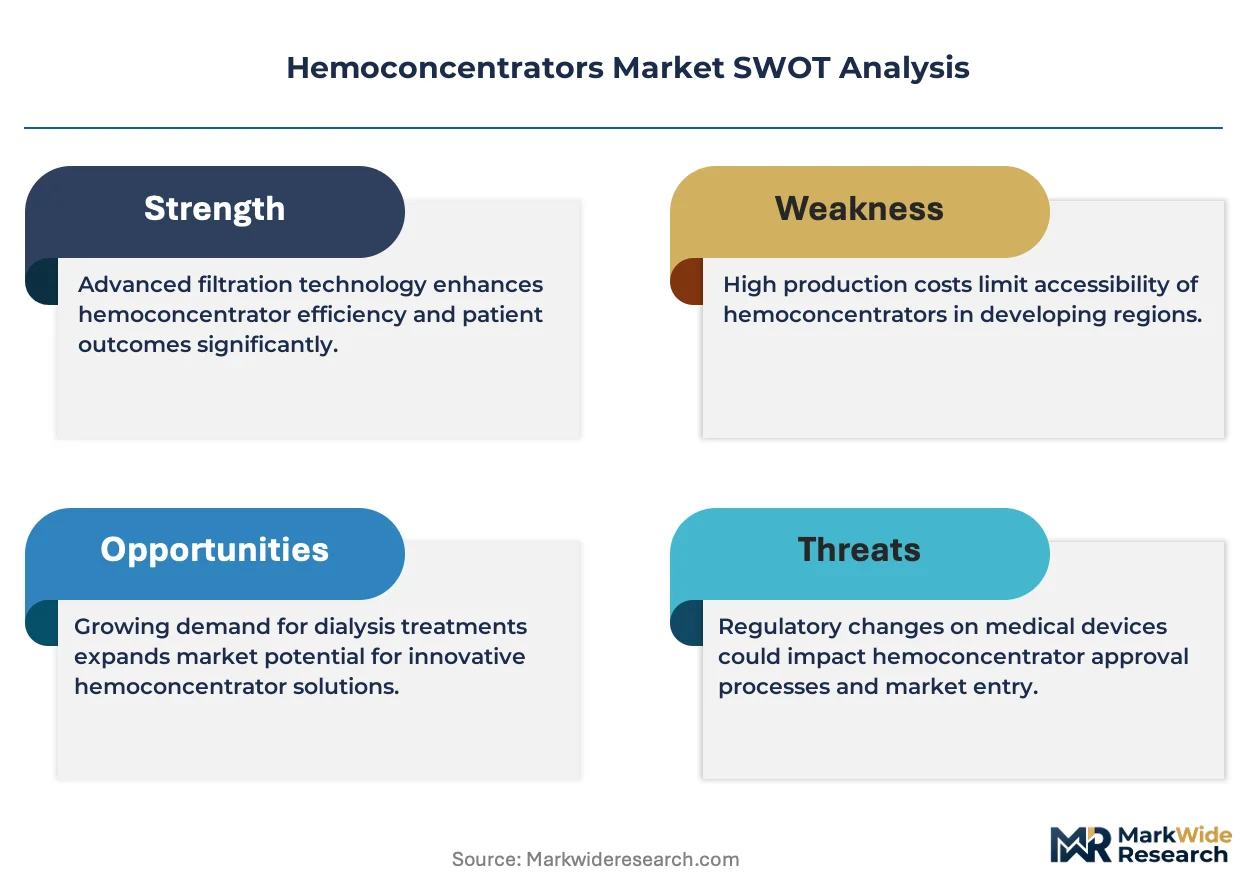
The EU Medical Device Regulation is recalibrating the cost-of-entry calculus for hemoconcentrator manufacturers seeking CE marking in Europe. Getinge AB leverages its integrated perfusion portfolio to sustain competitive positioning across high-volume cardiac centers. LivaNova PLC anchors its presence through specialized extracorporeal technology leadership, while Terumo Cardiovascular Systems Corporation differentiates via manufacturing scale and channel control in North American and Asian markets.
Hemoconcentrators are membrane-based medical devices that remove excess plasma water and concentrate cellular elements during cardiopulmonary bypass, typically employing hollow-fiber polyethersulfone membranes with pore sizes of 0.2–0.6 microns to achieve ultrafiltration rates of 10–50 mL/min at transmembrane pressures below 500 mmHg. Disposable hemoconcentrators dominate procurement volumes due to infection control protocols, while high-performance variants command premium positioning in complex congenital and aortic procedures where superior biocompatibility and solute clearance justify elevated pricing. Hospitals represent the primary end-user channel, though dialysis centers are expanding utilization for intra-dialytic fluid management applications.
FDA 510(k) clearance requirements, the EU MDR conformity assessment framework, and Japan's PMDA pharmaceutical and medical device regulations collectively shape product development timelines and market access pathways for hemoconcentrator manufacturers. ISO 10993 biocompatibility testing and hemocompatibility standards further constrain material selection and validation protocols, elevating R&D expenditure for new market entrants. Stakeholders must monitor evolving notified body capacity constraints in Europe and alignment of clinical evidence requirements across FDA and PMDA jurisdictions to optimize regulatory investment sequencing.
Market Dynamics
Cardiac surgery volume concentration in tertiary referral centers is compressing procurement cycles and consolidating purchasing power, forcing manufacturers to reconfigure their sales coverage models around high-throughput hospital clusters rather than dispersed community facilities.
Growth Catalysts
- EU MDR compliance deadlines:Stricter biocompatibility documentation requirements under the Medical Device Regulation are accelerating replacement demand for older hemoconcentrator models lacking updated clinical evidence packages.
- Congenital heart procedure expansion:Pediatric cardiac centers in the United States and Germany are scaling complex neonatal bypass programs that require premium ultrafiltration performance.
- Hollow-fiber membrane advances:Polyethersulfone surface modifications with heparin coatings are reducing complement activation and expanding device utilization in prolonged perfusion cases.
Market Restraints
- Polymer feedstock volatility:Specialized medical-grade polysulfone and polyethersulfone resins face supply tightness from limited European and Japanese chemical producers, squeezing gross margins.
- Notified body capacity constraints:EU MDR transition has created bottlenecks at designated conformity assessment organizations, extending CE marking timelines by 12-18 months for new entrants.
- Peritoneal dialysis substitution:Advances in continuous ambulatory peritoneal dialysis systems are reducing occasional hemoconcentrator use in select fluid management applications.
Strategic Opportunities
- Japanese cardiac surgery modernization:PMDA streamlining of medical device approval pathways is opening access for manufacturers with existing FDA 510(k) clearances to enter Asia's second-largest perfusion market.
- Dialysis center channel expansion:Outpatient renal care facilities are adopting hemoconcentrators for intra-dialytic volume management, creating a parallel demand stream outside hospital cardiac suites.
- ISO 10993-4 hemocompatibility harmonization:Emerging alignment between FDA, PMDA, and EU notified bodies on thrombogenicity testing standards is reducing redundant validation costs for multi-regional product launches.
Industry Challenges
- Perfusionist workforce scarcity:Specialized extracorporeal technologist training programs in the United States and Germany are failing to match retirement rates, constraining procedure volume growth and device utilization.
- Legacy sterilization validation:Transition from ethylene oxide to low-temperature hydrogen peroxide sterilization methods requires complete requalification of membrane integrity and fiber potting adhesion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemoconcentrators Market |
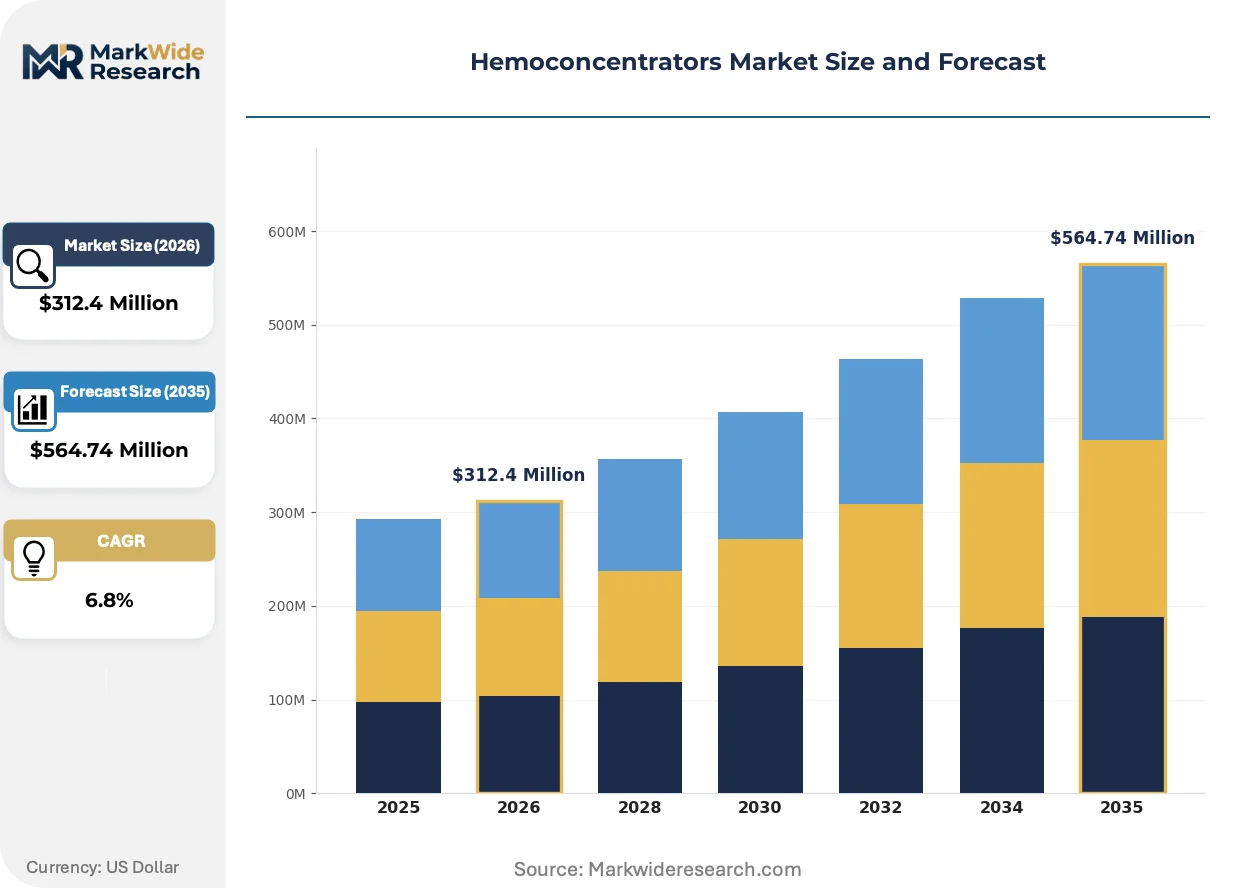
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Hemoconcentrators, High-Performance Hemoconcentrators, Disposable Hemoconcentrators, Continuous Hemoconcentrators End User: Hospitals, Dialysis Centers, Research Laboratories, Homecare Providers Material: Polyethersulfone, Polypropylene, Silicone, Polyvinyl Chloride Application: Blood Purification, Fluid Removal, Solute Concentration, Dialysis |
| Companies Covered | Getinge AB, Andocor, LivaNova PLC, Maquet, Nipro, Terumo Cardiovascular Systems Corporation, Medica S.p.A, Braile Biomédica, MEDIVATORS Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemoconcentrators Market Emerging Trajectories
Membrane surface engineering and regulatory data science are converging to redefine performance benchmarks and market access velocity. Device architecture is evolving toward integrated sensor compatibility, while procurement patterns are consolidating around outcome-linked supply agreements.
Surface-modified polyethersulfone membranes with covalently bound heparin coatings are reducing platelet adhesion and extending safe perfusion duration. Pediatric cardiac centers and aortic surgery programs are adopting these variants for complex procedures exceeding four hours. The technology is electrifying competitive positioning around biocompatibility metrics rather than raw ultrafiltration capacity.
EU MDR Article 10 technical documentation requirements are mandating systematic clinical evaluation reports with post-market surveillance integration. Manufacturers must maintain electronic systems for traceability and periodic safety updates. High-volume cardiac centers in Germany and the Netherlands are now prioritizing suppliers with established European authorized representatives and robust quality management systems.
Hospital purchasing cooperatives are consolidating hemoconcentrator procurement with broader perfusion circuit contracts, bundling disposable oxygenators, arterial filters, and tubing sets. Independent cardiac surgery centers are losing negotiating leverage as integrated delivery networks capture volume discounts. This concentration is most pronounced in the United States, where Catholic health systems and for-profit chains dominate tertiary cardiac service lines.
Hemoconcentrators Market Segmentation
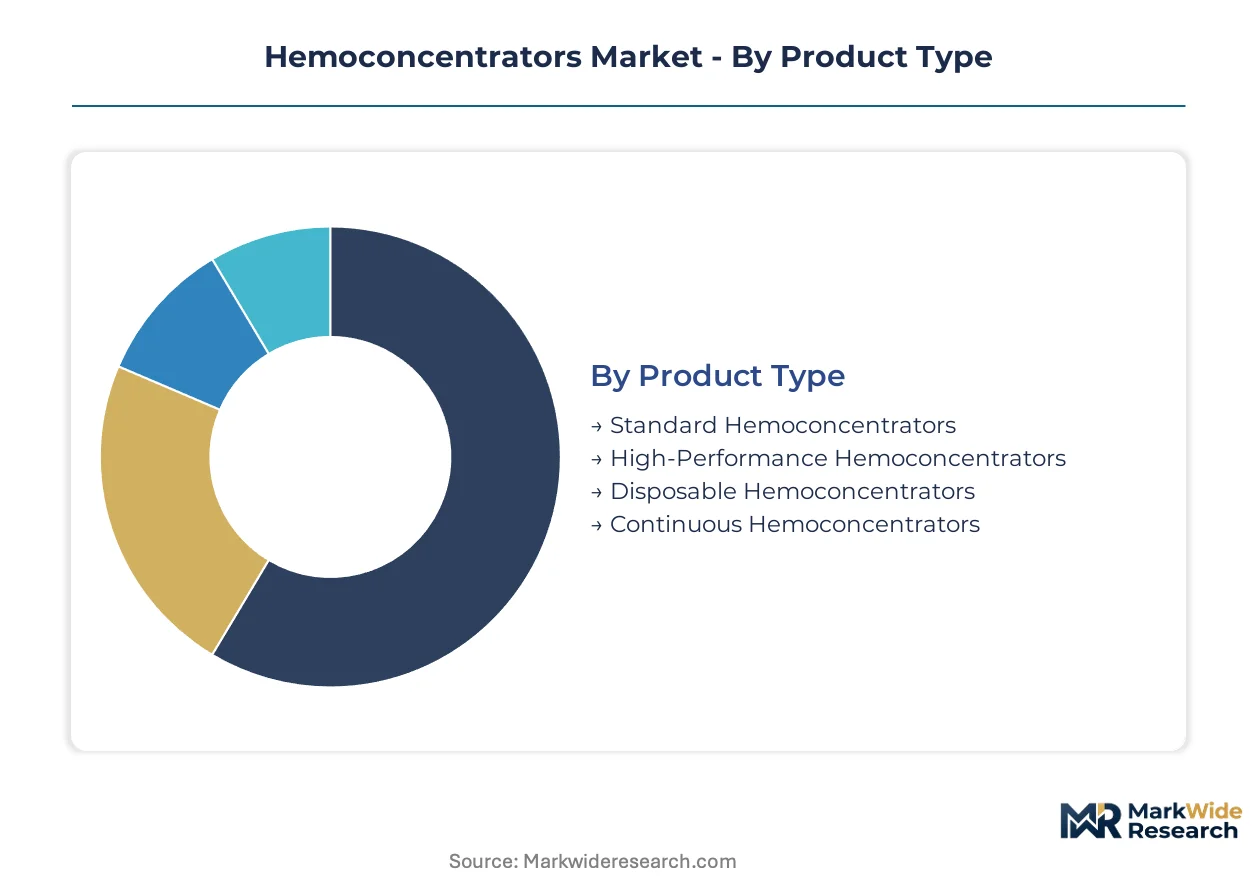
Hemoconcentrator procurement patterns diverge sharply across clinical settings and performance tiers. Material specifications and sterilization compatibility constrain cross-segment substitution, locking manufacturers into discrete product architectures.
Product Type:
Membrane surface engineering and ultrafiltration capacity separate commercial positioning across the four product architectures.
- Standard Hemoconcentrators:Hollow-fiber polyethersulfone configurations deliver 10-30 mL/min ultrafiltration rates for routine cardiopulmonary bypass under four hours. Community hospital cardiac programs in the United States and Germany concentrate procurement here, constrained by budget ceilings and lower procedure complexity.
- High-Performance Hemoconcentrators:Surface-modified membranes with heparin coatings achieve 30-50 mL/min rates with reduced complement activation. Tertiary congenital heart centers and aortic surgery programs in Japan and the United States absorb premium pricing for perfusion durations exceeding four hours.
- Disposable Hemoconcentrators:Single-use sterilized units dominate infection control protocols across European cardiac centers.
- Continuous Hemoconcentrators:Extended-duration designs serve prolonged extracorporeal membrane oxygenation circuits in specialized intensive care units.
Mature deployment sits with Standard Hemoconcentrators. Newer deployment is concentrated in High-Performance variants.
End User:
Channel economics and clinical workflow integration determine purchasing authority and contract structure.
- Hospitals:Tertiary cardiac centers command integrated perfusion circuit contracts bundling oxygenators, filters, and tubing sets. Catholic health systems and for-profit chains in the United States leverage volume concentration for price tier separation across premium and standard device grades.
- Dialysis Centers:Outpatient renal facilities adopt hemoconcentrators for intra-dialytic fluid management, creating parallel demand outside cardiac suites. German and Japanese dialysis networks are expanding utilization fastest.
- Research Laboratories:Academic medical centers validate membrane biocompatibility under ISO 10993 protocols.
- Homecare Providers:Limited penetration reflects perfusionist supervision requirements and device complexity.
Procurement authority concentrates in Hospitals. Volume expansion is climbing the fastest in Dialysis Centers.
Material:
Polymer selection governs hemocompatibility, sterilization tolerance, and regulatory validation burden.
- Polyethersulfone:Dominant membrane material with 0.2-0.6 micron pore structures enabling precise ultrafiltration control. Japanese and German manufacturers source medical-grade resin from limited European and Japanese chemical producers, exposing supply chains to feedstock volatility.
- Polypropylene:Housing and potting applications benefit from thermal stability during steam sterilization cycles.
- Silicone:Gasket and sealing components require specialized platinum-cured formulations for blood contact.
- Polyvinyl Chloride:Tubing connectors face regulatory pressure from phthalate plasticizer restrictions under EU REACH.
Volume concentration rests with Polyethersulfone. Regulatory scrutiny is intensifying around Polyvinyl Chloride.
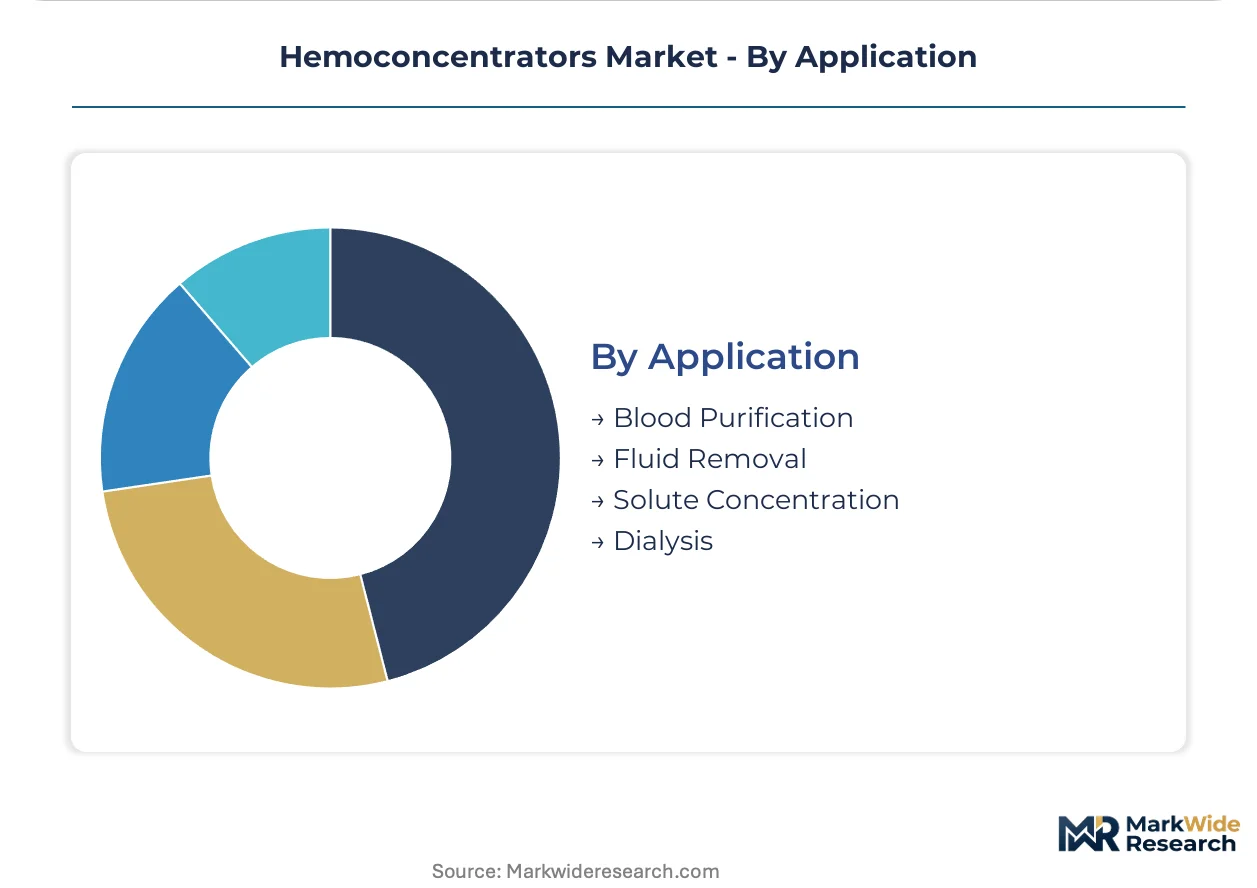
Application:
Clinical indication specificity drives device specification and reimbursement coding.
- Blood Purification:Intraoperative removal of inflammatory mediators and activated complement factors during cardiopulmonary bypass. Complex congenital procedures in the United States and Germany absorb premium device configurations.
- Fluid Removal:Ultrafiltration of excess plasma water to optimize hematocrit and reduce allogeneic transfusion exposure.
- Solute Concentration:Preservation of cellular elements while clearing low-molecular-weight solutes.
- Dialysis:Adjunctive hemoconcentration during intermittent hemodialysis sessions.
Established utilization centers on Blood Purification. Emerging uptake is gaining share fastest in Fluid Removal applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized economic zones for medical device manufacturing in Ireland and Singapore are concentrating hemoconcentrator production capacity near major cardiac surgery clusters. Tax-advantaged status and streamlined regulatory pathways in these jurisdictions attract capital investment from perfusion technology suppliers. Proximity to high-volume hospital networks reduces logistics costs for single-use sterile devices.
United States
Tertiary cardiac centers in Cleveland, Houston, and Boston drive demand for high-performance hemoconcentrators in complex congenital procedures. FDA 510(k) clearance pathways shape product development timelines for manufacturers targeting American hospitals. Catholic health systems and for-profit chains consolidate purchasing power through integrated delivery networks across the Midwest and Southeast.
Germany
The EU Medical Device Regulation accelerates replacement demand as hospitals retire legacy devices lacking updated clinical evidence packages. Notified body capacity constraints in Berlin and Munich extend CE marking timelines for new market entrants. The Bavarian medical technology corridor anchors production of polyethersulfone membrane components for European and Asian markets.
Japan
PMDA streamlining of approval pathways opens access for manufacturers with existing FDA clearances to enter Asia's second-largest perfusion market. Pediatric cardiac centers in Tokyo and Osaka scale complex neonatal bypass programs requiring premium ultrafiltration performance. Domestic chemical producers in the Kansai region supply medical-grade polysulfone resins with limited import substitution.
Netherlands
High-volume cardiac centers in Amsterdam and Rotterdam prioritize suppliers with established European authorized representatives under EU MDR Article 10 requirements. The Eindhoven medical technology cluster hosts contract manufacturers specializing in hollow-fiber membrane potting and sterilization validation. Dutch hospital purchasing cooperatives bundle hemoconcentrators with broader perfusion circuit contracts.
Hemoconcentrators Market Vendor Landscape
North American producers anchor the premium-tier segment; European specialists hold regulatory compliance advantages under EU MDR. The vendor base concentrates around integrated perfusion portfolio providers and standalone membrane technology firms. Three archetypes dominate: diversified medical technology conglomerates with cardiac surgery divisions, pure-play extracorporeal device manufacturers, and contract sterilization and packaging specialists. Competitive moves center on backward integration into polymer resin sourcing and geographic expansion through authorized representative networks.
Among diversified technology holding companies, Getinge AB and LivaNova PLC exemplify integrated portfolio strategies spanning oxygenators, arterial filters, and hemoconcentrator modules. Terumo Cardiovascular Systems Corporation occupies a position as a scale-driven manufacturer with channel control across North American and Asian hospital networks. These three anchors represent distinct competitive vectors: European regulatory depth, American volume concentration, and Japanese manufacturing precision.
| Leading Market Players |
|---|
| Getinge AB |
| Andocor |
| LivaNova PLC |
| Maquet |
| Nipro |
| Terumo Cardiovascular Systems Corporation |
| Medica S.p.A |
| Braile Biomédica |
| MEDIVATORS Inc. |
| Others |
Supply Flow & Price Mechanics
Performance-tier bifurcation between heparin-coated high-performance modules and standard hollow-fiber configurations splits procurement economics across German and Japanese cardiac centers, with premium variants commanding sustained margin premiums while commodity-grade devices face cost compression from polymer feedstock volatility and consolidated hospital purchasing power.
Pricing Analysis
Lead-time-driven pricing stratification rewards manufacturers with FDA 510(k) and PMDA pre-clearance stockholding, enabling spot premiums for urgent cardiac surgery schedules while contract-based long-term offtake agreements with Catholic health systems and for-profit chains secure volume discounts. Price differentiation hinges on ISO 10993-4 hemocompatibility certification tier and heparin surface modification complexity. Pricing pressure stems from EU MDR compliance cost pass-through requirements. Community hospital cardiac programs exhibit highest price sensitivity; tertiary congenital centers absorb premium positioning.
Supply Chain Analysis
Dual-sourcing mandates from high-volume cardiac centers in the United States and Germany require qualified backup suppliers for medical-grade polyethersulfone resin, compelling manufacturers to maintain parallel relationships with European and Japanese chemical producers. Raw material dependencies center on specialized polysulfone resins, platinum-cured silicone gaskets, and hollow-fiber spinning equipment. Single-source vulnerability concentrates in the Kansai region's domestic resin supply. Distribution runs through sterile device logistics networks anchored near tertiary hospital clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hemoconcentrator sector is accelerating into a vertical-integration race where captive control over medical-grade polyethersulfone resin supply and heparin coating chemistry represents the decisive margin lever.
For Market Incumbents: Anticipate EU MDR notified body capacity constraints extending CE marking timelines for challengers by securing European authorized representative infrastructure and pre-positioning clinical evaluation report documentation. Backward integration into polymer resin sourcing defends margin position against feedstock volatility from limited Japanese and European chemical producers. Prioritize heparin surface modification R&D to sustain premium-tier pricing power against standard-device commoditization. For New Entrants and Emerging Players: Dialysis center procurement managers outside traditional cardiac surgery suites represent an underserved buyer archetype with lower regulatory entry barriers and fragmented purchasing authority compared to hospital GPO contracts. Japanese PMDA streamlining creates the most penetrable geography for manufacturers holding existing FDA 510(k) clearances. Pursue software companion development for integrated sensor-compatible hemoconcentrator architectures as the go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with membrane technology specialists possessing ISO 10993-4 validation capabilities and established European authorized representative networks given EU MDR compliance deadline acceleration. Long-term viability over the next decade favors targets with dual FDA-PMDA clearance pathways and heparin coating intellectual property. Monitor notified body capacity expansion announcements as the inflection signal for new entrant threat intensity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10 technical documentation accelerates replacement demand from legacy device retirement. |
| Hospital System Partnership | Integrated delivery network contracts with Catholic health systems consolidate purchasing power across Midwest cardiac centers. |
| Backward Integration | Captive polyethersulfone resin supply from Bavarian chemical corridors insulates margins from Japanese feedstock volatility. |
| Software Companion Development | Sensor-compatible hemoconcentrator architectures enable real-time ultrafiltration monitoring in prolonged ECMO circuits. |
| Reimbursement Strategy | Dialysis center channel expansion requires distinct coding alignment for intra-dialytic fluid management applications. |
Methodological Framework
FDA 510(k) filings, PMDA approval databases, and EU MDR notified body registration records formed the secondary backbone, cross-referenced with primary interviews involving perfusionists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers across Cleveland, Houston, Boston, and Tokyo cardiac centers. Bottom-up and top-down triangulation validated segment-level demand estimates against polymer resin import data and hospital procedure volume disclosures.
Bottom-up modeling anchored volume projections to installed base of cardiopulmonary bypass machines and replacement cycle frequencies, while top-down analysis calibrated value estimates against disclosed perfusion circuit contract values from integrated delivery networks. Segmentation dimensions spanned product performance tier, end-user channel, membrane material specification, and regional regulatory cluster. CAGRs derived from slope-intercept analysis of historical replacement demand and projected congenital procedure expansion. Industry-specific inputs incorporated perfusionist workforce retirement rates and EU MDR transition timelines.
Revisions become necessary when notified body capacity constraints intensify beyond current 12-18 month CE marking delays, polymer feedstock supply tightens from European chemical producer consolidation, or peritoneal dialysis substitution accelerates in fluid management applications. Deviation in PMDA approval pathway streamlining velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Pelvic Floor Electric Stimulator Market
Medical Devices
Global High-Flow Nasal Cannula Market
Medical Devices
Global Digital Therapeutic Devices Market
Medical Devices
Infant Radiant Warmer Market
Medical Devices
Global Interspinous Spacers Market
Medical Devices
Europe Organ Preservation Market
Medical Devices
Radiotherapy Devices Market
Medical Devices
Skull Clamp Market
Medical Devices
Extended Wear Contact Lens Market
Medical Devices
Electrocautery Devices Market
Medical Devices
Cochlear Implant Systems Market
Medical Devices
Photorejuvenation Devices Market
Medical Devices
Global Ileostomy Market
Medical Devices
Venous Procedure Devices Market
Medical Devices
Asia-Pacific Medical Device Market
Medical Devices
Global Medical Devices Market