
 Europe Orthopedic Devices Market | 2026-2036
Europe Orthopedic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Orthopedic Devices Market Insights
The EU Medical Device Regulation is realigning the cost-of-entry calculus for orthopedic device manufacturers across Europe, forcing substantial investments in clinical data generation and notified body relationships. Stryker Corporation leverages its established European infrastructure to sustain market access under tightened conformity assessment procedures. Zimmer Biomet Holdings Inc. anchors its competitive position through specialized expertise in hip and knee reconstruction systems that meet elevated biocompatibility testing standards.
Orthopedic devices encompass implantable prostheses, fixation hardware, surgical instrumentation, and patient-specific instruments engineered from titanium alloys, cobalt-chrome, and ultra-high molecular weight polyethylene to restore musculoskeletal function. These devices serve primary industrial purposes in joint reconstruction, fracture management, and spinal correction, with functional parameters governed by ISO 5832 material standards and fatigue testing protocols. Implants capture the dominant value share within product type categories, while robotics-assisted platforms represent the fastest-expanding technology segment as hospitals prioritize surgical precision and reproducible outcomes. Joint reconstruction applications command the deepest margin pools, though spine surgery platforms are gaining traction through minimally invasive approaches that reduce hospitalization duration.
EMA coordination with national competent authorities and the EU Medical Device Regulation framework shape product standards, post-market surveillance obligations, and market access pathways across member states. CE marking requirements under the MDR extend clinical evaluation demands, favoring manufacturers with substantial regulatory affairs capabilities and European-based quality management systems. Stakeholders must monitor notified body capacity constraints and evolving harmonized standards that will determine which product portfolios achieve sustained commercial viability.
Market Dynamics
The EU Medical Device Regulation is compressing market access timelines while simultaneously elevating clinical evidence burdens, forcing orthopedic manufacturers to restructure regulatory affairs capabilities and notified body relationships across member states.
Growth Catalysts
- MDR Clinical Evidence Requirements:Elevated biocompatibility testing standards under the EU Medical Device Regulation favor established manufacturers with European-based quality management systems, consolidating procurement decisions toward certified suppliers.
- German Surgical Volume Expansion:Rising joint reconstruction procedures at university hospitals in Germany amplify demand for precision instrumentation and robotics-compatible implant platforms.
- Titanium Alloy Innovation:Advanced additive manufacturing of porous titanium structures is improving osseointegration performance, accelerating adoption in hip and knee reconstruction applications.
Market Restraints
- Cobalt-Chrome Supply Concentration:European orthopedic manufacturers face input cost volatility from concentrated cobalt sourcing, with refining capacity concentrated outside the region creating price instability.
- Notified Body Capacity Constraints:Limited designation of notified bodies under MDR Article 35 extends certification timelines, delaying product launches and freezing capital in development pipelines.
- Polyethylene Wear Limitations:Conventional ultra-high molecular weight polyethylene exhibits oxidative degradation in long-term implant applications, constraining product lifecycle claims and revision surgery economics.
Strategic Opportunities
- Eastern European Hospital Modernization:Poland and Romania present underpenetrated demand for spinal fixation systems as national health systems upgrade surgical infrastructure.
- Patient-Specific Instrument Convergence:Integration of 3D printing with preoperative planning software enables customized cutting guides, reducing operative time and implant positioning errors.
- France Centralized Procurement Tailwinds:Regional hospital group purchasing organizations favor suppliers with comprehensive quality documentation, creating access advantages for MDR-compliant portfolios.
Industry Challenges
- Regulatory Affairs Talent Scarcity:MDR technical documentation and post-market surveillance requirements exceed current workforce capabilities, with experienced regulatory professionals commanding premium compensation.
- Robotics Platform Integration Complexity:Surgical navigation systems require specialized training protocols and maintenance infrastructure, creating adoption friction at mid-sized orthopedic centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Orthopedic Devices Market |
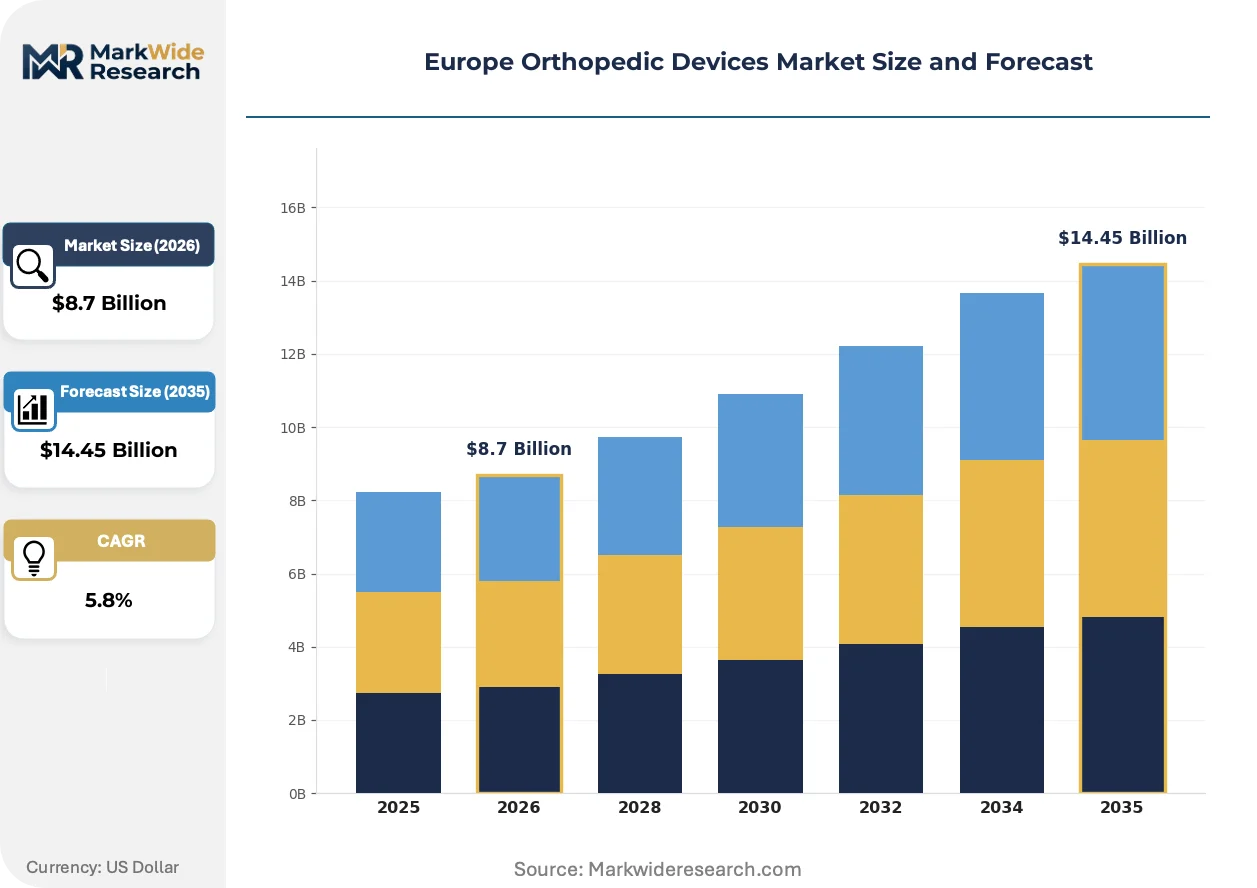
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
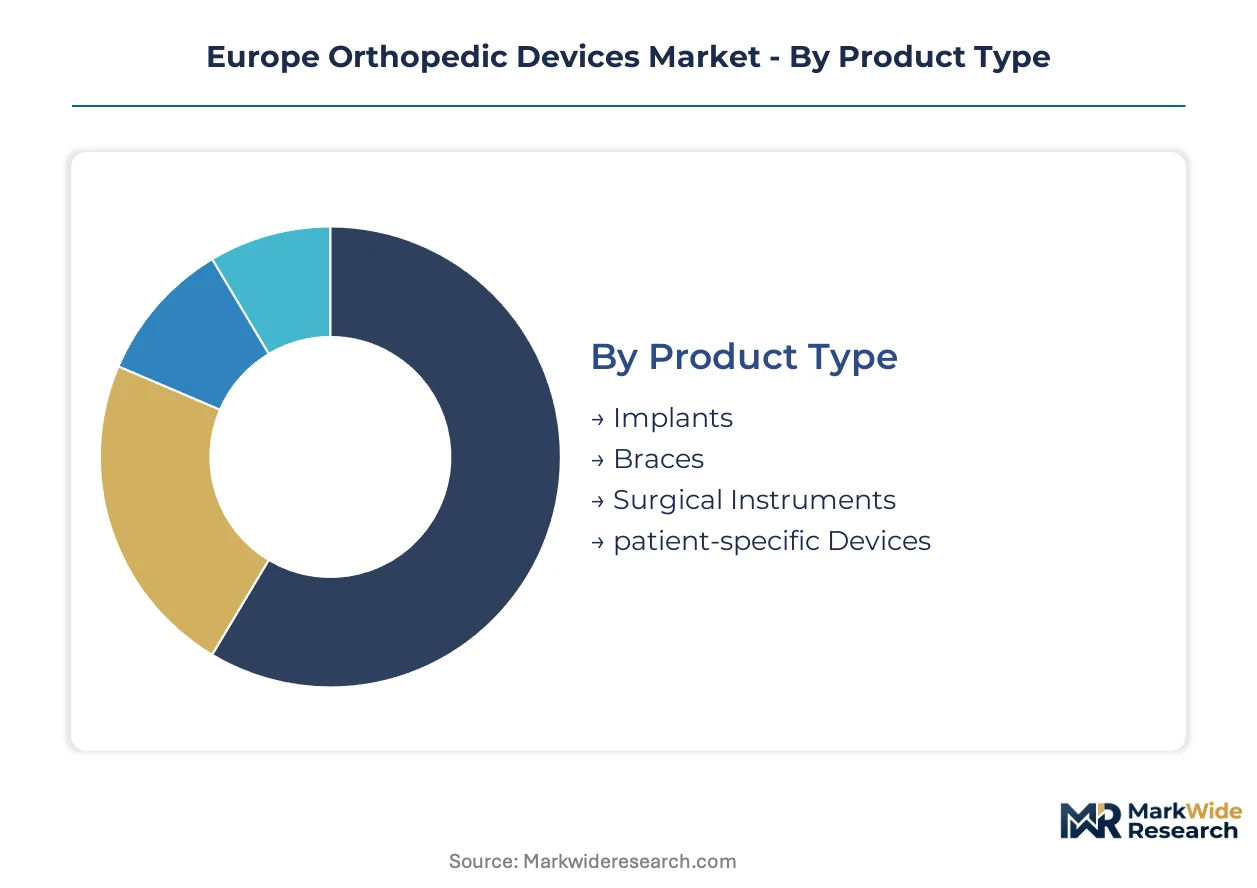
| Segmentation | Product Type: Implants, Braces, Surgical Instruments, patient-specific Devices Application: Joint Reconstruction, Trauma, Spine Surgery, Sports Injury End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Home Care Technology: Robotics, Biologics, Minimally Invasive Surgery, Hybrid Devices |
| Companies Covered | Smith & Nephew plc, B. Braun SE, Zimmer Biomet Holdings Inc., Globus Medical Inc., Arthrex Inc., Stryker Corporation, Medtronic plc, NuVasive Inc., DePuy Synthes (Johnson & Johnson), Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Orthopedic Devices Market Trends and Innovations
Orthopedic device development is converging on precision personalization and regulatory compliance automation, with manufacturers restructuring R&D priorities around modular platform architectures and evidence-generation capabilities.
Robotics-assisted surgical platforms is modularizing across European hospital networks. These systems integrate optical tracking with haptic feedback to enable reproducible bone preparation. German and French academic medical centers are deploying these platforms at accelerating cadence. The technology is modularizing capital expenditure models, allowing hospitals to upgrade software and instrument sets without full system replacement.
EU Medical Device Regulation post-market surveillance mandates are restructuring clinical data obligations for implant manufacturers. The regulation requires systematic literature reviews and periodic safety update reports across product lifecycles. Joint reconstruction portfolios face the steepest compliance burdens due to long-term implant survival data requirements. Manufacturers are responding by establishing European-based clinical affairs teams and registry participation frameworks.
Hospital procurement consortia are consolidating orthopedic device purchasing across regional health systems. France's regional hospital agencies and England's NHS Supply Chain are aggregating demand and standardizing supplier qualification criteria. This concentration is displacing traditional distributor relationships with direct manufacturer contracting. The United Kingdom exhibits the most advanced consolidation, with specialized orthopedic frameworks replacing product-by-product tenders.
Europe Orthopedic Devices Market Segmentation
Orthopedic device procurement in Europe diverges sharply by clinical setting and reimbursement pathway. Understanding these segment boundaries clarifies where MDR compliance investments yield access advantages versus where price sensitivity dominates purchasing decisions.
Product Type:
Cost tier differentiation separates capital-intensive implantable systems from consumable support products.
- Implants:Titanium alloy and cobalt-chrome prostheses engineered to ISO 5832 fatigue standards command premium pricing through long-term survival data requirements. German university hospitals concentrate demand for robotics-compatible implant platforms as surgical volumes expand.
- Surgical Instruments:Reusable and single-use cutting guides, reamers, and alignment tools designed for specific implant systems. French regional hospital agencies favor instrument sets bundled with comprehensive quality documentation under centralized procurement frameworks.
- Braces:External stabilization devices ranging from rigid fracture management to soft-tissue support systems.
- Patient-Specific Devices:Custom cutting guides and anatomical models derived from preoperative imaging.
Implants lead volumes today; patient-specific devices are gaining share fastest.
Application:
Procedure complexity and revision economics determine margin structure across clinical indications.
- Joint Reconstruction:Hip and knee arthroplasty systems generate the deepest margin pools through long implant lifecycles and recurring revision procedures. United Kingdom NHS Supply Chain consolidation is standardizing supplier qualification criteria toward established MDR-compliant portfolios.
- Spine Surgery:Pedicle screw systems, interbody cages, and minimally invasive access platforms. Poland and Romania present underpenetrated demand as national health systems upgrade surgical infrastructure for degenerative disc treatment.
- Trauma:Fracture fixation plates, intramedullary nails, and external fixation hardware for acute injury management.
- Sports Injury:Soft-tissue repair anchors, meniscal repair systems, and ligament reconstruction grafts.
Joint reconstruction dominates revenue capture; spine surgery shows the steepest expansion trajectory.
End User:
Capital availability and regulatory sophistication separate institutional purchasers from distributed care settings.
- Hospitals:Acute care facilities with robotics infrastructure and specialized orthopedic departments. England's NHS Supply Chain and France's regional hospital agencies are aggregating demand and displacing traditional distributor relationships with direct manufacturer contracting.
- Orthopedic Clinics:Specialized ambulatory surgical centers performing high-volume joint procedures. These settings concentrate demand for streamlined instrument sets and rapid sterilization turnaround protocols.
- Rehabilitation Centers:Post-acute facilities managing recovery protocols and brace fitting.
- Home Care:Patient-managed mobility aids and continuous passive motion devices.
Hospitals anchor procurement volume; orthopedic clinics are expanding their share fastest.
Technology:
Integration burden and training requirements create adoption friction that favors specific customer profiles.
- Robotics:Optical tracking platforms with haptic feedback enabling reproducible bone preparation. German and French academic medical centers are deploying these systems at accelerating cadence through modular capital expenditure models.
- Minimally Invasive Surgery:Reduced-port access systems and specialized retractors that shorten hospitalization duration. United Kingdom hospitals prioritize these approaches to meet NHS waiting list reduction targets.
- Biologics:Bone graft substitutes, growth factor carriers, and cellular therapies for enhanced healing.
- Hybrid Devices:Implant systems incorporating drug-eluting or sensor-enabled components.
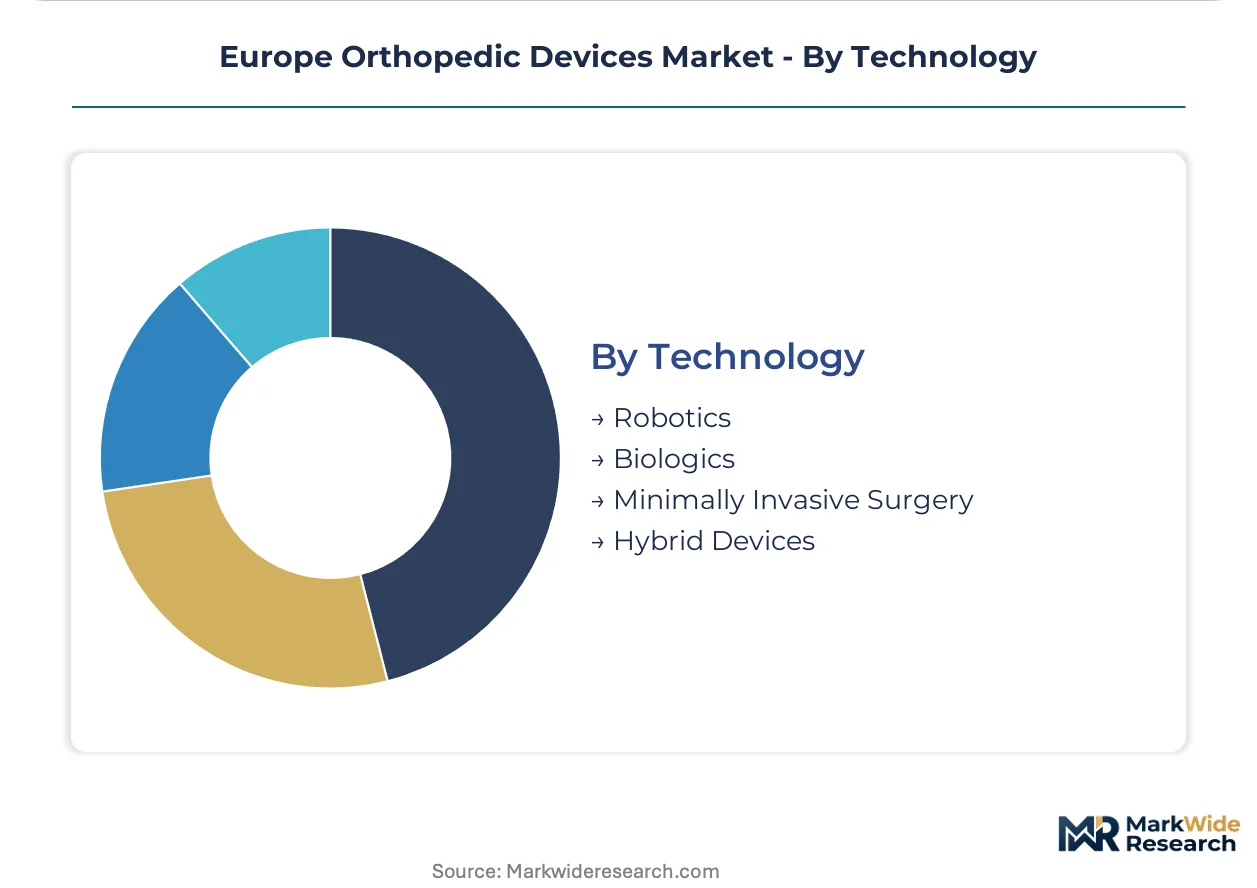
Robotics leads technology investment; minimally invasive surgery is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized orthopedic surgical talent clusters in German university hospitals and French academic medical centers anchor European demand generation for advanced implant platforms and robotics-assisted systems.
Germany
Rising joint reconstruction volumes at Charité Berlin and Heidelberg University Hospital drive demand for precision instrumentation and titanium alloy implants. The EU Medical Device Regulation extends certification timelines through notified body capacity constraints. Bavaria's medical technology corridor around Munich concentrates additive manufacturing facilities producing porous titanium structures for hip and knee applications.
United Kingdom
NHS Supply Chain consolidation aggregates orthopedic device purchasing across England's regional hospital networks. The Medicines and Healthcare products Regulatory Agency enforces post-market surveillance obligations under MDR equivalence arrangements. London and the Southeast anchor specialized orthopedic centers deploying minimally invasive spine surgery platforms to reduce hospitalization duration.
France
Regional hospital agencies in Île-de-France and Auvergne-Rhône-Alpes standardize supplier qualification toward MDR-compliant portfolios. ANSM coordinates with EMA on clinical evidence requirements for long-term implant survival data. The Lyon-Grenoble medical device cluster houses quality management systems serving centralized procurement frameworks.
Poland
National health system infrastructure upgrades generate underpenetrated demand for spinal fixation systems and degenerative disc treatment platforms. The Polish Office for Registration of Medicinal Products aligns device certification with EU MDR transitional provisions. Warsaw and Krakow academic hospitals are modernizing surgical departments to accommodate robotics-compatible implant platforms.
Switzerland
Swissmedic maintains autonomous device regulation while recognizing CE marking through bilateral agreements with the EU. Basel and Zurich concentrate precision manufacturing of cobalt-chrome components and surgical instrumentation. The country's orthopedic research institutes collaborate with German university hospitals on biocompatibility testing protocols.
Europe Orthopedic Devices Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with established European regulatory affairs infrastructure. Market access under MDR Article 35 notified body requirements favors manufacturers with substantial clinical data generation capabilities and European-based quality management systems. Two strategic archetypes dominate: integrated implant-surgical system providers and specialized robotics platform developers. Competitive moves concentrate on MDR compliance investments and strategic partnerships with academic medical centers for clinical evidence development.
Among diversified orthopedic technology providers, Stryker Corporation and Zimmer Biomet Holdings Inc. exemplify the integrated implant-surgical system archetype, while Smith & Nephew plc occupies a position within specialized wound and extremities segments. These companies represent varying approaches to MDR technical documentation and post-market surveillance obligations.
| Leading Market Players |
|---|
| Smith & Nephew plc |
| B. Braun SE |
| Zimmer Biomet Holdings Inc. |
| Globus Medical Inc. |
| Arthrex Inc. |
| Stryker Corporation |
| Medtronic plc |
| NuVasive Inc. |
| DePuy Synthes (Johnson & Johnson) |
| Others |
Pricing and Supply Chain Analysis
MDR certification grade bifurcation separates CE-marked implant portfolios from non-compliant inventory, concentrating procurement decisions toward suppliers with European-based quality management systems while compressing margins for distributors caught between notified body delays and hospital consolidation.
Pricing Analysis
Bundled service contracts dominate German university hospital procurement, with robotics-compatible implant platforms commanding premium positioning through long-term survival data and maintenance-inclusive pricing. Price differentiation rests on ISO 5832 material certification tier and after-sales technical support depth. Cost compression in standard titanium alloy hip and knee systems intensifies as French regional hospital agencies aggregate demand through centralized frameworks. Orthopedic clinics exhibit the sharpest price sensitivity, while academic medical centers prioritize clinical evidence over unit economics.
Supply Chain Analysis
Dual-sourcing mandates from England's NHS Supply Chain and French regional hospital agencies require manufacturers to qualify secondary cobalt-chrome and titanium alloy suppliers, extending procurement timelines but reducing single-source vulnerability. Raw material dependencies center on German additive manufacturing facilities for porous titanium structures, Swiss precision machining for surgical instrumentation, and Belgian refining for cobalt-chrome feedstock. Tariff exposure on non-EU cobalt concentrates creates input cost volatility. Distribution runs through direct manufacturer contracting with hospital procurement consortia, displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe orthopedic devices market functions as a stable compounder, with aging demographics and surgical volume expansion at German university hospitals generating predictable demand trajectories regardless of cyclical pressures.
For Market Incumbents: Extend MDR technical documentation capabilities and notified body relationships to defend access advantages as certification timelines compress competitive windows. Deepen backward integration into titanium alloy additive manufacturing around Munich and Bavaria to secure supply continuity against cobalt-chrome price volatility. Anchor positioning through long-term framework agreements with France's regional hospital agencies and England's NHS Supply Chain. For New Entrants and Emerging Players: Mid-sized orthopedic clinics in Poland and Romania present the most penetrable buyer archetype, with underinvested surgical infrastructure and limited robotics adoption creating white-space for streamlined instrument sets and rapid sterilization protocols. Target spinal fixation systems in Warsaw and Krakow academic hospitals modernizing degenerative disc treatment capabilities. Pursue direct contracting with national health system procurement offices rather than distributor intermediaries. For Investors and Strategic Acquirers: Consolidation pressure builds where MDR compliance investments exceed mid-cap balance sheet capacity, creating acquisition opportunities for specialized robotics platform developers and patient-specific instrument manufacturers with established European quality management systems. Prioritize targets with ANSM or MHRA regulatory relationships and existing CE marking pathways. Watch notified body designation expansion as the inflection signal for accelerated product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Article 35 compliance secures market access across German and French hospital networks. |
| Hospital System Partnership | Framework agreements with NHS Supply Chain displace distributor relationships and lock in volume. |
| Backward Integration | In-house additive manufacturing of porous titanium reduces cobalt-chrome supply exposure. |
| Software Companion Development | Preoperative planning integration enables patient-specific instrument customization at French academic centers. |
| Reimbursement Strategy | Long-term implant survival data alignment with ANSM requirements supports premium positioning. |
Research Methodology
Coverage spans Western Europe, Central Europe, and the United Kingdom, with primary inputs from each territory combined with secondary validation. Interviews with orthopedic surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers informed demand-side dynamics. Secondary sources included EMA MDR guidance documents, ANSM periodic safety update reports, NHS Supply Chain procurement databases, and ISO 5832 harmonized standards. Bottom-up surgical volume modeling and top-down manufacturer revenue analysis were triangulated to derive market sizing.
Rate-of-change decomposition across the projection horizon separated volume growth from price-mix effects. Segmentation dimensions modeled include product type, application, end user, and technology tier. CAGRs were derived from surgical procedure forecasts, implant penetration rates, and robotics platform adoption curves. Forecast inputs incorporated German university hospital expansion plans, French regional hospital agency procurement frameworks, and Polish national health system infrastructure budgets.
Underlying measurement precision varies by segment; joint reconstruction and robotics-assisted platforms carry tighter precision than emerging biologics categories. Forecasts reflect assumptions regarding notified body capacity expansion, cobalt supply stability, and MDR transitional provision deadlines. Deviation in notified body designation velocity or German surgical volume growth would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Orthopedic Extremity Market
Orthopedic Devices
Personalized Orthopaedic Implant Market
Orthopedic Devices
Middle East and Africa Knee Cartilage Repair Market
Orthopedic Devices
Physiotherapy Devices Market
Orthopedic Devices
Podiatry Laser Market
Orthopedic Devices
Orthopedic Trauma Fixation Devices Market
Orthopedic Devices
Medical Crutches Market
Orthopedic Devices
Orthopedic Artificial Bone Defect Repair Materials Market
Orthopedic Devices
Closed Heel Nursing Shoes Market
Orthopedic Devices
Polyethylene Orthopaedic Insert Market
Orthopedic Devices
Orthopedic Drill Bits Market
Orthopedic Devices
Hip Orthosis Market
Orthopedic Devices
Vertebroplasty Needles Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Needles Market
Orthopedic Devices
Orthopedic Prosthetic Devices Market
Orthopedic Devices
Global Minimally Invasive Spine Surgery Market