
 Spinal Surgery Devices Market | 2026-2036
Spinal Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Spinal Surgery Devices Market Outlook
The capital-intensity divergence between high-throughput manufacturers and boutique technology developers is reorganizing competitive tiers in spinal surgery devices. Medtronic plc leverages integrated implant and biologic portfolios to sustain pricing power across major hospital networks. Stryker Corporation anchors its position through robotic-assisted surgical platforms that command premium placement in ambulatory surgery centers.
Spinal surgery devices encompass implantable hardware, bone graft substitutes, and instrumented fixation systems designed to restore vertebral column stability, typically manufactured from titanium alloys or polyetheretherketone with precision tolerances below 50 microns for thread engagement safety. Fusion devices and biomaterials capture concentrated margin pools as surgeons prioritize osteobiologic integration and long-term construct durability. Minimally invasive and robotic-assisted technologies represent the fastest-expanding technology segments, driven by patient demand for reduced hospital stays and payor preference for lower complication rates.
FDA premarket notification pathways and EU MDR conformity assessments govern device approval timelines and clinical evidence requirements, directly shaping R&D allocation and market entry sequencing for manufacturers. The FDA's evolving guidance on spinal biologics and the EU MDR's heightened scrutiny of implantable device traceability are compressing timelines for quality system investments. Stakeholders must monitor reimbursement parity between inpatient and outpatient spinal fusion settings as site-of-care economics increasingly dictate technology adoption trajectories.
Market Dynamics
Hospital procurement consolidation and the migration of spinal fusion procedures to ambulatory surgery centers are compressing vendor margins while elevating the importance of integrated robotic platforms that demonstrate measurable outcome differentials.
Growth Catalysts
- Ambulatory Surgery Center Expansion:CMS reimbursement parity for select spinal procedures in outpatient settings accelerates site-of-care migration. ASC administrators prioritize capital-efficient robotic systems that reduce length-of-stay metrics.
- EU MDR Traceability Mandates:The regulation's unique device identification requirements for implantable spinal hardware create compliance-driven replacement cycles. Manufacturers with pre-positioned quality systems capture share from lagging competitors.
- Titanium Alloy Advancements:Additive manufacturing of porous titanium interbody cages improves osteointegration rates. Surgeons in high-volume German hospitals increasingly specify these constructs for complex multi-level fusions.
Market Restraints
- PEEK Raw Material Concentration:Polyetheretherketone resin supply concentrates among a limited set of European chemical producers. Device manufacturers face input cost volatility and extended lead times for implant-grade polymer.
- FDA 510(k) Clinical Evidence Escalation:The agency's heightened scrutiny of substantial equivalence claims for posterior cervical fusion systems extends clearance timelines. Early-stage developers exhaust capital reserves during extended review periods.
- Non-Fusion Motion Preservation:Artificial disc replacement and dynamic stabilization systems substitute for traditional fusion in select indications. Younger patient cohorts in Japan increasingly select motion-sparing alternatives.
Strategic Opportunities
- Brazil's Underpenetrated Market:Private hospital chains in São Paulo and Rio de Janeiro expand orthopedic service lines. ANVISA's streamlined registration pathway for Class III devices accelerates market entry for qualified manufacturers.
- AI-Enabled Preoperative Planning:Machine learning algorithms analyzing CT and MRI datasets converge with robotic navigation platforms. Integrated systems reduce screw misplacement rates and revision surgery incidence.
- Direct-to-Employer Contracting:Self-insured corporations in Texas and Florida negotiate bundled payment arrangements for spinal procedures. Device vendors bypass traditional distributor markups through direct hospital system agreements.
Industry Challenges
- Robotics Technician Scarcity:Ambulatory surgery centers struggle to recruit and retain certified biomedical engineers capable of maintaining precision navigation systems. Training programs at technical institutes in Ohio and Arizona expand capacity but lag demand.
- Legacy EHR Integration:Robotic surgical platforms generate procedural data requiring seamless flow into hospital information systems. IT departments at mid-sized health systems allocate substantial resources to API customization and workflow reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spinal Surgery Devices Market |
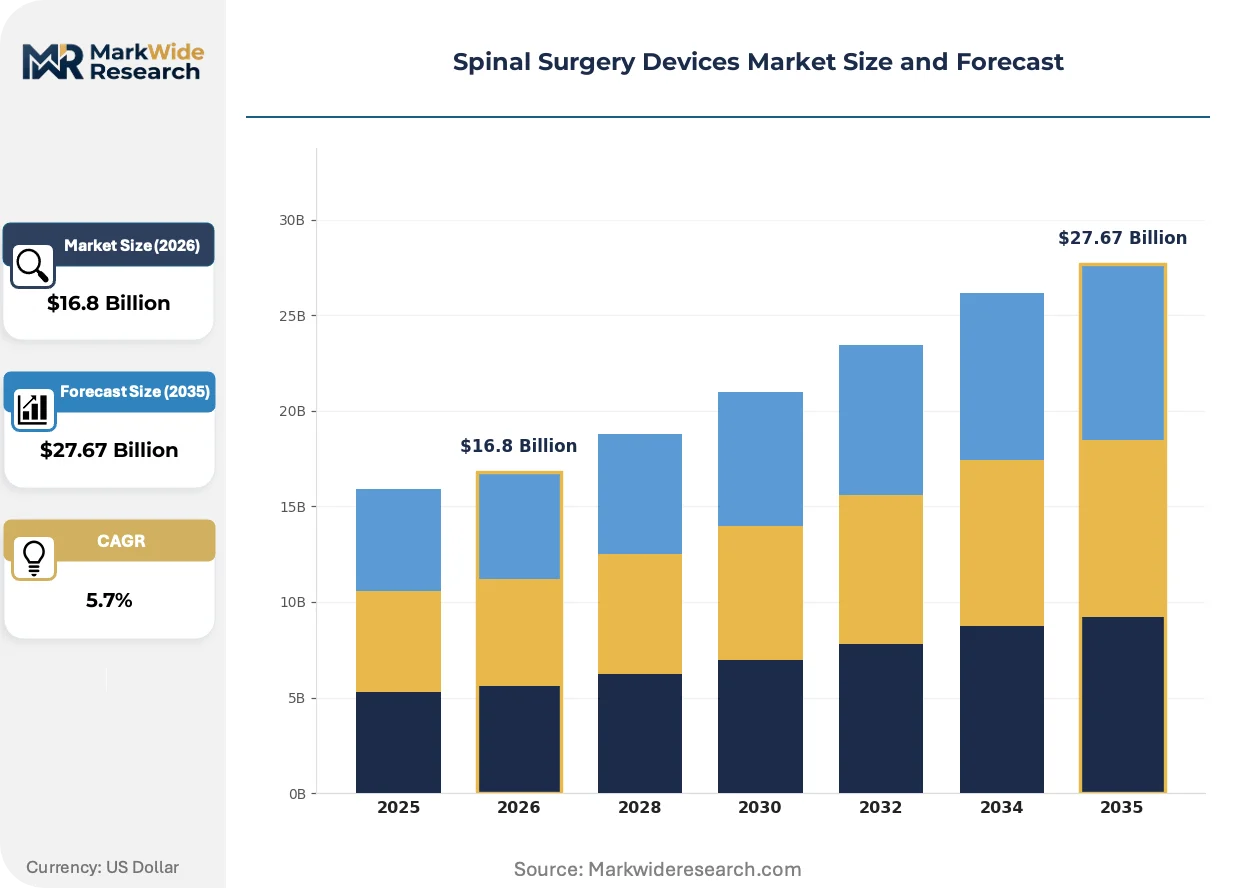
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $27.67 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implants, Fusion Devices, Distraction Devices, Biomaterials End User: Hospitals, Ambulatory Surgery Centers, Specialty Clinics, Rehabilitation Centers Application: Degenerative Disc Disease, Spinal Stenosis, Scoliosis, Trauma Technology: Minimally Invasive, Robotic-Assisted, Traditional, Fusion Technology |
| Companies Covered | Medtronic plc, Johnson & Johnson Services, Inc., Stryker Corporation, Zimmer Biomet Holdings, Inc., Globus Medical, Inc., NuVasive, Inc., Orthofix Medical Inc., Alphatec Holdings, Inc., RTI Surgical Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spinal Surgery Devices Market Strategic Shifts
Spinal surgery device innovation concentrates on reducing operative invasiveness while expanding the addressable patient population through enhanced biologic integration and intelligent instrumentation.
Expandable interbody fusion cages fabricated from titanium lattice structures are miniaturizing access requirements for lumbar procedures. Surgeons at high-throughput ASCs in Florida and Texas adopt these devices for same-day discharge protocols. The technology is miniaturizing incision lengths from traditional open approaches while maintaining disc height restoration capabilities.
Japan's PMDA implemented revised guidance on spinal biologics requiring extended follow-up data for demineralized bone matrix products. Domestic manufacturers accelerate clinical trial investments to satisfy evidentiary thresholds. The regulation most affects allograft processors seeking approval for cervical spine indications.
Hospital value analysis committees now mandate real-world evidence packages demonstrating 90-day readmission reductions before granting robotic platform contracts. Traditional capital equipment vendors face displacement by outcome-guaranteeing suppliers. This behavioral shift appears most pronounced in California integrated delivery networks consolidating purchasing authority at the system level.
Spinal Surgery Devices Market Segmentation
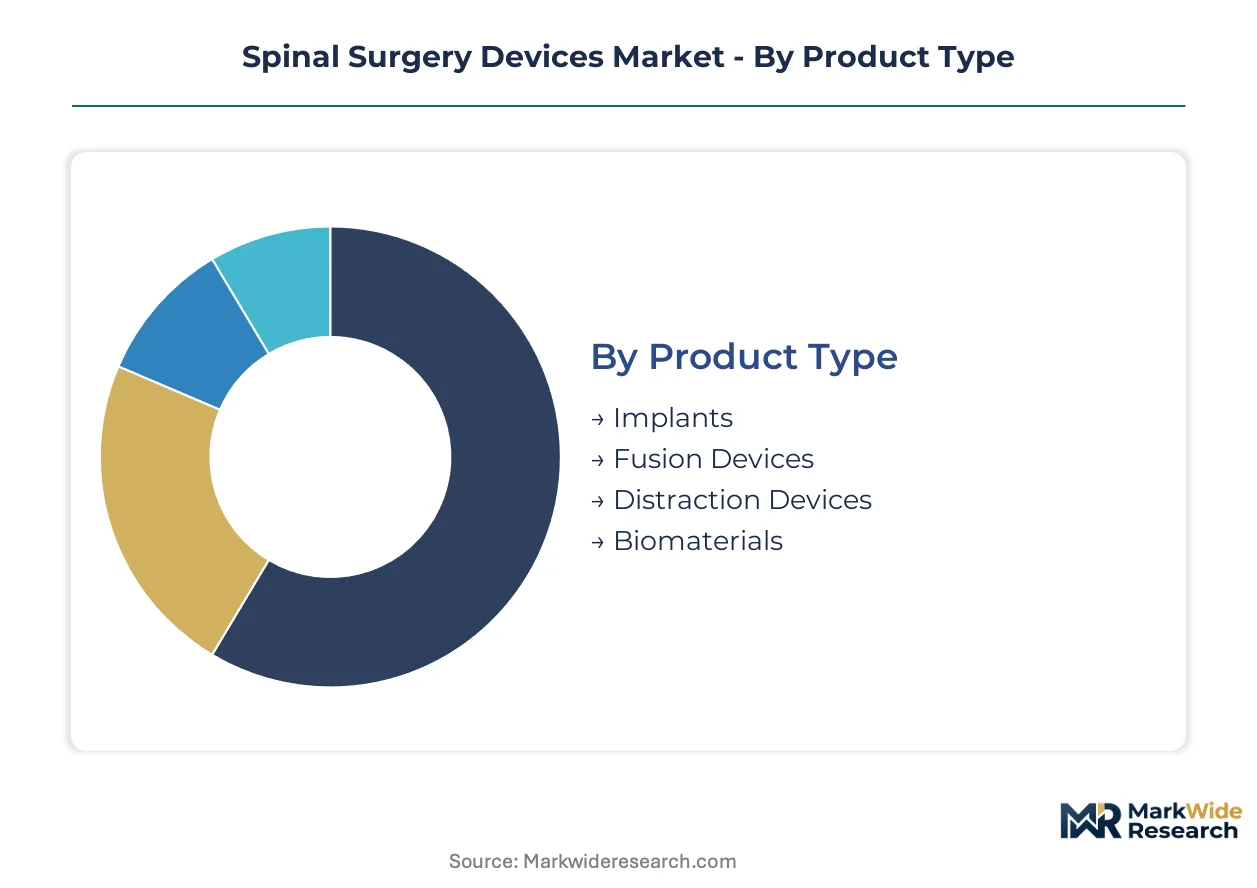
Segmentation reveals how margin pools concentrate in fusion hardware and robotic platforms while site-of-care economics reshape purchasing authority across provider types. Understanding these divisions exposes where technology premiums command sustainable pricing power.
Product Type:
Margin concentration follows biologic integration performance and construct durability specifications, with porous titanium architectures capturing premium placement in complex multi-level procedures.
- Implants:Titanium alloy and polyetheretherketone constructs manufactured to sub-50-micron tolerances anchor vertebral fixation. German hospital systems specify these for universal coverage-funded fusion volumes, with additive manufacturing expanding porous surface architectures.
- Fusion Devices:Interbody cages and pedicle screw systems integrate demineralized bone matrix and synthetic osteobiologics. Ambulatory surgery centers in Florida and Texas prioritize expandable titanium lattice designs enabling same-day discharge protocols.
- Distraction Devices:Mechanical and hydraulic systems restore disc height in minimally invasive approaches. Devices face substitution pressure from expandable cage technologies in high-volume ASC settings.
- Biomaterials:Allograft, synthetic bone graft substitutes, and cellular matrices require extended PMDA follow-up data in Japan. Processors concentrate investments on cervical spine indication expansions.
The dominant share belongs to Fusion Devices, while Biomaterials is closing the gap fastest.
End User:
Procurement authority is migrating toward outpatient settings where capital-efficient robotics and compressed length-of-stay metrics determine vendor selection.
- Hospitals:Integrated delivery networks consolidate purchasing across robotic-assisted platforms and comprehensive implant portfolios. Value analysis committees mandate 90-day readmission evidence before capital commitment.
- Ambulatory Surgery Centers:CMS reimbursement parity for select spinal procedures accelerates site-of-care migration. Administrators prioritize systems reducing operative time and enabling same-day discharge.
- Specialty Clinics:Focused orthopedic and neurosurgical practices concentrate on motion-preservation alternatives for younger patient cohorts. Clinics in Japan increasingly select artificial disc replacement over fusion.
- Rehabilitation Centers:Post-acute facilities coordinate with surgical sites on bundled payment arrangements. Texas and Florida self-insured employers negotiate direct device procurement bypassing distributor markups.
Hospitals retain the largest procurement volume, though Ambulatory Surgery Centers are expanding share most rapidly.
Application:
Procedure volumes concentrate where aging demographics intersect with established reimbursement pathways, while trauma applications respond to acute care infrastructure.
- Degenerative Disc Disease:Lumbar and cervical disc pathology drives the majority of fusion procedures. German universal coverage sustains high volumes of multi-level interventions in patients over 65.
- Spinal Stenosis:Decompression with or without fusion addresses neural element compression. Minimally invasive approaches reduce hospital stays and satisfy payor preference for lower complication rates.
- Scoliosis:Adolescent and adult deformity correction requires complex instrumentation and longer operative times. Procedures concentrate in academic medical centers with specialized surgical teams.
- Trauma:Acute vertebral fractures from high-energy mechanisms demand urgent stabilization. Emergency department throughput and imaging availability dictate regional device utilization patterns.
Degenerative Disc Disease holds the greatest procedure volume, with Spinal Stenosis gaining share through outpatient migration.
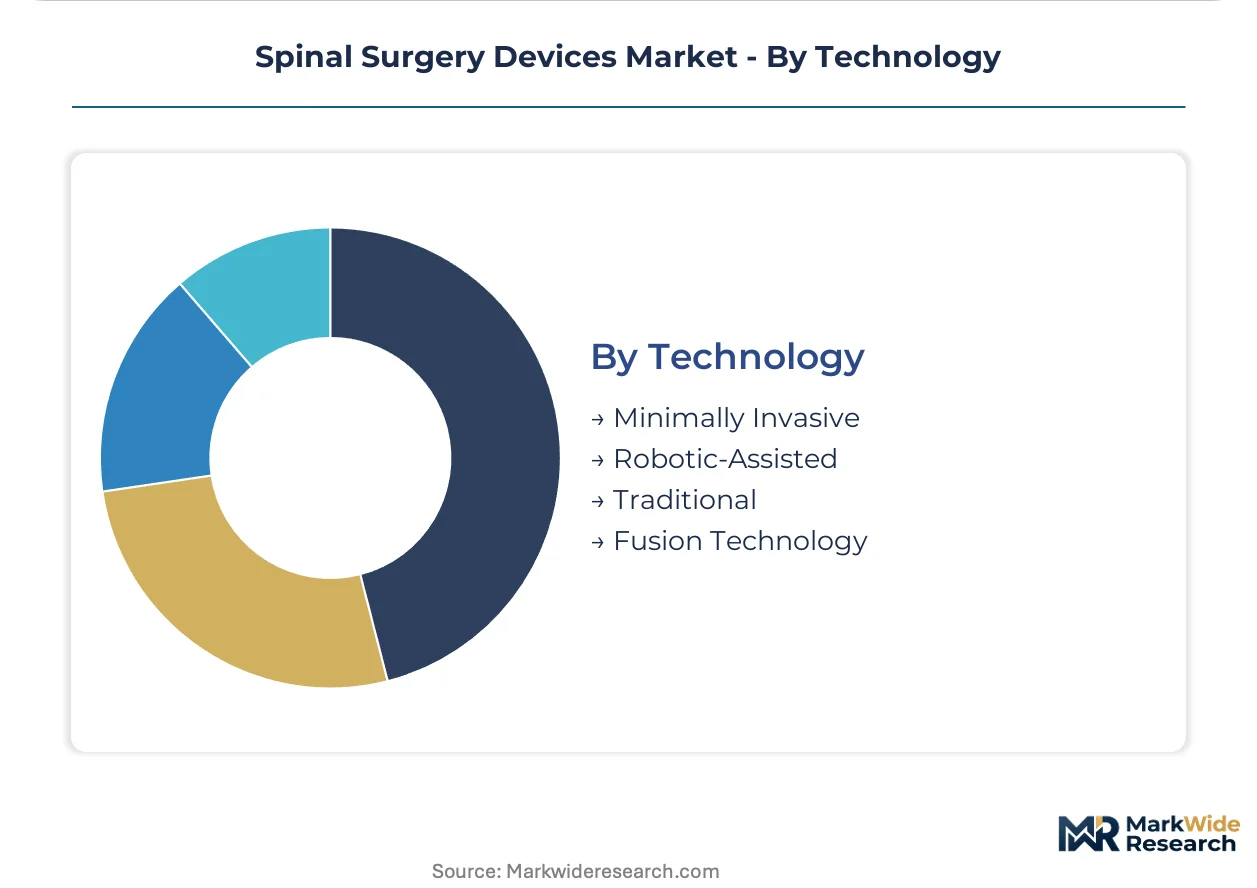
Technology:
Capital allocation concentrates where navigation precision and reduced tissue disruption demonstrate measurable outcome differentials against conventional approaches.
- Minimally Invasive:Tubular retractor systems and percutaneous fixation reduce paraspinal muscle disruption. Surgeons at high-throughput ASCs adopt these for patient selection criteria emphasizing rapid recovery.
- Robotic-Assisted:Navigation platforms with preoperative planning software reduce screw misplacement and revision incidence. AI-enabled CT and MRI analysis converges with robotic instrumentation in integrated systems.
- Traditional:Open approaches with direct visualization remain standard for complex deformity and trauma. Techniques persist where capital constraints limit robotic platform acquisition.
- Fusion Technology:Instrumented fixation with interbody support represents the established standard of care. Constructs integrate with biologics to accelerate arthrodesis and reduce pseudarthrosis rates.
Robotic-Assisted platforms command the steepest expansion trajectory, while Traditional approaches defend volume in complex deformity correction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. German buyers absorb premium titanium constructs through universal coverage pools. Brazilian private hospitals negotiate aggressively on implant bundles. Japanese surgeons demand motion-preservation alternatives that command higher unit economics.
United States
Hospital procurement consolidation and ASC migration compress vendor margins. CMS reimbursement parity for outpatient spinal fusion accelerates site-of-care shifts. Florida and Texas ASC clusters prioritize capital-efficient robotic platforms enabling same-day discharge protocols.
Germany
Aging demographics sustain high volumes of multi-level fusion procedures. Universal health coverage eliminates patient cost barriers to premium titanium interbody cages. Bavarian hospital networks specify additive-manufactured porous constructs for complex deformity corrections.
Japan
Younger patient cohorts select artificial disc replacement over traditional fusion. PMDA extended follow-up requirements for demineralized bone matrix products reshape clinical trial investments. Osaka-based orthopedic centers concentrate motion-preservation expertise.
Brazil
Private hospital chains in São Paulo and Rio de Janeiro expand orthopedic service lines. ANVISA streamlined Class III device registration accelerates qualified manufacturer entry. São Paulo metropolitan clusters drive Latin America's highest spinal procedure volumes.
China
Domestic manufacturers scale production of titanium alloy pedicle screw systems. NMPA regulatory harmonization with international standards elevates quality system investments. Yangtze River Delta medical device clusters concentrate high-volume production capacity.
Spinal Surgery Devices Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in spinal surgery devices. Consolidated implant-biologic portfolios and robotic platform ecosystems define the upper tier. Mid-scale specialists compete through titanium additive manufacturing expertise or motion-preservation portfolios. Dominant competitive moves include strategic partnerships linking navigation software to hardware platforms and backward integration into implant-grade polymer supply.
Among integrated multinational corporations, Medtronic plc and Johnson & Johnson Services, Inc. occupy positions exemplifying comprehensive implant-biologic portfolios. Stryker Corporation anchors the robotic-assisted tier. These three represent distinct competitive archetypes: full-stack integration, diversified healthcare conglomeration, and precision navigation specialization.
| Leading Market Players |
|---|
| Medtronic plc |
| Johnson & Johnson Services, Inc. |
| Stryker Corporation |
| Zimmer Biomet Holdings, Inc. |
| Globus Medical, Inc. |
| NuVasive, Inc. |
| Orthofix Medical Inc. |
| Alphatec Holdings, Inc. |
| RTI Surgical Holdings, Inc. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts for implant-grade titanium sponge lock in supply access and price visibility for device manufacturers navigating volatile aerospace and medical alloy markets. These arrangements insulate high-volume producers from spot market swings while compressing margins for buyers locked into legacy pricing tiers.
Pricing Analysis
After-sales service contracts and extended maintenance agreements on robotic navigation systems drive lifetime value beyond initial hardware placement. Three-tier pricing structure across premium, standard, and economy levels segments buyers by surgical volume and outcome guarantee requirements. Cost compression in the standard tier is intensifying because hospital procurement consolidation demands bundled implant-biologic pricing. Ambulatory surgery centers exhibit highest price sensitivity due to capital constraints, while academic medical centers absorb premium tiers for complex deformity platforms.
Supply Chain Analysis
Port congestion on transpacific lanes from Shanghai to Long Beach elevates inbound logistics costs for Asian-manufactured titanium components and finished implants. Supply concentrates in Germany for precision-machined fixation hardware, China for titanium sponge and wire feedstock, and Switzerland for PEEK polymer compounding. Device manufacturers rely on PEEK resin from European chemical producers and precision-ground titanium rod from Japanese metallurgical specialists. Single-source vulnerability in implant-grade polymer supply creates exposure to extended lead times. Distribution runs through specialized orthopedic distributors with hospital GPO contracts and direct-to-health-system agreements bypassing traditional markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of certified biomedical engineers capable of maintaining robotic navigation systems constrains ambulatory surgery center expansion and elevates service contract premiums. This capability gap rewards vendors with captive training infrastructure and outcome-guaranteeing maintenance programs.
For Market Incumbents: Shield implant-biologic portfolio margins by accelerating backward integration into titanium additive manufacturing feedstock and PEEK polymer supply. Consolidate purchasing relationships with integrated delivery networks through bundled capital equipment and consumable contracts that raise switching costs for rival robotic platforms. Prioritize FDA 510(k) clearance pipeline investment to defend against emerging navigation software entrants. For New Entrants and Emerging Players: Brazil's ANVISA streamlined Class III registration pathway offers fastest regulatory entry for qualified manufacturers seeking white-space expansion. Target São Paulo metropolitan private hospital chains with capital-efficient expandable cage designs that enable same-day discharge protocols. Pursue direct contracting with Texas and Florida self-insured employers bypassing distributor markups through bundled payment arrangements. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale specialists with captive titanium additive manufacturing expertise and established surgeon training ecosystems. Long-term viability favors platforms demonstrating measurable 90-day readmission reduction evidence required by hospital value analysis committees. Monitor CMS reimbursement parity expansion signals as inflection indicator for ambulatory surgery center addressable market growth.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Integrated delivery network contracts secure robotic platform placement and implant volume commitments. |
| FDA Submission | Premarket notification pathways for posterior cervical systems compress competitor clearance timelines. |
| CE Marking Pathway | EU MDR conformity assessments for implantable hardware traceability mandate quality system investment. |
| Software Companion Development | AI-enabled preoperative planning integration with robotic navigation reduces screw misplacement rates. |
| Reimbursement Strategy | CMS outpatient parity documentation accelerates ambulatory surgery center site-of-care migration. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, EU MDR notified body conformity assessments, and hospital GPO contract filings. Interviews with orthopedic surgeons, biomedical engineering directors, ASC administrators, and implant procurement managers inform demand-side validation. Bottom-up procedure volume estimates triangulate against top-down manufacturer revenue disclosures and CMS Medicare claims data.
Segmentation dimensions modeled span product type, end user facility category, application indication, and technology platform across the analysis window. CAGRs derive from procedure volume trajectories, site-of-care migration rates, and technology substitution elasticities. Forecast inputs incorporate EU MDR compliance-driven replacement cycle timing and ambulatory surgery center capital equipment adoption curves.
Underlying assumptions cover sustained CMS reimbursement parity expansion, titanium raw material supply continuity, and regulatory clearance timeline stability, with deviation risk concentrated in FDA evidentiary escalation for biologics and PEEK supply concentration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Orthopedic Artificial Bone Defect Repair Materials Market
Orthopedic Devices
Orthobiologics Market
Orthopedic Devices
France Neurology Devices Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Market
Orthopedic Devices
Revision Knee Replacement Market
Orthopedic Devices
Hip Replacement Market
Orthopedic Devices
Global Minimally Invasive Spine Surgery Market
Orthopedic Devices
Middle East and Africa Knee Cartilage Repair Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Needles Market
Orthopedic Devices
3D Medical Implant Market
Orthopedic Devices
Orthopedic Pedicle Screw Market
Orthopedic Devices
Knee Cartilage Repair Market
Orthopedic Devices
GCC Orthopedic Braces and Supports Market
Orthopedic Devices
Global Orthopedic Splints Market
Orthopedic Devices
India Orthopedic Braces and Supports Market
Orthopedic Devices
South Africa Spinal Surgery Devices Market