
 Europe Biodegradable Cups Market | 2026-2036
Europe Biodegradable Cups Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Biodegradable Cups Market Foresight
The EU Single-Use Plastics Directive is pivoting foodservice procurement toward certified compostable serviceware across member states. Huhtamaki Group leverages its molded fiber capacity to supply major European coffee chains with plastic-free cup solutions. Vegware Ltd. specializes in plant-based laminated products that meet industrial composting standards in France and the Netherlands. BVO International GmbH anchors its position through direct wholesale partnerships with German event caterers and institutional buyers.
Biodegradable cups are single-use beverage containers engineered from polylactic acid, bagasse pulp, or coated paper substrates designed to decompose under industrial composting conditions within 90 to 180 days. These products typically withstand temperatures from minus 20 to 85 degrees Celsius and serve the on-premise and takeaway foodservice sectors where regulatory bans on conventional plastics have eliminated traditional alternatives. PLA-based cups occupy the premium tier due to clarity and printability advantages, while bagasse variants compete aggressively on unit cost in high-volume restaurant applications. The 12 oz and 16 oz size categories capture the majority of cafe and fast-casual demand, with food trucks and outdoor events driving growth in the 20 oz format. Online distribution channels are expanding fastest among independent hospitality operators seeking smaller minimum order quantities.
EMA, EFSA, and the EU Green Deal collectively establish compostability certification requirements, food-contact safety standards, and carbon reduction targets that determine market access for biodegradable cup suppliers. REACH compliance for chemical migration limits and the F-Gas Regulation's indirect pressure on petroleum-based alternatives further tighten the regulatory perimeter around conventional competitors. Stakeholders must monitor evolving national transpositions of the Packaging and Packaging Waste Regulation to anticipate certification harmonization or fragmentation across European markets.
Market Dynamics
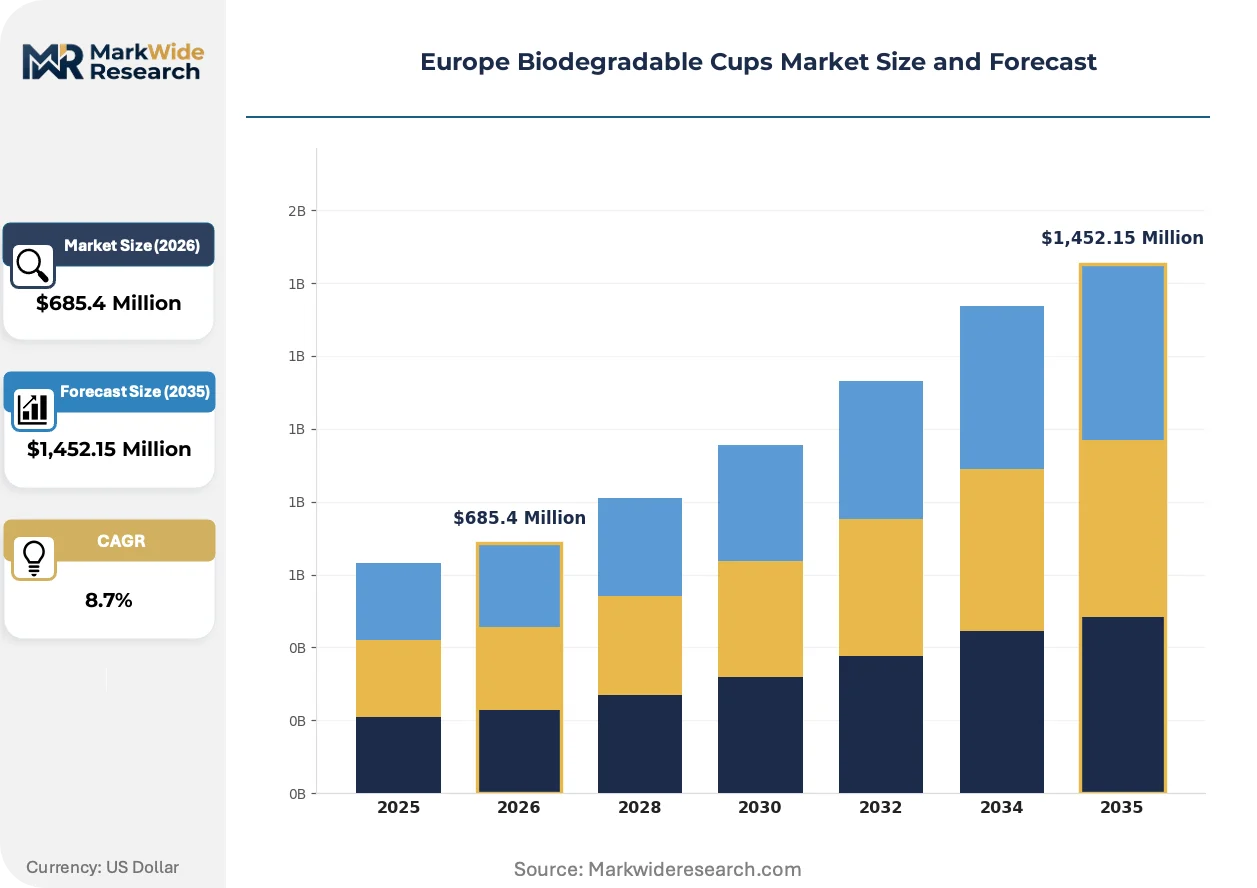
The EU Single-Use Plastics Directive is compressing the transition timeline for foodservice operators across member states. This regulatory pressure is restructuring procurement priorities and accelerating capital reallocation toward certified compostable packaging infrastructure.
Growth Catalysts
- REACH chemical migration standards:These protocols are eliminating conventional plastic cup alternatives from food-contact applications across German and French foodservice channels.
- Bagasse pulp processing:Advances in fiber molding technology are reducing unit production costs for high-volume restaurant and cafe applications in Western Europe.
- Quick-service restaurant procurement mandates:Major European coffee chains are requiring compostable serviceware specifications in supplier contracts.
Market Restraints
- PLA resin supply concentration:European biopolymer production capacity remains insufficient to serve projected foodservice demand, creating input cost volatility.
- Industrial composting infrastructure gaps:Limited processing facility availability in Eastern European markets restricts end-of-life value realization for certified products.
- Conventional paper cup substitution:PE-lined alternatives continue competing on unit economics in price-sensitive institutional catering segments.
Strategic Opportunities
- Polish and Romanian foodservice expansion:Underpenetrated markets present first-mover positioning for certified compostable cup suppliers establishing distribution partnerships.
- EU Green Deal carbon accounting:Scope 3 emission reduction targets are incentivizing corporate catering buyers to switch from petroleum-based serviceware.
- Direct-to-operator e-commerce platforms:Digital wholesale channels are compressing minimum order quantities for independent hospitality operators.
Industry Challenges
- Compostability certification timelines:ECHA and national transposition delays are extending product approval cycles for new substrate formulations.
- Barrier coating R&D expenditure:Developing heat-resistant PLA laminates requires sustained capital commitment without guaranteed regulatory harmonization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Biodegradable Cups Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PLA, Paper, Pulp, Bagasse Size: 8 oz, 12 oz, 16 oz, 20 oz End User: Cafes, Restaurants, Food Trucks, Events Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Huhtamaki Group, Genpak LLC, Pactiv LLC, BVO International GmbH, Go-Pak Limited, Vegware Ltd., Biopac (U.K.) Ltd., Bio Futura Group, Scyphus Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Biodegradable Cups Market Shifts & Advancements
Material science convergence with regulatory compliance requirements is redefining competitive advantage in European foodservice packaging. Suppliers are racing to develop substrates that satisfy both performance specifications and accelerated biodegradation timelines.
Barrier-coated bagasse formulations are integrating heat-sealable PLA laminates to achieve hot-beverage performance parity with conventional cups. German and Dutch coffee chains are adopting these hybrid substrates for takeaway applications. This material convergence is integrating premium clarity characteristics with aggressive unit cost positioning, compressing the price-performance gap between plant-based and petroleum-derived alternatives.
REACH amendments are tightening chemical migration limits for food-contact materials across all EU member states. Industrial consequences include accelerated phase-out of fluorinated coatings in cup linings. Quick-service restaurant chains in France and Belgium are responding by reformulating procurement specifications to exclude non-compliant substrate categories.
Certification-driven specification changes are altering buyer evaluation criteria for institutional foodservice contracts. European corporate catering operators are requiring industrial compostability certification as a mandatory bid qualification. This behavioral shift is most visible in Netherlands and Nordic markets, where municipal procurement guidelines now prioritize verified end-of-life pathways over unit cost minimization.
Europe Biodegradable Cups Market Segmentation
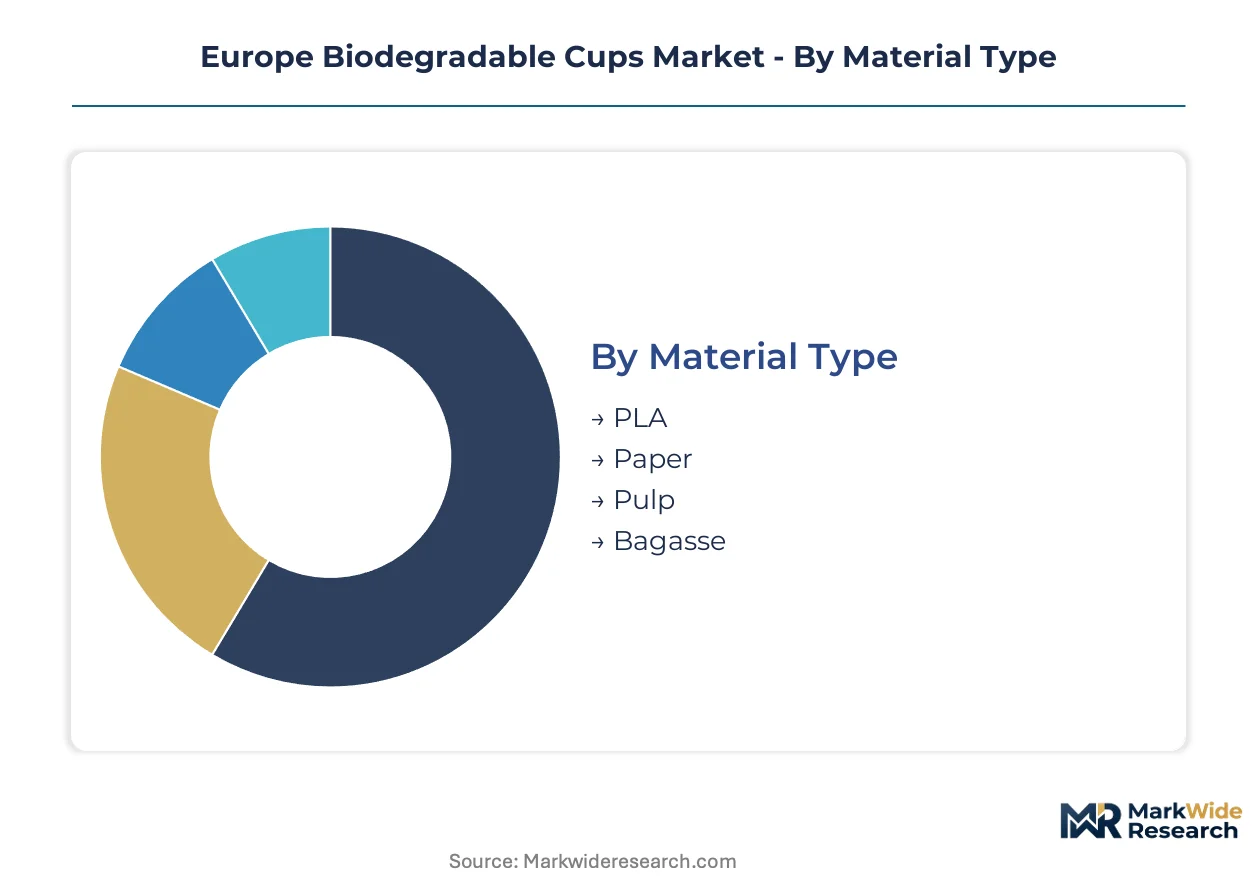
Certification requirements under REACH and the EU Single-Use Plastics Directive fragment the European biodegradable cups landscape by material composition and end-use application. Suppliers must align substrate selection with specific industrial composting infrastructure availability and food-contact compliance pathways across member states.
Material Type:
Certification burdens concentrate most heavily on PLA formulations requiring EFSA food-contact approval and industrial compostability verification, while bagasse and pulp substrates face simpler fiber-sourcing traceability requirements under ECHA guidelines.
- PLA:Polylactic acid derived from corn starch delivers optical clarity and precise printability for branded takeaway applications. German and Dutch coffee chains specify PLA for cold-beverage lines where visual presentation drives procurement decisions. REACH chemical migration compliance and industrial composting certification create dual regulatory gates for new entrants.
- Bagasse:Molded sugarcane fiber achieves aggressive unit economics in high-volume restaurant deployments across France and Spain. Heat-sealable PLA laminates now extend performance into hot-beverage segments previously dominated by conventional cups. Limited EFSA approval timelines for novel coating chemistries constrain formulation innovation cycles.
- Paper:Coated cellulose substrates balance cost positioning with established recycling infrastructure familiarity among institutional buyers.
- Pulp:Wood fiber alternatives serve price-sensitive Eastern European markets where composting certification awareness remains nascent.
Leading the category by volume: Bagasse. Growing fastest: PLA laminates with heat-barrier functionality.
Size:
Volume concentration in standard cafe formats creates manufacturing scale advantages, while specialty sizes command margin premiums through limited production runs and event-specific procurement patterns.
- 12 oz:The dominant format for espresso-based beverages across Italian and French cafe chains. PLA and bagasse suppliers both target this specification for production line economies. Procurement contracts from major coffee retailers anchor demand stability.
- 16 oz:Standard for filtered coffee and cold-brew takeaway in Nordic markets. Bagasse variants capture share through aggressive pricing against PE-lined conventional alternatives. Seasonal demand spikes align with summer beverage promotional cycles.
- 8 oz:Concentrated in premium single-origin espresso service where unit margins justify higher substrate costs.
- 20 oz:Event catering and food truck applications in Germany and Belgium drive intermittent high-volume orders with compressed lead times.
Manufacturing scale centers on 12 oz and 16 oz. Steepest expansion trajectory: 20 oz for outdoor hospitality recovery.
End User:
Procurement sophistication varies sharply across buyer categories, with corporate coffee chains imposing certified compostability mandates while independent operators prioritize unit cost and minimum order flexibility.
- Cafes:Branded coffee chains in France, Germany, and the Netherlands require industrial compostability certification as a mandatory supplier qualification. Multi-year procurement agreements with Huhtamaki Group and Vegware Ltd. lock in volume commitments. Menu standardization across outlet networks simplifies specification consolidation.
- Restaurants:Quick-service and fast-casual operators balance performance requirements with throughput demands in high-volume dine-in and takeaway environments. Bagasse pulp formulations dominate procurement tenders where price sensitivity exceeds brand presentation priorities.
- Food Trucks:Mobile operators in Berlin and Paris prioritize compact storage and rapid product turnover over substrate premiumization.
- Events:Festival organizers and stadium caterers in Belgium and the Netherlands face municipal procurement guidelines mandating verified end-of-life pathways.
Highest procurement sophistication: Cafe chains. Fastest certification adoption: Event catering under municipal mandate pressure.
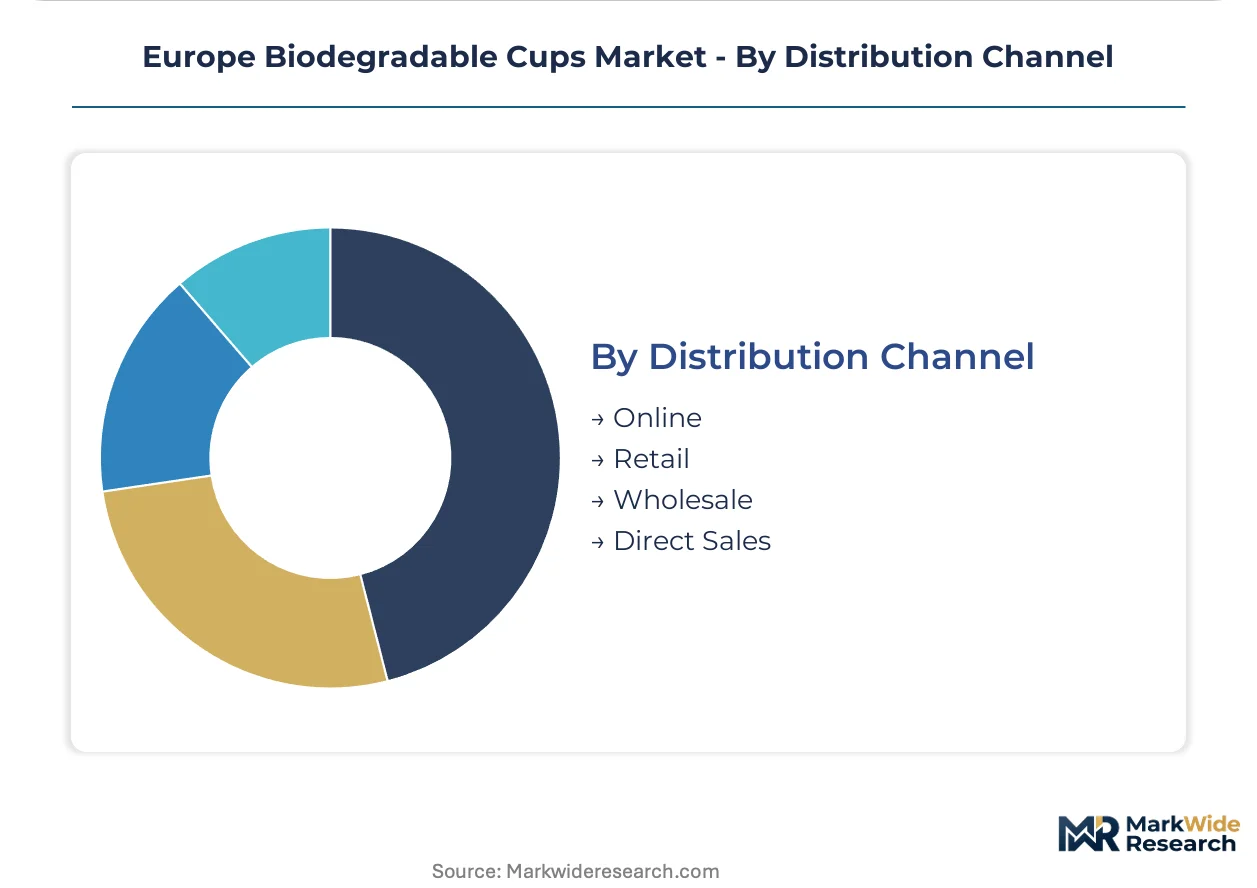
Distribution Channel:
Channel selection determines margin structure and customer acquisition cost, with direct sales capturing institutional volume while digital platforms fragment order patterns among smaller operators.
- Wholesale:BVO International GmbH and comparable distributors anchor supply relationships with German event caterers and institutional foodservice contractors. Pallet-scale logistics and established credit terms sustain incumbent positioning against digital challengers.
- Online:Direct-to-operator platforms compress minimum order quantities for independent hospitality businesses in Poland and Romania. Digital procurement penetration is climbing fastest among first-time compostable cup adopters seeking trial volumes without warehouse commitments.
- Retail:Limited presence in consumer-facing packaging for home entertaining and small office applications.
- Direct Sales:Major coffee chain accounts bypass intermediaries through multi-year supply agreements with molded fiber specialists.
Volume concentration: Wholesale partnerships. Channel expanding most quickly: Online platforms for independent operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Amsterdam anchors European compostable packaging innovation through clustered R&D facilities serving Dutch coffee chains and municipal procurement offices. The Randstad corridor channels certified cup volumes into Belgian and German distribution networks.
Germany
Berlin's food truck operators and Munich's event caterers drive bagasse cup procurement under strict municipal waste ordinances. The F-Gas Regulation indirectly pressures petroleum-based alternatives while REACH amendments tighten chemical migration limits. North Rhine-Westphalia hosts molded fiber production clusters supplying quick-service restaurant chains across the Benelux region.
France
Parisian cafe chains mandate industrial compostability certification in supplier contracts, displacing conventional PE-lined alternatives. ANSM enforces food-contact safety protocols alongside EU Single-Use Plastics Directive transposition. The Île-de-France region concentrates laminated PLA formulation R&D for branded takeaway applications.
Netherlands
Rotterdam's port logistics enable efficient biopolymer resin imports for domestic cup manufacturing. Municipal procurement guidelines in Amsterdam and The Hague prioritize verified end-of-life pathways over unit cost minimization. Eindhoven's packaging technology cluster advances heat-sealable barrier coatings for hot-beverage applications.
Belgium
Festival organizers in Flanders face regional mandates requiring certified compostable serviceware for outdoor events. Brussels-based institutional caterers align procurement with EU Green Deal carbon accounting frameworks. Wallonia's emerging foodservice distributors trial digital wholesale platforms for independent hospitality operators.
Poland
Warsaw's quick-service restaurant sector exhibits nascent certification awareness amid accelerating Western European supply chain extension. National transposition of Packaging and Packaging Waste Regulation lags core EU markets. Krakow's independent cafe operators represent first-mover opportunities for direct-to-operator e-commerce penetration.
Europe Biodegradable Cups Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and substrate technology dimensions. The vendor base organizes around three strategic archetypes: molded fiber specialists with captive pulp processing, laminated PLA formulators targeting branded clarity requirements, and wholesale distributors anchoring institutional volume relationships. Consolidation pressure concentrates among mid-scale operators lacking vertical integration into raw material sourcing. Capacity expansion and certification-driven portfolio diversification constitute the dominant competitive moves reshaping supplier positioning.
Within the molded fiber tier, Huhtamaki Group and Vegware Ltd. exemplify divergent geographic anchoring strategies. Huhtamaki's Finnish corporate structure positions it within Nordic sustainability procurement networks, while Vegware's UK base aligns with Commonwealth-influenced certification pathways. BVO International GmbH occupies the wholesale distributor archetype, its German GmbH structure signaling embeddedness in Central European institutional catering supply chains. These three entities collectively represent the certification-premium, substrate-technology, and distribution-scale vectors defining competitive differentiation.
| Leading Market Players |
|---|
| Huhtamaki Group |
| Genpak LLC |
| Pactiv LLC |
| BVO International GmbH |
| Go-Pak Limited |
| Vegware Ltd. |
| Biopac (U.K.) Ltd. |
| Bio Futura Group |
| Scyphus Limited |
| Others |
Supply & Pricing Matrix
Family-owned molded fiber specialists across Germany and the Netherlands anchor supply discipline through captive pulp processing and long-term bagasse sourcing contracts. Their ownership structure insulates pricing from quarterly earnings pressure while enabling sustained investment in compostability certification.
Pricing Analysis
Outcome-based pricing tied to verified industrial composting performance anchors procurement contracts for major French and Dutch coffee chains. Three-tier pricing structure across premium PLA clarity grades, standard bagasse laminates, and economy pulp formats separates certified compostability tiers. Cost compression in economy pulp segments is intensifying because Polish and Romanian distributors are importing Asian-sourced alternatives. Quick-service restaurant chains exhibit highest price sensitivity, while event caterers under municipal mandate pressure accept premium positioning.
Supply Chain Analysis
Direct-to-foodservice channels handle hyperscale demand from Huhtamaki Group and Vegware Ltd., while wholesale distributors serve fragmented independent operators. Manufacturing concentrates in Germany, the Netherlands, and Finland, drawing from corn starch biopolymer feedstocks, sugarcane bagasse pulp, and wood fiber alternatives. Single-source vulnerability in PLA resin supply creates input cost volatility when European biopolymer capacity falls short. Distribution runs through Rotterdam port logistics for resin imports and North Rhine-Westphalia molded fiber clusters for finished cup assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
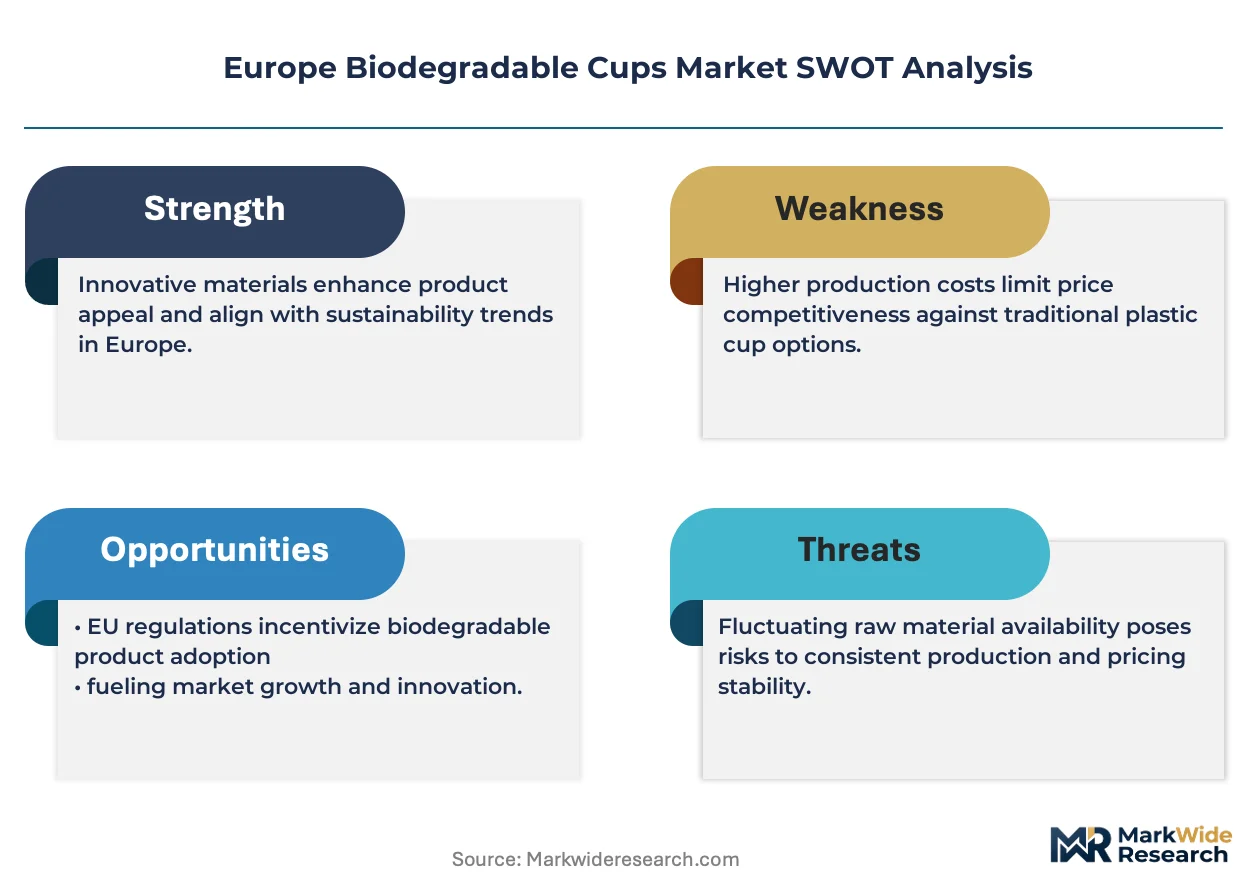
Heat-sealable PLA barrier coatings are displacing conventional PE-lined cups across EU foodservice channels, compressing the transition timeline for substrate suppliers and buyers alike.
For Market Incumbents: Cement supply security through backward integration into bagasse pulp processing or captive PLA resin partnerships. Defend margin position by accelerating heat-barrier R&D ahead of REACH coating amendments that will disqualify fluorinated alternatives from French and Belgian procurement specifications. For New Entrants and Emerging Players: Launch via direct-to-operator e-commerce platforms targeting Warsaw and Krakow independent cafes where certification awareness is nascent but Western supply chain extension is accelerating. Polish quick-service restaurants represent the most penetrable segment due to lagging national transposition of Packaging and Packaging Waste Regulation. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale molded fiber operators in Eastern Germany with underutilized capacity and established EFSA compliance pathways. Watch municipal procurement guideline adoption in Belgian Flanders and Dutch Randstad corridors as the inflection signal for certification-premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Barrier Coating R&D | REACH amendments on fluorinated chemistries are forcing reformulation investments in French and Belgian supply chains. |
| Backward Integration into Pulp | Captive bagasse sourcing insulates German molded fiber specialists from Asian import price volatility. |
| Direct-to-Operator E-Commerce | Digital platforms compress minimum orders for Polish and Romanian independent hospitality operators. |
| Industrial Compostability Certification | EFSA and ECHA dual approval gates lock in premium positioning for Dutch and German coffee chain contracts. |
| Eastern European Distribution Partnerships | First-mover positioning in Warsaw and Bucharest captures pre-mandate adoption curves before regulatory harmonization. |
Research Methodology
EU regulatory filings, EFSA food-contact safety databases, and national customs trade records formed the secondary backbone for supply chain mapping and certification pathway analysis. Primary interviews with procurement directors at German quick-service restaurant chains, Dutch municipal catering officers, and French packaging R&D heads combined with secondary validation through REACH amendment tracking and industrial composting facility databases. Bottom-up volume modeling across material type, size category, and end-use segment triangulated against top-down European foodservice packaging expenditure estimates.
Historical trendline analysis of bagasse pulp processing cost curves and PLA resin import volumes established baseline growth trajectories across the projection horizon. The analytical framework modeled segmentation dimensions including material substrate technology, cup size format, end-user procurement sophistication, and distribution channel structure. CAGRs derived from segment-level volume buildups incorporating ECHA certification timeline delays and EU Single-Use Plastics Directive enforcement phases.
Regulatory transposition delays, biopolymer supply disruptions, and municipal procurement guideline adoption lags are the dominant revision risks for forecast trajectories. Forecast outputs reflect documented assumptions on certification harmonization timelines and industrial composting infrastructure rollout. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
Middle East and Africa Biodegradable Film Market
Biodegradable Packaging
Asia-Pacific Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Europe Biodegradable Film Market
Biodegradable Packaging
Biodegradable Packaging Materials Market
Biodegradable Packaging
Starch-Based Bioplastics Packaging Market
Biodegradable Packaging
Biodegradable Water Bottles Market
Biodegradable Packaging
Clear Bioplastics Packaging Market
Biodegradable Packaging
Biodegradable Food Packaging Market
Biodegradable Packaging
Oxo-Biodegradable Plastic Packaging Market
Biodegradable Packaging
Botanical Packaging Market
Biodegradable Packaging
Global Biodegradable Tableware Market
Biodegradable Packaging
Biopolymer Packaging Market
Biodegradable Packaging
Biodegradable Packaging Products Market
Biodegradable Packaging
Biodegradable Lidding Films Market
Biodegradable Packaging
Biodegradable Packing Peanuts Market
Biodegradable Packaging
Biofoam Packaging Market