
 Bottle Pourers Market | 2026-2036
Bottle Pourers Market Size, Share, and Industry Trends Forecast 2026-2036
Bottle Pourers Market Outlook
Modular bundling of pourers with cleaning brushes and measurement jiggers is repositioning buyer choice away from standalone units. LifeStraw leverages its outdoor-equipment distribution network to cross-sell bartending accessories into camping and glamping retail channels. Brita anchors its position through kitchen-countertop brand recognition that extends into pourer adjacencies. Katadyn Group competes by applying its filtration-engineering heritage to precision-flow mechanisms in professional bar tools.
Bottle pourers are precision dispensing devices, typically machined from stainless steel or food-grade polymers, designed to regulate liquid flow rates through engineered venting channels and tapered spout geometries. Their primary commercial purpose centers on controlled portioning of spirits, oils, and syrups in high-velocity service environments. Stainless steel pourers occupy the premium tier in bartending applications where thermal stability and repeated sanitization cycles matter, while plastic variants dominate high-volume catering procurement where unit cost governs replacement schedules. Measuring pourers represent the fastest-growing type segment as portion-control mandates tighten across chain hospitality operations.
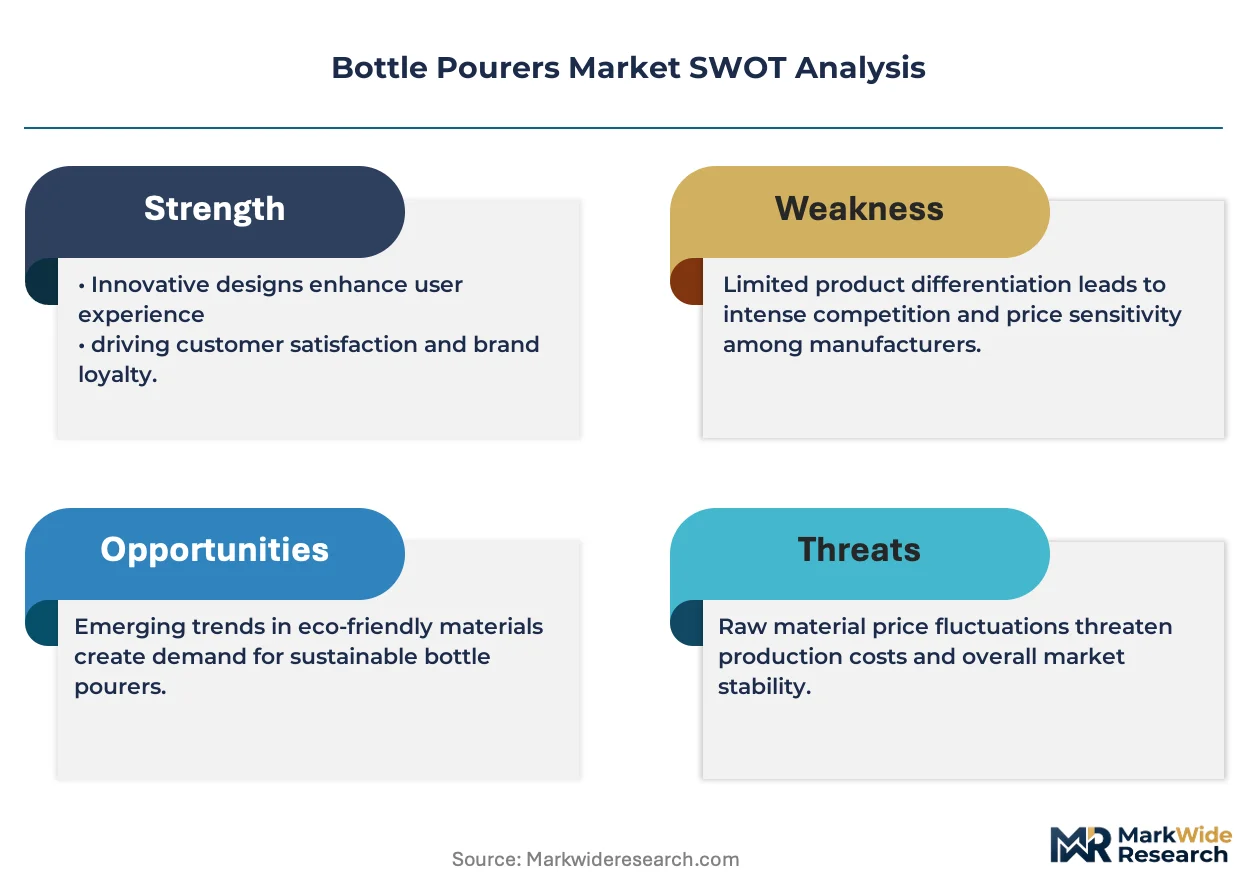
REACH restricts phthalate content in European food-contact plastics, compelling manufacturers to reformulate silicone gaskets and polymer bodies. FDA food-contact notification requirements govern spout materials in United States commercial kitchens, creating compliance friction for imported Asian products. ISO 22000 food safety management certifications increasingly gate access to European Union and North American distributor networks. Stakeholders must monitor evolving PFAS restrictions in polymer coatings, as regulatory scope expansion threatens to obsolete existing material platforms without warning.
Market Dynamics
REACH compliance deadlines and FDA food-contact material rules are forcing simultaneous reformulation of silicone gaskets and polymer bodies across manufacturing footprints, compressing supplier lead times and reshaping procurement criteria in hospitality supply chains.
Growth Catalysts
- Mixology training expansion:Bartending academies in Germany and the United States are embedding precision-pour techniques into certification curricula, institutionalizing demand for engineered flow-control devices.
- ISO 22000 certification requirements:European Union and North American distributors increasingly gate network access behind food safety management credentials, filtering out uncertified suppliers.
- Silicone elastomer advances:Reformulated high-temperature gasket materials now withstand repeated commercial dishwasher cycles without deformation, extending service intervals in high-velocity venues.
Market Restraints
- Stainless steel input volatility:Nickel and chromium price swings compress margin predictability for premium-tier manufacturers dependent on austenitic grades.
- Asian import friction:FDA food-contact notification gaps block substantial volumes of polymer pourers from entering United States commercial channels without reformulation.
- Precision machining bottlenecks:Tapered spout geometries requiring CNC tolerances below 50 microns concentrate production capacity among limited European tool-and-die specialists.
Strategic Opportunities
- Camping and glamping retail channels:Outdoor equipment distributors are cross-merchandising bartending accessories into portable bar setups for experiential hospitality.
- Measuring pourer mandates:Chain hospitality operations in Germany face tightening portion-control requirements, accelerating replacement of free-pour devices with calibrated alternatives.
- PFAS-free coating platforms:Anticipated regulatory scope expansion around perfluorinated compounds creates first-mover advantage for suppliers with compliant polymer formulations.
Industry Challenges
- Sanitization protocol standardization:Divergent commercial dishwasher temperature and chemical specifications across hospitality groups complicate universal product design.
- Legacy inventory obsolescence:Rapid shifts in food-contact material rules strand existing polymer stock in distributor warehouses, forcing write-downs or re-export.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bottle Pourers Market |
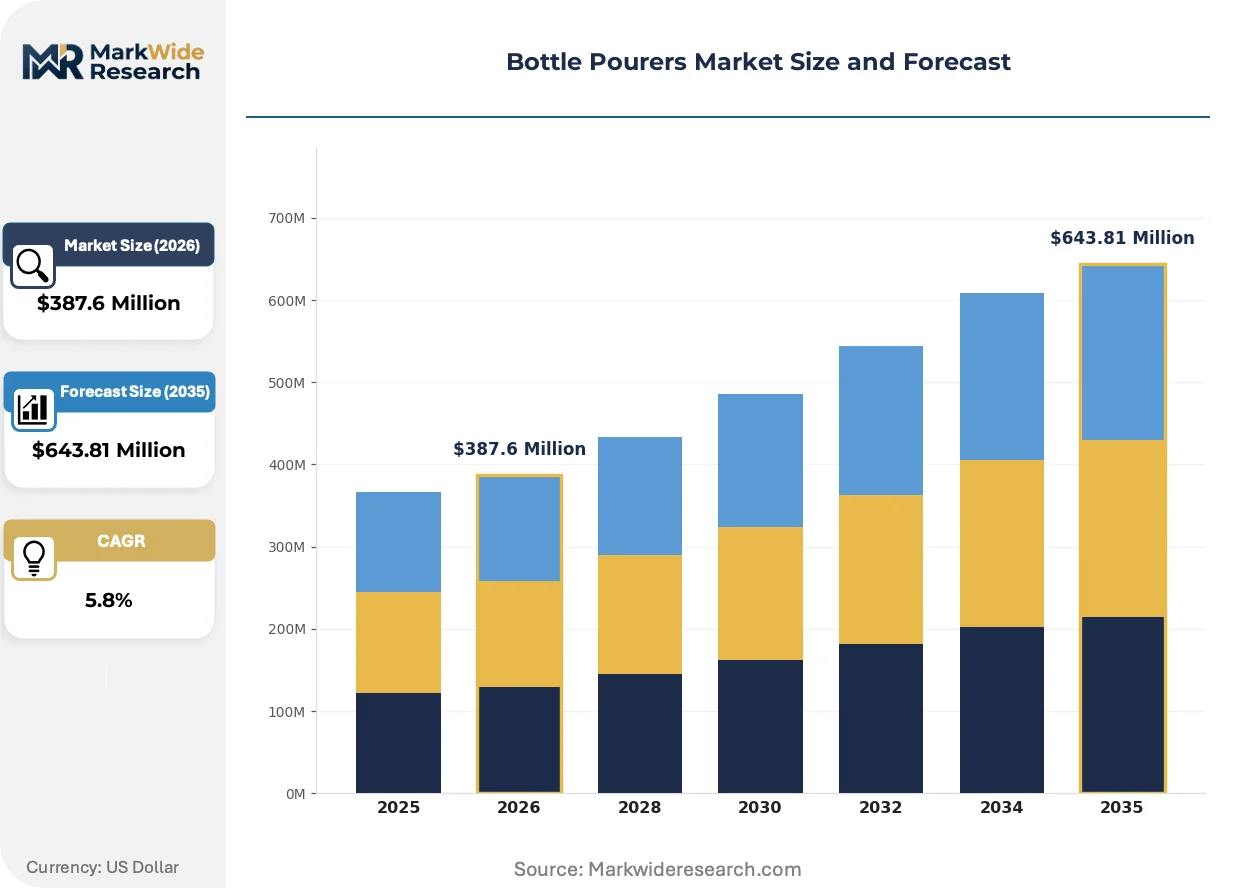
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Non-Drip, Spring-loaded, Spout, Measuring Material: Plastic, Stainless Steel, Glass, Silicone Application: Kitchen, Bartending, Catering, Laboratory Closure Style: Cork, Screw Cap, Flip Top, Pump |
| Companies Covered | Sawyer Products Inc., GRAYL, Cascade Designs Inc., Survivor Filter, Aquamira Technologies Inc., LifeStraw, Brita, Clearly Filtered, Katadyn Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bottle Pourers Market Strategic Shifts
Material science breakthroughs and regulatory pressure are converging to redefine performance benchmarks for precision dispensing devices, with flow-mechanism engineering now inseparable from compliance architecture.
Electropolished stainless steel spout assemblies with laser-etched venting channels are absorbing demand from premium bartending venues seeking thermal stability through rapid temperature cycling. German hotel groups specify these surfaces for their resistance to acidic citrus corrosion and compatibility with high-temperature sanitization protocols. The technology is absorbing market share from chrome-plated brass alternatives that degrade under repeated chemical exposure.
REACH restrictions on phthalate content in food-contact plastics are compelling manufacturers to source bio-based plasticizers for silicone gasket compounds. Reformulation timelines extend 18-24 months for full material qualification, compressing product refresh cycles. German precision-engineering suppliers are responding fastest, leveraging existing polymer laboratories to validate alternatives ahead of enforcement windows.
Chain hospitality procurement departments now bundle pourers with measurement jiggers and cleaning brushes into single-source contracts, collapsing the standalone accessory market. Independent distributors in the United States are losing shelf space to direct manufacturer relationships with national restaurant groups. Germany exhibits the most advanced consolidation, where procurement centralization among hotel alliances has halved vendor counts since 2022.
Bottle Pourers Market Segmentation
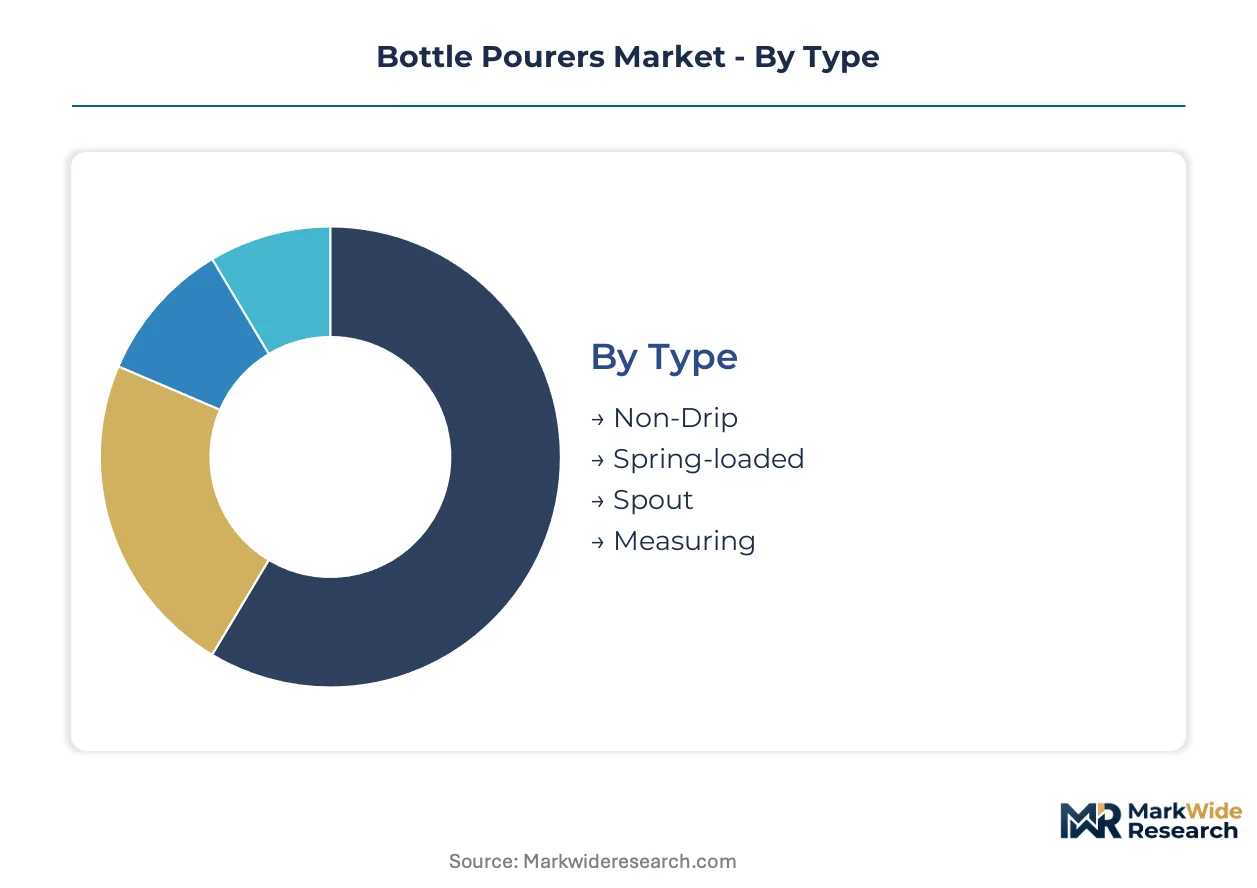
Pourer segmentation separates commodity replacement cycles from premium specification wins. Material and application boundaries determine margin capture, while closure mechanics dictate channel placement and end-user training requirements.
Type:
Volume applications favor simple mechanical designs, while precision service environments extract premium pricing from engineered flow control.
- Measuring:Calibrated internal chambers dispense fixed volumes through tilt-activated valving. German chain hospitality procurement now mandates these devices for portion compliance, displacing free-pour alternatives in regulated venues.
- Non-Drip:Membrane-sealed spout geometries prevent residual dripping through surface tension engineering. High-velocity bartending in United States metropolitan markets drives specification for these mechanisms to protect counter surfaces and reduce waste.
- Spring-loaded:Self-sealing mechanisms activate through bottle tilt angle, enabling one-handed operation during multi-bottle sequences.
- Spout:Basic tapered geometries without flow modulation dominate catering procurement where unit cost governs replacement schedules.
Today's leader: Measuring. Tomorrow's challenger: Non-Drip.
Material:
Cost tier stratification aligns with sanitization intensity and thermal cycling demands across end-use environments.
- Stainless Steel:Austenitic grades with electropolished finishes withstand commercial dishwasher protocols and acidic citrus exposure. German hotel groups specify these surfaces for thermal stability through rapid temperature cycling in premium venues.
- Silicone:High-temperature elastomer compounds now survive repeated sanitization without deformation. REACH phthalate restrictions are accelerating bio-based plasticizer reformulation among European compounders.
- Plastic:Food-grade polymers dominate high-volume catering procurement where replacement frequency exceeds durability concerns.
- Glass:Borosilicate constructions serve laboratory and specialty oil applications requiring chemical inertness and visual clarity.
Stainless steel commands specification authority; silicone compounds are climbing the fastest as gasket and body formulations advance.
Application:
Customer type determines performance thresholds, with professional service environments extracting measurable productivity gains from precision engineering.
- Bartending:Mixology certification programs in Germany and the United States institutionalize precision-pour technique requirements. Flow-rate consistency directly impacts pour-cost accuracy in high-velocity service.
- Catering:Event-service procurement prioritizes unit economics and rapid replacement over extended service intervals. Plastic variants absorb volume demand through disposable-equipment budgeting.
- Kitchen:Home and commercial cooking applications emphasize oil and vinegar dispensing with drip prevention for counter protection.
- Laboratory:Chemical resistance and precise volumetric control govern specification in research and quality-control environments.
Bartending anchors premium positioning; catering sustains volume throughput.
Closure Style:
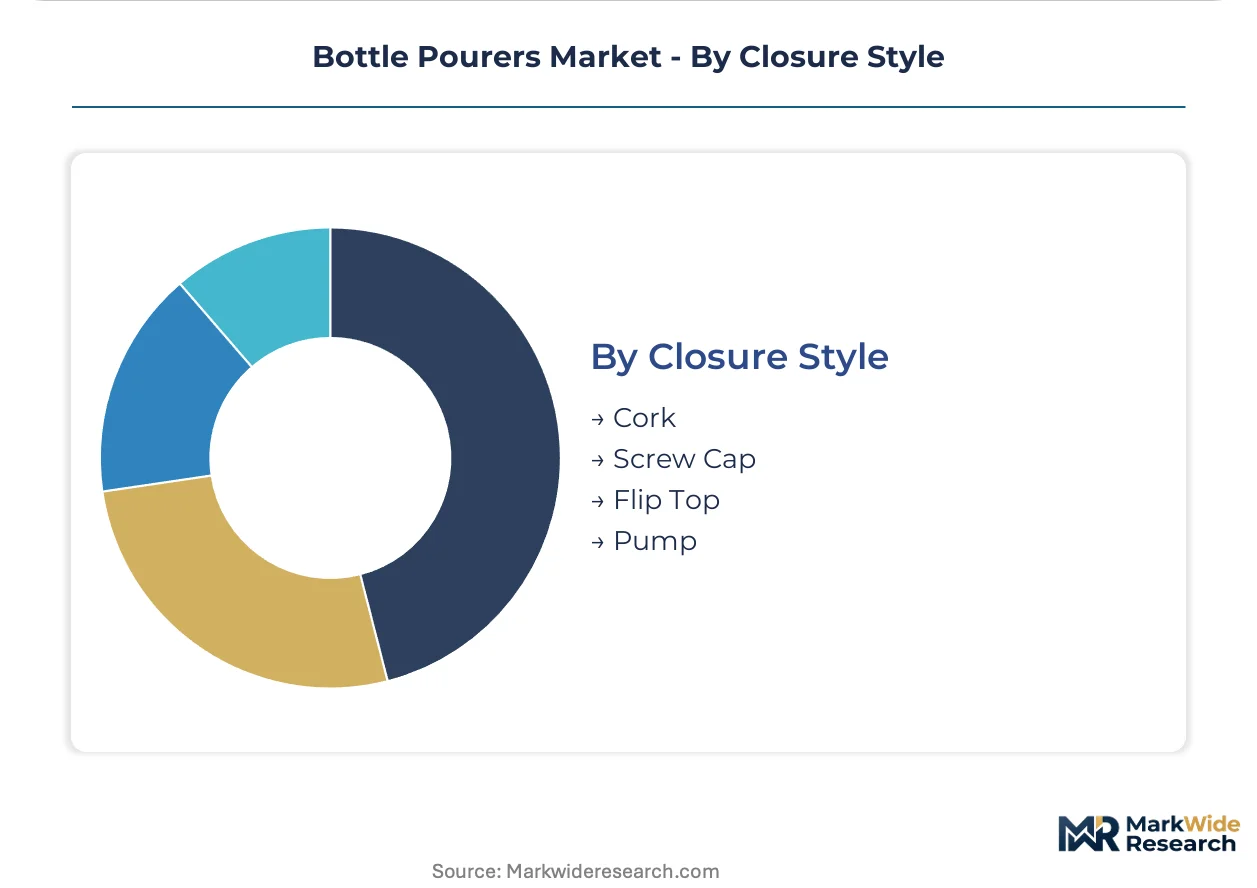
Interface geometry determines compatibility breadth and seal integrity across bottle neck standards.
- Cork:Tapered friction fits conform to traditional wine and spirit bottle necks. European wine-producing regions maintain specification dominance for heritage-format compatibility.
- Screw Cap:Threaded interfaces secure pourers to standardized neck finishes common in spirits and oil packaging. United States retail channels favor these mechanisms for consumer confidence in seal integrity.
- Flip Top:Hinged closures protect spout openings between uses in intermittent-service environments.
- Pump:Pressurized dispensing mechanisms serve high-viscosity syrups and sauces in controlled-portion applications.
Cork retains installed-base dominance; screw cap formats are expanding most quickly through standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bottle pourer manufacturing traces its precision-engineering lineage to German metalworking traditions established in Solingen and Stuttgart during the early twentieth century. These industrial clusters originally supplied machined components for laboratory glassware before adapting tapered spout geometries for hospitality applications. Contemporary demand patterns reflect this heritage while incorporating regulatory pressures from multiple jurisdictions.
Germany
Precision-engineered bar tools command premium positioning in professional venues across Berlin, Munich, and Hamburg. ECHA REACH compliance deadlines force simultaneous reformulation of silicone gaskets and polymer bodies, compressing supplier lead times. The Stuttgart industrial corridor hosts specialized tool-and-die shops capable of CNC tolerances below 50 microns for electropolished stainless steel spout assemblies.
United States
Mixology certification programs in New York and Chicago institutionalize precision-pour technique requirements among bartending academies. FDA food-contact notification requirements govern spout materials in commercial kitchens, creating compliance friction for imported polymer products. The Pacific Northwest outdoor equipment distribution network cross-merchandises bartending accessories into camping and glamping retail channels.
France
Heritage wine-producing regions maintain specification dominance for cork-tapered friction fits conforming to traditional bottle necks. ANSM oversees food-contact material safety assessments alongside evolving EU-wide PFAS restrictions. The Île-de-France hospitality procurement market demonstrates advanced consolidation, with hotel alliances centralizing vendor relationships.
United Kingdom
London metropolitan bartending venues drive specification for non-drip membrane-sealed spout geometries to protect counter surfaces in high-velocity service. Post-Brexit regulatory divergence from REACH creates dual compliance obligations for suppliers serving both UK and EU markets. Midlands-based distributors increasingly gate network access behind ISO 22000 food safety management credentials.
Italy
Commercial kitchen applications in Milan and Rome emphasize oil and vinegar dispensing with drip prevention for counter protection. Lombardy-based manufacturers leverage existing polymer laboratories to validate bio-based plasticizer alternatives ahead of enforcement windows. The Emilia-Romagna packaging cluster supplies standardized neck finishes compatible with screw cap pourer interfaces.
Bottle Pourers Market Competitive Environment
Premium-margin players sit above commodity-margin players across material-grade and certification-tier dimensions. The vendor base separates into stainless steel precision specialists, polymer high-volume fabricators, and outdoor-equipment cross-sellers. Three archetypes dominate: filtration-engineering heritage firms applying flow-control expertise, kitchen-countertop brand recognition extenders, and camping-equipment channel leverage specialists. Competitive moves concentrate on direct manufacturer relationships with national restaurant groups and anticipatory PFAS-free coating platform development.
Among filtration-engineering heritage firms, Katadyn Group exemplifies precision-flow mechanism adaptation from water purification to professional bar tools. LifeStraw occupies a position leveraging outdoor-equipment distribution infrastructure for cross-category bartending accessory placement. Brita anchors the kitchen-countertop brand recognition extension archetype, translating consumer trust into adjacent pourer categories. These three represent distinct competitive vectors without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Sawyer Products Inc. |
| GRAYL |
| Cascade Designs Inc. |
| Survivor Filter |
| Aquamira Technologies Inc. |
| LifeStraw |
| Brita |
| Clearly Filtered |
| Katadyn Group |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap metalworking specialists in Germany's Stuttgart corridor anchor premium-tier supply, translating multi-generational tooling expertise into pricing discipline that resists commoditization. Their ownership structure insulates capacity decisions from quarterly earnings pressure, sustaining investment in CNC tolerances below 50 microns that Asian contract manufacturers cannot replicate without equivalent capital intensity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates electropolished stainless steel assemblies from silicone-gasket polymer bodies and basic catering-grade plastics. Price differentiation hinges on ISO 22000 certification tier and thermal cycling durability specifications. Cost compression in the polymer tier is intensifying because REACH phthalate reformulation timelines extend 18-24 months, stranding pre-compliant inventory. Chain hospitality procurement exhibits the least price sensitivity, while independent catering distributors absorb the most margin pressure.
Supply Chain Analysis
Direct-to-hotel-group channels handle hyperscale buyer demand, collapsing traditional distributor intermediaries in Germany and the United States. Manufacturing concentrates in Germany, Italy's Emilia-Romagna packaging cluster, and select Asian polymer fabrication centers. Raw material flows draw from austenitic stainless steel mills, bio-based silicone elastomer compounders, and food-grade polymer resin suppliers. Single-source vulnerability concentrates in European tool-and-die shops capable of sub-50-micron CNC tolerances, where capacity constraints bottleneck electropolished spout assembly output.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in PFAS-free coating platforms and certified precision-tier positioning, where regulatory anticipation converts compliance investment into pricing power ahead of enforcement windows.
For Market Incumbents: Lock in direct manufacturer relationships with national restaurant groups before procurement centralization completes, while accelerating bio-based plasticizer qualification in existing polymer laboratories to outpace REACH enforcement timelines. Channel control and certification investment defend against Asian import friction threatening polymer-tier margins. For New Entrants and Emerging Players: Launch via outdoor-equipment distribution networks into camping and glamping retail channels, where bartending accessory cross-merchandising remains underdeveloped relative to established hospitality supply chains. The Pacific Northwest and German alpine tourism corridors present the most penetrable white-space for experiential hospitality positioning. For Investors and Strategic Acquirers: Valuations sit cheapest among polymer high-volume fabricators facing inventory obsolescence risk from rapid food-contact material rule shifts. Long-term viability favors stainless steel precision specialists with captive tool-and-die capacity and ISO 22000 credentials already in place. The signal to watch is PFAS regulatory scope expansion announcements from ECHA or EPA, which would trigger immediate repricing of compliant versus non-compliant coating platforms.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Coating Platform Development | Anticipatory compliance with ECHA restrictions creates first-mover pricing power in polymer formulations. |
| Direct Manufacturer Relationships | Bypassing distributors captures margin from consolidating German hotel alliance procurement centralization. |
| Outdoor Equipment Channel Expansion | Cross-merchandising into LifeStraw's camping retail network accesses experiential hospitality growth. |
| ISO 22000 Certification Investment | Food safety credentials gate European Union and North American distributor network access. |
| Silicone Elastomer Reformulation | Bio-based plasticizer validation ahead of REACH deadlines protects existing polymer product lines. |
Study Parameters
Bottom-up hospitality procurement modeling reconciled against top-down manufacturing capacity tracking forms the analytical core. Primary interviews with bartending academy curriculum directors, hotel group procurement officers, polymer laboratory technical directors, and outdoor equipment category managers combined with secondary validation from ECHA regulatory filings, FDA food-contact notification databases, ISO certification registries, and hospitality trade association procurement surveys. Top-down supply-side analysis triangulates against bottom-up demand segmentation across material tiers and application channels.
Input-output matrices map stainless steel mill capacity, polymer compounding throughput, and precision machining utilization against chain hospitality replacement cycles and mixology training program expansion rates. Segmentation dimensions include pourer type, material grade, application environment, closure mechanics, and regional regulatory cluster. CAGRs derive from weighted average of demand-side adoption curves and supply-side capacity constraints across the projection horizon. Forecast inputs incorporate REACH compliance timeline assumptions and PFAS regulatory scope anticipation.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated PFAS restriction scenarios or nickel price volatility spikes. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
PET Bottle Market
Beverage Packaging
Dispensing Carboy Market
Beverage Packaging
Pre-Made Cups Market
Beverage Packaging
Self-Chilling Can Market
Beverage Packaging
Middle East and Africa Soft Drinks Packaging Market
Beverage Packaging
Reservoir Media Bottle Market
Beverage Packaging
Cardboard Flask Market
Beverage Packaging
Beverage Cans Market
Beverage Packaging
Europe Beverage Packaging Market
Beverage Packaging
Bottled Water Packaging Market
Beverage Packaging
Beverage Aluminum Cans Market
Beverage Packaging
Self-Cleaning Bottle Market
Beverage Packaging
Pouring Spout Market
Beverage Packaging
Biotainer Market
Beverage Packaging
Disposable Water Bottle Market
Beverage Packaging
Multicomponent Bottle Market