
 Cup Filler Market | 2026-2036
Cup Filler Market Size, Share, and Industry Trends Forecast 2026-2036
Cup Filler Market Analysis
EU MDR is decoupling equipment certification from legacy CE-only pathways, forcing European cup filler suppliers to absorb new documentation and validation costs. Accutek Packaging leverages its California-based engineering base to sustain FDA-compliant build standards for dairy and nutraceutical clients. Spee-Dee Packaging anchors its competitive position through specialized servo-driven auger systems that dominate North American powder filling applications.
A cup filler is an automated or semi-automated machine that dispenses measured volumes of liquid, powder, or granular product into pre-formed cups or containers, typically achieving fill accuracies within one percent and operating at speeds exceeding 300 units per minute in rotary configurations. These machines serve primary packaging lines across food processing, pharmaceutical dosing, and cosmetic sampling operations where precise volumetric consistency and contamination control are mandatory. Pneumatic technology occupies the largest installed base due to proven reliability in wet and viscous product handling, though electronic filler systems are capturing the fastest growth trajectory as Industry 4.0 integration demands real-time fill weight feedback and recipe-driven changeovers. Food and beverage end users concentrate the dominant revenue pool, while pharmaceutical applications command premium margin positions driven by FDA validation requirements and clean-in-place protocols.
FDA food safety regulations and EU MDR conformity frameworks jointly determine equipment design standards, material traceability, and supplier qualification pathways for cup filler manufacturers serving regulated sectors. OSHA machine guarding standards in the United States and REACH chemical compliance in Europe further constrain material selection and operator interface configurations. Stakeholders must monitor evolving harmonization between FDA hazard analysis requirements and EU food contact material regulations to anticipate dual-certification cost burdens.
Market Dynamics
Rotary servo architectures are displacing pneumatic cup filler systems across dairy and pharmaceutical packaging corridors, compressing changeover times from hours to minutes while forcing incumbent suppliers to absorb reengineering costs or cede installed base to electronic-native competitors.
Growth Catalysts
- EU MDR validation pathways:Medical device packaging mandates under the EU MDR framework are compelling pharmaceutical contract manufacturers to replace legacy cup fillers with certified clean-in-place systems, creating replacement demand across European sterile filling operations.
- China dairy automation corridors:Regional packaging automation accelerates in Hebei and Inner Mongolia processing zones as domestic dairy majors expand UHT and probiotic cup lines to capture premium chilled segment growth.
- Servo-driven auger integration:Powder handling accuracy improvements in nutraceutical dosing applications are pulling electronic filler adoption ahead of pneumatic alternatives in North American contract manufacturing facilities.
Market Restraints
- Stainless steel input volatility:Grade 316L sourcing concentration in Chinese and Indian mill complexes exposes European and North American cup filler fabricators to alloy price swings and extended lead times for hygienic contact surfaces.
- EU MDR documentation burden:Technical file compilation and notified body engagement timelines for medical packaging equipment extend commercialization cycles by eight to fourteen months versus legacy CE-only pathways.
- Pre-formed cup substitution pressure:Thermoform-fill-seal inline systems capture volume in ambient yogurt and dessert applications where flexible packaging economics undercut rigid cup filler throughput advantages.
Strategic Opportunities
- Southeast Asian contract manufacturing zones:Vietnam and Thailand pharmaceutical packaging parks lack domestic cup filler suppliers capable of FDA-compliant build standards, creating import substitution openings for validated equipment vendors.
- Industry 4.0 recipe management:Convergence of OPC-UA connectivity with real-time fill weight feedback enables predictive maintenance contracts and remote diagnostics revenue streams beyond hardware sales.
- Clean-label beverage sampling formats:Single-serve functional drink and kombucha startups in California and Colorado are commissioning compact rotary cup fillers for direct-to-consumer pilot production before scaling to co-manufactured volume.
Industry Challenges
- Servo motion programming expertise scarcity:Electronic filler commissioning requires controls engineers fluent in both packaging mechanics and PLC motion profiles, a skill combination concentrated at OEM headquarters and thinly distributed across field service networks.
- Legacy pneumatic integration friction:Food processors with extensive Allen-Bradley or Siemens pneumatic infrastructures face capital inefficiency when retrofitting electronic cup fillers into existing line control architectures.
- FDA 21 CFR Part 11 validation timeline compression:Pharmaceutical packagers demand electronic record and signature compliance in compressed project windows, stretching supplier documentation and factory acceptance testing resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cup Filler Market |
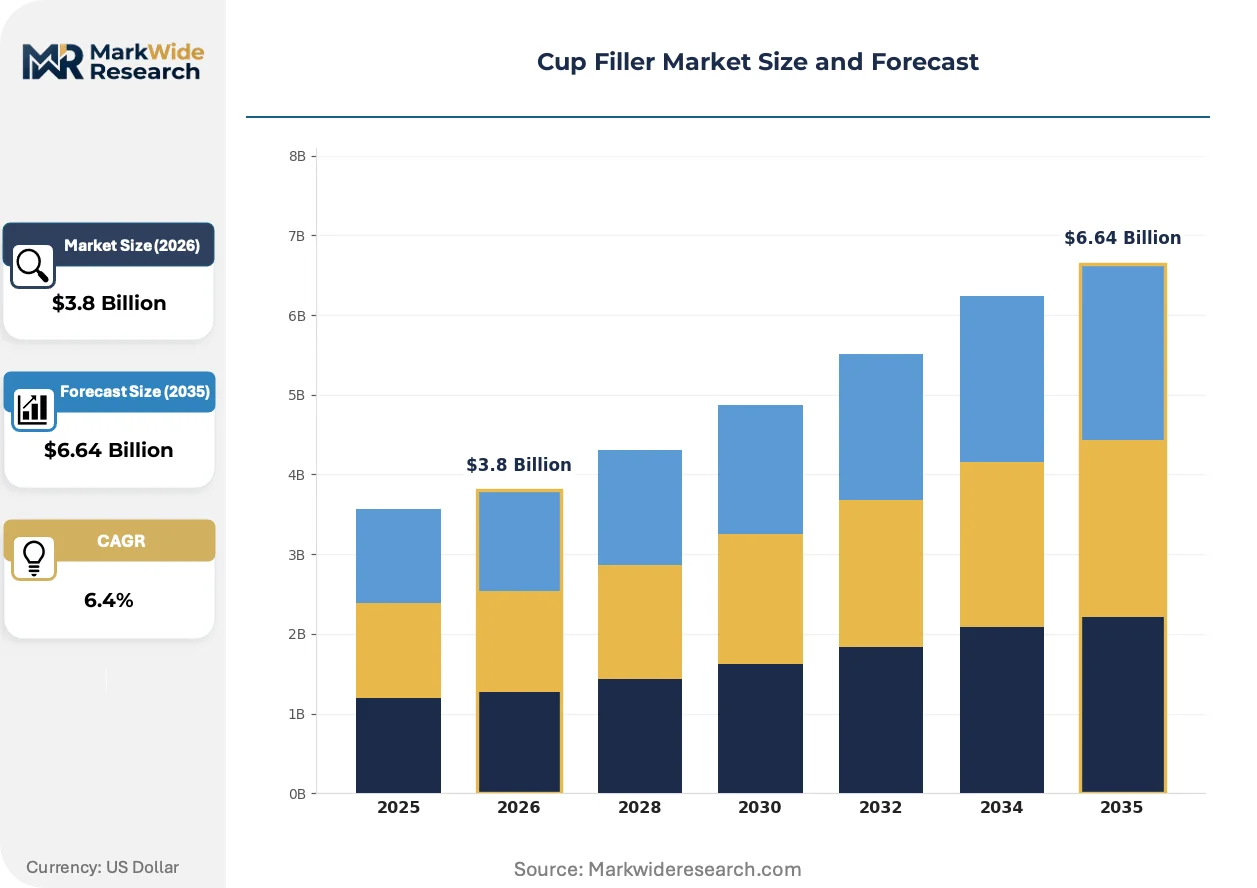
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Fillers, Semi-Automatic Fillers, Manual Fillers, Gravity Fillers End User: Food & Beverage, Pharmaceuticals, Cosmetics, Chemicals Technology: Pneumatic, Mechanical, Electronic, Vacuum Installation: Floor Mounted, Table Top, Wall Mounted, Portable |
| Companies Covered | All-Fill Inc., Spee-Dee Packaging, Tinsley Equipment Company, AMS Filling Systems, Accutek Packaging, Paxiom Group, R.A. Jones, Serac Group, Barry Wehmiller Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cup Filler Market Emerging Trajectories
Electronic control architectures, regulatory data integrity mandates, and buyer procurement model evolution are jointly restructuring competitive position in cup filler supply. Equipment differentiation increasingly hinges on software-enabled service attachment rather than mechanical throughput specifications alone.
Machine vision inspection is converging with cup filler discharge stations to enable real-time seal verification and foreign particle detection without line speed degradation. Dairy processors in Wisconsin and Minnesota are piloting these integrated stations for extended shelf-life yogurt applications. The technology is converging with existing HMI platforms to collapse quality control headcount and reduce downstream rework rates.
EU MDR Annex I general safety and performance requirements now explicitly govern packaging equipment interfacing with sterile medical devices, extending validation scope beyond the cup filler itself to upstream feeding and downstream sealing modules. German and Swiss packaging OEMs are restructuring technical file ownership to accommodate this systems-level liability. Pharmaceutical contract manufacturers in Ireland and the Netherlands now require single-source validation accountability from cup filler suppliers rather than component-level certification.
After-sales service unbundling is accelerating as food and beverage processors separate preventive maintenance contracts from original equipment purchases, enabling third-party service providers to capture recurring revenue from installed electronic filler bases. Large dairy cooperatives in California and Wisconsin are consolidating vendor relationships around regional service response time guarantees rather than OEM brand loyalty. This pattern concentrates service capability investment in proximity to major dairy processing corridors while marginalizing distant OEM branch operations.
Cup Filler Market Segmentation
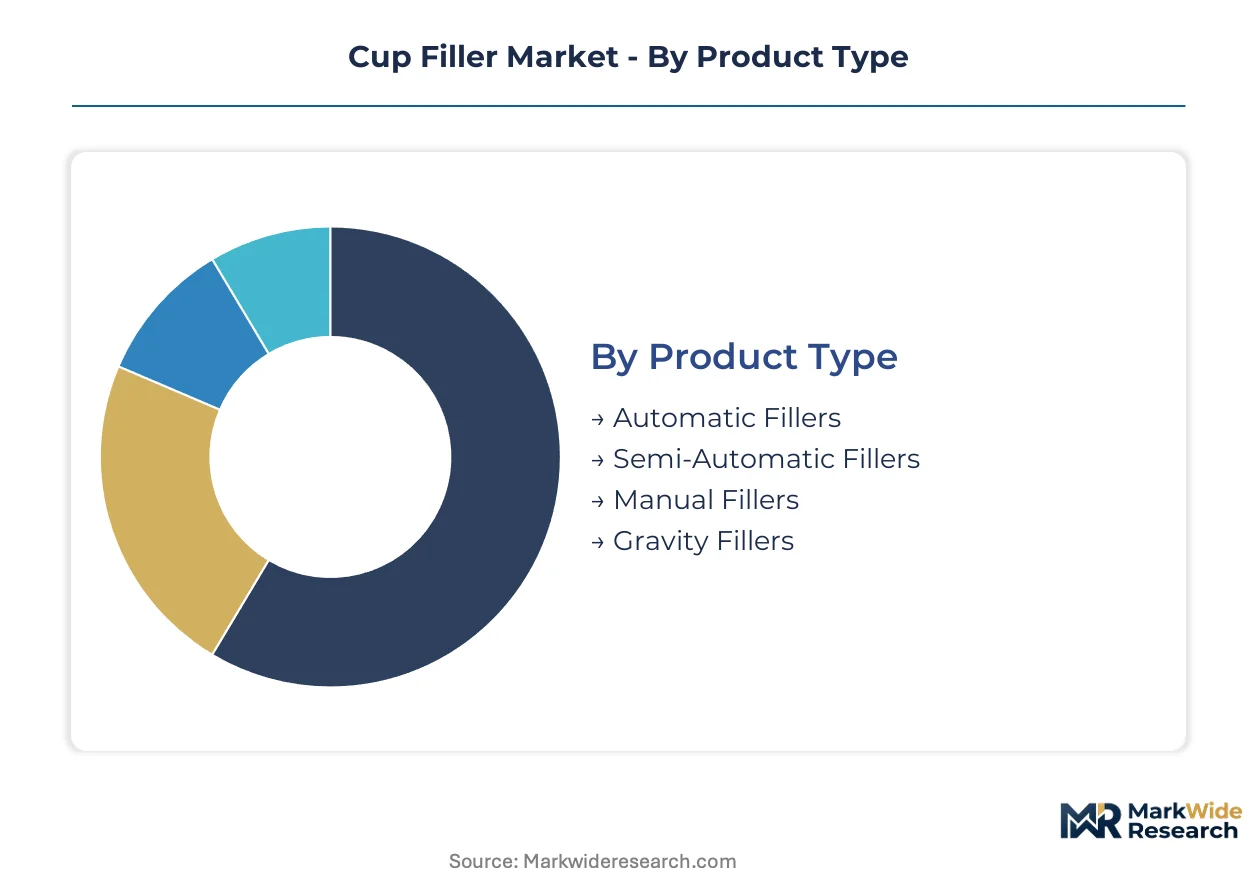
Cup filler procurement decisions hinge on validation requirements that vary sharply across product types and end-use sectors. FDA 21 CFR Part 11, EU MDR, and FSSAI compliance each impose distinct documentation burdens that segment supplier selection and pricing structures.
Product Type:
Automatic fillers carry the heaviest certification load for pharmaceutical and dairy applications, while semi-automatic and manual variants face lighter documentation thresholds in emerging market contract manufacturing.
- Automatic Fillers:Rotary servo architectures achieve fill accuracies within one percent at speeds exceeding 300 units per minute. Demand concentrates in German dairy processing corridors and Wisconsin extended shelf-life yogurt lines where EU MDR and FDA validation mandates compel clean-in-place system adoption.
- Semi-Automatic Fillers:Intermittent motion systems suit mid-volume nutraceutical contract manufacturers balancing throughput flexibility against capital constraints. California kombucha startups and Colorado functional beverage pilots commission these units for direct-to-consumer production before co-manufactured scale-up.
- Manual Fillers:Benchtop volumetric units serve cosmetic sampling and specialty chemical pilot batches where batch record traceability exceeds speed requirements.
- Gravity Fillers:Open-nozzle designs handle thin liquids in non-aseptic food applications with minimal moving parts and reduced maintenance protocols.
Leading the category by volume: Automatic Fillers. Expanding most quickly: Semi-Automatic Fillers.
End User:
Margin structures diverge across end-use sectors, with pharmaceutical applications commanding premium pricing for validation documentation while food and beverage volume concentrates supplier economies of scale.
- Food & Beverage:Dairy processors in Hebei and Inner Mongolia drive rotary cup filler installations for UHT and probiotic lines. FDA hazard analysis requirements and EU food contact material regulations impose dual-certification cost burdens on equipment sourcing.
- Pharmaceuticals:Sterile medical device packaging under EU MDR Annex I extends validation scope to upstream feeding and downstream sealing modules. Irish and Dutch contract manufacturers now demand single-source validation accountability from suppliers.
- Cosmetics:Sampling format production favors compact tabletop installations with rapid changeover capabilities for SKU proliferation in premium skincare.
- Chemicals:Corrosive product handling necessitates Grade 316L contact surfaces with REACH-compliant material traceability for European market access.
Dominating revenue: Food & Beverage. Steepest expansion trajectory: Pharmaceuticals.
Technology:
Installed base composition reflects generational transition pressures, with pneumatic legacy systems defending position in wet product handling while electronic architectures capture specification share in precision dosing applications.
- Pneumatic:Proven reliability in viscous dairy and dessert applications sustains installed base across Midwest dairy cooperatives. Allen-Bradley and Siemens infrastructure integration reduces retrofit friction for incumbent processors.
- Electronic:Servo-driven auger systems dominate North American powder filling with real-time fill weight feedback and recipe-driven changeovers. OPC-UA connectivity enables predictive maintenance revenue streams beyond hardware sales.
- Mechanical:Cam-driven volumetric mechanisms persist in cost-sensitive emerging market installations with limited controls engineering support.
- Vacuum:Negative pressure filling suits fragile granular products and aerated liquids where mechanical compression risks product degradation.
Largest installed base: Pneumatic. Gaining share fastest: Electronic.
Installation:
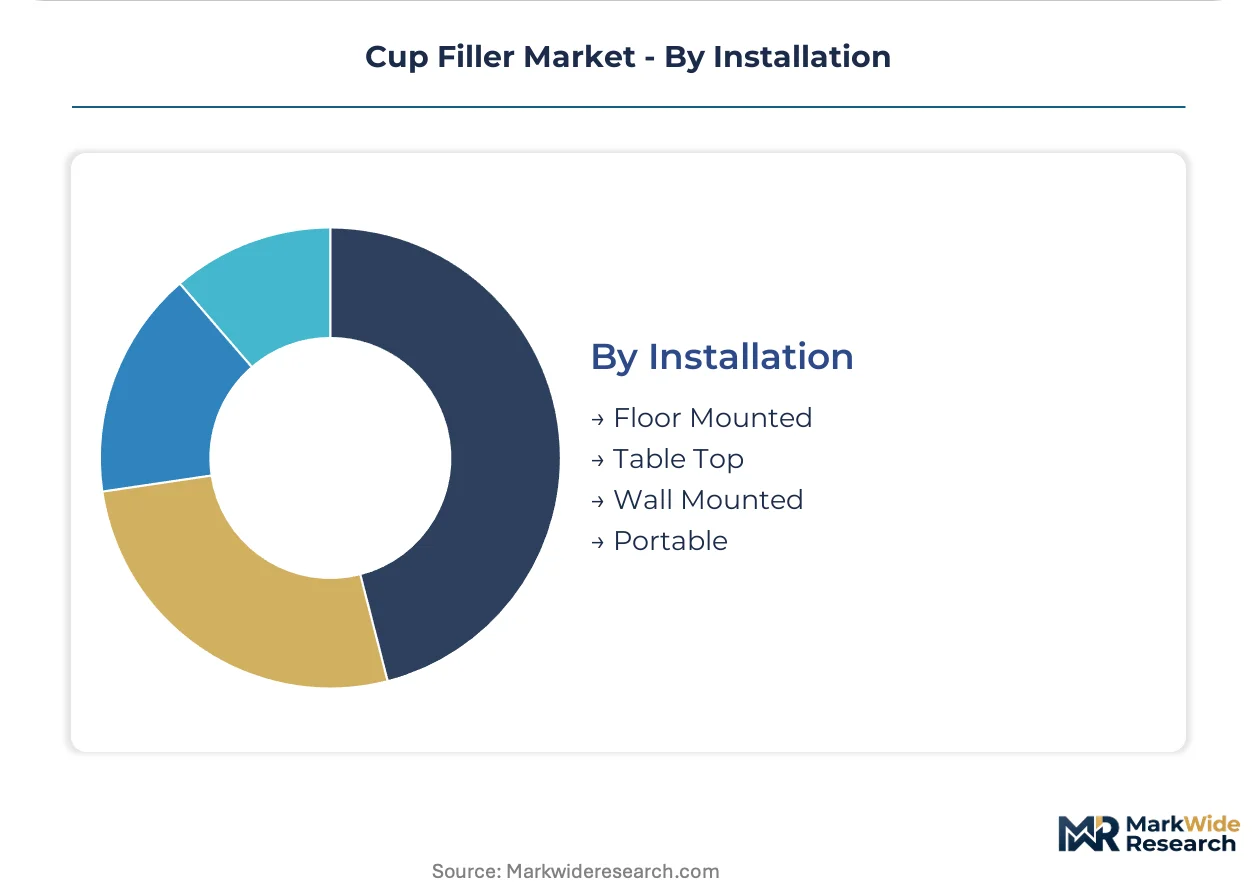
Facility configuration constraints and line integration complexity determine installation mode selection, with floor-mounted systems anchoring high-volume dairy corridors and portable units serving pilot-scale flexibility requirements.
- Floor Mounted:Heavy-duty rotary configurations integrate into automated filling lines across Southeast Asian contract manufacturing zones. Vietnam and Thailand pharmaceutical packaging parks import FDA-compliant build standards from validated equipment vendors.
- Table Top:Compact servo fillers enable clean-label beverage sampling formats in California and Colorado startup facilities with limited production footprints.
- Wall Mounted:Space-constrained cosmetic and chemical operations utilize vertical mounting for gravity-fed product supply with minimal floor space allocation.
- Portable:Castor-mounted units support multi-product contract manufacturers with frequent line reconfiguration and seasonal demand fluctuation.
Standard for high-volume dairy: Floor Mounted. Climbing fastest among craft producers: Table Top.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in German dairy processing corridors and Chinese automation zones, with secondary pull from North American nutraceutical contract manufacturing and Southeast Asian pharmaceutical packaging parks.
United States
FDA 21 CFR Part 11 validation timelines compress project windows for pharmaceutical packagers in New Jersey and North Carolina biotech corridors. California kombucha startups and Colorado functional beverage pilots commission compact rotary cup fillers for direct-to-consumer production before scaling to co-manufactured volume.
Germany
EU MDR Annex I extends validation scope to upstream feeding and downstream sealing modules for sterile medical device packaging. Bavarian and Baden-Württemberg packaging OEMs restructure technical file ownership to accommodate systems-level liability under notified body engagement protocols.
China
Domestic dairy majors expand UHT and probiotic cup lines in Hebei and Inner Mongolia processing zones to capture premium chilled segment growth. SAMR food safety enforcement and GB standards compliance accelerate replacement of legacy pneumatic systems with servo-driven architectures.
Vietnam
Pharmaceutical packaging parks in Ho Chi Minh City and Hanoi lack domestic cup filler suppliers capable of FDA-compliant build standards. Import substitution openings emerge for validated equipment vendors serving contract manufacturers targeting EU and US export markets.
Switzerland
Swissmedic medical device packaging mandates align with EU MDR frameworks, compelling sterile filling operations in Basel and Zurich pharmaceutical clusters to adopt clean-in-place systems. German and Swiss OEMs compete for single-source validation accountability contracts.
Cup Filler Market Vendor Landscape
German and Swiss producers anchor the premium validation tier; Chinese fabricators hold cost-sensitive emerging market positions. The vendor base stratifies across three tiers: multinational packaging groups with full-service validation capabilities, mid-cap specialists in servo-driven powder handling, and regional fabricators serving commodity dairy applications. Consolidation pressure intensifies as electronic architecture adoption forces pneumatic legacy suppliers toward strategic partnerships or technology licensing arrangements.
Among North American packaging specialists, Accutek Packaging and Spee-Dee Packaging exemplify contrasting archetypes within the precision dosing segment. Accutek occupies a position aligned with California-based engineering standards for dairy and nutraceutical compliance, while Spee-Dee anchors the servo-driven auger specialization dominant in powder filling applications. Both represent the migration from pneumatic to electronic control architectures reshaping competitive position in regulated sectors.
| Leading Market Players |
|---|
| All-Fill Inc. |
| Spee-Dee Packaging |
| Tinsley Equipment Company |
| AMS Filling Systems |
| Accutek Packaging |
| Paxiom Group |
| R.A. Jones |
| Serac Group |
| Barry Wehmiller Companies |
| Others |
Supply Flow & Price Mechanics
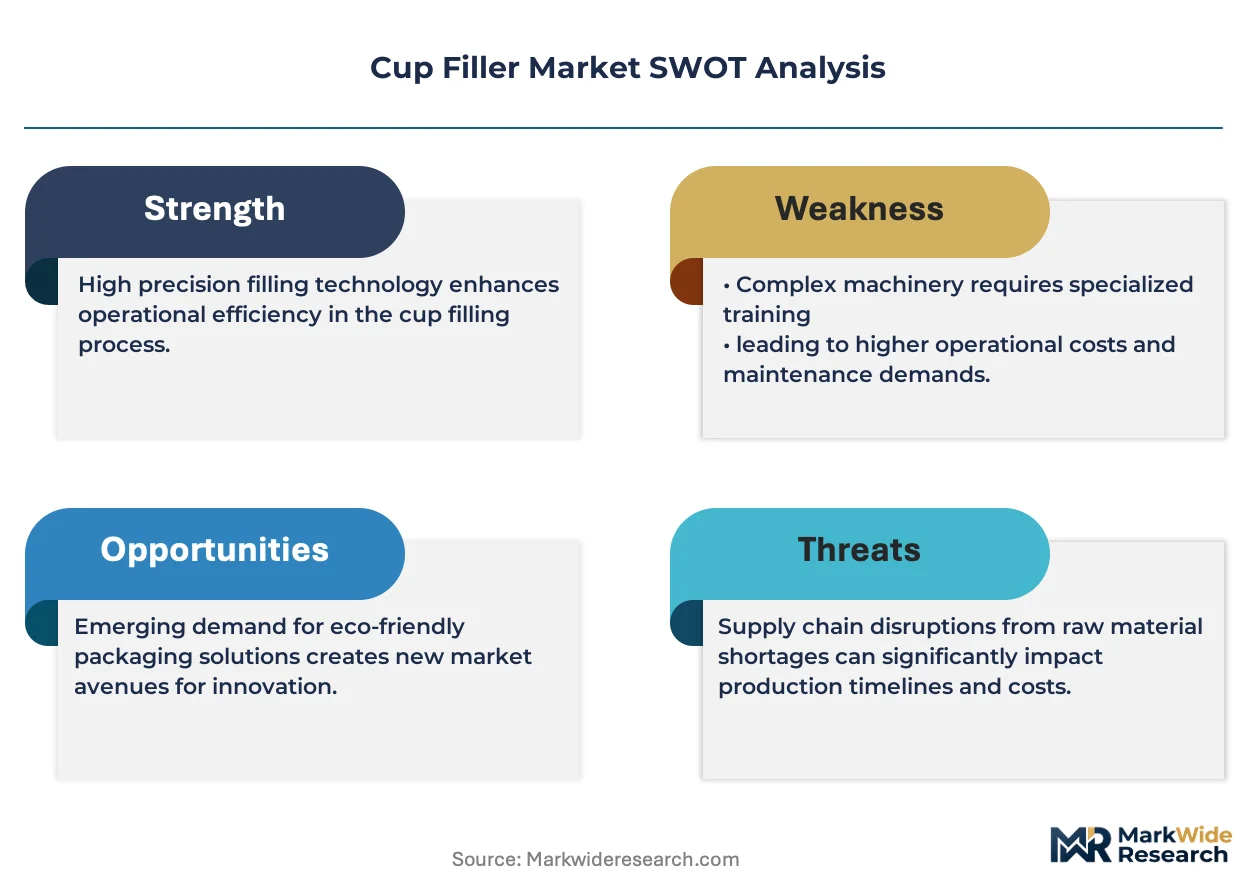
REACH chemical compliance and EU MDR documentation mandates gate qualified supply access for European cup filler fabricators, compressing premium-tier pricing to validated OEMs while spot-market buyers absorb extended lead times and alloy cost pass-throughs from Grade 316L mill concentration.
Pricing Analysis
Short-lead-time premiums separate urgent pharmaceutical line replacements from standard-cycle dairy equipment procurement, with spot inventory discounts available for semi-automatic units in emerging market corridors. Three-tier pricing structure across FDA-validated premium, CE-standard mid-tier, and economy pneumatic legacy levels reflects certification burden differentiation. Pricing pressure stems from thermoform-fill-seal substitution in ambient yogurt applications. Contract manufacturers exhibit highest price sensitivity; sterile medical device packagers absorb premium validation costs without volume negotiation.
Supply Chain Analysis
Refurbishment flows for electronic servo modules create secondary supply channels as dairy cooperatives unbundle after-sales service from original equipment purchases. Grade 316L stainless steel draws from Chinese and Indian mill complexes, servo motors from German and Japanese precision manufacturers, and control systems from Allen-Bradley and Siemens infrastructure. Single-source vulnerability concentrates in hygienic contact surface alloys exposed to commodity price swings. Distribution runs through OEM direct sales for pharmaceutical validation accounts and regional distributor networks for food and beverage volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR Annex I systems-level liability requirements erect a cost-of-compliance moat that consolidates supplier tiers around validated OEMs capable of single-source technical file ownership.
For Market Incumbents: Hedge pneumatic installed base erosion by licensing electronic servo architectures from specialized motion control partners rather than absorbing full reengineering costs. Acquire field service capabilities in Wisconsin and California dairy corridors before third-party providers capture recurring maintenance revenue from unbundled contracts. For New Entrants and Emerging Players: Enter via FDA-compliant build standards for Vietnam and Thailand pharmaceutical packaging parks lacking domestic validated suppliers. Target Southeast Asian contract manufacturers serving EU and US export markets with compact rotary servo fillers. Pursue direct technical file partnership with German notified bodies to compress validation timelines. For Investors and Strategic Acquirers: Consolidation of dairy cooperative vendor relationships around regional service response guarantees is the leading indicator that proximity-based service capability commands premium valuation multiples. Five-to-ten year viability favors mid-cap specialists with servo-driven auger expertise over pneumatic legacy suppliers facing technology licensing dependency. Monitor EU MDR notified body engagement queue lengths as inflection signal for validation bottleneck severity.| Strategic Initiative | Industry Significance |
|---|---|
| OPC-UA Platform Integration | Enables predictive maintenance contracts beyond hardware sales for dairy processors. |
| Servo Architecture Licensing | Accelerates electronic filler commercialization for pneumatic legacy suppliers facing displacement. |
| Regional Service Capability Buildout | Captures unbundled maintenance revenue as California cooperatives consolidate vendor relationships. |
| Clean-in-Place System Certification | Satisfies EU MDR Annex I requirements for Irish and Dutch pharmaceutical contract manufacturers. |
| Machine Vision Inspection Convergence | Collapses quality control headcount for Wisconsin extended shelf-life yogurt applications. |
Methodological Framework
Trade publications, customs filings, and SEC equipment manufacturer disclosures formed the secondary backbone, supplemented by primary interviews with dairy processing plant engineers, pharmaceutical packaging operations directors, OEM procurement managers, and aftermarket service heads. Bottom-up triangulation across installed base estimates and top-down validation against capital expenditure disclosures anchored volume and value outputs.
Historical trendline analysis across rotary and inline configuration shipments informed the projection framework, with segmentation modeling across automatic, semi-automatic, and manual product tiers; food and beverage, pharmaceutical, cosmetic, and chemical end-use sectors; pneumatic, electronic, mechanical, and vacuum technology types; and floor-mounted, tabletop, wall-mounted, and portable installation modes. CAGRs derived from regression analysis of replacement cycle compression and regulatory-driven upgrade demand, with specific inputs including EU MDR validation timeline extensions and SAMR enforcement acceleration in Chinese dairy corridors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under stainless steel alloy price volatility and thermoform-fill-seal substitution acceleration. Practitioners should monitor notified body queue lengths and Grade 316L mill capacity utilization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Sugarcane Bottles Market
Beverage Packaging
Graduated Sample Bottle Market
Beverage Packaging
Bottle Shippers Market
Beverage Packaging
Vending Cups Market
Beverage Packaging
Skep Bottle Market
Beverage Packaging
Bottle Pourers Market
Beverage Packaging
Foldable Bottles Market
Beverage Packaging
Bomber Bottles Market
Beverage Packaging
Fruit Juice Packaging Market
Beverage Packaging
Ice Transport Buckets Market
Beverage Packaging
Cardboard Flask Market
Beverage Packaging
Global Beverage Container Market
Beverage Packaging
Europe Beverage Container Market
Beverage Packaging
Pouring Spout Market
Beverage Packaging
Insulated Cup Sleeves Market
Beverage Packaging
Water Bottle Racks Market