
 French Square Bottle Market | 2026-2036
French Square Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
French Square Bottle Market Foresight
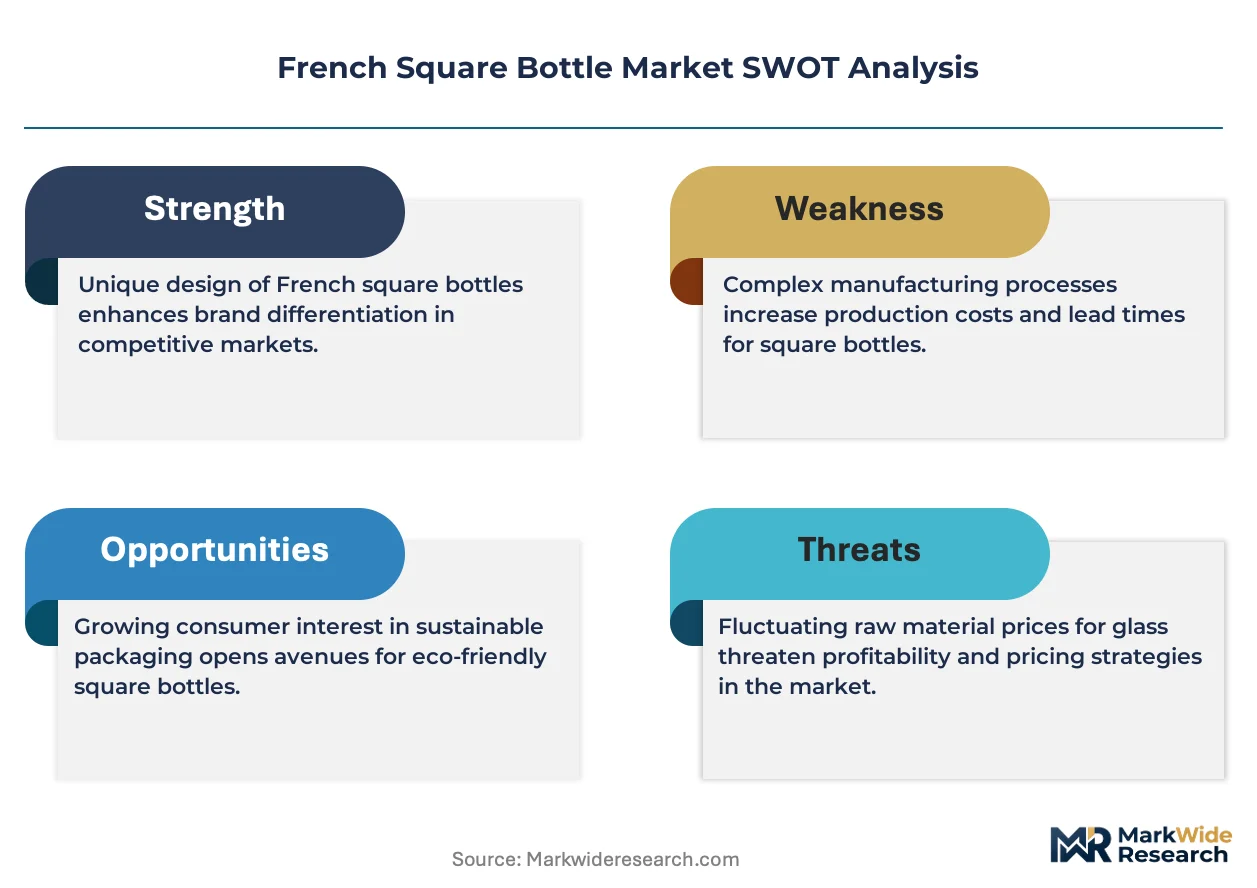
The blow-molding automation gap is rotating capital toward integrated glassworks. Owens-Illinois leverages its furnace scale to dominate pharmaceutical-grade borosilicate output. Berlin Packaging anchors European distribution through its multi-material sourcing platform. DURAN Group GmbH specializes in laboratory-certified French square formats for analytical chemistry.
A French square bottle features four equal vertical faces with sharp 90-degree corners, typically manufactured from soda-lime glass, borosilicate glass, or polyethylene terephthalate through IS machine blow-and-blow or injection stretch blow molding processes. Its geometric profile maximizes palletization density and shelf-facing area for premium branding in cosmetics and spirits. Glass material commands the highest margin pools in perfume and pharmaceutical segments where chemical inertness and barrier properties justify unit premiums. The 100ml and 250ml capacity tiers lead volume in fragrance and skincare applications, while 500ml and 1L formats expand fastest in homecare refills and food condiments. Screw cap and pump dispenser closures concentrate in mass-market personal care, whereas cork and dropper configurations dominate luxury perfume and serum positioning.
ANSM enforces material traceability for pharmaceutical contact packaging under France's national pharmacopoeia, while REACH governs substance restrictions across EU-sourced polymers and coatings. ECHA's evolving SVHC candidate list is forcing reformulation of decorative coatings and UV-cured inks on glass surfaces. Stakeholders must monitor regulatory divergence between France's national pharmacy rules and harmonized EU medical device regulations as MDR implementation reshapes packaging qualification pathways for drug-device combinations.
Market Dynamics
ANSM's material traceability mandates are compressing supplier qualification timelines while Île-de-France cosmetics houses demand shorter batch-release cycles, forcing integrated glassworks to embed laboratory certification capabilities directly into furnace operations.
Growth Catalysts
- Pharmaceutical serialization rules:France's national pharmacopoeia now requires unit-level traceability for primary packaging, pulling borosilicate French square formats into chronic medication dispensing.
- Provence-Alpes-Côte d'Azur fragrance cluster:Niche perfume houses in Grasse are specifying custom-embossed glass with UV-cured ceramic decoration for limited editions, expanding premium SKU counts.
- Homecare refill economics:PET French square bottles at 500ml and 1L capacities are capturing shelf space in French mass retail as concentrated formulas reduce per-use packaging cost.
Market Restraints
- Energy cost volatility:Natural gas prices for glass furnace operations in northern France have compressed margin pools at mid-scale IS machine operators unable to hedge long-term.
- Borosilicate supply concentration:Pharmaceutical-grade tubing production clusters in Germany and Switzerland, creating import dependency for ANSM-certified drug packaging.
- Decorative coating reformulation:ECHA's SVHC candidate list expansion is forcing removal of certain UV stabilizers from glass surface treatments, extending qualification timelines.
Strategic Opportunities
- Occitanie wine and spirits:AOC-designated producers are adopting heavy-base French square bottles for premium digestif positioning, displacing traditional Burgundy shapes.
- MDR convergence:The EU Medical Device Regulation is creating dual-use packaging pathways where drug-device combination products require French square formats with integrated dosing mechanisms.
- Direct-to-brand digital sampling:Cosmetics houses are bypassing traditional distribution to ship 30ml French square serum bottles through subscription platforms, capturing first-party consumer data.
Industry Challenges
- Colorimetric matching expertise:The scarcity of technicians capable of reproducing heritage glass tints across furnace campaigns is extending custom color development to 16-week lead times.
- Furnace reconfiguration capex:Converting soda-lime capacity to borosilicate output requires €40-60 million per line, straining balance sheets of family-owned glassworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | French Square Bottle Market |
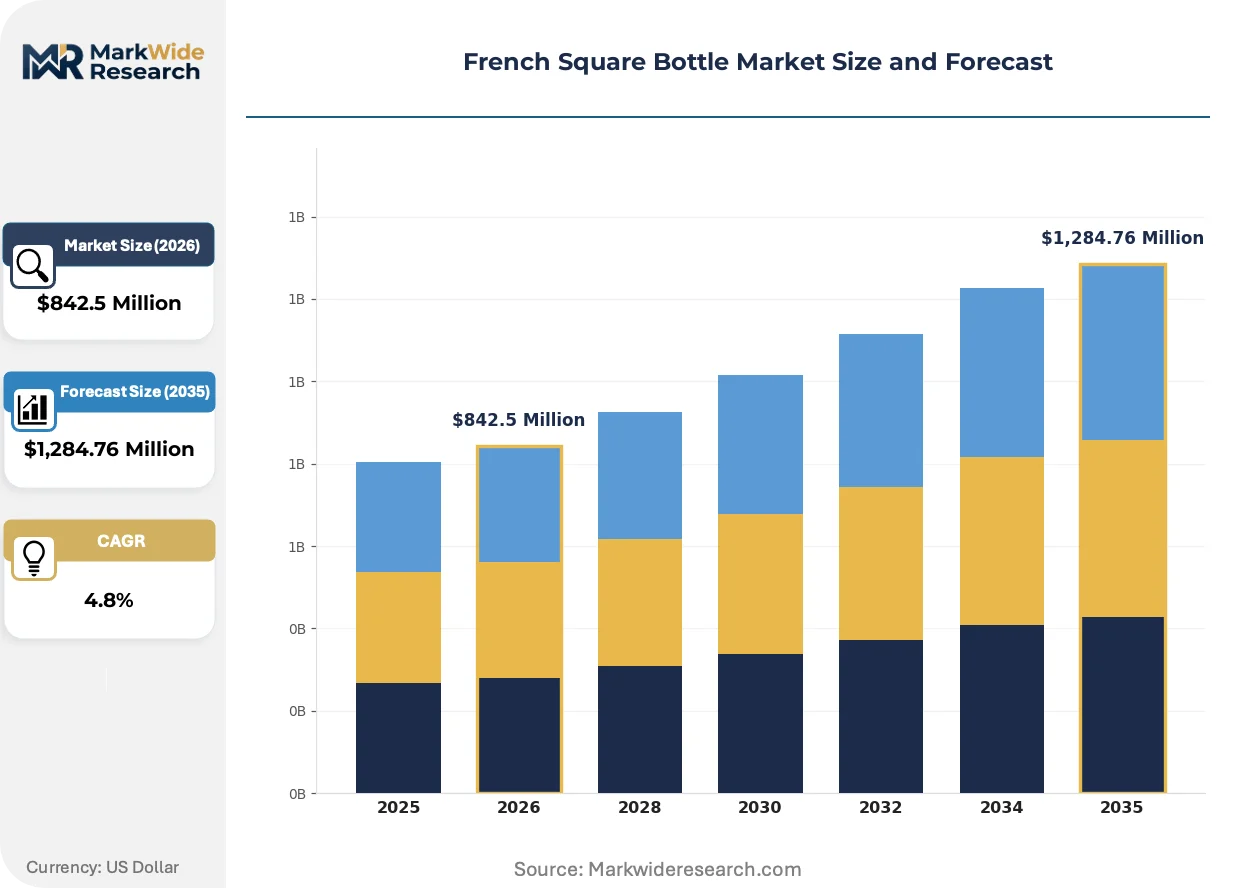
| Market Size in 2026 | $842.5 Million |
| Market Size in 2035 | $1,284.76 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Glass, Plastic, Metal, Ceramic, Composite Capacity: 100ml, 250ml, 500ml, 1L, 2L End Use Industry: Perfume, Pharmaceuticals, Cosmetics, Food & Beverage, Homecare Closure Type: Screw Cap, Cork, Flip Top, Dropper, Pump Dispenser |
| Companies Covered | Owens-Illinois, Berlin Packaging, Sartorius AG, DURAN Group GmbH, Merck KGaA, Container and Packaging, O.Berk, United States Plastic, Bioswisstec AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
French Square Bottle Market Shifts & Advancements
Digital printing and furnace analytics are compressing the traditional mold-to-shelf timeline for decorated glass packaging, while regulatory data requirements are embedding traceability hardware into bottle design specifications.
Thin-walled borosilicate forming is decomposing the traditional thick-wall standard for laboratory French square bottles. Analytical chemistry contract labs in Lyon and Strasbourg are adopting these formats to reduce shipping weight and thermal mass. This shift is decomposing the historical margin premium attached to heavy-wall heritage designs.
REACH substance restrictions are forcing systematic reformulation of decorative coatings and UV-cured inks applied to glass surfaces. French packaging decorators are migrating to water-based ceramic inks with lower volatile organic compound profiles. The perfume segment, where surface aesthetics command price premiums, is absorbing the longest qualification delays.
Buyer consolidation among French pharmacy chains is compressing supplier negotiation cycles and unbundling decoration services from bottle supply. Regional cooperatives in Brittany and Normandy are aggregating procurement for generic medication packaging, displacing direct relationships between individual manufacturers and glassworks.
French Square Bottle Market Segmentation
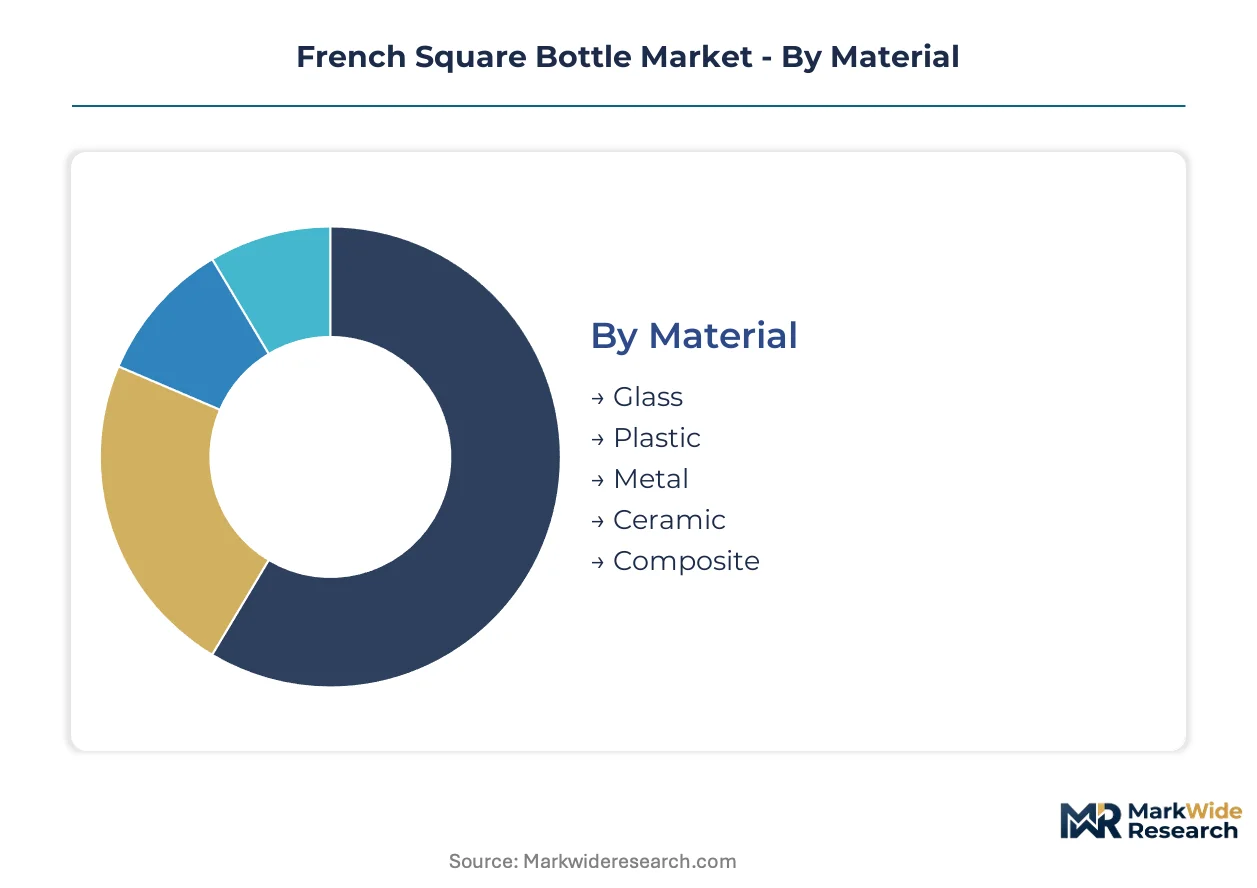
French square bottle demand fragments across material grades and capacity tiers that map to distinct channel economics. Pharmaceutical serialization rules and cosmetics refill platforms are reshaping which segments capture margin versus volume.
Material:
Glass commands pharmacy and perfume channels where ANSM traceability requirements disqualify polymer alternatives, while PET flows through mass retail homecare aisles where unit cost drives shelf placement decisions.
- Glass:Soda-lime and borosilicate compositions dominate Île-de-France fragrance houses and ANSM-certified pharmaceutical packaging. Furnace-scale producers embed laboratory certification directly into production lines to compress supplier qualification timelines.
- Plastic:PET injection stretch blow molding captures 500ml and 1L homecare refill formats in French mass retail. Concentrated formula trends reduce per-use packaging cost and expand shelf-facing economics for private label brands.
- Metal:Aluminum French square formats serve specialty spirits and limited-edition cosmetics where weight differentiation supports premium positioning. Occitanie AOC producers specify heavy-base variants for digestif applications.
- Ceramic:Glazed stoneware variants appear in artisanal skincare and home fragrance segments where tactile surface properties justify unit premiums above glass equivalents.
- Composite:Glass-PET hybrid constructions with decorative outer shells address sustainability messaging requirements for cosmetics subscription platforms shipping direct-to-consumer.
Glass dominates installed base in value terms. Plastic is where expansion concentrates for volume-driven homecare refill economics.
Capacity:
Volume tiers align with dosing conventions and retail format constraints, with smaller formats capturing pharmacy compliance requirements and larger sizes enabling concentrated formula economics.
- 100ml:Standard serum and perfume travel formats specified by Grasse niche houses for limited edition releases. UV-cured ceramic decoration extends qualification timelines but supports price premiums.
- 250ml:Core skincare and fragrance tier where shelf-facing area maximizes brand visibility in Sephora and Marionnaud retail fixtures. Glass retains dominance despite PET inroads.
- 500ml:Homecare refill sweet spot where concentrated dish and laundry formulations reduce per-use cost. PET blow-molding automation gaps rotate capital toward integrated glassworks for premium positioning.
- 1L:Food condiment and bulk homecare applications expanding fastest in French hypermarket channels. Screw cap closures concentrate here for mass-market personal care.
- 2L:Industrial and institutional cleaning supply formats where palletization density outweighs premium branding requirements.
100ml and 250ml command value concentration. 500ml and 1L are climbing the fastest as refill economics reshape household purchasing patterns.
End Use Industry:
Regulatory intensity and decoration complexity create divergent margin pools across applications, with pharmaceutical serialization forcing hardware investments that cosmetics brands avoid.
- Perfume:Grasse cluster houses specify custom-embossed glass with heritage tint reproduction requiring scarce colorimetric technicians. ECHA SVHC restrictions on UV stabilizers extend coating qualification timelines.
- Pharmaceuticals:ANSM unit-level traceability mandates pull borosilicate formats into chronic medication dispensing. Regional pharmacy cooperatives in Brittany and Normandy aggregate procurement, compressing negotiation cycles.
- Cosmetics:Direct-to-brand digital sampling bypasses traditional distribution, with 30ml serum bottles shipped through subscription platforms capturing first-party consumer data.
- Food & Beverage:Occitanie wine and spirits producers adopt French square profiles for premium digestif positioning, displacing traditional Burgundy bottle shapes in AOC-designated ranges.
- Homecare:Concentrated formula trends enable PET 500ml and 1L formats to capture shelf space in Carrefour and E.Leclerc mass retail channels.
Pharmaceuticals and perfume dominate value capture. Homecare is gaining share fastest as refill economics penetrate mass-market purchasing.
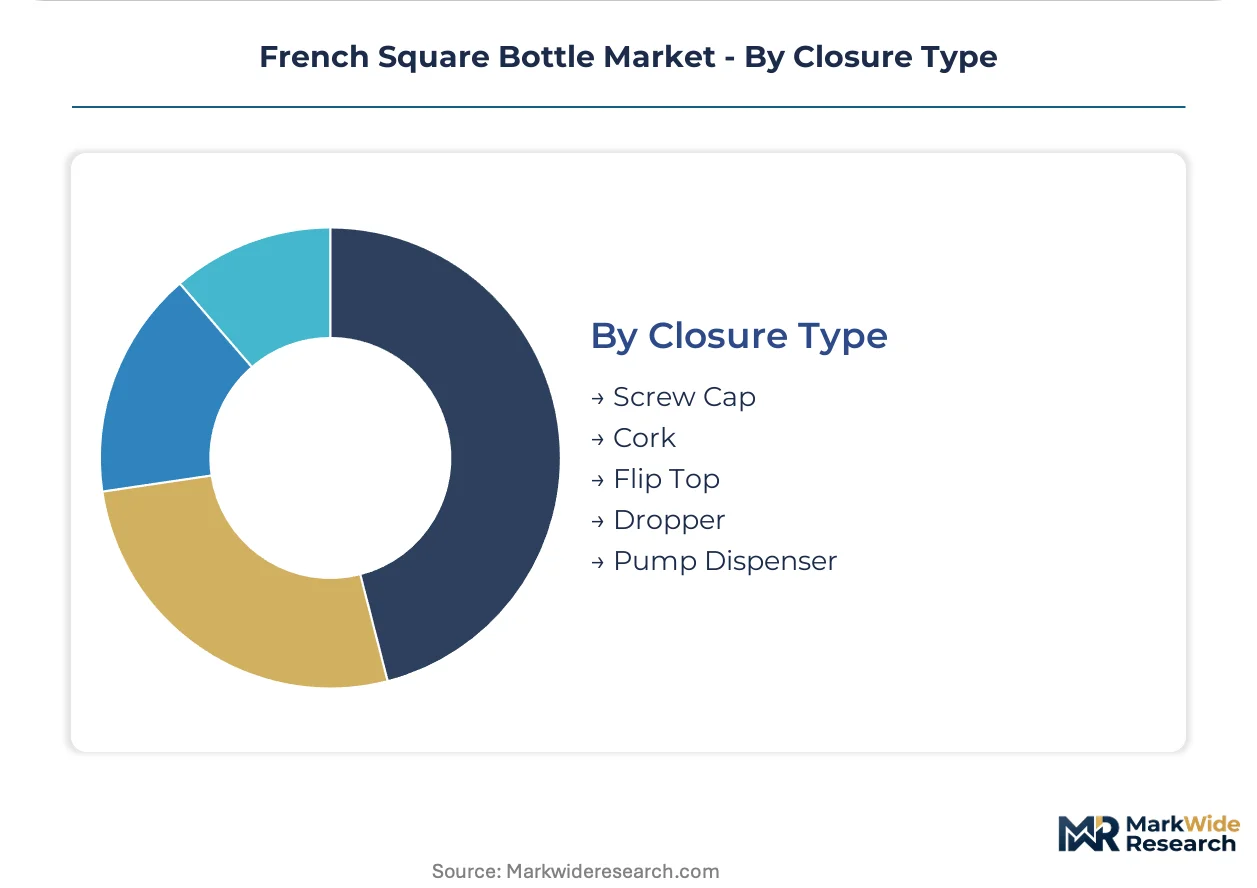
Closure Type:
Mechanism selection tracks price tier and dosing precision requirements, with pump and dropper formats commanding premiums in serum applications versus commodity screw caps in homecare.
- Screw Cap:Mass-market standard for homecare refills and food condiments where cost minimization outweighs user experience differentiation.
- Cork:Luxury perfume positioning in Grasse heritage houses where natural material authenticity supports storytelling and price architecture.
- Flip Top:Convenience-driven personal care applications in travel and gym segments where single-handed operation matters.
- Dropper:Precision dosing for facial serums and essential oils where controlled dispensing justifies glass pipette construction.
- Pump Dispenser:Skincare and haircare formats where airless design extends product shelf life and supports premium pricing in pharmacy channels.
Screw cap dominates unit volume. Pump dispenser and dropper configurations are where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France exports specialty glass French square bottles to neighboring EU markets while importing pharmaceutical-grade borosilicate tubing from Germany and Switzerland. This trade pattern concentrates value-added finishing in French glassworks while upstream material supply remains cross-border dependent.
France
ANSM traceability mandates for pharmaceutical packaging pull borosilicate French square formats into chronic medication dispensing. REACH substance restrictions force reformulation of UV-cured decorative coatings on glass surfaces. The Île-de-France and Provence-Alpes-Côte d'Azur clusters concentrate perfume and cosmetics demand, with Grasse niche houses specifying custom-embossed heritage tints.
Germany
Pharmaceutical-grade borosilicate tubing production serves as the primary import source for French drug packaging manufacturers. BfArM pharmacovigilance standards align with ANSM requirements, easing cross-border qualification pathways. Specialized glassworks in Bavaria and Baden-Württemberg maintain furnace certification for laboratory-grade French square formats.
Switzerland
Swissmedic pharmaceutical regulations drive precision standards for borosilicate container exports into French supply chains. The country's chemical-pharmaceutical cluster around Basel supplies high-purity glass tubing with documented batch lineage. Swiss converters specialize in small-volume custom runs for French cosmetics houses requiring rapid turnaround.
Italy
Luxury fragrance packaging demand from Lombardy and Piedmont cosmetics brands competes with French producers for decorative glass capacity. Italian glassworks leverage furnace scale for UV-cured ceramic decoration on French square profiles. The country's national pharmacopoeia maintains equivalence with French ANSM standards for pharmaceutical contact materials.
Spain
Mass retail homecare refill platforms in Madrid and Barcelona source PET French square bottles from French converters for concentrated formula distribution. Spanish pharmacy cooperatives aggregate procurement for generic medication packaging, following ANSM-equivalent AEMPS traceability guidelines. The country's logistics hubs serve as distribution nodes for French-manufactured glass into Iberian markets.
French Square Bottle Market Competitive Landscape
Concentration sits with furnace-scale glassworks and multi-material distribution platforms. The market structure tiers between integrated producers with captive borosilicate capacity and specialized decorators serving fragrance houses. Three archetypes dominate: furnace-scale integrated glassworks, multi-material sourcing platforms, and laboratory-certified specialists. Competitive moves center on furnace reconfiguration capex for borosilicate conversion and embedding laboratory certification into production lines.
Within the furnace-scale tier, Owens-Illinois and DURAN Group GmbH exemplify divergent specialization vectors. Owens-Illinois leverages furnace scale for pharmaceutical-grade output, while DURAN Group GmbH anchors laboratory-certified formats for analytical chemistry. Berlin Packaging occupies the multi-material sourcing platform archetype, coordinating European distribution across glass and polymer alternatives.
| Leading Market Players |
|---|
| Owens-Illinois |
| Berlin Packaging |
| Sartorius AG |
| DURAN Group GmbH |
| Merck KGaA |
| Container and Packaging |
| O.Berk |
| United States Plastic |
| Bioswisstec AG |
| Others |
Supply & Pricing Matrix
PET substitution for glass in homecare refill formats is simultaneously shifting production geography toward injection stretch blow molding clusters in northern France and compressing unit economics at mid-scale integrated glassworks unable to match cycle times. This material transition concentrates pricing power with furnace-scale operators serving ANSM-certified pharmaceutical channels while eroding margins in undifferentiated mass retail tiers.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the French square bottle market. Price differentiation rests on certification grade and volume scale, with ANSM-traceable borosilicate formats commanding substantial premiums over soda-lime alternatives. Cost compression in PET homecare tiers is intensifying because concentrated formula trends reduce per-use packaging cost. Regional pharmacy cooperatives exhibit highest price sensitivity, whereas Grasse fragrance houses prioritize heritage tint reproduction over unit cost.
Supply Chain Analysis
Inventory lead times for custom-embossed glass with UV-cured ceramic decoration now extend to sixteen weeks due to scarce colorimetric technician availability. Supply concentrates in France for finished glass conversion, Germany and Switzerland for pharmaceutical-grade borosilicate tubing, and Spain for PET resin processing. Raw material dependencies encompass natural gas for furnace operations, high-purity silica sand, and imported borosilicate tubing. Single-source vulnerability in German-Swiss borosilicate supply creates structural risk for ANSM-certified drug packaging. Distribution runs through Berlin Packaging's multi-material sourcing platform and direct furnace relationships with Île-de-France cosmetics houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The French square bottle market sits in a cyclical recovery phase driven by pharmaceutical serialization investments and homecare refill platform expansion. ANSM traceability mandates and ECHA coating reformulation requirements are compressing supplier qualification timelines while opening margin pools for integrated operators.
For Market Incumbents: Compound laboratory certification capabilities directly into furnace operations to compress ANSM qualification timelines for pharmaceutical clients. Pursue backward integration into borosilicate capacity through furnace reconfiguration capex, defending margin position against mid-scale IS machine operators exposed to energy cost volatility. Secure long-term natural gas hedging to stabilize input cost exposure.
For New Entrants and Emerging Players: Differentiate on rapid-turnaround custom decoration services for Grasse niche perfume houses requiring heritage tint reproduction. Target the direct-to-brand digital sampling channel with 30ml serum formats shipped through cosmetics subscription platforms. Establish partnerships with regional pharmacy cooperatives in Brittany and Normandy bypassing traditional distribution hierarchies.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors furnace-scale integrated glassworks with captive borosilicate certification. Long-term viability over a five-to-ten-year window rests on regulatory data integration capabilities and cross-border qualification pathways under converging EU MDR frameworks. Watch for furnace reconfiguration announcements as the primary inflection indicator for capacity realignment toward pharmaceutical-grade output.
| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Reconfiguration for Borosilicate | ANSM certification requirements pull capital toward pharmaceutical-grade capacity conversion. |
| Laboratory Certification Integration | Embedding traceability hardware compresses supplier qualification timelines for drug packaging. |
| Digital Decoration Platform Investment | UV-cured ceramic ink migration addresses ECHA SVHC restrictions while preserving premium aesthetics. |
| Direct-to-Brand Distribution Partnership | Subscription platform relationships capture first-party consumer data for cosmetics houses. |
| Regional Cooperative Procurement Aggregation | Brittany and Normandy pharmacy networks consolidate generic medication packaging demand. |
Research Methodology
Initial hypotheses were tested against primary input from furnace operations managers, cosmetics packaging procurement leads, pharmaceutical regulatory affairs directors, and regional pharmacy cooperative purchasing committees, then refined against secondary validation. Secondary sources encompassed ANSM pharmacovigilance filings, ECHA SVHC candidate list updates, French customs trade data for glass and polymer packaging, and SEC disclosures from listed packaging manufacturers. Bottom-up volume modeling triangulated with top-down value estimates across material grades and capacity tiers.
Variance decomposition across the projection horizon isolates drivers by material substitution dynamics, regulatory compliance cost pass-through, and end-use industry concentration shifts. Segmentation dimensions modeled encompass material composition, capacity tier, end-use industry vertical, closure mechanism type, and regional production cluster within France. CAGRs were derived from trend extrapolation anchored in disclosed capacity expansion timelines and buyer procurement aggregation patterns. Forecast inputs incorporated natural gas price sensitivity for furnace economics and ECHA regulatory timeline assumptions for coating reformulation.
The analysis sits within stated boundaries; outcomes outside sustained ANSM enforcement intensity or accelerated ECHA SVHC expansion would require recalibration. Forecasts reflect documented assumptions regarding furnace reconfiguration capex feasibility and cross-border borosilicate supply continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Beveled Bottles Market
Beverage Packaging
Can Sleeves Market
Beverage Packaging
Foamer Bottle Market
Beverage Packaging
Aluminium Cup Market
Beverage Packaging
Soft Drinks Packaging Market
Beverage Packaging
Beverage Aluminum Cans Market
Beverage Packaging
Light Water Tap Market
Beverage Packaging
Dual Chamber Dispensing Bottles Market
Beverage Packaging
PET Bottle Market
Beverage Packaging
Drink Can Market
Beverage Packaging
Europe Beverage Container Market
Beverage Packaging
Beverage Cups Market
Beverage Packaging
Skep Bottle Market
Beverage Packaging
Europe Beverage Packaging Market
Beverage Packaging
Self-Chilling Can Market
Beverage Packaging
Reservoir Media Bottle Market