
 Light Water Tap Market | 2026-2036
Light Water Tap Market Size, Share, and Industry Trends Forecast 2026-2036
Light Water Tap Market Foresight
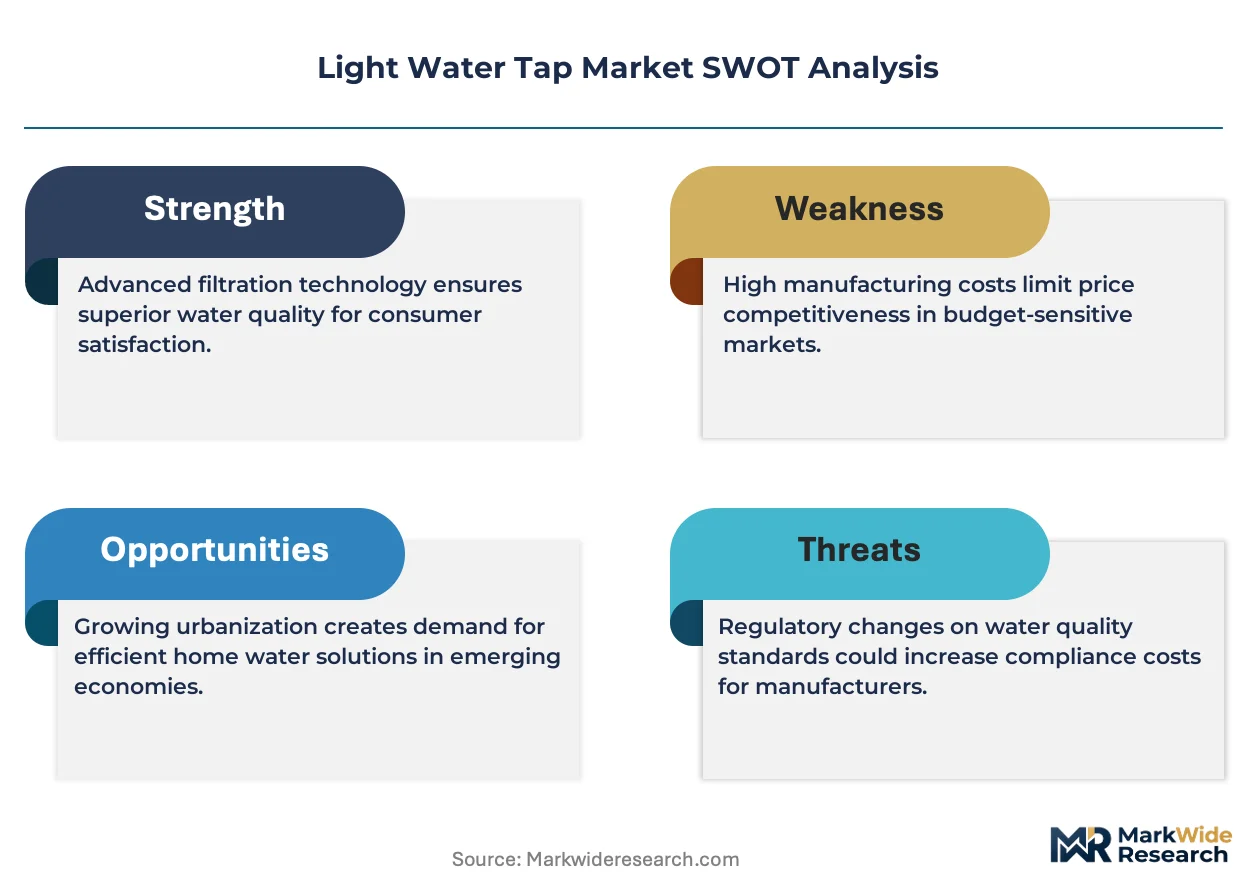
Chinese brass foundry output is hardening as the dominant supply base for global faucet manufacturing. LIXIL Group Corporation leverages integrated ceramic cartridge production across its Asian facilities to secure component availability. Kohler Co. anchors North American distribution through direct builder partnerships and exclusive showroom networks. Moen Incorporated differentiates via connected-home water monitoring systems embedded in its premium pull-down lines.
A light water tap is a manually or sensor-activated valve assembly controlling potable water discharge, typically rated for pressures between 0.1 and 1.0 MPa and constructed with lead-free brass or 304-grade stainless steel to comply with potable contact standards. The device regulates flow volume and temperature mixing for residential kitchens, commercial restrooms, and industrial wash stations. Sensor taps are capturing margin pools in commercial end-user segments where hygiene protocols and water conservation mandates tighten operational requirements. Stainless steel material grades command pricing premiums in residential applications across coastal geographies where corrosion resistance determines replacement frequency. Wall-mounted installation methods retain dominance in European institutional settings where space optimization and maintenance access drive specification choices.
EPA lead-free certification under the Safe Drinking Water Act governs US market access for brass alloy formulations, while EU REACH restrictions on nickel release influence surface plating specifications for European distribution. China's GB standards for water efficiency labeling directly shape product development priorities for manufacturers serving its domestic construction sector. Stakeholders must monitor evolving state-level water restriction codes in California and Texas, as these jurisdictions typically prefigure broader North American efficiency mandates that will reshape inventory and certification requirements.
Market Dynamics
EU F-Gas Regulation phase-downs are compressing refrigerant-dependent cooling systems and redirecting specification budgets toward low-flow aerator technologies in commercial fixture procurement.
Growth Catalysts
- Sensor Technology Maturation:Infrared and capacitive activation systems are penetrating institutional washroom specifications across Germany and France as hygiene protocols harden in healthcare and foodservice facilities.
- Water Efficiency Mandates:California's Title 24 building standards and Texas Senate Bill 1151 are accelerating replacement cycles for pre-2016 fixtures in residential and commercial construction.
- Smart Home Integration:China's GB standards for water efficiency labeling are converging with MIIT smart home certification frameworks, creating bundled specification demand in Shanghai, Beijing, and Shenzhen residential towers.
Market Restraints
- Brass Alloy Input Volatility:Chinese foundry capacity concentration in Zhejiang and Guangdong provinces exposes global manufacturers to zinc and copper price transmission lag effects.
- REACH Nickel Release Constraints:ECHA surface plating specifications for European distribution are extending qualification timelines for chrome and PVD finish variants by 4-8 months.
- Technical Limitation in Low-Pressure Deployment:Sensor tap minimum activation thresholds of 0.15 MPa exclude rural and aging infrastructure applications where static pressure falls below operational floors.
Strategic Opportunities
- Underpenetrated Southeast Asian Hospitality:Thailand and Vietnam resort construction pipelines are specifying European-branded fixtures without equivalent domestic sensor tap supply, creating import substitution windows.
- Regulatory Tailwind from IRA Efficiency Credits:US commercial building retrofit tax incentives under the Inflation Reduction Act are expanding specification authority for facilities managers in Class B office and retail properties.
- Technology Convergence:LoRaWAN and Bluetooth mesh protocols are enabling battery-free sensor taps harvesting kinetic energy from valve actuation, collapsing maintenance cost structures in high-traffic airports and stadiums.
Industry Challenges
- Cross-Disciplinary Talent Scarcity:Firmware engineering for IoT-enabled fixtures requires simultaneous competency in fluid dynamics and RF communication protocols, a combination rarely cultivated in traditional plumbing supply chains.
- Multi-Jurisdiction Certification Burden:Simultaneous EPA lead-free, NSF/ANSI 61, and cUPC compliance for North American market entry demands parallel testing tracks that compress margin realization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Light Water Tap Market |
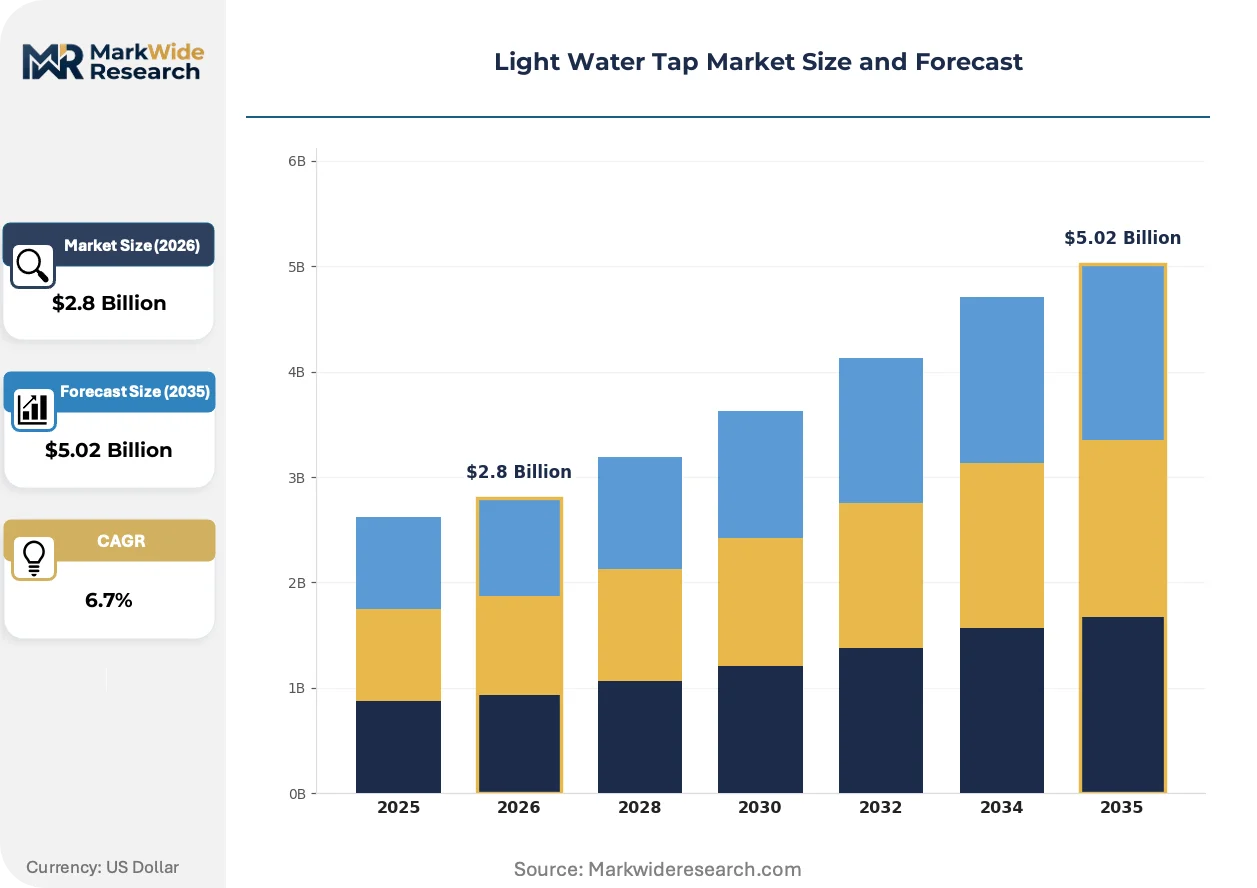
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Tap, Sensor Tap, Pull-Down Tap, Wall-Mounted Tap Material: Stainless Steel, Brass, Plastic, Chrome Installation Method: Deck-Mounted, Wall-Mounted, Freestanding, Under-Counter End User: Residential, Commercial, Industrial, Institutional |
| Companies Covered | LIXIL Group Corporation, Kohler Co., Delta Faucet Company, Moen Incorporated, Hansgrohe SE, TOTO Ltd., Roca Sanitario, Jaquar Group, American Standard Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Light Water Tap Market Shifts & Advancements
Product development trajectories are bifurcating between premium connected fixtures with embedded diagnostics and stripped-down mechanical variants optimized for emerging market cost floors.
Ceramic disc cartridge technology is absorbing precision manufacturing investments previously directed toward compression valve assemblies. Commercial specifiers in healthcare and education verticals are standardizing 35mm and 40mm ceramic platforms for maintenance interchangeability. This consolidation is absorbing supplier R&D budgets and compressing mechanical valve aftermarket viability.
EU F-Gas Regulation amendments are mandating lower global warming potential refrigerants in cooling systems that share specification channels with commercial tap procurement. MEP engineers are bundling low-flow fixture selection with HVAC efficiency compliance to optimize whole-building certification scores. German KfW green building finance programs are weighting this bundled approach in loan rate calculations.
Builder procurement departments are consolidating vendor relationships from fragmented regional distributor networks toward direct manufacturer partnerships with national account pricing. Large multifamily developers in Texas and Florida are bypassing traditional plumbing wholesalers for factory-direct container programs. This channel compression is most visible in 200-plus unit residential projects where specification uniformity and volume pricing override local service proximity preferences.
Light Water Tap Market Segmentation
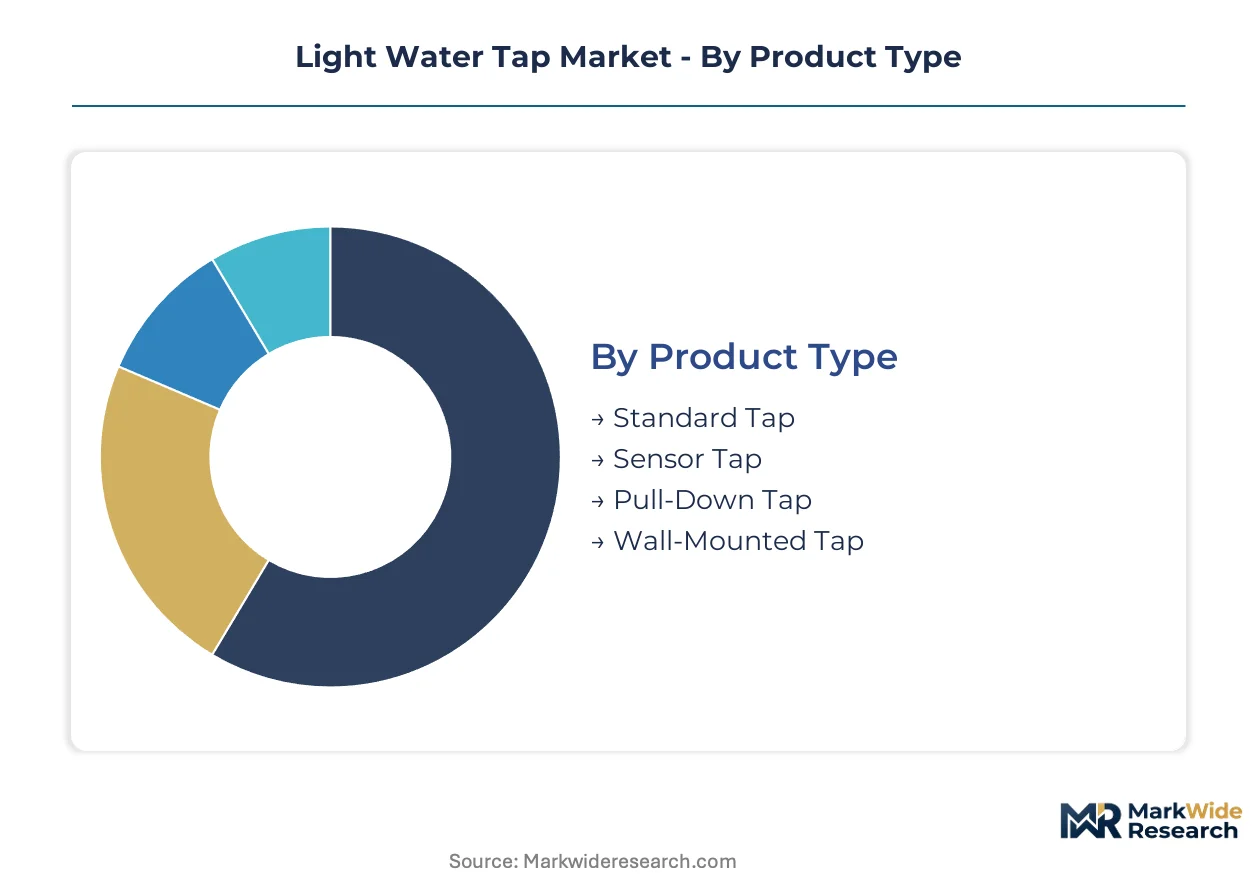
Segmentation in the light water tap market exposes divergent margin structures across activation technologies and material specifications. Procurement patterns in Germany and France favor sensor-equipped variants for hygiene-critical installations, while China's tier-one cities drive premium material substitution cycles.
Product Type:
Activation mechanism and user interface design separate segments by installed cost and maintenance intensity.
- Standard Tap:Manual lever or cross-handle valve assemblies utilizing ceramic disc cartridges for temperature and flow control. Residential renovation demand concentrates in suburban France and rural Germany where fixture replacement cycles lag urban adoption curves by 3-5 years.
- Sensor Tap:Infrared or capacitive activation systems eliminating physical contact for hygiene compliance. Healthcare and foodservice procurement in Germany's Klinikum networks and France's collective catering facilities are hardening specifications around 0.15 MPa minimum pressure thresholds and battery-free kinetic harvesting.
- Pull-Down Tap:Retractable spray-head configurations with braided nylon hose integration for sink-perimeter coverage. North American kitchen renovation demand favors this format for deep-basin pot filling and produce washing workflows.
- Wall-Mounted Tap:Concealed valve body with exposed spout assembly optimizing counter surface area. European institutional specifications in education and healthcare verticals prioritize this format for maintenance access and vandal resistance.
Standard tap leads on scale; sensor tap leads on momentum.
Material:
Raw material selection governs corrosion resistance, potable water compliance, and finished goods pricing tiers.
- Stainless Steel:304-grade and 316-grade austenitic formulations resisting chloride-induced pitting in coastal geographies. Premium residential applications in Shenzhen and Shanghai specify brushed or PVD finishes where salt-air exposure accelerates brass degradation.
- Brass:Lead-free copper-zinc alloys complying with EPA Safe Drinking Water Act and EU Drinking Water Directive limits. Chinese foundry output from Zhejiang province supplies the dominant feedstock for global faucet manufacturing.
- Plastic:Engineering polymer formulations including POM and ABS for cost-optimized utility installations.
- Chrome:Electroplated surface finish layer applied over brass substrates for aesthetic specification in hospitality and retail environments.
Brass dominates volume throughput; stainless steel commands expanding share in premium coastal markets.
Installation Method:
Mounting configuration determines rough-in requirements, spatial planning constraints, and maintenance accessibility.
- Deck-Mounted:Through-counter valve body installation with above-deck spout and handle assembly. Standard configuration for residential kitchen and lavatory applications across North American and Asian markets.
- Wall-Mounted:Concealed rough-in valve with exposed spout and control interface. European institutional specifications favor this method for barrier-free accessibility compliance and cleaning protocol efficiency.
- Freestanding:Floor-mounted supply connection with integral valve body for vessel sink and bathtub applications. Boutique hospitality projects in Thailand and Vietnam specify European-branded variants for design differentiation.
- Under-Counter:Remote valve location with countertop-mounted control interface or sensor activation. Integrated with stone or solid-surface countertops in high-end residential specifications.
Deck-mounted retains volume leadership; wall-mounted is expanding most quickly in institutional retrofit programs.
End User:
Demand concentration varies by specification authority, procurement cycle length, and compliance stringency.
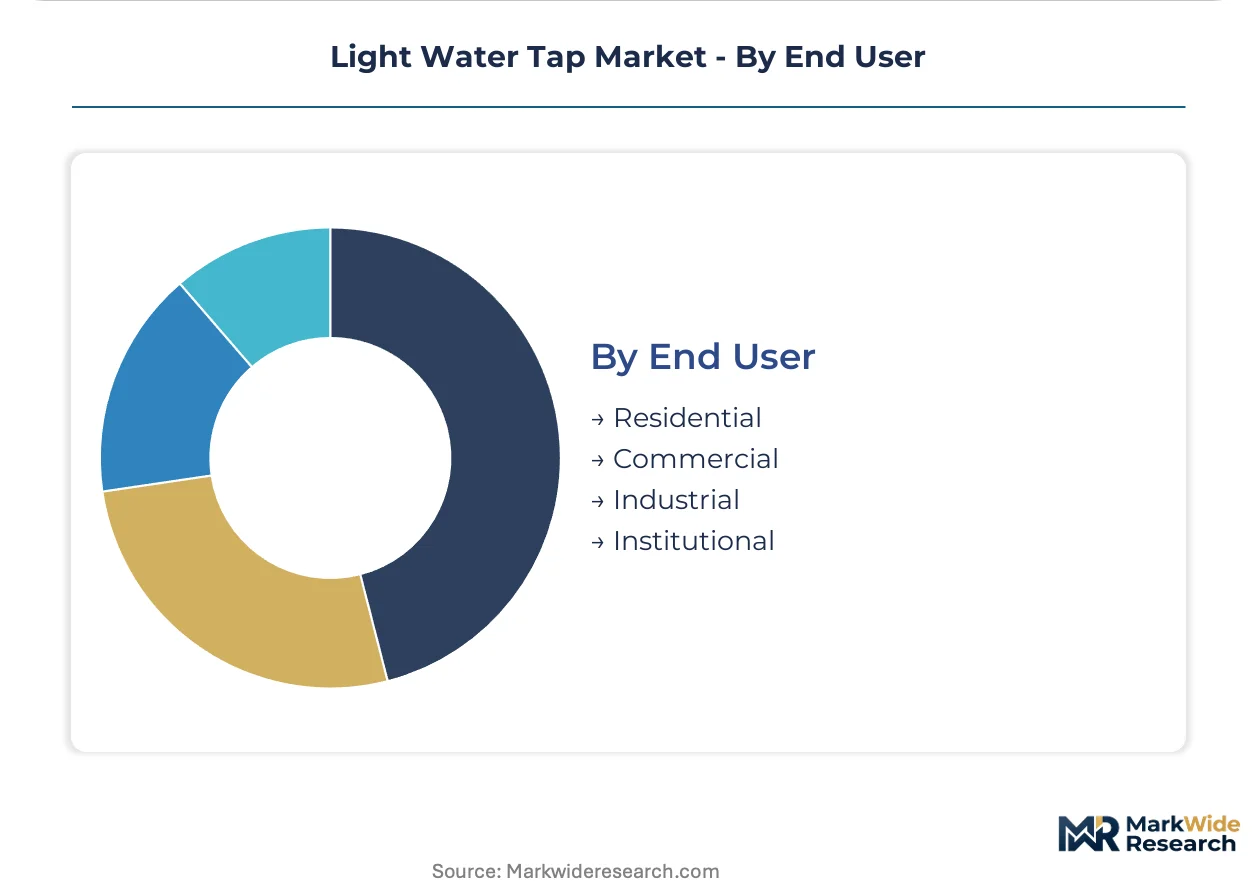
- Residential:Single-family and multifamily construction and renovation demand driven by fixture replacement cycles and smart home integration preferences. China's MIIT certification frameworks for connected devices are bundling sensor tap procurement with whole-home automation in Beijing and Shanghai residential towers.
- Commercial:Office, retail, and hospitality facilities where water efficiency mandates and hygiene protocols intersect. US Inflation Reduction Act efficiency credits are expanding specification authority for Class B office retrofit projects.
- Industrial:Manufacturing and processing facilities requiring heavy-duty valve assemblies for wash station and process water applications.
- Institutional:Healthcare, education, and government facilities with extended procurement timelines and maintenance interchangeability requirements. German KfW green building finance programs weight bundled fixture and HVAC efficiency in loan rate calculations.
Residential anchors volume absorption; commercial shows steepest expansion trajectory on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost-of-compliance gaps between jurisdictions are redirecting brass foundry investment toward Zhejiang province while EU REACH nickel-release constraints extend European qualification timelines. Manufacturers arbitrage these divergent regulatory burdens through dual-sourcing strategies that concentrate primary production in China and finish assembly in target markets.
China
MIIT smart home certification frameworks are converging with GB water efficiency standards to bundle sensor tap procurement in Beijing and Shanghai residential towers. SAMR market surveillance intensifies on lead-free brass claims, tightening documentation requirements for export-bound production. Zhejiang province foundries in Wenzhou and Taizhou supply the dominant feedstock for global faucet manufacturing.
Germany
Klinikum healthcare network renovations are hardening specifications around battery-free kinetic-harvesting sensor taps for hygiene-critical installations. KfW green building finance programs weight bundled fixture and HVAC efficiency in loan rate calculations. Bavaria's industrial clusters around Munich and Nuremberg concentrate precision ceramic cartridge production for European distribution.
United States
IRA commercial building retrofit tax incentives are expanding specification authority for facilities managers in Class B office and retail properties across Texas and Florida. EPA Safe Drinking Water Act lead-free enforcement tightens alloy documentation for brass imports. Large multifamily developers in Houston and Miami bypass traditional wholesalers for factory-direct container programs.
France
Collective catering facilities and healthcare procurement are standardizing infrared activation systems for foodservice hygiene compliance. ANSM surface contact regulations influence nickel-release testing protocols for chrome-plated finishes. Auvergne-Rhône-Alpes manufacturing bases around Saint-Étienne maintain specialized PVD coating capacity for premium hospitality specifications.
Thailand
Resort construction pipelines in Phuket and Bangkok are specifying European-branded fixtures without equivalent domestic sensor tap supply, creating import substitution windows. The country's national building efficiency codes are tightening water fixture specifications for new hospitality developments. Eastern Economic Corridor industrial zones attract component assembly investment serving ASEAN distribution.
Light Water Tap Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue connected-home integration and kinetic energy harvesting. The vendor base stratifies across three tiers: multinational fixture conglomerates with captive foundry relationships, mid-scale specialists in ceramic cartridge technology, and regional fabricators serving cost-optimized utility segments. Two dominant competitive moves define current positioning: direct builder partnerships that bypass traditional distribution, and backward integration into brass alloy production to secure input cost stability.
Within the multinational tier, LIXIL Group Corporation and Kohler Co. exemplify divergent geographic anchoring strategies, with the former leveraging integrated Asian production networks and the latter securing North American distribution through exclusive showroom channels. Moen Incorporated occupies a position within the connected-product archetype, representing the premium vector where embedded diagnostics and water monitoring systems differentiate specification authority. These three entities collectively illustrate how scale, regional production gravity, and technology integration separate competitive positions without requiring identical strategic postures.
| Leading Market Players |
|---|
| LIXIL Group Corporation |
| Kohler Co. |
| Delta Faucet Company |
| Moen Incorporated |
| Hansgrohe SE |
| TOTO Ltd. |
| Roca Sanitario |
| Jaquar Group |
| American Standard Brands |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap brass foundries in Zhejiang province anchor production discipline through generational ownership structures that resist short-term margin compression, transmitting cost stability downstream to fixture assemblers while preserving pricing power on lead-free alloy certifications.
Pricing Analysis
Distributor margin layers compress as large multifamily developers in Texas and Florida negotiate factory-direct container programs, bypassing traditional wholesale markups. Three-tier pricing structure across premium, standard, and economy levels separates sensor-enabled connected fixtures from ceramic-cartridge mechanical variants and plastic utility-grade alternatives. Pricing pressure stems from Chinese foundry capacity concentration exposing assemblers to zinc and copper lag effects. Residential renovation buyers in suburban France exhibit highest price sensitivity; institutional healthcare procurement in Germany shows lowest.
Supply Chain Analysis
Single-source vulnerability sits with Zhejiang and Guangdong province foundries that feed global brass alloy demand. Raw material dependencies center on copper and zinc concentrates, ceramic disc cartridges from Bavarian precision manufacturers, and infrared sensor modules from South Korean electronics suppliers. Supply chain risk concentrates in tariff exposure on US-bound brass alloy shipments. Distribution runs through consolidated national account partnerships displacing fragmented regional wholesaler networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on kinetic energy harvesting technology collapsing battery replacement costs in high-traffic commercial installations, while premium sensor tap penetration in China's tier-one cities shifts mix toward higher-ASP categories.
For Market Incumbents: To counter emerging IoT-native entrants with firmware-first development cultures, LIXIL and Kohler should deepen backward integration into captive brass alloy production in Wenzhou and Taizhou, while locking exclusive ceramic cartridge supply from Bavarian precision clusters through long-term offtake agreements. For New Entrants and Emerging Players: Capture underpenetrated resort construction pipelines in Phuket and Bangkok where European-branded fixture specifications lack domestic sensor tap supply. Target kinetic-harvesting battery-free variants for Thailand's Eastern Economic Corridor assembly investment serving ASEAN distribution. For Investors and Strategic Acquirers: Plumbing fixture conglomerates pursuing smart home integration are the most active acquirer in this space. Five-to-ten-year viability favors mid-scale ceramic cartridge specialists with ISO-certified precision manufacturing. Watch for MIIT smart home certification acceleration in Beijing and Shanghai as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Kinetic Energy Harvesting Integration | Battery-free sensor taps reduce maintenance costs in German Klinikum healthcare networks. |
| Backward Integration into Brass Alloy | Captive foundry supply insulates margin from Zhejiang copper-zinc price transmission lags. |
| Direct Builder Partnership Programs | Factory-direct container sales bypass distributor markups for Texas multifamily developers. |
| Ceramic Cartridge Platform Standardization | 35mm and 40mm interchangeability locks maintenance contracts in European institutional verticals. |
| Smart Home Certification Bundling | MIIT-GB convergence in Shanghai residential towers accelerates premium sensor tap specification. |
Research Methodology
Direct dialogue with plumbing fixture procurement managers, ceramic cartridge manufacturing engineers, MEP specification consultants, and facilities directors at German healthcare networks grounded qualitative findings. Secondary validation drew from EPA Safe Drinking Water Act filings, EU REACH nickel-release documentation, China SAMR market surveillance records, and customs trade data on brass alloy shipments. Bottom-up and top-down triangulation cross-checked channel inventory estimates against foundry output figures.
Bottom-up modeling aggregated unit economics across sensor tap, standard tap, pull-down, and wall-mounted product categories, while top-down analysis calibrated against construction permit flows in Beijing, Shanghai, Houston, and Miami. Segmentation dimensions included activation technology, material grade, installation method, and end-user vertical. CAGRs derived from regression against historical replacement cycles and regulatory mandate implementation timelines, with inputs from water efficiency code adoption curves and smart home penetration rates.
Brass alloy price volatility, REACH qualification timeline extensions, and MIIT certification pace are the dominant revision risks to projection assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Sugarcane Bottles Market
Beverage Packaging
Stackable Beaker Market
Beverage Packaging
Baritainer Jerry Can Market
Beverage Packaging
Beverage Can Ends Market
Beverage Packaging
Bottled Water Packaging Market
Beverage Packaging
North America Soft Drinks Packaging Market
Beverage Packaging
United States Aluminum Beverage Cans Market
Beverage Packaging
Europe Soft Drinks Packaging Market
Beverage Packaging
Dual Chamber Dispensing Bottles Market
Beverage Packaging
Aluminium Cup Market
Beverage Packaging
Can Sleeves Market
Beverage Packaging
Self-Cleaning Bottle Market
Beverage Packaging
Asia Pacific Beverage Packaging Market
Beverage Packaging
US Soft Drinks Packaging Market
Beverage Packaging
Bowl Cans Market
Beverage Packaging
Fruit Juice Packaging Market