
 PET Syrup Bottle Market | 2026-2036
PET Syrup Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
PET Syrup Bottle Market Analytics
The pharmaceutical end-use vertical is repositioning PET syrup bottle procurement toward child-resistant and tamper-evident formats. Amcor Plc leverages its blow molding scale across multiple continents to serve this shift. Berry Global Inc. anchors North American supply through extensive preform manufacturing networks. Silgan Holdings Inc. competes on closure integration, combining bottle and cap systems for pharmaceutical clients.
PET syrup bottles are polyethylene terephthalate containers engineered for viscous liquid storage, typically blow-molded with wall thicknesses of 0.3–0.8 mm and barrier-enhanced multilayer structures to prevent oxygen ingress and preserve shelf stability. Their primary purpose centers on protecting pharmaceutical elixirs, cough syrups, and liquid nutraceuticals from contamination, UV degradation, and moisture vapor transmission. Round bottles dominate pharmaceutical applications due to ergonomic handling and label adhesion reliability, while custom shape bottles command premium positioning in personal care where shelf differentiation determines purchase decisions. Blow molding technology leads volume production for standard formats, though injection molding gains traction in precision medical applications requiring tight dimensional tolerances.
FDA food-contact notification requirements govern resin additives and recycling content claims for pharmaceutical packaging sold in the United States. EMA's medical device regulation and EU REACH chemical restrictions shape material compliance obligations for European market access. India's CDSCO packaging standards for drug formulations add another compliance layer for exporters targeting that concentrated demand hub. Stakeholders must monitor evolving extended producer responsibility frameworks and recycled content mandates that will determine competitive positioning in resin sourcing and converter qualification.
Market Dynamics
Pharmaceutical packaging procurement is pivoting toward child-resistant and tamper-evident formats as unit-dose liquid medications expand across North American markets. This structural shift in end-use specifications is compressing converter qualification timelines and reshaping resin sourcing decisions.
Growth Catalysts
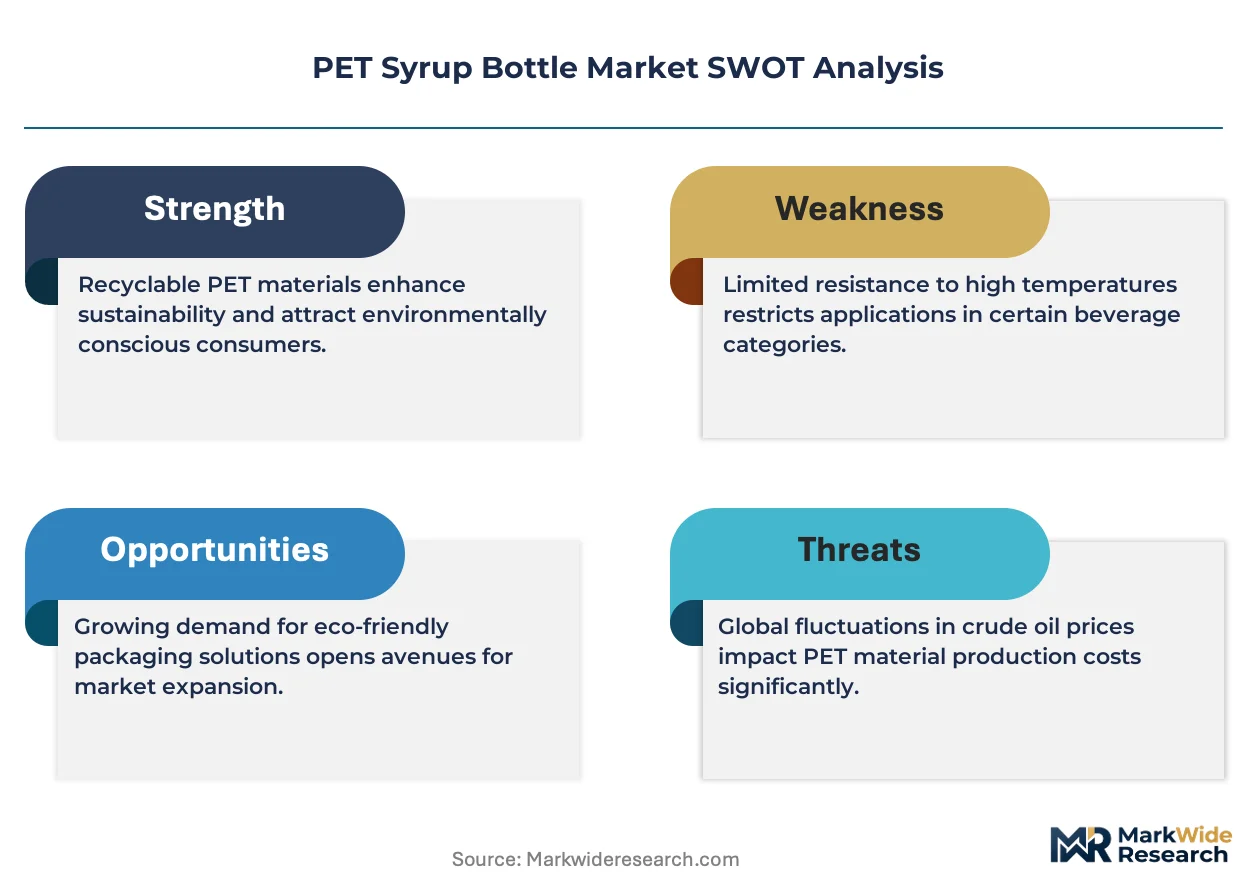
- CDSCO packaging standards:India's drug regulator mandates specific barrier properties for pharmaceutical containers, driving volume demand from domestic syrup formulators and over-the-counter liquid medication producers.
- Multilayer blow molding:Barrier-enhanced PET structures with oxygen-scavenging layers are displacing glass in liquid nutraceuticals, preserving shelf stability for temperature-sensitive formulations.
- Unit-dose expansion:North American pharmaceutical manufacturers are scaling single-serve liquid medication formats, requiring precision-molded bottles with integrated dosing closures.
Market Restraints
- Resin price volatility:Purified terephthalic acid and monoethylene glycol feedstock costs fluctuate with crude oil indices, compressing converter margins on fixed-price pharmaceutical contracts.
- REACH compliance burden:EU chemical restrictions on resin additives and recycling content claims force reformulation investments for exporters targeting European pharmaceutical markets.
- Glass substitution limits:High-barrier liquid formulations requiring near-zero oxygen transmission remain locked in borosilicate containers, capping PET penetration in premium pharmaceutical segments.
Strategic Opportunities
- Extended producer responsibility frameworks:EU Green Deal packaging mandates are creating first-mover advantages for converters with verified post-consumer recycled content supply chains.
- Precision medical injection molding:Tight dimensional tolerance requirements for auto-injector compatibility are opening premium niches beyond standard blow-molded formats.
- Direct-to-pharmacy distribution:E-commerce channel expansion for over-the-counter liquid medications is demanding smaller lot sizes and regional fulfillment center proximity.
Industry Challenges
- Blow molding technician scarcity:Specialized process engineers capable of calibrating multilayer coextrusion systems command premium wages, constraining capacity expansion timelines.
- FDA food-contact notification delays:Resin additive approvals for recycled content claims extend qualification cycles, freezing procurement decisions for sustainability-focused pharmaceutical clients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PET Syrup Bottle Market |
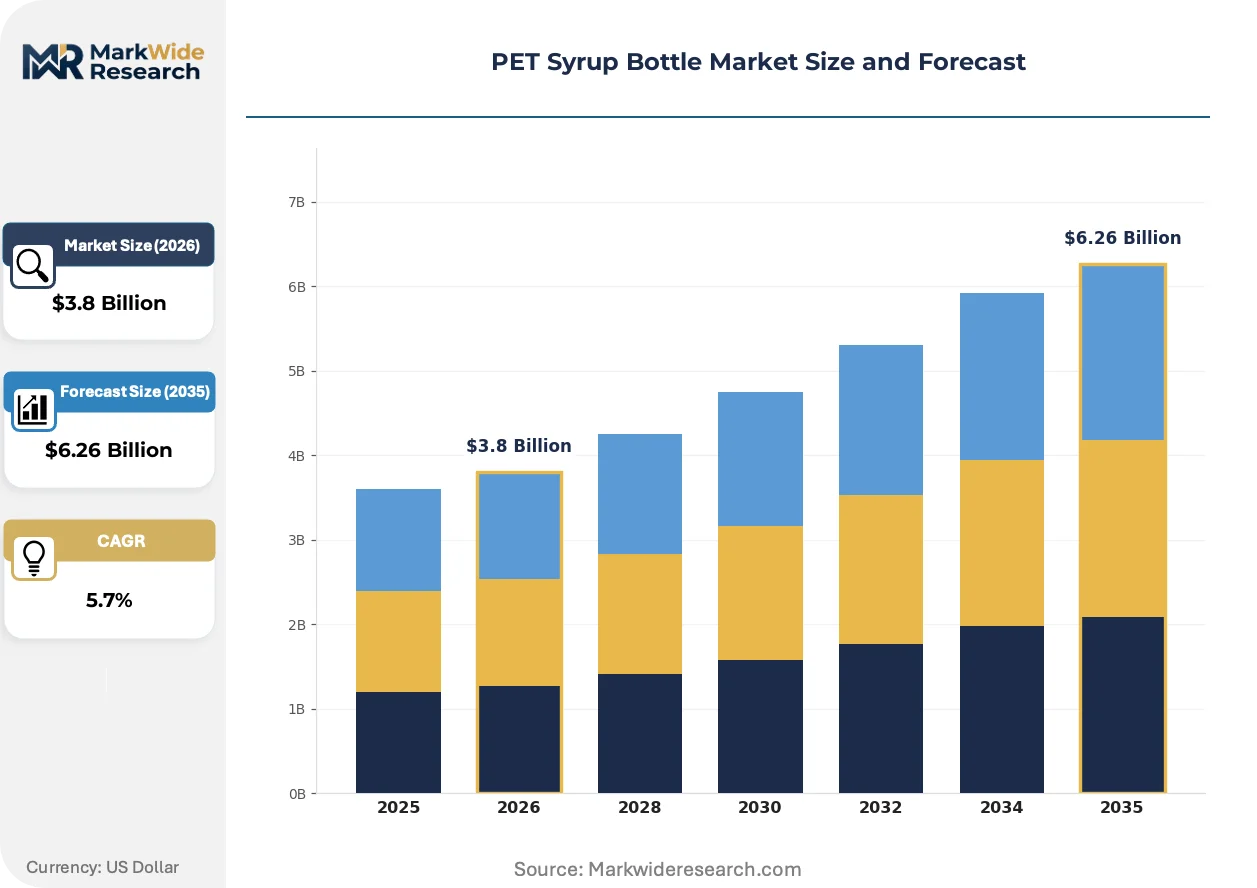
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Round Bottle, Square Bottle, Rectangular Bottle, Custom Shape Bottle Application: Pharmaceutical, Food & Beverage, Personal Care, Household Technology: Blow Molding, Injection Molding, Extrusion, Thermoforming Closure Type: Screw Cap, Flip Top Cap, Dropper Cap, Others |
| Companies Covered | Alpha Plastics Inc., Altium Packaging, Amcor Plc, Berry Global Inc., Indorama Ventures Public Co. Ltd., Sheth PET and Polymers Pvt Ltd., Silgan Holdings Inc., Gerresheimer AG, ALPLA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PET Syrup Bottle Market Evolving Landscape
Active and intelligent packaging integration is redefining pharmaceutical container specifications, with sensor-enabled bottles tracking temperature exposure and dosing adherence. These capabilities are migrating from clinical trial supply chains into commercial liquid medication distribution.
Barrier-enhanced coextrusion technology is automating quality assurance in multilayer PET production. Pharmaceutical contract packagers in Germany and Switzerland are deploying inline near-infrared spectroscopy to verify layer thickness uniformity at production speeds exceeding 30,000 bottles per hour. This automation is compressing batch release timelines from days to hours while reducing manual inspection headcount.
EMA's medical device regulation is reclassifying certain drug-device combination products, triggering additional conformity assessment procedures for bottles with integrated dosing pumps. European pharmaceutical manufacturers are restructuring supplier qualification protocols to capture clinical evidence requirements. Smaller converters without dedicated regulatory affairs functions are exiting this segment, concentrating supply among firms with MDR technical documentation capabilities.
Hospital and pharmacy buying groups are consolidating procurement for generic liquid medications, shifting volume toward converters offering multi-SKU fulfillment from single manufacturing sites. This concentration is visible in North American group purchasing organization contracts, where three-year supply agreements now specify geographic redundancy requirements. Regional converters with captive preform production and distributed blow molding assets are capturing share from single-facility competitors.
PET Syrup Bottle Market Segmentation
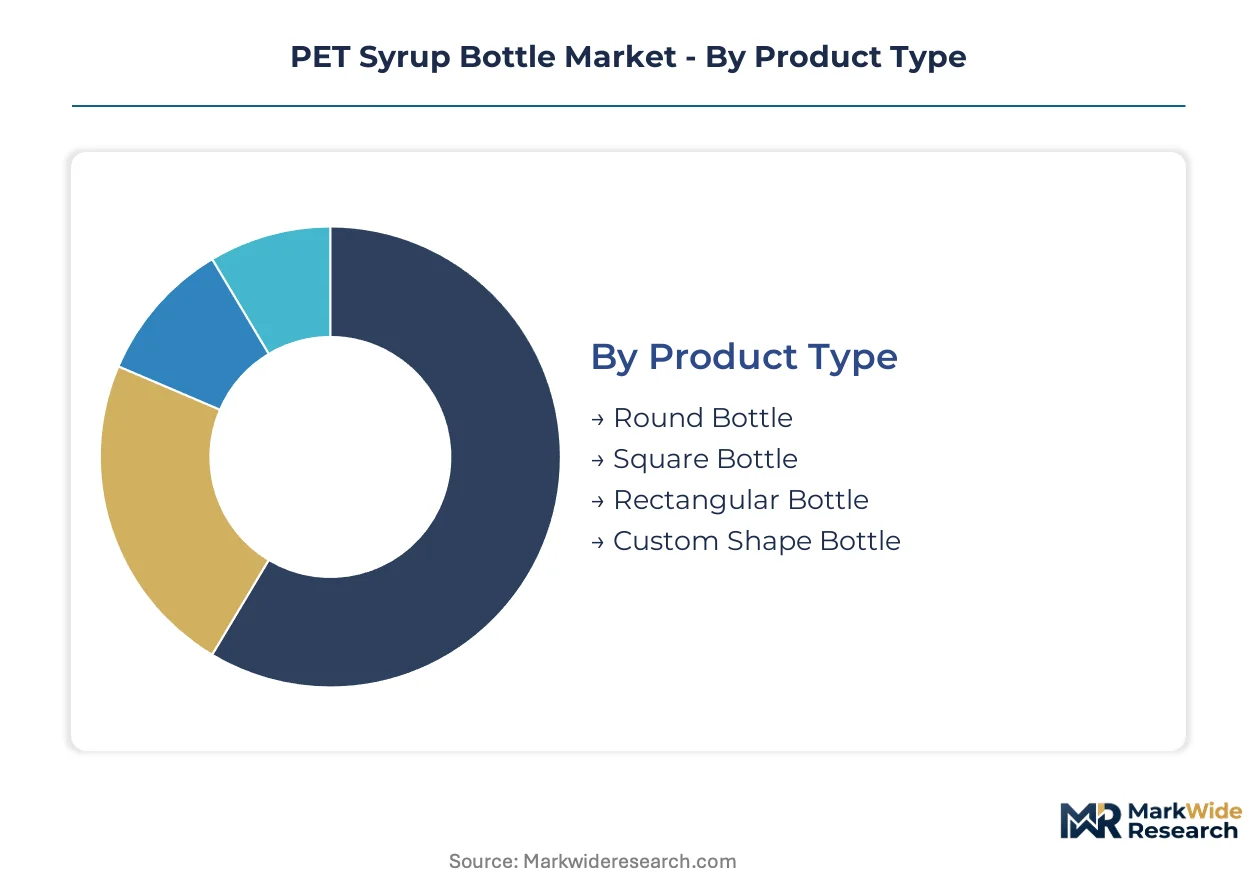
PET syrup bottle procurement decisions diverge sharply across end-use verticals, with pharmaceutical buyers prioritizing barrier integrity and personal care brands emphasizing shelf differentiation. Understanding these segment boundaries reveals where converter capabilities align with buyer specifications and where capability gaps create supply risk.
Product Type:
Round bottles dominate standalone pharmaceutical applications where ergonomic handling and label adhesion reliability matter most, while custom shapes embed into personal care systems requiring visual differentiation at point of purchase.
- Round Bottle:Blow-molded with uniform wall thickness distribution and optimized label adhesion surfaces. Pharmaceutical contract packagers in India and Germany specify round formats for cough syrups and liquid nutraceuticals where line efficiency and child-resistant closure compatibility drive procurement.
- Custom Shape Bottle:Injection-molded or hybrid-process containers with asymmetric geometries and specialized grip zones. Personal care brands in France and South Korea commission custom silhouettes for premium positioning in retail environments where shelf visibility determines purchase decisions.
- Square Bottle:Space-efficient stacking geometry for warehouse and retail shelf density.
- Rectangular Bottle:Flat-panel design maximizing label real estate for regulatory text and dosing instructions.
Round bottles lead volumes today; custom shapes are gaining share fastest.
Application:
Cost tier separation is pronounced across applications, with pharmaceutical buyers absorbing premium pricing for compliance documentation and household brands optimizing for unit economics at scale.
- Pharmaceutical:Barrier-enhanced multilayer structures with oxygen-scavenging layers and tamper-evident closure integration. CDSCO packaging standards in India and FDA food-contact notifications in the United States mandate specific resin grades and additive disclosures, compressing supplier qualification timelines.
- Personal Care:Aesthetic-focused formats with UV-stabilized resins and decorative finishing compatibility. Brands in Switzerland and Japan specify clarity grades and surface treatments that support premium positioning in cosmetic and nutraceutical segments.
- Food & Beverage:Flavor-preserving barrier properties for syrup concentrates and liquid sweeteners.
- Household:Cost-optimized single-layer construction for cleaning solutions and bulk dispensers.
Pharmaceutical applications command the highest unit margins; personal care is expanding most quickly.
Technology:
Volume concentration varies by manufacturing precision requirements, with blow molding serving high-throughput pharmaceutical contracts and injection molding capturing precision medical niches.
- Blow Molding:Coextrusion-capable systems producing multilayer barriers at speeds exceeding 30,000 units per hour. German and Swiss contract packagers deploy inline near-infrared spectroscopy for layer thickness verification, compressing batch release timelines.
- Injection Molding:Tight dimensional tolerance control for auto-injector compatibility and precision dosing systems. Medical device manufacturers in the United States and Japan specify injection-molded bottles where EMA medical device regulation and FDA combination product rules apply.
- Extrusion:Continuous profile production for specialty tubing and connected delivery systems.
- Thermoforming:Sheet-based conversion for shallow-draw containers and blister-compatible formats.
Blow molding dominates production volumes; injection molding is climbing the fastest in value terms.
Closure Type:
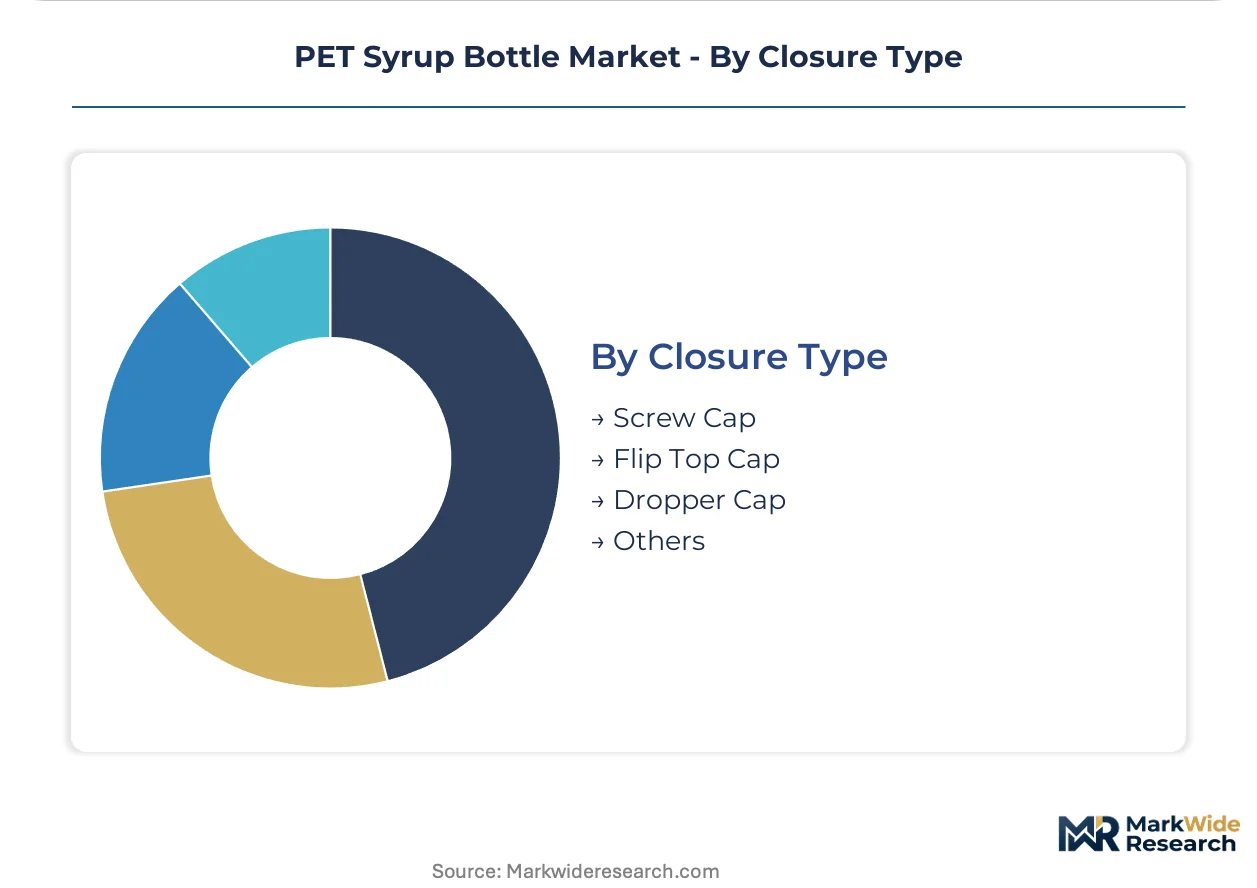
Customer type segmentation separates institutional pharmaceutical buyers seeking child-resistant compliance from retail-facing brands prioritizing consumer convenience.
- Screw Cap:Threaded closure systems with torque specifications calibrated for automated capping lines. Generic pharmaceutical manufacturers in North America specify screw caps for multi-SKU contracts with group purchasing organizations.
- Flip Top Cap:Hinged dispensing mechanisms enabling single-hand operation. Over-the-counter liquid medication brands in the United States and Brazil favor flip-top designs for direct-to-pharmacy e-commerce fulfillment where consumer convenience drives repeat purchase.
- Dropper Cap:Integrated pipette systems for precise volumetric dosing in pediatric and geriatric formulations.
- Others:Specialized closures including pump dispensers, spray actuators, and tamper-evident break-ring designs.
Screw caps lead volumes today; flip top caps are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ahmedabad's PET packaging cluster anchors pharmaceutical bottle production for India's domestic syrup formulators and export-oriented contract manufacturers.
United States
Unit-dose liquid medication expansion drives precision-molded bottle demand from North Carolina and New Jersey pharmaceutical corridors. FDA food-contact notification requirements for resin additives compress supplier qualification timelines for converters serving generic drug manufacturers. Chicago-area contract packagers are deploying automated blow molding lines with integrated child-resistant closure systems to capture group purchasing organization contracts.
Germany
Barrier-enhanced multilayer PET structures for liquid nutraceuticals command premium positioning from Bavarian and Baden-Württemberg converters. EMA medical device regulation reclassification of drug-device combinations triggers additional conformity assessments for integrated dosing pump bottles. Stuttgart-region packagers deploy inline near-infrared spectroscopy for layer thickness verification at production speeds exceeding 30,000 units hourly.
India
Domestic syrup formulations and over-the-counter liquid pharmaceuticals concentrate demand in Maharashtra and Gujarat pharmaceutical manufacturing zones. CDSCO packaging standards mandate specific barrier properties for pharmaceutical containers, driving volume from Mumbai-Pune and Ahmedabad industrial belts. Daman and Silvassa converters specialize in cost-optimized single-layer formats for regional generic medication distributors.
Switzerland
Precision medical injection molding for auto-injector compatibility attracts premium pricing from Basel-region pharmaceutical device manufacturers. Swissmedic technical documentation requirements filter supplier qualification toward converters with dedicated regulatory affairs functions. Zurich-area specialists capture niche volumes for clinical trial supply chains requiring sensor-enabled intelligent packaging integration.
Japan
UV-stabilized resin grades for premium nutraceutical positioning drive specification intensity from Osaka and Tokyo metropolitan packaging converters. METI circular economy guidelines accelerate post-consumer recycled content verification requirements for pharmaceutical supply chains. Nagoya industrial corridor manufacturers invest in coextrusion capability upgrades to preserve shelf stability for temperature-sensitive liquid formulations.
PET Syrup Bottle Market Competitive Landscape
Capacity expansion dominates the current landscape as converters race to install multilayer coextrusion systems capable of oxygen-scavenging barrier production. The vendor base stratifies across three tiers: integrated resin-to-bottle conglomerates with captive preform networks, regional specialists focused on pharmaceutical qualification protocols, and commodity converters serving household chemical applications. Strategic archetypes include barrier technology licensors, closure-integrated system providers, and recycled-content supply chain architects. M&A activity concentrates on preform manufacturing assets and regulatory-compliant facility acquisitions.
Within the integrated conglomerate tier, Amcor Plc and Berry Global Inc. exemplify scale-driven positioning through distributed blow molding footprints across multiple continents. Silgan Holdings Inc. occupies a specialist position emphasizing closure integration and combined bottle-cap system supply for pharmaceutical clients. Among European-focused players, Gerresheimer AG represents precision medical molding capability aligned with EMA medical device regulation compliance requirements. These named entities serve as anchors for understanding how competitive positioning fragments across technology specialization, geographic coverage, and regulatory capability depth rather than pure manufacturing scale.
| Leading Market Players |
|---|
| Alpha Plastics Inc. |
| Altium Packaging |
| Amcor Plc |
| Berry Global Inc. |
| Indorama Ventures Public Co. Ltd. |
| Sheth PET and Polymers Pvt Ltd. |
| Silgan Holdings Inc. |
| Gerresheimer AG |
| ALPLA Group |
| Others |
Value Network & Pricing Analysis
Purified terephthalic acid feedstock costs transmit from Asian petrochemical corridors through converter margins to pharmaceutical contract pricing tiers, with multilayer barrier grades commanding premiums over commodity single-layer formats.
Pricing Analysis
Distributor markups on pharmaceutical-grade PET syrup bottles compress as group purchasing organizations consolidate procurement volumes across North American hospital systems. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated multilayer formats with oxygen-scavenging layers from CDSCO-compliant regional grades and cost-optimized household chemical variants. Pricing pressure stems from resin volatility tied to crude oil indices, with generic pharmaceutical manufacturers exhibiting highest price sensitivity and precision medical device converters absorbing premiums for EMA MDR compliance documentation.
Supply Chain Analysis
CDSCO packaging standards and FDA food-contact notification requirements filter supplier qualification toward converters with dedicated regulatory affairs functions, concentrating pharmaceutical-grade supply among German, Swiss, and Indian manufacturers with verified compliance documentation. Raw material sourcing draws from purified terephthalic acid producers in China and South Korea, monoethylene glycol from Middle Eastern petrochemical complexes, and specialty oxygen-scavenging additives from Japanese chemical suppliers. Single-source vulnerability concentrates in multilayer coextrusion equipment with European machine-tool origins. Distribution runs through regional contract packagers serving pharmaceutical manufacturing corridors in North Carolina, Bavaria, and Maharashtra.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PET syrup bottle market compounds steadily as chronic disease prevalence sustains liquid medication volumes across aging demographics in developed and emerging economies alike.
For Market Incumbents: Anchor barrier technology leadership through captive preform network expansion in Ahmedabad and Stuttgart industrial corridors. Invest in inline near-infrared spectroscopy systems to compress batch release timelines from days to hours. Defend against emerging regional specialists by locking three-year group purchasing organization contracts with geographic redundancy clauses.
For New Entrants and Emerging Players: EU Green Deal packaging mandates in Germany and France open a window for post-consumer recycled content verification services. Target Swiss and Japanese precision medical injection molding niches where EMA MDR and PMDA documentation requirements filter out commodity converters. Pursue direct-to-pharmacy e-commerce fulfillment partnerships with over-the-counter liquid medication brands seeking regional distribution center proximity.
For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory compliance documentation functions concentrate among fewer qualified converters. Frame long-term viability around pharmaceutical packaging's non-discretionary demand profile and barrier technology moats. Monitor FDA food-contact notification approval timelines for recycled content claims as inflection signal for sustainability-focused procurement shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Multilayer Coextrusion Capacity Expansion | Enables oxygen-scavenging barrier production for liquid nutraceutical shelf stability requirements. |
| Regulatory Compliance Documentation Investment | Builds EMA MDR and FDA combination product technical files for drug-device combination markets. |
| Post-Consumer Recycled Content Supply Chain | Captures EU Green Deal first-mover advantages in pharmaceutical packaging sustainability mandates. |
| Precision Medical Injection Molding Capability | Opens auto-injector compatibility niches with tight dimensional tolerance specifications. |
| Direct-to-Pharmacy Distribution Partnership | Aligns with e-commerce channel expansion for over-the-counter liquid medication fulfillment. |
Research Methodology
Multiple input streams — converter production data, resin trade flows, and pharmaceutical procurement contract terms — were reconciled through bottom-up and top-down triangulation. Primary interviews with blow molding process engineers, pharmaceutical packaging procurement managers, CDSCO regulatory consultants, and group purchasing organization contract specialists informed operational assumptions. Secondary validation drew from FDA food-contact notification filings, EMA medical device regulation guidance documents, CDSCO packaging standard circulars, and customs records tracking purified terephthalic acid and monoethylene glycol import volumes.
Historical volume trajectories were cross-referenced against panel input from industry participants to construct analytical frameworks across product type, application, technology, closure type, and geographic regulatory cluster dimensions. CAGRs were derived from segmented growth rate reconciliation with macro pharmaceutical production indices. Forecast inputs incorporated unit-dose liquid medication expansion rates, multilayer barrier adoption curves in liquid nutraceuticals, and extended producer responsibility framework implementation timelines.
Revisions become necessary when resin feedstock volatility exceeds modeled bands or when regulatory approval timelines for recycled content claims materially diverge from baseline assumptions. A model refresh is warranted upon material change in pharmaceutical contract packager consolidation patterns or group purchasing organization geographic redundancy requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Drink Can Market
Beverage Packaging
Sugarcane Bottles Market
Beverage Packaging
Biotainer Market
Beverage Packaging
North America Beverage Packaging Market
Beverage Packaging
Self-Cleaning Bottle Market
Beverage Packaging
Foamer Bottle Market
Beverage Packaging
Square Media Bottle Market
Beverage Packaging
Beverage Can Ends Market
Beverage Packaging
Bottle Shippers Market
Beverage Packaging
Beverage Cups Market
Beverage Packaging
Pre-Made Cups Market
Beverage Packaging
Global Beverage Container Market
Beverage Packaging
Multicomponent Bottle Market
Beverage Packaging
Bamboo Cups Market
Beverage Packaging
Pop-Up Pourer Market
Beverage Packaging
North America Soft Drinks Packaging Market