
 North America Soft Drinks Packaging Market | 2026-2036
North America Soft Drinks Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Soft Drinks Packaging Market Analytics
Premium-grade recycled content specifications is redrawing competitive dynamics across North America. Amcor Ltd. leverages its film and container R&D network to sustain leadership in lightweight barrier technologies. Ball Corporation anchors aluminum can supply through integrated metal sourcing and beverage customer co-location. Crown Holdings differentiates via decorated two-piece can capabilities that command position in energy drink and sparkling water segments.
North America soft drinks packaging encompasses primary and secondary containment systems engineered to preserve carbonation, prevent light oxidation, and withstand internal pressures ranging from 30 to 90 psi depending on beverage formulation. PET blow-molding, aluminum draw-and-iron can forming, and aseptic carton filling constitute the dominant manufacturing processes serving shelf-stable and chilled distribution channels. Bottles retain the largest volume footprint across the region, though aluminum cans capture accelerated placement in sparkling water and reduced-sugar portfolios where portability drives purchase. Plastic as a material category faces structural pressure from rPET minimum-content mandates, while paperboard cartons gain refrigerated juice and ready-to-drink tea applications where shelf differentiation matters. Foodservice end-use channels show the fastest expansion as fountain syrup-to-cup systems and on-premise can programs recover post-pandemic traffic patterns.
The US FDA governs food-contact substance notifications and recycling stream contamination thresholds that directly determine which post-consumer resins qualify for beverage contact. EPA rules on hazardous waste classification of printing inks and adhesives shape converter operational compliance costs, while California SB 54 and pending Canadian federal extended producer responsibility legislation force brand owners to internalize collection infrastructure investment. Stakeholders must monitor how state-level recycled content thresholds propagate beyond California into Oregon, Washington, and Canadian provincial frameworks, as compliance geography will dictate where converters add rPET decontamination capacity versus sourcing virgin resin alternatives.
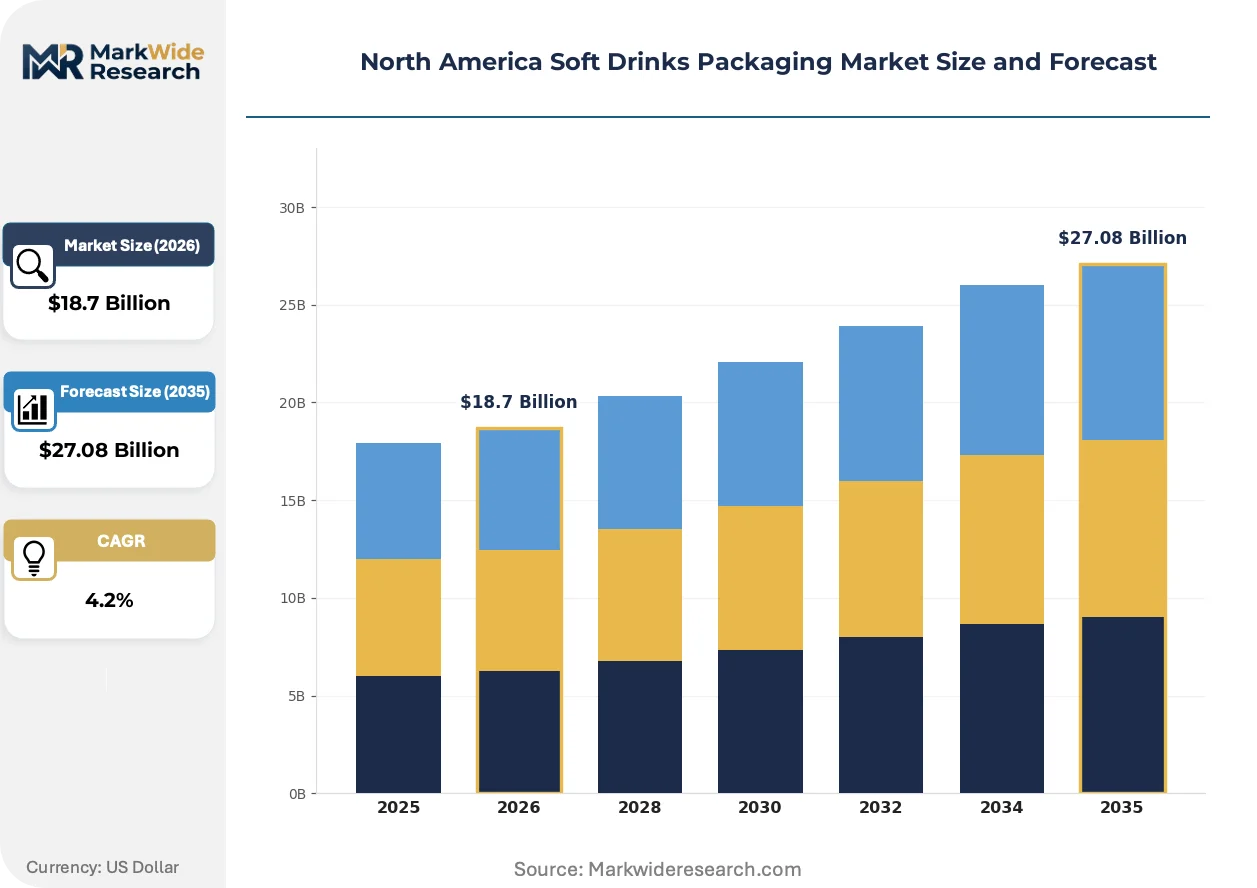
Market Dynamics
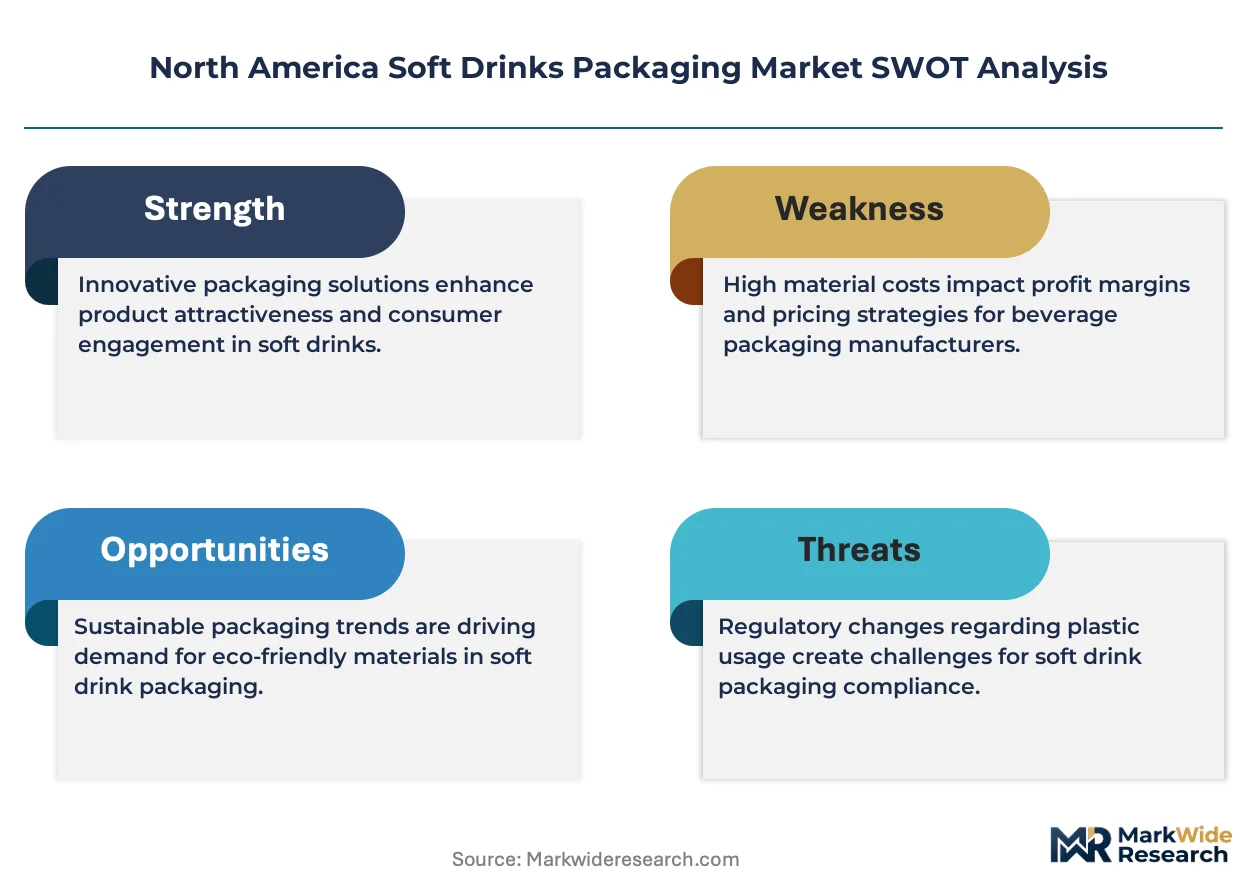
Extended producer responsibility mandates are forcing brand owners to internalize post-consumer collection infrastructure costs, fundamentally altering converter economics and resin sourcing strategies across the US Southeast packaging corridor.
Growth Catalysts
- California SB 54:The state's recycled content thresholds are accelerating rPET decontamination capacity additions by converters serving carbonated soft drink bottlers.
- Foodservice channel recovery:Fountain syrup-to-cup systems and on-premise can programs are rebuilding volume as post-pandemic traffic patterns normalize in urban centers.
- Aluminum draw-and-iron forming:This process is capturing accelerated placement in sparkling water and reduced-sugar portfolios where portability drives purchase decisions.
Market Restraints
- rPET feedstock volatility:Post-consumer bale quality inconsistency and contamination thresholds set by the US FDA constrain qualified resin availability and inflate purification costs.
- Converter concentration risk:Blow-molding capacity for premium-grade recycled content concentrates among a limited supplier base in Georgia and the Carolinas.
- Technical barrier limitations:Current lightweight barrier technologies struggle to match the shelf-life extension of conventional multilayer PET structures for oxygen-sensitive formulations.
Strategic Opportunities
- Canadian federal EPR legislation:Pending extended producer responsibility frameworks will force brand owners to fund collection infrastructure, creating first-mover advantages for converters with integrated recycling operations.
- Refrigerated juice cartons:Aseptic carton filling lines are gaining placement in ready-to-drink tea applications where shelf differentiation and sustainability credentials matter.
- Oregon and Washington state thresholds:Propagating recycled content mandates beyond California will dictate regional rPET capacity investment patterns through 2035.
Industry Challenges
- Contamination control expertise:The shortage of polymer scientists and process engineers capable of managing FDA-compliant decontamination protocols limits converter expansion timelines.
- Legacy blow-molding asset retrofit:Existing PET lines require substantial capital reconfiguration to handle higher recycled content ratios without throughput degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Soft Drinks Packaging Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Cans, Pouches, Cartons Material Type: Plastic, Metal, Glass, Paperboard End User: Retail, Foodservice, E-Commerce, Institutional Size: Small, Medium, Large, Extra Large |
| Companies Covered | Pactive LLC, Amcor Ltd., Genpak LLC, Graham Packaging Company, Ball Corporation, Crown Holdings, Owens-Illinois, Berry Global, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Soft Drinks Packaging Market Evolving Landscape
Active packaging formats and regulatory compliance technologies are redrawing competitive positioning across primary containment systems. Material substitution pressures and collection infrastructure investments now determine converter profitability as much as manufacturing efficiency.
Mono-material PET structures with enhanced barrier coatings are displacing multilayer constructions in carbonated applications. Mid-tier sparkling water brands are adopting these formats fastest, driven by California's recycled content mandates. The shift is compressing demand for ethylene vinyl alcohol copolymers and aluminum oxide deposition equipment while expanding blow-molding flexibility.
California SB 54 and Oregon's pending recycled content rules are mandating minimum rPET thresholds that cascade through supply contracts. Brand owners now specify decontamination certification levels in procurement agreements. Carbonated soft drink bottlers face the steepest compliance curves, forcing early rPET offtake commitments to secure qualified resin.
Direct-to-retailer can programs are shortening traditional distributor intermediation for aluminum formats. Energy drink and sparkling water portfolios are bypassing legacy beverage distribution networks fastest, particularly in Texas and Florida metropolitan markets. This channel compression rewards converters with co-located filling partnerships and regional logistics density.
North America Soft Drinks Packaging Market Segmentation
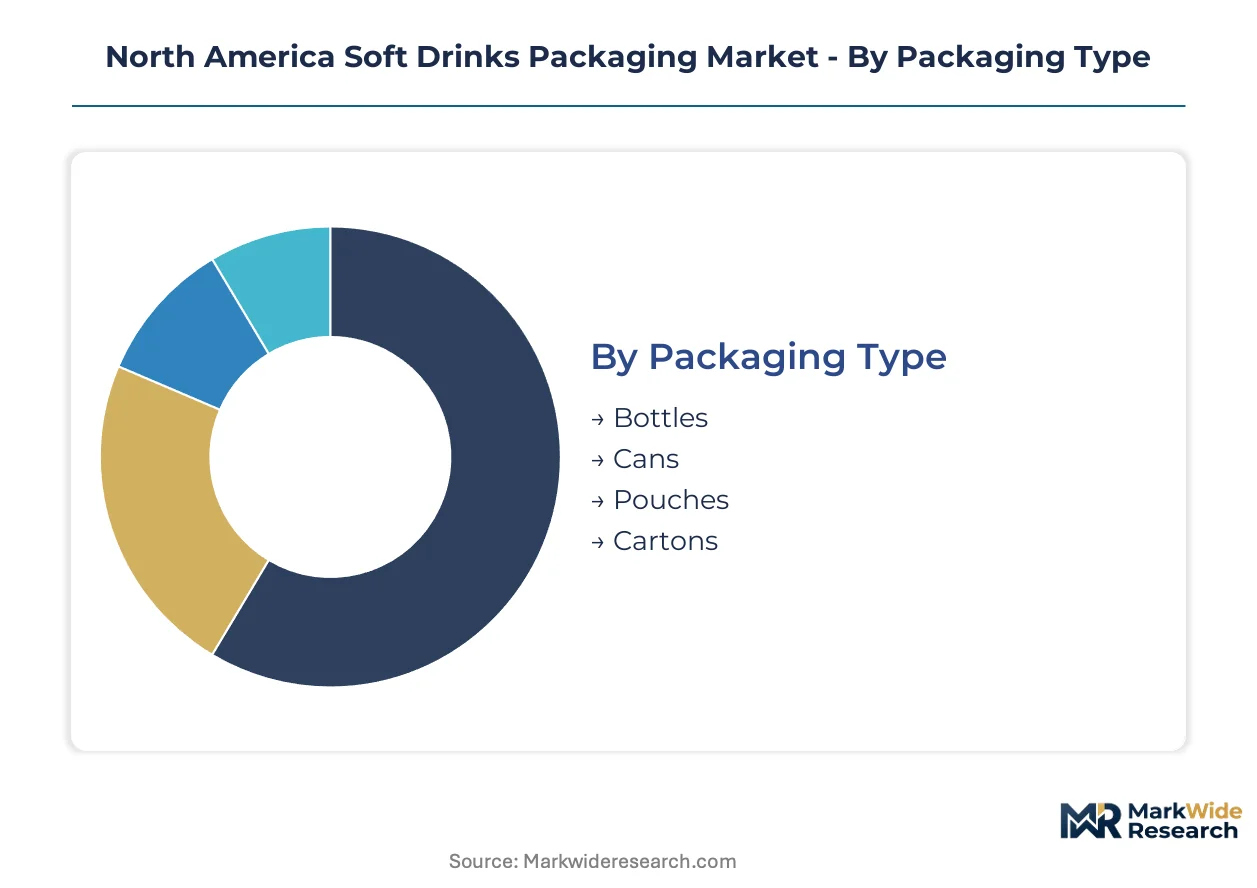
Segmentation in North America soft drinks packaging reveals how regulatory pressure and channel economics reshape procurement priorities. California SB 54 and extended producer responsibility frameworks force brand owners to specify packaging formats by recycled content compliance tiers rather than cost alone.
Packaging Type:
FDA food-contact substance notifications and state recycled content mandates differentiate formats by decontamination pathway feasibility.
- Bottles:PET blow-molding dominates carbonated soft drink containment with internal pressure tolerance to 90 psi. Demand concentrates in the US Southeast packaging corridor where Georgia-based converters add rPET decontamination capacity to meet California SB 54 thresholds.
- Cans:Aluminum draw-and-iron forming delivers portability advantages in sparkling water and reduced-sugar portfolios. The format captures accelerated placement in Texas and Florida metropolitan markets where direct-to-retailer programs bypass legacy distribution networks.
- Pouches:Flexible laminated structures serve single-serve juice and sports drink applications with lightweight logistics benefits.
- Cartons:Aseptic filling lines gain refrigerated ready-to-drink tea placement where shelf differentiation and sustainability credentials drive procurement.
Established volume favors bottles; emerging adoption favors cans.
Material Type:
Cost tier differentiation separates virgin resin specifications from premium-grade recycled content grades commanding supply premiums.
- Plastic:rPET minimum-content mandates under California SB 54 and pending Oregon rules force structural sourcing shifts. Post-consumer bale quality inconsistency constrains qualified resin availability for beverage contact applications.
- Metal:Aluminum draw-and-iron can forming anchors supply through integrated metal sourcing and beverage customer co-location. Crown Holdings and Ball Corporation concentrate capacity in the US Southeast corridor.
- Glass:Returnable bottle systems persist in premium mineral water and craft soda segments with localized filling infrastructure.
- Paperboard:Carton filling lines expand in refrigerated juice applications where aseptic barrier performance meets shelf-life requirements.
Procurement premiums concentrate in plastic compliance grades; operational stability favors metal supply chains.
End User:
Channel recovery velocity post-pandemic determines format specification intensity across customer types.
- Retail:Multi-pack configurations and shelf-ready secondary packaging dominate supermarket and convenience store placement. rPET content labeling requirements influence brand owner converter selection.
- Foodservice:Fountain syrup-to-cup systems and on-premise can programs are rebuilding volume fastest as urban traffic patterns normalize.
- E-Commerce:Ship-ready primary containment with drop-test certification drives specification for direct-to-consumer beverage subscriptions.
- Institutional:Bulk fountain systems and portion-controlled dispensers serve education and healthcare facility contracts.
Margin compression concentrates in retail compliance costs; volume expansion favors foodservice channel recovery.
Size:
Portability requirements and consumption occasion segmentation dictate dimensional specification patterns.
- Small:Single-serve 8-12 ounce formats capture on-the-go consumption in urban centers and transit-oriented retail.
- Medium:16-20 ounce bottles and cans balance portability with value perception in convenience store channels.
- Large:Multi-serve 1-2 liter bottles retain household pantry stocking preference for carbonated soft drink portfolios.
- Extra Large:Fountain syrup canisters and bag-in-box systems serve foodservice and institutional volume accounts.
Unit economics favor medium formats; per-ounce efficiency drives large-format household penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian bottlers exhibit the highest price elasticity as rPET premiums compress margins, while Mexican converters absorb cost volatility through integrated resin sourcing. US Southeast demand remains inelastic due to concentrated converter capacity and brand owner co-location.
United States
California SB 54 mandates 25% recycled content by 2025, forcing carbonated soft drink bottlers to secure qualified rPET offtake. The FDA's food-contact substance notifications determine which post-consumer resins qualify for beverage applications. Georgia-based converters in the US Southeast packaging corridor are adding decontamination capacity to serve West Coast brand owners.
Canada
Pending federal extended producer responsibility legislation will force brand owners to fund collection infrastructure investments. Health Canada and PMRA regulate food-contact materials alongside provincial packaging stewardship programs. Ontario and Quebec converters are positioning for first-mover advantages through integrated recycling operations ahead of EPR implementation.
Mexico
Beverage brand owners leverage proximity to US markets while sourcing virgin PET from domestic petrochemical complexes. The country's national environmental regulator oversees hazardous waste classification for printing inks and adhesives used in converter operations. Northern border states concentrate blow-molding capacity serving cross-border supply chains.
North America Soft Drinks Packaging Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North America soft drinks packaging market. The structure consolidates around integrated metal suppliers and specialized plastic converters, with mid-tier specialists occupying niche barrier coating segments. Three archetypes dominate: integrated aluminum producers with captive metal sourcing, rPET specialists with FDA-certified decontamination assets, and diversified packaging conglomerates with cross-format flexibility. M&A activity concentrates on recycling asset integration, while capacity expansion targets the US Southeast corridor to minimize logistics costs for California-bound volume.
Within the integrated metal tier, Ball Corporation and Crown Holdings occupy positions defined by beverage customer co-location and regional logistics density. Amcor Ltd. exemplifies the diversified archetype spanning film, container, and barrier technologies. These three companies represent the competitive poles around which procurement patterns organize: aluminum can supply security, rPET compliance certification, and lightweight barrier innovation.
| Leading Market Players |
|---|
| Pactive LLC |
| Amcor Ltd. |
| Genpak LLC |
| Graham Packaging Company |
| Ball Corporation |
| Crown Holdings |
| Owens-Illinois |
| Berry Global |
| Sonoco Products Company |
| Others |
Value Network & Pricing Analysis
California SB 54's recycled content certification tiers gate both converter qualification and price premiums simultaneously. Brand owners sourcing rPET for beverage contact must pay decontamination-grade resin spreads that widen as FDA-compliant bale scarcity intensifies across the US Southeast packaging corridor.
Pricing Analysis
After-sales revenue from decontamination certification audits and ongoing compliance verification drives lifetime value for rPET specialists. Three-tier pricing structure across FDA-certified premium, state-compliant standard, and non-certified economy grades separates carbonated soft drink bottlers by regulatory exposure. Cost compression in standard-tier virgin PET alternatives is intensifying because Georgia-based converters expand decontamination capacity. Foodservice channel buyers exhibit highest price sensitivity; California-bound brand owners show lowest elasticity due to mandate-driven procurement.
Supply Chain Analysis
Inventory lead times for post-consumer PET bales stretch 8-14 weeks as contamination sorting bottlenecks persist. Supply concentrates in the United States, Mexico, and Canada, with Georgia and the Carolinas anchoring blow-molding capacity. Raw material flows draw from municipal collection systems, MRF sorting facilities, and resin reclamation plants. Single-source vulnerability concentrates in FDA-certified decontamination assets. Distribution runs through converter-brand owner direct contracts, bypassing traditional resin distributor networks for compliance-grade volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Decontamination-as-a-service contracts and extended producer responsibility compliance management are expanding faster than base packaging hardware sales. Recurring revenue from certification maintenance and collection infrastructure operation now exceeds equipment margins for specialized converters.
For Market Incumbents: Consolidate rPET decontamination capacity in the US Southeast corridor to defend against new entrants leveraging Canadian EPR implementation timelines. Acquire FDA-certified reclamation assets to secure qualified resin supply as California SB 54 thresholds escalate. Backward integration into post-consumer bale sourcing reduces feedstock volatility exposure.
For New Entrants and Emerging Players: Anchor in Oregon and Washington state compliance markets ahead of recycled content mandate propagation. Target mid-tier sparkling water brands bypassing legacy distributor networks through direct-to-retailer aluminum can programs. Lead with aseptic carton filling partnerships for refrigerated ready-to-drink tea applications where barrier coating innovation gaps persist.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across rPET decontamination infrastructure as FDA compliance thresholds tighten. Five-to-ten year viability favors converters with integrated recycling operations and co-located brand owner relationships. Acquisition target archetype: mid-scale blow-molders with dormant certification pathways and Southeast logistics density. The signal to watch is state-level EPR legislation propagation velocity beyond California.
| Strategic Initiative | Industry Significance |
|---|---|
| rPET Decontamination Capacity Expansion | California SB 54 compliance curves force early offtake commitments from carbonated soft drink bottlers. |
| Direct-to-Retailer Can Program Launch | Energy drink portfolios in Texas and Florida metropolitan markets bypass legacy beverage distribution networks. |
| Integrated Recycling Operation Acquisition | FDA-certified reclamation assets secure qualified resin supply as post-consumer bale quality inconsistency intensifies. |
| Aseptic Carton Filling Partnership | Refrigerated ready-to-drink tea placement rewards shelf differentiation and sustainability credential alignment. |
| Foodservice Channel Recovery Investment | Fountain syrup-to-cup systems rebuild volume as post-pandemic urban traffic patterns normalize. |
Research Methodology
A spread of perspectives from PET blow-molding plant managers, brand owner procurement leads, FDA regulatory affairs specialists, and MRF operations directors converged on the working assumptions. Primary interviews with converter technical R&D directors and extended producer responsibility policy advisors combined with secondary validation from EPA hazardous waste classifications, California SB 54 implementation documents, FDA food-contact substance notification databases, and SEC 10-K filings from packaging conglomerates. Bottom-up capacity installation tracking and top-down demand modeling triangulated volume estimates.
Segmentation dimensions modeled include packaging type, material grade tier, end-use channel, and geographic regulatory cluster across the analysis window. CAGRs derived from installed capacity expansion schedules, brand owner offtake contract timelines, and state mandate implementation trajectories. Industry-specific forecast inputs incorporate rPET decontamination certification velocity and aluminum can forming line deployment patterns.
Material uncertainties — feedstock contamination threshold revisions, state EPR legislation propagation delays, and foodservice channel recovery discontinuities — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory compliance cost pass-through and converter margin sustainability. Revision becomes warranted when FDA food-contact notification backlog durations or post-consumer bale availability crosses critical supply security thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Beveled Bottles Market
Beverage Packaging
Bomber Bottles Market
Beverage Packaging
Can Sleeves Market
Beverage Packaging
United States Aluminum Beverage Cans Market
Beverage Packaging
Light Water Tap Market
Beverage Packaging
Dual Chamber Bottles Market
Beverage Packaging
Beverage Packaging Machine Market
Beverage Packaging
Media Bottles Market
Beverage Packaging
Stackable Beaker Market
Beverage Packaging
Twin Neck Bottles Market
Beverage Packaging
Bottle Dividers Market
Beverage Packaging
Insulated Cup Sleeves Market
Beverage Packaging
Cup Carriers Market
Beverage Packaging
Pop-Up Pourer Market
Beverage Packaging
Bowl Cans Market
Beverage Packaging
Cup Filler Market