
 Foam Cups Market | 2026-2036
Foam Cups Market Size, Share, and Industry Trends Forecast 2026-2036
Foam Cups Market Foresight
EU Single-Use Plastics Directive enforcement is shifting the cost-of-entry calculus for foam cup manufacturers selling into European foodservice channels. Dart Container Corporation leverages its captive resin supply and domestic molding footprint to sustain margin stability against resin price swings. Huhtamaki Group anchors its position through laminated paper and biodegradable foam R&D pipelines targeting regulated markets.
Foam cups are disposable beverage containers manufactured primarily from expanded polystyrene foam, typically ranging from 8 to 32 ounces in capacity, with wall thickness calibrated for thermal insulation between 2 and 4 millimeters. These vessels serve quick service restaurants, beverage vendors, and catering operators requiring low-cost, lightweight, and temperature-retentive serving solutions. Expanded polystyrene retains volume leadership across foodservice applications despite regulatory headwinds, while biodegradable foam and PLA foam categories are capturing fastest growth as operators preempt compliance deadlines in restricted jurisdictions. Hot cups command premium positioning through dual-wall and sleeve-compatible designs, whereas cold cups dominate unit economics in high-turnover fountain beverage programs.
US FDA food-contact regulations, EPA manufacturing emissions standards, and EU REACH chemical restrictions collectively determine material eligibility and cross-border market access for foam cup suppliers. State-level extended producer responsibility frameworks in California and New York are forcing reformulation timelines that compress R&D cycles for conventional polystyrene-dependent producers. Stakeholders must monitor biopolymer scale-up economics and regional ban phase-in schedules to align capacity investments with demand migration away from legacy resin platforms.
Market Dynamics
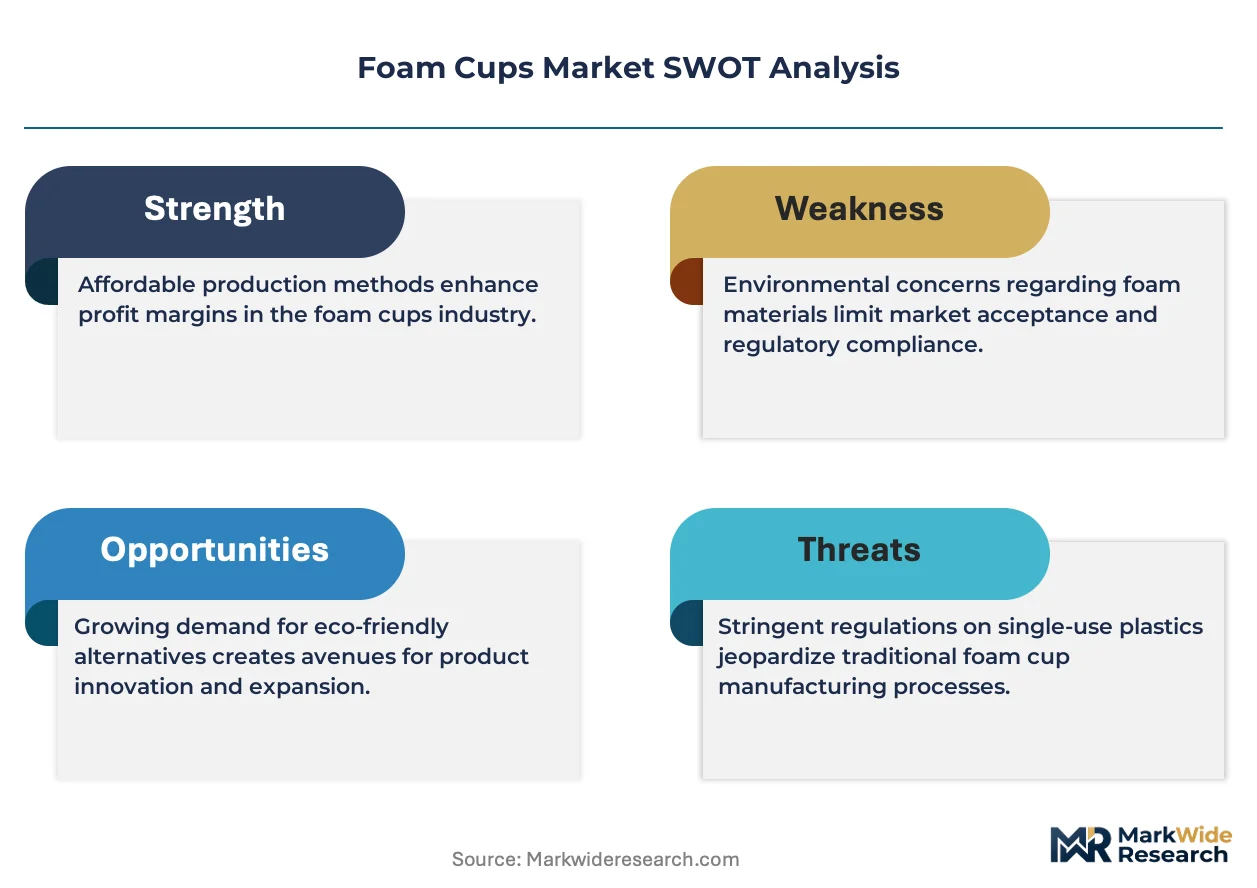
State-level single-use plastic bans and extended producer responsibility frameworks are compressing reformulation timelines for expanded polystyrene-dependent producers while pulling procurement toward biodegradable alternatives.
Growth Catalysts
- Quick service restaurant cold beverage expansion:Fountain drink programs at QSR chains are scaling foam cup procurement for high-turnover locations requiring thermal retention and low unit costs.
- EU Single-Use Plastics Directive:Enforcement deadlines across member states are creating compliance-driven replacement demand that biodegradable foam suppliers are capturing ahead of conventional resin bans.
- Biodegradable foam R&D maturation:PLA and starch-based formulations are achieving price parity with expanded polystyrene in regulated jurisdictions, enabling volume scale-up.
Market Restraints
- Resin price volatility:Expanded polystyrene feedstock costs fluctuate with benzene and styrene monomer spot markets, compressing margins for non-integrated molders.
- Concentrated petroleum-based supply:Virgin resin production clusters along the US Gulf Coast expose foam cup manufacturers to hurricane-related supply disruptions and logistics bottlenecks.
- Mechanical recycling limitations:Contaminated post-consumer foam streams face technical barriers to reprocessing that limit circular economy claims and EPR compliance options.
Strategic Opportunities
- Southeast US foodservice corridor:Quick service restaurant density across Georgia, Florida, and Texas offers volume growth before state-level bans phase in.
- Laminated paper-foam hybrid formats:Dual-material constructions are penetrating premium beverage channels requiring printability and insulation performance.
- California EPR framework:The state's extended producer responsibility mandates are creating first-mover advantages for suppliers with certified recyclable or compostable formats.
Industry Challenges
- Biopolymer processing expertise gap:Conventional polystyrene molders lack thermal profile optimization skills for PLA and starch-based foams, requiring equipment retrofits and technician retraining.
- Multi-jurisdiction certification complexity:FDA food-contact approvals, BPI compostability certifications, and state-level recyclable claims demand parallel compliance tracks that extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foam Cups Market |
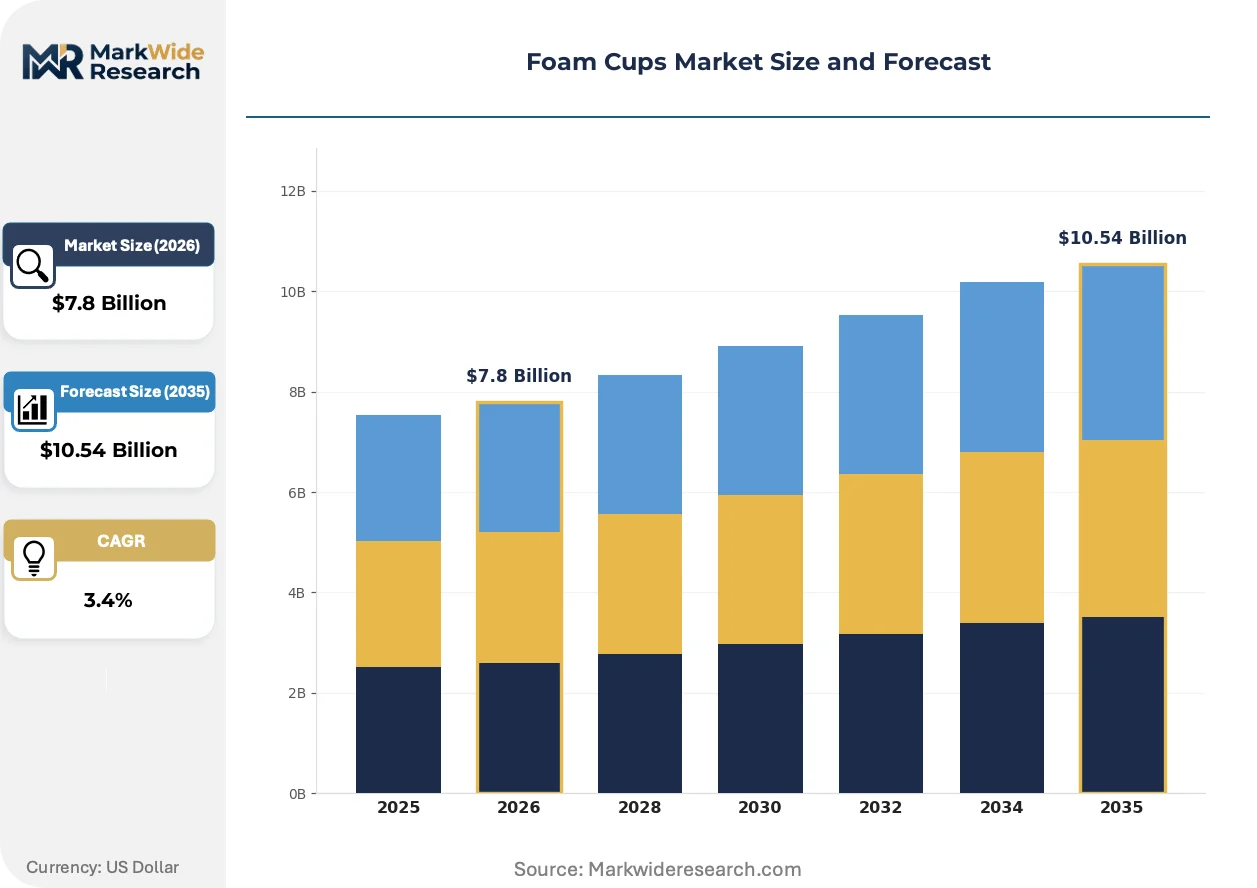
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $10.54 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Cups, Cold Cups, Hinged Lids, Sleeves Material Composition: Expanded Polystyrene, Polyethylene, Biodegradable Foam, PLA Foam, Laminated Paper End Use Industry: Quick Service Restaurants, Beverage Vendors, Catering Services, Event Organizers Distribution Channel: Wholesale Distributors, Online Retailers, Foodservice Suppliers, Convenience Stores |
| Companies Covered | Genpak LLC, Berry Global Inc., Dart Container Corporation, Ardagh Group S.A., WinCup Inc., Pactiv Evergreen Inc., Huhtamaki Group, Guangzhou NANYA Industrial Co., Ltd., Solo Cup Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foam Cups Market Shifts & Advancements
Material science advances and regulatory enforcement calendars are converging to accelerate format diversification beyond legacy expanded polystyrene platforms.
Biodegradable foam formulations derived from polylactic acid and cassava starch are expanding into quick service restaurant cold cup programs as operators preempt compliance deadlines in California, New York, and EU member states. Pilot deployments at regional beverage chains are validating performance parity with conventional EPS on insulation and stackability metrics. This transition is expanding into supply base restructuring as resin compounders build dedicated biopolymer capacity adjacent to foodservice molding clusters.
REACH chemical restrictions and EU Single-Use Plastics Directive enforcement are eliminating expanded polystyrene access to European foodservice channels by designated phase-out dates. Manufacturers serving cross-border quick service restaurant networks must maintain dual resin inventories and separate production lines to satisfy divergent regional compliance regimes. The regulatory burden falls heaviest on mid-cap molders lacking dedicated European formulation expertise and certification management infrastructure.
Direct procurement relationships between quick service restaurant chains and foam cup manufacturers are displacing traditional distributor intermediaries in high-volume beverage programs. Chains with standardized cup specifications are consolidating supplier panels and negotiating multi-year volume commitments that lock in capacity and stabilize input cost pass-through mechanisms. This consolidation concentrates in the US Southeast and Midwest corridors where fountain beverage penetration and QSR location density intersect most favorably.
Foam Cups Market Segmentation
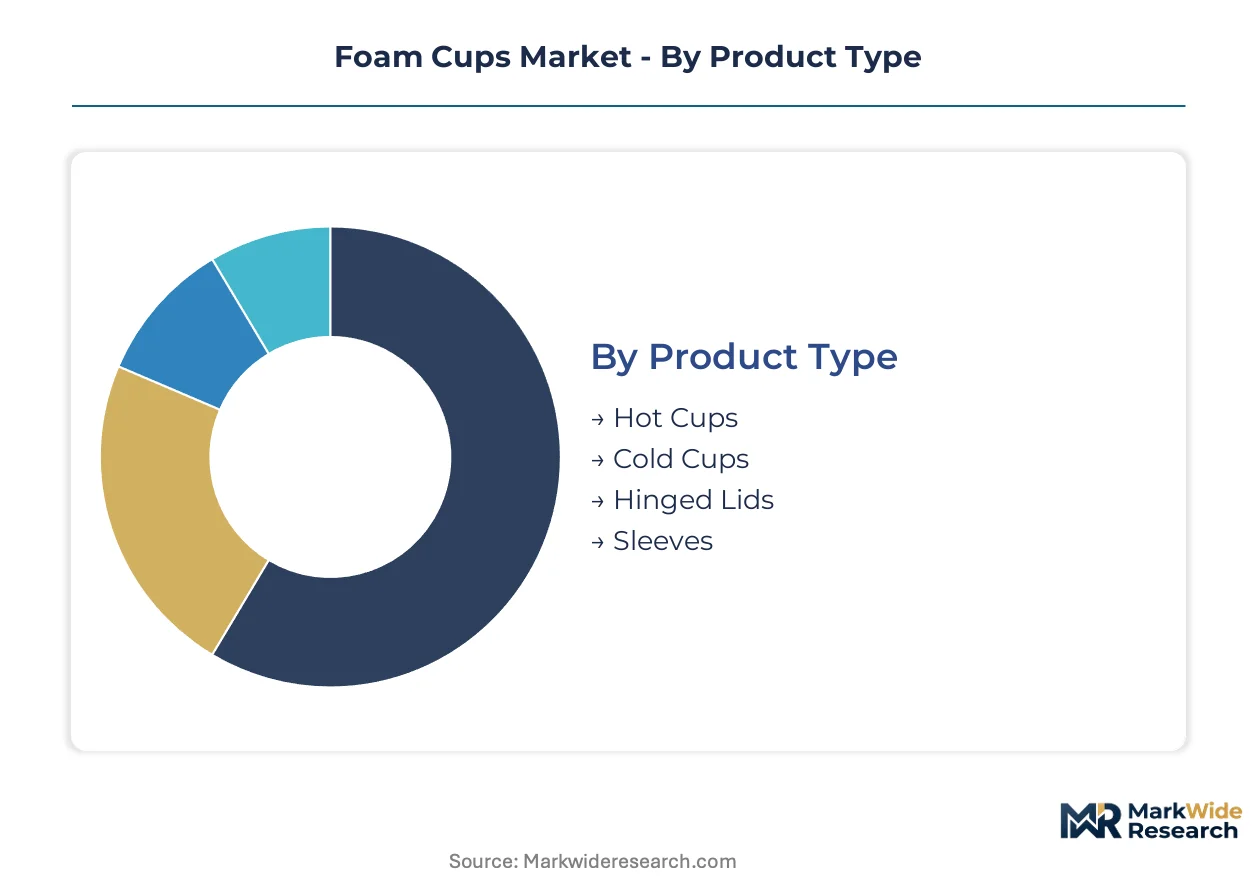
Segmentation in the foam cups market reveals how material compliance deadlines and thermal performance requirements split procurement decisions across foodservice channels. Suppliers must align formulation investments with the divergent cost and regulatory pressures shaping each product category and end-use vertical.
Product Type:
Wall thickness and thermal retention specifications differentiate cup formats across hot and cold beverage programs.
- Hot Cups:Dual-wall constructions with 3-4 millimeter EPS thickness and sleeve-compatible rims serve coffee and tea programs where burn protection commands premium positioning. Quick service restaurant chains in the US Southeast specify these for drive-thru operations where handling safety reduces liability exposure.
- Cold Cups:Single-wall 2-3 millimeter foam with rolled rims dominates fountain beverage turnover at QSR locations. High-throughput corridors in Texas and Florida favor this format for cost efficiency in 32-ounce and 44-ounce sizes.
- Hinged Lids:Snap-fit closures with straw slots prevent spillage in mobile consumption settings.
- Sleeves:Secondary insulation accessories extend cup versatility without format conversion costs.
Hot Cups lead on scale; Cold Cups lead on momentum.
Material Composition:
Resin selection now tracks regulatory geography more tightly than historical cost optimization.
- Expanded Polystyrene:Virgin and recycled-content EPS retains volume leadership through established molding infrastructure and sub-cent unit economics. Gulf Coast resin supply clusters sustain this position for operators in unregulated US states, though California and New York EPR frameworks are compressing accessible demand.
- Biodegradable Foam:Cassava starch and PLA-blend formulations achieve price parity in EU member states where REACH restrictions and Single-Use Plastics Directive enforcement eliminate conventional EPS access. Pilot programs at regional beverage chains validate insulation performance parity.
- Polyethylene:Extruded PE foam offers moisture resistance for frozen beverage applications.
- PLA Foam:Polylactic acid variants target compostability certification for California EPR compliance.
- Laminated Paper:Paper-foam hybrid constructions penetrate premium channels requiring printability.
Expanded Polystyrene leads on scale; Biodegradable Foam leads on momentum.
End Use Industry:
Procurement scale and specification standardization vary sharply across foodservice operator types.
- Quick Service Restaurants:National chains with standardized fountain programs negotiate multi-year volume commitments that lock in molding capacity. Direct procurement relationships are displacing distributor intermediaries for high-turnover locations in Georgia, Florida, and Texas corridors.
- Beverage Vendors:Regional coffee and smoothie chains drive biodegradable foam trials ahead of compliance deadlines in restricted jurisdictions.
- Catering Services:Event-based demand favors lowest-unit-cost EPS for single-serve applications.
- Event Organizers:Stadium and festival operators face visible sustainability pressure that shifts procurement toward certified compostable formats.
Quick Service Restaurants lead on scale; Beverage Vendors lead on momentum.
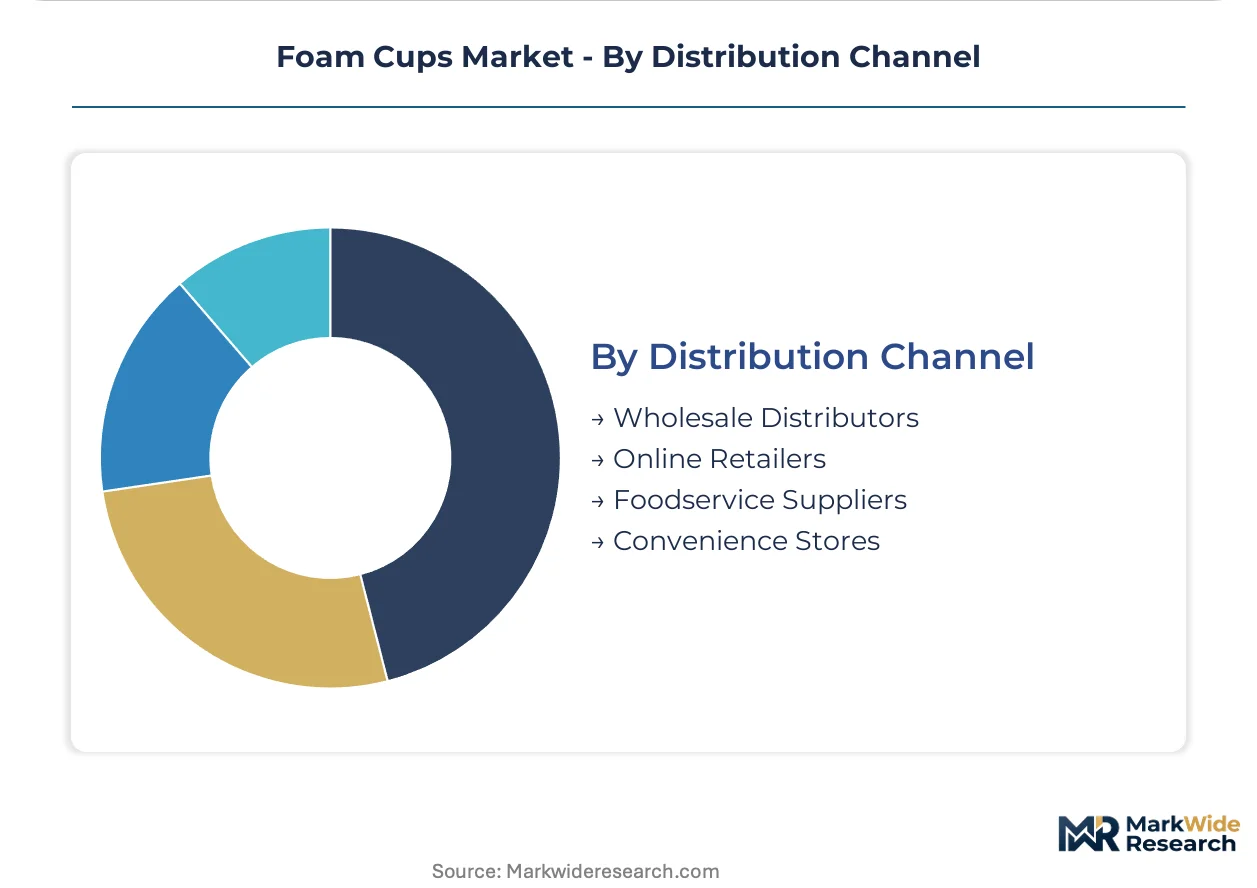
Distribution Channel:
Channel structure determines margin capture and customer relationship depth for cup manufacturers.
- Wholesale Distributors:Broadline foodservice distributors aggregate fragmented independent restaurant demand across the US Midwest and Southeast, though their role diminishes as large QSR chains consolidate direct supplier panels.
- Foodservice Suppliers:Specialty operators with formulation expertise manage multi-jurisdiction certification complexity for cross-border restaurant networks.
- Online Retailers:E-commerce platforms serve small-format buyers with minimum-order-quantity flexibility.
- Convenience Stores:C-store chains with captive beverage programs represent emerging volume for standardized cold cup formats.
Wholesale Distributors lead on scale; Foodservice Suppliers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foodservice packaging engineers and polymer chemists cluster in the United States, Germany, and China, anchoring the technical workforce that shapes regional foam cup supply capabilities.
United States
Quick service restaurant chains in Georgia, Florida, and Texas drive foam cup procurement for fountain beverage programs. FDA food-contact regulations and state-level extended producer responsibility frameworks in California and New York compress reformulation timelines for expanded polystyrene-dependent producers. The Gulf Coast resin production corridor supplies virgin styrene monomer to domestic molding operations.
Germany
REACH chemical restrictions and EU Single-Use Plastics Directive enforcement eliminate conventional expanded polystyrene access to foodservice channels. Biodegradable foam compounders in Baden-Württemberg build dedicated polylactic acid capacity adjacent to European molding clusters. The country's national packaging regulator enforces strict compostability certification requirements for market entry.
China
Guangzhou-based industrial manufacturers supply extruded foam formats to domestic beverage vendors and export markets. The country's national standards body issues GB standards for food-contact materials that determine cross-border market access. The Pearl River Delta concentration of polymer processing equipment supports scale manufacturing for cost-sensitive applications.
Japan
Convenience store chains with captive beverage programs represent emerging demand for standardized cold cup formats. METI industrial policy frameworks incentivize lightweight packaging innovation to reduce logistics emissions. The Kansai region around Osaka hosts precision molding specialists serving premium beverage channels.
India
Regional tea and coffee chains in Maharashtra and Karnataka pilot biodegradable foam trials ahead of anticipated compliance deadlines. The Food Safety and Standards Authority of India regulates food-contact materials for domestic and export-bound production. Gujarat-based chemical processors build starch-based foam compound capacity to serve South Asian foodservice markets.
Foam Cups Market Competitive Landscape
The competitive structure tilts toward integrated resin-to-cup manufacturers with captive supply chains and geographic diversification capabilities. Market concentration remains moderate, with tier-one players commanding multi-regional distribution networks while mid-cap molders serve protected state-level markets before ban phase-ins. Three archetypes dominate: vertically integrated resin producers with domestic molding footprints, biopolymer specialists with compostability certification expertise, and Asian-scale manufacturers with cost-optimized extrusion capabilities. Capacity expansion and backward integration into resin compounding represent the dominant competitive moves as margin pressure intensifies.
Among North American integrated manufacturers, Dart Container Corporation and Pactiv Evergreen Inc. exemplify the resin-captive archetype with domestic molding networks serving quick service restaurant chains. Huhtamaki Group occupies a position bridging European regulatory compliance expertise with multi-continental production scale. Guangzhou NANYA Industrial Co., Ltd. represents the Asia-Pacific cost-optimization tier, leveraging Pearl River Delta polymer processing infrastructure for volume manufacturing.
| Leading Market Players |
|---|
| Genpak LLC |
| Berry Global Inc. |
| Dart Container Corporation |
| Ardagh Group S.A. |
| WinCup Inc. |
| Pactiv Evergreen Inc. |
| Huhtamaki Group |
| Guangzhou NANYA Industrial Co., Ltd. |
| Solo Cup Company |
| Others |
Supply & Pricing Matrix
Quick service restaurant procurement consolidation across Georgia, Florida, and Texas corridors is forcing molders to absorb resin volatility or risk volume displacement, compressing margins for non-integrated suppliers while rewarding captive resin producers with pricing power.
Pricing Analysis
Direct procurement contracts versus distributor-mediated spot purchasing splits the market into divergent pricing regimes. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume commitment scale, with California EPR-compliant biodegradable formats commanding tier-one positioning. Cost compression in conventional EPS runs through benzene feedstock volatility and hurricane-related Gulf Coast supply disruptions. High-turnover QSR chains with multi-year volume commitments exhibit lowest price sensitivity, while independent catering operators and event organizers remain most exposed to spot-market fluctuations.
Supply Chain Analysis
California and New York domestic-content mandates for EPR compliance are reshaping sourcing patterns toward regional biopolymer compounders. Virgin styrene monomer production clusters along the US Gulf Coast, with Guangzhou-based extrusion specialists and Baden-Württemberg biodegradable foam compounders anchoring international supply. Feedstock dependencies center on benzene derivatives, cassava starch, and polylactic acid resin streams. Single-source vulnerability concentrates around Gulf Coast petrochemical infrastructure exposed to weather-related shutdowns. Distribution runs through consolidated direct procurement channels for national QSR chains and broadline foodservice distributors for fragmented independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in biodegradable foam formats where EPR compliance premiums offset biopolymer scale-up costs, while conventional EPS producers face structural cost-down pressure from resin volatility.
For Market Incumbents: Deploy captive resin supply as a pricing shield against Gulf Coast volatility by locking in multi-year styrene monomer offtake agreements. Incumbent molders must simultaneously build parallel biopolymer compounding capacity to serve California and EU restricted markets before ban phase-ins eliminate EPS access. Backward integration into PLA resin sourcing and BPI certification infrastructure represents the critical defensive lever against specialty compounder disruption. For New Entrants and Emerging Players: EU Single-Use Plastics Directive enforcement across member states opens a window for biodegradable foam specialists to capture compliance-driven replacement demand ahead of conventional resin bans. White-space targets concentrate in regional beverage chain pilot programs and California EPR-mandated foodservice channels. A certification-first go-to-market approach—securing BPI compostability and FDA food-contact approvals before volume scaling—differentiates entrants against incumbent reformulation laggards. For Investors and Strategic Acquirers: Asymmetric upside sits with biopolymer compounders possessing certified compostable formats and European regulatory expertise. Long-term viability over the next decade hinges on capacity positioning ahead of multi-jurisdiction ban calendars. The acquisition target archetype combines PLA foam R&D pipelines with established QSR direct procurement relationships. Watch biodegradable foam price parity achievement in regulated EU markets as the inflection signal for volume migration acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biopolymer Resin | Captive PLA supply secures margin stability against petroleum feedstock volatility. |
| BPI Compostability Certification Investment | California EPR compliance unlocks premium pricing in restricted foodservice channels. |
| Southeast US Capacity Expansion | Georgia and Florida QSR density supports volume growth before state ban phase-ins. |
| Dual-Resin Production Line Deployment | Parallel EPS and biodegradable foam lines serve divergent regional compliance regimes. |
| Direct Procurement Relationship Consolidation | National QSR chain panel reduction locks in multi-year volume commitments. |
Research Methodology
Multiple input streams—primary interviews with polymer chemists, foodservice procurement directors, and regulatory compliance officers; secondary validation through FDA food-contact filings, EU ECHA substance registrations, and state-level EPR framework documents; plus customs trade data on styrene monomer imports—were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged plant managers at Gulf Coast resin facilities, QSR supply chain executives, and biodegradable foam R&D directors. Secondary sources included SEC 10-K disclosures from integrated packaging manufacturers, BPI compostability certification databases, and ACC industry shipment reports.
Data-stream reconciliation applied across the projection horizon employed segmentation modeling by material composition, end-use industry, and regional regulatory cluster. The analytical framework derived CAGRs from volume shipment trajectories, price elasticity estimates for QSR procurement, and substitution elasticity between EPS and biodegradable formats. Industry-specific forecast inputs incorporated biopolymer scale-up cost curves and state-level ban phase-in schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU enforcement timelines or Gulf Coast weather disruptions. Forecasts reflect assumptions on biopolymer price parity achievement and regulatory deadline adherence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Corrugated Fish Box Market
Paper & Paperboard Packaging
US Corrugated and Folding Boxboard Market
Paper & Paperboard Packaging
Disposable Paper Cups Market
Paper & Paperboard Packaging
White Sack Kraft Paper Market
Paper & Paperboard Packaging
Liquid Packaging Board Market
Paper & Paperboard Packaging
Natural Sack Kraft Papers Market
Paper & Paperboard Packaging
Mailer Box Market
Paper & Paperboard Packaging
MAP Trays Market
Paper & Paperboard Packaging
South East Asia Corrugated Packaging Market
Paper & Paperboard Packaging
Canada Paper Packaging Market
Paper & Paperboard Packaging
Coated Paper Market
Paper & Paperboard Packaging
Bamboo Packaging Market
Paper & Paperboard Packaging
Corrugated Handle Box Market
Paper & Paperboard Packaging
Industrial Paper Sacks Market
Paper & Paperboard Packaging
Letterpress Card Market
Paper & Paperboard Packaging
Clear Envelopes and Mailing Supplies Market