
 Ice Transport Buckets Market | 2026-2036
Ice Transport Buckets Market Size, Share, and Industry Trends Forecast 2026-2036
Ice Transport Buckets Market Foresight
Aftermarket service revenue for replacement lids, gaskets, and caster assemblies is reshaping profit distribution across the ice transport bucket value chain. Cambro Manufacturing leverages its extensive distributor network to sustain replacement part availability. Vollrath Company anchors its position through stainless steel fabrication expertise and institutional channel penetration. Igloo Products Corp. competes on consumer-brand recognition that extends into light-commercial applications.
An ice transport bucket is a thermally insulated or uninsulated vessel, typically constructed from polyethylene, rotomolded plastic, or stainless steel with wall thicknesses ranging from 0.125 to 0.5 inches, designed to preserve ice integrity during manual or cart-based movement across foodservice, healthcare, and recreational environments. Insulated buckets command premium positioning due to extended hold-time performance in catering and commercial use, while non-insulated variants dominate high-turnover, short-duration event applications. Plastic construction leads volume across portable and bulk transport formats, though stainless steel maintains durable footholds in healthcare and institutional settings where sanitization protocols are most stringent.
FDA food-contact substance regulations govern plastic and rubber components used in ice transport buckets distributed across the United States, while NSF International standards certify sanitation performance for commercial food equipment. The EU Green Deal and REACH chemical restrictions shape material selection for products entering European markets, pressuring manufacturers toward recycled-content plastics and reduced additive portfolios. Stakeholders must monitor evolving state-level extended producer responsibility frameworks and building energy codes that increasingly restrict single-use cooling accessories in favor of reusable transport systems.
Market Dynamics
Commercial foodservice operators are consolidating purchasing decisions through national distribution agreements, compressing the vendor landscape and elevating replacement-part availability as a competitive differentiator for incumbent manufacturers.
Growth Catalysts
- Off-premise catering expansion:Event logistics operators are scaling insulated vessel fleets to serve outdoor weddings, corporate gatherings, and festival circuits across the United States.
- FDA food-contact compliance:Tightened sanitation protocols are disqualifying non-certified suppliers and rewarding manufacturers with validated material traceability systems.
- Rotomolded polyethylene durability:The material's impact resistance and thermal retention properties are displacing metal alternatives in high-mobility catering applications.
Market Restraints
- Petrochemical input volatility:Polyethylene resin prices fluctuate with crude oil benchmarks, squeezing margin predictability for plastic-format producers.
- Healthcare stainless steel concentration:Institutional buyers in hospital and long-term care segments remain locked into premium metal specifications that limit plastic penetration.
- REACH chemical restrictions:EU additive limitations are forcing reformulation cycles that delay product launches for European-bound shipments.
Strategic Opportunities
- Extended producer responsibility frameworks:State-level mandates in California and New York are creating first-mover advantages for manufacturers with closed-loop recycling programs.
- Smart cold-chain integration:RFID-enabled temperature logging is hybridizing with traditional insulated vessels to serve pharmaceutical and high-value food logistics.
- Direct-to-caterer e-commerce:Bypassing traditional foodservice distributors opens margin recovery for mid-tier manufacturers with digital fulfillment capabilities.
Industry Challenges
- NSF certification timelines:Sanitation testing protocols for new material formulations extend product development cycles by six to twelve months.
- Legacy caster standard incompatibility:Replacement part interoperability across vendor generations complicates fleet maintenance for multi-brand operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ice Transport Buckets Market |
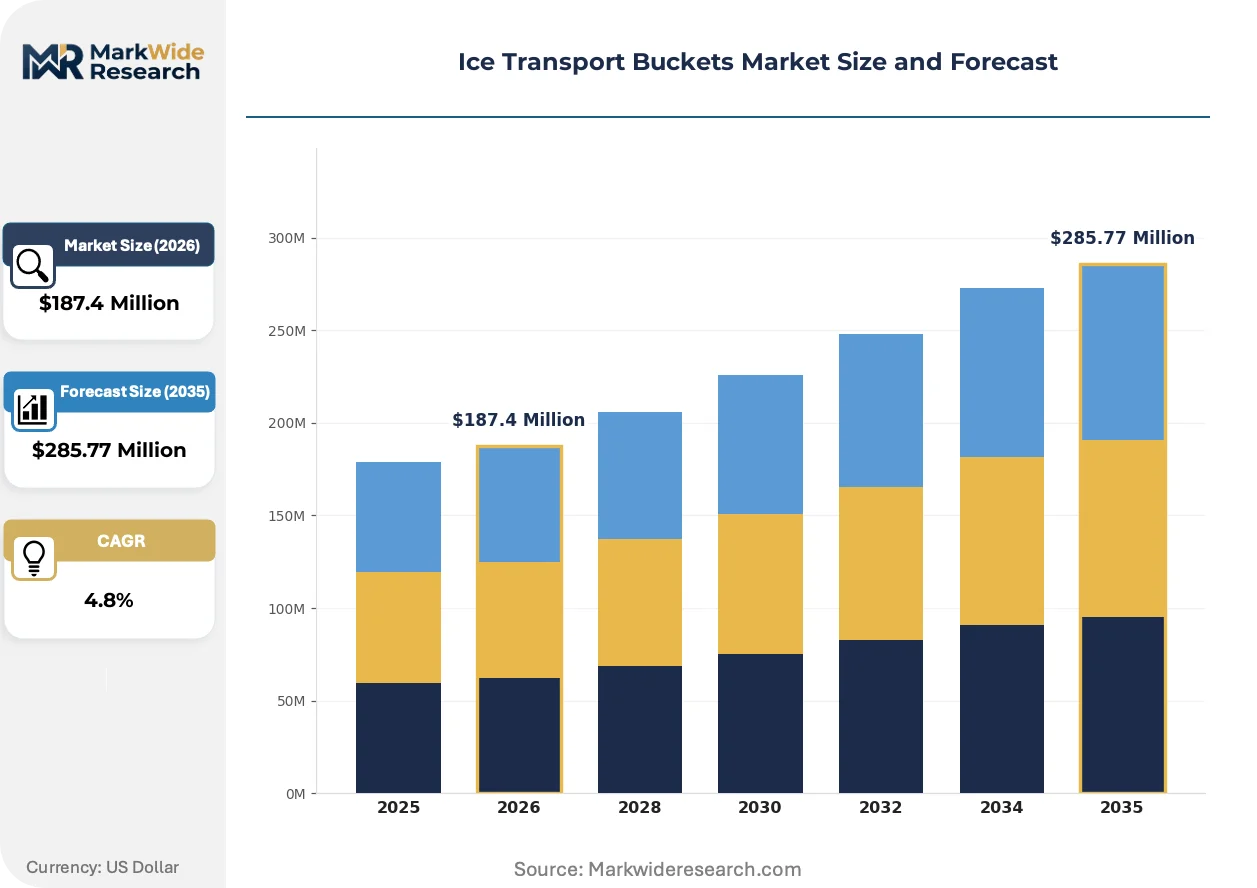
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated Buckets, Non-Insulated Buckets, Portable Buckets, Bulk Transport Buckets Material: Plastic, Aluminum, Stainless Steel, Fiberglass Size: Small, Medium, Large, Extra Large Application: Catering, Events, Outdoor Activities, Commercial Use |
| Companies Covered | Winco, Cambro Manufacturing, Vollrath Company, Igloo Products Corp., Beverage-Air, Leer Inc., Turbo Air, Polar Temp, Iowa Rotocast Plastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ice Transport Buckets Market Shifts & Advancements
Material science advances and regulatory pressure are converging to redefine performance benchmarks, with thermal efficiency and circularity credentials now outweighing unit cost in vendor selection criteria.
Phase-change material liners are hybridizing with conventional foam insulation to extend hold times beyond twelve hours in catering applications. Large-scale event operators in Texas and Florida are piloting these vessels for multi-site beverage service. The technology is hybridizing product categories by blurring distinctions between portable ice storage and active refrigeration systems.
The EU Green Deal's packaging waste directives are mandating minimum recycled-content thresholds for plastic food-contact equipment entering European markets. Manufacturers serving export channels are retooling compounding operations to incorporate post-industrial polyethylene streams. German and French distributors are now requiring supplier documentation of carbon footprint per unit shipped.
Aftermarket unbundling is accelerating as institutional buyers separate vessel procurement from replacement-part contracts. Hospital purchasing cooperatives are negotiating multi-year lid and gasket supply agreements independent of initial bucket purchases. This pattern concentrates most visibly in the southeastern United States where healthcare system consolidation has created super-regional buying entities.
Ice Transport Buckets Market Segmentation
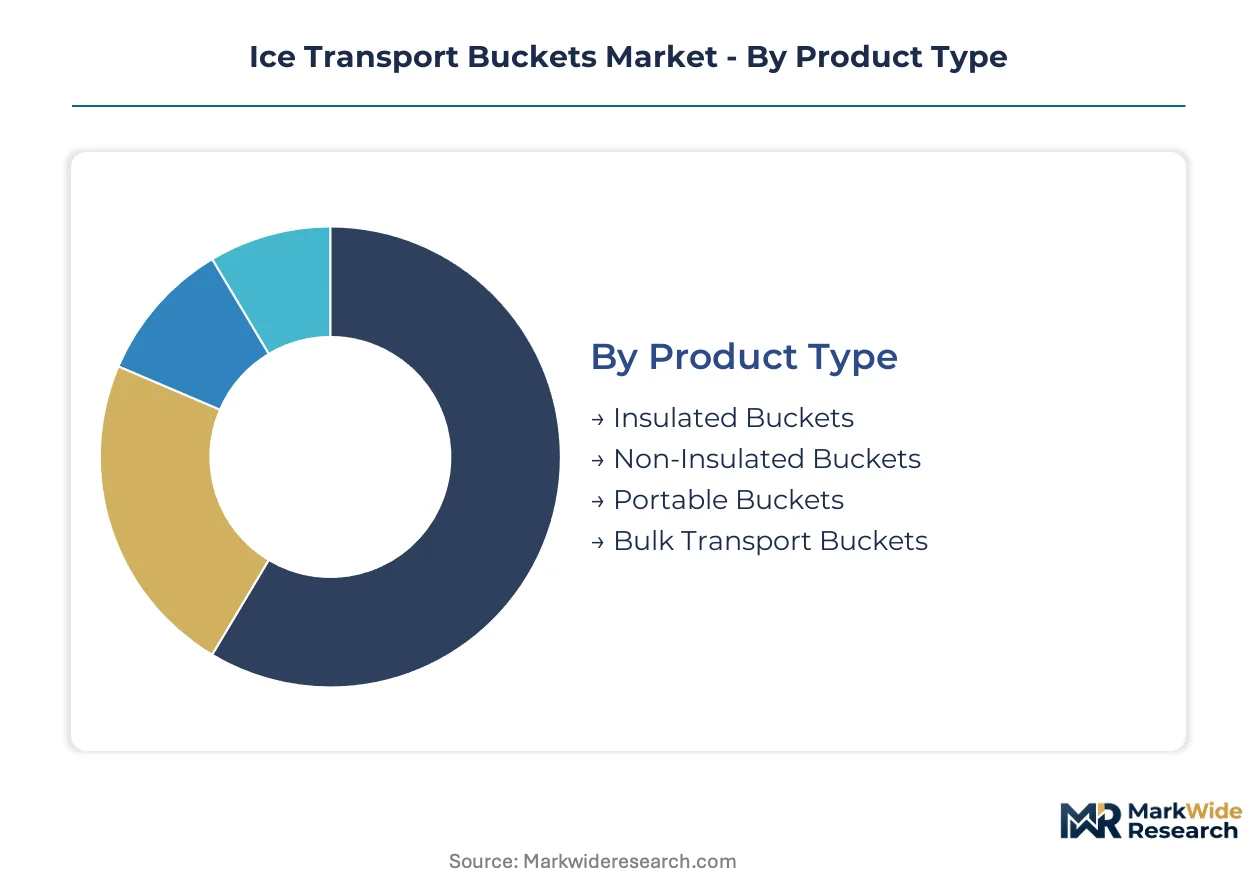
Segmentation in ice transport buckets reveals how thermal performance requirements and mobility constraints split procurement patterns across foodservice, healthcare, and recreational channels. Vendors must align product portfolios with distinct durability, sanitation, and capacity specifications that vary sharply by end-use environment.
Product Type:
Mature insulated formats anchor commercial foodservice procurement, while emerging smart-enabled and hybrid vessels are reshaping premium tier positioning.
- Insulated Buckets:Double-wall construction with polyurethane or polystyrene foam cores delivers 4-12 hour thermal retention for off-premise catering operations. Texas and Florida event logistics operators are scaling fleet purchases to serve multi-site beverage circuits where hold-time performance determines vendor selection.
- Non-Insulated Buckets:Single-wall polyethylene or metal construction prioritizes light weight and rapid turnover for high-volume, short-duration applications. Stadium concession operators across the United States favor these for ice replenishment cycles under two hours where thermal retention offers marginal value.
- Portable Buckets:Compact formats with ergonomic handles and wheeled bases target mobile bartending and poolside service.
- Bulk Transport Buckets:High-capacity rotomolded vessels with reinforced caster systems serve institutional kitchen-to-event logistics.
Insulated buckets handle the majority of throughput; portable buckets are expanding most quickly on share as mobile catering formats proliferate.
Material:
Cost tier stratification separates commodity resin formulations from premium metal specifications that command institutional certification premiums.
- Plastic:Rotomolded polyethylene dominates portable and mid-capacity segments with impact resistance and chemical inertness. FDA food-contact compliance requirements are disqualifying non-certified compounders from national foodservice distribution.
- Stainless Steel:304 and 316-grade fabrication satisfies NSF sanitation standards for hospital and long-term care environments where autoclave compatibility is mandatory. Northeastern United States healthcare systems are consolidating procurement through super-regional cooperatives that lock in multi-year stainless supply agreements.
- Aluminum:Lightweight rolled or cast construction serves recreational and light-commercial applications where thermal conductivity is acceptable.
- Fiberglass:Reinforced thermoset resins offer chemical resistance for industrial and specialized food processing environments.
Plastic commands volume leadership; stainless steel captures the steepest margin expansion trajectory as healthcare procurement consolidates.
Size:
Application-driven volume requirements segment procurement across individual server mobility versus centralized bulk distribution workflows.
- Small:1-5 gallon capacity formats with single-hand portability target bartending and tableside service. Boutique catering operators in California and New York are standardizing on compact insulated vessels for wine and champagne service at vineyard weddings and rooftop events.
- Large:20-40 gallon rotomolded vessels with forklift pockets and heavy-duty casters serve centralized ice storage for festival and stadium operations. Southeast United States outdoor event circuits are driving fleet standardization around 30-gallon formats that optimize trailer cube utilization.
- Medium:5-15 gallon crossover formats balance mobility with capacity for mid-scale catering operations.
- Extra Large:40+ gallon bulk containers with pallet-base compatibility target institutional commissary and distribution center applications.
Large formats handle the majority of institutional throughput; small formats are gaining share fastest as premium mobile catering segments expand.
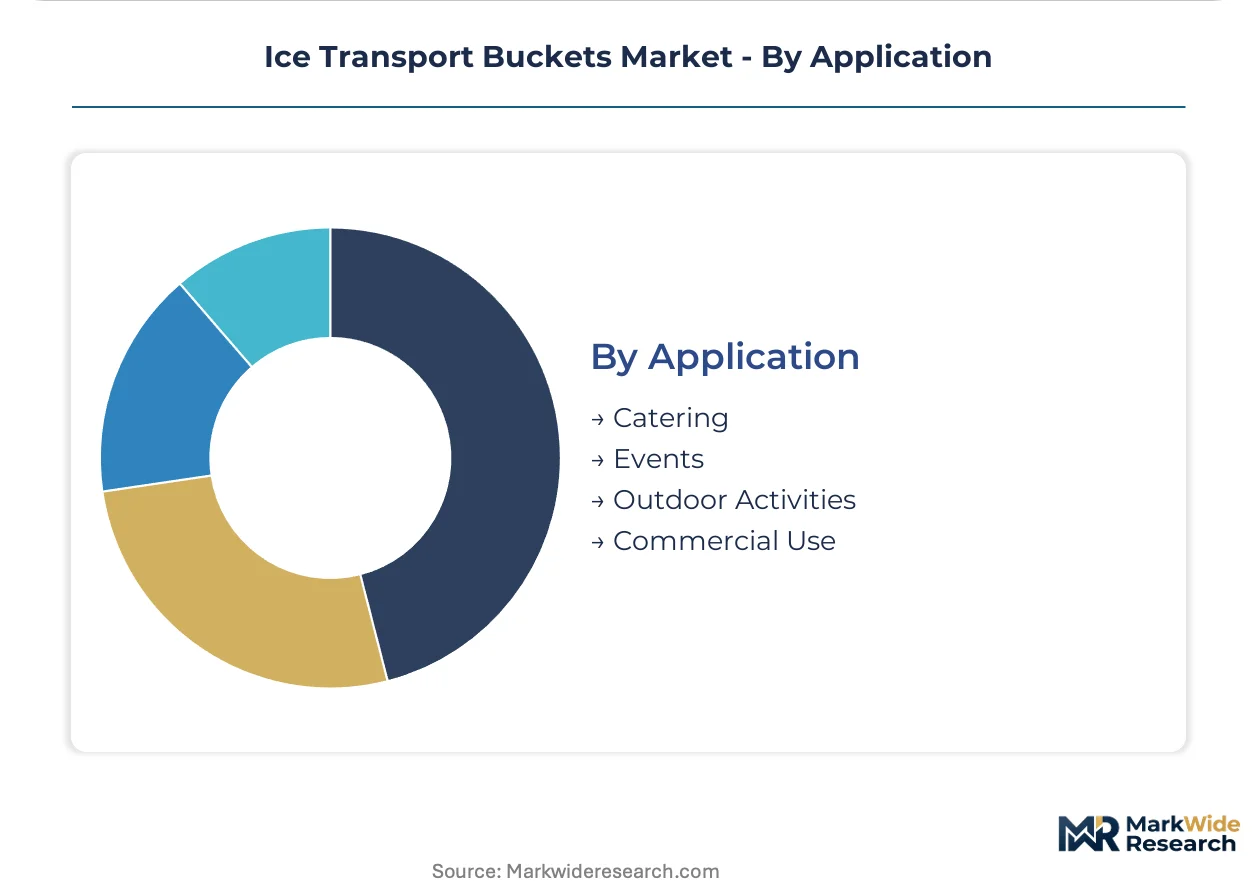
Application:
Customer type differentiation separates high-frequency commercial operators from intermittent recreational purchasers with divergent durability and price sensitivity profiles.
- Catering:Full-service and drop-off operators require NSF-certified vessels with validated thermal performance for health department compliance. Off-premise catering expansion across the United States is elevating replacement-part availability and fleet standardization as competitive differentiators in vendor selection.
- Commercial Use:Institutional foodservice, healthcare, and hospitality buyers prioritize sanitation documentation and multi-year total cost of ownership. Hospital purchasing cooperatives in the southeastern United States are unbundling vessel procurement from lid and gasket replacement contracts to optimize lifecycle economics.
- Events:Festival, wedding, and corporate gathering operators demand rapid-deployment formats with branding compatibility.
- Outdoor Activities:Recreational boating, camping, and tailgating purchasers prioritize retail availability and consumer-brand recognition over commercial specifications.
Commercial use handles the majority of procurement volume; catering is climbing the fastest on share as off-premise event formats proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Institutional buyers in Germany tolerate stainless steel premiums for NSF-certified durability, while high-turnover event operators in Brazil prioritize low-unit-cost polyethylene formats.
United States
FDA food-contact compliance and off-premise catering expansion drive vessel procurement across Texas and Florida event circuits. NSF International certification requirements disqualify non-validated suppliers from national foodservice distribution. Southeast hospital purchasing cooperatives unbundle lid and gasket contracts from initial bucket purchases.
Germany
EU Green Deal packaging waste directives mandate minimum recycled-content thresholds for plastic food-contact equipment. REACH chemical restrictions force reformulation cycles that delay product launches. Bavarian and North Rhine-Westphalian distributors now require carbon footprint documentation per unit shipped.
China
Rotomolded polyethylene capacity scales to serve domestic catering infrastructure and export manufacturing. GB standards govern food-contact material safety for vessels distributed domestically. Yangtze River Delta fabricators supply both local event logistics operators and North American private-label programs.
Brazil
Stadium concession and festival circuit operators favor low-cost non-insulated formats for rapid ice replenishment cycles. ANVISA regulates food-contact materials for commercial foodservice equipment. São Paulo event logistics clusters drive volume procurement for multi-site beverage service.
Canada
Healthcare procurement consolidation across Ontario and Quebec sustains stainless steel specification premiums. Health Canada guidelines align with FDA food-contact protocols for cross-border supply chains. Atlantic Canada seafood processing operations demand chemical-resistant fiberglass variants for industrial cold storage.
Ice Transport Buckets Market Competitive Landscape
Specialized fabricators and diversified foodservice equipment conglomerates split the market along material expertise lines. Vendor concentration remains moderate, with incumbent manufacturers defending positions through distributor network depth and replacement-part availability. Three archetypes dominate: rotomolded polyethylene specialists, stainless steel institutional fabricators, and consumer-brand hybrids extending into light-commercial channels. Competitive moves center on aftermarket service unbundling and geographic expansion through distributor partnerships.
Among North American diversified manufacturers, Cambro Manufacturing, Vollrath Company, and Igloo Products Corp. exemplify distinct strategic positions. Cambro Manufacturing represents the distributor-network archetype with extensive replacement-part infrastructure. Vollrath Company anchors the stainless steel fabrication tier for institutional channel penetration. Igloo Products Corp. occupies the consumer-brand hybrid position extending recognition into light-commercial applications.
| Leading Market Players |
|---|
| Winco |
| Cambro Manufacturing |
| Vollrath Company |
| Igloo Products Corp. |
| Beverage-Air |
| Leer Inc. |
| Turbo Air |
| Polar Temp |
| Iowa Rotocast Plastics |
| Others |
Supply & Pricing Matrix
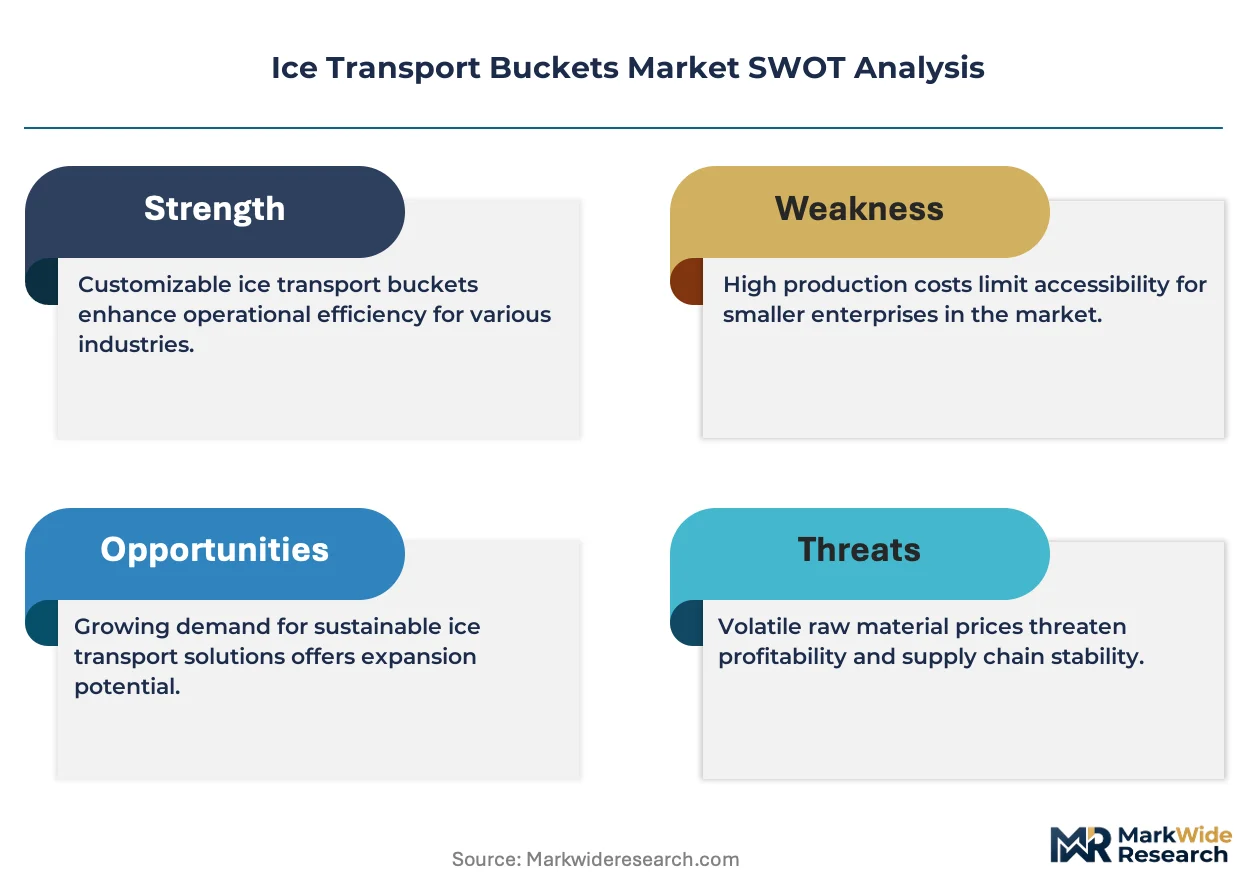
Rotomolded polyethylene capacity utilization across the Yangtze River Delta sits at elevated levels, compressing margin buffers for commodity-format producers while simultaneously elevating pricing leverage for manufacturers with validated FDA material traceability systems and captive replacement-part infrastructure.
Pricing Analysis
Aftermarket service revenue from replacement lids, gaskets, and caster assemblies now drives lifetime value capture more than initial vessel sales. Three-tier pricing structure across premium insulated, standard portable, and economy non-insulated levels separates NSF-certified institutional specifications from high-turnover event formats. Cost compression in commodity polyethylene tiers is intensifying because resin prices fluctuate with crude oil benchmarks. Stadium concession operators exhibit the highest price sensitivity, while hospital purchasing cooperatives tolerate stainless steel premiums for validated sanitation documentation.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for rotomolded polyethylene sourcing. Manufacturing concentrates in China, the United States, and Germany, with compounding operations drawing from petrochemical feedstocks in the Middle East and North America. Single-source vulnerability in FDA-certified resin grades threatens production continuity for export-bound shipments. Distribution runs through national foodservice equipment distributors, with direct-to-caterer e-commerce emerging as a secondary channel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Replacement-part and service contracts are expanding faster than hardware sales, converting transactional vessel procurement into recurring-revenue relationships that reshape enterprise value calculations across the value chain.
For Market Incumbents: Insulate market position by deepening backward integration into rotomolded polyethylene compounding operations and expanding captive replacement-part fulfillment networks. Cambro Manufacturing's distributor infrastructure demonstrates how parts availability locks in fleet standardization. Vertical control over FDA-certified resin sourcing neutralizes petrochemical price volatility threats. For New Entrants and Emerging Players: Establish a beachhead in direct-to-caterer digital channels where incumbent distributor relationships remain underdeveloped. The mid-scale catering segment in Texas and Florida offers the most penetrable white space, with event logistics operators prioritizing rapid-deployment formats over institutional certification. A digital-first fulfillment model with transparent replacement-part pricing bypasses traditional foodservice distribution gatekeepers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with unbundled lid and gasket supply agreements independent of initial vessel purchases. Long-term viability across the next decade rests on circular economy positioning and closed-loop recycling program scale. The signal to monitor is state-level extended producer responsibility mandate adoption, which will consolidate share toward first-mover recyclers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | FDA-certified captive supply secures margin stability against petrochemical volatility. |
| Replacement-Part Infrastructure Expansion | Multi-year lid and gasket contracts lock in hospital purchasing cooperative loyalty. |
| Direct-to-Caterer E-Commerce Launch | Digital fulfillment recovers margin compression from national distributor agreements. |
| Closed-Loop Recycling Program Development | California and New York EPR mandates create first-mover certification advantages. |
| Smart Cold-Chain Integration Partnership | RFID-enabled temperature logging opens pharmaceutical logistics adjacencies. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with rotomolded fabricators, foodservice distributor procurement heads, hospital GPO contract managers, and catering fleet operators; and secondary validation against FDA food-contact substance filings, NSF International certification databases, customs trade records, and state-level extended producer responsibility regulatory texts. Bottom-up vessel shipment estimates triangulated against top-down foodservice equipment spending patterns.
Forecast inputs span insulated versus non-insulated product mix, material grade stratification across polyethylene and stainless steel, and application channel expansion in off-premise catering against healthcare procurement consolidation. Segmentation dimensions modeled include thermal performance tier, material certification level, capacity format, and end-use environment across commercial foodservice, healthcare, and recreational channels. CAGRs derived from elasticity-adjusted demand projections and replacement-cycle velocity assumptions.
Sensitivities concentrate around petrochemical price volatility, REACH reformulation delays for European-bound shipments, and state-level EPR mandate adoption timing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Sugarcane Bottles Market
Beverage Packaging
North America Soft Drinks Packaging Market
Beverage Packaging
Dispensing Carboy Market
Beverage Packaging
Beverage Cans Market
Beverage Packaging
Bullet Bottles Market
Beverage Packaging
Juice Packaging Market
Beverage Packaging
Bowl Cans Market
Beverage Packaging
Bottled Water Packaging Market
Beverage Packaging
Skep Bottle Market
Beverage Packaging
Pre-Made Cups Market
Beverage Packaging
Foamer Bottle Market
Beverage Packaging
Cardboard Flask Market
Beverage Packaging
Cup Sleeves Market
Beverage Packaging
Drink Hoses Market
Beverage Packaging
Light Water Tap Market
Beverage Packaging
Cup Filler Market