
 Marine Telematics Market | 2026-2036
Marine Telematics Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Telematics Market Outlook
Subscription-based fleet connectivity leasing is reconfiguring capital deployment across the marine telematics sector. ORBCOMM Inc. leverages satellite-terrestrial hybrid networks to sustain recurring revenue from cargo vessel operators. KVH Industries, Inc. anchors its position through compact VSAT terminals designed for mid-size commercial fleets. Garmin Ltd. competes in recreational boating through integrated chartplotter-communication ecosystems that reduce hardware fragmentation.
Marine telematics encompasses the integrated hardware-software systems that transmit, receive, and process vessel operational data via satellite, cellular, and radio-frequency links, typically operating across L-band, Ku-band, and VHF maritime frequencies with latency thresholds under 500 milliseconds for safety-critical applications. These systems enable real-time position reporting, engine diagnostics, and environmental compliance monitoring for ship operators and maritime authorities. Fleet Management applications dominate value capture due to long-term service contracts tied to fuel optimization and regulatory reporting, while IoT-enabled sensor networks represent the fastest-expanding technology layer as hull-mounted devices proliferate for predictive maintenance. GPS and AIS product categories remain mature with compressed hardware margins, whereas Satcom terminals command premium pricing through bandwidth arbitrage on high-throughput satellite constellations.
The International Maritime Organization enforces vessel data collection through its Data Collection System for fuel consumption monitoring, while the EU MRV Regulation mandates emissions verification for ships calling at European ports. The US Coast Guard implements AIS carriage requirements under 33 CFR Part 164, creating baseline connectivity demand for domestic and international vessels operating in US waters. Stakeholders must weigh satellite constellation refresh cycles against regulatory compliance deadlines when committing to multi-year fleet upgrade programs.
Market Dynamics
The International Maritime Organization's emissions data mandates are forcing fleet operators to retrofit legacy vessels with connected monitoring infrastructure, compressing upgrade timelines and reshaping vendor contract structures toward long-term service bundling.
Growth Catalysts
- EU MRV Regulation:Mandatory emissions verification for vessels calling at European ports sustains baseline demand for fuel monitoring sensors and automated reporting software.
- Hull-mounted IoT proliferation:Predictive maintenance applications for engine diagnostics and structural integrity monitoring expand addressable hardware attach rates across commercial fleets.
- Norway's maritime technology cluster:Dense concentration of system integrators and satellite service providers accelerates R&D spillover into adjacent Nordic shipping markets.
Market Restraints
- Satellite bandwidth cost volatility:L-band and Ku-band lease rates fluctuate with constellation refresh cycles, squeezing margins for fleet connectivity providers locked into multi-year service contracts.
- Hardware margin compression in GPS/AIS:Mature positioning and collision-avoidance categories face commoditization as generic chipset suppliers capture value downstream.
- Radio-frequency spectrum fragmentation:Inconsistent maritime frequency allocation across coastal jurisdictions complicates terminal design and certification costs.
Strategic Opportunities
- Recreational boating digitization:Integrated chartplotter-communication ecosystems remain underpenetrated in mid-tier leisure vessel segments outside established North American and Mediterranean bases.
- High-throughput satellite constellations:VSAT terminal demand concentrates in mid-size commercial fleets seeking to arbitrage bandwidth pricing against legacy L-band contracts.
- Subscription-based fleet connectivity leasing:Capital-light service models reduce upfront hardware barriers for smaller cargo operators in emerging Southeast Asian shipping corridors.
Industry Challenges
- Retrofit integration complexity:Legacy vessel communication architectures require extensive middleware development to interface with modern IP-based sensor networks, extending deployment timelines.
- Maritime cybersecurity certification:Evolving threat vectors and fragmented national standards for connected ship systems delay product approval cycles and inflate compliance staffing requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Telematics Market |
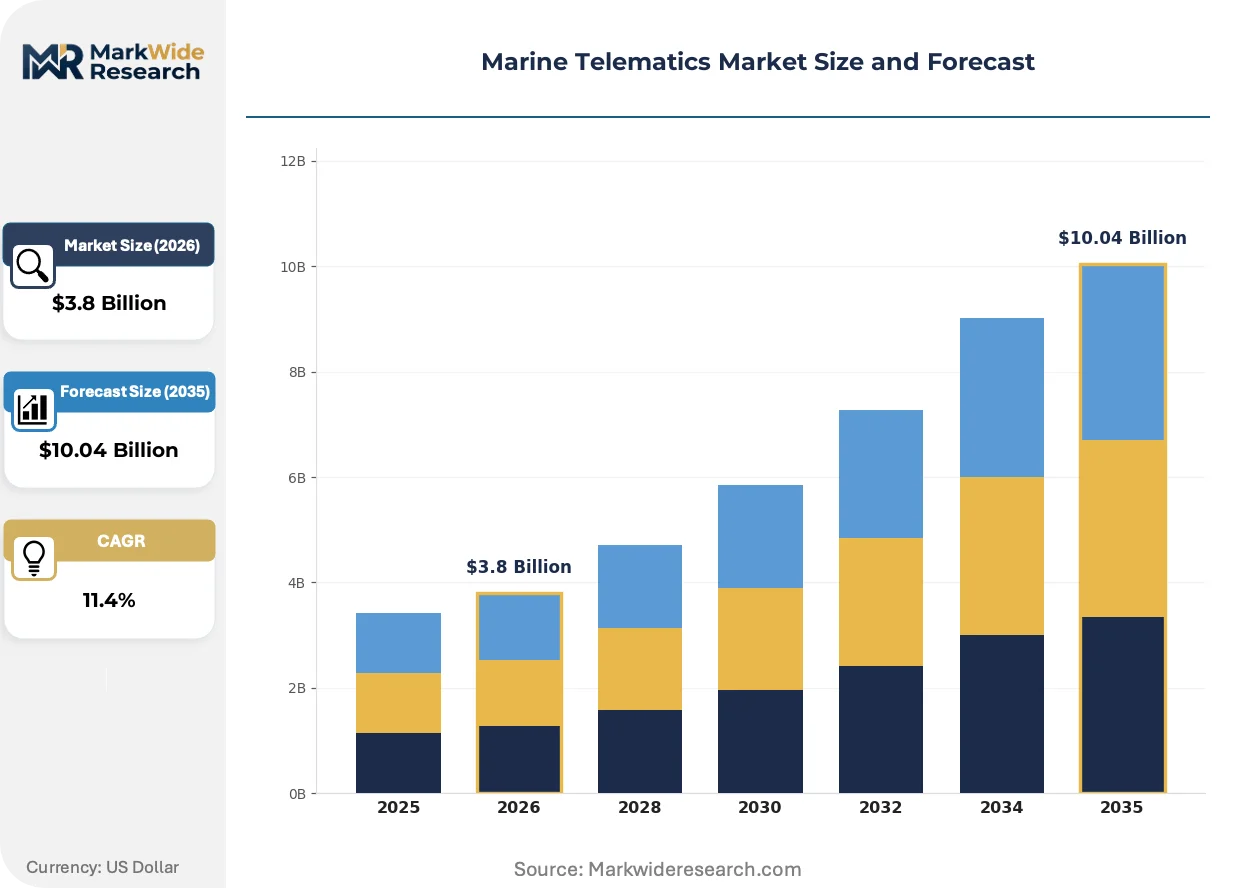
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GPS, AIS, VHF Radio, Satcom Technology: Cloud Computing, Big Data, IoT, Mobile Application Application: Fleet Management, Cargo Tracking, Weather Monitoring, Safety Navigation End User: Commercial Shipping, Recreational Boating, Fisheries, Government Agencies |
| Companies Covered | Teledyne Technologies, Inc., ORBCOMM Inc., Garmin Ltd., Furuno Electric Co., Ltd., KVH Industries, Inc., Kongsberg Gruppen ASA, Inmarsat plc, Iridium Communications Inc., Wärtsilä Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Telematics Market Strategic Shifts
Maritime connectivity architecture is pivoting from proprietary closed systems toward modular, software-defined platforms that decouple hardware refresh cycles from service layer upgrades. This shift compresses vendor lock-in periods and accelerates feature deployment velocity.
Edge computing capabilities are migrating from shore-based data centers to vessel-mounted processing units. Commercial shipping operators with route-optimization requirements deploy onboard analytics engines to reduce satellite uplink costs and enable sub-second decision latency for autonomous navigation assists. This architecture is migrating from centralized cloud dependency toward distributed hull intelligence, fragmenting traditional hardware-software bundling models.
The US Coast Guard enforces AIS carriage requirements under 33 CFR Part 164, creating baseline connectivity demand for domestic and international vessels operating in US waters. Ship operators must reconcile these mandates with overlapping EU MRV data formats, driving consolidation around multi-protocol terminal designs. The compliance burden falls heaviest on smaller fleet operators lacking dedicated regulatory technology staff.
Fleet procurement patterns favor outcome-based fuel efficiency guarantees over discrete hardware purchases. Cargo vessel operators in trans-Pacific routes increasingly contract for guaranteed consumption reductions, transferring performance risk to telematics vendors. This reconfiguration concentrates contract value with integrated service providers capable of sensor deployment, data analytics, and optimization consulting.
Marine Telematics Market Segmentation
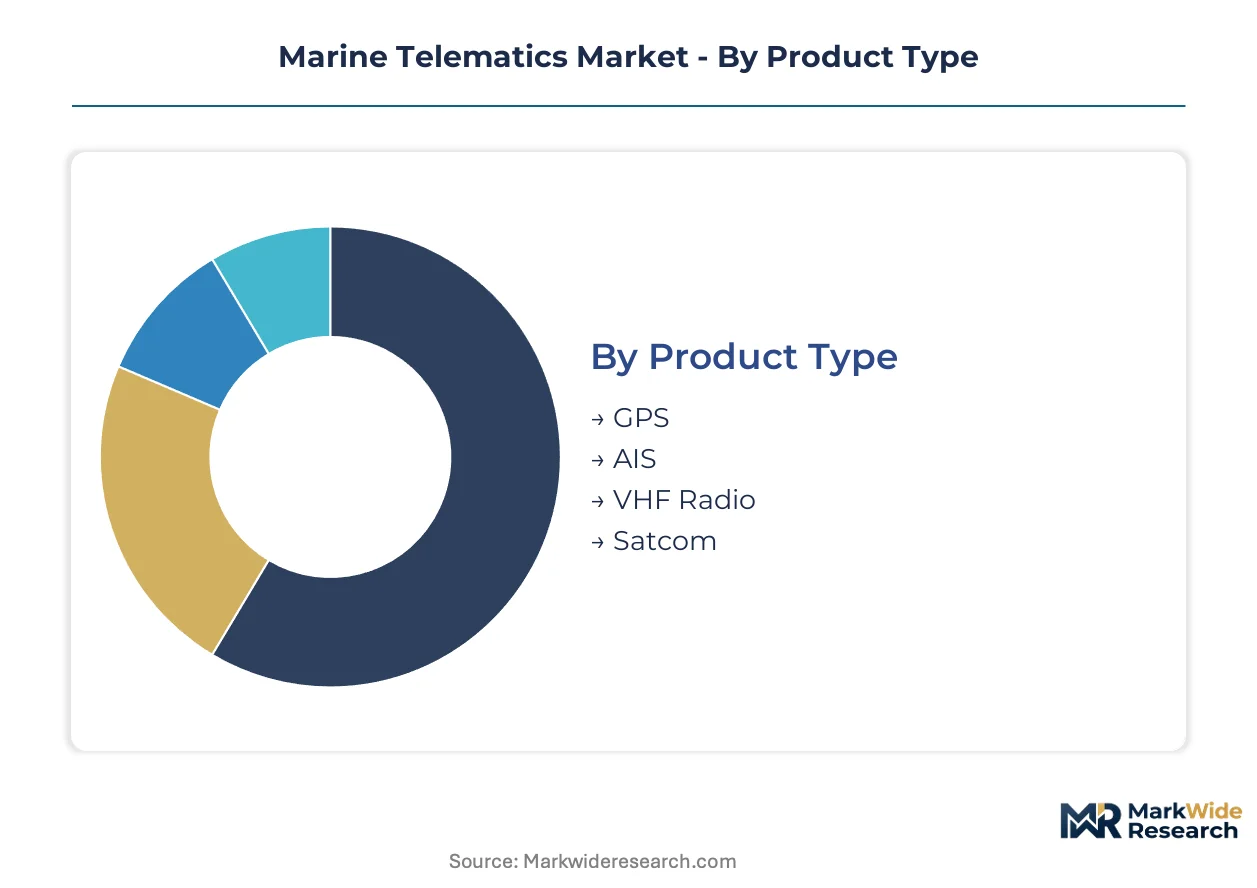
Marine telematics segmentation reveals how hardware commoditization, software service layers, and regulatory compliance requirements stratify value capture across vessel types and operational profiles. Product architecture and end-use intensity determine margin structures and contract durability.
Product Type:
Cost tier stratification separates commoditized positioning hardware from premium bandwidth arbitrage equipment serving commercial fleets.
- GPS:Satellite-based positioning receivers utilizing L1/L2 frequency bands deliver sub-meter accuracy for vessel tracking. Commercial shipping operators in Singapore and Rotterdam deploy GPS as baseline infrastructure, though chipset commoditization compresses hardware margins and shifts value toward correction service subscriptions.
- Satcom:VSAT and L-band terminals enable high-throughput data transmission across Ku-band and Ka-band frequencies for fleet connectivity. Norwegian operators leverage compact stabilized antennas to arbitrage bandwidth pricing against legacy contracts, with terminal vendors bundling multi-year service agreements to lock in recurring revenue.
- AIS:Automatic Identification System transceivers broadcast vessel position, course, and speed on VHF maritime channels for collision avoidance. US Coast Guard mandates under 33 CFR Part 164 sustain baseline demand despite mature hardware economics.
- VHF Radio:Short-range voice and data communication systems operate on marine VHF frequencies for port operations and distress signaling. Coastal jurisdictions require carriage for vessels under domestic flag registries.
Satcom holds installed capacity. GPS is rotating up the share rankings through service layer attachment.
Technology:
Application maturity separates established cloud infrastructure from emerging edge computing deployments reshaping vessel data architecture.
- IoT:Hull-mounted sensor networks transmit engine diagnostics, structural integrity metrics, and environmental compliance data via low-power wireless protocols. Predictive maintenance applications for commercial tanker fleets in the Persian Gulf drive hardware attach rate expansion as operators seek to minimize unscheduled dry-docking.
- Cloud Computing:Centralized data processing platforms aggregate fleet-wide operational telemetry for route optimization and regulatory reporting. Large container operators consolidate multi-vessel analytics through shore-based data lakes, though latency constraints limit real-time navigation applications.
- Big Data:Historical voyage pattern analysis identifies fuel consumption anomalies and port congestion prediction models. Charterers in the Baltic trade route leverage aggregated fleet datasets to benchmark vessel performance against comparable tonnage.
- Mobile Application:Smartphone and tablet interfaces deliver crew-accessible voyage planning, weather routing, and maintenance logging. Recreational boating segments in the Mediterranean adopt integrated chartplotter-communication ecosystems that reduce hardware fragmentation for mid-tier leisure vessels.
Cloud Computing holds installed capacity. IoT is climbing the fastest through predictive maintenance contract expansion.
Application:
End-use intensity differentiates long-term service contracts from discrete hardware sales based on operational criticality and regulatory exposure.
- Fleet Management:Integrated vessel monitoring platforms combine position reporting, fuel optimization, and maintenance scheduling for commercial operators. EU MRV Regulation compliance requirements sustain multi-year service contracts tied to emissions verification and automated reporting software for vessels calling at European ports.
- Safety Navigation:Real-time collision avoidance, weather routing, and distress signaling systems integrate AIS, radar, and satellite data feeds. SOLAS-mandated equipment carriage creates non-discretionary demand independent of commercial cycle fluctuations.
- Cargo Tracking:Container-level sensor deployment monitors location, temperature, and shock events through cellular and satellite links. Reefer container operators on trans-Pacific routes contract for condition monitoring to reduce spoilage claims and insurance premiums.
- Weather Monitoring:Meteorological data integration for route optimization and severe weather avoidance. Fishing fleets in the North Atlantic subscribe to granular sea state forecasting to minimize gear damage and crew safety incidents.
Fleet Management holds installed capacity. Safety Navigation is gaining share fastest through regulatory mandate expansion.
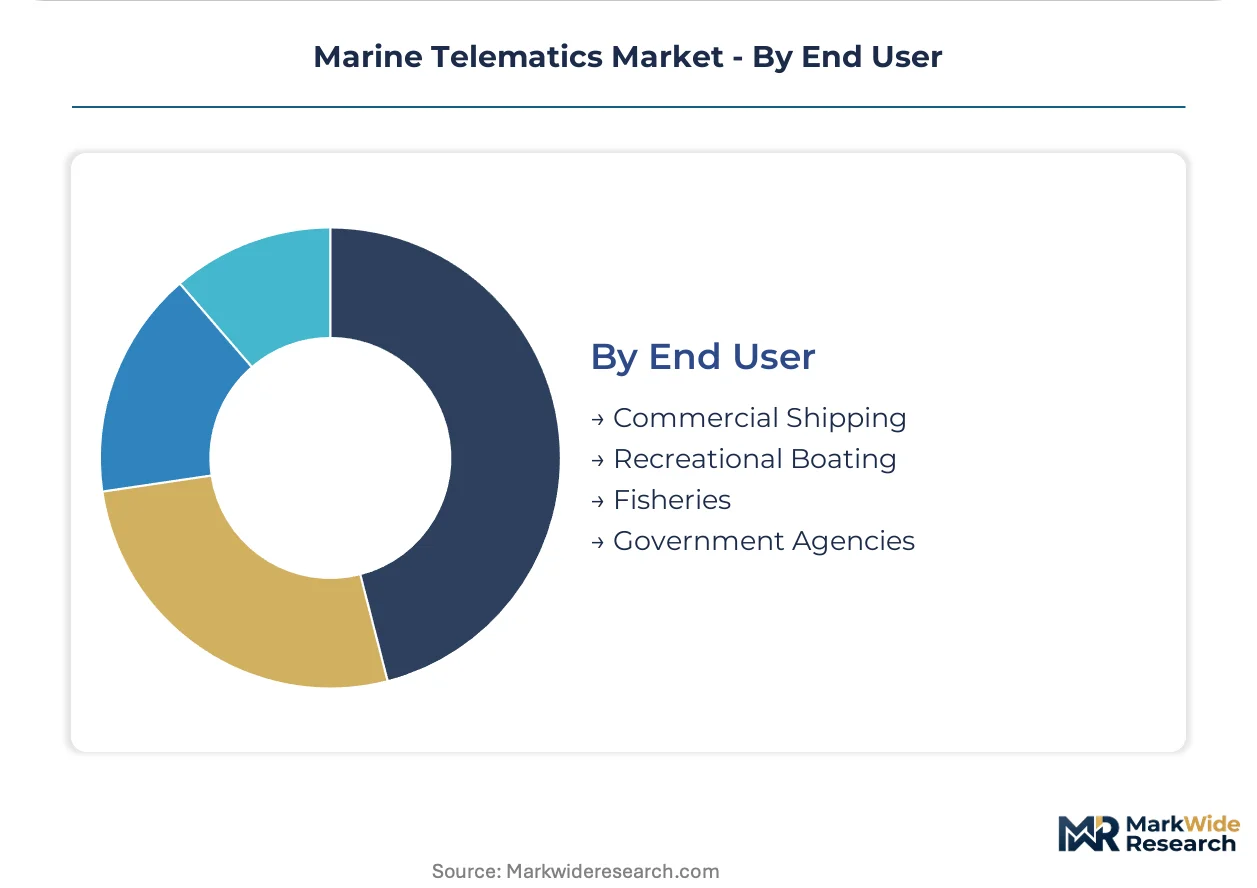
End User:
Customer type determines procurement sophistication, contract structure preferences, and price sensitivity across operational scale.
- Commercial Shipping:Deep-sea cargo vessel operators and tanker fleets deploy comprehensive telematics stacks for regulatory compliance and fuel optimization. Outcome-based contracting transfers performance risk to vendors, with guaranteed consumption reductions replacing discrete hardware purchases on major trade routes.
- Recreational Boating:Leisure vessel owners and charter operators prioritize integrated navigation-communication ecosystems with simplified user interfaces. Mid-tier segments outside established North American and Mediterranean bases remain underpenetrated, presenting expansion opportunity for subscription-based connectivity leasing.
- Fisheries:Commercial fishing operations require catch monitoring, quota compliance, and crew safety systems for EEZ operations. National fisheries regulators in Iceland and New Zealand mandate vessel monitoring system carriage to combat illegal, unreported, and unregulated fishing.
- Government Agencies:Coast guards, navies, and maritime authorities deploy secure, encrypted telematics for search and rescue, border enforcement, and fleet logistics. Procurement prioritizes cybersecurity certification and sovereign data control over cost optimization.
Commercial Shipping holds installed capacity. Recreational Boating is rotating up the share rankings through digitization penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial shipping operators and recreational fleet owners concentrate demand in maritime corridors with dense port infrastructure and stringent emissions enforcement. Norway, the United States, Singapore, Germany, and Japan anchor regional deployment patterns through distinct regulatory frameworks and technology clusters.
Norway
Deep-sea fleet operators in Oslo and Bergen drive sensor deployment for fuel optimization and EU MRV compliance. The Norwegian Maritime Authority enforces stringent emissions verification protocols for vessels under domestic registry. Kongsberg Gruppen ASA anchors a dense maritime technology cluster in Kongsberg, exporting integrated bridge systems across Nordic shipping markets.
United States
Coastal cargo operators and recreational boating fleets sustain dual demand tracks for fleet management and integrated navigation ecosystems. The US Coast Guard implements AIS carriage requirements under 33 CFR Part 164, mandating baseline connectivity for domestic and international vessels. KVH Industries, Inc. maintains manufacturing and R&D concentration in Rhode Island, serving mid-size commercial fleets with compact VSAT terminals.
Singapore
Container transshipment operators and tanker fleets deploy comprehensive telematics stacks for route optimization through the Strait of Malacca. The Maritime and Port Authority of Singapore mandates digital reporting for vessels calling at the port, compressing upgrade timelines for legacy fleet infrastructure. Technology integrators cluster in the Tuas industrial corridor, supporting predictive maintenance rollouts across Southeast Asian shipping corridors.
Germany
Elbe River container operators and North Sea fishing fleets sustain demand for regulatory compliance and catch monitoring systems. The Federal Maritime and Hydrographic Agency enforces emissions data collection aligned with EU MRV frameworks, driving automated reporting software adoption. Hamburg anchors a concentration of system integrators and satellite service providers serving Baltic and North Atlantic trade routes.
Japan
Domestic coastal shipping operators and distant-water fishing fleets require vessel monitoring systems for EEZ operations and quota compliance. The Japan Coast Guard mandates AIS carriage and position reporting for vessels over specified tonnage thresholds. Tokyo and Yokohama host dense concentrations of electronics manufacturers and maritime technology specialists exporting integrated bridge systems across Asia-Pacific markets.
Marine Telematics Market Competitive Environment
Channel-controlling players compete with product-specialist players across hardware, service, and integrated platform layers. The vendor base stratifies into satellite service providers, terminal manufacturers, and system integrators with overlapping but distinct value capture models. Three archetypes dominate: bandwidth arbitrage specialists leveraging constellation refresh cycles, hardware-software bundlers capturing recurring service revenue, and navigation ecosystem integrators reducing device fragmentation for recreational segments. Consolidation pressure concentrates in satellite service provision, while terminal manufacturing retains fragmentation due to specialized antenna stabilization requirements.
Within the satellite communications tier, Inmarsat plc and Iridium Communications Inc. occupy positions as established service infrastructure providers. ORBCOMM Inc. exemplifies the hybrid network archetype, combining satellite and terrestrial links for cargo vessel operators. Among Nordic system integrators, Kongsberg Gruppen ASA and Wärtsilä Corporation represent the integrated platform approach, bundling sensor deployment with optimization consulting for commercial fleets.
| Leading Market Players |
|---|
| Teledyne Technologies, Inc. |
| ORBCOMM Inc. |
| Garmin Ltd. |
| Furuno Electric Co., Ltd. |
| KVH Industries, Inc. |
| Kongsberg Gruppen ASA |
| Inmarsat plc |
| Iridium Communications Inc. |
| Wärtsilä Corporation |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in L-band satellite transponder leasing across the North Atlantic corridor compresses vendor margins while concentrating pricing power with constellation operators. Fleet connectivity providers absorb cost volatility through multi-year service bundling, transferring risk to cargo operators locked into emissions compliance deadlines.
Pricing Analysis
Cost-plus contracts indexed to Ku-band lease rates dominate commercial fleet connectivity agreements, with terminal vendors embedding multi-year bandwidth commitments into hardware financing packages. Three-tier pricing structure across premium stabilized VSAT, standard L-band terminals, and economy cellular-hybrid units separates performance tiers by antenna stabilization grade and throughput guarantees. Price differentiation centers on certification tier — IMO-compliant safety systems command 40-60% premiums over recreational-grade equivalents. Pricing pressure stems from hardware commoditization in GPS/AIS categories, where generic chipset suppliers erode terminal manufacturer margins. Smaller cargo operators in Southeast Asian shipping corridors exhibit highest price sensitivity, while EU-flagged deep-sea fleets prioritize compliance-grade equipment over cost optimization.
Supply Chain Analysis
Contract manufacturing concentrates with Jabil Circuit and Flex Ltd. holding stabilized antenna assembly capacity, while Foxconn and Pegatron dominate consumer-grade GPS chipset packaging. Geographic supply concentration clusters in Taiwan for RF component fabrication, South Korea for high-precision gyroscopic sensors, and China for aluminum antenna housing extrusion. Raw material dependencies draw from gallium arsenide substrates for L-band amplifiers, rare earth magnets for antenna stabilization motors, and marine-grade aluminum alloys for corrosion-resistant enclosures. Single-source vulnerability runs through gallium arsenide wafer supply, where two foundries control 80% of merchant capacity. Distribution runs through system integrator channels in Norway, Singapore, and Germany, with direct OEM relationships dominating large fleet procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine telematics is crossing into platform economics as software-defined terminals decouple hardware refresh from service layer upgrades, fragmenting vendor lock-in periods and accelerating ecosystem interoperability.
For Market Incumbents: Insulate recurring revenue streams by deepening captive satellite bandwidth positions through long-term constellation lease commitments before Ka-band refresh cycles compress arbitrage margins. Consolidate middleware capabilities to capture retrofit integration complexity premiums as legacy vessel architectures proliferate across aging commercial fleets. Threat substitution from low-earth orbit constellations demands defensive certification investment in multi-protocol terminal designs. For New Entrants and Emerging Players: Southeast Asian mid-tier cargo corridors offer underpenetrated white-space for subscription-based connectivity leasing, where capital-light service models reduce upfront hardware barriers. Recreational boating digitization in Mediterranean mid-tier segments presents secondary entry point through integrated chartplotter-communication ecosystems. Go-to-market execution should anchor on outcome-based fuel efficiency guarantees rather than discrete equipment sales, transferring performance risk to vendor balance sheets. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-defined terminal sub-segments as hardware-software decoupling reduces inventory carrying costs and accelerates feature deployment velocity. Long-term viability favors integrated platform providers with sensor deployment, data analytics, and optimization consulting capabilities over pure-play hardware manufacturers. Acquisition target archetype: Nordic system integrators with dense maritime technology clusters and established EU MRV compliance service relationships. Signal to watch: constellation refresh cycle announcements from Inmarsat and Iridium as bandwidth pricing inflection triggers.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Terminal Migration | Decouples hardware refresh cycles from service layer upgrades, compressing vendor lock-in periods. |
| Multi-Protocol Certification Investment | Enables simultaneous EU MRV, US Coast Guard AIS, and IMO DCS compliance through unified terminal architectures. |
| Outcome-Based Contracting Transition | Transfers fuel optimization performance risk from cargo operators to telematics vendors on trans-Pacific routes. |
| Edge Computing Vessel Deployment | Migrates analytics engines from shore-based data centers to hull-mounted processing units for sub-second navigation latency. |
| Satellite Bandwidth Arbitrage Positioning | Leverages Ka-band constellation refresh against legacy L-band contracts for mid-size commercial fleet capture. |
Study Parameters
The analysis maps satellite communications infrastructure, hull-mounted sensor networks, and regulatory compliance software layers, each validated through vessel operations directors, fleet procurement managers, maritime authority regulators, and terminal manufacturer product strategists. Primary fieldwork combined structured interviews with secondary triangulation against IMO circulars, EU MRV implementation guidance, US Coast Guard NVICs, satellite operator service disclosures, and customs records for VSAT terminal trade flows. Bottom-up vessel deployment counts and top-down bandwidth consumption estimates were reconciled through iterative stakeholder feedback.
Assumptions held satellite constellation refresh timelines and regulatory compliance deadlines fixed across the projection horizon, while fuel price volatility and trade route demand patterns were modeled as scenario variables. Segmentation dimensions spanned product architecture, technology maturity, application intensity, and end-user procurement sophistication, with vessel tonnage class and flag registry as industry-specific stratifiers. CAGRs were derived from installed base expansion rates and service contract renewal intensity, incorporating predictive maintenance attach rate trajectories and recreational boating digitization penetration curves as forward indicators.
Practitioners should monitor constellation launch delays, emissions regulation enforcement variance across port states, and cybersecurity certification standard fragmentation for early signals of forecast revision. Quarterly review of satellite bandwidth lease rate indices, IMO circular amendment schedules, and fleet operator capex disclosure patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Telematics in Automotive Market
Telematics and Infotainment
Automotive Navigation Solutions Market
Telematics and Infotainment
Connected Car Market
Telematics and Infotainment
In-Taxi Digital Signage Market
Telematics and Infotainment
Electric Vehicle Infotainment Market
Telematics and Infotainment
Consumer Telematics Market
Telematics and Infotainment
Electric Vehicle Telematics Market
Telematics and Infotainment
Asia Pacific Automotive Navigation System Market
Telematics and Infotainment
Europe Automotive Navigation System Market
Telematics and Infotainment
C-V2X OBU Market
Telematics and Infotainment
Asia-Pacific Automotive Telematics Market
Telematics and Infotainment
Automotive Dashboard Camera Market
Telematics and Infotainment
Internet of Cars Market
Telematics and Infotainment
Global 5G in Automotives Market
Telematics and Infotainment
North America Automotive Navigation System Market
Telematics and Infotainment
Mobile Resource Management (MRM) Market