
 Park Assist Camera Market | 2026-2036
Park Assist Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Park Assist Camera Market Insights
East Asian sensor fabs are recalibrating capacity allocation toward automotive-grade image sensors as EV platforms multiply camera counts per vehicle. Continental AG leverages its integrated electronics architecture to bundle park assist cameras with domain controllers, reducing wiring complexity for OEM customers. Robert Bosch GmbH anchors its position through in-house semiconductor capabilities that sustain supply security during foundry allocation cycles. Valeo competes on thermal management expertise, allowing its camera modules to operate across wider temperature ranges than standard alternatives.
A park assist camera is a vehicle-mounted imaging sensor, typically operating at 720p to 2-megapixel resolution with IP67 sealing and low-lux sensitivity below 0.1 lux, designed to feed real-time video into surround-view processing units for obstacle detection and automated parking maneuvers. Front cameras and 360-degree camera arrays dominate value capture as OEMs standardize surround-view systems on mid-range and premium trims, while rear cameras represent the mature volume base driven by regulatory mandates. Digital technology leads new design wins over legacy analog interfaces, though embedded systems with on-chip image signal processing are gaining traction as automakers seek to reduce central compute loads.
NHTSA Federal Motor Vehicle Safety Standard 111 mandates rear-visibility systems on all light vehicles sold in the United States, directly expanding the installed base of park assist cameras. Euro NCAP assessment protocols reward multi-camera configurations with higher safety ratings, pushing European OEMs toward 360-degree coverage. China's MIIT new-energy vehicle technical guidelines encourage intelligent driving sensor suites, creating compliance-driven demand for camera integration. Stakeholders must monitor how ISO 26262 functional safety certification requirements evolve for camera modules, as ASIL-rated designs will separate qualified suppliers from commodity competitors.
Market Dynamics
OEM platform consolidation around domain-centralized architectures is compressing camera module counts while demanding higher per-unit resolution and processing capability, forcing suppliers to absorb silicon cost inflation without passing full burden to vehicle programs.
Growth Catalysts
- NHTSA Federal Motor Vehicle Safety Standard 111:Mandated rear-visibility systems on all US light vehicles sustain baseline camera deployment across mass-market and premium segments alike.
- Surround-view imaging:360-degree camera arrays are penetrating mid-range vehicle trims as OEMs differentiate through parking assistance user experience.
- Euro NCAP safety protocols:Higher ratings for multi-camera configurations push European automakers toward comprehensive coverage beyond regulatory minimums.
Market Restraints
- Automotive-grade image sensor allocation:Foundry capacity constraints at East Asian semiconductor fabs create supply bottlenecks during allocation cycles.
- ISO 26262 functional safety certification:ASIL-rated design requirements extend development timelines and qualification costs for module suppliers.
- Legacy analog interface installed base:Mature rear-camera volumes resist digital migration, fragmenting production runs and diluting scale economies.
Strategic Opportunities
- China MIIT new-energy vehicle guidelines:Intelligent driving sensor suite mandates create compliance-driven demand for integrated camera systems on domestic EV platforms.
- On-chip image signal processing:Embedded processing architectures reduce central compute loads and wiring complexity for domain-controller-integrated designs.
- Thermal management specialization:Extended operating temperature ranges enable camera deployment in commercial vehicle and off-highway applications beyond passenger car norms.
Industry Challenges
- Automotive vision algorithm talent scarcity:Shortage of embedded software engineers with functional safety expertise constrains supplier R&D velocity.
- Multi-generational platform integration:Simultaneous support for legacy analog and emerging digital interfaces fragments engineering resources and test protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Park Assist Camera Market |
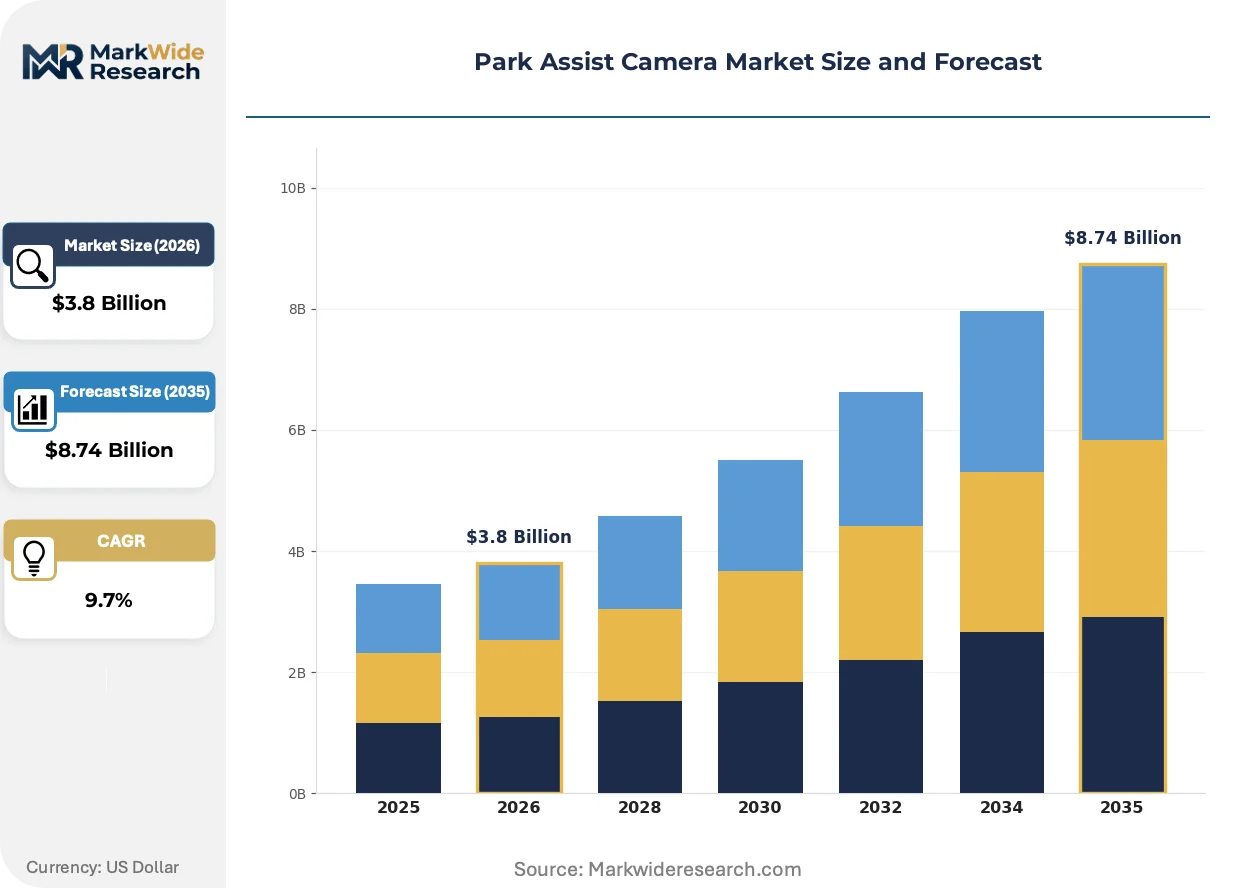
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Cameras, Rear Cameras, 360-Degree Cameras, Side Cameras Technology: Analog, Digital, Wireless, Embedded End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Owners Installation Type: Integrated, Standalone, Retrofit, Custom |
| Companies Covered | Continental AG, Valeo, Robert Bosch GmbH, Denso Corporation, Magna International, ZF Friedrichshafen AG, Ficosa, Gentex, Aptiv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Park Assist Camera Market Trends and Innovations
Resolution escalation and edge-processing migration are redefining camera module value propositions as automakers consolidate distributed sensors into centralized compute domains. These shifts compress hardware margins while elevating software and thermal engineering differentiation.
2-megapixel and higher-resolution image sensors are absorbing the functional requirements previously distributed across multiple lower-resolution units. Premium OEMs in Germany and South Korea are specifying these denser formats for front and surround-view positions. This concentration is absorbing wiring harness complexity and reducing module counts per vehicle platform.
Euro NCAP assessment protocols now weight multi-camera configurations directly into overall safety scoring, accelerating 360-degree system standardization across European OEM lineups. The industrial consequence is tiered supplier qualification where uncertified module makers face program exclusion. Mid-range European vehicle segments are responding fastest, bundling surround-view as trim-level differentiators.
Fleet procurement of automated parking systems is compressing traditional equipment-specification cycles for commercial vehicle operators. Leasing companies and logistics fleets are replacing discrete option selection with standardized sensor suites across vehicle classes. This pattern is most visible in German commercial vehicle channels, where total-cost-of-ownership calculations now embed parking-assistance downtime reduction.
Park Assist Camera Market Segmentation
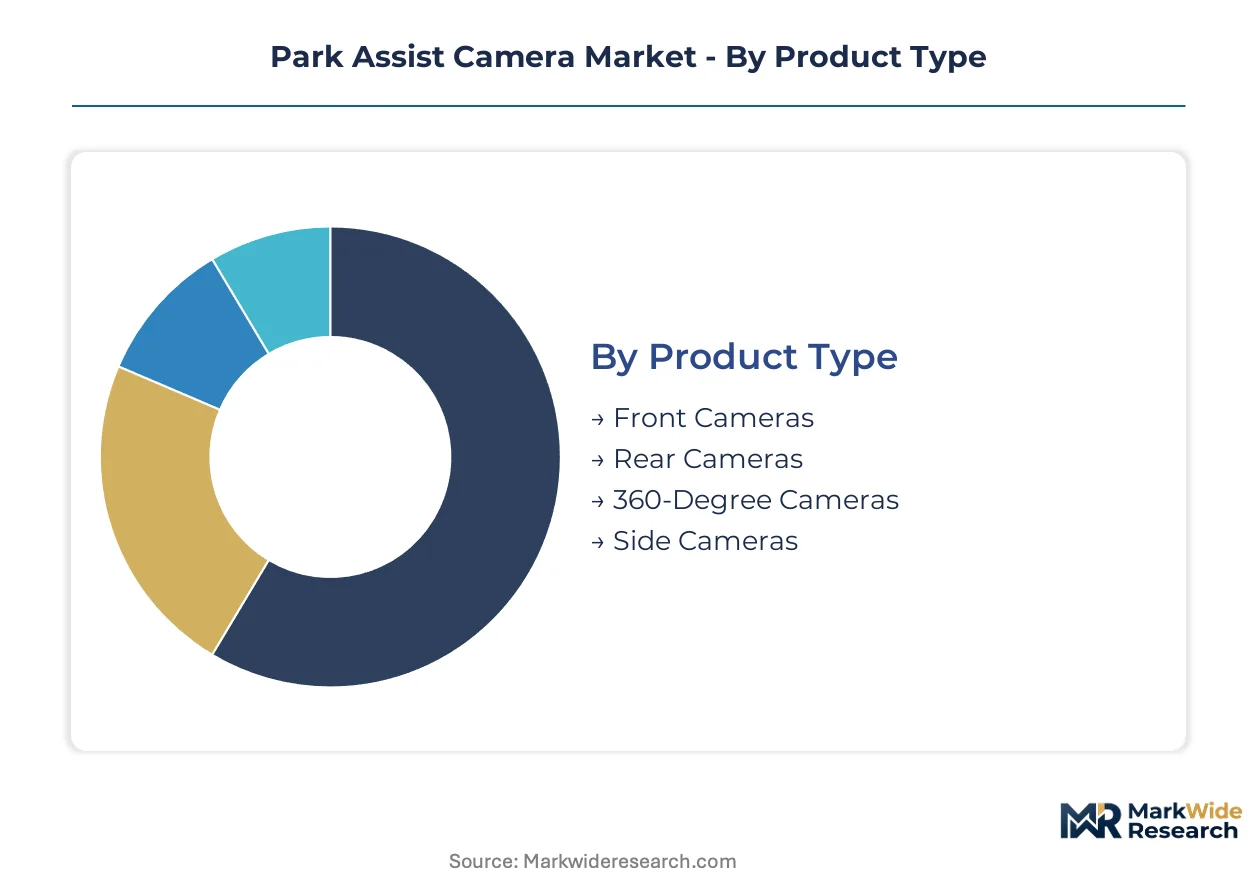
Segmentation in the park assist camera market reveals how resolution tiers, interface protocols, and integration depth fragment procurement patterns across passenger and commercial vehicle programs. OEM platform strategies create divergent volume concentrations that reshape supplier qualification criteria.
Product Type:
Standardization dominates rear-camera specifications driven by NHTSA Federal Motor Vehicle Safety Standard 111, while front and surround-view positions demand customized optical stacks and thermal profiles.
- Front Cameras:These modules operate at 2-megapixel resolution with dynamic range exceeding 120dB to handle direct sunlight ingress during forward-facing operation. German premium OEMs source heavily from domestic Tier-1 suppliers for these positions, prioritizing lane-keeping fusion compatibility over pure parking assistance.
- Rear Cameras:720p analog and digital variants with IP67 sealing constitute the mature volume base, with module costs compressed by regulatory mandate standardization across US and European mass-market platforms. Legacy interface persistence fragments production runs between analog legacy and digital migration pathways.
- 360-Degree Cameras:Multi-camera arrays with synchronized image stitching feed domain controllers for surround-view synthesis, penetrating mid-range trims as OEM differentiation tools.
- Side Cameras:Mirror-replacement and blind-spot monitoring positions extend operating temperature ranges beyond passenger car norms for commercial vehicle deployment.
Leading the category by volume: Rear Cameras. Growing fastest: 360-Degree Cameras.
Technology:
Cost tier stratification separates legacy analog infrastructure from digital and embedded architectures absorbing silicon cost inflation.
- Analog:CVBS and LVDS interfaces persist in rear-camera positions where regulatory minimums resist digital migration, fragmenting supplier production scale across interface generations.
- Digital:MIPI CSI-2 and GMSL2 protocols enable higher bandwidth for megapixel sensors, with South Korean and German OEMs specifying these for front and surround-view positions to consolidate wiring harness complexity.
- Wireless:Wi-Fi and UWB transmission eliminates coaxial cabling for retrofit and trailer-hitch applications, though latency constraints limit OEM adoption for safety-critical functions.
- Embedded:On-chip image signal processing reduces central compute loads, with ASIL-rated designs separating qualified suppliers from commodity competitors under ISO 26262 functional safety protocols.
Highest margin concentration: Embedded. Steepest expansion trajectory: Digital.
End User:
Customer type determines specification authority, with OEMs driving architecture consolidation while aftermarket channels capture replacement and upgrade demand.
- OEMs:Vehicle manufacturers specify camera resolution, interface protocol, and thermal envelope through platform engineering teams, with domain-centralized architectures compressing module counts while demanding higher per-unit capability.
- Tier-1 Suppliers:Continental AG and Robert Bosch GmbH integrate camera modules with domain controllers, reducing wiring complexity and absorbing qualification costs for ASIL-rated designs.
- Aftermarket Providers:Retrofit and upgrade channels serve vehicle owners seeking parking assistance additions beyond factory specification, with wireless transmission enabling simplified installation.
- Vehicle Owners:End-consumer procurement concentrates in fleet and leasing segments where total-cost-of-ownership calculations embed parking-assistance downtime reduction.
Dominant specification authority: OEMs. Fastest-growing procurement channel: Tier-1 Suppliers.
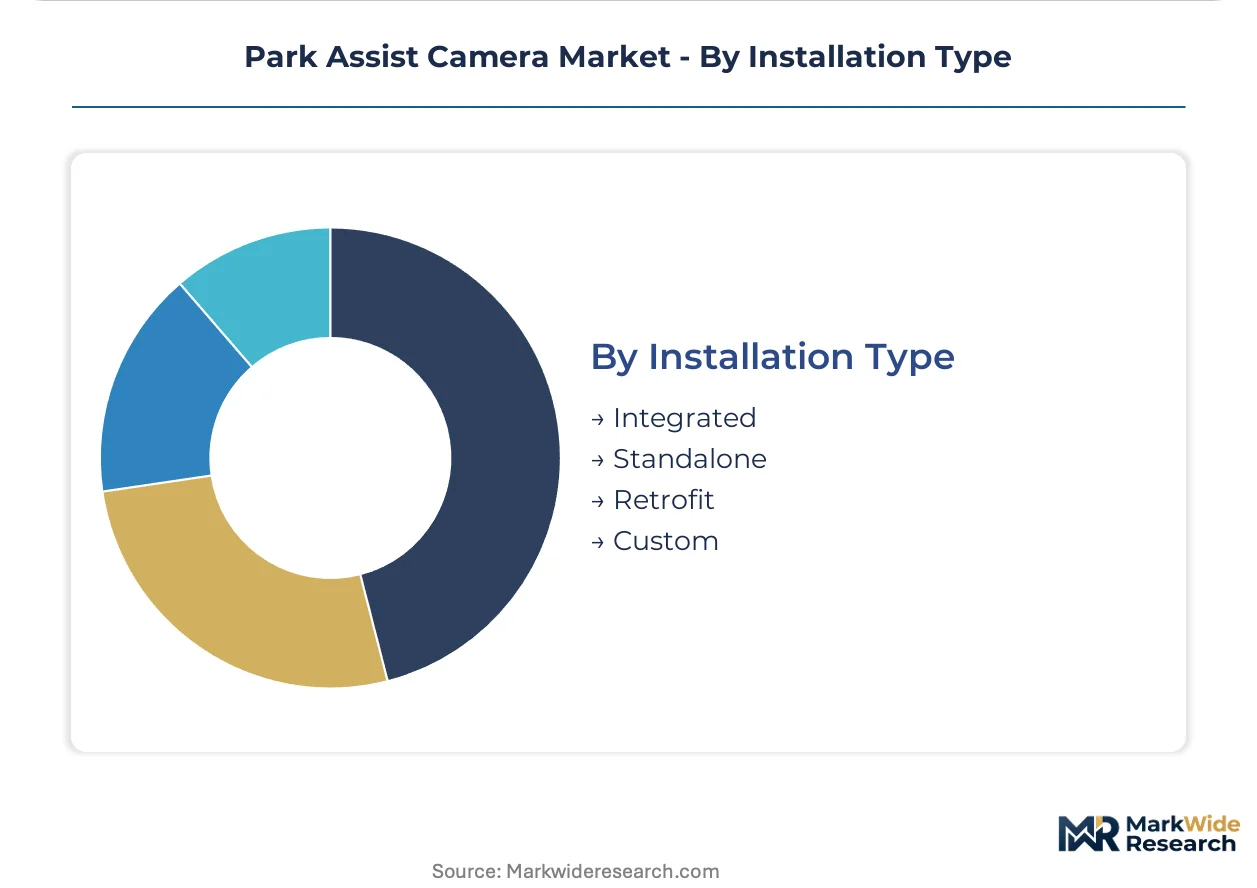
Installation Type:
Integration depth varies from factory-embedded domain controller attachment to standalone retrofit modules with independent processing.
- Integrated:Camera modules mount directly into bumper fascias and mirror housings with sealed electrical connectors, feeding surround-view processing units as permanent vehicle architecture elements.
- Standalone:Self-contained units with embedded displays serve commercial vehicle operators and off-highway equipment where factory camera specification remains absent.
- Retrofit:Wireless and minimal-wiring solutions attach to license plate frames or adhesive mounts, with Chinese EV platforms multiplying intelligent driving sensor suite mandates under MIIT guidelines.
- Custom:Specialized thermal management and extended temperature ranges enable deployment in mining, agriculture, and defense applications beyond passenger car norms.
Highest factory penetration: Integrated. Gaining share fastest: Retrofit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive-grade image sensor fabs and South Korean semiconductor foundries anchor regional supply capacity for park assist camera modules, with procurement patterns diverging sharply between regulatory-mandated rear-camera volumes and premium surround-view specifications.
United States
NHTSA Federal Motor Vehicle Safety Standard 111 sustains baseline rear-camera deployment across mass-market and premium vehicle segments alike. The regulation mandates rear-visibility systems on all light vehicles sold domestically, directly expanding installed base requirements. Detroit-area OEM engineering centers coordinate Tier-1 supplier qualification for domain-controller-integrated designs.
Germany
Premium automakers source heavily from domestic Tier-1 suppliers for front and surround-view camera positions, prioritizing lane-keeping fusion compatibility. Euro NCAP assessment protocols reward multi-camera configurations with higher safety ratings, pushing domestic OEMs toward 360-degree coverage. Stuttgart and Munich engineering clusters concentrate ASIL-rated design qualification expertise for functional safety certification.
China
MIIT new-energy vehicle technical guidelines encourage intelligent driving sensor suites, creating compliance-driven demand for camera integration on domestic EV platforms. East Asian sensor fabs are recalibrating capacity allocation toward automotive-grade image sensors as local EV platforms multiply camera counts per vehicle. Shanghai and Shenzhen electronics manufacturing corridors concentrate module assembly capacity for both domestic OEMs and export programs.
Japan
Domestic OEMs specify high-resolution front cameras with dynamic range exceeding 120dB for direct sunlight ingress conditions during forward-facing operation. METI industrial policy supports automotive semiconductor supply security through domestic foundry partnerships. Nagoya and Tokyo metropolitan engineering centers anchor Tier-1 supplier relationships for integrated electronics architecture development.
South Korea
Domestic OEMs specify MIPI CSI-2 and GMSL2 digital protocols for front and surround-view positions to consolidate wiring harness complexity. Semiconductor foundries allocate capacity toward automotive-grade image sensors as domestic EV platforms expand camera counts. Seoul metropolitan area engineering clusters concentrate domain-controller integration expertise for centralized compute architectures.
Park Assist Camera Market Competitive Landscape
Global majors compete with regional champions across functional safety certification and domain-controller integration capabilities, producing a tiered structure where ASIL-rated design qualification separates qualified suppliers from commodity competitors. The vendor base stratifies between integrated electronics architects, semiconductor-capable diversified suppliers, and thermal management specialists. Three archetypes dominate: domain-controller bundlers, in-house semiconductor producers, and extended-temperature-range module makers. Competitive moves concentrate on strategic partnerships for foundry allocation security and portfolio diversification toward embedded processing architectures.
Among Germany-based diversified suppliers, Continental AG and Robert Bosch GmbH exemplify the domain-controller integration archetype, while Valeo occupies a position representing thermal management specialization for extended operating temperature ranges.
| Leading Market Players |
|---|
| Continental AG |
| Valeo |
| Robert Bosch GmbH |
| Denso Corporation |
| Magna International |
| ZF Friedrichshafen AG |
| Ficosa |
| Gentex |
| Aptiv |
| Others |
Pricing and Supply Chain Analysis
Embedded vision engineering talent scarcity in Stuttgart and Munich engineering clusters widens labor-cost differentials between ASIL-certified module suppliers and commodity competitors, compressing pricing spreads across premium, standard, and economy tiers.
Pricing Analysis
Warranty and field-service bundling separates qualified Tier-1 suppliers from aftermarket providers, with Continental AG and Robert Bosch GmbH embedding multi-year service coverage into domain-controller-integrated camera modules. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 26262 certification grade and thermal management capability. Pricing pressure stems from foundry allocation cycles at East Asian semiconductor fabs, which force silicon cost absorption without full pass-through to OEM vehicle programs. Fleet procurement channels exhibit highest price sensitivity due to total-cost-of-ownership calculations, while German premium OEMs demonstrate lowest sensitivity when sourcing front-camera positions with lane-keeping fusion compatibility.
Supply Chain Analysis
Single-source vulnerability sits with automotive-grade image sensor foundry capacity concentrated in Taiwan, South Korea, and Japan. Raw material dependencies include silicon wafers, specialized optical glass, and IP67-rated sealing compounds. Tariff exposure on semiconductor imports from East Asian fabrication facilities presents structural risk to module cost structures. Distribution runs through Tier-1 supplier integration with OEM platform engineering teams, bypassing independent distributor networks for factory-fit camera systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
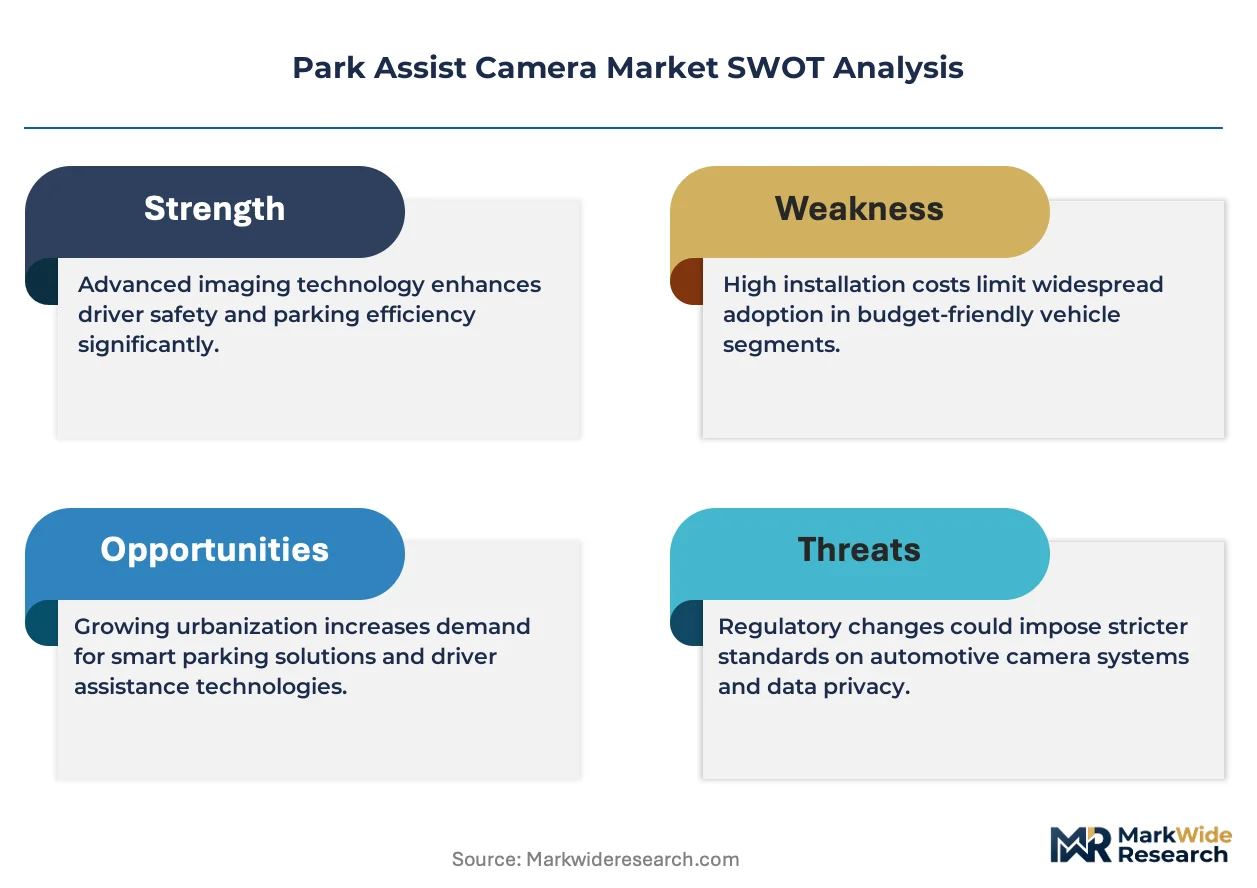
This market is consolidating around ASIL-rated functional safety certification, with ISO 26262 qualification timelines forcing weaker module suppliers toward program exclusion or acquisition.
For Market Incumbents: Cement supply security through captive foundry partnerships or long-term allocation agreements with East Asian semiconductor fabs. Deepen backward integration into image signal processing semiconductor design to reduce central compute load dependency. Defend against thermal management specialists like Valeo by extending operating temperature range specifications for commercial vehicle applications. For New Entrants and Emerging Players: Aftermarket wireless retrofit channels offer lowest barrier to entry, with Chinese EV platforms under MIIT intelligent driving guidelines creating compliance-driven demand for simplified camera installation. Target trailer-hitch and commercial vehicle segments where factory specification gaps persist. Pursue partnerships with domestic Tier-2 electronics assemblers in Shenzhen and Shanghai manufacturing corridors to bypass incumbent qualification bottlenecks. For Investors and Strategic Acquirers: Re-rating potential sits with embedded processing architecture specialists given on-chip image signal processing migration reducing central compute loads. Long-term viability favors suppliers with in-house semiconductor capabilities or secured foundry allocation across the projection horizon. Watch NHTSA rear-visibility mandate expansion to commercial vehicle classes as inflection indicator for volume acceleration beyond passenger car norms.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-Rated Design Certification | ISO 26262 functional safety qualification separates qualified suppliers from commodity competitors in OEM procurement. |
| Foundry Allocation Security | Long-term semiconductor supply agreements with Taiwan and South Korean fabs mitigate silicon cost volatility. |
| Domain Controller Integration | Bundling camera modules with centralized compute architectures reduces wiring complexity for German premium OEMs. |
| Embedded Processing Migration | On-chip image signal processing reduces central compute loads and elevates software differentiation. |
| Thermal Management Specialization | Extended temperature range capabilities enable penetration of commercial vehicle and off-highway equipment markets. |
Research Methodology
Independent corroboration across OEM platform engineering teams, Tier-1 supplier procurement leads, and aftermarket distributor networks underwrites the qualitative findings. Primary fieldwork engaged automotive semiconductor sourcing managers, domain controller integration specialists, and thermal engineering directors at module suppliers. Secondary validation drew from NHTSA Federal Motor Vehicle Safety Standard 111 regulatory filings, Euro NCAP assessment protocol documentation, and vehicle production databases. Bottom-up camera module shipment estimates triangulated against top-down OEM platform content analysis.
Rate-of-change decomposition across the analysis window separates volume growth from value migration toward higher-resolution and embedded processing architectures. Segmentation dimensions modeled include camera position, interface protocol, integration depth, and OEM tier classification. CAGRs derived from production volume trajectories weighted by resolution tier and regional regulatory compliance requirements. Forecast inputs incorporated foundry capacity allocation cycles and MIIT new-energy vehicle guideline implementation timelines.
Caveats apply where East Asian semiconductor fab allocation disruptions or NHTSA mandate scope revisions could materially shift the outlook. Forecasts reflect assumptions about domain-centralized architecture penetration and analog-to-digital interface migration velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
India Connected Car Market
Telematics and Infotainment
Commercial Telematics Market
Telematics and Infotainment
Global in Dash Navigation System Market
Telematics and Infotainment
Advanced Traveller Information System Market
Telematics and Infotainment
Electronic Rotary Controller Systems for Infotainment Market
Telematics and Infotainment
APAC Internet of Cars Market
Telematics and Infotainment
Vehicle Trip Computers Market
Telematics and Infotainment
Motor Racing Telematics Market
Telematics and Infotainment
United States Commercial Telematics Market
Telematics and Infotainment
Global Car Digital Cockpit Market
Telematics and Infotainment
APAC Telematics Market
Telematics and Infotainment
Asia-Pacific Automotive Telematics Market
Telematics and Infotainment
Telematics and Connectivity Control Unit Systems Market
Telematics and Infotainment
Europe Telematics Market
Telematics and Infotainment
Asia-Pacific Connected Cars Market
Telematics and Infotainment
Car Generated Data Market