
 Europe Dashboard Camera Market | 2026-2036
Europe Dashboard Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Dashboard Camera Market Foresight
CE marking and E-mark certification under ECE R10 electromagnetic compatibility standards is collapsing the supplier base to technically qualified manufacturers. Nextbase leverages its in-house firmware development to sustain premium positioning across UK retail channels. Garmin Ltd. anchors its European presence through integrated GPS dashcams that compete on mapping accuracy rather than price alone. Valeo differentiates via OEM supply relationships with French and German automakers, controlling factory-fit installation volumes that aftermarket rivals cannot replicate.
A dashboard camera is a windscreen-mounted digital video recorder capturing continuous footage through CMOS or CCD image sensors with resolutions from 1080p to 4K, designed to document traffic incidents, driver behavior, and road conditions for insurance and legal evidence. Dual-channel systems integrating front and cabin-facing lenses command higher average selling prices and margin pools as fleet managers prioritize driver monitoring alongside forward recording. Wi-Fi-enabled models are displacing SD-card-dependent units as real-time footage transfer becomes standard for taxi services and ride-sharing operators. Aftermarket installation still dominates volume but OEM fitment is accelerating as automakers bundle dashcams within connected-car packages.
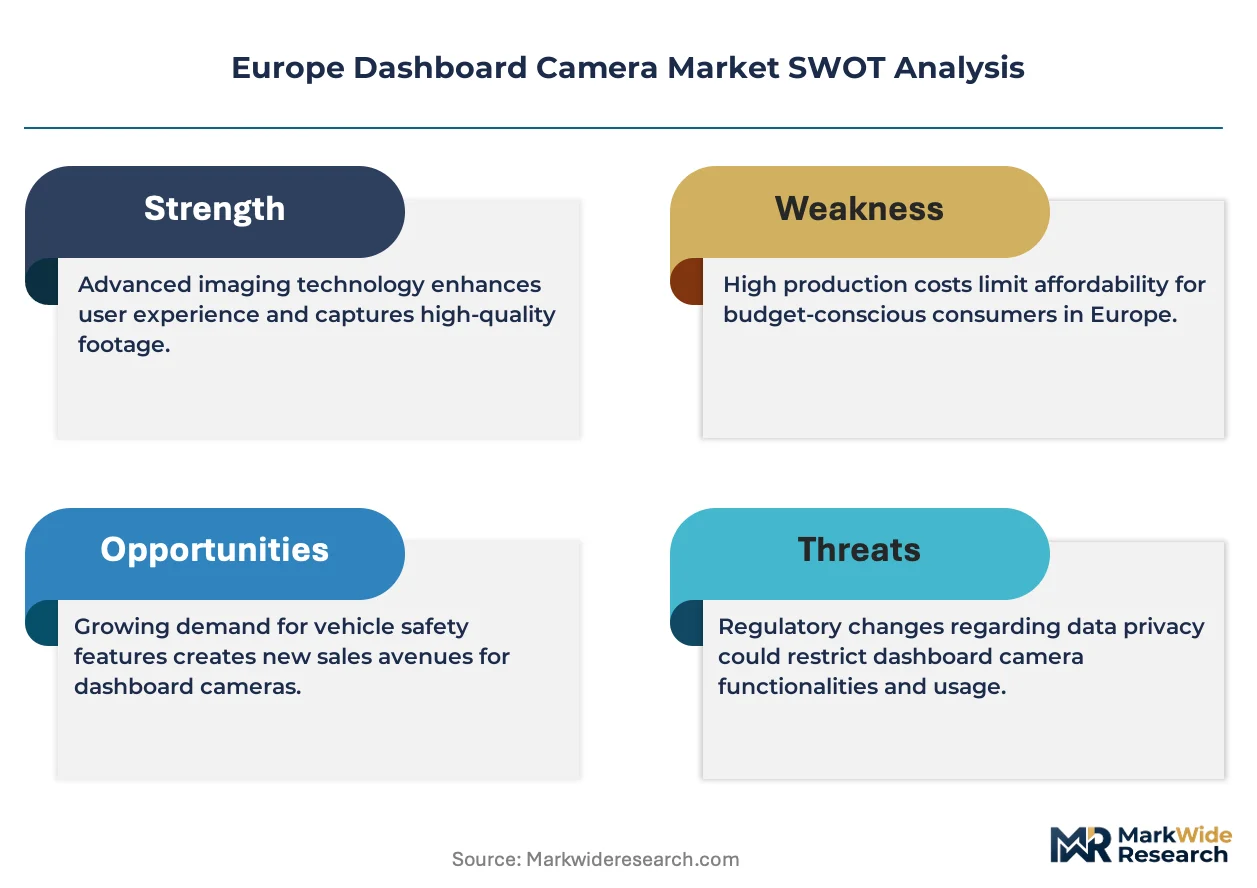
The EU General Safety Regulation mandates intelligent speed assistance and event data recording capabilities that EMA and national type-approval bodies are enforcing through homologation requirements. GDPR compliance for video footage storage and biometric data handling adds a second regulatory layer that shapes product architecture and cloud service design. The EU AI Act's risk classification for driver monitoring systems will further constrain which technology configurations gain market access. Stakeholders must monitor how CE marking evolution and data protection enforcement interact to determine which product portfolios retain commercial viability across member states.
Market Dynamics
The EU General Safety Regulation is compressing product development cycles as E-mark certification requirements force manufacturers to redesign hardware architectures for electromagnetic compatibility compliance before vehicles reach European roads.
Growth Catalysts
- Intelligent Speed Assistance Mandates:The EU General Safety Regulation requires event data recording capabilities that fleet operators across Germany and Poland must satisfy through video telematics deployments.
- Insurance Premium Incentives:German logistics corridors now offer documented premium reductions for dashcam-equipped commercial vehicles, creating sustained procurement pull from trucking firms.
- Wi-Fi-Enabled Real-Time Transfer:Taxi services and ride-sharing operators are replacing SD-card-dependent units with cloud-connected systems for immediate footage accessibility.
Market Restraints
- GDPR Compliance Architecture:Video footage storage and biometric data handling requirements add development costs that constrain smaller firmware developers from entering European markets.
- CE Marking Concentration:ECE R10 electromagnetic compatibility standards are collapsing the supplier base to technically qualified manufacturers with in-house testing facilities.
- Dual-Channel Cost Premium:Front and cabin-facing lens systems command higher average selling prices that limit penetration among price-sensitive private vehicle owners.
Strategic Opportunities
- OEM Factory-Fit Bundling:French and German automakers are accelerating connected-car packages that integrate dashcams at production, locking out aftermarket rivals from new vehicle sales.
- AI Act Risk Classification:The EU AI Act's driver monitoring system categories will create tiered market access that rewards early compliance investments.
- Fleet Telematics Convergence:Video systems merging with GPS tracking and driver behavior analytics present white space for integrated service providers serving commercial operators.
Industry Challenges
- Homologation Timeline Compression:EMA and national type-approval bodies are enforcing shorter certification windows that strain engineering resource allocation.
- Firmware Talent Scarcity:In-house development capabilities for real-time image processing and encryption are concentrating among established players with dedicated R&D centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Dashboard Camera Market |
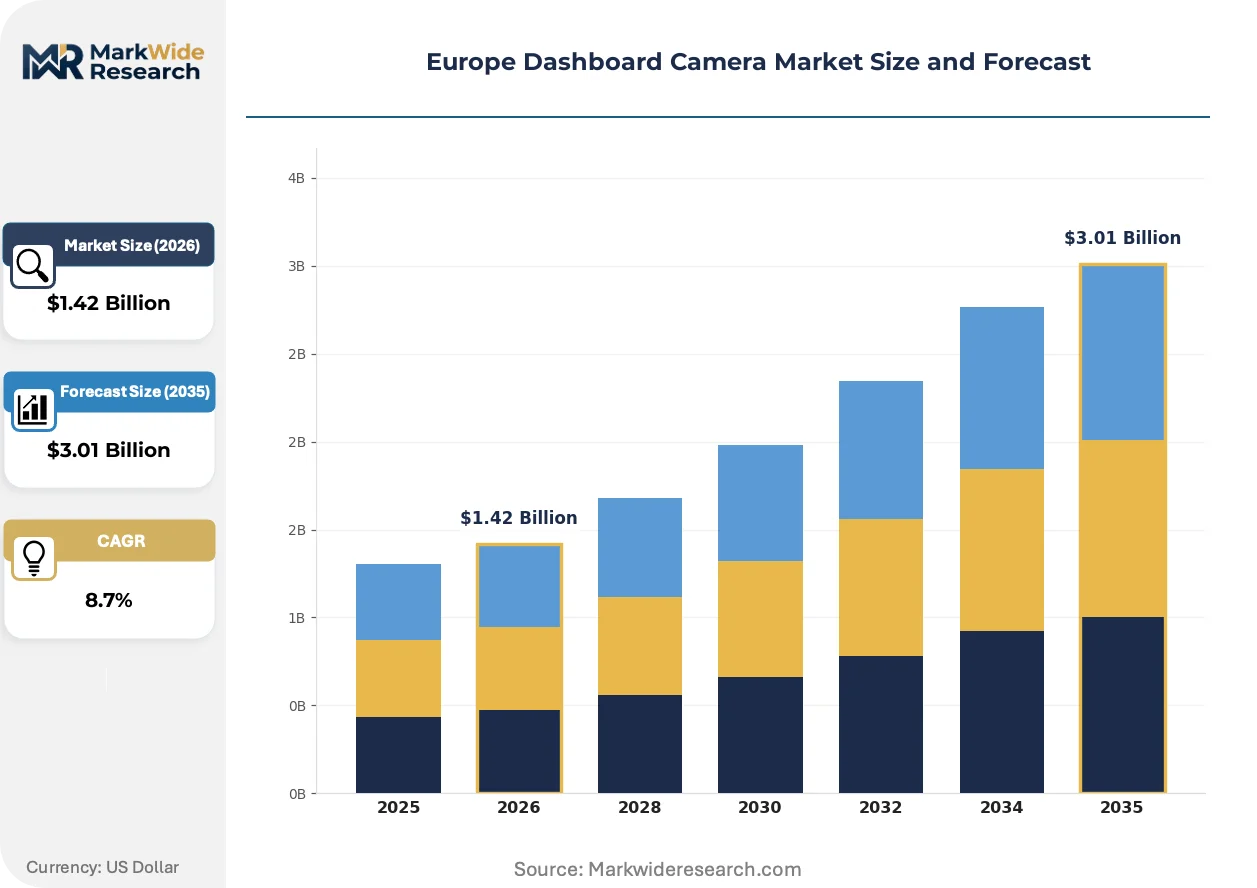
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Channel, Dual-Channel, 360-Degree, Rearview Technology: Wi-Fi, GPS, ADAS, Night Vision End User: Private Vehicles, Commercial Trucks, Taxi Services, Ride-Sharing Installation: DIY, Professional, OEM, Aftermarket |
| Companies Covered | Nextbase, Garmin Ltd., Samsara Inc., Valeo, Aptiv, Koninklijke Philips N.V., Vantrue Inc., BlackVue, Thinkware, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Dashboard Camera Market Shifts & Advancements
CMOS sensor architectures and edge computing capabilities are actively compressing device footprints while expanding real-time analytical functions that fleet managers demand for driver monitoring applications.
CMOS image sensors with 4K resolution capabilities are replacing CCD alternatives in premium dashcam configurations. Fleet operators in Germany's logistics corridor are specifying these sensors for license plate capture accuracy in low-light conditions. The form factor reduction is miniaturizing windshield mounting hardware and enabling discrete cabin-facing lens placement that complies with driver privacy expectations.
The EU AI Act's risk classification framework for driver monitoring systems is creating new product architecture requirements. Manufacturers must now document algorithmic transparency and bias testing before gaining market access across member states. Dual-channel systems with biometric analysis capabilities face heightened scrutiny that is delaying launch timelines for several product lines.
Commercial fleet procurement is consolidating around integrated telematics platforms that bundle video recording with GPS tracking and fuel monitoring. German and Polish logistics firms are specifying single-vendor contracts that displace standalone dashcam suppliers. This specification consolidation is most visible in long-haul trucking contracts where insurance documentation requirements mandate unified data streams.
Europe Dashboard Camera Market Segmentation
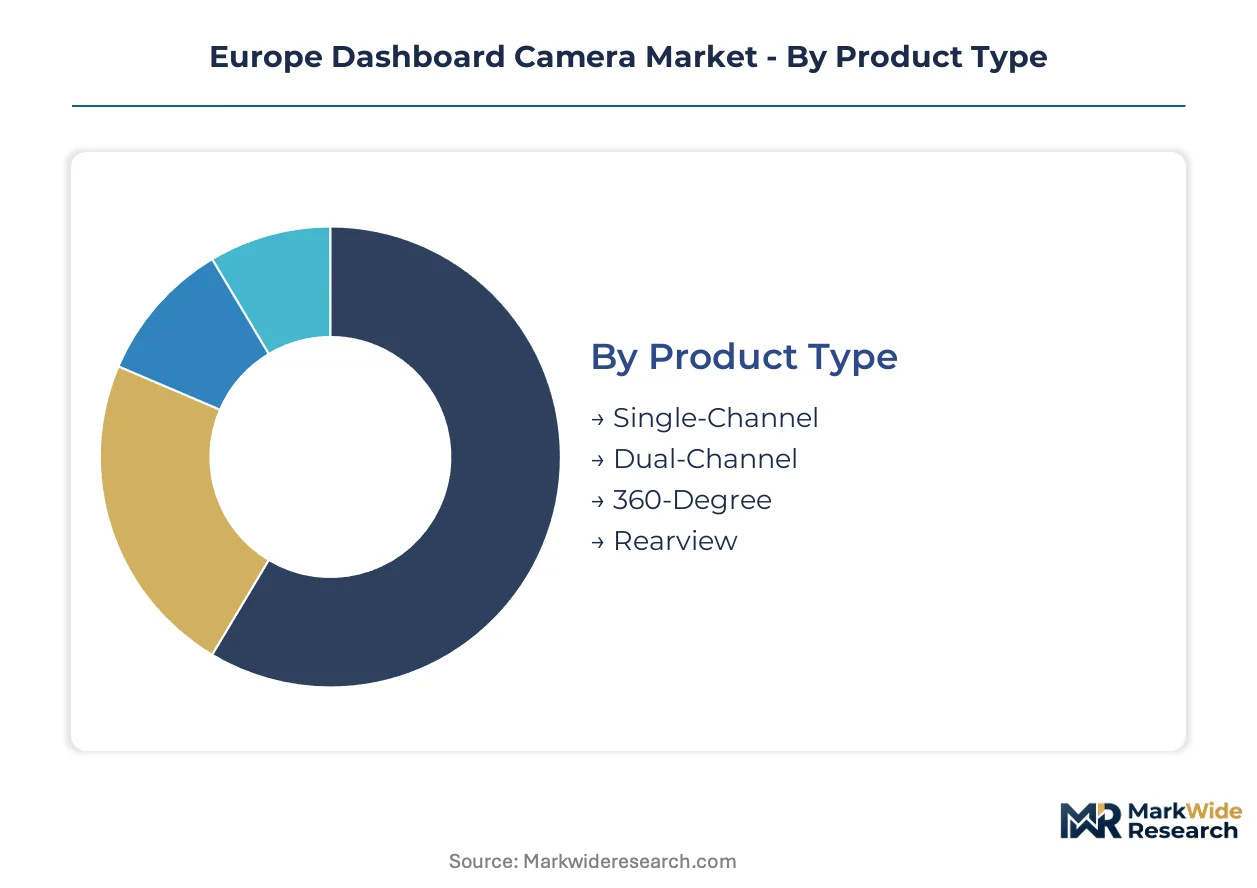
Dashboard camera purchasing decisions across Europe diverge sharply between fleet operators seeking integrated telematics and private owners prioritizing discrete installation. CE marking requirements and GDPR compliance architectures reshape which product configurations retain market access across member states.
Product Type:
Single-channel units face intensifying substitution pressure from dual-channel systems as fleet managers demand simultaneous road and cabin footage for insurance documentation.
- Single-Channel:Front-facing CMOS sensors with 1080p to 4K resolution dominate private vehicle installations in Germany and Poland. Price-sensitive consumers favor these units for basic incident documentation despite lacking driver monitoring capabilities.
- Dual-Channel:Integrated front and cabin-facing lenses command premium positioning across commercial trucking fleets. German logistics corridors specify these systems for unified data streams that satisfy insurance premium incentive programs.
- 360-Degree:Multi-lens arrays capturing circumferential footage serve ride-sharing operators requiring comprehensive liability coverage.
- Rearview:Supplementary rear-facing modules integrate with existing front units for complete vehicle surveillance.
Single-channel retains volume leadership; dual-channel holds the steepest expansion curve.
Technology:
Cost tier stratification separates premium sensor configurations from connectivity-focused mid-market offerings as firmware development costs concentrate among qualified manufacturers.
- Wi-Fi:Cloud-connected architectures enable real-time footage transfer for taxi services and ride-sharing operators. Polish fleet managers specify these units to eliminate SD-card retrieval delays during incident investigations.
- GPS:Integrated location tagging provides speed and route documentation that German insurers require for premium reductions. Garmin anchors European positioning through mapping accuracy rather than hardware pricing alone.
- ADAS:Lane departure and collision warning algorithms face heightened scrutiny under the EU AI Act's risk classification framework.
- Night Vision:Low-light optimized CMOS sensors with wide dynamic range serve long-haul trucking routes across Eastern European corridors.
GPS-enabled units anchor the premium tier; Wi-Fi connectivity is climbing the fastest among technology integrations.
End User:
Application-specific requirements fragment procurement patterns as commercial operators consolidate around integrated platforms while private owners prioritize discrete form factors.
- Private Vehicles:Windshield-mounted units with minimal cabin intrusion dominate German and French consumer retail channels. GDPR-compliant local storage architectures satisfy driver privacy expectations.
- Commercial Trucks:E-mark certified systems with electromagnetic compatibility documentation serve German logistics firms under EU General Safety Regulation mandates. Insurance premium incentives sustain procurement pull across long-haul corridors.
- Taxi Services:Dual-channel Wi-Fi systems with immediate cloud upload satisfy municipal licensing requirements in Warsaw and Berlin.
- Ride-Sharing:Integrated telematics bundles displace standalone dashcams as platform operators mandate unified vendor contracts.
Commercial trucks retain volume leadership; ride-sharing platforms hold the steepest expansion curve.
Installation:
Supply concentration among qualified manufacturers with in-house testing facilities reshapes channel economics as OEM bundling accelerates.
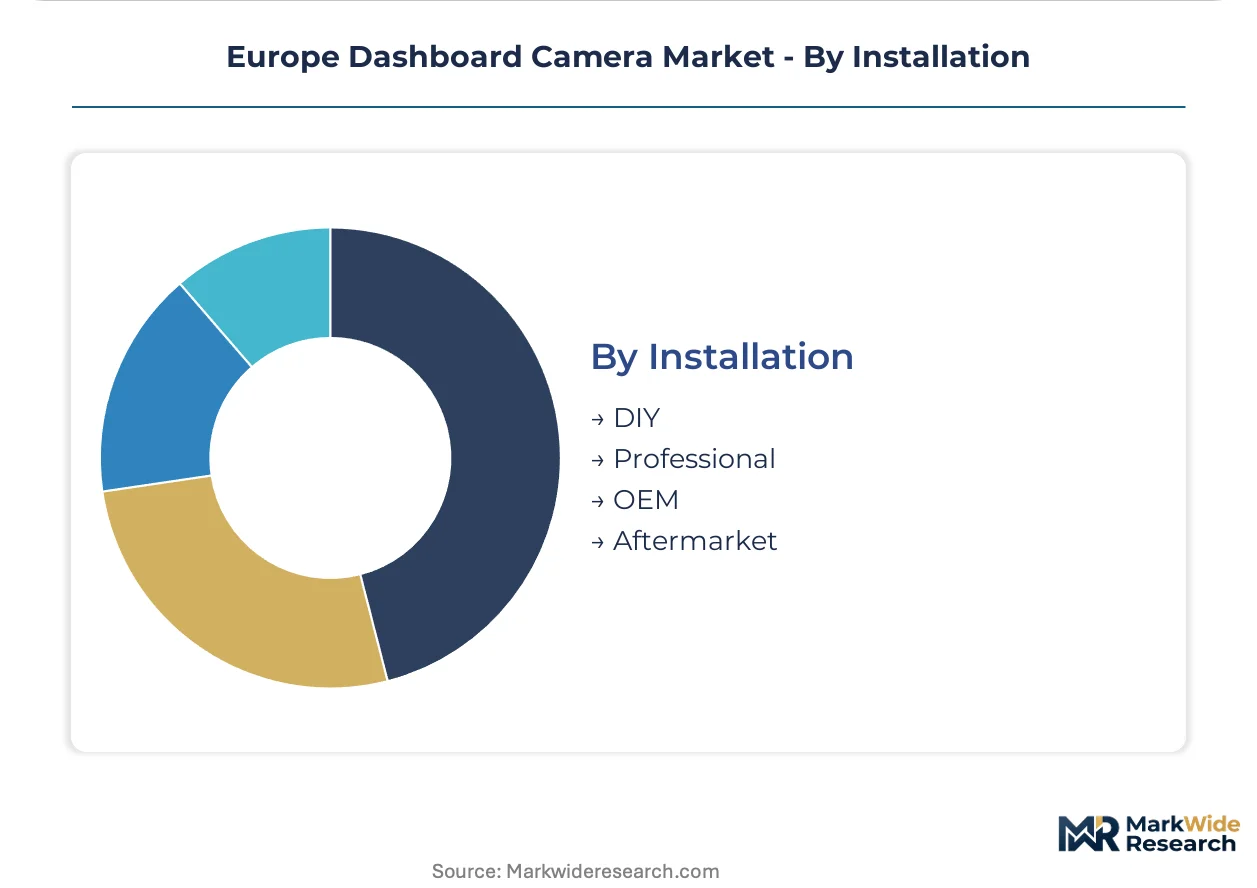
- DIY:Suction-cup or adhesive-mounted units with plug-and-play power routing serve price-sensitive private owners. German retail channels favor these configurations for consumer self-installation.
- Professional:Hardwired installations with concealed cable routing satisfy fleet aesthetics and theft-deterrence requirements across Polish commercial operators.
- OEM:Factory-fit integration within connected-car packages locks out aftermarket rivals from new vehicle sales. Valeo controls these volumes through supply relationships with French and German automakers.
- Aftermarket:Post-purchase installation still dominates total volume but faces compression as OEM bundling accelerates.
Aftermarket retains volume leadership; OEM holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators and logistics firms dominate procurement across Europe, with insurance premium incentives and EU safety mandates driving concentrated demand in Germany's freight corridors and Poland's trucking networks.
Germany
Commercial trucking fleets in the Rhine-Ruhr and Hamburg logistics corridors specify E-mark certified dual-channel systems for insurance documentation. KBA enforces electromagnetic compatibility standards that compress supplier qualification timelines. Bavarian automotive clusters around Munich are accelerating OEM factory-fit bundling within connected-car packages.
Poland
Long-haul operators across the Warsaw-Berlin freight axis deploy Wi-Fi-enabled units for real-time incident footage transfer. GDPR compliance architectures for biometric data handling constrain firmware developers without dedicated legal teams. Silesian logistics hubs near Katowice are consolidating procurement around single-vendor telematics contracts.
United Kingdom
Retail channels in Greater London and the Midlands favor single-channel 4K units for private vehicle owners seeking discrete windshield mounting. DVLA documentation requirements for commercial operators mirror EU General Safety Regulation provisions. Manchester-based fleet services are specifying GPS-integrated models for route verification.
France
Parisian taxi services and ride-sharing platforms mandate dual-channel Wi-Fi systems with immediate cloud upload capabilities. CNIL data protection enforcement shapes local storage architectures that satisfy driver privacy expectations. Lyon and Marseille logistics operators are migrating from aftermarket installation to professional hardwired configurations.
Netherlands
Randstad port logistics firms specify night-vision optimized CMOS sensors for low-light documentation across Rotterdam-Antwerp corridors. REACH chemical compliance for device materials adds supplier documentation burdens. Eindhoven technology clusters are prototyping edge-computing dashcam architectures for real-time driver analytics.
Europe Dashboard Camera Market Competitive Landscape
Player mix skews toward established electronics specialists with in-house firmware capabilities and automotive-tier suppliers with OEM relationships. CE marking and E-mark certification requirements under ECE R10 have compressed the qualified supplier base to technically capable manufacturers. Strategic archetypes include retail-focused consumer electronics brands, fleet telematics integrators, and automotive component suppliers controlling factory-fit volumes. Dominant competitive moves center on backward integration into sensor manufacturing and geographic expansion through distribution partnerships.
Among UK-based specialists, Nextbase anchors consumer retail positioning through proprietary firmware development. Garmin Ltd. exemplifies the GPS-integrated premium tier competing on mapping accuracy rather than hardware pricing alone. Valeo occupies the automotive supply position through OEM relationships with French and German automakers that control factory-fit installation volumes aftermarket rivals cannot replicate.
| Leading Market Players |
|---|
| Nextbase |
| Garmin Ltd. |
| Samsara Inc. |
| Valeo |
| Aptiv |
| Koninklijke Philips N.V. |
| Vantrue Inc. |
| BlackVue |
| Thinkware |
| Others |
Supply & Pricing Matrix
Eighteen-week firmware certification lead times at E-mark testing facilities concentrate pricing power among manufacturers with captive electromagnetic compatibility labs. Inventory cycles spanning 45-60 days of CMOS sensor stock bind procurement flexibility to Taiwanese foundry allocation schedules.
Pricing Analysis
Cost-plus contracts with quarterly CMOS sensor indexation dominate fleet procurement agreements across German logistics corridors. Three-tier pricing structure across premium, standard, and economy levels separates E-mark certified dual-channel systems from CE-marked single-channel units and unbranded import alternatives. Cost compression in the economy tier intensifies as Polish distributors consolidate volume under single-vendor telematics contracts. Private vehicle owners exhibit highest price sensitivity, while commercial fleet operators prioritize certification documentation over unit economics.
Supply Chain Analysis
Port congestion at Rotterdam-Antwerp corridors elevates inbound logistics costs for CMOS sensor modules originating from Taiwanese and South Korean foundries. Manufacturing concentration in China, Taiwan, and Vietnam feeds European assembly operations with image sensors, Wi-Fi chipsets, and lens arrays. Single-source vulnerability in 4K CMOS supply exposes downstream producers to allocation disruptions during semiconductor cycle peaks. Distribution runs through German automotive-tier distributors and Polish fleet telematics integrators serving commercial end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud footage storage subscriptions and firmware update services expand at multiples exceeding hardware shipment growth, repositioning vendor economics toward recurring revenue attachment. Fleet telematics bundling accelerates this shift as operators prioritize unified data platforms over standalone device procurement.
For Market Incumbents: Fortify E-mark certification pipelines through in-house electromagnetic compatibility testing facilities that compress homologation timelines. Deepen backward integration into CMOS sensor sourcing to defend margin position against Taiwanese foundry allocation volatility. Channel control through exclusive distribution partnerships with German automotive-tier suppliers locks out aftermarket rivals from OEM bundling opportunities. For New Entrants and Emerging Players: Anchor in Polish Silesian logistics hubs where single-vendor telematics consolidation has displaced standalone dashcam suppliers. Target ride-sharing platform operators mandating dual-channel Wi-Fi systems with immediate cloud upload for municipal licensing compliance. Pursue white-label manufacturing partnerships with established firmware developers to bypass GDPR compliance architecture barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified automotive electronics parents seeking to divest non-core dashcam divisions amid OEM bundling acceleration. Mid-cap specialists with CE marking expertise and fleet telematics integration capabilities present viable acquisition profiles. Watch EMA homologation timeline compression as inflection indicator for supplier base consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| E-Mark Certification Investment | In-house electromagnetic compatibility testing compresses homologation timelines for KBA type-approval. |
| Firmware-as-a-Service Launch | Cloud update subscriptions attach recurring revenue to hardware deployments across German fleet operators. |
| CMOS Sensor Supply Agreement | Long-term foundry contracts with Taiwanese manufacturers hedge against semiconductor allocation volatility. |
| OEM Factory-Fit Partnership | Integration within French and German automaker connected-car packages locks out aftermarket competitors. |
| GDPR Compliance Platform | Biometric data handling architectures satisfy CNIL enforcement and unlock taxi service procurement. |
Research Methodology
A spread of perspectives from fleet operations directors, automotive procurement managers, E-mark testing engineers, and insurance underwriting specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with German logistics corridor operators and Polish long-haul trucking firms alongside secondary validation through KBA type-approval databases, EMA regulatory filings, and customs import records for CMOS sensor modules. Bottom-up shipment estimates triangulated against top-down fleet telematics market sizing.
Segmentation dimensions modeled span product type, technology integration, end-user application, and installation channel across the projection horizon. CAGRs derived from logistic curve fitting to historical fleet adoption patterns and regulatory mandate implementation schedules. Industry-specific forecast inputs incorporate EU General Safety Regulation enforcement timelines and insurance premium incentive program expansion trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained E-mark certification stringency and stable CMOS sensor supply; material deviation would warrant model refresh. Specific risks include GDPR enforcement escalation affecting biometric data handling architectures and EU AI Act risk classification delays for driver monitoring systems. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Global 5G in Automotives Market
Telematics and Infotainment
Motorcycle Infotainment System Market
Telematics and Infotainment
Global Automotive Infotainment System Market
Telematics and Infotainment
Telematics and Connectivity Control Unit Systems Market
Telematics and Infotainment
Vehicle Trip Computers Market
Telematics and Infotainment
Asia Pacific Automotive Navigation System Market
Telematics and Infotainment
GCC Commercial Telematics Market
Telematics and Infotainment
North America Dashboard Camera Market
Telematics and Infotainment
Asia Pacific Automotive Infotainment Systems Market
Telematics and Infotainment
In Vehicle Infotainment Market
Telematics and Infotainment
Electric Vehicle Infotainment Market
Telematics and Infotainment
Telematics Market
Telematics and Infotainment
Europe Automotive Infotainment Systems Market
Telematics and Infotainment
Trailer Telematics Market
Telematics and Infotainment
Automotive Embedded Telematics Market
Telematics and Infotainment
Roadside Assistance Software Market