
 Global Carpool-As-A-Service Market | 2026-2036
Global Carpool-As-A-Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Carpool-As-A-Service Market Foresight
Corporate buyer concentration is pivoting as Fortune 500 employers consolidate vendor relationships with multi-year corporate contracts rather than reimbursing individual ride-hail expenses. Uber leverages its enterprise-grade API infrastructure to anchor fleet management partnerships with multinational employers. BlaBlaCar sustains dominant position in European intercity corridors through community-driven trust mechanisms and fixed-route density. Didi Chuxing controls regulatory navigation in China's mobility sector via deep data integration with municipal transport authorities.
Carpool-as-a-Service denotes a digitally intermediated shared mobility model where algorithmic matching consolidates multiple passengers into single-vehicle trips along correlated origin-destination pairs, typically operating through GPS-enabled dynamic routing with real-time demand-supply balancing. The platform's core function reduces vehicle-kilometers traveled per passenger while capturing utilization premiums from empty seat inventory. Subscription service structures command the most predictable revenue streams and lowest churn among recurring commuter cohorts. Last-mile connectivity applications represent the fastest-expanding segment as transit agencies white-label carpool integrations to bridge fixed-route service gaps. Mobile applications dominate distribution channel economics, though partner networks with automotive OEMs and fuel retailers are capturing incremental user acquisition at lower CAC.
FAA regulations govern drone-based aerial carpool pilots in select US corridors, while the EU AI Act imposes algorithmic transparency requirements on European matching engines that affect pricing and driver-rider allocation logic. India's MEE urban mobility directives and state-level electric vehicle mandates in Maharashtra and Karnataka are reshaping fleet composition requirements for platform operators. Stakeholders must monitor how GDPR-derived data localization pressures in Europe and emerging biometric verification standards in Asian markets will alter identity verification costs and cross-border service scalability.
Market Dynamics
Corporate Scope 3 emissions accounting is compressing procurement cycles for shared mobility vendors as Fortune 500 employers consolidate vendor relationships into multi-year enterprise contracts rather than reimbursing individual ride-hail expenses.
Growth Catalysts
- EU Green Deal transport decarbonization targets:Fleet operators across Germany, France, and the Netherlands are integrating carpool platforms into compliance strategies to meet mandated carbon intensity reductions in urban corridors.
- Last-mile connectivity gaps:Metro-rail infrastructure deficits in Indian megacities like Bengaluru and Mumbai create persistent demand for algorithmic trip consolidation that bridges fixed-route service interruptions.
- Dynamic routing algorithms:GPS-enabled real-time demand-supply balancing is reducing vehicle-kilometers traveled per passenger while capturing utilization premiums from empty seat inventory.
Market Restraints
- GDPR-derived data localization:European identity verification requirements are elevating compliance costs and constraining cross-border service scalability for platform operators.
- Algorithmic transparency mandates:The EU AI Act imposes explainability requirements on pricing and driver-rider allocation logic that increase engineering overhead for matching engines.
- Biometric verification standards:Emerging identity protocols in Asian markets are altering user onboarding friction and altering customer acquisition economics.
Strategic Opportunities
- Transit agency white-label integrations:Municipal transport authorities in the United States and Canada are licensing carpool technology to bridge fixed-route coverage gaps in suburban corridors.
- Maharashtra and Karnataka EV mandates:State-level electric vehicle composition requirements in India are creating fleet modernization incentives that favor shared mobility operators with capital deployment capacity.
- Automotive OEM partner networks:Vehicle manufacturers and fuel retailers are capturing incremental user acquisition at lower customer acquisition cost than pure mobile application distribution.
Industry Challenges
- Regulatory navigation complexity:Platform operators must simultaneously comply with FAA drone pilot regulations in US corridors, EU algorithmic governance, and India's MEE urban mobility directives.
- Enterprise API integration:Fleet management partnerships with multinational employers require sustained investment in enterprise-grade infrastructure that strains mid-cap platform technical resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Carpool-As-A-Service Market |
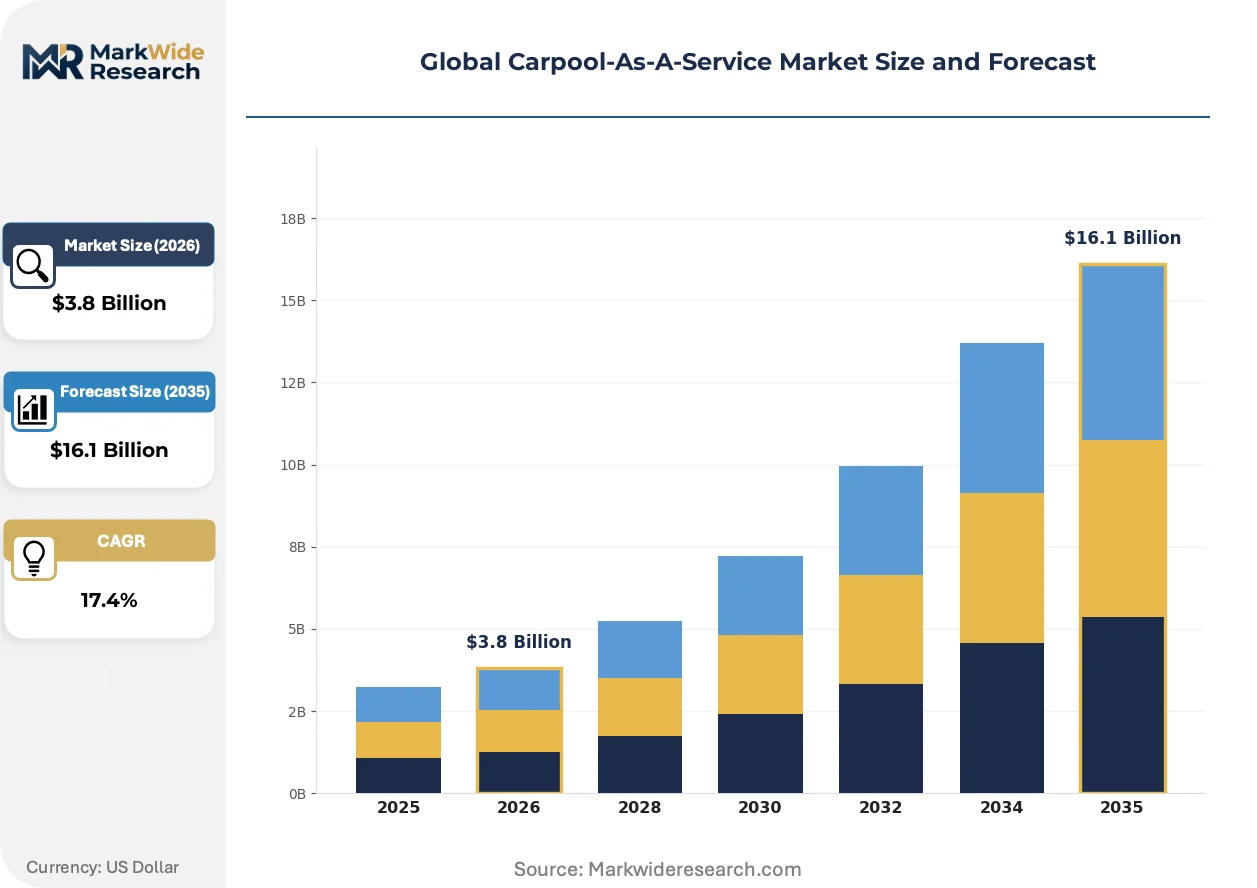
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $16.1 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Subscription, Pay-As-You-Go, Premium Membership, Corporate Contracts Application: Commute Solutions, Event Transportation, Last-Mile Connectivity, School Transit End User: Corporate Employees, University Students, Tourists, Local Commuters Distribution Channel: Mobile Applications, Web Platforms, Dedicated Kiosks, Partner Networks |
| Companies Covered | Grab, Gojek Tech, Uber, Bolt, Via Transportation, Lyft, BlaBlaCar, Cabify, Didi Chuxing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Carpool-As-A-Service Market Shifts & Advancements
Algorithmic matching sophistication is displacing static route optimization as the primary competitive differentiator, with platform investment concentrating on predictive demand modeling and multi-modal trip orchestration.
Machine learning-powered occupancy prediction is expanding into commuter corridor planning by analyzing historical origin-destination patterns to pre-position vehicle supply. Large employers in technology and financial services verticals are adopting these predictive tools to optimize corporate shuttle scheduling. The structural consequence is compressing deadhead mileage and improving per-seat revenue yields for fleet operators.
The EU AI Act's algorithmic transparency requirements are mandating explainable decision trees for driver-rider matching and surge pricing mechanisms. European platform operators must now document allocation logic for regulatory audit. Intercity corridor providers face the steepest compliance burden given the complexity of multi-party route optimization algorithms.
Subscription service structures are displacing per-trip pricing as the dominant revenue model for recurring commuter cohorts. Corporate procurement teams favor predictable monthly expenditures over variable reimbursement processing. This behavioral shift is most visible in German and French enterprise mobility budgets, where multi-year vendor contracts now specify guaranteed ride pools rather than ad-hoc expense claims.
Global Carpool-As-A-Service Market Segmentation
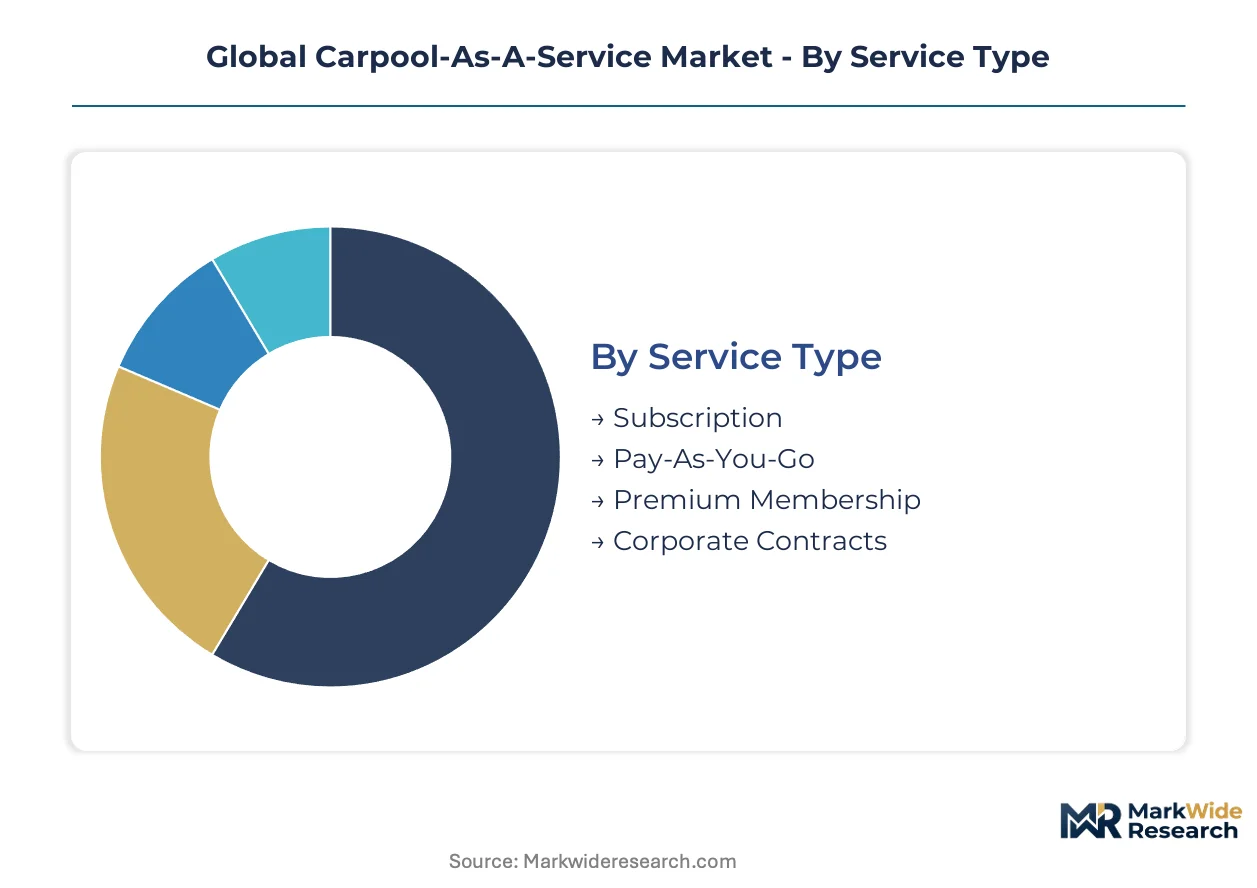
Segmentation reveals how platform operators configure pricing architectures, compliance burdens, and partnership strategies around distinct user behaviors. Each dimension carries divergent margin profiles and regulatory exposure that shape capital allocation decisions.
Service Type:
GDPR audit trails and EU AI Act documentation requirements fall most heavily on subscription and corporate contract tiers due to persistent data retention obligations.
- Subscription:Recurring revenue structures with fixed monthly fees generate predictable cash flows and lowest churn among daily commuter cohorts. German and French enterprise mobility budgets increasingly mandate guaranteed ride pools over variable reimbursement. Corporate procurement teams favor this model for Scope 3 emissions accounting simplicity.
- Corporate Contracts:Multi-year enterprise agreements consolidate vendor relationships for Fortune 500 employers seeking parking congestion relief and carbon intensity reductions. Fleet management partnerships require sustained API infrastructure investment that strains mid-cap platform technical resources.
- Pay-As-You-Go:Per-trip pricing dominates tourist and occasional user segments with higher acquisition costs and seasonal demand volatility.
- Premium Membership:Tiered benefits including priority matching and guaranteed seating capture price-insensitive urban professionals in congested corridors.
Corporate contracts sit at the top of the volume ranking, with subscription services climbing the fastest.
Application:
Cost tier stratification separates high-frequency low-margin commute solutions from episodic high-yield event transportation deployments.
- Commute Solutions:Daily origin-destination consolidation along correlated corridors represents the core revenue base with thin per-trip margins offset by volume density. Machine learning-powered occupancy prediction tools optimize corporate shuttle scheduling for technology and financial services employers.
- Last-Mile Connectivity:Algorithmic trip consolidation bridges fixed-route service gaps where metro-rail infrastructure deficits persist. Transit agencies in the United States and Canada license white-label carpool technology for suburban coverage extension.
- Event Transportation:Surge-priced episodic demand around sporting venues and concert halls generates premium yields with acute supply positioning challenges.
- School Transit:Biometric verification protocols and guardian notification systems impose elevated compliance costs in Asian markets with emerging identity standards.
Commute solutions maintain volume leadership, while last-mile connectivity gains share fastest among application segments.
End User:
Customer type concentration determines onboarding friction, payment modality, and retention engineering priorities across divergent demographic profiles.
- Corporate Employees:Enterprise-subsidized adoption with integrated expense management and sustainability reporting requirements. Fortune 500 consolidation of vendor relationships compresses procurement cycles for shared mobility vendors.
- University Students:Price-sensitive cohort with semester-based demand patterns and campus-specific routing optimization requirements.
- Tourists:Episodic usage with language localization needs and destination discovery integration demands.
- Local Commuters:Habitual daily users forming the retention core with highest lifetime value and lowest acquisition cost through referral networks.
Corporate employees anchor volume concentration, with university students showing the steepest expansion trajectory in emerging markets.
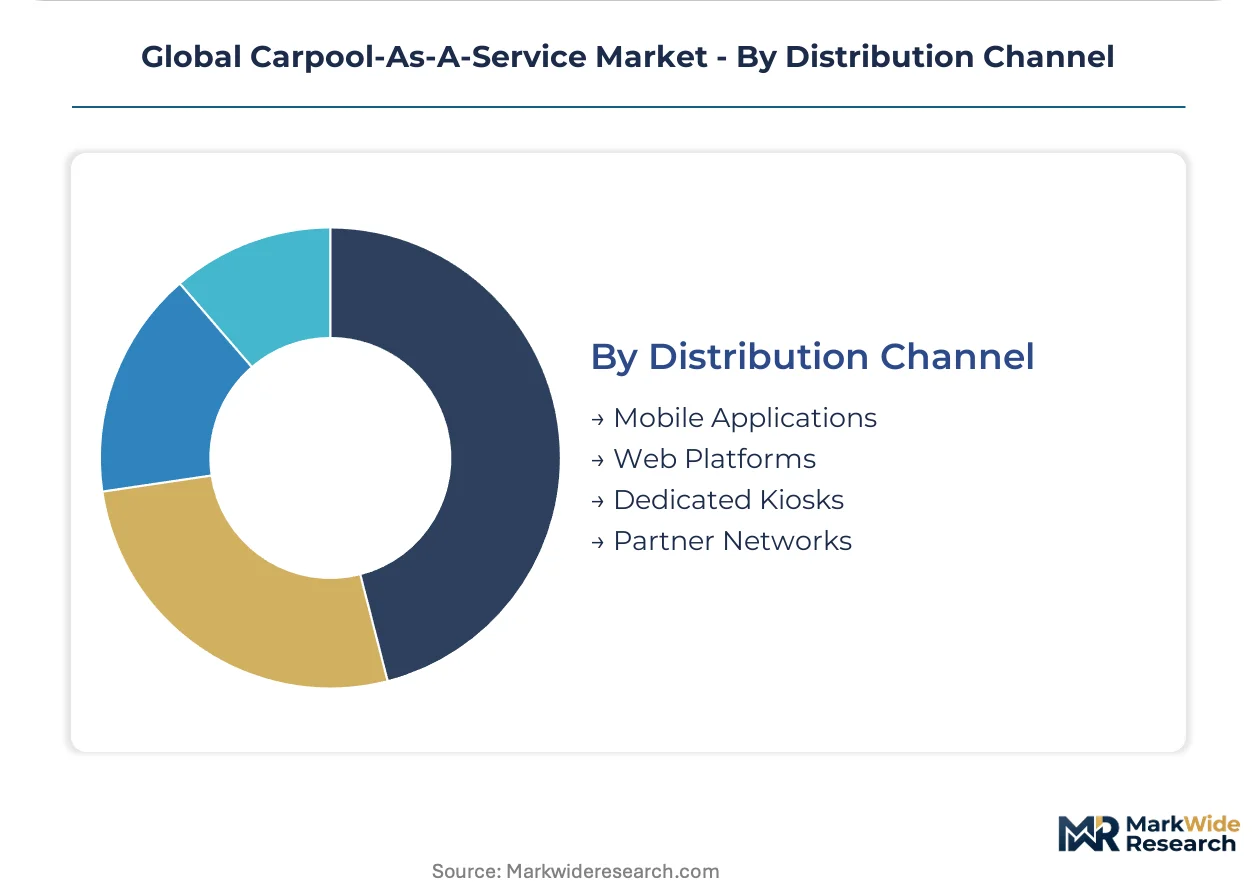
Distribution Channel:
Supply concentration in mobile-first acquisition is producing channel cost divergence between high-CAC application stores and lower-friction partner network embeddings.
- Mobile Applications:Dominant distribution economics with platform store fees and attribution complexity. GPS-enabled dynamic routing and real-time demand-supply balancing require native mobile infrastructure.
- Partner Networks:Automotive OEM and fuel retailer collaborations capture incremental user acquisition at lower customer acquisition cost than pure mobile distribution. Vehicle manufacturers embed carpool functionality into connected car dashboards.
- Web Platforms:Secondary channel for enterprise procurement workflows and trip planning research before mobile conversion.
- Dedicated Kiosks:Physical presence at transit hubs and corporate campuses for cash-preferred demographics and digital accessibility compliance.
Mobile applications command volume primacy, with partner networks expanding most quickly as OEM integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France commands denser intercity corridor networks than India, yet both markets exhibit divergent regulatory pathways shaping platform economics and fleet composition mandates.
United States
Corporate campus clusters in Silicon Valley and Seattle generate concentrated commuter demand that platforms address through subscription enterprise contracts. FAA drone pilot regulations govern emerging aerial carpool pilots in select urban corridors. Austin and Denver metropolitan areas anchor dynamic routing deployment as municipal transit agencies license white-label integrations for suburban coverage extension.
Germany
Fortune 500 employers in Frankfurt and Munich consolidate vendor relationships into multi-year agreements prioritizing Scope 3 emissions accounting simplicity. The EU AI Act imposes algorithmic transparency requirements on matching engines affecting pricing logic. The Rhine-Ruhr corridor sustains highest fixed-route density for intercity providers leveraging community-driven trust mechanisms.
India
Metro-rail infrastructure deficits in Bengaluru and Mumbai create persistent last-mile inefficiencies that algorithmic trip consolidation addresses. Maharashtra and Karnataka state-level electric vehicle mandates reshape fleet composition requirements for platform operators. Delhi-NCR anchors fastest subscriber growth as corporate procurement teams adopt guaranteed ride pools over variable reimbursement structures.
China
Didi Chuxing's data integration with municipal transport authorities controls regulatory navigation in tier-one cities. The country's dual carbon goals accelerate fleet electrification timelines for shared mobility operators. Shenzhen and Guangzhou metropolitan clusters concentrate predictive demand modeling investment for corporate shuttle optimization.
France
BlaBlaCar's community-driven trust mechanisms sustain dominant positioning in European intercity corridors originating from Paris. The EU Green Deal's transport decarbonization targets compel fleet operators to integrate shared mobility into compliance strategies. Lyon and Marseille anchor dense origin-destination pairing efficiency for algorithmic matching optimization.
Global Carpool-As-A-Service Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a market structure consolidating around enterprise-grade API infrastructure and algorithmic matching sophistication. Tier-one players anchor fleet management partnerships with multinational employers while mid-cap platforms strain technical resources sustaining such integrations. Three archetypes dominate: vertically integrated mobility conglomerates with cross-border regulatory expertise, intercity corridor specialists leveraging community trust mechanisms, and white-label technology providers licensing infrastructure to transit agencies. Competitive moves concentrate on strategic partnerships with automotive OEMs and geographic expansion through regulatory navigation capabilities.
Among Asia-Pacific-based mobility conglomerates, Grab and Gojek Tech exemplify diversified platform archetypes spanning multiple service verticals beyond carpool intermediation. Uber anchors the enterprise contract tier through sustained investment in API infrastructure serving multinational employer procurement teams. BlaBlaCar occupies a distinct specialist position within European intercity corridors where community-driven trust mechanisms and fixed-route density create defensive positioning against algorithmic-first competitors.
| Leading Market Players |
|---|
| Grab |
| Gojek Tech |
| Uber |
| Bolt |
| Via Transportation |
| Lyft |
| BlaBlaCar |
| Cabify |
| Didi Chuxing |
| Others |
Supply & Pricing Matrix
Vehicle acquisition costs in Germany and India cascade through subscription pricing tiers as fleet operators balance EV mandate compliance against per-seat revenue yields. This input cost pressure stratifies across corporate contract, subscription, and pay-as-you-go tiers with divergent margin absorption capacity.
Pricing Analysis
Capacity additions in Maharashtra and Karnataka are reshaping price floors for electric fleet deployments as state-level EV mandates compress vehicle procurement economics. Subscription service structures generate predictable cash flows with lowest churn among daily commuter cohorts, while pay-as-you-go pricing dominates tourist segments with higher acquisition costs and seasonal volatility. Price differentiation rests on guaranteed ride pools versus variable reimbursement structures, with corporate procurement teams favoring fixed monthly expenditures for Scope 3 emissions accounting simplicity. Pricing pressure stems from algorithmic transparency mandates elevating engineering overhead for European matching engines.
Supply Chain Analysis
Domestic-content requirements in India's MEE urban mobility directives are reshaping sourcing patterns for platform operators deploying in Bengaluru and Mumbai corridors. Vehicle supply concentrates in China, Germany, and Japan as automotive OEMs embed carpool functionality into connected car dashboards. Battery cell and telematics hardware dependencies draw from East Asian manufacturing clusters. Single-source vulnerability runs through semiconductor availability for GPS-enabled dynamic routing systems. Distribution runs through mobile application stores and fuel retailer partner networks with divergent customer acquisition economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
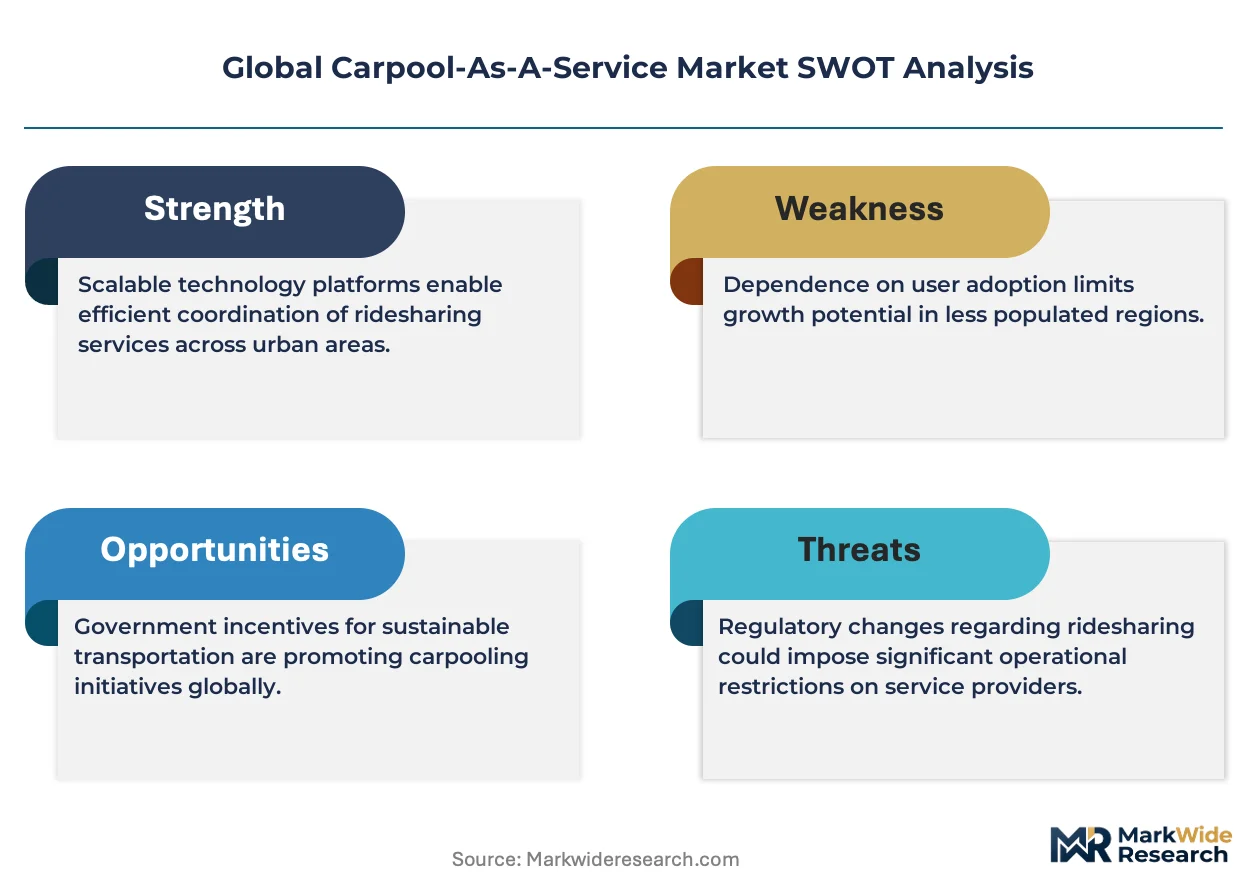
The Global Carpool-As-A-Service Market compounds steadily as corporate Scope 3 emissions accounting locks Fortune 500 employers into multi-year vendor relationships with predictable renewal economics.
For Market Incumbents: Anticipate regulatory fragmentation across FAA drone pilot corridors, EU AI Act algorithmic governance, and India's MEE directives by diversifying compliance infrastructure investments. Deepen API integration capabilities to defend enterprise contract tier positioning against mid-cap platform technical resource constraints. Prioritize predictive demand modeling R&D to maintain algorithmic matching sophistication advantages.
For New Entrants and Emerging Players: Automotive OEM partner networks offer lower customer acquisition cost entry points than saturated mobile application store channels. Target last-mile connectivity white-label integrations with municipal transit agencies in suburban United States and Canadian corridors where fixed-route coverage gaps persist. Pursue transit agency licensing agreements as the most penetrable go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where enterprise-grade API infrastructure requirements strain mid-cap platform technical resources. Five-to-ten year viability favors vertically integrated mobility conglomerates with cross-border regulatory expertise over pure-play specialists. Acquisition target archetypes include intercity corridor specialists with community-driven trust mechanisms. Monitor EU AI Act enforcement patterns as the signal to watch for compliance cost inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Transit Agency White-Label Integration | Municipal licensing agreements in Austin and Denver extend suburban coverage without capital-intensive fleet ownership. |
| Predictive Demand Modeling Investment | Machine learning-powered occupancy prediction optimizes corporate shuttle scheduling for technology sector employers. |
| Automotive OEM Dashboard Embedding | Connected car integrations by vehicle manufacturers capture incremental user acquisition at lower customer acquisition cost. |
| EU AI Act Compliance Documentation | Explainable decision trees for driver-rider matching satisfy regulatory audit requirements in German and French corridors. |
| State-Level EV Fleet Modernization | Maharashtra and Karnataka electric vehicle mandates reshape fleet composition requirements for platform operators. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with platform operations executives, municipal transit authority planners, corporate procurement managers, and automotive OEM partnership leads with secondary validation. Regulatory filings from the FAA, EU AI Act documentation, and India's MEE urban mobility directives anchored policy analysis. SEC disclosures, connected vehicle deployment data, and shared mobility utilization databases supplied volume benchmarks. Bottom-up service tier modeling and top-down regional demand aggregation provided triangulation.
Segment-weighting approaches distributed value across subscription, corporate contract, pay-as-you-go, and premium membership service types, with application segmentation spanning commute solutions, last-mile connectivity, event transportation, and school transit. End user stratification incorporated corporate employees, university students, tourists, and local commuters. Distribution channel analysis weighted mobile applications against partner networks, web platforms, and dedicated kiosks. CAGRs derived from historical trajectory fitting and driver elasticity modeling across the projection horizon. Corporate Scope 3 emissions accounting intensity and EV mandate compliance timelines served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory enforcement variance in European algorithmic governance and biometric verification standard adoption across Asian markets. Forecasts reflect documented assumptions regarding enterprise contract renewal rates and fleet electrification capital deployment capacity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Fleet Telematics System Market
Telematics and Infotainment
Asia Pacific Automotive Navigation System Market
Telematics and Infotainment
Car Generated Data Market
Telematics and Infotainment
Automotive Embedded Telematics Market
Telematics and Infotainment
Global Automotive Remote Diagnostics Market
Telematics and Infotainment
Global in Dash Navigation System Market
Telematics and Infotainment
Transport Data Logger Market
Telematics and Infotainment
Vehicle Digital Cockpit Market
Telematics and Infotainment
Global Automotive Infotainment System Market
Telematics and Infotainment
Dashboard Camera Market
Telematics and Infotainment
In Car Infotainment System Market
Telematics and Infotainment
Automotive Telematics System Market
Telematics and Infotainment
India Fleet Management Software Market
Telematics and Infotainment
Asia-Pacific Automotive Telematics Market
Telematics and Infotainment
Telematics Market
Telematics and Infotainment
Internet of Things Vehicle-To-Vehicle Communication Market