
 Autonomous Freight Trains Market | 2026-2036
Autonomous Freight Trains Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Freight Trains Market Outlook
Multi-source procurement of sensor suites and braking subsystems is rebalancing toward vertically integrated platform contracts. Siemens AG leverages its European signaling heritage to anchor turnkey automation packages across German and Austrian freight corridors. CRRC Corporation Limited sustains manufacturing scale through captive production of LiDAR arrays and onboard control computers. Wabtec Corporation differentiates via its North American installed base of Positive Train Control hardware, converting legacy fleets to autonomous-ready configurations.
Autonomous freight trains are self-propelled rail vehicles operating without onboard human operators, guided by fused sensor arrays, machine-vision cameras, and centralized traffic management algorithms achieving positioning accuracy within centimeters. Their primary purpose is to move bulk commodities and intermodal containers across extended distances with minimized crew costs and optimized fuel consumption. AI Algorithms now command the fastest growth trajectory as neural-network-based obstacle detection displaces rule-based systems in new installations. Logistics applications generate the deepest margin pools, particularly on dedicated mining and port-haulage routes where single-commodity flows simplify operational complexity.
The Federal Railroad Administration enforces Positive Train Control standards that mandate collision-avoidance capabilities, effectively pre-certifying autonomous system architectures for U.S. freight operators. E.U. Agency for Railways coordinates cross-border interoperability standards under the European Rail Traffic Management System, shaping vendor design priorities for transnational corridors. The International Organization for Standardization publishes functional-safety benchmarks for automated railway applications that gate market access across jurisdictions. Stakeholders must weigh regulatory pre-certification timelines against technology refresh cycles when committing to platform architectures.
Market Dynamics
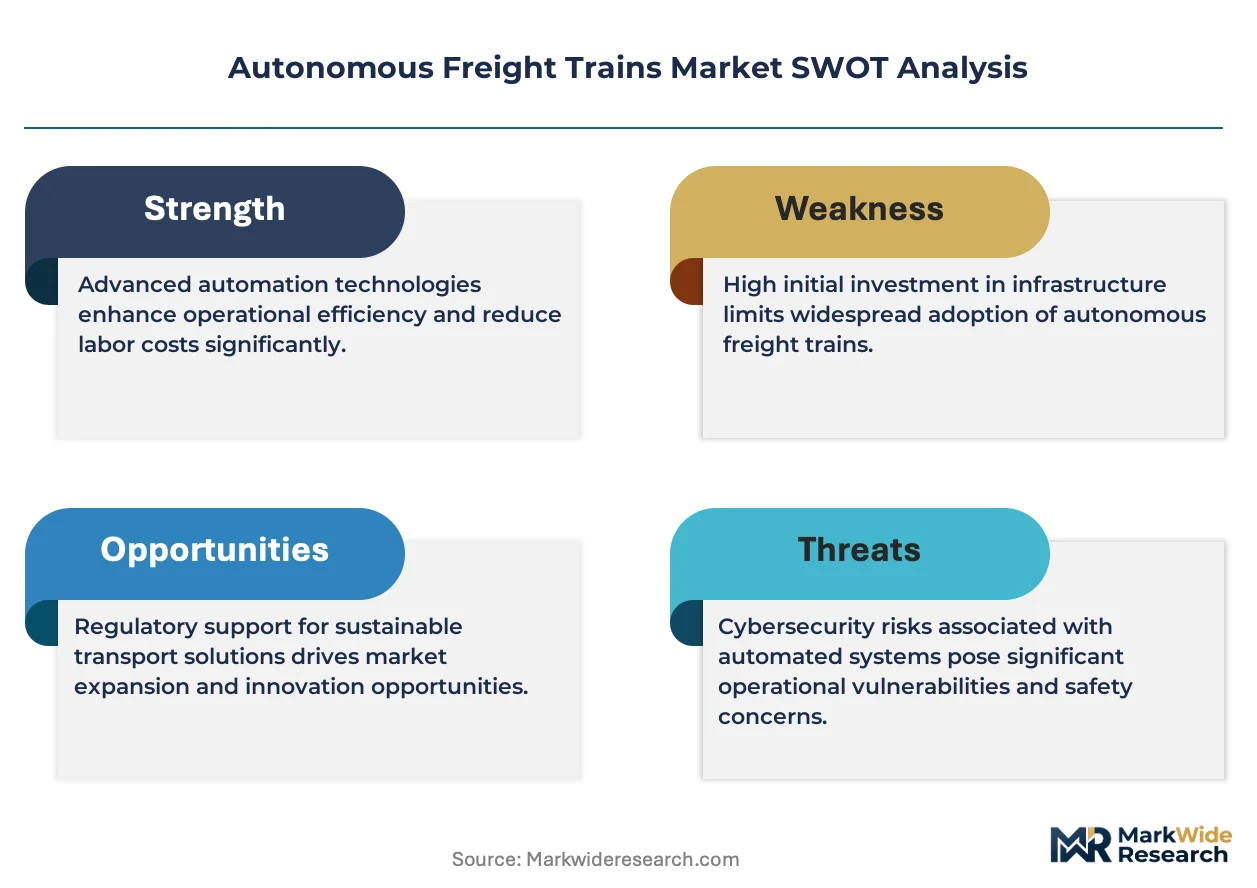
The convergence of Positive Train Control mandates and neural-network obstacle detection is compressing procurement cycles, forcing freight operators to commit to full-platform automation architectures rather than incremental sensor upgrades.
Growth Catalysts
- Positive Train Control Mandates:Federal Railroad Administration collision-avoidance standards in the United States pre-certify autonomous architectures, eliminating redundant safety validation phases for Class I railroads.
- Mining Automation Economics:Australian iron ore corridors demonstrate measurable fuel efficiency gains and shift consistency improvements that validate business cases for heavy-haul autonomy.
- LiDAR Cost Curves:Solid-state sensor manufacturing scale is collapsing per-unit positioning system costs, enabling centimeter-accuracy train control without mechanical scanning assemblies.
Market Restraints
- Legacy Fleet Retrofit Costs:Converting existing locomotive braking and propulsion systems to autonomous-ready configurations demands capital expenditure comparable to new-build alternatives.
- Signaling Protocol Fragmentation:European Rail Traffic Management System interoperability requirements create engineering friction for vendors targeting cross-border corridors through Germany, Austria, and Switzerland.
- Copper Supply Concentration:Traction motor and power electronics manufacturing depends on Chilean and Peruvian mining output, exposing production schedules to South American concentrate availability.
Strategic Opportunities
- Brazilian Agricultural Corridors:Soy and iron ore export routes from Minas Gerais to Atlantic ports remain underpenetrated by autonomous systems, presenting first-mover positioning for integrated platform providers.
- Battery-Electric Convergence:Catenary-independent locomotive architectures combining autonomous control with lithium-titanate traction batteries enable operation on non-electrified mining spurs.
- EU Green Deal Alignment:Carbon border adjustment mechanisms and emissions trading scheme obligations create procurement preference for fuel-optimized autonomous haulage among European bulk operators.
Industry Challenges
- Functional Safety Engineering Talent:ISO 26262 and rail-specific CENELEC SIL-4 certification expertise concentrates in German and Japanese industrial centers, constraining vendor scaling.
- Multi-Jurisdiction Type Approval:Achieving simultaneous Federal Railroad Administration, E.U. Agency for Railways, and Australian Office of the National Rail Safety Regulator certification extends platform launch timelines.
- Legacy Traffic Management Integration:Autonomous train control systems must interface with decades-old centralized traffic control installations without disrupting mixed-fleet operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Freight Trains Market |
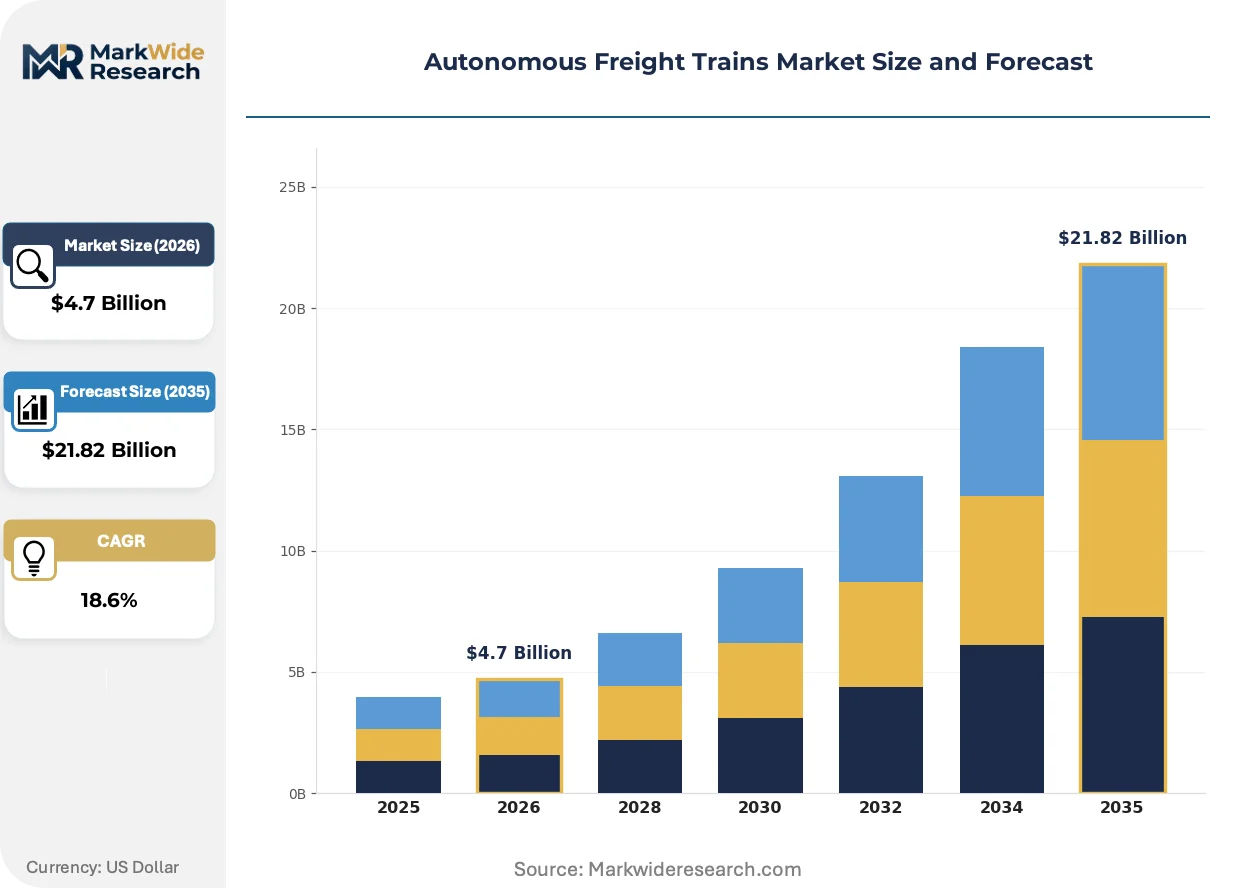
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Computer Vision, Sensors, AI Algorithms, GPS Navigation Application: Logistics, Supply Chain Management, Industrial Transport, Freight Handling End User: Rail Operators, Freight Companies, Logistics Providers, Public Transport Agencies Deployment: On-Premise, Cloud-Based, Hybrid, Remote Monitoring |
| Companies Covered | Siemens AG, Alstom SA, CRRC Corporation Limited, Wabtec Corporation, Hitachi Rail, Kawasaki Heavy Industries, Mitsubishi Heavy Industries Ltd., Thales Group, CAF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Freight Trains Market Strategic Shifts
Neural-network perception architectures and solid-state sensor platforms are displacing rule-based automation, while regulatory pre-certification frameworks compress vendor qualification timelines across North American and European procurement cycles.
Digital interlocking systems with integrated machine-vision validation layers are electrifying trackside safety architectures. Mining operators in Western Australia deploy these configurations to eliminate mechanical signal infrastructure maintenance. The technology is electrifying capital allocation patterns, shifting investment from wayside hardware to onboard computing platforms.
E.U. Agency for Railways interoperability mandates under the European Rail Traffic Management System are standardizing cross-border train control protocols. Vendors must engineer multi-national certification compatibility into base platform designs. German and Austrian freight corridors experience the most acute compliance pressure, accelerating consolidation around turnkey automation suppliers.
Long-term service agreements bundling predictive maintenance with per-ton-kilometer usage fees are displacing traditional equipment procurement. Mining conglomerates and port authorities in Western Australia favor this structure for dedicated haulage routes. Brazilian agricultural exporters are piloting similar arrangements for seasonal grain movements.
Autonomous Freight Trains Market Segmentation
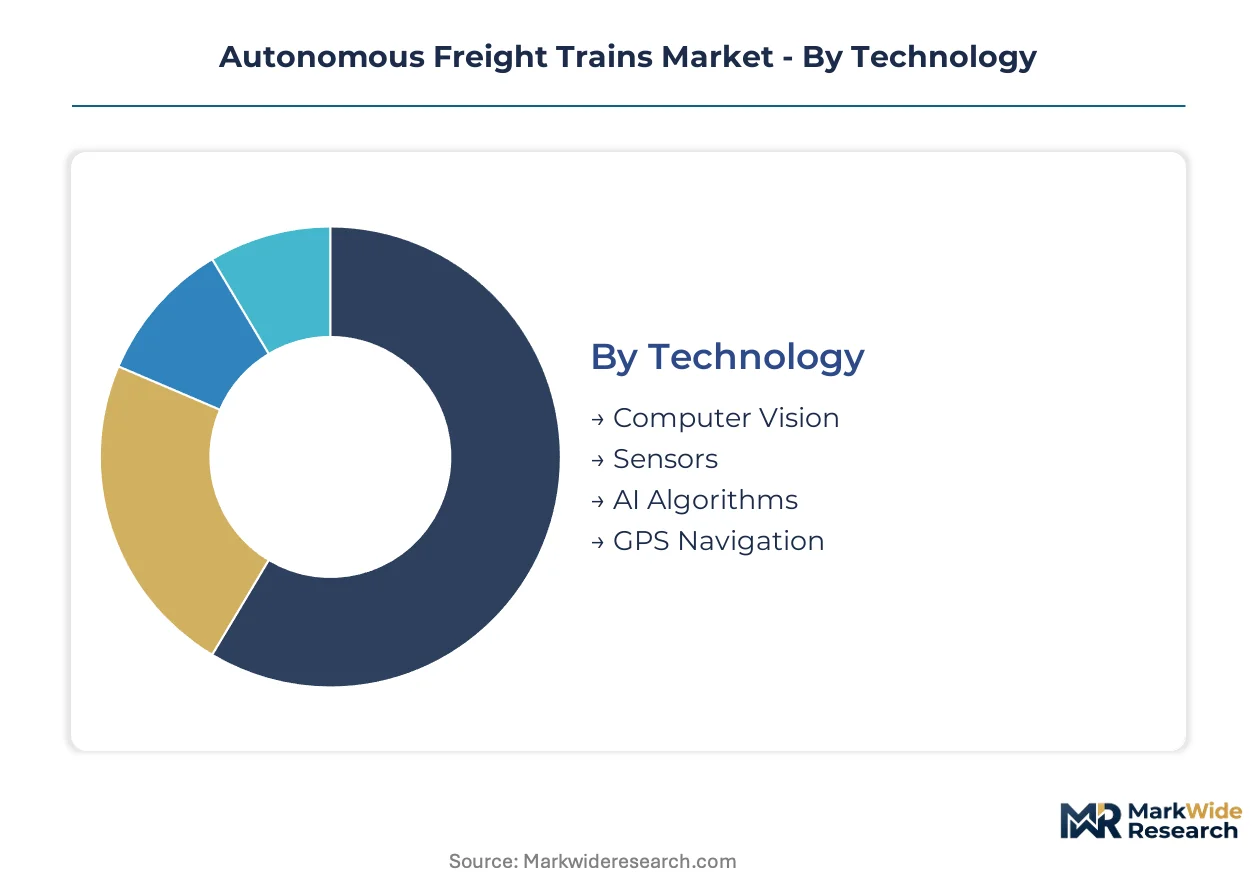
Segmentation in autonomous freight trains reveals how certification burdens and operational complexity distribute across technology layers and customer types. Procurement patterns diverge sharply between mining operators seeking heavy-haul autonomy and intermodal logistics providers prioritizing last-mile integration.
Technology:
Certification requirements vary dramatically across technology layers, with safety-critical perception systems demanding CENELEC SIL-4 validation while navigation components face lighter functional-safety scrutiny.
- Computer Vision:Machine-vision cameras process track geometry, obstacle detection, and switch alignment through convolutional neural networks. Mining corridors in Western Australia deploy these systems for centimeter-accuracy positioning in dust-heavy environments, where mechanical LiDAR suffers degradation.
- AI Algorithms:Neural-network perception architectures displace rule-based automation for obstacle classification and predictive braking. Logistics applications on dedicated port-haulage routes generate the deepest margin pools, as single-commodity flows simplify training data requirements and reduce edge-case complexity.
- Sensors:Solid-state LiDAR arrays and radar fusion platforms provide redundant environmental mapping.
- GPS Navigation:Differential GPS with real-time kinematic correction enables absolute positioning.
AI Algorithms sits at the top of the volume ranking, with Computer Vision climbing the fastest.
Application:
Application segments stratify by operational complexity, with dedicated routes commanding simpler certification pathways than mixed-traffic networks.
- Logistics:Intermodal container movements across extended distances demand autonomous coordination with port terminal operating systems. North American Class I railroads prioritize this segment under Federal Railroad Administration Positive Train Control mandates, which pre-certify collision-avoidance architectures.
- Industrial Transport:Bulk commodity haulage from mine to processing facility operates on captive infrastructure with minimal grade crossings. Western Australian iron ore corridors demonstrate measurable fuel efficiency gains that validate business cases for full-platform automation.
- Supply Chain Management:End-to-end visibility platforms integrate autonomous train status with warehouse management.
- Freight Handling:Yard switching and terminal marshalling require precise low-speed maneuvering.
Industrial Transport captures the dominant revenue share, while Logistics expands most quickly through port-haulage electrification.
End User:
End-user procurement authority concentrates with asset owners who control route access and infrastructure maintenance schedules.
- Rail Operators:Track infrastructure owners dictate system architecture through specification of signaling protocol and traffic management interfaces. European operators face acute compliance pressure from E.U. Agency for Railways interoperability mandates under the European Rail Traffic Management System.
- Freight Companies:Commodity shippers prioritize per-ton-kilometer economics over platform flexibility. Brazilian agricultural exporters pilot long-term service agreements bundling predictive maintenance with seasonal grain movements.
- Logistics Providers:Third-party integrators seek API-compatible platforms for multimodal coordination.
- Public Transport Agencies:Mixed-traffic freight corridors require harmonization with passenger scheduling.
Rail Operators hold the largest installed base, with Freight Companies gaining share fastest through mining automation economics.
Deployment:
Deployment models reflect cybersecurity risk tolerance and latency requirements for real-time control decisions.
- On-Premise:Localized computing clusters process sensor fusion and braking commands within locomotive-mounted enclosures. Heavy-haul mining operators favor this architecture for operational continuity during satellite communication outages in remote territories.
- Hybrid:Edge computing handles safety-critical functions while cloud layers manage fleet optimization and predictive maintenance. German and Austrian freight corridors deploy this configuration to balance E.U. Agency for Railways data sovereignty requirements with centralized traffic management efficiency.
- Cloud-Based:Centralized processing enables fleet-wide model updates and traffic optimization.
- Remote Monitoring:Human oversight stations intervene during anomaly events without onboard crew.
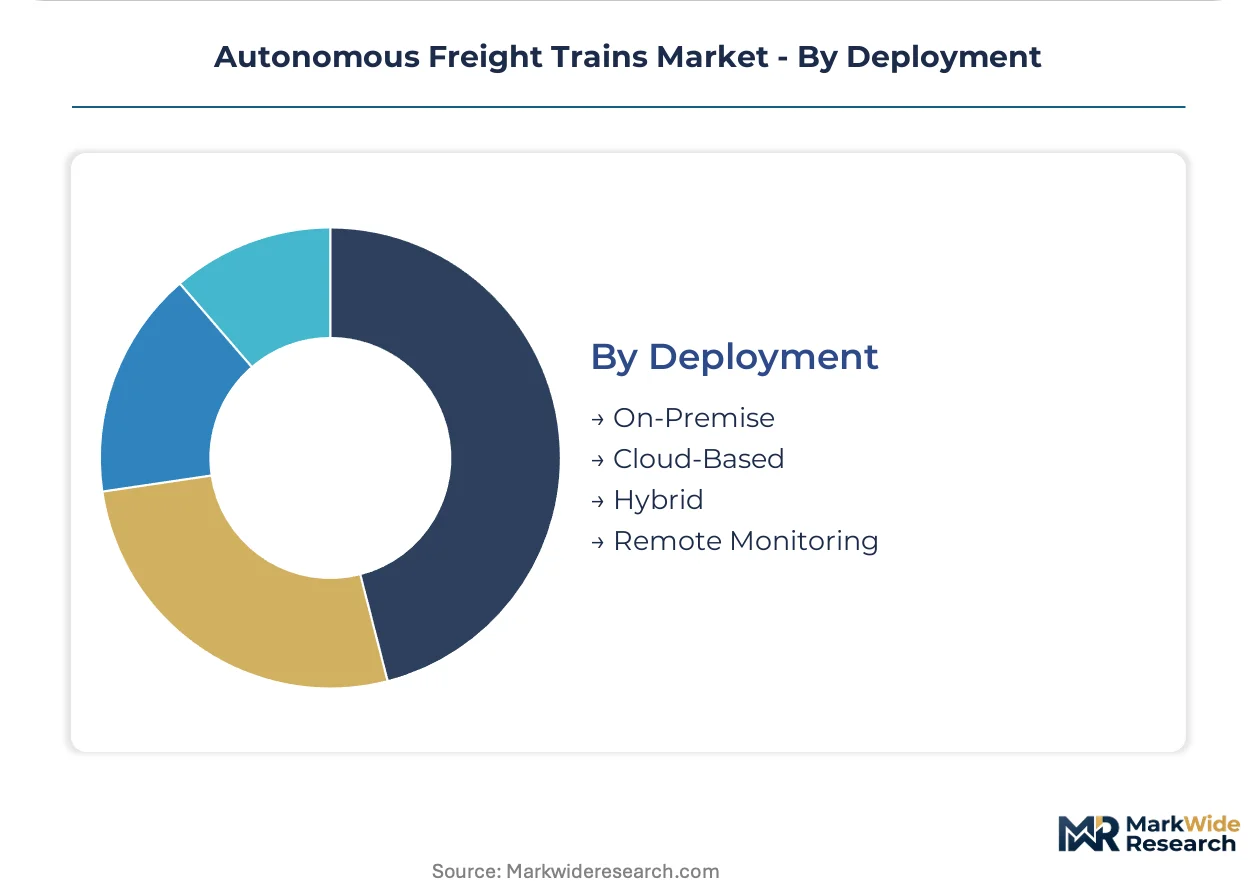
On-Premise dominates current installations, with Hybrid posting the steepest expansion trajectory as cross-border corridors multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western Australia's Pilbara region hosts the world's longest autonomous heavy-haul corridors, where Rio Tinto and BHP have validated full-platform automation economics across iron ore networks spanning hundreds of kilometers without onboard crews.
United States
Class I railroads BNSF and Union Pacific drive procurement under Federal Railroad Administration Positive Train Control mandates that pre-certify collision-avoidance architectures. The Chicago freight hub concentrates autonomous-ready locomotive retrofits as operators convert legacy fleets to comply with federal safety standards. Nebraska and Illinois maintenance facilities process the highest volumes of control system upgrades.
Germany
Deutsche Bahn Cargo prioritizes cross-border interoperability for transnational freight corridors through the E.U. Agency for Railways European Rail Traffic Management System framework. The Rhine-Ruhr industrial belt anchors signaling protocol standardization efforts that shape vendor design priorities for German-Austrian freight routes. Bavarian rail technology clusters supply digital interlocking systems with integrated machine-vision validation layers.
Australia
Rio Tinto and BHP demonstrate measurable fuel efficiency gains and shift consistency improvements across Western Australian iron ore networks. The Office of the National Rail Safety Regulator certifies autonomous operations on captive mining infrastructure with minimal grade crossings. Perth engineering centers support predictive maintenance algorithms for heavy-haul autonomy platforms.
China
CRRC Corporation Limited sustains manufacturing scale through captive production of LiDAR arrays and onboard control computers for domestic freight corridors. The Beijing-Tianjin-Hebei region concentrates high-speed rail technology spillover into heavy-haul automation. Shanxi coal transport routes pilot autonomous control systems on dedicated bulk commodity networks.
Brazil
Vale and agricultural exporters pilot autonomous systems on soy and iron ore routes from Minas Gerais to Atlantic ports that remain underpenetrated by automation providers. ANVISA and national rail safety frameworks coordinate type approval for integrated platform providers entering Latin American markets. The São Paulo industrial corridor hosts service agreement pilots bundling predictive maintenance with seasonal grain movements.
Autonomous Freight Trains Market Competitive Environment
Global majors compete with regional champions across signaling heritage and manufacturing scale, producing a tiered structure where European turnkey providers, Chinese integrated manufacturers, and North American retrofit specialists occupy distinct competitive positions. Siemens AG leverages German and Austrian freight corridor relationships to anchor automation packages, while CRRC Corporation Limited exploits captive component production for cost positioning. Wabtec Corporation converts its Positive Train Control installed base into autonomous-ready fleet configurations. Consolidation pressures intensify as full-platform contracts displace multi-source procurement of sensor suites and braking subsystems.
Among European signaling heritage providers, Siemens AG and Alstom SA exemplify the turnkey automation archetype, leveraging cross-border corridor relationships to bundle digital interlocking with onboard control systems. CRRC Corporation Limited occupies a scale-driven position through backward integration into LiDAR and computing hardware. Wabtec Corporation represents the retrofit-specialist archetype, converting North American Positive Train Control infrastructure into autonomous-ready configurations. Hitachi Rail and Thales Group sit within the multi-modal technology tier, applying rail signaling expertise developed across passenger and freight applications.
| Leading Market Players |
|---|
| Siemens AG |
| Alstom SA |
| CRRC Corporation Limited |
| Wabtec Corporation |
| Hitachi Rail |
| Kawasaki Heavy Industries |
| Mitsubishi Heavy Industries Ltd. |
| Thales Group |
| CAF |
| Others |
Value Chain & Pricing Dynamics
Functional-safety engineering talent concentration in German and Japanese industrial centers creates labor-cost differentials that widen pricing-tier spreads between SIL-4 certified platforms and uncertified alternatives. Buyers in mining automation corridors absorb premium pricing for validated systems while budget-constrained retrofit markets face compressed margins.
Pricing Analysis
Input-cost pass-through from solid-state LiDAR manufacturing scale and copper supply volatility shapes platform pricing structures across autonomous freight train deployments. Three-tier pricing structure across premium, standard, and economy levels separates full-turnkey automation packages from modular sensor upgrades and legacy retrofit configurations. Price differentiation hinges on CENELEC SIL-4 certification grade and after-sales service bundling intensity. Cost compression in economy-tier retrofits is intensifying because legacy fleet conversion demands capital expenditure comparable to new-build alternatives. Mining operators in Western Australia demonstrate lowest price sensitivity due to measurable fuel efficiency gains validating business cases, while Brazilian agricultural exporters exhibit highest sensitivity through seasonal volume uncertainty.
Supply Chain Analysis
Workforce availability constraints in German signaling engineering clusters and Japanese rail-technology centers tether production schedules to regional labor migration patterns. Geographic supply concentrates in China for LiDAR arrays and onboard control computers, Germany for digital interlocking systems, and the United States for Positive Train Control hardware. Raw material dependencies draw from Chilean copper concentrate for traction motors, Australian iron ore demand fluctuations for mining corridor deployments, and lithium supply chains for battery-electric locomotive convergence. Single-source vulnerability in South American copper mining exposes production schedules to concentrate availability disruptions. Distribution runs through long-term service agreements bundling predictive maintenance with per-ton-kilometer usage fees, displacing traditional equipment procurement in Western Australian mining corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Autonomous Freight Trains Market operates as a stable compounder, with regulatory pre-certification frameworks under Positive Train Control mandates and European Rail Traffic Management System interoperability requirements generating predictable procurement cycles across North American and European freight corridors.
For Market Incumbents: Deepen backward integration into solid-state sensor manufacturing to capture LiDAR cost curve benefits and defend margin position against Chinese scale competitors. Anchor turnkey automation packages through signaling heritage relationships in German-Austrian corridors while converting Positive Train Control installed bases into autonomous-ready configurations before regulatory refresh cycles accelerate. Prioritize CENELEC SIL-4 certification investment as emerging entrants without rail-specific functional-safety expertise threaten commoditization of uncertified subsystems. For New Entrants and Emerging Players: Port terminal operators represent the most accessible channel partner type for autonomous coordination pilots, offering API-compatible platforms that integrate with existing terminal operating systems without demanding full traffic management replacement. Brazilian agricultural corridors from Minas Gerais to Atlantic ports present underpenetrated white-space for first-mover positioning, with seasonal grain movements enabling service agreement pilots that bundle predictive maintenance with usage-based fees. Target battery-electric convergence applications on non-electrified mining spurs where catenary-independent architectures reduce infrastructure dependency barriers. For Investors and Strategic Acquirers: Mining conglomerates with captive haulage infrastructure represent the most active acquirer in this space, consolidating integrated platform providers to secure supply chain control over autonomous heavy-haul operations. Long-term viability across the coming decade rests on regulatory pre-certification moats and signaling protocol standardization capabilities that resist commoditization. Acquisition target archetypes include mid-cap specialists with E.U. Agency for Railways interoperability validation or Australian Office of the National Rail Safety Regulator certification track records. Watch for inflection signals in Brazilian ANVISA type approval timelines, as acceleration would indicate Latin American market opening.| Strategic Initiative | Industry Significance |
|---|---|
| Long-Term Service Agreement Structuring | Per-ton-kilometer pricing bundles predictive maintenance with platform access, aligning vendor incentives with mining operator uptime requirements across Western Australian iron ore corridors. |
| Cross-Border Interoperability Certification | E.U. Agency for Railways validation under European Rail Traffic Management System gates vendor access to German-Austrian freight corridors and shapes design priorities for transnational automation. |
| Battery-Electric Locomotive Integration | Lithium-titanate traction battery architectures enable autonomous operation on non-electrified mining spurs, expanding addressable infrastructure beyond catenary-dependent routes. |
| Neural-Network Perception Migration | Convolutional neural networks displace rule-based automation for obstacle classification, reducing edge-case complexity on dedicated single-commodity port-haulage routes. |
| Legacy Fleet Retrofit Program | Positive Train Control hardware conversion to autonomous-ready configurations captures North American Class I railroad procurement cycles under Federal Railroad Administration mandates. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary field engagement with rail operators, freight company procurement directors, signaling system engineers, and predictive maintenance algorithm developers alongside secondary validation. Primary sources included executives at Class I railroads, mining automation program managers, and European rail technology cluster representatives. Secondary data drew from Federal Railroad Administration Positive Train Control implementation reports, E.U. Agency for Railways interoperability documentation, Australian Office of the National Rail Safety Regulator certification records, and customs trade data for LiDAR and traction motor components. Bottom-up segment sizing and top-down macro constraint triangulation anchored volume estimates.
Segment-weighting approaches distributed value and volume across technology layers, application types, and deployment models, with AI Algorithms and Computer Vision receiving differentiated growth assumptions based on neural-network adoption curves in mining versus intermodal logistics. End-user segmentation weighted Rail Operators heaviest given infrastructure ownership and procurement authority, while Freight Companies captured accelerating share through mining automation economics. Deployment model splits reflected cybersecurity risk tolerance and latency requirements, with Hybrid configurations posting steepest expansion as cross-border corridors multiplied. CAGRs derived from technology substitution rates, regulatory mandate compliance timelines, and commodity flow projections across the analysis window.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to copper supply concentration disruptions, multi-jurisdiction type approval timeline extensions, and functional-safety engineering talent migration patterns. Forecasts reflect assumptions about regulatory pre-certification stability, solid-state sensor cost curve trajectories, and mining corridor automation economics validation. Material deviation in Federal Railroad Administration mandate enforcement intensity, E.U. Agency for Railways interoperability acceleration, or Chilean-Peruvian mining concentrate availability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Zonal Vehicle Control Unit Architectures Market
Autonomous Vehicles
Middle East and Africa ADAS Market
Autonomous Vehicles
Automotive Autonomous Emergency Braking System Market
Autonomous Vehicles
Autonomous Driving Technology Market
Autonomous Vehicles
Europe Autonomous Navigation Market
Autonomous Vehicles
Automotive Automated Parking System Market
Autonomous Vehicles
Self Driving Car Market
Autonomous Vehicles
Norway Autonomous Navigation Market
Autonomous Vehicles
Greece Autonomous Navigation Market
Autonomous Vehicles
Autonomous Intelligent Vehicle Market
Autonomous Vehicles
Driverless Taxi Market
Autonomous Vehicles
AI in Transportation Market
Autonomous Vehicles
Autonomous Vehicle ECU Market
Autonomous Vehicles
Autonomous Emergency Braking System (AEBS) Market
Autonomous Vehicles
Autonomous System Market
Autonomous Vehicles
Vehicle Intelligence System Market