
 5G V2X Communications Market | 2026-2036
5G V2X Communications Market Size, Share, and Industry Trends Forecast 2026-2036
5G V2X Communications Market Insights
Embedded systems engineering talent is rotating toward automotive wireless stacks as telecom and semiconductor employers compete for the same RF protocol specialists. Qualcomm Inc. leverages its Snapdragon Automotive platform to dominate modem-to-cloud integration for C-V2X deployments. Continental AG anchors European OEM relationships through its roadside unit and onboard unit hardware portfolio. NXP Semiconductors differentiates via secure element silicon purpose-built for V2X message authentication.
5G V2X communications denotes direct vehicle-to-vehicle and vehicle-to-infrastructure connectivity over cellular networks operating in licensed spectrum below 6 GHz, with ultra-reliable low-latency communication enabling sub-20 millisecond message exchange for collision avoidance and cooperative maneuvering. C-V2X technology leads deployment roadmaps because it shares LTE and 5G NR infrastructure, reducing dedicated roadside buildout costs versus DSRC alternatives. Fleet Management applications generate the fastest-growing demand as logistics operators deploy truck platooning and predictive maintenance systems. Edge Computing deployment architectures concentrate margin pools by minimizing backhaul latency for safety-critical autonomous vehicle functions.
The FCC governs spectrum access at 5.9 GHz for intelligent transportation services in the United States, while the EU AI Act and GDPR impose algorithmic transparency and data governance requirements on automated driving systems processing V2X data streams. China's MIIT issues GB standards mandating C-V2X compatibility for new vehicle type approvals, effectively locking deployment architecture. Stakeholders must decide whether to pursue multi-protocol hardware flexibility or commit fully to C-V2X as regional regulatory divergence hardens.
Market Dynamics
The transition from DSRC to C-V2X as the dominant vehicular connectivity standard is compressing equipment refresh cycles and forcing roadside infrastructure owners to commit capital before protocol uncertainty resolves.
Growth Catalysts
- FCC 5.9 GHz spectrum reallocation:The FCC's rulemaking reserves upper 30 MHz for C-V2X, eliminating DSRC ambiguity and triggering state DOT procurement cycles for intelligent transportation infrastructure.
- Truck platooning adoption:Fleet operators in long-haul logistics are deploying vehicle-to-vehicle coordination systems to reduce aerodynamic drag and fuel consumption across highway corridors.
- Edge computing node deployment:Telecom infrastructure providers are installing roadside MEC servers to process sub-20 millisecond safety messages without backhaul latency to centralized clouds.
Market Restraints
- Silicon supply concentration:Secure element manufacturing for V2X message authentication depends on a limited foundry base concentrated in East Asia, creating single-source vulnerability for automotive tier-1 suppliers.
- DSRC stranded asset risk:Early municipal deployments of IEEE 802.11p roadside units in Japan and parts of Europe face write-down pressure as C-V2X gains regulatory preference.
- Cross-border spectrum fragmentation:Divergent channel plans between the FCC's 5.9 GHz allocation and Europe's harmonized 5.875-5.925 GHz band complicate multi-region vehicle platform engineering.
Strategic Opportunities
- Predictive maintenance integration:Vehicle health monitoring via C-V2X broadcasts creates aftermarket service revenue streams for commercial fleet management platforms.
- EU AI Act compliance services:Algorithmic transparency requirements for automated driving systems processing V2X data streams open consulting and certification service markets.
- V2X-to-smart-city convergence:Municipal traffic signal priority systems and pedestrian safety alerts represent untapped demand from urban planning departments.
Industry Challenges
- RF protocol engineering scarcity:Automotive OEMs and tier-1 suppliers compete with consumer electronics and telecom equipment manufacturers for embedded wireless stack specialists.
- Multi-standard hardware validation:Suppliers must maintain DSRC compatibility for legacy markets while engineering C-V2X-only cost-optimized variants, duplicating certification effort.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G V2X Communications Market |
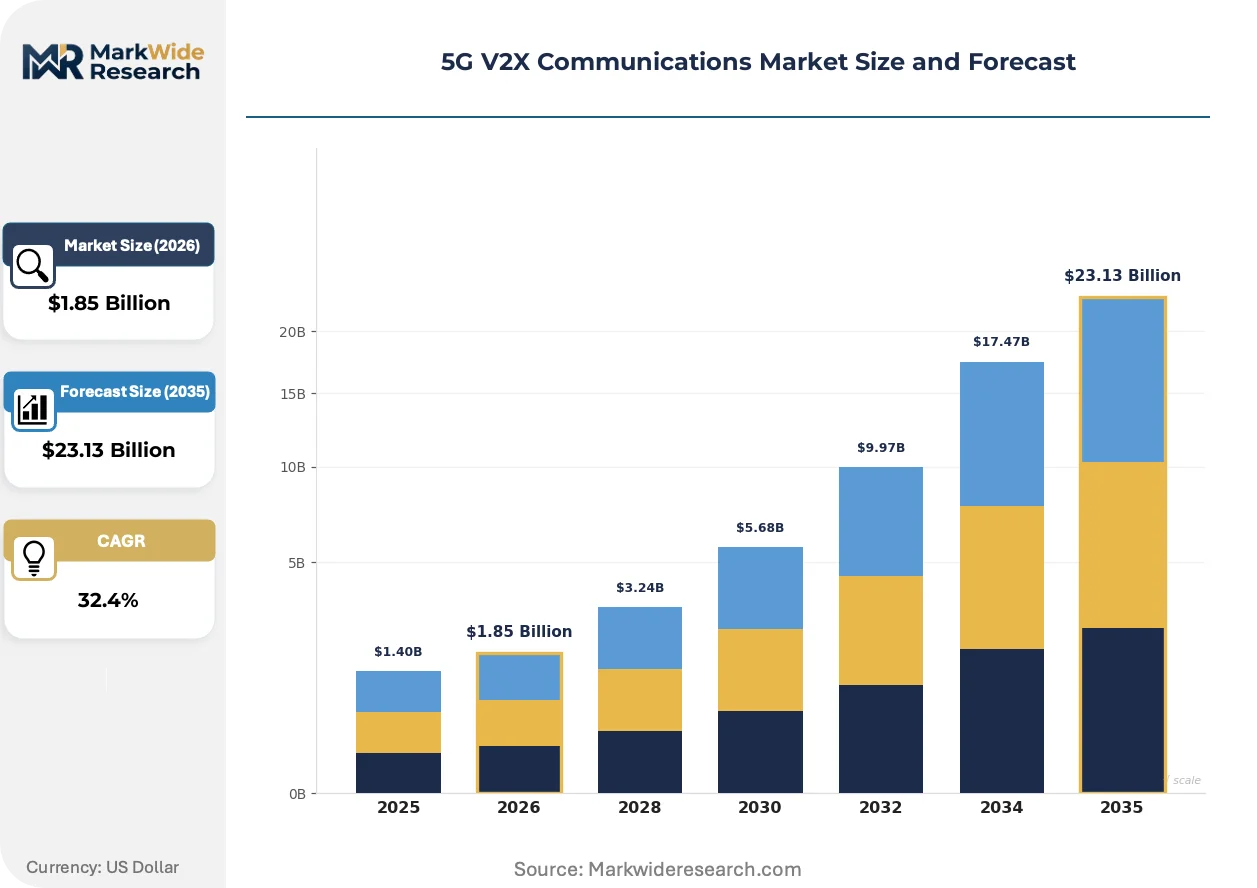
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $23.13 Billion |
| CAGR (2026 – 2036) | 32.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: DSRC, C-V2X, LTE-V, Others Application: Autonomous Vehicles, Fleet Management, Traffic Management, Emergency Services End User: Automotive Manufacturers, Government Agencies, Transportation Providers, Telecom Operators Deployment: Edge Computing, Cloud-Based, On-Premises, Hybrid |
| Companies Covered | Qualcomm Inc., Huawei Technologies, Continental AG, NXP Semiconductors, Ericsson AB, Autotalks, Harman International, Denso Corporation, Nokia Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G V2X Communications Market Trends and Innovations
Wireless module architecture is converging with automotive zonal compute platforms, compressing the traditional separation between connectivity hardware and domain controllers. This integration is redrawing supplier boundaries and value capture.
Dual-mode V2X chipsets combining 4G LTE-V2X and 5G NR-V2X in single packages is miniaturizing onboard unit footprints while preserving backward compatibility for vehicles operating in regions with incomplete 5G roadside coverage. Tier-1 integrators are adopting these consolidated modules to reduce antenna count and wiring complexity. The resulting space and weight savings enable placement in mirror housings and lamp assemblies previously inaccessible to larger units.
China's MIIT GB standards mandate C-V2X compatibility for new vehicle type approvals, effectively locking deployment architecture for domestic and export-bound automotive platforms. This regulatory compression accelerates chipset volume ramps but forces foreign suppliers to establish local certification partnerships. European and North American OEMs with Chinese joint ventures are adapting platform strategies to this mandatory specification.
Fleet procurement departments are consolidating vendor relationships around end-to-end telematics providers capable of integrating V2X data streams with existing dispatch and maintenance software. This buyer concentration favors suppliers with cloud-native architectures over hardware-centric specialists. The shift is most visible in North American trucking, where large operators are reducing supplier counts from twelve-plus to four or five strategic partners.
5G V2X Communications Market Segmentation
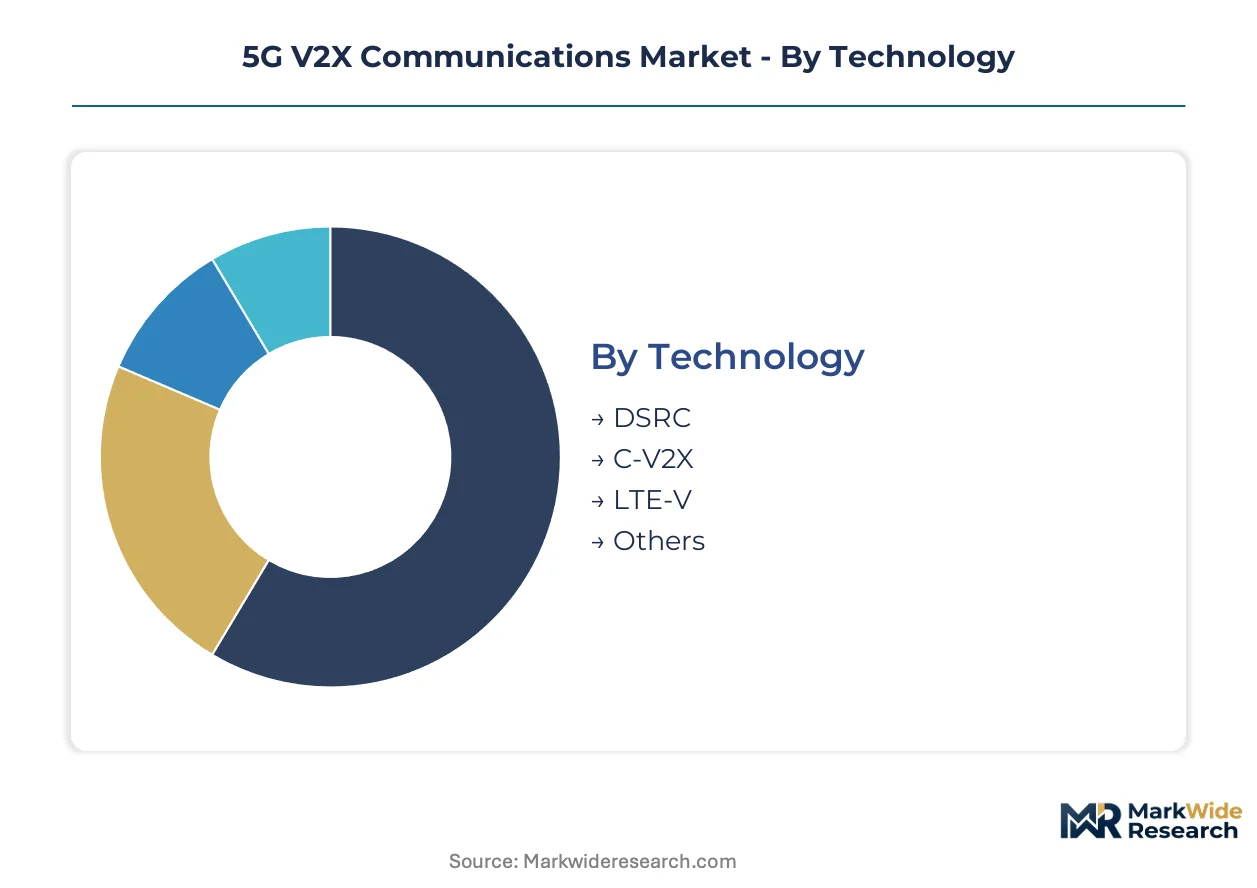
5G V2X Communications Market segmentation reveals how value concentrates across protocol standards, deployment architectures, and buyer categories. Each dimension carries distinct margin profiles and competitive dynamics that shape supplier strategy.
Technology:
Margin pools concentrate in integrated modem-chipset combinations that secure automotive design wins early in platform development cycles.
- C-V2X:Cellular vehicle-to-everything technology leverages existing LTE and 5G NR infrastructure, reducing dedicated roadside buildout costs for transportation agencies. China's MIIT mandates GB standard compatibility, locking deployment architecture and accelerating chipset volume ramps for domestic and export-bound platforms.
- DSRC:Dedicated short-range communications operates in 5.9 GHz spectrum with IEEE 802.11p protocols, facing write-down pressure as C-V2X gains regulatory preference in major automotive markets. Early municipal deployments in Japan and parts of Europe now confront stranded asset risk.
- LTE-V:LTE-based vehicle connectivity provides backward compatibility for regions with incomplete 5G roadside coverage, enabling dual-mode chipset strategies.
- Others:Satellite augmentation and mesh networking variants address coverage gaps in rural corridors and tunnel environments.
C-V2X holds installed capacity. LTE-V is rotating up the share rankings.
Application:
Application segmentation tracks where latency requirements and safety-criticality translate into premium pricing power.
- Fleet Management:Truck platooning and predictive maintenance systems generate expanding demand from logistics operators seeking fuel efficiency across highway corridors. North American trucking consolidation around end-to-end telematics providers favors suppliers with cloud-native architectures.
- Autonomous Vehicles:Cooperative maneuvering and collision avoidance functions demand sub-20 millisecond message exchange, concentrating procurement around ultra-reliable low-latency communication stacks.
- Traffic Management:Municipal signal priority systems and congestion optimization represent procurement from urban planning departments with extended budget cycles.
- Emergency Services:First responder preemption and hazard broadcast applications require hardened reliability specifications.
Fleet Management is climbing the fastest. Autonomous Vehicles commands premium unit economics.
End User:
End user segmentation distinguishes between volume-driven automotive OEM procurement and infrastructure-led government deployment.
- Automotive Manufacturers:Platform engineering teams specify onboard units for new vehicle type approvals, with Chinese joint ventures adapting to MIIT GB mandates. RF protocol engineering scarcity intensifies competition for embedded wireless stack specialists.
- Government Agencies:State DOTs trigger procurement cycles following FCC 5.9 GHz reallocation, concentrating roadside unit installation decisions.
- Transportation Providers:Fleet operators consolidate vendor relationships around integrated telematics platforms.
- Telecom Operators:Infrastructure providers install roadside MEC servers to minimize backhaul latency for safety-critical functions.
Automotive Manufacturers anchor volume commitments. Government Agencies is expanding most quickly.
Deployment:
Deployment architecture determines where latency constraints and data sovereignty requirements concentrate margin.
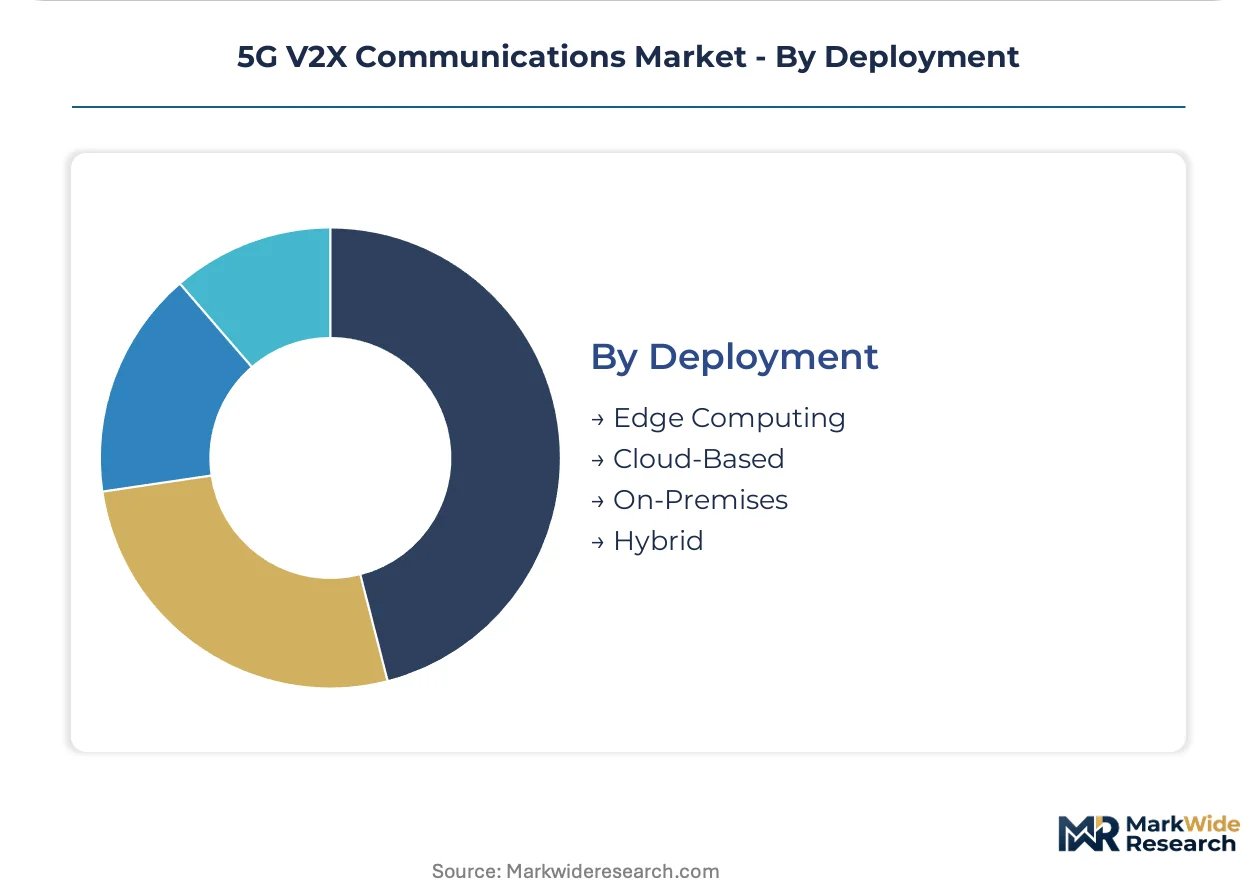
- Edge Computing:Roadside MEC servers process safety messages without centralized cloud backhaul, capturing premium positioning for sub-20 millisecond applications. Telecom infrastructure providers are installing these nodes along highway corridors.
- Hybrid:Architectures split critical safety functions to edge nodes while routing telematics to centralized clouds, balancing latency and cost optimization.
- Cloud-Based:Centralized processing suits non-time-sensitive fleet analytics and predictive maintenance workloads.
- On-Premises:Dedicated infrastructure addresses data sovereignty requirements in sensitive transportation corridors.
Edge Computing holds technology leadership. Hybrid is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT anchors the dominant geography through mandatory GB standards that lock C-V2X deployment architecture for domestic and export-bound automotive platforms. The United States, Germany, Japan, and South Korea represent the other critical concentration points where spectrum allocation and automotive manufacturing intersect.
United States
Fleet operators in long-haul logistics deploy truck platooning systems across Interstate highway corridors. The FCC's 5.9 GHz spectrum reallocation reserves upper 30 MHz exclusively for C-V2X, eliminating DSRC ambiguity and triggering state DOT procurement cycles. Michigan's automotive corridor concentrates roadside unit pilot programs near Detroit manufacturing clusters.
Germany
Continental AG anchors European OEM relationships through roadside and onboard unit hardware portfolios. The EU AI Act imposes algorithmic transparency requirements on automated driving systems processing V2X data streams. Bavaria's automotive engineering ecosystem drives validation testing for dual-mode V2X chipsets combining 4G LTE-V2X and 5G NR-V2X.
Japan
Early municipal DSRC deployments face write-down pressure as C-V2X gains regulatory preference globally. METI coordinates spectrum harmonization discussions with automotive manufacturers transitioning platform strategies. Nagoya's Chubu region hosts tier-1 supplier engineering centers adapting to multi-protocol hardware validation requirements.
South Korea
Telecom infrastructure providers install roadside MEC servers to minimize backhaul latency for safety-critical autonomous vehicle functions. The country's national spectrum regulator coordinates 5.9 GHz channel plans with automotive export requirements. Seoul Capital Area concentrates edge computing node deployment along highway corridors serving the domestic market.
5G V2X Communications Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the 5G V2X communications ecosystem. The market structure consolidates around semiconductor modem providers, automotive tier-1 integrators, and telecom infrastructure specialists. Three strategic archetypes dominate: integrated platform vendors controlling modem-to-cloud stacks, hardware-focused roadside unit manufacturers, and secure element specialists. Competitive moves concentrate on strategic partnerships between chipset vendors and automotive OEMs, plus geographic expansion through local certification partnerships in China.
Within the integrated platform tier, Qualcomm Inc. and Huawei Technologies occupy positions exemplifying modem-to-cloud dominance. Continental AG represents the automotive tier-1 hardware archetype through its European OEM relationships. NXP Semiconductors anchors the secure element specialization segment. These three companies collectively illustrate how supplier boundaries redraw as wireless module architecture converges with automotive zonal compute platforms.
| Leading Market Players |
|---|
| Qualcomm Inc. |
| Huawei Technologies |
| Continental AG |
| NXP Semiconductors |
| Ericsson AB |
| Autotalks |
| Harman International |
| Denso Corporation |
| Nokia Corporation |
| Others |
Pricing and Supply Chain Analysis
Forty-five to sixty days of secure element inventory now separates automotive tier-1 suppliers from production halts, concentrating pricing power with East Asian foundries while forcing buyers into long-term offtake commitments. This lead-time exposure feeds directly into module cost structures, as C-V2X chipset vendors pass through wafer premiums to OEM platform teams locked into MIIT GB compliance timelines.
Pricing Analysis
Unit economics spread three-to-one between North American fleet telematics deployments and Chinese domestic OEM volume contracts, reflecting divergent certification burdens and after-sales service bundling. Pricing stratifies across automotive-grade, industrial-grade, and commercial-grade certification tiers, with AEC-Q100 validation adding substantial premiums. Cost compression in the commercial-grade tier is intensifying because logistics operators consolidate vendor relationships around cloud-native architectures. Fleet procurement departments exhibit highest price sensitivity, while autonomous vehicle platform teams prioritize latency performance over unit cost.
Supply Chain Analysis
Taiwan and South Korea anchor advanced node wafer fabrication for V2X modem silicon, while China concentrates backend packaging and testing capacity for automotive secure elements. Raw material dependencies span gallium arsenide substrates, high-frequency laminates, and automotive-grade epoxy resins. Single-source vulnerability concentrates in EUV lithography equipment for sub-7nm modem designs. Distribution runs through tier-1 automotive electronics integrators holding direct OEM relationships, with limited spot-market availability for certified modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 5G V2X communications market is recovering from DSRC protocol uncertainty, with FCC 5.9 GHz reallocation and MIIT GB standard mandates providing cyclical clarity for capital deployment.
For Market Incumbents: Fortify modem-to-cloud integration capabilities against Huawei's platform dominance in China by deepening partnerships with European and North American OEMs. Secure alternative foundry capacity outside Taiwan for secure element production to mitigate geographic concentration risk. Prioritize certification investment for dual-mode 4G/5G chipsets that preserve backward compatibility during infrastructure transition periods. For New Entrants and Emerging Players: Anchor in predictive maintenance software layers where fleet operators seek V2X-integrated telematics platforms, avoiding hardware-dominated segments where Qualcomm and Continental hold entrenched positions. Municipal smart-city traffic signal priority systems represent the most penetrable application, with urban planning departments lacking incumbent supplier relationships. Pursue cloud-native SaaS delivery models that bypass capital-intensive roadside unit manufacturing. For Investors and Strategic Acquirers: Carve-out targets emerge from telecom infrastructure providers spinning off roadside MEC server divisions as autonomous vehicle deployment timelines extend. Long-term viability hinges on C-V2X protocol standardization holding against satellite and mesh networking alternatives. Monitor FCC enforcement actions on 5.9 GHz spectrum utilization as the critical inflection signal for infrastructure investment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | MIIT GB mandates force OEMs toward unified C-V2X architectures, accelerating chipset volume ramps. |
| Edge Computing Partnership | Telecom infrastructure providers install roadside MEC servers to capture sub-20 millisecond safety message processing. |
| Secure Element Supply Agreement | Automotive tier-1 suppliers seek alternative foundry capacity to reduce Taiwan concentration exposure. |
| Fleet Telematics Integration | Logistics operators consolidate around end-to-end providers capable of V2X-dispatch software fusion. |
| Regulatory Certification Investment | Dual-mode 4G/5G chipset validation preserves market access across incomplete 5G coverage regions. |
Research Methodology
A standing panel of automotive platform engineers, tier-1 supplier procurement directors, state DOT intelligent transportation specialists, and telecom infrastructure planners provided ongoing calibration against market developments. Primary fieldwork combined structured interviews with secondary validation through FCC rulemaking dockets, MIIT GB standard publications, vehicle production databases, and SEC filings from disclosed automotive electronics suppliers. Bottom-up unit economics triangulated against top-down infrastructure deployment forecasts across the analysis window.
Consistency checks validated volume and value outputs against roadside unit installation trajectories, chipset shipment disclosures, and fleet telematics adoption benchmarks. The analytical framework modeled technology transitions, application latency requirements, deployment architecture choices, and regional regulatory clusters throughout the forecast period. CAGRs derived from S-curve penetration modeling for connected vehicle platforms, with explicit inputs for spectrum allocation timing and OEM platform refresh cycles.
Decision-makers should treat outputs as directional under assumptions of C-V2X protocol dominance and sustained automotive semiconductor demand; material deviation in DSRC residual viability or foundry capacity expansion would warrant model refresh. Recalibration cycles align with material shifts in FCC enforcement posture, MIIT standard updates, and autonomous vehicle deployment milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
In-Vehicle Infotainment Systems Market
Telematics and Infotainment
Motor Racing Telematics Market
Telematics and Infotainment
Global Car GPS Navigation System Market
Telematics and Infotainment
Transport Data Logger Market
Telematics and Infotainment
Consumer Telematics Market
Telematics and Infotainment
Telematics Market
Telematics and Infotainment
Telematics and Connectivity Control Unit Systems Market
Telematics and Infotainment
Automotive Personal Navigation Systems Market
Telematics and Infotainment
Park Assist Camera Market
Telematics and Infotainment
Electric Vehicle Telematics Market
Telematics and Infotainment
Automotive Human Machine Interface (HMI) Market
Telematics and Infotainment
APAC Telematics Market
Telematics and Infotainment
Automotive Navigation Solutions Market
Telematics and Infotainment
Asia Pacific Automotive Navigation System Market
Telematics and Infotainment
In-Taxi Digital Signage Market
Telematics and Infotainment
North America Dashboard Camera Market