
 Automotive Navigation Solutions Market | 2026-2036
Automotive Navigation Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Navigation Solutions Market Outlook
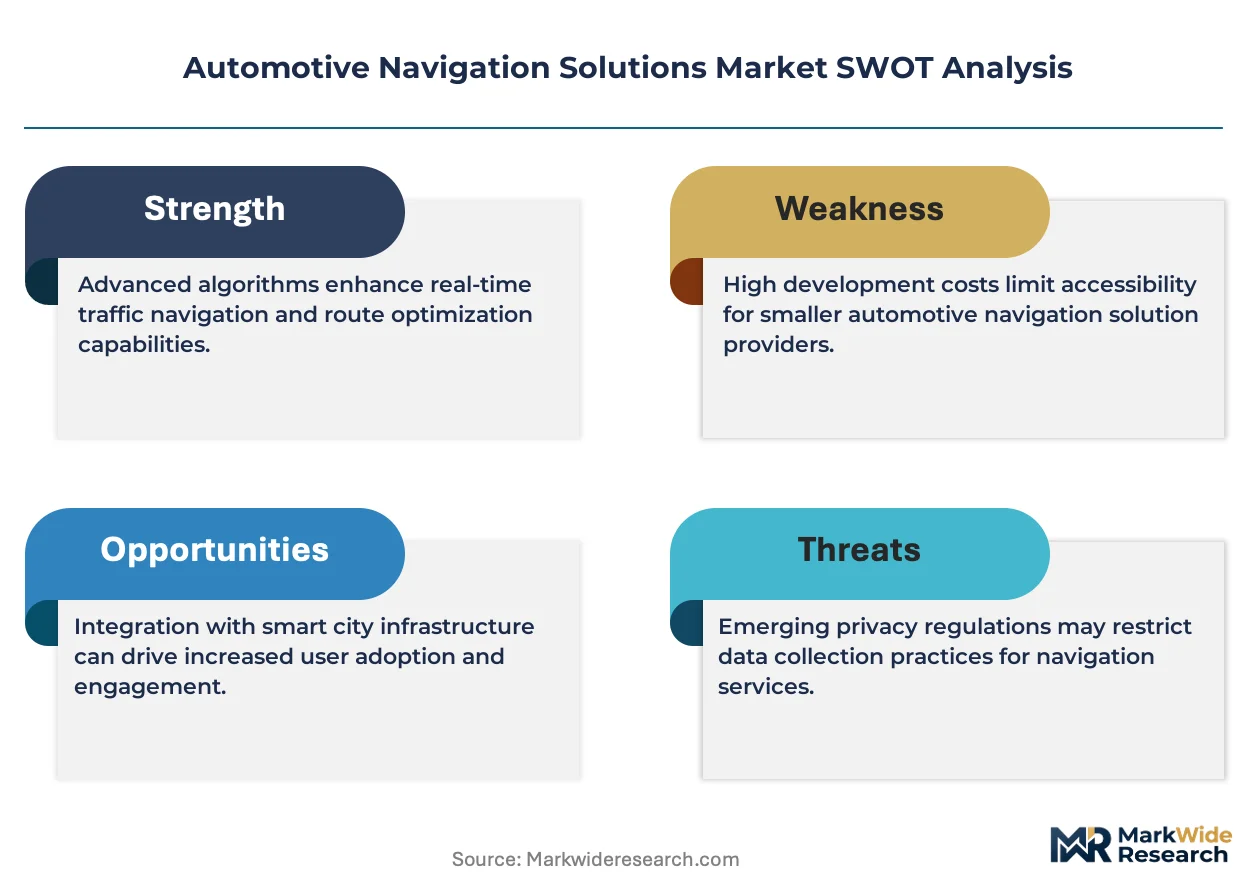
Germany's automotive electronics corridor is reconfiguring how navigation hardware and software co-develop within European supply chains. Continental AG anchors embedded system production through its Ingolstadt and Regensburg facilities, leveraging deep ties to domestic OEM programs. HERE Technologies competes on high-definition mapping coverage, sustaining data collection networks across multiple continents. Robert Bosch GmbH dominates sensor fusion modules, integrating GPS with LiDAR inputs for tier-one supply contracts.
Automotive navigation solutions encompass positioning, routing, and guidance systems that process satellite signals, camera feeds, and vehicle-to-infrastructure data to calculate optimal travel paths. These systems typically operate with sub-meter GPS accuracy and refresh map data through over-the-air updates to maintain route validity. Embedded Systems capture the largest installed base due to OEM pre-installation economics, while Cloud-Based platforms represent the fastest-expanding segment as fleet operators prioritize real-time traffic integration and remote fleet management. Aftermarket Solutions retain margin pools in regions where vehicle replacement cycles lag technology refresh rates.
The EU AI Act and GDPR constrain how navigation providers process location data across European markets, forcing architecture changes toward edge-based computation. Germany's KBA enforces type-approval standards for driver assistance systems that incorporate navigation inputs, directly shaping product certification timelines. In the United States, NHTSA guidelines on automated driving system safety influence how navigation platforms validate route data for autonomous operation. Stakeholders must weigh regulatory fragmentation against the cost of region-specific compliance architectures as deployment scales.
Market Dynamics
Fleet operators are consolidating routing decisions onto cloud-native platforms that ingest real-time traffic, weather, and infrastructure data streams. This shift compresses hardware refresh cycles while elevating software subscription revenue in supplier economics.
Growth Catalysts
- EU AI Act compliance mandates:European OEMs must certify navigation systems processing driver biometric data, creating recurring revenue pools for compliance-architecture vendors.
- HD map layer proliferation:Autonomous driving stacks in China require centimeter-accurate road geometry, pulling navigation providers into sensor fusion partnerships with domestic EV manufacturers.
- Edge computing migration:Germany's KBA type-approval standards for driver assistance systems are forcing computation onto vehicle-mounted processors, expanding embedded system addressable market.
Market Restraints
- Semiconductor input volatility:GPS receiver chipsets and automotive-grade GPUs face allocation constraints from Taiwan-based foundry concentration, inflating bill-of-material costs.
- GPRS/4G module dependency:Over-the-air map updates require persistent cellular connectivity, exposing operators to telecom tariff regimes and sunsetting network protocols.
- GDPR territorial friction:Cross-border fleet routing triggers data-localization requirements that fragment cloud architecture and inflate compliance overhead.
Strategic Opportunities
- Aftermarket retrofit penetration in India:Commercial vehicle fleets operating legacy trucks without factory navigation represent unserved demand for smartphone-integrated dash-mounted units.
- V2X mandate alignment in Germany:The country's connected-vehicle infrastructure investment program creates specification pull for navigation systems with vehicle-to-infrastructure communication modules.
- LiDAR-GPS fusion convergence:Sensor hardware cost curves are enabling tier-two suppliers to bundle positioning with perception stacks for mid-market OEM programs.
Industry Challenges
- Functional safety certification timelines:ISO 26262 ASIL-D validation for navigation inputs to automated driving systems extends product development cycles by 18-24 months.
- Map data freshness operations:Maintaining sub-meter accuracy requires continuous ground-truthing fleets, compressing margin at scale.
- Cross-platform integration complexity:Navigation software must synchronize with proprietary OEM infotainment operating systems, fragmenting engineering resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Navigation Solutions Market |
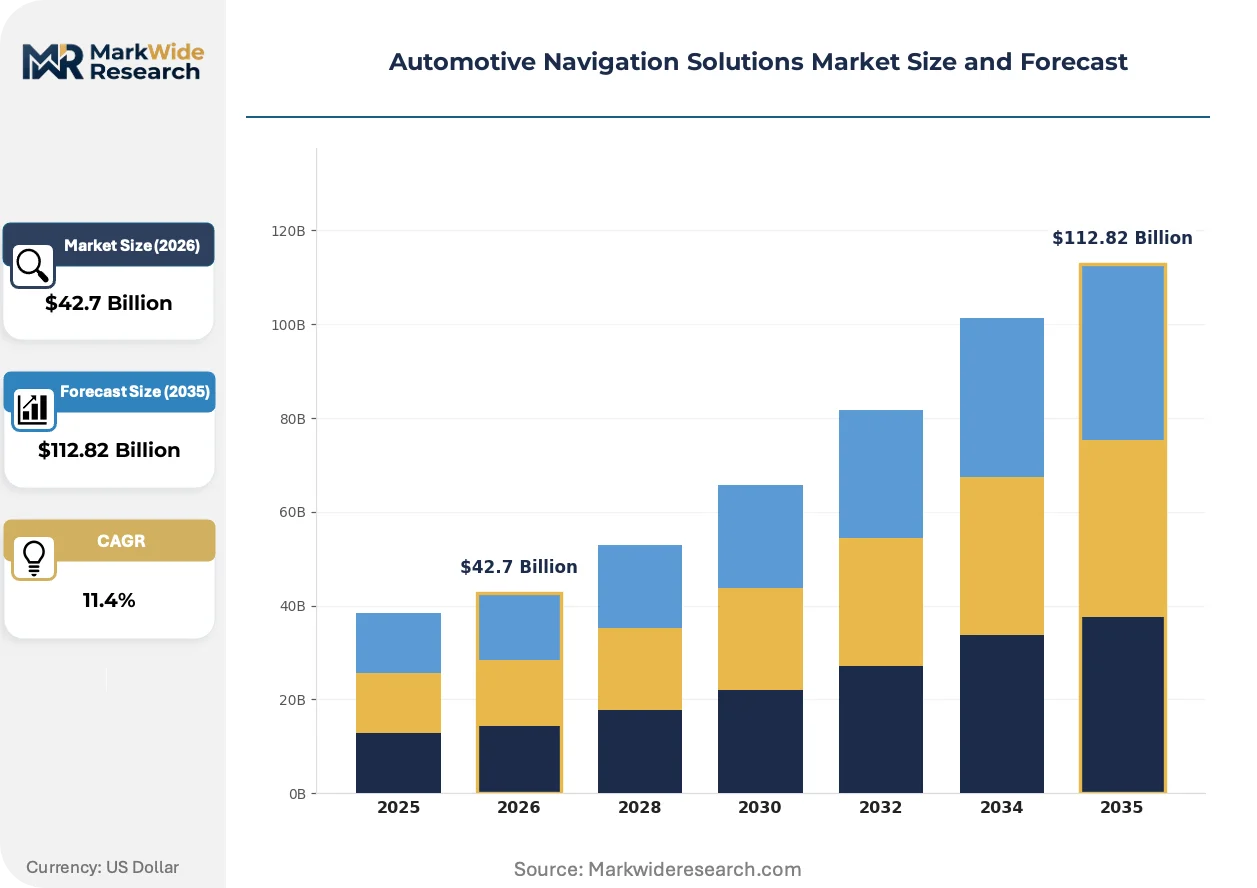
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $112.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded Systems, Cloud-Based, Handheld Devices, Aftermarket Solutions Technology: GPS, LiDAR, Computer Vision, V2X Communication End User: OEMs, Fleet Operators, Consumer Vehicles, Ride-Sharing Companies Application: Traffic Management, Route Optimization, Navigation Assistance, Autonomous Driving |
| Companies Covered | Garmin Ltd., TomTom International BV, Continental AG, Robert Bosch GmbH, HERE Technologies, DENSO Corporation, Alpine Electronics, Harman International, Pioneer Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Navigation Solutions Market Strategic Shifts
Navigation architectures are decoupling from dedicated hardware, with positioning intelligence migrating to software-defined vehicle platforms. This reconfiguration alters how suppliers capture value and how buyers contract for capability.
High-definition mapping is virtualizing the physical road network into machine-readable semantic layers that autonomous systems consume for path planning. Tier-one suppliers are adopting these data products for highway pilot programs. The technology is virtualizing traditional map publishing economics, compressing per-kilometer data collection costs while elevating recurring licensing revenue.
Germany's KBA enforcement of UN ECE R79 standards for lane-keeping assistance is mandating navigation-grade positioning accuracy for regulatory compliance. OEMs must validate route data against certified map sources. European premium vehicle programs face the tightest certification timelines, compressing supplier qualification windows.
Fleet procurement is consolidating vendor relationships around integrated telematics-navigation bundles rather than standalone routing licenses. Logistics operators in the United States are disintermediating aftermarket hardware distributors, contracting directly with platform providers for subscription-based fleet management. This pattern concentrates buyer power and shifts pricing toward per-vehicle-per-month structures.
Automotive Navigation Solutions Market Segmentation
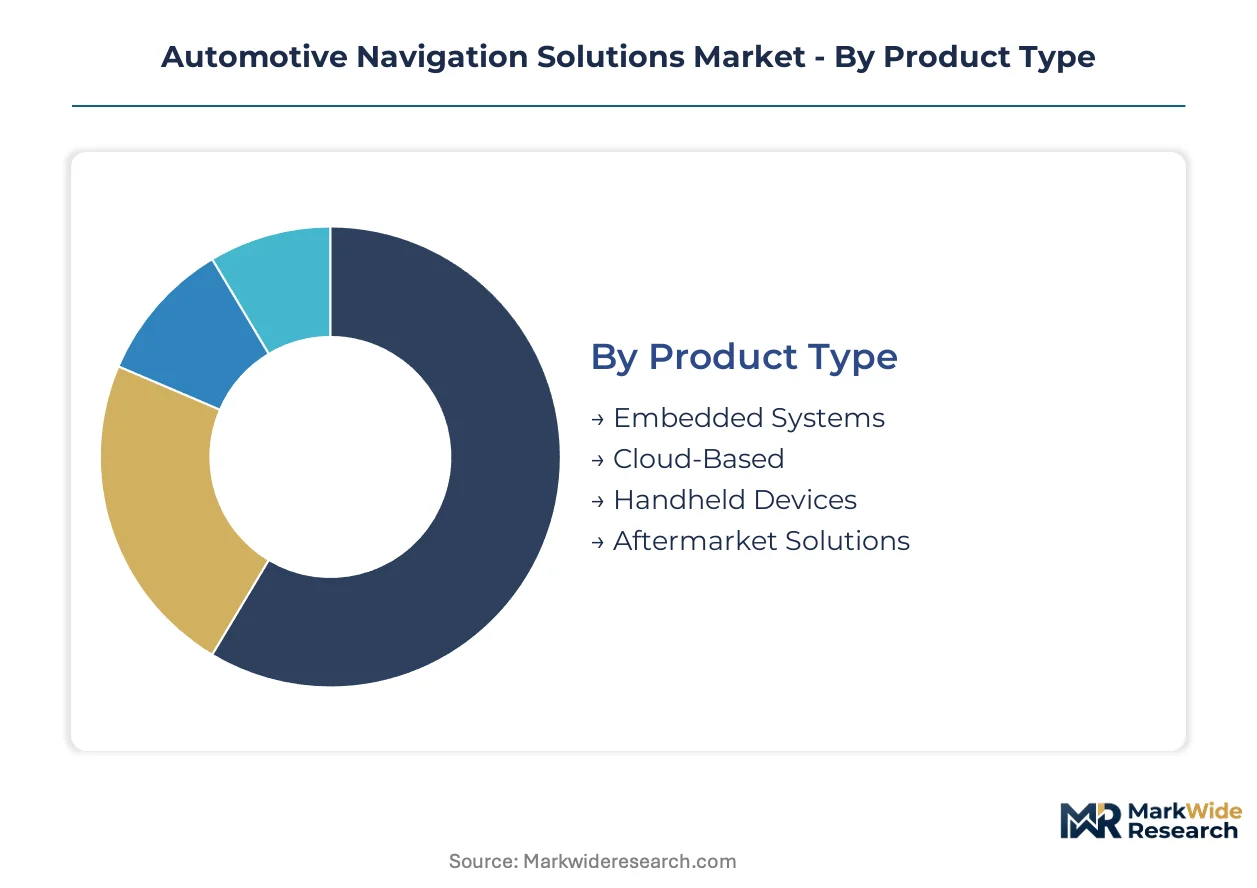
Automotive navigation solutions fragment across hardware-software boundaries and deployment models. Each segment carries distinct refresh economics, certification burdens, and buyer contracting patterns that reshape supplier positioning.
Product Type:
Embedded Systems turn over slowest, locked to vehicle platform lifecycles. Cloud-Based platforms refresh quarterly. Handheld Devices and Aftermarket Solutions occupy intermediate cycle positions tied to consumer electronics obsolescence.
- Embedded Systems:Factory-integrated navigation hardware with dedicated GPUs and hardened GPS receivers. OEM pre-installation contracts in Germany and Japan concentrate demand, though EU AI Act compliance extends development timelines.
- Cloud-Based:Software-defined routing platforms delivered via cellular connectivity. Fleet operators in the United States and China are consolidating procurement onto these systems for real-time traffic ingestion and remote fleet management capabilities.
- Handheld Devices:Portable GPS units with suction-mount displays. Recreational vehicle owners and commercial drivers in regions with aging vehicle fleets sustain residual demand.
- Aftermarket Solutions:Dash-mounted or smartphone-integrated units retrofitting legacy vehicles. India and Southeast Asia present expansion terrain where factory navigation penetration remains low.
Embedded Systems dominates installed base. Cloud-Based is where expansion concentrates.
Technology:
Cost tiers separate these technologies sharply. GPS modules sit at the commodity base. LiDAR and V2X occupy premium positions with concentrated supply chains.
- GPS:Satellite-based positioning using civilian L1/L2 frequency bands. Ubiquitous in entry-level vehicles and aftermarket devices, though signal degradation in urban canyons limits standalone reliability.
- LiDAR:Laser-ranging sensors generating centimeter-accurate point clouds. Chinese autonomous driving programs and German highway pilot systems are pulling tier-one suppliers into sensor fusion partnerships.
- Computer Vision:Camera-based lane detection and traffic sign recognition. OEMs in Japan and South Korea integrate these inputs for lane-keeping assistance meeting regulatory mandates.
- V2X Communication:DSRC or C-V2X modules enabling vehicle-to-infrastructure data exchange. Germany's connected-vehicle infrastructure investment program creates specification pull for navigation systems with these modules.
GPS captures volume leadership. LiDAR is climbing the fastest as autonomous stacks mature.
End User:
Customer types diverge on procurement centralization and contract duration. Fleet Operators and Ride-Sharing Companies aggregate purchasing power. OEMs and Consumer Vehicles fragment across individual transactions.
- OEMs:Vehicle manufacturers contracting tier-one suppliers for platform-integrated navigation. German and Japanese OEMs enforce the strictest functional safety certification timelines.
- Fleet Operators:Logistics and delivery companies procuring telematics-navigation bundles. United States-based operators are disintermediating hardware distributors for direct platform subscriptions.
- Consumer Vehicles:Individual owners selecting factory options or aftermarket alternatives. Price sensitivity concentrates demand in mid-tier feature packages.
- Ride-Sharing Companies:Mobility platforms equipping driver fleets with standardized navigation. Real-time routing optimization directly impacts driver utilization rates and platform economics.
OEMs anchor revenue stability. Fleet Operators are gaining share fastest through subscription model adoption.
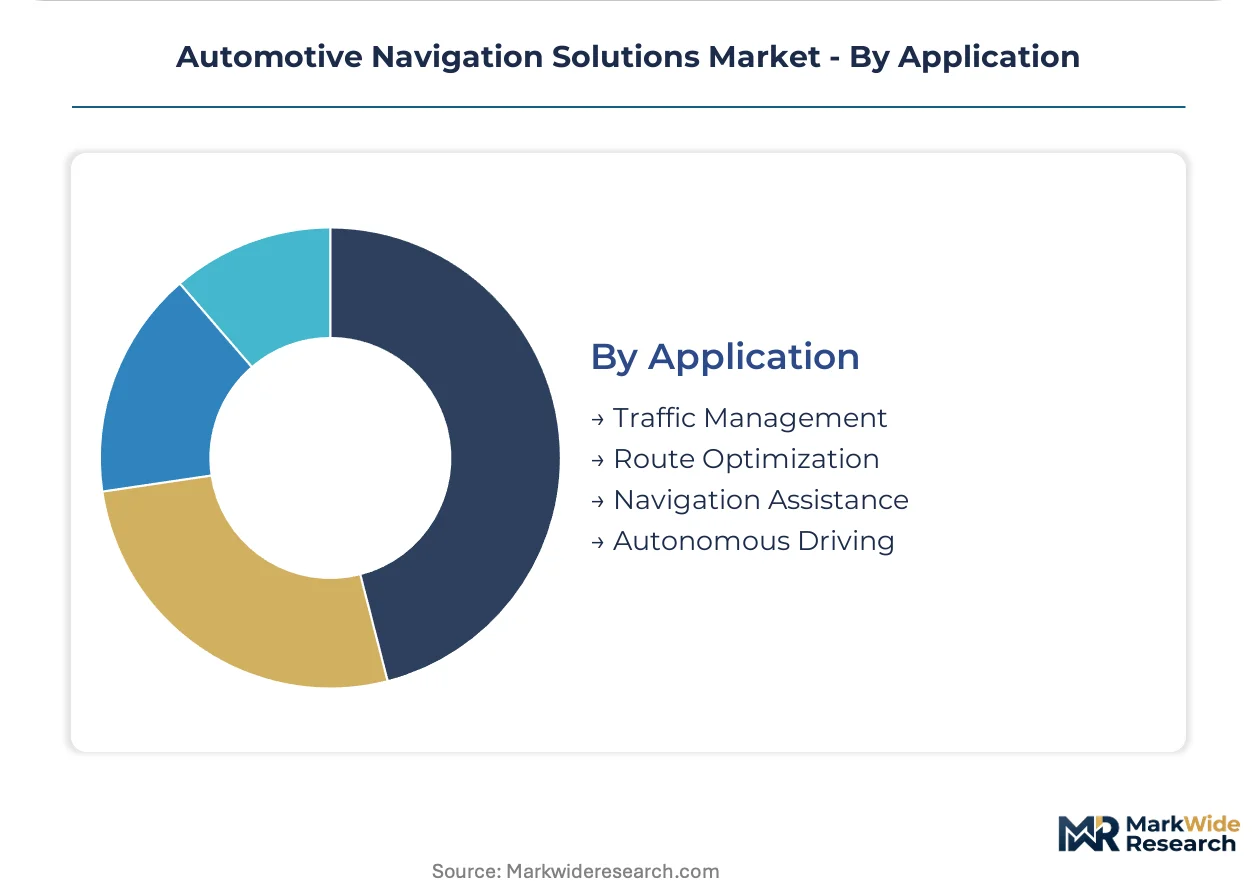
Application:
Maturity stages separate these use cases. Navigation Assistance represents legacy functionality. Autonomous Driving sits at the emerging frontier with unproven monetization.
- Traffic Management:Real-time congestion monitoring and incident detection systems. Municipal deployments in China and the United States leverage aggregated vehicle probe data.
- Route Optimization:Algorithmic path calculation minimizing travel time or fuel consumption. Fleet logistics operators in Europe prioritize these capabilities for regulatory compliance with emissions standards.
- Navigation Assistance:Turn-by-turn guidance with voice prompts and visual displays. Saturated in premium vehicle segments, now penetrating economy vehicle classes in India and Brazil.
- Autonomous Driving:Navigation inputs for automated path planning and execution. HD map layer consumption by Chinese EV manufacturers and German premium OEMs is steepest expansion trajectory.
Navigation Assistance dominates current deployment. Autonomous Driving is where technology investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT anchors the dominant geography through connected-vehicle mandates that accelerate navigation integration with autonomous driving stacks. Domestic OEMs in Beijing and Shanghai are pulling global suppliers into sensor fusion partnerships. The regulatory push creates certification urgency across multiple continents.
China
Domestic EV manufacturers in Shenzhen and Hangzhou are consuming HD map layers for highway pilot systems. MIIT mandates vehicle-to-infrastructure communication modules in new vehicle categories. The Yangtze River Delta cluster concentrates tier-one supplier engineering centers serving NIO, XPeng, and Li Auto programs.
Germany
Premium OEMs in Munich and Stuttgart require navigation-grade positioning accuracy for lane-keeping assistance compliance. KBA enforces UN ECE R79 standards that validate route data against certified map sources. The Ingolstadt-Regensburg corridor anchors Continental AG's embedded system production for European supply chains.
United States
Fleet operators in Texas and California are consolidating procurement onto cloud-native telematics-navigation bundles. NHTSA guidelines on automated driving system safety influence how platforms validate route data. The Detroit metroplex maintains tier-one supplier headquarters serving domestic OEM autonomous programs.
Japan
Camera-based lane detection and traffic sign recognition systems integrate navigation inputs for regulatory compliance. METI standards shape infotainment operating system requirements. The Nagoya-Tokyo corridor concentrates DENSO Corporation and Pioneer Corporation engineering resources for domestic OEM platforms.
India
Commercial vehicle fleets in Maharashtra and Gujarat operate legacy trucks creating aftermarket retrofit demand. BIS certification requirements for automotive electronics constrain import timelines. The Chennai-Bangalore corridor hosts Alpine Electronics and Harman International manufacturing for regional supply.
Automotive Navigation Solutions Market Competitive Environment
Embedded system specialists and cloud-native platform providers split the market along hardware-software boundaries. Tier-one automotive suppliers maintain consolidated positions through OEM pre-installation contracts. Two strategic archetypes dominate: integrated electronics conglomerates with captive semiconductor sourcing, and mapping-software pure-plays with data network effects. Competitive moves concentrate on sensor fusion partnerships and edge-computing architecture shifts.
Among Germany-based integrated suppliers, Continental AG and Robert Bosch GmbH exemplify the conglomerate archetype through embedded system dominance and sensor fusion module integration. HERE Technologies occupies a position within the mapping-software tier, sustaining data collection networks across multiple continents. Garmin Ltd. and TomTom International BV represent the navigation-specialist segment, with the latter anchoring European HD map coverage for autonomous driving programs.
| Leading Market Players |
|---|
| Garmin Ltd. |
| TomTom International BV |
| Continental AG |
| Robert Bosch GmbH |
| HERE Technologies |
| DENSO Corporation |
| Alpine Electronics |
| Harman International |
| Pioneer Corporation |
| Others |
Value Chain & Pricing Dynamics
The Rotterdam-Genoa freight corridor's volatile container rates compress margin pools for navigation hardware importers while amplifying price spreads between embedded system tiers and cloud-native alternatives. OEM procurement teams leverage Taiwan foundry concentration to extract volume discounts on GPS chipsets, forcing tier-two suppliers toward software-only positioning stacks that trade hardware margin for recurring licensing revenue.
Pricing Analysis
Price spreads between German premium OEM contracts and Indian aftermarket retrofits exceed three-to-one on equivalent positioning capability. Three-tier pricing structure across premium, standard, and economy levels segments by ISO 26262 ASIL certification grade and map data refresh frequency. Cost compression in entry-level embedded modules intensifies as Chinese domestic OEMs internalize navigation software development. Fleet operators in North America exhibit lowest price sensitivity due to fuel savings quantification, while Indian commercial vehicle owners drive hardest bargain on upfront hardware cost.
Supply Chain Analysis
Tariff exposure between Taiwan and Germany dominates supply chain risk calculus for GPS receiver chipsets and automotive-grade GPUs. Manufacturing concentrates in Taiwan, South Korea, and China for semiconductor inputs, with Germany and Japan anchoring sensor fusion module assembly. Bill-of-materials draws from lithium tantalate substrates, precision MEMS oscillators, and hardened automotive displays. Single-source vulnerability persists at leading-edge process nodes below seven nanometers. Distribution runs through tier-one supplier direct contracts to OEM platform teams, bypassing traditional electronics distributors for navigation-specific procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smartphone-native navigation applications threaten embedded system incumbents by commoditizing turn-by-turn guidance; substitution defense requires repositioning around regulatory-mandated positioning accuracy that consumer devices cannot satisfy.
For Market Incumbents: Insulate core OEM relationships through exclusive HD map licensing partnerships that lock in sensor fusion data pipelines for autonomous driving programs. Deepen backward integration into LiDAR perception hardware to capture margin migrating from software licenses. Prioritize KBA type-approval certification investment ahead of EU AI Act enforcement timelines to freeze out unqualified competitors.
For New Entrants and Emerging Players: Indian commercial vehicle aftermarket presents the most penetrable white-space, where factory navigation penetration lags replacement cycles by eight to ten years. Target smartphone-integrated dash-mounted units with offline map storage to bypass cellular dependency in rural corridors. Pursue direct fleet operator contracting in Maharashtra and Gujarat, disintermediating legacy electronics distributors through subscription pricing models.
For Investors and Strategic Acquirers: Mapping-software pure-plays with continental-scale data collection networks offer the strongest acquisition target archetype for autonomous driving stack integration. Long-term viability hinges on recurring revenue share from HD map layer consumption rather than one-time licensing. Monitor Chinese MIIT connected-vehicle mandate implementation velocity as the critical inflection signal for sensor fusion partnership demand.
| Strategic Initiative | Industry Significance |
|---|---|
| HD Map Data Network Expansion | Continental coverage density determines autonomous driving stack partnership eligibility with German premium OEMs. |
| Edge Computing Architecture Migration | KBA type-approval standards force computation onto vehicle-mounted processors, expanding embedded system addressable market. |
| Sensor Fusion Partnership Formation | LiDAR-GPS integration contracts with Chinese EV manufacturers accelerate revenue concentration in highway pilot programs. |
| Cloud-Native Platform Consolidation | Fleet operator procurement centralization onto telematics-navigation bundles shifts pricing toward per-vehicle-per-month structures. |
| V2X Module Certification Investment | Germany's connected-vehicle infrastructure program creates specification pull for DSRC and C-V2X navigation integration. |
Study Parameters
Initial hypotheses were tested against primary input from OEM platform engineers, tier-one supplier procurement leads, aftermarket distribution channel heads, and fleet operations managers, then refined through secondary validation against vehicle production databases, IHS Markit registration data, EU regulatory filings, and SEC automotive segment disclosures. Bottom-up unit economics modeling triangulated with top-down market sizing across embedded system, cloud-based, and aftermarket solution categories.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derived from segment-level growth rate reconciliation against macro automotive production forecasts and technology adoption S-curves. Inputs included MIIT connected-vehicle mandate implementation schedules and KBA type-approval certification timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic OEMs internalizing navigation software development would shift outcomes toward accelerated cloud-native platform adoption. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
In-Cabin Lighting-Climate-Audio Synchronized Experience Systems Market
Telematics and Infotainment
Electronic Rotary Controller Systems for Infotainment Market
Telematics and Infotainment
Automotive Dashboard Camera Market
Telematics and Infotainment
Asia-Pacific Automotive Telematics Market
Telematics and Infotainment
Global 5G in Automotives Market
Telematics and Infotainment
Next Generation in-Vehicle Networking (IVN) Market
Telematics and Infotainment
Vehicle Trip Computers Market
Telematics and Infotainment
Global Car Digital Cockpit Market
Telematics and Infotainment
Europe Telematics Market
Telematics and Infotainment
Global Automotive Navigation System Market
Telematics and Infotainment
Intelligent Transport Systems (ITS) Market
Telematics and Infotainment
Global Automotive Infotainment System Market
Telematics and Infotainment
Park Assist Camera Market
Telematics and Infotainment
Motor Racing Telematics Market
Telematics and Infotainment
Motorcycle Infotainment System Market
Telematics and Infotainment
APAC Telematics Market