
 Peer-To-Peer Electric Vehicle Charging Market | 2026-2036
Peer-To-Peer Electric Vehicle Charging Market Size, Share, and Industry Trends Forecast 2026-2036
Peer-To-Peer Electric Vehicle Charging Market Intelligence
Residential driveway access is tilting from a passive asset into a monetizable grid node. ChargePoint Inc. leverages its installed base of home chargers to seed peer-to-peer liquidity in suburban neighborhoods. Enel X anchors European network effects through utility-integrated billing and dynamic load management. Power Hero competes via a hardware-agnostic app that lowers entry barriers for individual hosts.
Peer-to-peer electric vehicle charging denotes a distributed energy service where private charger owners sell surplus capacity to third-party EV drivers through digital platforms, typically operating at 7–22 kW AC (Level 2) to balance session duration with grid load. The primary purpose is to extend charging coverage beyond public infrastructure while allowing asset owners to recover capital costs. Level 2 charging dominates residential host economics due to lower installation complexity and broader dwelling compatibility. Pay-per-use models attract occasional drivers who resist subscription lock-in, while smartphone app connectivity leads platform onboarding by eliminating hardware dependencies for first-time users.
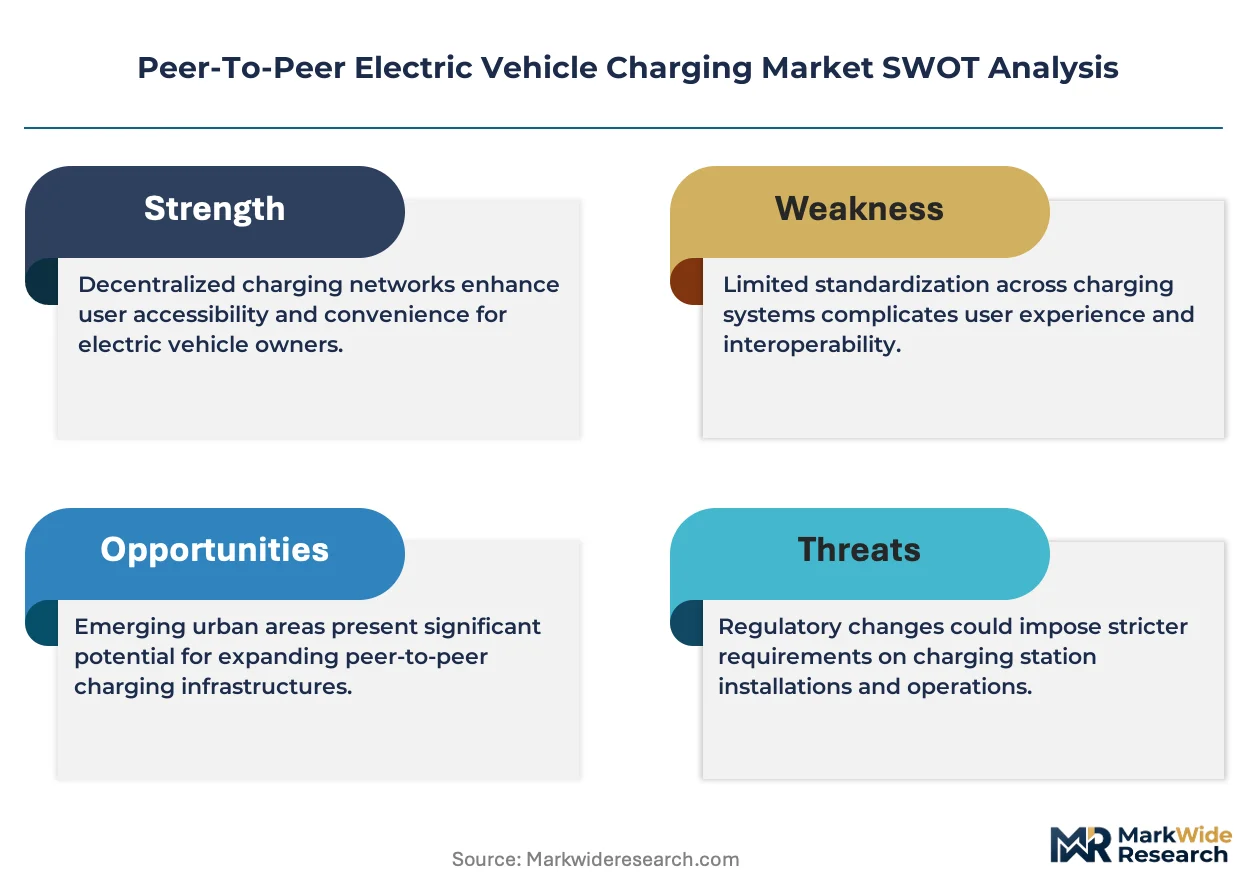
The US Department of Energy's alternative fuel corridor designations and the EU's AFIR regulation both mandate payment interoperability and real-time availability data, which directly shapes platform technical requirements and market access conditions. California's building codes and Germany's F-Gas Regulation on refrigerants in charging equipment add layered compliance obligations for hardware-software bundles. Stakeholders must monitor how NHTSA vehicle-to-grid guidance and evolving ISO 15118 plug-and-charge standards will redefine liability splits between hosts, platform operators, and utilities.
Market Dynamics
Platform liquidity thresholds are compressing charger deployment timelines as network density in suburban clusters accelerates host recruitment velocity beyond traditional infrastructure buildout cycles.
Growth Catalysts
- AFIR Interoperability Mandate:The European Union's Alternative Fuels Infrastructure Regulation forces payment standardization across member states, eliminating platform fragmentation and reducing host onboarding friction.
- Apartment-Dweller Demand:Urban residential parking scarcity creates captive demand for overnight charging access, converting driveway owners into service providers without dedicated commercial investment.
- Dynamic Load Management:Utility-integrated software stacks enable real-time grid balancing, allowing hosts to monetize peak-shaving capacity alongside base charging revenue streams.
Market Restraints
- Copper and Semiconductor Input Volatility:Level 2 charger manufacturing depends on power electronics and wiring harnesses subject to commodity price swings, compressing hardware margins for platform equipment partners.
- Liability Ambiguity Under NHTSA Guidance:Unclear fault allocation between hosts, platform operators, and vehicle manufacturers in vehicle-to-grid interactions elevates insurance costs and deters risk-averse property owners.
- Alternating Current Speed Limitations:7–22 kW residential units cannot serve commercial fleet operators requiring 150+ kW DC fast charging, capping addressable demand to private passenger vehicles.
Strategic Opportunities
- Workplace Parking Integration:Employer-subsidized daytime charging at suburban office parks captures fleet vehicles and commuters with predictable dwell times, expanding utilization beyond overnight residential patterns.
- ISO 15118 Plug-and-Charge Convergence:Automated authentication between vehicle and charger eliminates app dependency, reducing platform customer acquisition costs and improving session completion rates.
- Multi-Unit Dwelling Retrofit Mandates:California's building code requirements for EV-ready parking in new construction create captive infrastructure pools awaiting software-layer activation.
Industry Challenges
- Electrical Contractor Capacity Bottlenecks:Qualified installers capable of residential panel upgrades and 240V circuit deployment are concentrated in metropolitan markets, extending deployment timelines in secondary cities.
- Interoperability Certification Delays:Platform operators must validate hardware-software bundles against evolving OCPP standards and regional grid codes, stretching product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peer-To-Peer Electric Vehicle Charging Market |
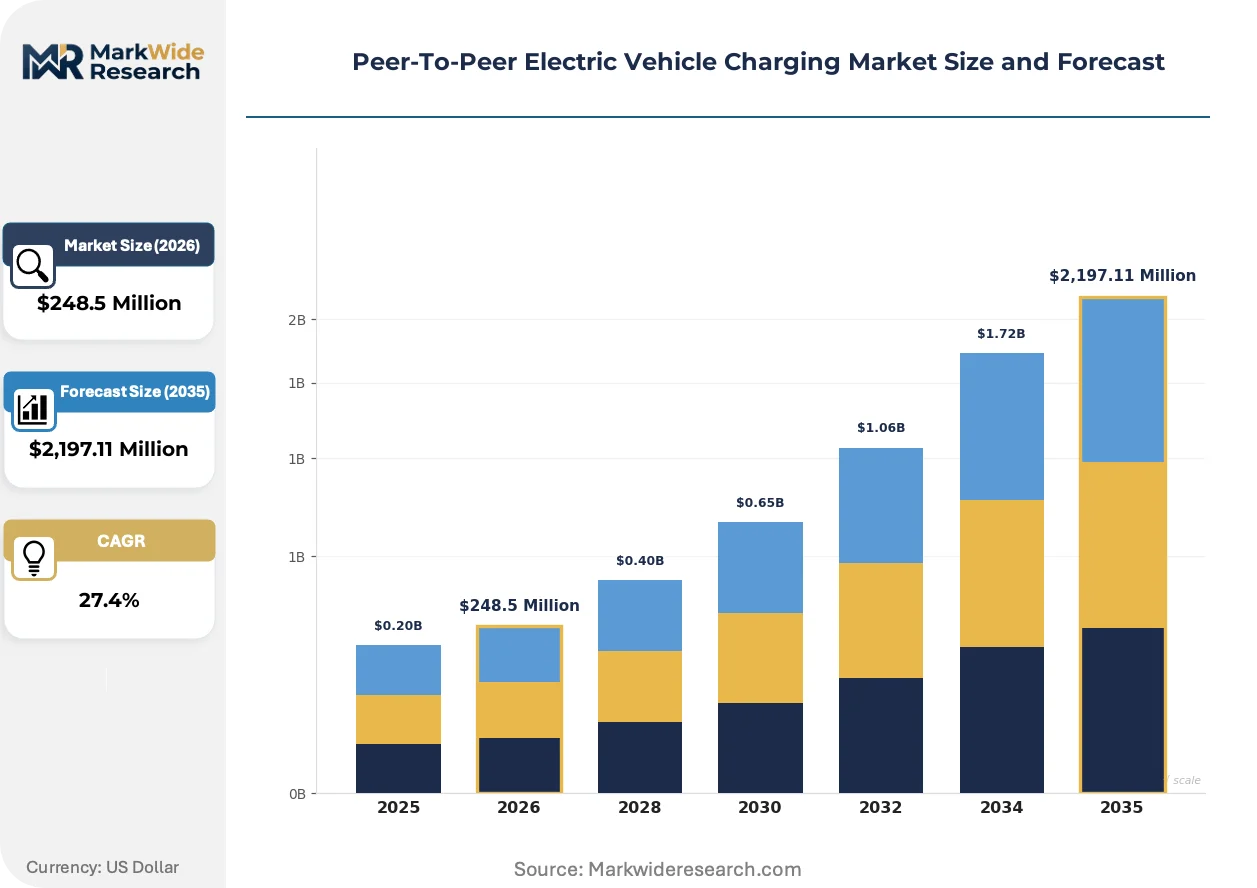
| Market Size in 2026 | $248.5 Million |
| Market Size in 2035 | $2,197.11 Million |
| CAGR (2026 – 2036) | 27.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Charging Type: Level 1, Level 2, DC Fast Charging, Wireless Charging Customer Segment: Residential Users, Commercial Fleets, Car Rentals, Urban Drivers Payment Model: Subscription, Pay-Per-Use, Flat Fee, Freemium Connectivity Feature: Smartphone App, RFID, QR Code, Bluetooth |
| Companies Covered | ChargePoint Inc., ClipperCreek Inc., Enel X, EVBox, EV Meter, Greenlots, has·to·be gmbh, Power Hero, Webasto Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peer-To-Peer Electric Vehicle Charging Market Strategic Shifts & Innovations
Software-defined energy routing is dissolving the boundary between residential consumption and commercial service provision, enabling asset owners to arbitrage electricity prices across multiple revenue streams simultaneously.
Vehicle-to-grid bidirectional charging is collapsing the distinction between energy consumer and grid resource. Early adopters in Germany and California are retrofitting home chargers with export capability, allowing hosts to sell stored vehicle energy back to utilities during peak demand windows. This technology compresses payback periods for residential equipment investments while creating new liability frameworks around battery degradation attribution.
The EU F-Gas Regulation on refrigerants in charging equipment is forcing hardware redesigns across European supply chains. Manufacturers must eliminate high-global-warming-potential cooling agents from power electronics enclosures, accelerating adoption of liquid-cooled architectures in temperate climates. German certification bodies are processing revised technical files under compressed timelines to maintain market access.
Subscription fatigue among occasional EV drivers is fragmenting platform revenue models. Pay-per-session pricing is displacing monthly membership structures in the Netherlands and California, where infrequent travelers resist fixed commitments. This behavioral shift pressures platform operators to optimize transaction fees and reduce per-session overhead through automated metering infrastructure integration.
Peer-To-Peer Electric Vehicle Charging Market Segmentation
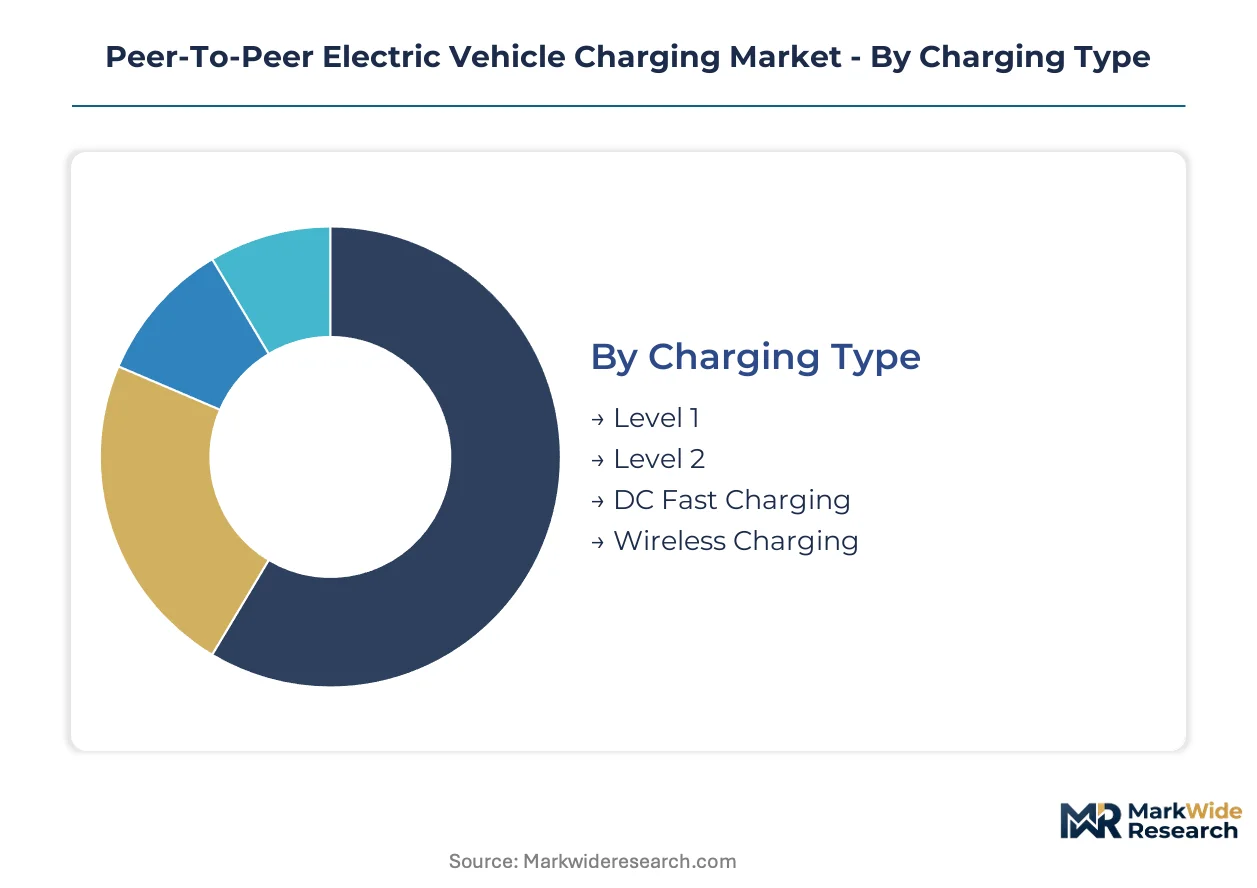
Segmentation in peer-to-peer electric vehicle charging reveals divergent monetization velocities across hardware tiers and user archetypes. Platform operators must align charger specifications with payment flexibility and authentication methods to capture distinct liquidity pools.
Charging Type:
Cycle times vary dramatically: Level 2 units turn over 4-6 sessions daily in dense suburbs, while DC fast charging sees sporadic utilization due to host electrical constraints and regulatory complexity.
- Level 1:Standard 120V residential outlets deliver 2-5 miles of range per hour with zero installation cost. Demand concentrates in legacy apartment buildings across Germany and California where panel upgrades are prohibitive, limiting throughput to overnight dwellers with predictable schedules.
- Level 2:240V AC systems operating at 7-22 kW dominate host economics through balanced capital intensity and session frequency. Suburban driveway owners in the Netherlands monetize surplus capacity during workday hours when vehicles are absent, generating recurring revenue without dedicated commercial infrastructure.
- DC Fast Charging:50-350 kW direct current systems require three-phase utility connections and specialized cooling. Deployment clusters near highway corridors in Germany where AFIR mandates interoperability, though host recruitment lags due to electrical contractor bottlenecks.
- Wireless Charging:Inductive pad systems eliminate connector wear but demand precise vehicle alignment and embedded ground coils. Pilot installations in California workplace parking demonstrate appeal for fleet operators seeking automated handoff.
Level 2 anchors the volume base while DC Fast Charging gains share at the steepest rate among commercially viable segments.
Customer Segment:
Cost tiers separate occasional users seeking transaction flexibility from fleet operators demanding guaranteed availability and consolidated billing.
- Residential Users:Homeowners with driveway access monetize idle infrastructure through platform-mediated sessions. Germany's F-Gas Regulation compliance costs filter margin-sensitive participants toward hardware-agnostic app solutions.
- Commercial Fleets:Delivery and service vehicle operators require predictable dwell-time charging at scale. Workplace parking integration in California captures daytime demand through employer-subsidized infrastructure, expanding utilization beyond residential overnight patterns.
- Car Rentals:Short-term vehicle providers need rapid turnaround charging to maintain fleet availability. Urban depot locations in the Netherlands leverage dynamic load management to arbitrage electricity prices across multiple revenue streams.
- Urban Drivers:Apartment dwellers without dedicated parking represent captive demand for overnight access. Platform liquidity in dense Dutch cities accelerates host recruitment velocity as network density crosses critical thresholds.
Residential Users anchor the volume base while Urban Drivers climb the fastest as parking scarcity intensifies platform adoption.
Payment Model:
Volume concentration favors low-friction entry, though margin structures diverge between recurring commitments and per-session economics.
- Subscription:Monthly fixed fees attract high-frequency drivers with predictable charging needs. Car rental operators in Germany favor this structure for consolidated fleet accounting and budget certainty.
- Pay-Per-Use:Transaction-based pricing eliminates commitment barriers for occasional travelers. Subscription fatigue in California and the Netherlands pushes platform operators toward automated metering infrastructure to reduce per-session overhead.
- Flat Fee:Unlimited access models suit workplace parking sponsors seeking simplified employer subsidy administration. Dutch office parks deploy this structure to capture commuter loyalty without complex usage tracking.
- Freemium:Tiered access combines basic connectivity with premium features like reservation guarantees. California platforms use this model to convert trial users toward higher-attachment paid tiers.
Pay-Per-Use anchors the volume base while Freemium expands most quickly as platforms optimize customer acquisition cost recovery.
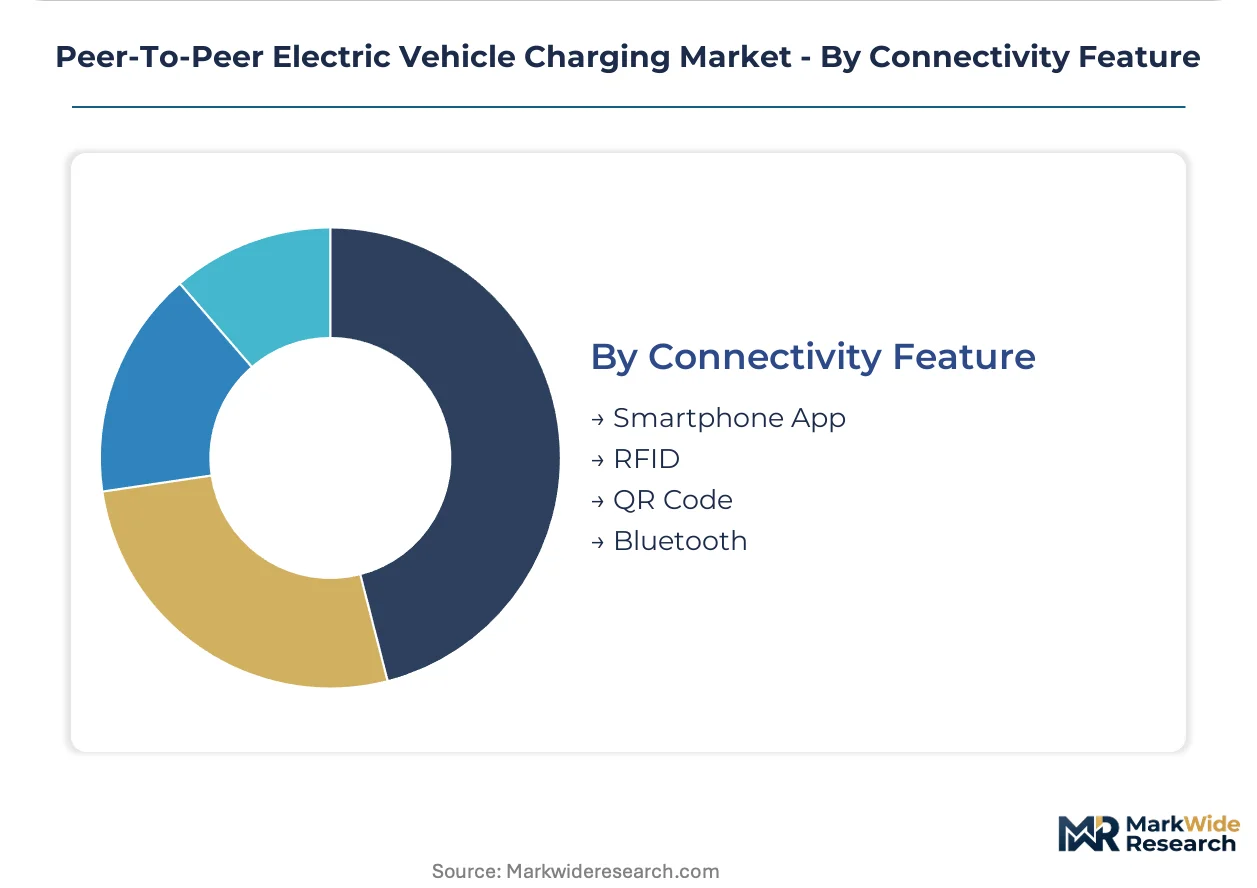
Connectivity Feature:
Authentication speed and hardware dependency shape onboarding friction and session completion rates across user demographics.
- Smartphone App:GPS-enabled discovery and digital payment dominate first-time user acquisition. Platform operators in the Netherlands and California prioritize app-native experiences to eliminate hardware procurement barriers for individual hosts.
- RFID:Radio-frequency cards enable offline authentication and fleet card integration. German commercial operators favor this modality for driver accountability and centralized billing reconciliation.
- QR Code:Camera-based activation requires no dedicated hardware beyond printed signage. Cost-sensitive residential hosts deploy this method to minimize upfront platform integration expenses.
- Bluetooth:Proximity-based pairing eliminates cellular dependency in underground parking structures. Urban deployments in dense German cities leverage this protocol for reliable session initiation where mobile coverage degrades.
Smartphone App anchors the volume base while Bluetooth gains share fastest as infrastructure penetrates signal-constrained environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Netherlands' dense Randstad urban corridor underwrites its position as the most liquid peer-to-peer charging market, where driveway density and parking scarcity create natural network effects. Germany's autobahn grid interconnects and utility-integrated billing infrastructure anchor continental European expansion. California's building code mandates and alternative fuel corridor designations establish the North American template.
Netherlands
Urban apartment dwellers without dedicated parking drive platform adoption in Amsterdam and Rotterdam corridors. The AFIR interoperability mandate eliminates payment fragmentation across Dutch borders. Randstad office parks deploy employer-subsidized daytime charging, converting commuter vehicles into grid-balancing assets during work hours.
Germany
Suburban homeowners with driveway access monetize surplus capacity through utility-integrated dynamic load management. The F-Gas Regulation forces refrigerant redesigns in charging equipment, compressing hardware certification timelines. Bavarian and Baden-Württemberg manufacturing clusters concentrate electrical contractor capacity for residential panel upgrades.
United States
California's building codes requiring EV-ready parking in new construction create captive infrastructure pools. NHTSA vehicle-to-grid guidance shapes liability frameworks for bidirectional charging hosts. Los Angeles and San Francisco Bay Area neighborhoods achieve platform liquidity thresholds ahead of national averages.
United Kingdom
London's ultra-low emission zone penalties accelerate EV adoption among drivers lacking home charging. OZEV grant programs subsidize residential charger installation for rental property landlords. Southeast England commuter towns seed peer-to-peer networks along rail corridors into the capital.
France
Île-de-France parking scarcity converts driveway owners into service providers for apartment-dwelling EV adopters. The EU Green Deal's charging infrastructure targets align with national building retrofit programs. Lyon and Marseille secondary cities extend network density beyond Parisian core clusters.
Peer-To-Peer Electric Vehicle Charging Market Key Industry Players
On the supply side, the industry is consolidating around platform operators with installed hardware bases and utility billing integrations. Three archetypes dominate: legacy charging network incumbents extending into residential monetization, hardware-agnostic software platforms lowering host barriers, and utility-affiliated operators leveraging grid management relationships. Competitive moves concentrate on strategic partnerships with electrical contractors and dynamic load management technology licensing.
Within the utility-integrated tier, Enel X anchors European network effects through billing infrastructure and grid balancing services. ChargePoint Inc. occupies a position bridging North American hardware deployment with software-layer liquidity seeding. Power Hero exemplifies the hardware-agnostic vector, reducing upfront procurement barriers for individual residential hosts through app-native onboarding.
| Leading Market Players |
|---|
| ChargePoint Inc. |
| ClipperCreek Inc. |
| Enel X |
| EVBox |
| EV Meter |
| Greenlots |
| has·to·be gmbh |
| Power Hero |
| Webasto Group |
| Others |
Cost & Logistics Intelligence
Copper and semiconductor input volatility functions as the dominant risk vector determining both tier spreads and supply chain configuration for peer-to-peer charging hardware. Commodity price swings compress margins at the economy tier while premium segments absorb cost pass-through through brand positioning, forcing platform operators to anchor procurement strategies around dual-source agreements for power electronics.
Pricing Analysis
Volume-discount tiering structures stratify across premium, standard, and economy levels based on certification grade and after-sales service bundling. Premium tiers command positioning through ISO 15118 plug-and-charge compliance and extended warranty coverage, while economy offerings compete on hardware-agnostic app compatibility alone. Pricing pressure stems from subscription fatigue pushing platforms toward pay-per-use models with thinner transaction fees. Fleet operators exhibit lowest price sensitivity due to consolidated billing requirements, whereas occasional urban drivers drive race-to-bottom dynamics in session economics.
Supply Chain Analysis
Supplier-financing facilities through utility-integrated platform operators extend payment terms for residential hosts, reducing upfront procurement barriers. Manufacturing concentrates in Germany, China, and South Korea for power electronics and enclosure assemblies. The supply chain draws from copper wiring harnesses, silicon carbide semiconductors, and liquid-cooled thermal management components. Single-source vulnerability sits with Taiwanese foundries for high-efficiency power conversion chips. Distribution runs through electrical contractor networks for installation, with software-layer activation completing downstream delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peer-to-peer electric vehicle charging represents an early-cycle expansion story where apartment-dweller demand without dedicated parking creates natural adoption tailwinds. Network density thresholds in suburban clusters accelerate host recruitment velocity beyond traditional infrastructure deployment timelines.
For Market Incumbents: Insulate platform liquidity through backward integration into residential panel upgrade services, countering electrical contractor capacity bottlenecks that delay host onboarding. Deepen certification investment for OCPP interoperability ahead of AFIR mandate enforcement, defending against hardware-agnostic entrants. Prioritize dynamic load management licensing to utilities as a recurring revenue anchor.
For New Entrants and Emerging Players: Build out workplace parking integration in California and Dutch office corridors where employer subsidies capture predictable daytime dwell times. Target the urban driver segment in dense European cities where parking scarcity creates captive demand and network effects compound fastest. Deploy QR-code authentication to minimize hardware procurement friction for cost-sensitive residential hosts.
For Investors and Strategic Acquirers: The market sits at a platform-formation phase that favors utility-affiliated operators with grid management relationships and installed billing infrastructure. Long-term viability hinges on ISO 15118 standardization enabling automated authentication and reducing customer acquisition costs. Watch NHTSA vehicle-to-grid guidance finalization as the signal for liability framework clarity and bidirectional charging investment inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration with Utility Billing | Enel X leverages grid balancing relationships to anchor European network effects through dynamic load management. |
| Hardware-Agnostic App Deployment | Power Hero reduces host onboarding friction by eliminating proprietary charger procurement requirements for residential participants. |
| ISO 15118 Plug-and-Charge Certification | Automated vehicle-to-charger authentication eliminates app dependency and improves session completion rates across platforms. |
| Workplace Parking Partnership Expansion | California office parks capture fleet vehicles and commuters with predictable dwell times beyond overnight residential patterns. |
| Electrical Contractor Network Partnership | ChargePoint seeds suburban liquidity by integrating installation capacity with home charger deployment for host recruitment. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with platform engineering leads, utility demand-response managers, residential electrical contractors, and EV fleet operations directors. Secondary validation drew from NHTSA regulatory filings, EU AFIR implementation documents, California Energy Commission building code databases, and OCPP standard committee records. Bottom-up host recruitment modeling and top-down addressable parking stock analysis were triangulated against utility interconnection data.
Calibration against historical charger deployment curves and network density thresholds informed the analytical framework across the projection horizon. Segmentation dimensions modeled include charging type tier, customer archetype, payment structure, and authentication modality alongside regional regulatory cluster. CAGRs were derived from penetration rate assumptions tied to parking scarcity indices and building code mandate timelines, with EV adoption curves and electricity rate arbitrage potential as key forecast inputs.
Stress conditions across copper price volatility, semiconductor lead time extension, and NHTSA guidance delay scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding AFIR interoperability implementation pace and ISO 15118 adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
EV Thermal System Market
Electric Vehicles
Electric Delivery Vans Market
Electric Vehicles
Africa Electric Vehicle Market
Electric Vehicles
EV Taxi Market
Electric Vehicles
Asia-Pacific Electric Vehicle (EV) Fluids Market
Electric Vehicles
Embedded System for Electric Vehicle Market
Electric Vehicles
France Hybrid Electric Vehicle Battery Market
Electric Vehicles
Electric Van Market
Electric Vehicles
Japan Solar E-Bike Market
Electric Vehicles
Poland E-Bike Market
Electric Vehicles
Italy Hybrid Electric Vehicle Battery Market
Electric Vehicles
Electric Mobility Market
Electric Vehicles
Car Battery Chargers Market
Electric Vehicles
North America Automotive Battery Thermal Management System Market
Electric Vehicles
Hybrid E-Scooter Market
Electric Vehicles
Denmark Solar E-Bike Market